
 Magnetic Drive Pumps Market | 2026-2036
Magnetic Drive Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Magnetic Drive Pumps Market Analysis
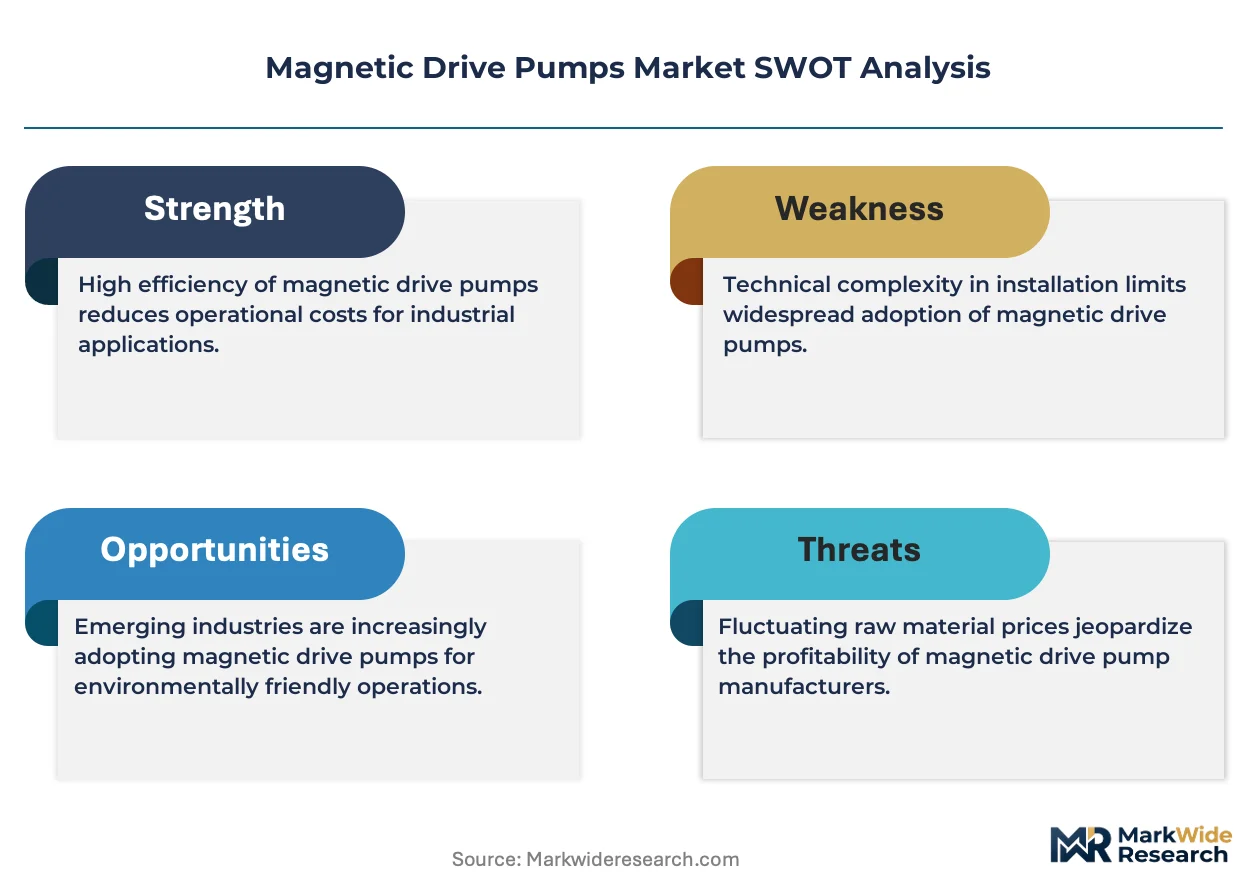
Asset-light leasing models for critical rotating equipment is rewriting competitive dynamics in the magnetic drive pumps landscape. Flowserve Corporation leverages its aftermarket service network to sustain long-term customer contracts across energy-intensive installations. Iwaki Co., Ltd. anchors its position through specialized fluoropolymer-lined designs for aggressive chemical environments. KSB SE & Co. KGaA competes on manufacturing scale, operating foundries and machining centers that control cost structures in standard pump categories.
Magnetic drive pumps are sealless centrifugal devices that transmit torque through a containment shell using permanent magnets or electromagnetic couplings, eliminating shaft seals and enabling leak-free operation for hazardous, corrosive, or high-purity fluids. Their primary purpose centers on eliminating fugitive emissions in chemical transfer and protecting product integrity in pharmaceutical manufacturing where contamination carries batch-loss consequences. Standard magnetic drive pumps occupy the largest installed base but generate thinner margins due to commoditized casting and widespread Asian supply. High temperature pumps command premium positioning where rare-earth magnet stability and non-metallic containment shell engineering create barrier-to-entry expertise. Sanitary pumps concentrate margin pools in pharmaceutical and food-grade applications requiring electropolished surfaces and FDA-compliant elastomer selections.
EPA regulations on hazardous air pollutants and volatile organic compound emissions directly mandate sealless technology in chemical processing, while FDA cGMP standards govern surface finish and material traceability in pharmaceutical installations. The EU REACH framework restricts certain elastomer and coating chemistries, forcing reformulation of containment shell linings and O-ring compounds. Stakeholders must monitor rare-earth magnet supply concentration and evolving per- and polyfluoroalkyl substance restrictions that threaten conventional fluoropolymer lining chemistries.
Market Dynamics
EPA enforcement of hazardous air pollutant standards is forcing chemical processors to retire mechanical seal pumps ahead of scheduled replacement cycles, compressing equipment procurement timelines and redirecting capital toward sealless architectures.
Growth Catalysts
- REACH compliance mandates:ECHA restrictions on perfluorinated compounds are accelerating reformulation of containment shell linings, pulling demand toward next-generation ceramic and metallic barrier designs that eliminate fluoropolymer dependency.
- Pharmaceutical batch integrity requirements:FDA cGMP surface finish specifications for electropolished 316L stainless steel are expanding sanitary pump installations in biologics manufacturing where single-batch losses exceed equipment capital costs.
- Rare-earth magnet stability engineering:Samarium-cobalt magnet formulations operating above 350°C are unlocking high-temperature process applications previously served by canned motor pumps, extending magnetic drive technology into catalytic reforming and polymerization loops.
Market Restraints
- Neodymium supply concentration:Chinese dominance in rare-earth oxide refining creates magnet cost volatility that compresses margins for standard pump categories where material inputs represent 40-50% of finished goods value.
- Containment shell thickness constraints:Eddy current losses in metallic barriers limit maximum power transmission, capping magnetic drive applicability in high-flow hydrocarbon transfer services above 500 kW.
- IRA domestic content thresholds:US Treasury guidance on clean energy manufacturing tax credits is fragmenting supply chains as OEMs dual-source magnet assemblies to qualify for incentive eligibility.
Strategic Opportunities
- Modular retrofit architectures:Drop-in magnetic drive cartridges compatible with existing ANSI pump casings are creating aftermarket revenue streams without full skid replacement, penetrating brownfield chemical installations in Texas and Louisiana.
- Digital twin integration:Vibration and temperature sensor arrays embedded in magnetic couplings are enabling predictive maintenance contracts that unbundle hardware sales from recurring service revenue.
- Hydrogen infrastructure buildout:Liquid hydrogen transfer specifications at -253°C are driving demand for specialized cryogenic magnetic drive designs in German and South Korean electrolyzer and fueling station deployments.
Industry Challenges
- Containment shell welding certification:ASME Section VIII pressure vessel qualifications for hastelloy and titanium barriers extend production lead times 12-16 weeks, constraining responsiveness to spot chemical plant turnaround schedules.
- Cross-functional commissioning expertise:Magnetic drive installations require simultaneous fluency in magnet circuit design, fluid dynamics, and process safety management systems, creating talent scarcity that inflates field service rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magnetic Drive Pumps Market |
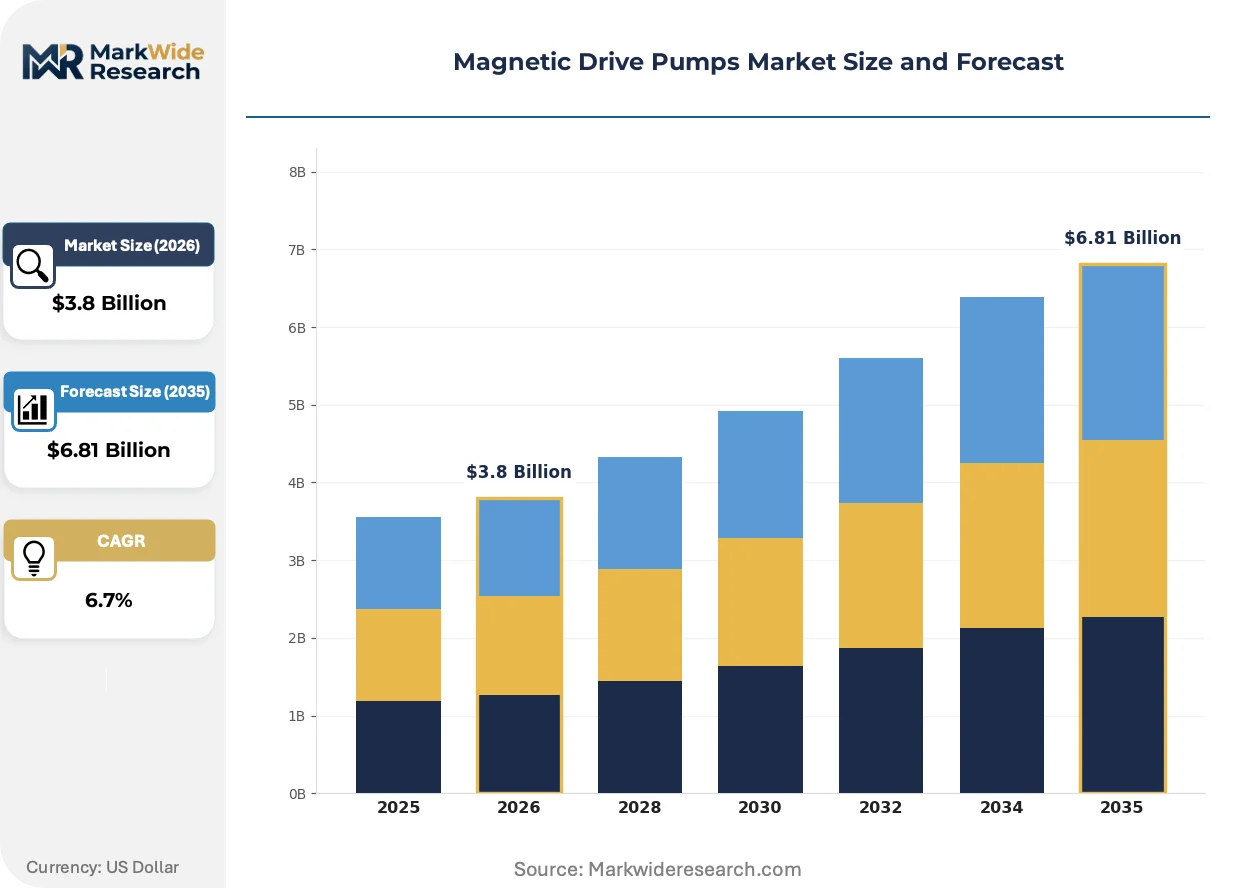
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Magnetic Drive Pumps, High Temperature Pumps, Self-Priming Pumps, Sanitary Pumps End User: Chemical Processing, Water Treatment, Food & Beverage, Pharmaceuticals Application: Liquid Transfer, Circulation, Chemical Feed, Tank Filling Capacity: Small Scale, Medium Scale, Large Scale, Custom Scale |
| Companies Covered | Flowserve Corporation, Iwaki Co., Ltd., Sulzer Ltd, KSB SE & Co. KGaA, Sundyne, Klaus Union, Dickow Pump Company, ITT Goulds Pumps, Verder Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magnetic Drive Pumps Market Emerging Trajectories
Equipment intelligence and material science advances are compressing the traditional trade-offs between sealless reliability and hydraulic performance that have governed pump selection for three decades.
Ceramic matrix composite containment shells are collapsing the eddy current penalty that historically forced engineers to choose between metallic barrier pressure ratings and non-metallic efficiency. Chemical processors in the US Gulf Coast are specifying silicon carbide-silicon carbide laminates for hydrofluoric acid service where metallic corrosion and polymer permeation previously mandated canned motor alternatives. The technology is collapsing the efficiency gap that reserved magnetic drives for lower-duty applications.
EPA's finalized National Emission Standards for Hazardous Air Pollutants for synthetic organic chemical manufacturing are mandating leak detection and repair program intensification that effectively prohibits new mechanical seal installations in light liquid service. The regulation is compressing replacement demand into 2024-2026 procurement windows as facilities accelerate compliance capital planning. Affected plants are specifying API 685-compliant magnetic drive packages with integrated secondary containment and leak detection instrumentation.
Asset-light operating models are fragmenting traditional OEM-customer relationships as chemical majors outsource rotating equipment ownership to service providers. Operators in Rotterdam's port industrial cluster are contracting for guaranteed availability per ton of throughput rather than capitalizing pump assets, shifting supplier economics toward lifecycle performance guarantees. The model concentrates specification authority with engineering procurement contractors who aggregate demand across multiple operating companies.
Magnetic Drive Pumps Market Segmentation
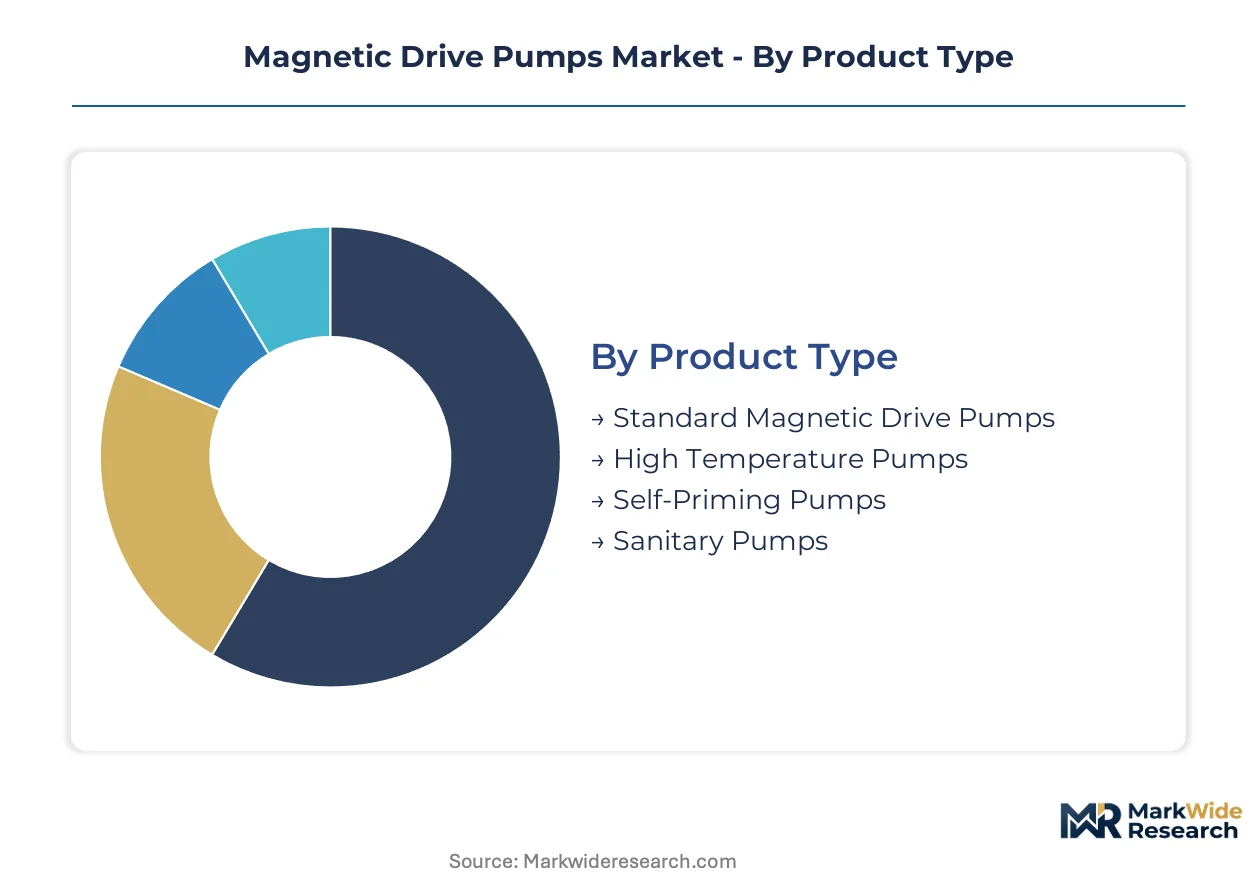
Segmentation in magnetic drive pumps reveals distinct service intensity profiles across product architectures and end-use environments. Chemical processors demand continuous monitoring capabilities, while pharmaceutical installations prioritize validation documentation over rapid response times.
Product Type:
After-sales-service intensity varies dramatically across magnetic drive pump architectures, with high-temperature and sanitary designs requiring specialized field engineering that standard products do not.
- Standard Magnetic Drive Pumps:Cast iron and 316L stainless steel configurations dominate brownfield chemical plant retrofits. Demand concentrates in Texas and Louisiana refineries where EPA leak detection mandates are accelerating ANSI pump replacements ahead of scheduled turnarounds. Service contracts emphasize spare cartridge availability rather than predictive diagnostics.
- High Temperature Pumps:Samarium-cobalt magnet assemblies and ceramic containment shells enable operation above 350°C in catalytic reforming loops. German polymerization facilities are specifying these for bisphenol-A production where thermal cycling destroys conventional magnet formulations. Field service requires magnet circuit recalibration expertise that commands premium labor rates.
- Self-Priming Pumps:Vacuum-assisted priming chambers address suction lift limitations in tanker unloading applications.
- Sanitary Pumps:Electropolished 316L surfaces and FDA-compliant elastomers serve biologics manufacturing where batch validation documentation exceeds hardware value.
By volume, Standard Magnetic Drive Pumps leads. By growth pace, High Temperature Pumps is ahead.
End User:
Customer procurement authority fragments differently across end-use sectors, with engineering contractors dominating chemical processing while pharmaceutical sites retain in-house specification control.
- Chemical Processing:Chlor-alkali and specialty chemical producers specify API 685-compliant packages with integrated secondary containment. Demand clusters in Germany's industrial corridor where REACH restrictions on fluorinated compounds are forcing containment shell material transitions. Procurement timelines compress around regulatory compliance deadlines rather than capital budget cycles.
- Water Treatment:Municipal desalination and industrial wastewater facilities prioritize corrosion-resistant fluoropolymer linings for brine and acid handling.
- Food & Beverage:Dairy and brewery applications require 3-A sanitary standards with clean-in-place compatibility.
- Pharmaceuticals:Single-use bioreactor feeds and buffer preparation systems demand surface finish certifications that extend factory acceptance testing protocols.
Chemical Processing commands the largest installed base. Pharmaceuticals is climbing the fastest as biologics capacity expands.
Application:
Application-specific duty cycles determine magnet thermal management requirements and bearing life calculations that differentiate warranty terms.
- Liquid Transfer:Continuous-duty hydrocarbon and chemical transfer services in US Gulf Coast terminals specify silicon carbide bearings and rare-earth magnet assemblies rated for 20,000-hour mean time between failures. Eddy current losses in metallic containment shells limit maximum power transmission, capping applicability below 500 kW in high-flow crude oil service.
- Circulation:Reactor jacket and heat exchanger loops impose thermal shock conditions that stress ceramic barrier laminates.
- Chemical Feed:Metering accuracy requirements in water treatment favor close-coupled configurations with variable frequency drives.
- Tank Filling:Intermittent duty cycles and dry-run risk in tanker unloading applications drive self-priming specification.
Liquid Transfer represents the highest volume segment. Circulation is gaining share fastest as process intensification raises heat removal demands.
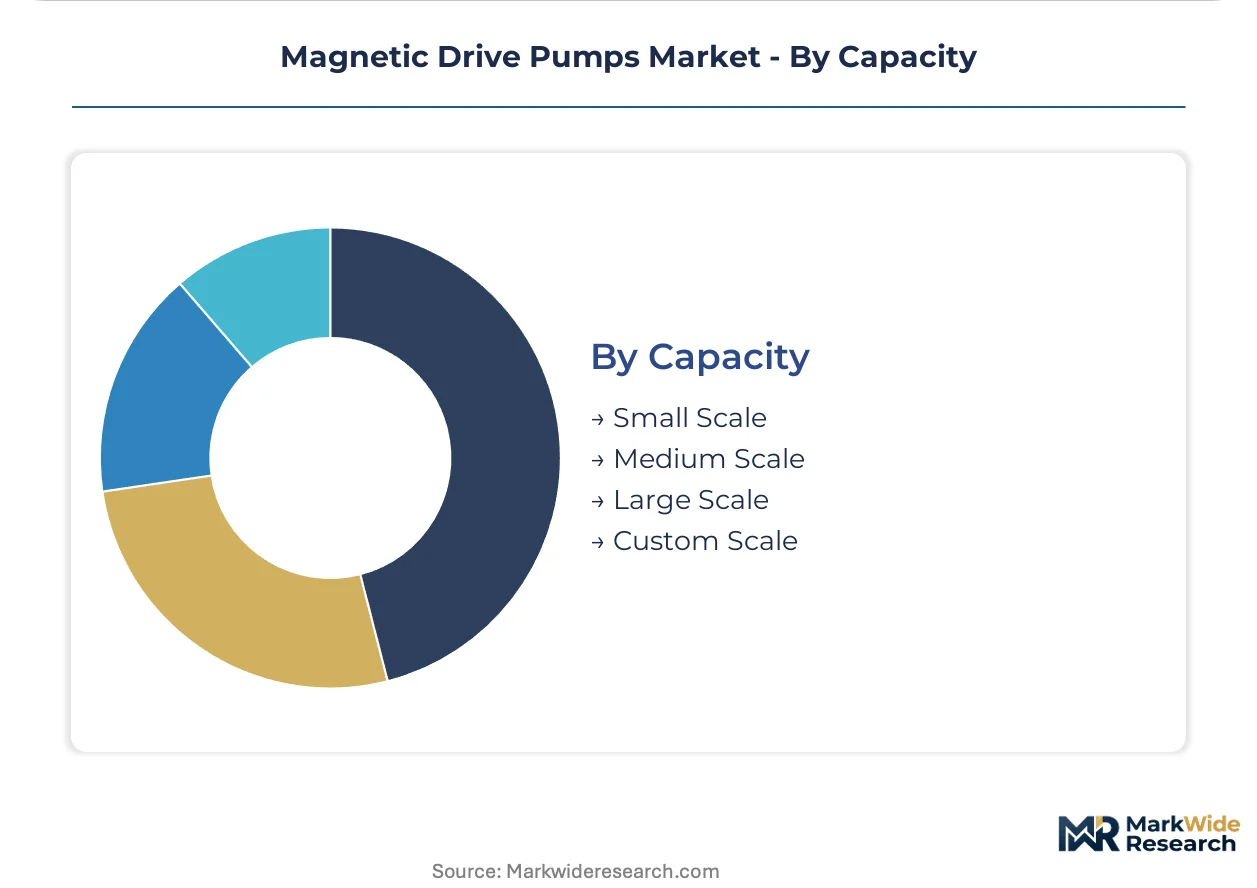
Capacity:
Manufacturing scale economies concentrate in medium and large categories, while custom fabrication commands margin premiums that offset batch production inefficiencies.
- Small Scale:Laboratory and pilot plant pumps below 5 kW utilize standardized magnet cartridges and polymer containment shells. South Korean electrolyzer manufacturers are specifying these for hydrogen research facilities where liquid nitrogen precooling tests cryogenic barrier materials.
- Medium Scale:5-75 kW configurations serve the majority of chemical transfer and circulation duties with cast or fabricated steel casings.
- Large Scale:Above 75 kW, eddy current penalties in metallic shells force canned motor alternatives in high-flow hydrocarbon service.
- Custom Scale:Titanium and hastelloy barriers for hydrofluoric acid service extend ASME Section VIII welding certification lead times to 12-16 weeks.
Medium Scale dominates unit shipments. Custom Scale shows the steepest expansion trajectory as corrosive process conditions proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA enforcement of hazardous air pollutant standards and IRA domestic content thresholds are redirecting capital flows toward sealless pump architectures across major industrial economies. Chemical processors in Germany's industrial corridor and US Gulf Coast terminals are compressing procurement timelines to meet compliance deadlines. Hydrogen infrastructure buildouts in South Korea and electrolyzer deployments in the Netherlands are opening specialized cryogenic applications.
United States
Texas and Louisiana refineries are accelerating ANSI pump replacements ahead of scheduled turnarounds to comply with EPA National Emission Standards for Hazardous Air Pollutants. US Treasury guidance on clean energy manufacturing tax credits is fragmenting supply chains as OEMs dual-source magnet assemblies to qualify for IRA incentive eligibility. Houston's petrochemical corridor is specifying API 685-compliant magnetic drive packages with integrated secondary containment.
Germany
Bisphenol-A production facilities in the industrial corridor are specifying samarium-cobalt magnet assemblies for thermal cycling applications above 350°C. ECHA restrictions on perfluorinated compounds under REACH are accelerating reformulation of containment shell linings toward ceramic and metallic barrier designs. BASF's Ludwigshafen complex and Bayer's Leverkusen operations are driving demand for high-temperature pump configurations.
China
Neodymium supply concentration in rare-earth oxide refining is creating magnet cost volatility that compresses margins for standard pump categories. The country's dual carbon goals are tightening fugitive emission standards in chemical processing zones along the Yangtze River Delta. Ningbo and Shanghai port industrial clusters are expanding chlor-alkali capacity with sealless technology specifications.
South Korea
Liquid hydrogen transfer specifications at -253°C are driving demand for specialized cryogenic magnetic drive designs in electrolyzer and fueling station deployments. Government hydrogen economy roadmaps are subsidizing domestic manufacturing of containment shell barriers for extreme low-temperature service. Ulsan's industrial complex and Gwangju's hydrogen innovation cluster are pilot-testing ceramic matrix composite barriers.
Netherlands
Rotterdam's port industrial cluster is contracting for guaranteed pump availability per ton of throughput rather than capitalizing assets, shifting supplier economics toward lifecycle performance guarantees. Asset-light operating models are concentrating specification authority with engineering procurement contractors who aggregate demand across multiple operating companies. Shell's Pernis refinery and chemical terminals along the Maasvlakte are retrofitting with modular magnetic drive cartridges.
Magnetic Drive Pumps Market Vendor Landscape
On the supply side, the industry is moderately consolidated with distinct tiering between integrated multinational OEMs and specialized regional fabricators. Scale-driven manufacturers compete through captive foundry operations and machining centers that control cost structures in standard pump categories. Niche specialists command premium positioning through rare-earth magnet stability engineering and ceramic containment shell expertise. Dominant competitive moves include strategic partnerships for aftermarket service networks and portfolio diversification into predictive maintenance contracts.
Within the integrated multinational tier, Flowserve Corporation exemplifies the aftermarket-centric archetype through long-term customer contracts sustained by service network density. KSB SE & Co. KGaA anchors the manufacturing-scale archetype with in-house foundry and machining operations. Iwaki Co., Ltd. occupies the specialized materials position through fluoropolymer-lined design expertise for aggressive chemical environments. These three represent the dominant competitive vectors: service bundling, vertical manufacturing control, and application-specific material engineering.
| Leading Market Players |
|---|
| Flowserve Corporation |
| Iwaki Co., Ltd. |
| Sulzer Ltd |
| KSB SE & Co. KGaA |
| Sundyne |
| Klaus Union |
| Dickow Pump Company |
| ITT Goulds Pumps |
| Verder Group |
| Others |
Supply Flow & Price Mechanics
Ningbo's rare-earth oxide refining cluster anchors magnet cost structures that cascade through finished pump pricing, with Chinese supply concentration amplifying volatility transmission to OEM margins. Standard pump categories absorb the sharpest price compression where neodymium inputs represent substantial finished goods value, while high-temperature and sanitary designs defend premiums through samarium-cobalt formulations and ceramic barrier engineering that insulate against commodity magnet swings.
Pricing Analysis
Certification level (API 685/FDA cGMP/CE marking) creates the primary spread between transactional tiers, with project-based pricing dominating capital equipment procurement and long-term service contracts unbundling hardware from recurring revenue streams. Price differentiation rests on magnet stability ratings and containment shell material grades, with EPA compliance deadlines compressing buyer timelines and reducing price sensitivity in chemical processing procurement. Pharmaceutical installations exhibit lowest price sensitivity where batch validation costs dwarf equipment capital, while municipal water treatment faces acute pressure from constrained public budgets.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk assessment, with dual-sourcing mandates under IRA domestic content thresholds fragmenting magnet assembly procurement. Manufacturing concentrates in China, Germany, and the United States, with rare-earth oxides, fluoropolymer linings, and hastelloy bar stock anchoring upstream dependencies. Distribution runs through engineering procurement contractors who aggregate demand across Rotterdam's port industrial cluster and Texas-Louisiana chemical corridors, compressing OEM direct sales relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance contracts and guaranteed availability agreements are expanding faster than hardware unit sales, converting capital equipment markets into service-attach opportunities with recurring revenue profiles.
For Market Incumbents: Harden aftermarket service network density to defend against asset-light operating models that outsource rotating equipment ownership to third-party providers. Deepen captive foundry control over standard pump castings to offset magnet cost volatility, while accelerating ceramic matrix composite barrier R&D to preempt REACH-driven fluoropolymer obsolescence. For New Entrants and Emerging Players: Build out modular retrofit cartridge capabilities for ANSI pump brownfield installations in Texas and Louisiana, where EPA compliance deadlines compress procurement windows and favor drop-in solutions over full skid replacement. Target hydrogen infrastructure specifications in South Korea and Germany, where cryogenic magnetic drive expertise remains underdeveloped relative to electrolyzer deployment timelines. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized material engineering firms with ceramic containment shell and rare-earth magnet stability capabilities over commoditized standard pump manufacturers. Acquisition screening should prioritize ASME Section VIII welding certification assets and field service talent pools, with inflection signals tracking ECHA perfluorinated compound restriction enforcement and hydrogen liquefaction capacity announcements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Magnet Supply | Captive magnet production insulates margins from Chinese oxide refining volatility. |
| Ceramic Matrix Composite Barrier Development | Eliminates REACH compliance exposure from fluoropolymer lining chemistries. |
| Predictive Maintenance Platform Deployment | Sensor-embedded couplings enable recurring revenue unbundled from hardware sales. |
| Hydrogen Cryogenic Pump Certification | Liquid hydrogen transfer specifications open specialized demand in electrolyzer deployments. |
| Modular Retrofit Cartridge Engineering | Drop-in ANSI compatibility penetrates brownfield chemical plant compliance upgrades. |
Methodological Framework
Desk research of trade customs data, SEC filings, and EPA regulatory dockets preceded structured interviews with plant maintenance directors, chemical procurement leads, aftermarket service heads, and containment shell engineering specialists. Primary fieldwork across Texas-Louisiana refineries and Germany's industrial corridor was validated against secondary sources including API standards documentation, ECHA restriction proposals, and hydrogen infrastructure project databases. Bottom-up unit shipment estimates triangulated against top-down capital expenditure tracking across chemical processing and pharmaceutical manufacturing sectors.
Assumptions around EPA enforcement intensity, REACH implementation timelines, and rare-earth supply concentration were held fixed across baseline scenarios while hydrogen infrastructure deployment pace and IRA domestic content interpretation were stress-tested. Segmentation modeling incorporated product architecture, end-use sector procurement authority, application duty cycle, and regional regulatory cluster dimensions. CAGRs were derived from equipment replacement cycle analysis and compliance-driven demand pull-in effects.
Stress conditions across neodymium price volatility bands, fluoropolymer restriction severity, and hydrogen liquefaction technology maturation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and magnet supply chain configuration. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Heavy Duty Dewatering Pumps Market
Pumps and Control Devices
Brine Tanks Market
Pumps and Control Devices
Axial Piston Pumps Market
Pumps and Control Devices
Global Mobile Hydraulic Pump Market
Pumps and Control Devices
Global Leak Detection Solutions Market
Pumps and Control Devices
Ion Pump Market
Pumps and Control Devices
Fertilizer Injection Pumps Market
Pumps and Control Devices
Water Pump Market
Pumps and Control Devices
APAC Centrifugal Pumps Market
Pumps and Control Devices
Droplet Separator Market
Pumps and Control Devices
Hydraulic Dosing Pump Market
Pumps and Control Devices
Rotary Pump Market
Pumps and Control Devices
Global Lubrication Pumps Market
Pumps and Control Devices
Paint Pump Market
Pumps and Control Devices
Rotating Equipment Market
Pumps and Control Devices
Horizontal Pumping Systems (HPS) Market