
 Tandem Piston Compressors Market | 2026-2036
Tandem Piston Compressors Market Size, Share, and Industry Trends Forecast 2026-2036
Tandem Piston Compressors Market Analytics
Cold chain logistics is expanding its share of tandem piston compressor procurement as pharmaceutical distributors and food processors retrofit facilities for tighter temperature integrity. Atlas Copco AB leverages its aftermarket service network to sustain recurring revenue from installed compressor fleets across Nordic industrial zones. BOGE Kompressoren anchors its position through specialized oil-free configurations that serve clean-room manufacturing requirements in Central Europe.
A tandem piston compressor arranges multiple pistons in series within a common crankcase to achieve higher pressure ratios than single-stage units, typically operating with discharge pressures exceeding 30 bar in industrial refrigeration and process gas duties. Oil-free compressor designs command premium positioning due to zero-contamination requirements in pharmaceutical and electronics manufacturing applications, while lubricated variants dominate general industrial settings where operational cost sensitivity prevails. The reciprocating technology segment retains structural importance in high-pressure, low-flow scenarios where rotary alternatives face efficiency constraints.
The EPA SNAP program in the United States and the EU F-Gas Regulation collectively reshape refrigerant compatibility requirements, forcing compressor manufacturers to redesign valve materials and sealing systems for lower-GWP alternatives. ISO 8573 air purity classes further segment product positioning between food-grade and general industrial supply tiers. Stakeholders must weigh captive manufacturing against outsourced assembly as refrigerant chemistry transitions accelerate component obsolescence risk across existing product lines.
Market Dynamics
The EU F-Gas Regulation and EPA SNAP program are forcing compressor manufacturers to redesign valve materials and sealing systems for lower-GWP refrigerant architectures, creating a structural pivot point across industrial refrigeration supply chains.
Growth Catalysts
- Pharmaceutical cold chain expansion:Temperature integrity mandates from FDA and EMA are driving retrofit demand for tandem piston systems in vaccine distribution networks.
- REACH compliance acceleration:European chemical safety protocols are phasing out legacy refrigerants, compelling OEMs to adopt compatible compressor architectures.
- Electronics manufacturing clustering:Clean-room requirements in semiconductor fabrication are pulling oil-free tandem configurations into high-purity process gas duties.
Market Restraints
- Specialized alloy input costs:Valve seat materials resistant to hydrofluoroolefin chemistries face price volatility from nickel and cobalt supply concentration in Central African mining regions.
- Technical displacement ceiling:Rotary screw compressors capture share in mid-pressure ranges above 15 bar, compressing tandem piston addressable volume in general industrial applications.
- Certification timeline friction:ISO 8573 air purity requalification cycles extend 18-24 months, freezing product line refreshes during refrigerant transition windows.
Strategic Opportunities
- India pharmaceutical manufacturing:CDSCO cold chain mandates and PLI scheme incentives are opening greenfield compressor procurement in biologics storage infrastructure.
- Carbon capture process integration:Tandem architectures handling CO2 transcritical pressures above 80 bar are converging with direct air capture system engineering.
- Service unbundling channels:Independent aftermarket providers are capturing compressor overhaul work previously captive to OEM networks.
Industry Challenges
- Refrigerant chemistry skill gaps:Field technicians lack training in lower-GWP blend handling, extending commissioning timelines and warranty exposure.
- Legacy control system integration:Digital compressor monitoring platforms face protocol mismatches with existing SCADA installations in mature industrial facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tandem Piston Compressors Market |
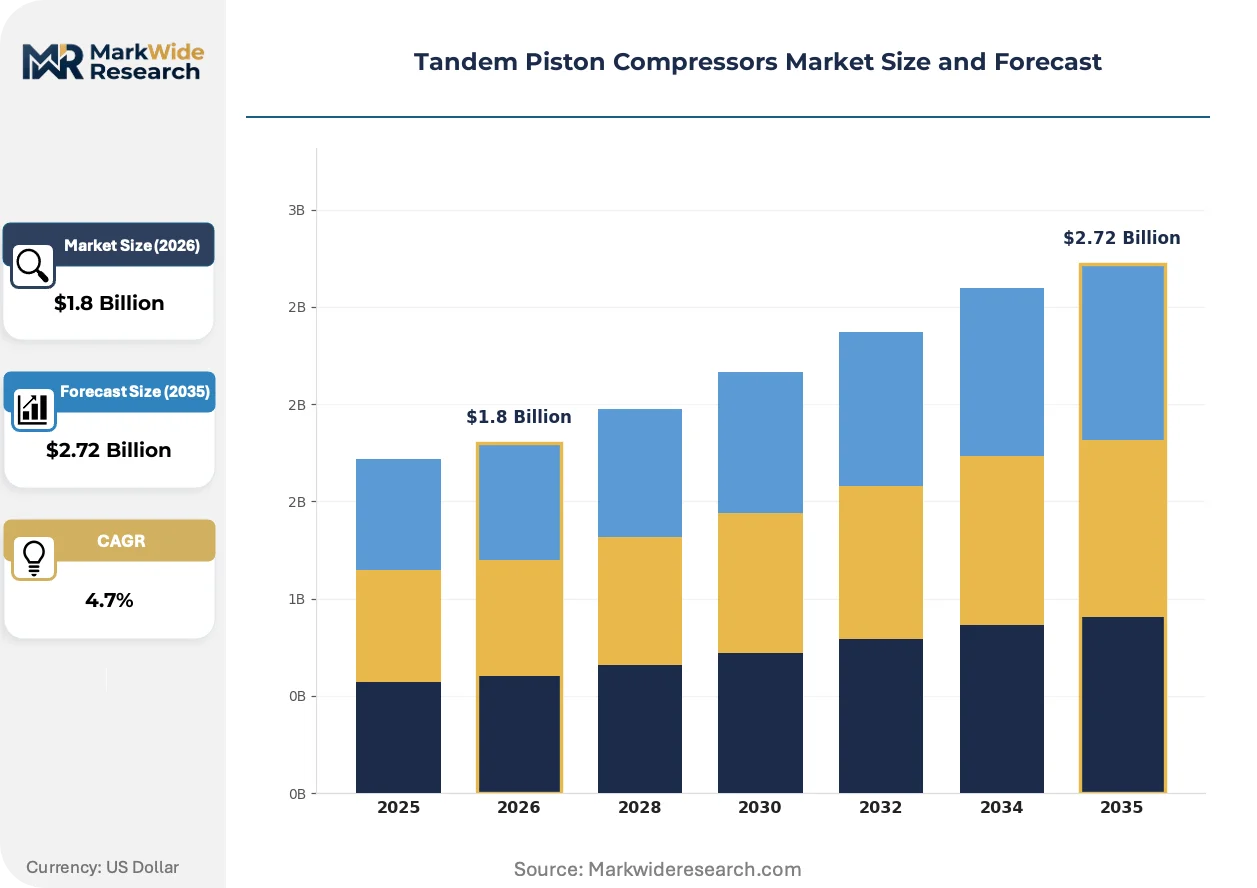
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oil-Free Compressors, Lubricated Compressors, Portable Compressors, Stationary Compressors Application: Manufacturing, Automotive, Construction, HVAC End User: OEMs, Aftermarket Providers, Industrial Facilities, Retail Outlets Technology: Positive Displacement, Rotary Screw, Reciprocating, Variable Speed |
| Companies Covered | Dorin S.p.A., NU AIR, Atlas Copco AB, FIMA SRL, Danfoss AS, BOGE Kompressoren, BAC Compressors, Nardi Compressor SRL, Shanghai Xinran Compressor Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tandem Piston Compressors Market Evolving Landscape
Refrigerant chemistry transitions are compressing product development cycles while digital monitoring platforms rewrite aftermarket revenue models across compressor fleets.
Variable speed drive technology is converging with tandem piston architectures to enable part-load efficiency optimization in fluctuating refrigeration demand profiles. Food processors with seasonal throughput variation are adopting these configurations fastest. The technology is converging with predictive maintenance platforms to compress unplanned downtime incidence in 24/7 cold storage operations.
The EU F-Gas Regulation mandates an 80% phase-down in hydrofluorocarbon consumption by 2030, forcing compressor valve metallurgy toward stainless steel and specialized polymer composites. This regulatory pressure is accelerating R&D allocation toward CO2-compatible designs. Industrial refrigeration OEMs in Germany and Italy are responding with dedicated transcritical product lines.
Equipment-as-a-service contracting is displacing capital purchase models among cold chain logistics operators seeking to transfer refrigerant compliance risk to manufacturers. This shifts balance sheet exposure from end-users to OEMs while locking in long-term service revenue streams. The pattern is most visible in Nordic markets where energy-as-a-service infrastructure already exists.
Tandem Piston Compressors Market Segmentation
Tandem piston compressor procurement patterns diverge sharply between integrated system builds and standalone replacement cycles. Understanding where each segment sits along this integration spectrum reveals margin structures and customer stickiness profiles.
Product Type:
Oil-free configurations embed into multi-stage process systems requiring zero contamination tolerance, while portable units circulate through rental fleets and emergency replacement channels.
- Oil-Free Compressors:These systems eliminate lubricant contact with compressed gas through specialized piston rings and self-lubricating materials. Pharmaceutical manufacturers in Germany and Switzerland specify these for sterile process duties under EMA contamination guidelines.
- Lubricated Compressors:Oil-flooded designs dominate general industrial refrigeration where operational cost sensitivity outweighs purity requirements. Cold storage operators in the United States retrofit existing facilities with these units to meet EPA SNAP refrigerant timelines.
- Portable Compressors:Mobile configurations serve construction site demands and emergency backup roles across rental fleets.
- Stationary Compressors:Fixed installations anchor permanent industrial refrigeration infrastructure in food processing plants.
Lubricated compressors lead volumes today; oil-free configurations are gaining share fastest.
Application:
Cost tier stratification separates mission-critical process applications from commodity utility supply, with certification requirements driving price multiples between adjacent tiers.
- Manufacturing:Process gas compression in semiconductor fabrication demands ISO 8573 Class 0 air purity. Electronics clusters in South Korea and Taiwan pull oil-free tandem architectures into clean-room environments.
- Automotive:Assembly line pneumatic power and paint shop applications favor lubricated units with lower lifecycle costs. OEM compressor procurement concentrates in Michigan, Stuttgart, and Toyota City manufacturing corridors.
- Construction:Mobile equipment rental pools absorb portable tandem units for temporary site power.
- HVAC:Commercial building refrigeration systems retrofit with lower-GWP compatible compressors under F-Gas Regulation mandates.
Manufacturing commands premium pricing; HVAC retrofit demand is climbing the fastest.
End User:
Customer type determines whether procurement flows through specification-driven OEM channels or price-sensitive aftermarket replacement cycles.
- OEMs:Original equipment manufacturers integrate compressors into packaged refrigeration systems and industrial gas handling skids. German industrial refrigeration OEMs cluster around compressor technology hubs in North Rhine-Westphalia.
- Aftermarket Providers:Independent service networks capture overhaul and remanufacturing work previously captive to factory channels. Nordic aftermarket specialists leverage existing energy-as-a-service infrastructure.
- Industrial Facilities:End-user direct procurement concentrates in large food processing and pharmaceutical manufacturing sites.
- Retail Outlets:Distributor networks serve small and mid-sized industrial customers through standardized product lines.
OEMs dominate specification-driven procurement; aftermarket providers are expanding share fastest.
Technology:
Maturity gradients separate established positive displacement architectures from digitally enabled variable speed configurations commanding service revenue premiums.
- Positive Displacement:Enclosed volume reduction principles underpin all reciprocating compressor designs. This foundational category retains structural importance in high-pressure, low-flow scenarios where rotary alternatives face efficiency constraints.
- Variable Speed:Drive technology enables part-load efficiency optimization in fluctuating refrigeration demand profiles. Food processors with seasonal throughput variation adopt these configurations fastest.
- Rotary Screw:Helical rotor designs capture share in mid-pressure ranges above 15 bar, compressing tandem piston addressable volume.
- Reciprocating:Piston-based compression remains the core tandem architecture for industrial refrigeration above 30 bar discharge pressure.
Positive displacement anchors installed base; variable speed drives show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting compressor procurement toward jurisdictions with phased compliance timelines, as manufacturers exploit the cost-of-compliance gap between early-adopter and lagging markets.
Germany
Industrial refrigeration OEMs cluster around compressor technology hubs in North Rhine-Westphalia, sourcing tandem architectures for transcritical CO2 systems. The EU F-Gas Regulation mandates 80% hydrofluorocarbon phase-down by 2030, forcing valve metallurgy redesigns toward stainless steel composites. Stuttgart-based fabricators anchor clean-room manufacturing demand for oil-free configurations serving pharmaceutical sterilization duties.
United States
Cold storage operators retrofit existing facilities to meet EPA SNAP refrigerant timelines, driving replacement cycles in food distribution networks. FDA temperature integrity mandates for vaccine distribution networks pull tandem piston systems into pharmaceutical logistics infrastructure. Michigan automotive corridors concentrate lubricated compressor procurement for assembly line pneumatic power and paint shop applications.
China
Electronics manufacturing clusters in the Yangtze River Delta pull oil-free tandem architectures into semiconductor fabrication clean-rooms. NMPA cold chain mandates for biologics storage accelerate compressor procurement in biopharmaceutical distribution infrastructure. Shanghai-based compressor fabricators serve both domestic demand and export markets across Southeast Asian industrial zones.
India
CDSCO cold chain mandates and PLI scheme incentives open greenfield compressor procurement in biologics storage infrastructure. BIS air purity standards segment product positioning between food-grade and general industrial supply tiers. Gujarat pharmaceutical manufacturing corridors concentrate demand for contamination-tolerant compressor configurations in sterile process duties.
Japan
Semiconductor fabrication clean-room requirements in Kyushu and Kansai regions sustain demand for ISO 8573 Class 0 air purity systems. METI energy efficiency standards accelerate variable speed drive adoption in seasonal food processing operations. Nagoya automotive manufacturing belts anchor lubricated compressor procurement for cost-sensitive assembly line applications.
Tandem Piston Compressors Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with specification-driven OEM channels favoring established European names while price-sensitive replacement cycles absorb Asian fabrication. The vendor base concentrates around three strategic archetypes: full-system integrators with captive compressor production, standalone compressor specialists serving retrofit markets, and contract manufacturers supplying private-label components. Capacity expansion and refrigerant-compatible portfolio diversification represent the dominant competitive moves as compliance deadlines compress product refresh windows.
Among European-based specialists, Dorin S.p.A. and NU AIR exemplify the compressor-focused archetype, while Atlas Copco AB occupies a position bridging full-system integration with aftermarket service networks. BOGE Kompressoren represents the oil-free specialization vector within German industrial zones. Shanghai Xinran Compressor Company anchors the contract manufacturing tier serving cost-optimized procurement channels across Asia-Pacific markets.
| Leading Market Players |
|---|
| Dorin S.p.A. |
| NU AIR |
| Atlas Copco AB |
| FIMA SRL |
| Danfoss AS |
| BOGE Kompressoren |
| BAC Compressors |
| Nardi Compressor SRL |
| Shanghai Xinran Compressor Company |
| Others |
Value Network & Pricing Analysis
EU F-Gas Regulation phase-down mandates gate qualified supply and premium-tier pricing access by compelling valve metallurgy upgrades toward stainless steel composites. Compressor manufacturers bearing these material conversion costs extract pricing premiums from pharmaceutical cold chain operators who cannot tolerate refrigerant containment failures.
Pricing Analysis
Distributor margin layers compress as OEM direct contracting expands among large food processors seeking refrigerant compliance risk transfer. Three-tier pricing structure across premium, standard, and economy levels separates ISO 8573 Class 0 oil-free systems from lubricated industrial units and portable rental configurations. Pricing pressure stems from nickel and cobalt alloy volatility in Central African supply regions. Cold storage operators exhibit highest price sensitivity; semiconductor fabricators accept premium positioning for contamination tolerance.
Supply Chain Analysis
Remanufacturing flows from independent aftermarket providers capture compressor overhaul work previously captive to OEM service networks, redirecting component demand toward specialized reconditioning facilities in Germany and Italy. Valve seat production concentrates in Germany, Italy, and China, drawing from nickel, cobalt, and specialized polymer composite inputs. Single-source vulnerability in Central African mining regions threatens alloy cost stability. Distribution runs through industrial refrigeration OEM channels in North Rhine-Westphalia and direct procurement at large pharmaceutical manufacturing sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion trajectories favor manufacturers converting refrigerant chemistry transitions into premium-tier positioning, while cost-down pressure from rotary screw alternatives compresses addressable volume in mid-pressure ranges.
For Market Incumbents: Extend aftermarket service bundling to lock in recurring revenue from installed compressor fleets facing refrigerant retrofit cycles. Deepen captive production of specialized valve alloys to hedge Central African supply concentration. Rotary screw displacement above 15 bar represents the primary share threat requiring architectural differentiation. For New Entrants and Emerging Players: Direct-to-facility digital sales channels bypass established distributor networks serving price-sensitive replacement cycles in mature industrial zones. Target India's CDSCO-mandated cold chain buildout as the most penetrable geography, leveraging PLI scheme visibility to anchor early procurement relationships. Lead with equipment-as-a-service contracting to transfer compliance risk and capture long-term service attachment. For Investors and Strategic Acquirers: Roll-up economics work for regional aftermarket specialists because refrigerant transition windows compress product refresh cycles and extend overhaul demand. Five-to-ten year viability hinges on CO2 transcritical capability buildout. Target independent service networks with established technician training infrastructure. Monitor EPA SNAP program expansion timelines as inflection indicators for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Valve Alloy Supply | Mitigates nickel and cobalt price volatility from Central African mining concentration. |
| CO2 Transcritical Product Line Launch | Captures EU F-Gas Regulation-driven demand from German industrial refrigeration OEMs. |
| Equipment-as-a-Service Contracting Expansion | Transfers refrigerant compliance risk to manufacturers while securing long-term service revenue. |
| Digital Monitoring Platform Integration | Enables predictive maintenance revenue streams across 24/7 cold storage operations. |
| India Pharmaceutical Cold Chain Partnership | Positions for CDSCO-mandated biologics storage infrastructure buildout under PLI incentives. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with compressor OEM procurement teams, aftermarket service directors, cold chain logistics operators, and plant maintenance engineers with secondary validation against EU F-Gas Regulation implementation reports, EPA SNAP program filings, customs trade data for compressor component flows, and SEC disclosures from listed industrial equipment manufacturers. Bottom-up installed base estimates and top-down refrigeration system demand projections were cross-referenced for triangulation.
Historical reference periods anchored the forecast window to pre-pandemic baseline demand patterns and subsequent refrigerant regulation acceleration phases. Segmentation modeling spanned product type, application tier, end-user channel, and technology architecture dimensions. CAGRs were derived from regression analysis against industrial refrigeration capacity additions and refrigerant phase-down compliance timelines. Variable speed drive penetration rates and CO2 transcritical system adoption curves served as industry-specific forecast inputs.
Regulatory enforcement variance, alloy supply disruption, and rotary screw technology advancement are the dominant revision risks to modeled projections. Practitioners should monitor EPA SNAP program expansion announcements and EU F-Gas Regulation amendment proposals for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Compressors
Portable Air Compressor Market
Compressors
Oil-Injected Screw Compressor Market
Compressors
Industrial Air Compressor Market
Compressors
Europe Compressor Market
Compressors
Desiccant Compressed Air Dryer Market
Compressors
Rotary Air Compressor Market
Compressors
Chlorine Compressors Market
Compressors
Turbocompressor Market
Compressors
Axial Compressor Market
Compressors
North America Air Compressor Market
Compressors
Centrifugal Compressors Market
Compressors
Hydrogen Compressor Market
Compressors
Oil Free Compressor Market
Compressors
Asia-Pacific Booster Compressor Market
Compressors
Stationary Air Compressor Market
Compressors
North America Compressor Market