
 Centrifugal Pumps Machines Market | 2026-2036
Centrifugal Pumps Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Centrifugal Pumps Machines Market Analysis
Direct distribution through OEM-aligned channel partners is fragmenting as regional pump distributors consolidate and e-procurement platforms gain share. Grundfos leverages its captive service network to sustain aftermarket revenue across municipal water contracts. Xylem competes through digital monitoring integration, while Flowserve Corporation anchors its position in oil and gas project engineering.
Centrifugal pumps machines convert rotational kinetic energy into hydrodynamic energy via an impeller to move fluids in industrial and commercial systems, with critical specifications including head capacity measured in meters, flow rate in cubic meters per hour, and net positive suction head to prevent cavitation. Single-stage pumps dominate volume in agricultural and residential water supply due to simpler maintenance and lower capital outlay, while multi-stage configurations command margin pools in high-pressure oil and gas and chemical processing applications where staged impeller arrays achieve discharge pressures exceeding 200 bar. Magnetic drive technology is displacing conventional sealed designs in chemical processing and hazardous fluid handling as sealless construction eliminates leakage paths and satisfies tightening emissions protocols.
The US Department of Energy enforces minimum efficiency standards for clean water pumps under federal conservation regulations, while the EU Ecodesign Directive mandates ecodesign requirements for water pumps sold in member states, effectively filtering non-compliant products from both markets. China's GB standards for pump energy efficiency and India's BIS certification for agricultural pumping equipment add further compliance layers for manufacturers serving Asia-Pacific demand centers. Stakeholders must monitor how tightening efficiency thresholds interact with material cost inflation in cast iron and stainless steel supply chains.
Market Dynamics
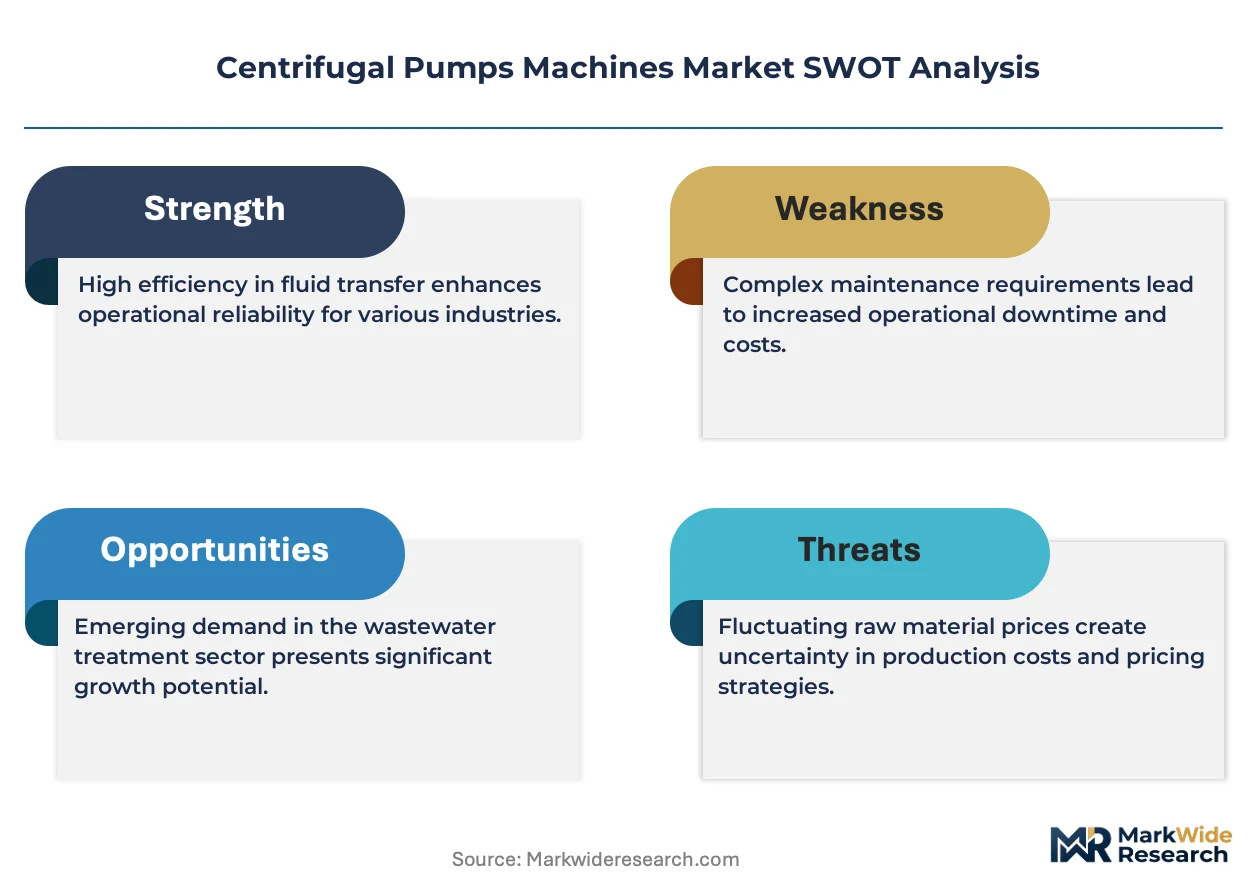
Magnetic drive sealless technology is compressing conventional mechanical seal architectures across chemical processing and hazardous fluid applications, forcing incumbent manufacturers to retool casting and assembly lines.
Growth Catalysts
- EU Ecodesign Directive:Mandatory efficiency thresholds for water pumps sold in member states are filtering non-compliant products and expanding addressable market for premium-tier manufacturers.
- Municipal water infrastructure:Aging distribution networks in China, India, and Germany are accelerating fleet replacement cycles for multi-stage and submersible configurations.
- Stainless steel impeller casting:Advances in investment casting precision are enabling thinner vane geometries that improve hydraulic efficiency without sacrificing cavitation resistance.
Market Restraints
- Cast iron and stainless steel cost volatility:Raw material price swings compress margin pools for mid-tier OEMs unable to pass through input cost fluctuations.
- Foundry capacity concentration:Southeast Asian casting supply chains face intermittent disruption from energy rationing and environmental compliance shutdowns.
- Mechanical seal maintenance burden:Conventional sealed designs face substitution pressure from magnetic drive alternatives in emissions-sensitive applications.
Strategic Opportunities
- India agricultural electrification:BIS-certified pump sets for solar-powered irrigation represent underpenetrated demand as rural grid extension lags.
- Digital monitoring convergence:Integration of vibration sensors with cloud analytics platforms enables predictive maintenance contracts in municipal water utilities.
- US Department of Energy conservation standards:Tightening federal minimum efficiency requirements create regulatory tailwind for premium motor-pairing suppliers.
Industry Challenges
- Hydraulic engineer scarcity:Specialized computational fluid dynamics expertise required for impeller optimization concentrates at tier-one manufacturers and specialized consultancies.
- Multi-certification timelines:Simultaneous pursuit of ATEX, IECEx, and UL listings for hazardous duty pumps extends product launch cycles.
- Legacy SCADA integration:New digital pump controllers face protocol fragmentation when interfacing with decades-old municipal control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Centrifugal Pumps Machines Market |
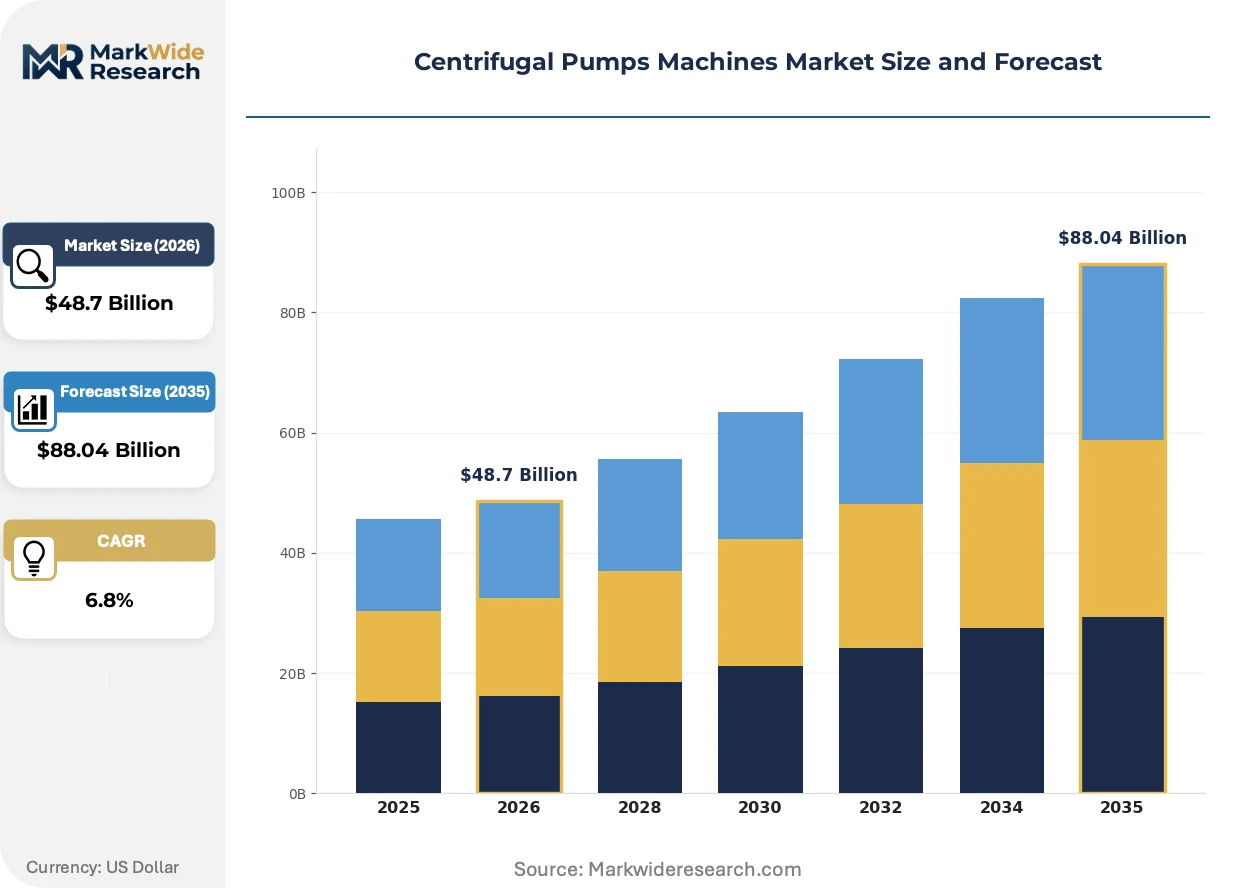
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Stage, Multi-Stage, Submersible, Horizontal Application: Agriculture, Oil & Gas, Water Supply, Chemical Processing End User: Industrial, Residential, Agricultural, Municipal Technology: Magnetic Drive, Electric, Solar-Powered, Hydraulic |
| Companies Covered | Grundfos, Xylem, Flowserve Corporation, KSB SE & Co. KGaA, Sulzer, Wilo SE, Ebara Corporation, ITT Goulds Pumps, Pentair, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Centrifugal Pumps Machines Market Emerging Trajectories
Digitalization and materials science are converging to redefine pump lifecycle economics, compressing traditional maintenance intervals and unlocking new service revenue architectures.
Permanent magnet synchronous motors paired with variable frequency drives are rendering obsolete fixed-speed induction motor configurations in municipal water boosting stations. Utilities in Germany and the Netherlands are retrofitting existing installations to capture part-load efficiency gains. The technology is rendering obsolete the historical trade-off between capital cost and operating expense that favored lower-first-cost equipment.
China's GB standards for pump energy efficiency are tightening disclosure requirements for nameplate performance testing. Domestic manufacturers must submit third-party verification to MIIT-registered laboratories before market entry. Exporters serving Chinese municipal procurement are accelerating in-house test loop investments to maintain bidding eligibility.
Service unbundling is fragmenting traditional OEM-captive maintenance contracts. Independent pump service providers in India's industrial corridors are capturing aftermarket revenue through standardized refurbishment protocols and non-proprietary spare parts. Municipal water authorities in Maharashtra and Gujarat are piloting multi-vendor service panels to reduce single-source dependency.
Centrifugal Pumps Machines Market Segmentation
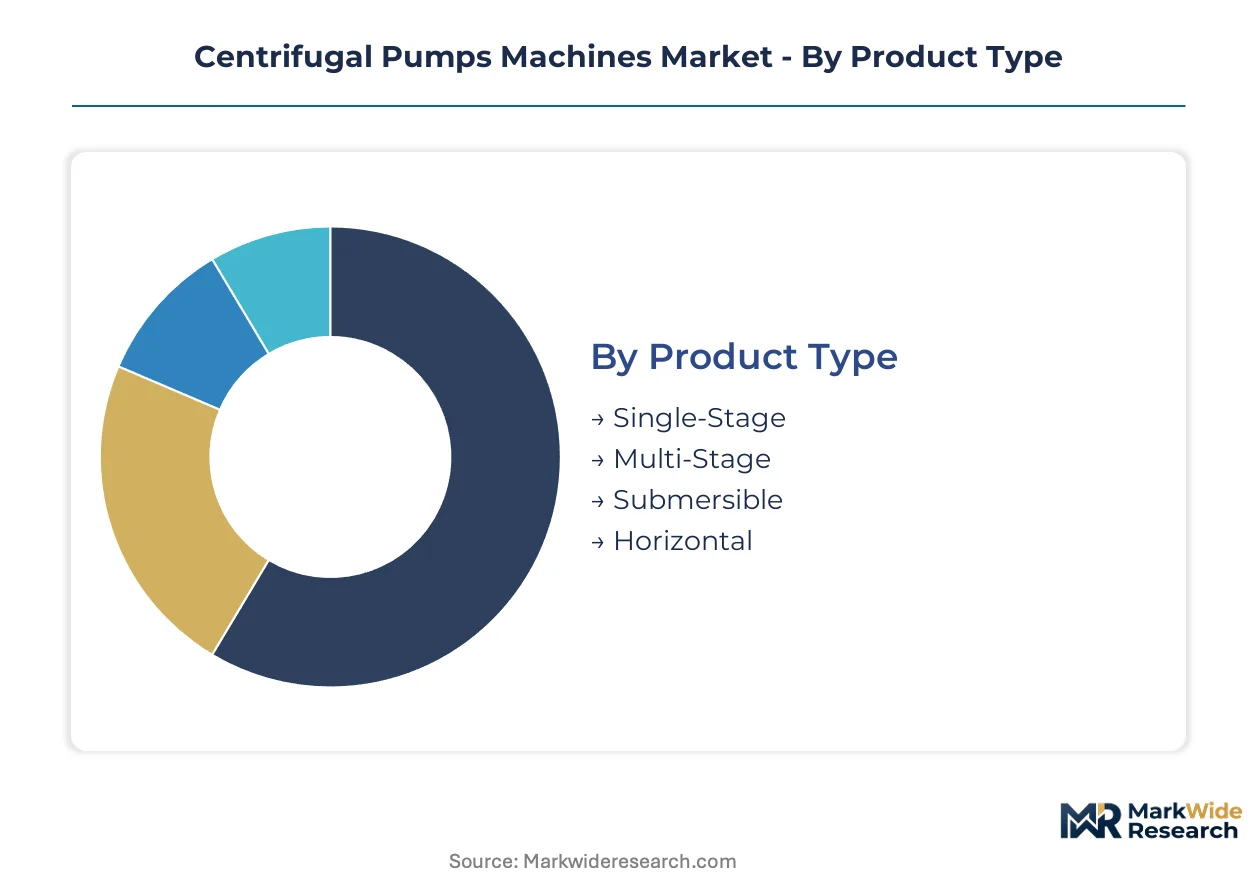
Centrifugal pump configurations vary dramatically in service intensity, with multi-stage municipal installations requiring predictive maintenance contracts while residential single-stage units operate on replace-rather-than-repair economics. Segmentation reveals where aftermarket revenue concentrates versus where low-touch distribution dominates.
Product Type:
After-sales service intensity diverges sharply across pump architectures, with submersible borehole installations demanding specialized retrieval equipment and horizontal split-case designs enabling in-situ bearing replacement.
- Multi-Stage:Stacked impeller arrays achieve discharge pressures exceeding 200 bar through sequential energy addition. Municipal water utilities in Germany and industrial boiler feed systems in India concentrate procurement here, driven by EU Ecodesign Directive efficiency mandates that filter non-compliant single-stage alternatives from premium tenders.
- Submersible:Hermetic motor-pump integration eliminates surface installation footprint and suction piping. Agricultural electrification programs in India and groundwater abstraction projects in China anchor demand, constrained by foundry capacity concentration in Southeast Asian casting supply chains facing environmental compliance shutdowns.
- Single-Stage:Single impeller designs dominate agricultural and residential water supply for simpler maintenance protocols.
- Horizontal:Split-case construction enables in-situ inspection without full disassembly, favored in large-flow municipal installations.
By volume, Single-Stage leads. By growth pace, Submersible is ahead.
Application:
Cost tier stratification separates specification-grade chemical processing pumps from price-sensitive agricultural equipment, with oil and gas project engineering commanding engineering-intensive procurement processes.
- Oil & Gas:API-compliant designs handle abrasive produced water and high-pressure injection duties. Upstream project engineering in the US and downstream refining in Germany concentrate demand, shaped by NHTSA-equivalent hazardous area certifications and ATEX compliance timelines that extend product launch cycles.
- Chemical Processing:Magnetic drive sealless technology eliminates leakage paths for emissions-sensitive fluid handling. EU REACH compliance and China's GB standards for pump energy efficiency jointly filter conventional sealed designs, with stainless steel impeller casting advances enabling thinner vane geometries.
- Water Supply:Municipal distribution networks and building services specify efficiency-optimized configurations.
- Agriculture:Solar-powered irrigation and flood irrigation systems prioritize capital efficiency over operating expense optimization.
By revenue concentration, Oil & Gas dominates. By regulatory tailwind, Chemical Processing is expanding most quickly.
End User:
Customer type determines procurement channel structure, with municipal utilities running multi-year framework agreements and residential segments fragmenting across e-procurement platforms.
- Municipal:Water authorities operate aging distribution networks requiring fleet replacement cycles for multi-stage and submersible configurations. Germany's utility sector and India's Maharashtra and Gujarat state water boards pilot multi-vendor service panels to reduce single-source dependency, constrained by legacy SCADA integration challenges with decades-old control systems.
- Industrial:Process plants specify predictive maintenance contracts with vibration sensor integration. Chemical processing facilities in the Netherlands and food manufacturing in Germany concentrate demand for digital monitoring convergence.
- Agricultural:BIS-certified pump sets for solar-powered irrigation represent underpenetrated demand as rural grid extension lags in India.
- Residential:Building services and small-scale water supply prioritize first-cost minimization over lifecycle efficiency.
By installed base, Municipal leads. By technology refresh rate, Industrial is climbing the fastest.
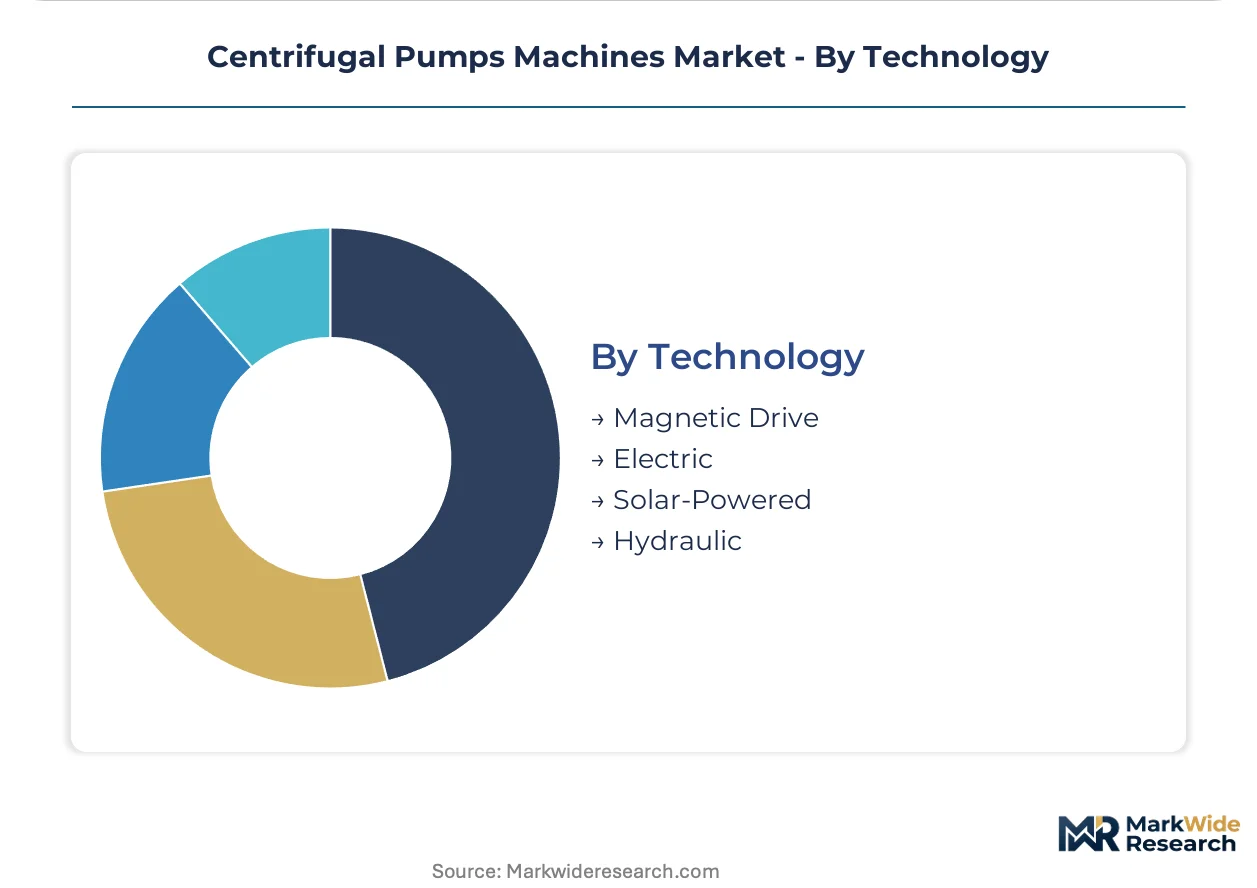
Technology:
Technology maturity curves separate established electric motor pairings from emerging solar-hybrid architectures, with magnetic drive adoption accelerating in emissions-regulated jurisdictions.
- Magnetic Drive:Sealless construction satisfies tightening emissions protocols across chemical processing and hazardous fluid handling. EU Ecodesign Directive and US Department of Energy conservation standards jointly compress conventional mechanical seal architectures, forcing incumbent manufacturers to retool casting and assembly lines.
- Solar-Powered:DC motor-pump integration eliminates grid dependency for remote agricultural abstraction. India's BIS certification requirements and agricultural electrification programs anchor demand, with solar resource availability determining economic viability versus diesel alternatives.
- Electric:Permanent magnet synchronous motors paired with variable frequency drives capture part-load efficiency gains in municipal water boosting stations.
- Hydraulic:Fluid power transmission serves specialized mobile and explosion-risk applications where electrical ignition sources are prohibited.
By current penetration, Electric leads. By policy alignment, Solar-Powered is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German municipal utilities command 15-20% pricing premiums over Indian state water boards for equivalent multi-stage specifications, reflecting divergent regulatory enforcement capacity and procurement sophistication. This asymmetry filters equipment tiers across geographies.
United States
Upstream oilfield reinjection and downstream refining anchor demand for API-compliant high-pressure configurations. The Department of Energy enforces minimum efficiency standards for clean water pumps under federal conservation regulations. Houston-Gulf Coast clusters concentrate project engineering capacity for Permian Basin developments.
Germany
Municipal water utilities operate aging distribution networks requiring predictive maintenance contracts with vibration sensor integration. The EU Ecodesign Directive mandates ecodesign requirements filtering non-compliant products from member state tenders. Ruhr Valley industrial corridors retrofit permanent magnet synchronous motor pairings into legacy boosting stations.
China
Groundwater abstraction projects and agricultural electrification programs drive submersible procurement volumes. GB standards for pump energy efficiency tighten disclosure requirements with MIIT-registered laboratory verification. Yangtze River Delta manufacturing bases accelerate in-house test loop investments to maintain municipal bidding eligibility.
India
Solar-powered irrigation and rural grid extension lag create underpenetrated demand for BIS-certified pump sets. The Bureau of Indian Standards certification requirements filter agricultural equipment specifications. Maharashtra and Gujarat state water boards pilot multi-vendor service panels to reduce single-source dependency in municipal procurement.
Netherlands
Food manufacturing and chemical processing facilities concentrate demand for magnetic drive sealless technology. REACH compliance and emissions protocols jointly compress conventional mechanical seal architectures. Rotterdam-Antwerp industrial corridors integrate digital monitoring platforms with cloud analytics for predictive maintenance contracts.
Centrifugal Pumps Machines Market Vendor Landscape
Integrated solution providers and specialized component fabricators split the market along service-intensity lines. The vendor base concentrates among European and Asian manufacturers with captive foundry networks or precision casting partnerships. Two archetypes dominate: full-lifecycle contractors capturing municipal framework agreements, and project-engineering specialists anchoring oil and gas procurement. Competitive moves center on digital monitoring convergence and magnetic drive technology licensing.
Within the full-lifecycle contractor tier, Grundfos and Xylem exemplify divergent strategic positioning. Grundfos anchors its position through captive service networks sustaining aftermarket revenue across municipal water contracts. Xylem occupies a position emphasizing digital monitoring integration with cloud analytics platforms. Flowserve Corporation sits within the project-engineering specialist archetype, anchoring oil and gas procurement through API-compliant design capabilities.
| Leading Market Players |
|---|
| Grundfos |
| Xylem |
| Flowserve Corporation |
| KSB SE & Co. KGaA |
| Sulzer |
| Wilo SE |
| Ebara Corporation |
| ITT Goulds Pumps |
| Pentair |
| Others |
Supply Flow & Price Mechanics
Cast iron and stainless steel cost volatility compresses margin pools for mid-tier OEMs and simultaneously widens pricing spreads between premium certified configurations and economy-tier alternatives, forcing procurement patterns toward long-term offtake contracts with foundry partners in Southeast Asia.
Pricing Analysis
Configured-to-order pricing for API-compliant multi-stage pumps commands 40-60% premiums over standard single-stage catalog units, with differentiation driven by ATEX/IECEx certification tiers and captive service bundling. Cost compression in the agricultural single-stage segment intensifies because Indian state water boards and rural electrification programs prioritize capital efficiency over lifecycle operating expense. Municipal utilities in Germany and the Netherlands exhibit lowest price sensitivity due to EU Ecodesign Directive compliance mandates that filter non-compliant economy alternatives from premium tenders.
Supply Chain Analysis
Upstream feedstock availability for precision investment casting draws from foundry networks concentrated in China, India, and Vietnam, with stainless steel impeller blanks and permanent magnet motor laminates serving as critical component dependencies. Single-source vulnerability concentrates in Southeast Asian casting supply chains facing intermittent environmental compliance shutdowns and energy rationing. Distribution runs through OEM-aligned channel partners consolidating around Grundfos and Xylem captive service networks, though e-procurement platforms gain share in residential and agricultural segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The centrifugal pumps machines market sits at a technology substitution inflection where magnetic drive sealless architectures displace conventional mechanical seal designs, creating asymmetric opportunity for early movers in emissions-regulated jurisdictions.
For Market Incumbents: Entrench municipal framework agreements through predictive maintenance contracts integrating vibration sensors and cloud analytics platforms, while deepening backward integration into precision stainless steel casting to defend margin position against magnetic drive substitution pressure from specialized chemical processing entrants.
For New Entrants and Emerging Players: Pursue solar-powered DC pump sets for BIS-certified agricultural irrigation in Maharashtra and Gujarat, where rural grid extension lags and state water boards pilot multi-vendor service panels to reduce single-source dependency, leveraging non-proprietary spare parts and standardized refurbishment protocols as the go-to-market angle.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors full-lifecycle contractors with captive foundry networks and digital monitoring integration capabilities, with long-term viability hinging on regulatory tailwinds from tightening EU Ecodesign Directive thresholds and US Department of Energy conservation standards; the signal to watch is foundry capacity acquisition activity in Yangtze River Delta and Ruhr Valley industrial corridors.
| Strategic Initiative | Industry Significance |
|---|---|
| Magnetic Drive Technology Licensing | Sealless construction satisfies EU REACH compliance and eliminates mechanical seal maintenance burden in chemical processing. |
| Backward Integration into Precision Casting | In-house stainless steel impeller production insulates margin pools from Southeast Asian foundry disruption risk. |
| Digital Monitoring Platform Integration | Cloud analytics convergence enables predictive maintenance contracts with German municipal water utilities. |
| Solar-Powered Pump Set Certification | BIS-certified DC motor-pump integration captures agricultural electrification demand in rural India. |
| Multi-Vendor Service Panel Participation | Standardized refurbishment protocols penetrate Maharashtra and Gujarat state water board procurement pilots. |
Methodological Framework
The analysis maps multi-stage, submersible, single-stage, and horizontal split-case configurations, each validated through maintenance directors at municipal water utilities, plant engineers at chemical processing facilities, OEM procurement teams, and aftermarket service heads at regional distributors. Primary fieldwork combined structured interviews with secondary validation against customs and trade data, SEC filings from listed pump manufacturers, EU Ecodesign Directive compliance registries, and BIS certification databases. Bottom-up unit economics triangulated against top-down market sizing across product type, application, end user, and technology dimensions.
Assumptions held fixed include current EU Ecodesign Directive efficiency thresholds, US Department of Energy conservation standards, and China's GB standards disclosure requirements, while raw material cost trajectories and foundry capacity utilization were varied across sensitivity scenarios. Segmentation modeling incorporated pump architecture, pressure rating tier, motor pairing technology, and regional regulatory cluster. CAGRs derived from installed base replacement cycles, infrastructure investment pipelines, and electrification program timelines.
Macroeconomic conditions sit as an overlay; deviation in construction activity indices, agricultural commodity prices, or central bank rate cycles would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement continuity and technology substitution pace. Cross-checking against MIIT-registered laboratory verification trends and municipal procurement award databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Radial Piston Pumps Market
Pumps and Control Devices
Cryogenic Pump Market
Pumps and Control Devices
Industrial ASME B73.1 Centrifugal Pumps Market
Pumps and Control Devices
Global Vacuum Pump Market
Pumps and Control Devices
Axial Piston Pumps Market
Pumps and Control Devices
Cone Penetrometer Market
Pumps and Control Devices
Rotating Equipment Market
Pumps and Control Devices
Domestic Booster Pump Market
Pumps and Control Devices
Fire Pump Test Meters Market
Pumps and Control Devices
India Industrial Pump Market
Pumps and Control Devices
Ultra High Pressure Water Pump Market
Pumps and Control Devices
Electrostatic Spraying System Market
Pumps and Control Devices
Asia-Pacific Peristaltic Pumps Market
Pumps and Control Devices
Subsea Pumping System Market
Pumps and Control Devices
Cooling Pump Market
Pumps and Control Devices
Axial and Mixed Flow Pumps Market