
 Chlorinated Polyolefin Adhesion Promoter Market | 2026-2036
Chlorinated Polyolefin Adhesion Promoter Market Size, Share, and Industry Trends Forecast 2026-2036
Chlorinated Polyolefin Adhesion Promoter Market Analysis
ISO 9001 quality management certification is bifurcating the competitive landscape into qualified suppliers and speculative entrants. BASF SE leverages its integrated polyolefin precursor chain to sustain cost advantages across chlorinated derivative grades. Evonik Industries AG anchors its position through specialized silane-modified chlorinated polyolefin architectures for electronics bonding. Eastman Chemical Company dominates solvent-based technology lanes with established automotive OEM qualification pathways.
Chlorinated polyolefin adhesion promoters comprise halogenated hydrocarbon resins manufactured through controlled free-radical chlorination of polyethylene or polypropylene feedstocks, typically achieving 20-40% chlorine content by weight to enable polar surface wetting on polypropylene and thermoplastic olefin substrates. These materials function as tie-layer chemistries enabling paint, adhesive, and coating adhesion on untreated low-surface-energy plastics across automotive interior and exterior component assembly. Chlorinated polypropylene variants lead product type demand owing to established automotive fascia and bumper substrate compatibility, while water-based technology represents the fastest-expanding segment as VOC regulations tighten across manufacturing jurisdictions. Modified polyolefins command premium positioning through grafted maleic anhydride functionality that expands substrate scope to engineered thermoplastics in electronics housings.
EPA VOC emissions standards under 40 CFR Part 59 constrain solvent-based formulation volumes in US coating applications, while REACH Annex XVII restrictions on chlorinated compound classifications shape product registration requirements across European manufacturing bases. China's GB standards for industrial coating VOC limits, administered by MEE, are accelerating domestic water-based technology substitution timelines. Stakeholders must monitor evolving substance hazard classifications under ECHA harmonized criteria and align R&D portfolios with low-halogen and bio-based adhesion chemistries before regulatory thresholds harden into market access barriers.
Market Dynamics
Automotive OEM qualification pathways for low-surface-energy plastic bonding are compressing supplier consolidation timelines as water-based formulations displace solvent-based incumbent technologies under tightening VOC mandates.
Growth Catalysts
- China GB Standard VOC Limits:MEE-administered industrial coating regulations are accelerating domestic water-based chlorinated polyolefin substitution timelines among local automotive paint manufacturers.
- Thermoplastic Olefin Substrate Expansion:Automotive fascia and bumper producers are expanding untreated polypropylene bonding specifications to reduce surface preparation costs in exterior component assembly.
- Electronics Housing Miniaturization:Engineered thermoplastics in consumer electronics are driving grafted maleic anhydride modified polyolefin demand for multi-material adhesion.
Market Restraints
- Feedstock Concentration Risk:Polyethylene and polypropylene precursor supply concentrates among integrated petrochemical complexes in the US Gulf Coast and Middle East, exposing derivative producers to feedstock allocation volatility.
- REACH Annex XVII Friction:ECHA harmonized hazard classifications for chlorinated compounds are extending product registration timelines and elevating compliance documentation burdens for European manufacturing bases.
- Water-Based Performance Gap:Aqueous chlorinated polyolefin formulations exhibit inferior wetting kinetics on highly crystalline polypropylene substrates versus solvent-based analogues, limiting full substitution in critical automotive applications.
Strategic Opportunities
- India Automotive Localization:PLI scheme incentives for domestic automotive component manufacturing are creating first-mover advantage windows for adhesion promoter suppliers establishing local technical service capabilities.
- Silane-Modified Architectures:Convergence of chlorinated polyolefin backbones with organosilane functionality is opening electronics bonding applications requiring moisture-cure adhesion to glass and metal substrates.
- Bio-Based Precursor Feedstocks:Renewable polyethylene derived from sugarcane ethanol is enabling halogenated resin producers to develop certified low-carbon footprint product lines for sustainability-mandated procurement.
Industry Challenges
- ISO 9001 Certification Bottleneck:Automotive OEM qualification protocols require 18-24 month quality management system audits, constraining speculative entrants from accessing tier-one supplier rosters.
- Free-Radical Chlorination Process Control:Maintaining 20-40% chlorine content uniformity across batch production demands specialized reactor engineering expertise that concentrates among legacy chlorinated resin specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chlorinated Polyolefin Adhesion Promoter Market |
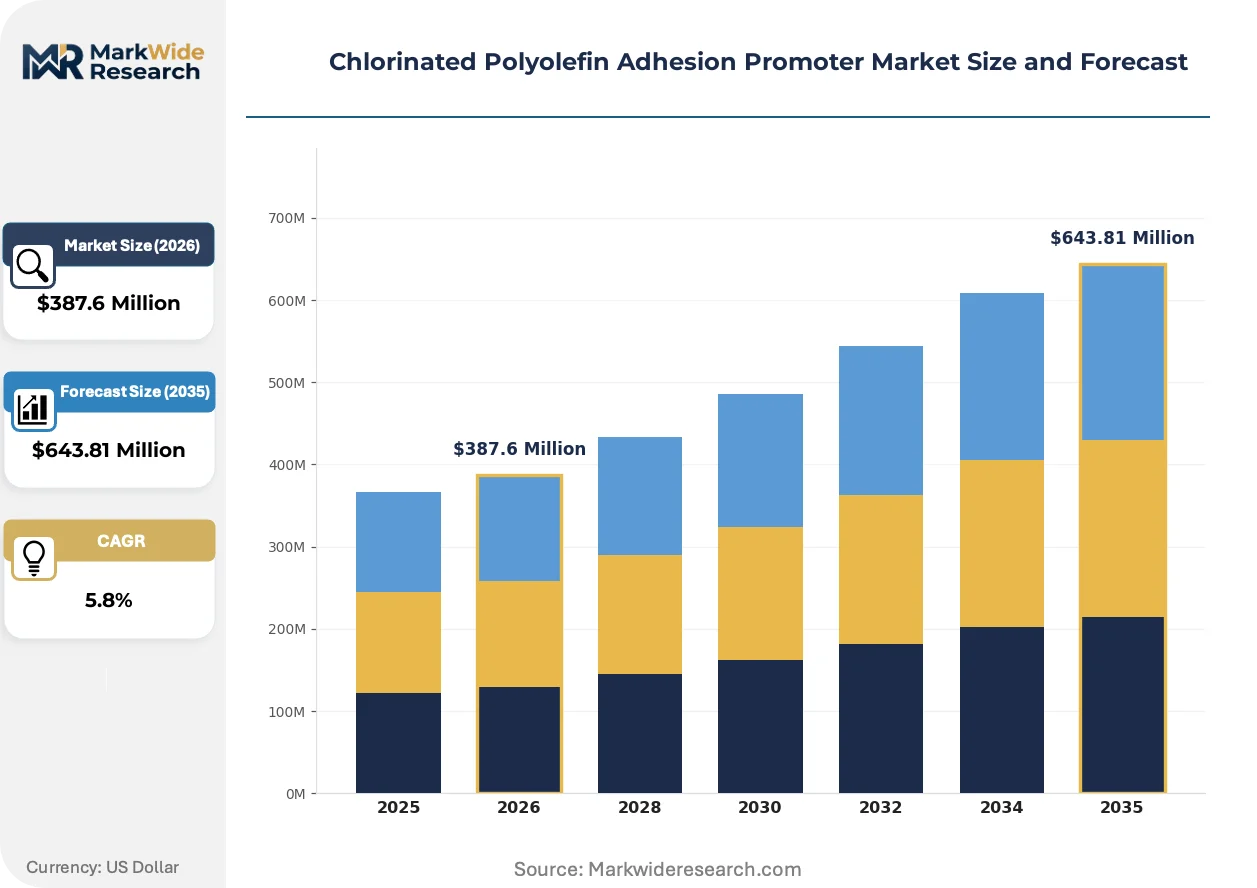
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $643.81 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chlorinated Polyethylene, Chlorinated Polypropylene, Modified Polyolefins, Elastomeric Adhesives End User: Automotive, Construction, Electronics, Packaging Application: Coatings, Sealants, Adhesives, Compounding Technology: Solvent-Based, Water-Based, Hot Melt, Reactive |
| Companies Covered | BASF SE, Evonik Industries AG, Momentive Performance Materials Inc, Air Products and Chemicals, Altana AG, Eastman Chemical Company, Arkema SA, AkzoNobel NV, Dow Corning Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chlorinated Polyolefin Adhesion Promoter Market Emerging Trajectories
Water-based formulation chemistry is decomposing the solvent-based technology hierarchy that has dominated automotive adhesion promotion for three decades, while regulatory VOC thresholds harden across manufacturing jurisdictions.
Aqueous chlorinated polypropylene dispersions are decomposing solvent-based incumbent positions in automotive interior component bonding. Tier-one seating and dashboard suppliers in Germany and Japan are adopting these formulations to meet OEM sustainability scorecards. The technology is decomposing historical solvent-based volume shares as MEE and EPA compliance deadlines approach.
REACH Annex XVII restrictions on chlorinated compound classifications are reshaping product registration requirements across European manufacturing bases. ECHA harmonized criteria are forcing reformulation investments toward reduced halogen content architectures. Water-based technology segments are capturing displaced solvent-based volumes as registration costs escalate for traditional chlorinated resin grades.
Automotive OEM procurement is consolidating adhesion promoter supply bases around qualified suppliers with integrated precursor chains. Tier-one paint manufacturers are eliminating secondary distributors to secure direct technical service relationships. This concentration is most visible in China where domestic automotive production scale demands localized formulation support.
Chlorinated Polyolefin Adhesion Promoter Market Segmentation
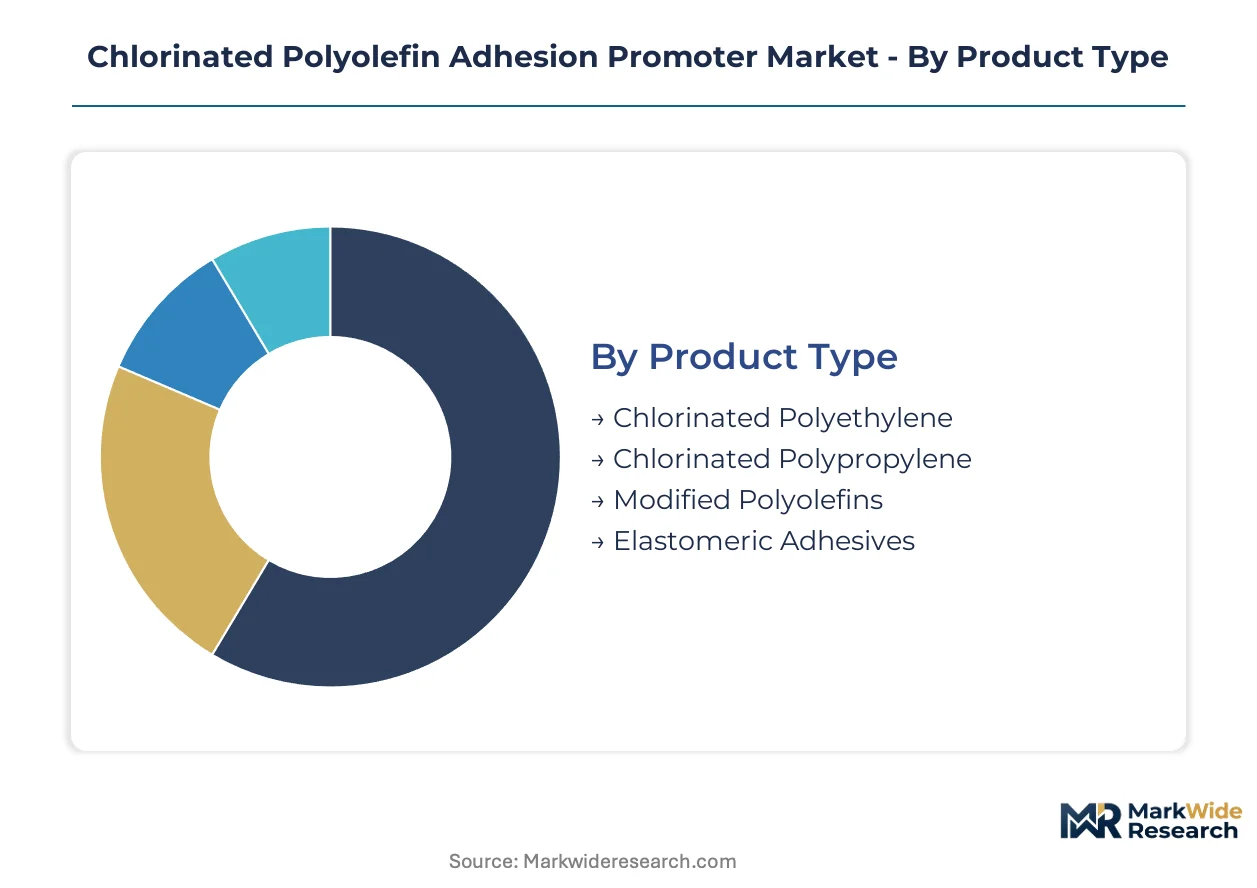
Segmentation in the chlorinated polyolefin adhesion promoter market reveals distinct margin architectures across product chemistry, application technology, and end-use verticals. Each category carries different qualification barriers, regulatory exposure, and growth trajectories that reshape supplier positioning.
Product Type:
Premium positioning concentrates in modified architectures where functional grafting commands formulation flexibility premiums.
- Chlorinated Polypropylene:Halogenated polypropylene resins achieving 20-40% chlorine content by weight deliver optimized surface wetting on untreated thermoplastic olefin substrates. Automotive fascia and bumper manufacturers in China specify these grades to eliminate flame or plasma surface preparation costs in exterior component assembly.
- Modified Polyolefins:Maleic anhydride grafted architectures expand substrate compatibility to engineered thermoplastics and metal oxides. Electronics housing miniaturization in Japan and South Korea is driving specification of these premium grades for multi-material bonding in consumer device enclosures.
- Chlorinated Polyethylene:Lower-cost halogenated polyethylene variants serve general industrial coating applications where substrate polarity requirements are moderate.
- Elastomeric Adhesives:Flexible chlorinated polyolefin formulations provide vibration-damping adhesion in automotive interior assemblies and construction membrane bonding.
Chlorinated polypropylene holds installed capacity. Modified polyolefins are rotating up the share rankings.
End User:
Qualification intensity varies sharply across verticals, with automotive OEM protocols creating the steepest barriers to supplier entry.
- Automotive:Untreated polypropylene bonding specifications for exterior fascias, bumpers, and interior trim dominate volume consumption. Tier-one paint manufacturers in Germany and Japan are consolidating supplier rosters around qualified partners with integrated precursor chains and localized technical service.
- Electronics:Miniaturized consumer device housings require silane-modified chlorinated polyolefin architectures for moisture-cure adhesion to glass and metal substrates. Evonik Industries anchors this niche through specialized organosilane functionalization.
- Construction:Membrane and roofing applications utilize elastomeric chlorinated polyolefin grades where flexibility and weathering resistance outweigh premium formulation costs.
- Packaging:Lower-specification bonding requirements in flexible packaging laminates concentrate demand in commodity chlorinated polyethylene grades.
Automotive maintains the deepest supplier relationships. Electronics is climbing the fastest as device complexity multiplies material interfaces.
Application:
Technology substitution patterns differ by application, with coatings experiencing the most acute water-based displacement pressure.
- Coatings:Automotive OEM paint systems represent the largest adhesion promoter consumption channel. Water-based chlorinated polypropylene dispersions are decomposing solvent-based incumbent positions as MEE-administered GB standard VOC deadlines approach in China.
- Adhesives:Structural bonding applications in electronics and automotive assembly favor reactive and hot-melt technologies where solvent content is already minimized or eliminated.
- Sealants:Construction and automotive seam sealing applications specify elastomeric chlorinated polyolefin grades for joint flexibility and substrate movement accommodation.
- Compounding:Masterbatch and polymer alloy formulations incorporate chlorinated polyolefins as compatibilizers in multi-polymer systems.
Coatings carries the heaviest regulatory transition burden. Adhesives is gaining share fastest as assembly technologies shift toward solvent-free curing systems.
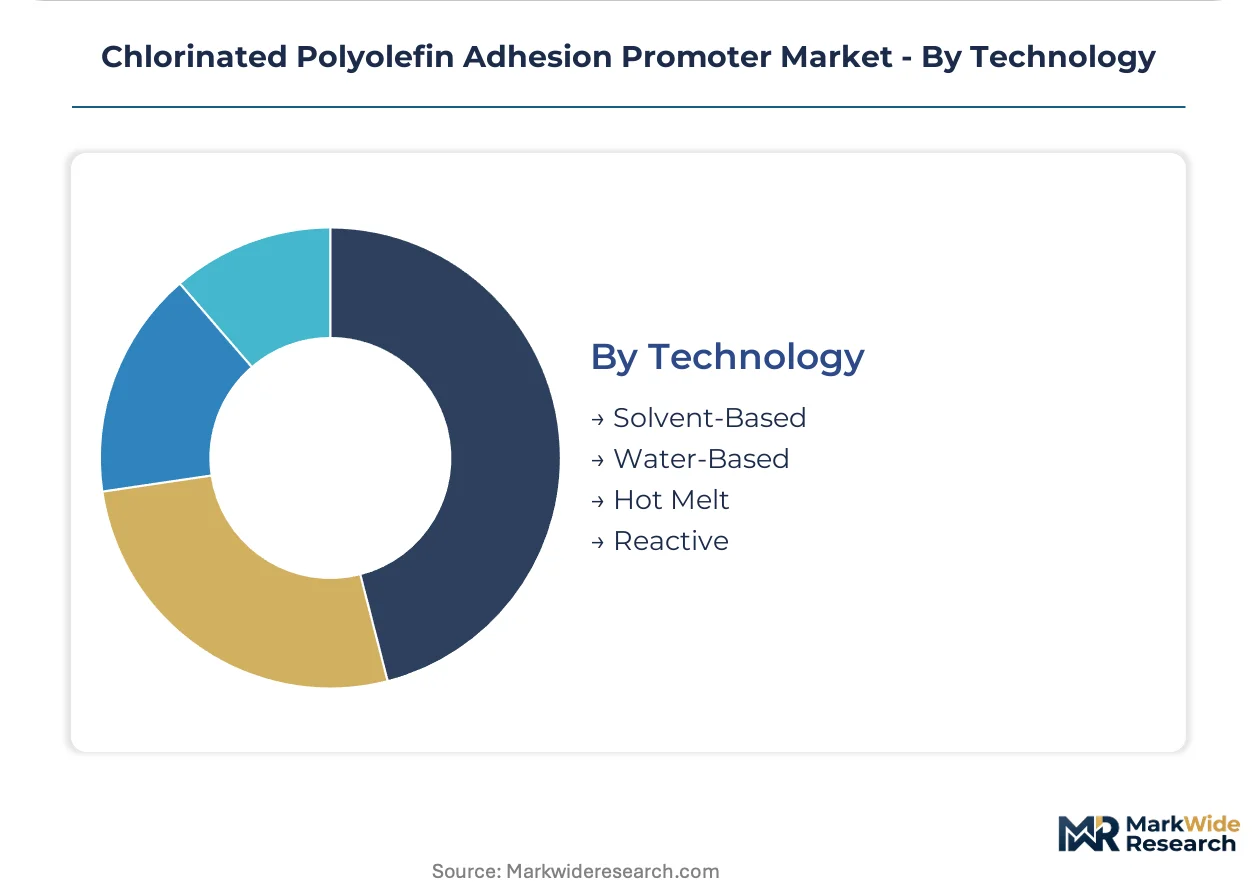
Technology:
Regulatory compliance timelines are compressing technology substitution windows, with water-based formulations capturing displaced solvent volumes.
- Water-Based:Aqueous chlorinated polyolefin dispersions achieve VOC compliance for automotive interior component bonding. Wetting kinetics limitations on highly crystalline polypropylene substrates constrain full substitution in critical exterior applications.
- Solvent-Based:Established automotive OEM qualification pathways and superior substrate wetting sustain incumbent positions despite EPA 40 CFR Part 59 and REACH Annex XVII pressure. Eastman Chemical dominates this lane through decades of tier-one supplier relationships.
- Hot Melt:Solvent-free application suits high-volume automotive interior assembly where thermal activation is compatible with substrate thermal stability.
- Reactive:Moisture-cure and UV-cure systems serve electronics and specialty automotive applications requiring precise cure control and minimal volatile content.
Solvent-based retains the deepest qualification heritage. Water-based is rotating up the share rankings as compliance deadlines harden across manufacturing jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive production incentives and tightening VOC regulations are redrawing regional demand maps for chlorinated polyolefin adhesion promoters. Production localization mandates and coating compliance deadlines are accelerating supplier facility investments across key manufacturing clusters.
China
Domestic automotive production scale and local coating manufacturer upgrades are concentrating demand in the Yangtze River Delta and Pearl River Delta regions. MEE-administered GB standards for industrial coating VOC limits are accelerating water-based technology substitution timelines. Shanghai and Guangzhou house the densest concentrations of tier-one automotive paint manufacturers qualifying new adhesion promoter suppliers.
Germany
Automotive OEM qualification protocols for exterior fascia bonding are sustaining demand for high-performance chlorinated polypropylene grades. REACH Annex XVII restrictions on chlorinated compound classifications are extending product registration timelines and elevating compliance documentation burdens. The Stuttgart and Munich industrial corridors host concentrated technical service operations supporting tier-one seating and dashboard suppliers.
United States
EPA VOC emissions standards under 40 CFR Part 59 are constraining solvent-based formulation volumes in coating applications across the Midwest and Southeast automotive belts. The US Gulf Coast concentrates polyethylene and polypropylene precursor supply among integrated petrochemical complexes. Detroit and Nashville automotive assembly clusters are driving specification of water-based alternatives for interior component bonding.
Japan
Miniaturized consumer electronics housings are driving grafted maleic anhydride modified polyolefin demand for multi-material adhesion in the Kanto and Kansai regions. METI industrial standards for chemical substance management are shaping product registration requirements for electronics-grade formulations. Osaka and Nagoya host specialized manufacturers supplying moisture-cure adhesion systems for glass and metal substrates.
India
PLI scheme incentives for domestic automotive component manufacturing are creating first-mover advantage windows for adhesion promoter suppliers establishing local technical service capabilities. BIS quality certification requirements are extending qualification timelines for imported formulations. Maharashtra and Tamil Nadu automotive clusters are attracting technical center investments from multinational suppliers seeking OEM qualification pathways.
Chlorinated Polyolefin Adhesion Promoter Market Vendor Landscape
Player mix skews toward integrated chemical conglomerates with captive polyolefin precursor supply and specialized modifiers serving electronics niche applications. Market structure concentrates around qualified suppliers with ISO 9001 certification and established automotive OEM relationships. Three archetypes dominate: integrated petrochemical majors controlling upstream resin supply, specialized adhesion chemistry houses with silane-modification expertise, and regional formulators serving local coating manufacturers. Competitive moves center on water-based technology licensing partnerships and precursor chain backward integration to secure feedstock allocation priority.
Within the integrated petrochemical tier, BASF SE and Eastman Chemical Company exemplify archetypes with upstream control over polyolefin feedstocks. Evonik Industries AG occupies a specialist position representing silane-modified chlorinated polyolefin architectures for electronics bonding applications. These three companies anchor the competitive structure through distinct capability configurations rather than overlapping market contestation.
| Leading Market Players |
|---|
| BASF SE |
| Evonik Industries AG |
| Momentive Performance Materials Inc |
| Air Products and Chemicals |
| Altana AG |
| Eastman Chemical Company |
| Arkema SA |
| AkzoNobel NV |
| Dow Corning Corporation |
| Others |
Supply Flow & Price Mechanics
Eighteen-to-twenty-four-month ISO 9001 certification lead times concentrate pricing power among qualified suppliers while compressing margins for speculative entrants seeking automotive OEM qualification pathways.
Pricing Analysis
Certification level creates the primary spread between premium and commodity tiers in this market. Three-tier pricing structure across qualified automotive-grade, standard industrial, and economy packaging-grade levels reflects qualification investment recovery timelines. Cost compression in solvent-based tiers is intensifying because REACH Annex XVII documentation burdens are escalating registration expenses. Tier-one automotive paint manufacturers exhibit lowest price sensitivity due to qualification lock-in effects, while regional coating formulators in emerging markets drive aggressive procurement negotiation.
Supply Chain Analysis
Inbound logistics costs from Middle East polyethylene and polypropylene feedstock sources through congested Asia-Europe container lanes are elevating working capital requirements for European formulation plants. Raw material supply concentrates in the US Gulf Coast, Saudi Arabia, and China, with chlorinated resin production drawing from captive petrochemical complex outputs. Feedstock allocation volatility represents the dominant structural risk as integrated majors prioritize derivative production during capacity constraints. Distribution runs through qualified technical service partnerships rather than commodity distributors, with tier-one automotive paint manufacturers demanding localized formulation support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: eighteen-to-twenty-four-month OEM qualification protocols create switching costs that protect incumbent positions from speculative challengers.
For Market Incumbents: Secure backward integration into polyolefin precursor supply to defend margin position against feedstock allocation volatility from Middle East and US Gulf Coast complexes. Prioritize water-based formulation R&D investments before MEE-administered GB standard VOC deadlines harden into market access barriers in China. Capacity addition in the Yangtze River Delta region captures localization mandates from domestic automotive production scaling.
For New Entrants and Emerging Players: Certification fast-track through BIS quality pathways in Maharashtra and Tamil Nadu automotive clusters offers the most penetrable entry wedge for India PLI scheme beneficiaries. Target electronics-grade silane-modified architectures where Evonik's specialized positioning leaves white space for moisture-cure adhesion alternatives. Technical service partnerships with domestic coating manufacturers in Guangzhou and Shanghai provide the essential go-to-market angle for water-based formulation qualification.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because automotive OEM procurement is eliminating secondary distributors to secure direct supplier relationships, concentrating volume among qualified partners with integrated precursor chains. Acquisition target archetype: regional formulators with established technical service capabilities in high-growth manufacturing clusters. The signal to watch is water-based technology licensing partnership announcements as compliance deadlines approach across manufacturing jurisdictions.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyolefin Feedstock | Captive precursor supply secures allocation priority during petrochemical complex capacity constraints. |
| Water-Based Formulation Scale-Up | MEE GB standard compliance positions suppliers for automotive interior component bonding specifications in China. |
| Silane-Modification R&D Investment | Organosilane functionalization opens electronics bonding applications requiring moisture-cure adhesion systems. |
| Regional Technical Center Establishment | Localized formulation support satisfies tier-one paint manufacturer demands for direct OEM qualification pathways. |
| Long-Term Supply Agreement with Automotive OEMs | Contractual volume commitments protect qualified supplier positions from procurement roster consolidation. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with plant managers at chlorinated resin production facilities, procurement leads at tier-one automotive paint manufacturers, and technical R&D directors at formulation houses; and secondary validation through customs and trade data, ACC and Cefic industry reports, and SEC 10-K filings from integrated petrochemical majors. Bottom-up demand modeling from end-use application specifications was triangulated against top-down capacity assessments from polyolefin precursor supply analysis.
Across the projection horizon, the analytical framework segmented volume and value outputs by product chemistry grade, application technology, end-use vertical, and regional manufacturing hub. CAGRs were derived from regression analysis of historical qualification timeline compression and technology substitution patterns. Forecast inputs incorporated REACH Annex XVII registration cost trajectories and MEE VOC compliance deadline enforcement intensity.
Underlying assumptions cover sustained automotive OEM qualification protocol rigidity and water-based formulation performance gap closure rates, with deviation risk concentrated in regulatory enforcement timing and feedstock allocation priority shifts at integrated petrochemical complexes. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Amine Curing Agents Market
Adhesives & Sealants
Global Dimer Acid Market
Adhesives & Sealants
Asia-Pacific Bone Glue Market
Adhesives & Sealants
Europe Hot-Melt Adhesives Market
Adhesives & Sealants
Silane Coupling Agents Market
Adhesives & Sealants
China Adhesives Market
Adhesives & Sealants
Global Anti-Tack Agents Market
Adhesives & Sealants
Polyurethane Adhesives and Sealants Market
Adhesives & Sealants
India Adhesives and Sealants Market
Adhesives & Sealants
Europe Human Fibrin Glue Market
Adhesives & Sealants
Global Electronics Adhesives Market
Adhesives & Sealants
Epoxy Putty and Construction Chemicals Market
Adhesives & Sealants
Wood to Metal Glue Market
Adhesives & Sealants
Gelatin Bone Glue Market
Adhesives & Sealants
De-Seamable Adhesives Market
Adhesives & Sealants
Epoxy Glue Market