
 Silane-Modified Polymers Market | 2026-2036
Silane-Modified Polymers Market Size, Share, and Industry Trends Forecast 2026-2036
Silane-Modified Polymers Market Outlook
Asset-light leasing models for specialty polymer production capacity are tilting competitive dynamics toward firms that can access toll manufacturing without heavy balance-sheet investment. Wacker Chemie AG leverages its integrated silane and polymer operations to sustain margin capture across the value chain. Dow Inc. anchors North American supply through proprietary silyl-modified polyether chemistry. Momentive Performance Materials Inc. specializes in silicone-silane hybrid platforms that differentiate performance in moisture-cure applications.
Silane-modified polymers are hybrid organic-inorganic materials formed by grafting alkoxysilane groups onto polymer backbones such as polyurethanes, polyethers, or polyacrylates, enabling moisture-cured crosslinking without isocyanate content. These materials function primarily as high-performance adhesives, sealants, and coatings where durability, elasticity, and substrate adhesion are critical. The sealants category leads volume consumption in construction joint applications across European and East Asian infrastructure projects. Water-based technology is gaining fastest in regulatory-sensitive regions where solvent emissions face restriction. Hot-melt formulations occupy niche positions in automotive assembly where rapid green-strength development justifies premium positioning.
EMA's Medical Device Regulation and REACH substance restrictions in Europe are elevating purity requirements for silane-modified materials entering healthcare and consumer-contact applications. EPA TSCA Section 5 premanufacture notification requirements in the United States shape new product introduction timelines and testing burdens. China's SAMR oversees national standards for construction chemical safety that directly affect adhesive and sealant formulation approvals. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions, as fluorinated silane chemistries face scrutiny that could redirect R&D investment toward non-fluorinated alternatives.
Market Dynamics
Moisture-cure chemistry is displacing isocyanate-based systems across transportation and electronics assembly, driven by occupational safety mandates and VOC emission ceilings in manufacturing clusters.
Growth Catalysts
- Electric vehicle battery encapsulation:Automotive manufacturers in Germany and Japan are expanding silane-modified adhesive use in thermal management and cell bonding applications. This end-use vertical commands premium formulation specifications.
- REACH substance restrictions:ECHA's tightening controls on isocyanate exposure are accelerating reformulation timelines across European construction sealant producers. Compliance deadlines are compressing supplier qualification windows.
- Semiconductor packaging operations:South Korean and Japanese electronics hubs are scaling moisture-cure encapsulants for advanced chip protection. Display manufacturing clusters in East Asia are specifying hybrid silane-silicone platforms.
Market Restraints
- Silane monomer supply concentration:Specialty silane feedstock production clusters in Germany and China create geographic vulnerability for formulators lacking backward integration into alkoxysilane precursors.
- Moisture sensitivity in logistics:Premature crosslinking during transport and storage limits distribution radius and requires climate-controlled supply chain infrastructure.
- Hot-melt polyurethane competition:Reactive hot-melt systems are capturing automotive assembly applications where rapid green-strength development outweighs durability advantages of silane-cure chemistry.
Strategic Opportunities
- Water-based formulation expansion:China's GB standards for volatile organic compound emissions are creating first-mover advantage for aqueous silane-modified systems in construction adhesives.
- Medical device encapsulation:EMA's Medical Device Regulation is elevating purity requirements that favor silane-modified materials with documented biocompatibility profiles.
- Photovoltaic module sealing:Dual carbon goals under China's MEE are mandating durable edge-seal materials for solar panel longevity in harsh climate exposure.
Industry Challenges
- Formulation chemist scarcity:Hybrid organic-inorganic polymer expertise sits concentrated at legacy silane producers, constraining new entrant R&D velocity.
- Multi-regulatory certification burden:EPA TSCA Section 5 premanufacture notification requirements in the United States and SAMR construction chemical approvals in China impose parallel testing timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silane-Modified Polymers Market |
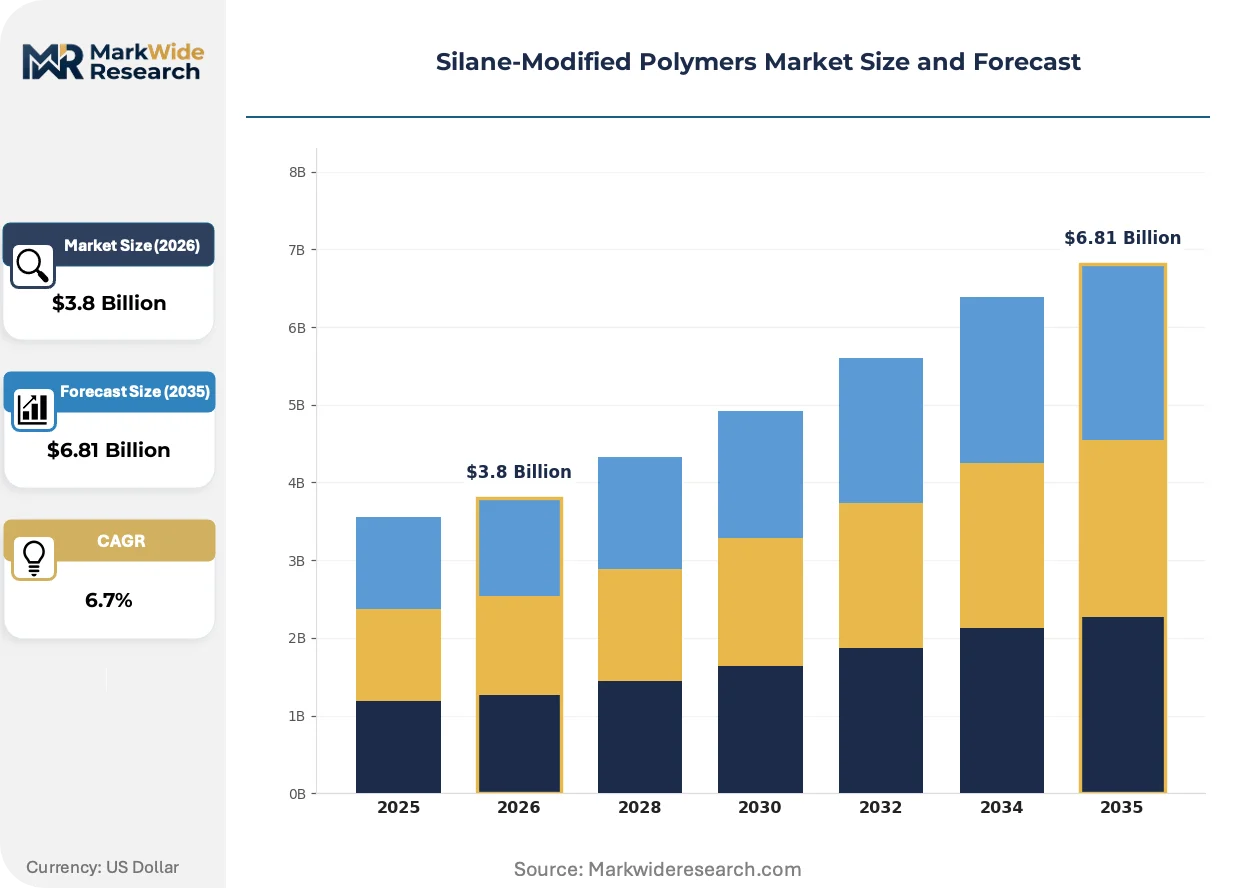
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coatings, Sealants, Adhesives, Compounds Application: Construction, Automotive, Electronics, Aerospace End User: Manufacturers, Contractors, Distributors, Retailers Technology: Solvent-Based, Water-Based, Hot-Melt, UV-Cured |
| Companies Covered | Dow Inc., Henkel AG & Co. KGaA, Wacker Chemie AG, BASF SE, Sika AG, Evonik Industries AG, Shin-Etsu Chemical Co., Ltd., 3M Company, Momentive Performance Materials Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silane-Modified Polymers Market Strategic Shifts
Formulation science is converging around low-emission, high-durability platforms that satisfy divergent regulatory regimes while enabling thinner application profiles in electronics miniaturization.
Silicone-silane hybrid chemistry is hybridizing performance characteristics of both material classes, combining silicone elasticity with silane substrate adhesion. Japanese display manufacturers and South Korean semiconductor packagers are adopting these platforms at accelerated qualification paces. The technology is hybridizing competitive positioning between pure silicone and conventional polyurethane suppliers.
Europe's F-Gas Regulation is restricting fluorinated gas use in industrial processes, indirectly pressuring fluorinated silane intermediate availability. Formulators are accelerating non-fluorinated silane R&D to preempt supply disruption. Construction sealant producers serving German infrastructure projects are most affected, with some redirecting toward alkyl-functional silane alternatives.
Buyer consolidation among tier-one automotive OEMs is compressing supplier qualification cycles and demanding integrated adhesive-substrate testing protocols. Traditional distribution through regional chemical distributors is giving way to direct technical service relationships. This pattern is most visible in German and Japanese electric vehicle supply chains, where battery encapsulation specifications are set at the platform engineering stage.
Silane-Modified Polymers Market Segmentation
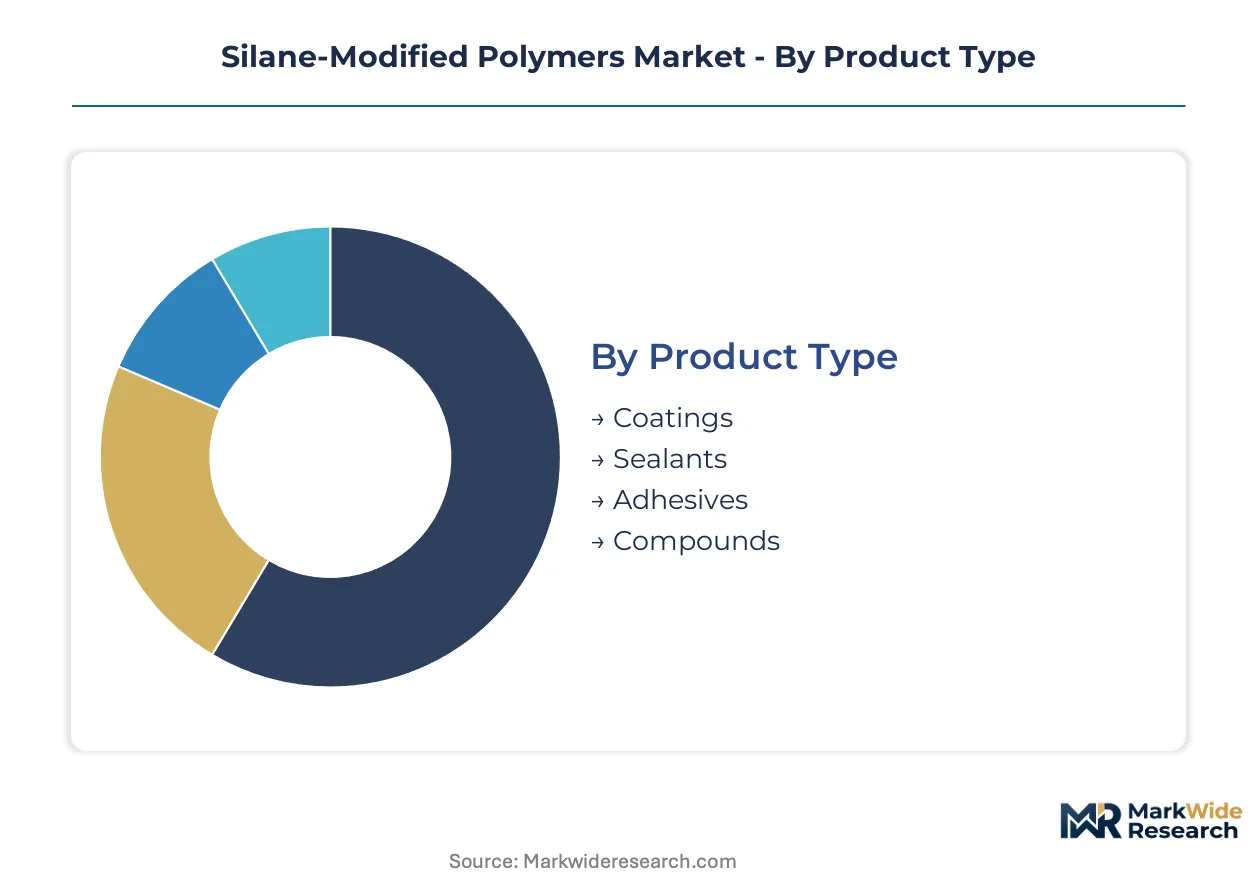
Silane-modified polymers serve divergent performance requirements across moisture-cure chemistries and application environments. Segmentation reveals where formulation complexity commands premium positioning versus where standardization enables volume scale.
Product Type:
Sealants turn inventory fastest in infrastructure maintenance cycles, while coatings extend longest through capital-intensive industrial specifications.
- Sealants:These moisture-cure formulations dominate construction joint applications with elastic recovery specifications. Demand concentrates in German infrastructure rehabilitation and Japanese seismic-resistant building codes where durability under cyclic loading is non-negotiable. REACH substance restrictions on isocyanates are accelerating specification shifts toward silane-cure alternatives in European commercial construction.
- Adhesives:High-strength bonding platforms enable electric vehicle battery encapsulation with thermal management properties. German and Japanese automotive OEMs are expanding direct technical service relationships for platform-level adhesive qualification, compressing traditional distribution channels.
- Coatings:Protective films for industrial substrates requiring chemical resistance and UV stability.
- Compounds:Specialized molding and encapsulation materials for electronics protection.
Sealants dominate installed base. Adhesives are where expansion concentrates.
Application:
Margin structure varies sharply: automotive commands formulation premiums while construction rewards logistics efficiency at scale.
- Construction:Joint sealing and waterproofing applications drive volume consumption across European and East Asian infrastructure. China's GB standards for volatile organic compound emissions are redirecting specification toward water-based silane-modified systems in commercial building projects.
- Automotive:Battery encapsulation and structural bonding applications carry the most stringent qualification protocols. German electric vehicle manufacturers are setting adhesive specifications at platform engineering stage, bypassing tier-two component suppliers.
- Electronics:Semiconductor packaging and display manufacturing in South Korea and Japan specify hybrid silane-silicone platforms for moisture-cure encapsulation with miniaturization tolerance.
- Aerospace:Lightweight structural bonding with flame-retardant certification requirements.
Construction holds the deepest installed base. Electronics represents the steepest expansion trajectory.
End User:
Procurement authority is consolidating: direct manufacturer relationships are displacing distributor intermediaries in technical applications.
- Manufacturers:OEMs and tier-one suppliers with in-house formulation specification authority and integrated substrate testing protocols. German and Japanese automotive battery producers are compressing supplier qualification cycles through platform-level engineering engagement.
- Contractors:Installation specialists purchasing through regional distribution for construction sealant applications.
- Distributors:Chemical and building products wholesalers serving mid-market formulators and regional contractors.
- Retailers:Consumer and light commercial channels for maintenance-grade sealant products.
Manufacturers capture the highest-value procurement. Distributors retain volume concentration in construction spot markets.
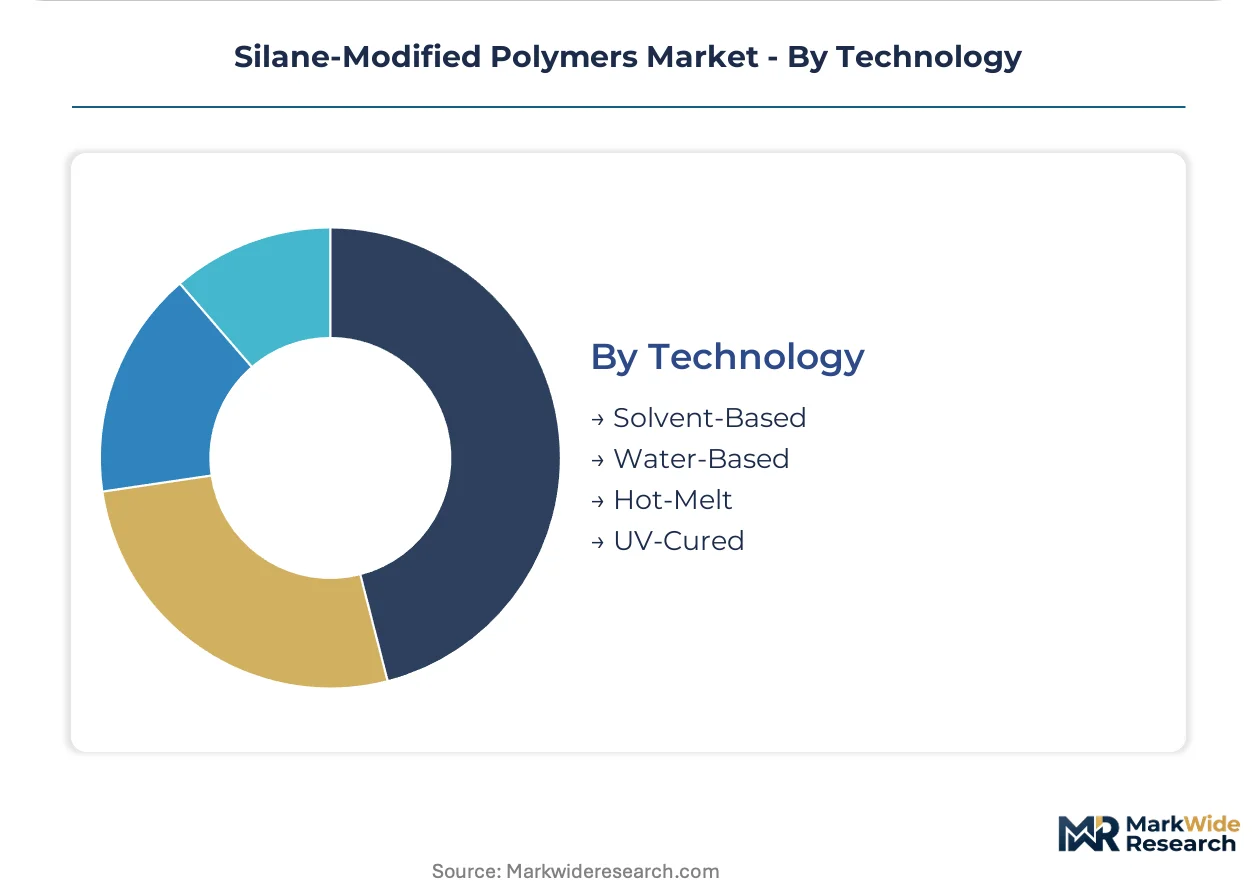
Technology:
Regulatory pressure is resequencing technology adoption curves across regional emission frameworks.
- Water-Based:Aqueous dispersions with silane crosslinking functionality are gaining fastest in regulatory-sensitive regions. China's GB VOC emission standards and REACH compliance requirements in Europe are creating first-mover advantage for aqueous systems in construction adhesives and sealants.
- Solvent-Based:Traditional high-performance formulations with established supply chains and application familiarity. These systems face declining specification share where emission restrictions tighten, though they retain position in automotive applications where rapid processing justifies controlled environment use.
- Hot-Melt:Reactive systems with rapid green-strength development for automated assembly lines.
- UV-Cured:Photoinitiated crosslinking for electronics miniaturization with precise thickness control.
Solvent-based systems retain the broadest installed base. Water-based platforms are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive OEMs and Japanese electronics manufacturers concentrate the highest-value procurement authority for silane-modified polymers, while Chinese construction chemical demand drives volume scale.
Germany
Electric vehicle battery encapsulation specifications from BMW and Volkswagen are accelerating direct technical service relationships with adhesive suppliers. REACH substance restrictions on isocyanate exposure are compressing reformulation timelines for construction sealant producers. The Rhine-Ruhr industrial corridor hosts Wacker Chemie's integrated silane-polymer operations serving both automotive and building chemical markets.
China
GB standards for volatile organic compound emissions are redirecting construction adhesive specifications toward water-based silane-modified systems. SAMR construction chemical safety approvals are lengthening formulation registration timelines for imported products. The Yangtze River Delta manufacturing belt concentrates photovoltaic module sealing demand under MEE dual carbon goals mandating durable edge-seal materials.
Japan
Display manufacturers in Osaka and semiconductor packagers in Tokyo are qualifying hybrid silane-silicone platforms for moisture-cure encapsulation. METI industrial standards are elevating purity requirements for electronics-grade materials. The Chubu region around Nagoya anchors automotive adhesive development for Toyota and Honda electric vehicle platforms.
United States
EPA TSCA Section 5 premanufacture notification requirements are shaping new product introduction timelines for specialty polymer entrants. Dow Inc.'s proprietary silyl-modified polyether chemistry anchors North American supply for transportation and industrial applications. The Gulf Coast petrochemical corridor provides alkoxysilane feedstock access for formulators serving automotive assembly plants in Michigan and Ohio.
South Korea
Samsung and SK Hynix semiconductor packaging operations are scaling moisture-cure encapsulants for advanced chip protection. MFDS medical device regulations are elevating biocompatibility documentation requirements for healthcare applications. The Seoul Capital Area concentration of electronics manufacturing is compressing supplier qualification cycles through integrated substrate testing protocols.
Silane-Modified Polymers Market Competitive Environment
Channel-controlling players compete with product-specialist players across divergent route-to-market strategies. Integrated chemical conglomerates with captive silane production anchor supply security, while formulation-focused firms compete on application-specific technical service. Three archetypes dominate: backward-integrated silane producers, proprietary chemistry developers, and silicone-silane hybrid specialists. Competitive moves concentrate on toll manufacturing partnerships and direct OEM technical engagement.
Among German-based integrated producers, Wacker Chemie AG exemplifies the backward-integrated archetype spanning alkoxysilane precursors through finished polymers. Dow Inc. represents North American proprietary chemistry developers with silyl-modified polyether platforms. Momentive Performance Materials Inc. occupies the silicone-silane hybrid specialist position, differentiating moisture-cure applications through combined material class performance.
| Leading Market Players |
|---|
| Dow Inc. |
| Henkel AG & Co. KGaA |
| Wacker Chemie AG |
| BASF SE |
| Sika AG |
| Evonik Industries AG |
| Shin-Etsu Chemical Co., Ltd. |
| 3M Company |
| Momentive Performance Materials Inc. |
| Others |
Value Chain & Pricing Dynamics
Rhine-Ruhr freight corridors linking Wacker Chemie's integrated silane-polymer operations to German automotive OEMs impose climate-controlled logistics costs that amplify price spreads between specialty formulations and commodity alternatives. REACH compliance investments and silane monomer supply concentration in Germany and China create asymmetric pricing power across the value chain.
Pricing Analysis
Cost-plus contracts with methanol and alkoxysilane feedstock indexation dominate long-term supply agreements between integrated producers and automotive OEMs. Three-tier pricing structure across premium, standard, and economy levels separates battery encapsulation formulations with thermal management certification from construction sealants and maintenance-grade products. Pricing pressure stems from hot-melt polyurethane competition in automotive assembly where rapid green-strength development commands processing efficiency premiums. Tier-one automotive manufacturers exhibit lowest price sensitivity due to platform-level engineering specifications, while regional construction contractors purchasing through distributors face compressed margins and volume-driven negotiation leverage.
Supply Chain Analysis
Toll manufacturing concentration among German chemical processors and Chinese construction chemical specialists shapes capacity access for non-integrated formulators. Specialty silane feedstock production clusters in Germany and China, with alkoxysilane precursor supply anchored in the Rhine-Ruhr industrial corridor and Yangtze River Delta manufacturing belt, create geographic vulnerability for formulators lacking backward integration. Raw material dependencies center on methanol-derived silane monomers, polyurethane polyols, and polyether backbones. Single-source vulnerability in electronics-grade silane intermediates for South Korean semiconductor packaging operations poses structural risk. Distribution runs through direct technical service relationships with OEMs for automotive and electronics applications, while regional chemical distributors retain construction sealant volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among tier-one automotive OEMs and South Korean electronics manufacturers, compressing supplier qualification cycles and displacing traditional distributor intermediaries with integrated substrate testing protocols.
For Market Incumbents: Pre-empt formulation chemist scarcity by securing exclusive toll manufacturing partnerships with German and Chinese alkoxysilane producers, locking in feedstock security against REACH substance restrictions and ECHA isocyanate exposure controls that accelerate reformulation timelines. Invest in water-based platform certification under China's GB VOC standards to capture first-mover advantage in construction adhesives before regulatory deadlines compress competitor windows. For New Entrants and Emerging Players: Pursue medical device encapsulation white space where EMA Medical Device Regulation purity requirements and MFDS biocompatibility documentation create qualification barriers favoring documented silane-modified materials over incumbent silicone suppliers. Target South Korean semiconductor packaging operations through direct technical engagement with Samsung and SK Hynix, leveraging integrated substrate testing protocols as the go-to-market angle to bypass established distribution channels. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with stranded silane-modified polymer assets lacking platform-level automotive engagement. Long-term viability hinges on backward integration into alkoxysilane precursors or proprietary hybrid chemistry positions that survive buyer consolidation. Monitor qualification pace of hybrid silane-silicone platforms in Japanese display manufacturing as inflection indicator for technology substitution risk against pure silicone incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alkoxysilane Precursors | Wacker Chemie's captive silane supply anchors margin capture across German automotive and construction markets. |
| Water-Based Formulation Certification | China's GB VOC standards create first-mover positioning for aqueous systems in commercial building projects. |
| Direct OEM Technical Engagement | BMW and Volkswagen battery platform specifications demand integrated adhesive-substrate testing protocols. |
| Hybrid Silane-Silicone Platform Development | Japanese display manufacturers and South Korean semiconductor packagers accelerate qualification of combined material performance. |
| Toll Manufacturing Partnership Expansion | Asset-light capacity access enables specialty formulators to compete without heavy balance-sheet investment in production infrastructure. |
Study Parameters
Operator-level perspectives from plant managers at integrated silane producers, procurement leads at German automotive OEMs, technical R&D directors at construction chemical formulators, and distribution channel partners in East Asian electronics hubs anchored the qualitative base. Primary interviews combined with secondary validation from customs and trade data, ACC and Cefic industry reports, EPA TSCA Section 5 filings, and SAMR construction chemical registration databases. Bottom-up segment sizing triangulated against top-down macroeconomic drivers across the analysis window.
Scenario-bracketing framed demand projections across product type, application vertical, technology platform, and regional regulatory cluster dimensions. CAGRs derived from elasticity-adjusted volume trajectories incorporating electric vehicle battery encapsulation adoption curves, REACH reformulation timelines, and semiconductor packaging technology shifts. Forecast inputs included silane monomer supply capacity announcements, OEM platform engineering schedules, and GB standards implementation enforcement patterns.
Macroeconomic conditions sit as an overlay; deviation in automotive production cycles, construction spending in China, or electronics capital expenditure would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement pace and technology substitution thresholds. Quarterly review of OEM platform engineering schedules, ECHA substance restriction proposal timelines, and MFDS medical device regulation guidance updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Thermoplastic Starch (TPS) Market
Polymers & Resins
Global Polyphenylene Market
Polymers & Resins
Global Amorphous Polyalphaolefin (APAO) for Hot Melt Market
Polymers & Resins
Silyl Acrylate Polymer (SAP) Market
Polymers & Resins
Flame Retardant Thermoplastics Market
Polymers & Resins
Polypropylene Copolymer Market
Polymers & Resins
Global Cyclic Olefin Copolymers Market
Polymers & Resins
Cyclic Olefin Polymers (COP) Polymer Syringes Market
Polymers & Resins
Global Encapsulation Resins Market
Polymers & Resins
Bio-Polybutadiene Market
Polymers & Resins
Europe Polyolefin Foam Market
Polymers & Resins
Global Chromatography Resin Market
Polymers & Resins
EVA Resins and Films Market
Polymers & Resins
Asia-Pacific Thermoplastics Market
Polymers & Resins
Polyvinyl Butyral (PVB) Market
Polymers & Resins
Global Vinyl Ester Market