
 Europe Human Fibrin Glue Market | 2026-2036
Europe Human Fibrin Glue Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Human Fibrin Glue Market Foresight
The EU Green Deal is broadening sustainability requirements across medical device supply chains, pushing hospitals toward biocompatible hemostatic products with lower environmental footprints. Grifols, S.A. leverages its plasma fractionation infrastructure to secure raw material access across Iberia. Baxter International Inc. anchors its position through hospital contracting networks in Northern Europe. B. Braun Melsungen AG differentiates via integrated manufacturing of surgical sealants and delivery systems.
Human fibrin glue comprises concentrated human fibrinogen and thrombin components that polymerize upon mixing to form a biodegradable clot matrix, typically containing aprotinin to slow fibrinolysis and calcium chloride to accelerate coagulation. The product serves primarily as a topical hemostatic agent and tissue adhesive in operative settings where conventional suture or cautery techniques prove insufficient. Fibrin sealants dominate current hospital procurement due to established reimbursement codes and surgeon familiarity, while fibrin gels capture expanding interest in orthopedic applications for cartilage repair and bone graft fixation. Spray delivery systems lead volume deployment in cardiac and general surgery suites, though pre-filled syringe formats gain traction in ambulatory settings where preparation time directly affects throughput economics.
EMA oversight through the Medical Device Regulation framework governs clinical evidence requirements and post-market surveillance, while REACH compliance affects chemical component sourcing and disposal protocols for thrombin stabilizers. National health technology assessment bodies in France, Germany, and England apply divergent cost-effectiveness thresholds that fragment pricing and access across the region. Stakeholders must monitor evolving MDR transition timelines and HTA convergence discussions to anticipate reimbursement headwinds in priority markets.
Market Dynamics
The EU MDR transition is compressing manufacturer timelines and consolidating procurement power among hospital networks that demand higher clinical evidence thresholds for hemostatic sealants. This regulatory pressure is reshaping competitive positioning across the continent.
Growth Catalysts
- Cardiac surgery expansion:German and French hospital systems are standardizing fibrin sealant protocols in open-heart procedures, creating pull-through demand for adjacent specialties.
- REACH compliance acceleration:Chemical component traceability requirements are favoring established suppliers with documented supply chain audit trails across Iberia and the Nordics.
- Ambulatory surgical center proliferation:Italy and Spain are licensing standalone day-surgery facilities where pre-filled syringe formats reduce preparation overhead and improve throughput economics.
Market Restraints
- Plasma fractionation concentration:Raw fibrinogen supply depends on a limited number of EU-licensed blood processing facilities, creating geographic single-point vulnerability.
- MDR clinical evidence costs:The Medical Device Regulation mandates expanded post-market surveillance studies that disproportionately burden mid-tier manufacturers.
- Synthetic sealant substitution:Polyethylene glycol-based adhesives are capturing select general surgery applications where immunogenicity concerns drive material preference shifts.
Strategic Opportunities
- Eastern European underpenetration:Poland and Romania maintain lower fibrin sealant utilization rates per capita than Western benchmarks, presenting volume expansion potential.
- Orthopedic cartilage repair:Fibrin gel formulations are displacing mechanical fixation in microfracture procedures and autologous chondrocyte implantation protocols.
- EU Green Deal biocompatibility mandates:Sustainability scoring in public procurement is favoring biodegradable hemostatic products over synthetic alternatives in Nordic hospital tenders.
Industry Challenges
- MDR notified body capacity:Certification backlog at designated conformity assessment organizations is extending product registration timelines by twelve to eighteen months.
- Cold chain integrity:Fibrinogen component stability requirements demand specialized logistics infrastructure that fragments distribution economics in peripheral markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Human Fibrin Glue Market |
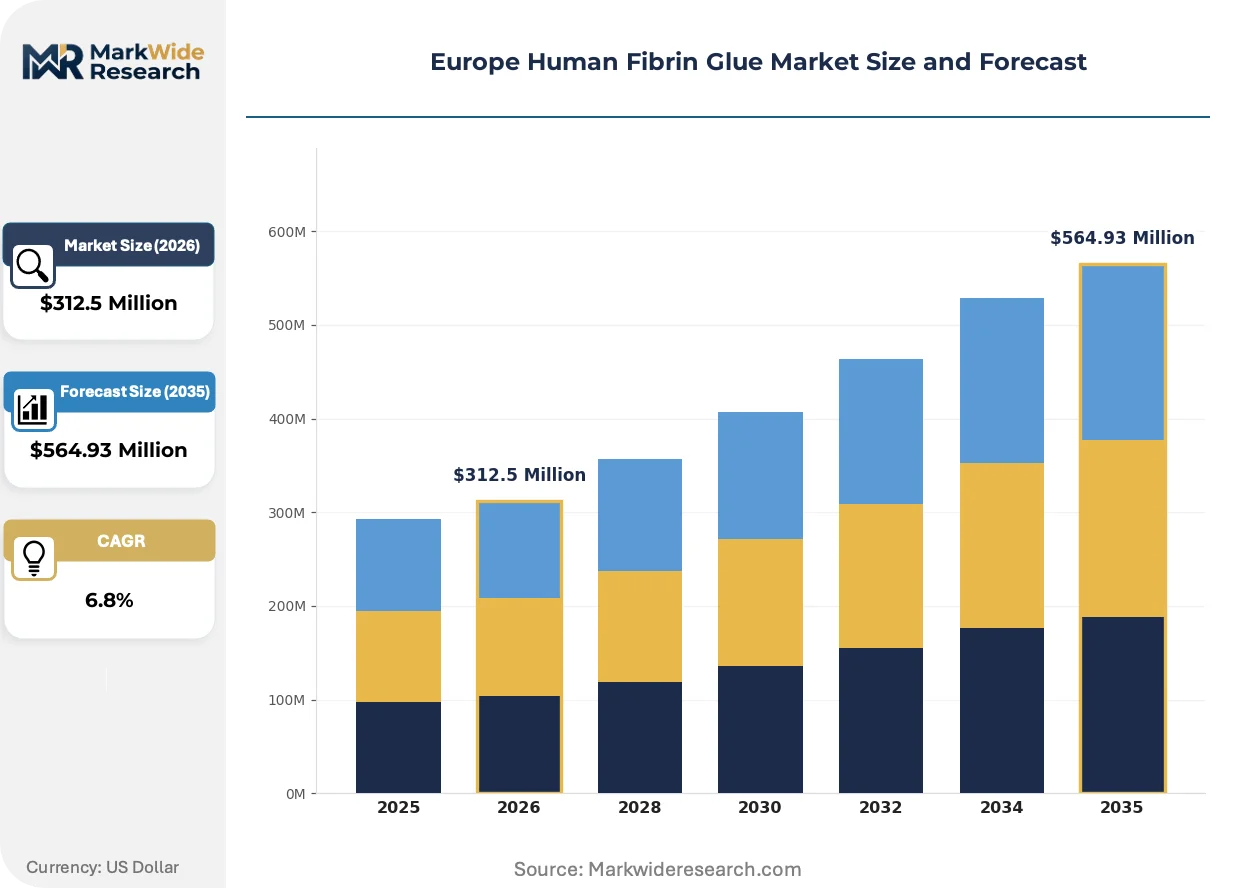
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $564.93 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fibrin Sealants, Fibrin Tissue Adhesives, Fibrin Gels, Fibrin Films Application: Cardiac Surgery, Orthopedic Surgery, Neurosurgery, General Surgery End User: Hospitals, Ambulatory Surgical Centers, Clinics, Research Institutions Delivery Mode: Spray, Liquid, Paste, Pre-filled Syringe |
| Companies Covered | Grifols, S.A., Vivostat A/S, Baxter International Inc., B. Braun Melsungen AG, Octapharma, Johnson & Johnson (Ethicon), Tissuemed Ltd., Integra LifeSciences, CSL Behring, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Human Fibrin Glue Market Shifts & Advancements
Delivery system miniaturization and component stabilization chemistry are converging to expand fibrin sealant applicability beyond traditional operative theaters into interventional suites and point-of-care settings.
Spray applicator technology is converging with laparoscopic instrument channels to enable precise fibrin deposition in minimally invasive cardiac and thoracic procedures. German surgical suites are adopting these integrated systems fastest, with French hospital networks following within eighteen to twenty-four month lag patterns. The convergence is compressing the addressable market for conventional open-surgery sealant formats.
MDR Article 10 clinical evaluation requirements are mandating prospective registry data for legacy products previously grandfathered under the Medical Device Directive. Manufacturers must now submit real-world evidence from EU member state post-market surveillance systems. High-volume cardiac centers in England and the Netherlands are prioritizing suppliers with established registry participation frameworks.
Hospital procurement consortia are consolidating hemostatic product contracts across multi-site networks, unbundling device selection from individual surgeon preference. Group purchasing organizations in France and Germany now control sixty to seventy percent of fibrin sealant volume in their territories. The concentration is visible most acutely in Paris and Berlin metropolitan hospital alliances.
Europe Human Fibrin Glue Market Segmentation
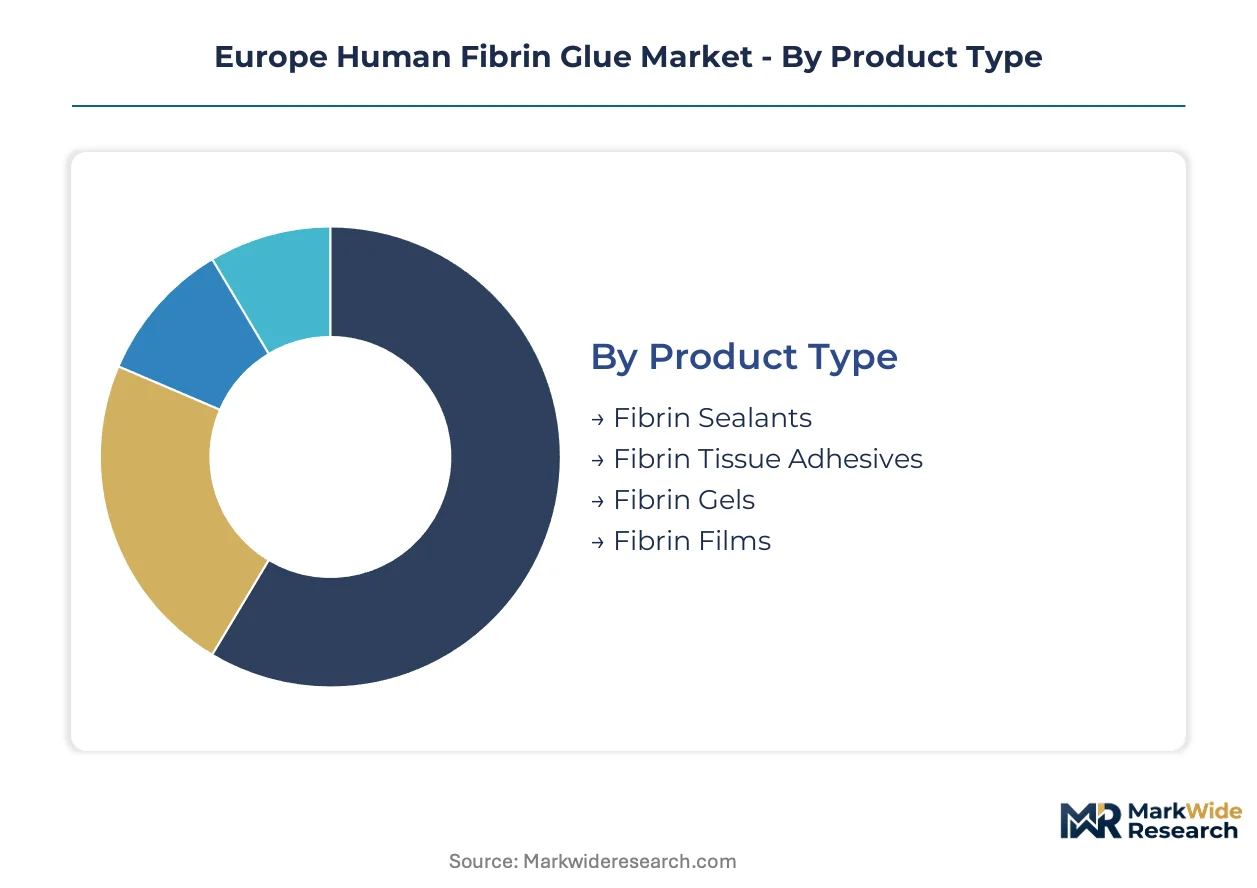
Human fibrin glue segmentation reveals distinct technology-surgery pairings where delivery format, tissue application, and care setting interlock. Procurement patterns diverge sharply between high-volume cardiac centers and specialized orthopedic clinics across EU member states.
Product Type:
Volume concentration sits with established sealant formats, while premium positioning attaches to next-generation gel and film technologies.
- Fibrin Sealants:Concentrated fibrinogen-thrombin combinations with aprotinin stabilization dominate hospital formularies. German cardiac surgery units in Berlin and Munich drive procurement consolidation through standardized protocols.
- Fibrin Tissue Adhesives:Lower fibrinogen concentration formulations optimized for superficial wound closure command ambulatory premium. French day-surgery networks in Lyon and Marseille favor these for reduced preparation complexity.
- Fibrin Gels:Viscous matrices for orthopedic cartilage repair and bone graft containment.
- Fibrin Films:Sheet formats for dural repair and barrier applications in neurosurgical settings.
Today's leader: Fibrin Sealants. Tomorrow's challenger: Fibrin Gels.
Application:
Surgical volume distributes unevenly across specialties, with cardiac and orthopedic procedures anchoring distinct supply chain configurations.
- Cardiac Surgery:Sternotomy hemostasis and bypass graft sealing require high-concentration sealant formulations. Italian cardiac centers in Milan and Bologna are expanding fibrin glue protocols to off-pump procedures.
- Orthopedic Surgery:Microfracture cartilage repair and tendon graft fixation favor gel viscosity ranges. Spanish orthopedic clusters in Barcelona and Madrid are driving fibrin gel adoption for sports medicine applications.
- Neurosurgery:Dural closure and cerebrospinal fluid leak prevention demand precise film and liquid deposition.
- General Surgery:Liver resection and splenic trauma applications utilize spray delivery for rapid hemostasis.
Cardiac Surgery commands current procurement volume. Orthopedic Surgery is climbing the fastest as cartilage repair protocols standardize.
End User:
Site-of-care economics fragment purchasing authority between centralized hospital networks and distributed ambulatory facilities.
- Hospitals:Multi-specialty surgical departments with cold chain infrastructure and pharmacy compounding capabilities. Dutch academic medical centers in Amsterdam and Rotterdam maintain the highest per-capita fibrin sealant utilization in the region.
- Ambulatory Surgical Centers:Pre-filled syringe formats reduce staffing overhead and enable same-day discharge economics. Portuguese day-surgery facilities in Lisbon are licensing standalone cardiac catheterization suites.
- Clinics:Wound care and minor procedure applications with limited sealant volume requirements.
- Research Institutions:Preclinical and clinical trial supply for regenerative medicine applications.
Hospitals retain procurement dominance. Ambulatory Surgical Centers are gaining share fastest through regulatory licensing expansion.
Delivery Mode:
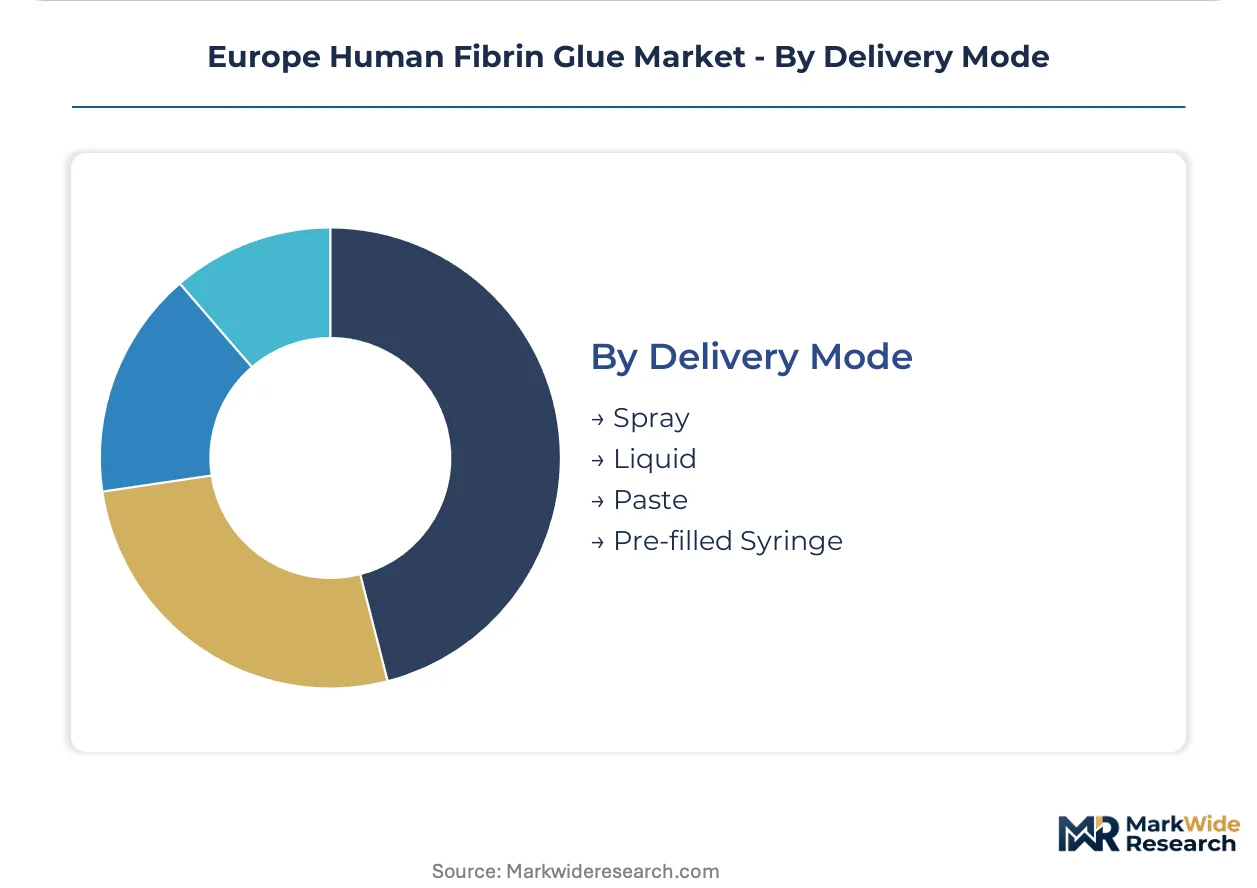
Format selection tracks procedure invasiveness and throughput pressure, with spray systems for open surgery and syringe formats for efficiency.
- Spray:Laparoscopic-compatible applicators enable precise deposition in minimally invasive cardiac and thoracic procedures. Belgian surgical suites in Brussels and Leuven are adopting integrated spray-laparoscope systems.
- Liquid:Flowable formulations for deep wound bed coverage and irregular tissue surfaces.
- Paste:High-viscosity options for bone void filling and orthopedic graft stabilization.
- Pre-filled Syringe:Dual-chamber designs eliminate reconstitution time and reduce preparation errors. Austrian ambulatory networks in Vienna are mandating these for all day-surgery hemostatic procedures.
Spray systems anchor current surgical workflow integration. Pre-filled Syringe formats are expanding most quickly through ambulatory licensing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Human fibrin glue manufacturing originated in European plasma fractionation facilities during the 1970s, with Swiss and German laboratories pioneering industrial-scale purification protocols that remain foundational to contemporary production.
Germany
Berlin and Munich cardiac surgery clusters drive standardized fibrin sealant procurement through hospital network consolidation. The Federal Institute for Drugs and Medical Devices enforces MDR transition timelines that compress manufacturer certification windows. Bavarian medical device manufacturers in the Munich-Stuttgart corridor are integrating spray delivery systems with laparoscopic platforms.
France
Lyon and Marseille ambulatory surgery networks favor pre-filled syringe formats for reduced preparation overhead in day-procedure settings. The National Agency for Food, Environmental and Occupational Health Safety applies REACH compliance standards to chemical stabilizer traceability. Paris metropolitan hospital alliances control sixty to seventy percent of national fibrin sealant procurement volume through consolidated tendering.
Italy
Milan and Bologna cardiac centers are expanding fibrin glue protocols to off-pump coronary procedures, creating specialty-specific demand pull. The Italian Medicines Agency coordinates EMA-aligned post-market surveillance requirements for hemostatic devices. Northern Italian orthopedic clusters in the Veneto region are piloting fibrin gel applications for cartilage repair protocols.
Spain
Barcelona and Madrid sports medicine facilities are driving fibrin gel adoption for tendon graft fixation and microfracture procedures. The Spanish Agency for Medicines and Health Products enforces CE marking compliance for novel delivery system formats. Catalan biomedical research institutes are advancing preclinical applications of fibrin matrices in regenerative medicine.
Netherlands
Amsterdam and Rotterdam academic medical centers maintain the highest per-capita fibrin sealant utilization rates in Europe. The Healthcare Inspectorate monitors cold chain integrity requirements for plasma-derived component stability. Dutch hospital procurement consortia are unbundling device selection from individual surgeon preference through multi-site contract consolidation.
Europe Human Fibrin Glue Market Competitive Landscape
Premium-margin players sit above commodity-margin players across regulatory compliance capability and plasma fractionation infrastructure depth. The vendor base stratifies between integrated plasma processors with captive raw material supply and device-focused assemblers dependent on external fibrinogen sourcing. Three archetypes dominate: plasma-derived biologics specialists with backward integration into blood processing, diversified medical device conglomerates with hospital contracting scale, and regional delivery system innovators with format-specific IP. Consolidation pressure and MDR certification backlog are forcing mid-tier manufacturers toward partnership or exit.
Within the plasma-integrated tier, Grifols, S.A. and Octapharma exemplify the raw material security archetype through Iberian and Central European fractionation infrastructure. Baxter International Inc. occupies a position representing the hospital network contracting model across Northern European markets. B. Braun Melsungen AG sits within the integrated manufacturing archetype combining sealant production with proprietary delivery system design.
| Leading Market Players |
|---|
| Grifols, S.A. |
| Vivostat A/S |
| Baxter International Inc. |
| B. Braun Melsungen AG |
| Octapharma |
| Johnson & Johnson (Ethicon) |
| Tissuemed Ltd. |
| Integra LifeSciences |
| CSL Behring |
| Others |
Supply & Pricing Matrix
Plasma fractionation input costs cascade through three distinct pricing tiers that segment hospital procurement contracts across Northern and Southern Europe. EMA MDR compliance investments compress margins at the standard tier while premium-positioned sealant formats retain pricing power through cold-chain reliability guarantees and surgeon training bundling.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by certification grade and after-sales service intensity. Premium tiers command position through MDR Article 10 clinical registry participation and dedicated field clinical specialist support, while economy tiers serve high-volume cardiac centers with stripped-down logistics and minimal technical service. Price differentiation stems from plasma sourcing traceability depth and delivery system integration complexity. Cost compression in the standard tier is intensifying because REACH compliance documentation requirements have added administrative overhead without corresponding reimbursement uplift. Ambulatory surgical centers in France and Italy exhibit the highest price sensitivity due to fixed reimbursement caps per procedure, whereas German academic medical centers prioritize supply security over unit cost minimization.
Supply Chain Analysis
Reverse-logistics infrastructure for temperature-exposed product returns remains underdeveloped across peripheral EU markets, creating write-off cost concentration in Greece and Portugal. Raw fibrinogen supply draws from fractionation facilities concentrated in Germany, Spain, and Switzerland, with thrombin component sourcing anchored in Austrian and Czech plasma processing plants. Supply chain risk centers on single-source vulnerability at the fibrinogen purification stage, where three EU-licensed facilities handle the majority of regional hospital network contracts. Distribution runs through specialized medical device wholesalers with validated cold-chain capabilities, bypassing general pharmaceutical distributors due to stability requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Human Fibrin Glue Market functions as a stable compounder anchored by irreversible surgical protocol standardization in cardiac and orthopedic specialties. EU MDR regulatory permanence ensures sustained replacement demand for compliant product formats across the forecast horizon.
For Market Incumbents: To counter synthetic sealant substitution in general surgery applications, deepen backward integration into plasma collection networks across Iberia and secure multi-year hospital system partnership frameworks that bundle device supply with clinical training infrastructure. CE marking renewal timelines at notified bodies represent a secondary threat requiring dedicated regulatory affairs capacity expansion. For New Entrants and Emerging Players: Begin with fibrin gel formulations targeting orthopedic cartilage repair protocols in Spanish and Italian sports medicine clusters, where surgeon familiarity with mechanical fixation creates receptive substitution dynamics. Pre-filled syringe formats for ambulatory surgical centers in Portugal and Eastern Europe offer the most penetrable entry vector, with regulatory licensing pathways shorter than hospital formulary inclusion timelines. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier manufacturers lack captive plasma supply and face MDR certification cost burdens exceeding twelve to eighteen month cash reserves. The five-to-ten year viability window favors acquisition targets with established notified body relationships and existing CE mark portfolios requiring only surveillance updates rather than full clinical re-submission. Monitor EMA MDR transition deadline extensions and notified body capacity expansion announcements as inflection indicators for competitive exit timing.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR Article 10 compliance secures hospital procurement eligibility across German and French networks. |
| Hospital System Partnership | Multi-year supply agreements with Paris and Berlin metropolitan alliances lock out competitor access. |
| Backward Integration | Plasma collection infrastructure in Spain and Portugal insulates raw material costs from fractionation concentration. |
| Software Companion Development | Spray applicator integration with laparoscopic platforms enables minimally invasive cardiac procedure capture. |
| Reimbursement Strategy | HTA alignment with French HAS and German IQWiG cost-effectiveness thresholds accelerates formulary inclusion. |
Research Methodology
Bottom-up surgical procedure volume modeling reconciled against top-down plasma fractionation capacity tracking forms the analytical core of this study. Primary interviews with cardiac surgeons, hospital procurement committee chairs, biomedical engineers, and GPO contracts managers informed demand-side assumptions, while secondary validation drew from EMA MDR submission databases, CE marking registries, hospital procurement tender records, and REACH compliance disclosure filings. Triangulation between end-use consumption patterns and supply-side production capacity ensures cross-verified volume estimates.
Historical trendline analysis of fibrin sealant utilization rates per cardiac procedure established baseline penetration assumptions across the projection horizon. The analytical framework segments by product format, surgical specialty, delivery mode, and care setting, with CAGRs derived from procedure volume growth elasticities and pricing trajectory modeling. Forecast inputs include EU MDR transition timeline adherence, ambulatory surgical center licensing expansion patterns, and orthopedic cartilage repair protocol adoption curves.
Several conditions sit outside the modeled scope, including geopolitical disruption to plasma collection networks, breakthrough synthetic sealant technologies achieving non-inferiority in cardiac applications, and fundamental reimbursement regime changes in major EU member states. Forecasts reflect documented assumptions regarding regulatory timeline stability and hospital procurement consolidation continuity. Practitioners should monitor notified body capacity expansion announcements, REACH chemical restriction list updates, and synthetic adhesive clinical trial readouts for early signals requiring forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
North America Adhesives and Sealants Market
Adhesives & Sealants
Global Disposable Hygiene Adhesives Market
Adhesives & Sealants
Cold Seal Adhesives Market
Adhesives & Sealants
Automotive Windshield Adhesives Market
Adhesives & Sealants
Spray Glue Market
Adhesives & Sealants
Tobacco and Cigarette Adhesives Market
Adhesives & Sealants
Global Adhesion Promoter Market
Adhesives & Sealants
Global Slack Wax Market
Adhesives & Sealants
Hot Melt Adhesives Market
Adhesives & Sealants
Flock Adhesives Market
Adhesives & Sealants
Middle East and Africa Flock Adhesives Market
Adhesives & Sealants
Global Adhesives Market
Adhesives & Sealants
Structural Sealants Market
Adhesives & Sealants
Europe Chemical Anchors Market
Adhesives & Sealants
Asia-Pacific Automotive Adhesives and Sealants Market
Adhesives & Sealants
Global Engineering Adhesives Market