
 Asia-Pacific Bone Glue Market | 2026-2036
Asia-Pacific Bone Glue Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Bone Glue Market Outlook
CE-mark-equivalent quality certification is reorganizing procurement standards across the Asia-Pacific Bone Glue Market. Stryker leverages its integrated trauma and extremities portfolio to dominate hospital formulary access in Australia and South Korea. Zimmer Biomet anchors its position through specialized synthetic bone glue formulations targeting revision arthroplasty. Kuros Biosciences differentiates via its biosynthetic segment leadership and direct surgeon training programs in Japan.
Bone glue comprises medical adhesives formulated from fibrinogen-thrombin systems, synthetic cyanoacrylate variants, or biodegradable polymer matrices that achieve hemostasis and osteoconduction at surgical interfaces. These materials typically set within 30-120 seconds and demonstrate shear adhesion strength exceeding 50 kPa for load-bearing orthopedic applications. Fibrin glue retains the largest revenue share due to established reimbursement pathways and surgeon familiarity, while synthetic bone glue is expanding fastest as PMDA and TGA pathways streamline novel polymer approvals. Hydrogel delivery modes command premium positioning in spinal applications where controlled release kinetics reduce revision rates.
PMDA biocompatibility standards, TGA medical device inclusion pathways, and Japan's JIS T 0313 testing framework collectively determine market access timelines and clinical evidence requirements for new entrants. Australia's Therapeutic Goods Administration has accelerated assessment parallel pathways for biodegradable bone adhesives, compressing approval cycles for EU-validated products. Stakeholders must monitor how China's NMPA harmonizes its technical review standards with international ISO 10993 protocols, as this alignment will reshape manufacturing location decisions and regional supply priorities.
Market Dynamics
Japan's PMDA biocompatibility tightening is compressing approval timelines for synthetic bone adhesives while accelerating biodegradable polymer adoption across the Asia-Pacific surgical supply chain. This regulatory pivot is forcing manufacturers to restructure formulation pipelines and evidence-generation strategies.
Growth Catalysts
- Outpatient spinal fusion expansion:Australia's private surgical center network is scaling same-day procedures, driving concentrated demand for rapid-setting fibrin systems in lumbar applications.
- TGA parallel assessment pathways:Australia's Therapeutic Goods Administration has compressed review cycles for EU-validated biodegradable bone adhesives, accelerating market entry for novel polymer platforms.
- Minimally invasive joint procedure adoption:Southeast Asian orthopedic clinics are expanding arthroscopic applications, creating pull-through for precision-delivery fibrin sealants in meniscal repair and cartilage fixation.
Market Restraints
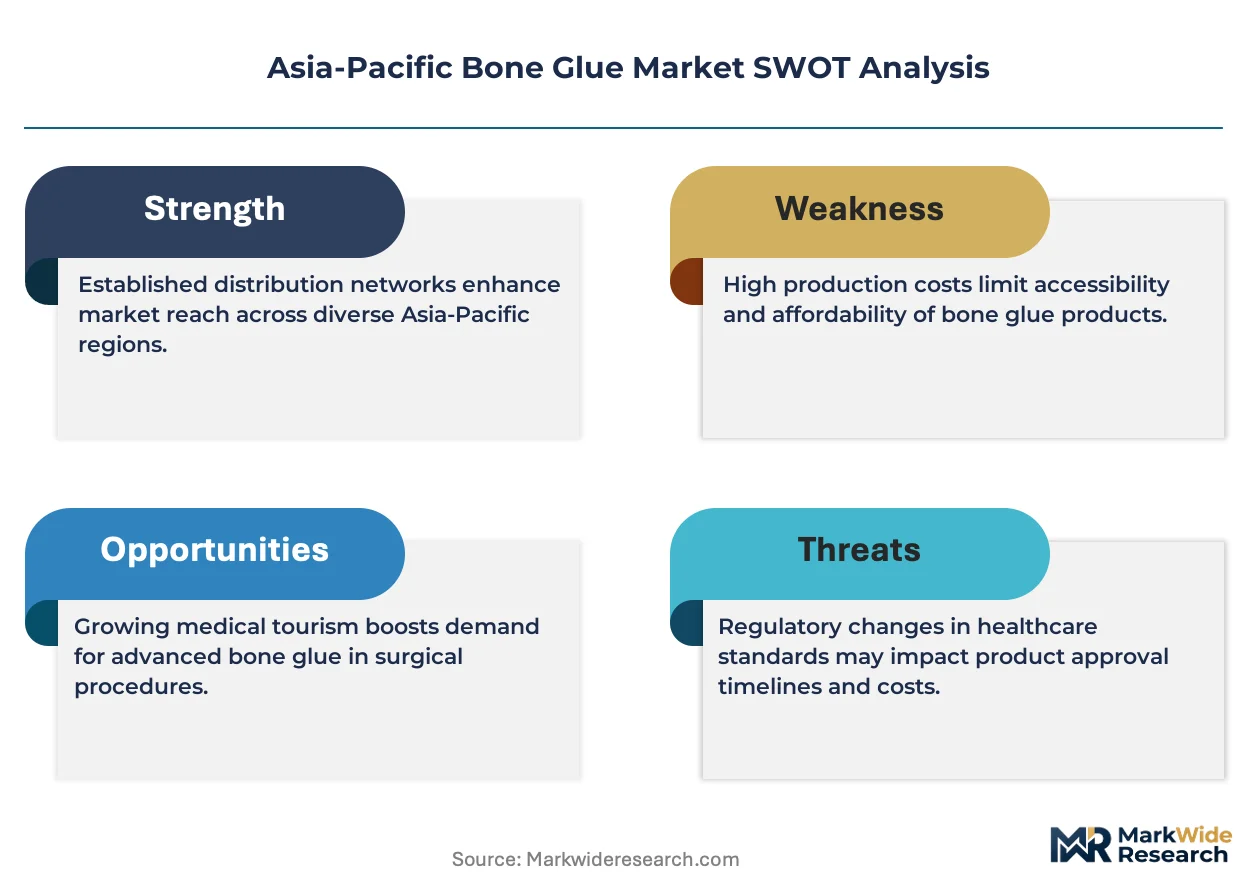
- Fibrinogen raw material concentration:Plasma-derived fibrinogen supply clusters in fractionation facilities concentrated in Australia and Japan, exposing manufacturers to batch-to-batch variability and donor pool limitations.
- PMDA biocompatibility testing burden:Japan's tightened ISO 10993-aligned protocols extend preclinical timelines by 12-18 months for synthetic cyanoacrylate entrants without EU predicate device history.
- Autograft persistence in load-bearing fusion:Iliac crest bone graft remains the gold standard for posterior lumbar interbody fusion across South Korean and Australian hospital systems, limiting adhesive penetration in high-stress spinal segments.
Strategic Opportunities
- India's underserved trauma fixation segment:Road accident trauma volumes exceed 150,000 annually requiring emergency orthopedic intervention, yet fibrin adhesive penetration in tier-2 and tier-3 cities remains below 15 percent.
- Hydrogel-synthetic hybrid platforms:Convergence of biodegradable polymer matrices with controlled-release hydrogel carriers enables dual-function osteoconduction and antibiotic elution for infection-prone revision arthroplasty.
- Japan's JIS T 0313 harmonization momentum:Alignment with international biocompatibility frameworks creates regulatory arbitrage for manufacturers holding EU MDR or FDA 510(k) clearances, compressing Japan entry costs.
Industry Challenges
- Surgical training standardization gaps:Fibrin adhesive application techniques vary widely across Asia-Pacific residency programs, creating inconsistent clinical outcomes that complicate payer evidence requirements.
- Legacy sterilization validation backlogs:Gamma and electron-beam sterilization protocols for synthetic bone adhesives require extensive polymer stability testing, delaying batch release cycles at contract manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Bone Glue Market |
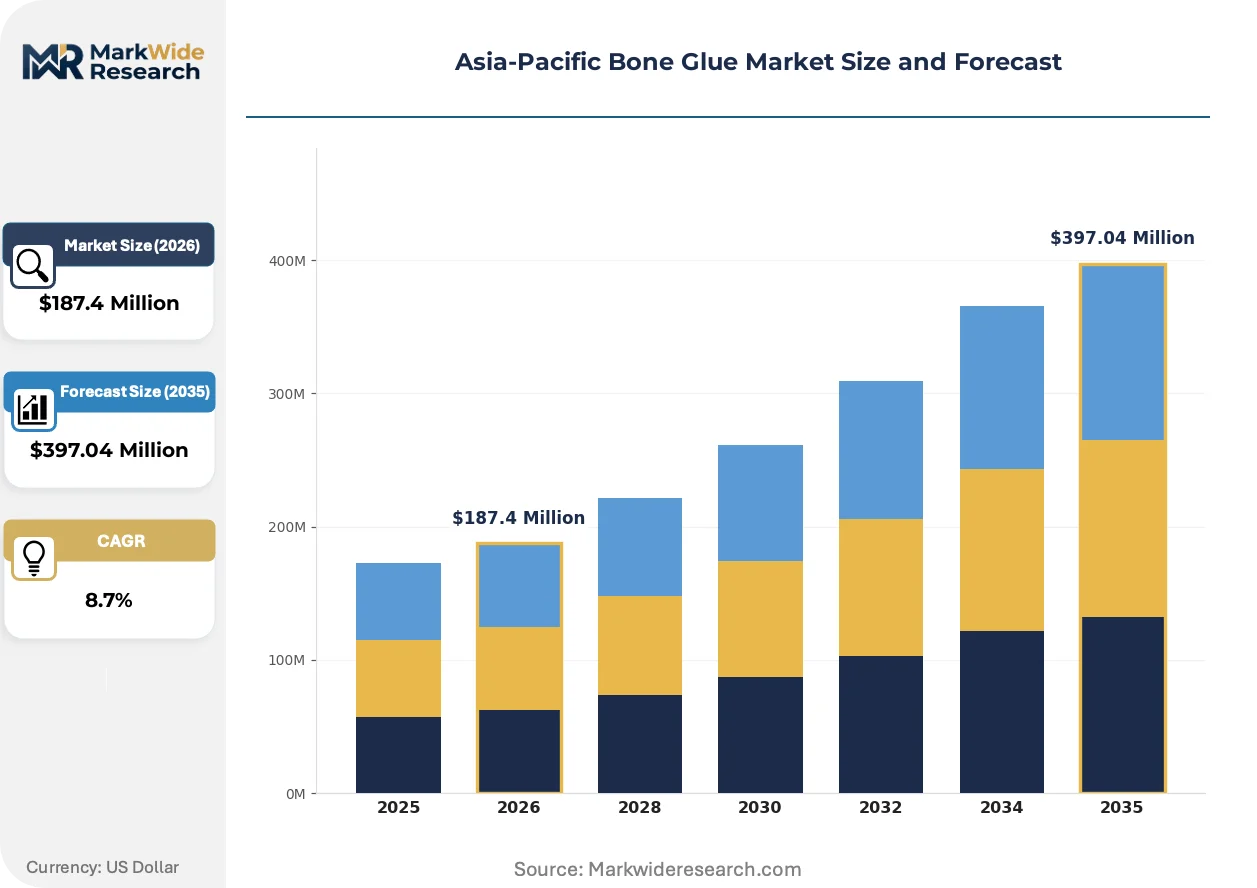
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fibrin Glue, Synthetic Bone Glue, Biodegradable Glue, Hydrogel End User: Hospitals, Orthopedic Clinics, Dental Clinics, Surgical Centers Application: Orthopedic Surgery, Dental Procedures, Tissue Repair, Wound Closure Delivery Mode: Syringe, Spray, Adhesive Patch, Liquid |
| Companies Covered | Stryker, Smith & Nephew, Zimmer Biomet, DePuy Synthes, Arthrex, DJO Global, Heraeus Medical, Kuros Biosciences, Cardinal Health, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Bone Glue Market Strategic Shifts
Biodegradable synthetic polymers are displacing fibrin dominance in load-bearing applications while regulatory harmonization and procurement centralization reshape competitive access across Asia-Pacific surgical supply chains.
Photocurable urethane-based bone adhesives are displacing traditional fibrin systems in spinal fusion applications where shear strength requirements exceed 100 kPa. Australian private surgical centers and South Korean university hospitals are piloting these platforms for posterior instrumented fusion cases. The technology is displacing autograft harvest morbidity while compressing operative time and blood loss metrics that drive outpatient eligibility.
PMDA's 2024 biocompatibility guidance revision mandates extended cytotoxicity and sensitization testing for all synthetic bone adhesives without five-year Japan market history. Manufacturers with EU MDR certificates face compressed technical documentation review but must still generate Japan-specific clinical performance data. Synthetic polymer entrants are responding by prioritizing biodegradable formulation pipelines that align with PMDA's stated preference for resorbable implant materials.
Hospital procurement consortiums in Australia and South Korea are consolidating formulary decisions through centralized value-analysis committees, displacing individual surgeon preference as the primary purchasing determinant. Device vendors must now demonstrate total procedure cost reduction across adhesive, operative time, and revision risk dimensions. This concentration is most visible in Australia's private hospital networks where Stryker and Zimmer Biomet hold integrated trauma and spine contracts that bundle bone adhesive access with implant volume commitments.
Asia-Pacific Bone Glue Market Segmentation
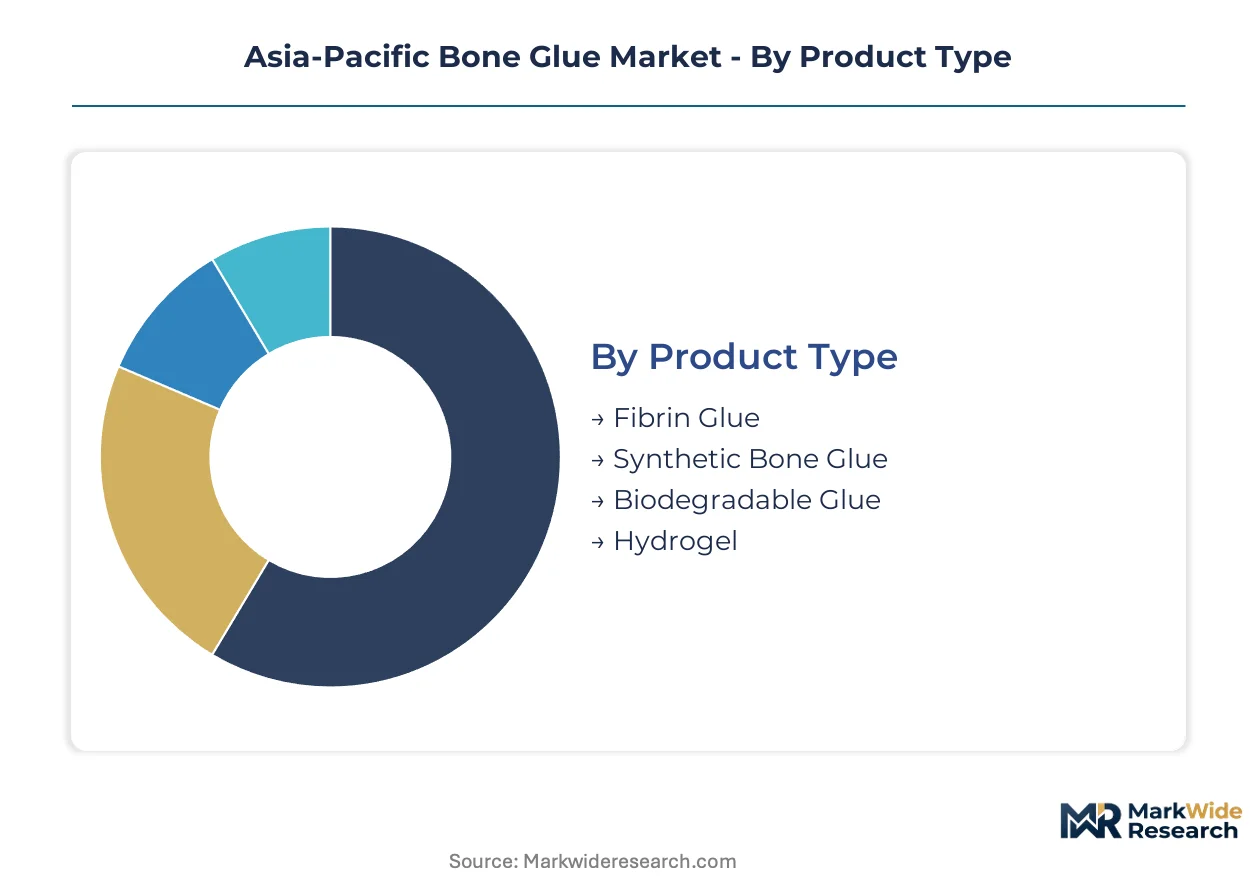
Segmentation in the Asia-Pacific Bone Glue Market reveals how regulatory pathways and surgical settings reshape product adoption. PMDA and TGA frameworks create divergent access corridors that concentrate demand in specific formulations and delivery systems across the region.
Product Type:
PMDA biocompatibility protocols and TGA parallel assessment pathways favor distinct formulation classes, fragmenting competitive positioning across biodegradable and synthetic platforms.
- Fibrin Glue:Plasma-derived fibrinogen-thrombin systems set within 30-120 seconds and demonstrate shear adhesion exceeding 50 kPa. Australia's private surgical centers and South Korean university hospitals drive concentrated procurement for rapid-setting lumbar applications where operative time compression enables outpatient eligibility.
- Synthetic Bone Glue:Cyanoacrylate and polymer-based formulations achieve higher mechanical strength for load-bearing fusion. Japan's tightened ISO 10993-aligned testing extends preclinical timelines for entrants without EU predicate history, compressing approval cycles only for biodegradable variants.
- Biodegradable Glue:Resorbable polymer matrices align with PMDA's stated preference for resorbable implant materials, accelerating pipeline prioritization among manufacturers holding EU MDR certificates.
- Hydrogel:Controlled-release carriers enable dual-function osteoconduction and antibiotic elution, commanding premium positioning in spinal applications where release kinetics reduce revision risk.
Fibrin Glue handles the majority of throughput; Hydrogel is gaining share fastest on the back of spinal procedure expansion.
End User:
Procurement centralization through value-analysis committees concentrates purchasing power differently across hospital networks and outpatient facilities.
- Hospitals:Australia's public hospital systems and South Korean university hospitals maintain integrated trauma contracts that bundle bone adhesive access with implant volume commitments, displacing individual surgeon preference.
- Orthopedic Clinics:Southeast Asian arthroscopic centers are scaling meniscal repair and cartilage fixation volumes, creating pull-through for precision-delivery fibrin sealants in minimally invasive joint procedures.
- Dental Clinics:Maxillofacial applications in Japan and Australia utilize fibrin systems for socket preservation and implant site preparation, though penetration remains below orthopedic levels.
- Surgical Centers:Australia's private same-day surgery networks are piloting photocurable urethane platforms for posterior instrumented fusion, compressing blood loss and operative time metrics that determine outpatient eligibility.
Hospitals dominate absolute volume; Surgical Centers are expanding most quickly as Australia's private networks scale spinal fusion outside traditional inpatient settings.
Application:
Load-bearing requirements and autograft persistence create tiered penetration patterns across surgical specialties.
- Orthopedic Surgery:Spinal fusion, joint reconstruction, and trauma fixation represent the core demand concentration. Iliac crest bone graft remains the gold standard for posterior lumbar interbody fusion across South Korean and Australian systems, limiting adhesive penetration in high-stress segments.
- Dental Procedures:Periodontal regeneration and implant osteotomy fixation utilize fibrin sealants for hemostasis and graft stabilization, with Japan's dental specialist network driving formulation refinement.
- Tissue Repair:Meniscal and cartilage applications in Southeast Asian clinics favor precision-delivery systems that enable arthroscopic placement without open exposure.
- Wound Closure:Sternotomy and soft-tissue applications in cardiac and general surgery utilize fibrin systems for hemostasis, though this sits outside core orthopedic demand.
Orthopedic Surgery commands the largest procedure volume; Tissue Repair is climbing fastest on Southeast Asian arthroscopic adoption.
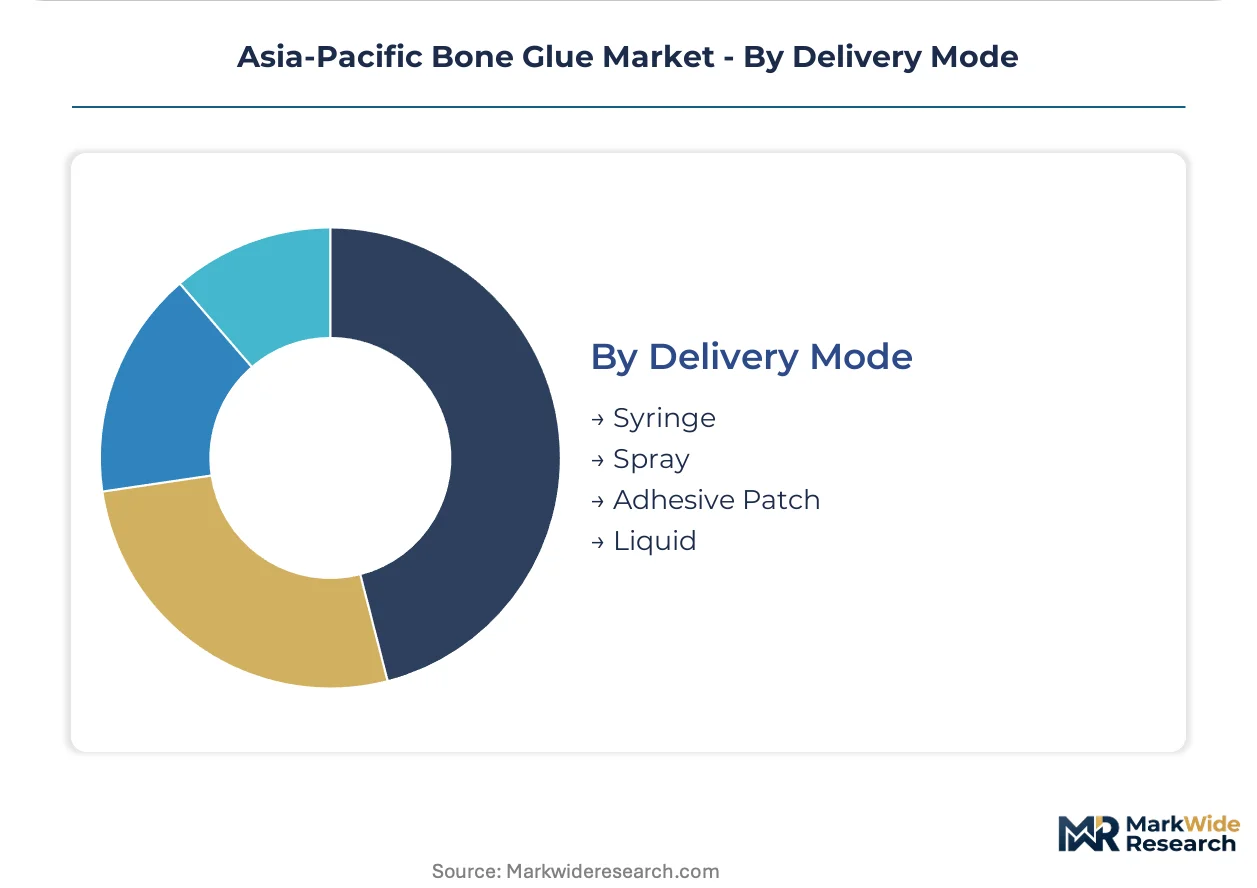
Delivery Mode:
Application site geometry and setting time requirements determine modality selection across open and minimally invasive approaches.
- Syringe:Dual-barrel systems enable controlled mixing of fibrinogen and thrombin components at the surgical interface, standard for arthroscopic and open orthopedic applications.
- Spray:Aerosolized delivery covers large surface areas in spinal fusion and sternotomy closure, with Australian surgical centers evaluating spray platforms for rapid hemostasis in outpatient lumbar cases.
- Adhesive Patch:Pre-formed matrices suit periodontal and superficial applications where mechanical fixation supplements chemical adhesion.
- Liquid:Low-viscosity formulations penetrate cancellous bone structures in vertebral augmentation and dental socket applications.
Syringe systems manage the highest procedure throughput; Spray configurations are expanding most quickly on spinal fusion volume growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependency on plasma-derived fibrinogen concentrates flows toward fractionation facilities in Australia and Japan, while synthetic polymer formulations attract manufacturing investment toward South Korea and Singapore as regulatory alignment accelerates.
Japan
PMDA's 2024 biocompatibility guidance revision mandates extended cytotoxicity testing for synthetic bone adhesives lacking five-year domestic market history. Tokyo and Osaka surgical centers drive demand for biodegradable polymer matrices that align with regulator preference for resorbable implant materials. Kuros Biosciences anchors biosynthetic segment positioning through direct surgeon training programs concentrated in the Kanto region.
Australia
Private surgical center networks in Sydney and Melbourne scale same-day spinal fusion procedures, concentrating procurement for rapid-setting fibrin systems. TGA parallel assessment pathways compress review cycles for EU-validated biodegradable bone adhesives, accelerating market entry for novel polymer platforms. The Therapeutic Goods Administration's streamlined pathways particularly benefit manufacturers holding MDR certificates seeking outpatient eligibility expansion.
South Korea
University hospitals in Seoul and Busan pilot photocurable urethane-based bone adhesives for posterior instrumented fusion cases exceeding 100 kPa shear strength requirements. MFDS harmonization with ISO 10993 protocols creates compressed technical documentation review for EU-cleared entrants. Hospital procurement consortiums consolidate formulary decisions through centralized value-analysis committees, displacing individual surgeon preference in implant-adhesive bundling arrangements.
China
NMPA technical review standard alignment with international biocompatibility frameworks reshapes manufacturing location decisions for export-oriented producers. Yangtze River Delta medical device clusters attract synthetic bone adhesive production targeting domestic revision arthroplasty volume growth. The regulator's harmonization momentum creates regulatory arbitrage for manufacturers holding EU MDR or FDA 510(k) clearances seeking accelerated pathway access.
India
Road accident trauma volumes exceeding 150,000 annually requiring emergency orthopedic intervention concentrate demand potential in tier-2 and tier-3 cities where fibrin adhesive penetration remains below 15 percent. CDSCO medical device rules implementation tightens quality certification requirements for imported bone adhesives. Maharashtra and Karnataka surgical networks represent the primary near-term expansion corridors for precision-delivery fibrin sealant distribution.
Asia-Pacific Bone Glue Market Competitive Environment
Listed leaders compete with private specialists across procurement access and surgeon training dimensions, creating tiered competitive dynamics where integrated trauma portfolios bundle adhesive access with implant volume commitments. The vendor base concentrates around three strategic archetypes: diversified orthopedic conglomerates with formulary dominance, specialized biosynthetic developers with direct education programs, and regional distributors leveraging regulatory pathway expertise. Competitive moves center on procurement consortium penetration and biodegradable formulation pipeline prioritization.
Within the diversified orthopedic tier, Stryker and Zimmer Biomet exemplify scale-driven positioning through integrated trauma and extremities portfolio bundling. Kuros Biosciences occupies the biosynthetic specialist archetype with differentiated surgeon training investment. Among distribution-focused players, Cardinal Health represents regulatory pathway navigation capabilities across fragmented Asia-Pacific hospital networks.
| Leading Market Players |
|---|
| Stryker |
| Smith & Nephew |
| Zimmer Biomet |
| DePuy Synthes |
| Arthrex |
| DJO Global |
| Heraeus Medical |
| Kuros Biosciences |
| Cardinal Health |
| Others |
Value Chain & Pricing Dynamics
Capacity reservation contracts with Australian fractionation facilities lock in fibrinogen supply access and stabilize raw material price visibility for manufacturers serving Japan's PMDA-regulated market. These arrangements compress procurement uncertainty while embedding volume commitments that shape competitive positioning across biodegradable and synthetic formulation tiers.
Pricing Analysis
Hospital procurement consortiums anchor three-tier pricing structure across premium, standard, and economy levels for bone adhesive procurement in Australia and South Korea. Price differentiation rests on TGA certification grade and surgical center volume scale, with premium tiers commanding position for rapid-setting hydrogel platforms. Cost compression in standard-tier synthetic formulations is intensifying because PMDA biocompatibility testing extends preclinical timelines for entrants without EU predicate history. Tier-2 and tier-3 hospital systems in India exhibit highest price sensitivity, while Australian private surgical centers demonstrate lowest sensitivity given bundled implant-adhesive contracts.
Supply Chain Analysis
Australia and Japan anchor plasma-derived fibrinogen concentration through fractionation facilities serving regional orthopedic adhesive manufacturers. Raw material procurement draws from bovine thrombin suppliers and synthetic polymer feedstock producers in South Korea and Singapore. Single-source vulnerability concentrates in Australian plasma collection networks, where donor pool limitations expose batch-to-batch variability risks. Distribution runs through hospital procurement consortiums and specialized surgical device distributors, with direct manufacturer-to-hospital contracting gaining share in consolidated Australian and South Korean networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Surgeon training program subscriptions represent a service-attach opportunity expanding faster than hardware sales, as PMDA-aligned biodegradable formulation adoption requires hands-on technique standardization that device vendors under-provision.
For Market Incumbents: Compound formulary dominance through backward integration into plasma fractionation capacity in Australia, securing fibrinogen supply continuity against emerging synthetic polymer substitutes. Deepen hospital procurement consortium penetration by bundling biodegradable adhesive access with spinal implant volume commitments, defending position against biosynthetic specialists building direct surgeon relationships. For New Entrants and Emerging Players: Precision-delivery system training gaps in Southeast Asian arthroscopic clinics represent under-served service layers where incumbents lack localized education infrastructure. Target India's tier-2 trauma fixation segment through distributor partnerships offering emergency response logistics, leveraging CDSCO quality certification requirements to differentiate against unvalidated imports. For Investors and Strategic Acquirers: Regional distribution specialists with PMDA pathway expertise and established surgeon training networks offer acquisition exposure to biodegradable polymer adoption curves. Monitor TGA parallel assessment pathway utilization rates as inflection indicator for EU-validated product market entry velocity across Australian surgical networks.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Formulation Pipeline Expansion | Aligns with PMDA resorbable material preference, compressing Japan market entry timelines for EU-cleared manufacturers. |
| Surgeon Training Program Development | Addresses technique standardization gaps that complicate payer evidence requirements across Asia-Pacific residency networks. |
| Hospital Procurement Consortium Penetration | Secures formulary access through value-analysis committees displacing individual surgeon preference in Australia and South Korea. |
| Plasma Fractionation Backward Integration | Reduces fibrinogen raw material concentration risk from Australian and Japanese donor pool limitations. |
| Photocurable Urethane Platform Launch | Captures outpatient spinal fusion volume growth in Australian private surgical centers exceeding shear strength thresholds. |
Study Parameters
Initial hypotheses were tested against primary input from orthopedic surgeons, hospital procurement managers, biomedical engineers, and regulatory affairs specialists at PMDA-notified bodies, then refined through secondary validation against TGA medical device inclusion databases, PMDA approval filings, hospital procurement contract records, and ISO 10993 biocompatibility testing protocols. Bottom-up demand modeling across fibrin glue, synthetic bone glue, biodegradable glue, and hydrogel segments triangulated with top-down market sizing from fractionation facility capacity disclosures.
Variance decomposition across product type, end user, application, and delivery mode segmentation dimensions enabled identification of growth contribution by formulation class and surgical setting throughout the projection horizon. CAGRs were derived from procedure volume trajectories in Australian private surgical networks, South Korean university hospital pilot programs, and Southeast Asian arthroscopic adoption curves, cross-referenced with regulatory pathway timeline assumptions for PMDA and TGA submissions.
Underlying assumptions cover PMDA biocompatibility guidance stability, TGA parallel assessment pathway continuity, and plasma-derived fibrinogen supply concentration persistence, with deviation risk concentrated in NMPA technical review harmonization pace and CDSCO enforcement intensity for imported device quality certification. Recalibration cycles align with material shifts in regulatory guidance revisions, procurement consortium consolidation events, and biodegradable polymer clinical performance data publication.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Windscreen Adhesive Market
Adhesives & Sealants
Light Curing Adhesives Market
Adhesives & Sealants
Die Cut Adhesive Market
Adhesives & Sealants
Thailand Sealants Market
Adhesives & Sealants
Conductive Glue Market
Adhesives & Sealants
Global Adhesives Market
Adhesives & Sealants
Global Ceramic Adhesives Market
Adhesives & Sealants
Asia-Pacific Epoxy Adhesive Market
Adhesives & Sealants
Structural Sealants Market
Adhesives & Sealants
Middle-East and Africa Hot-Melt Adhesives Market
Adhesives & Sealants
Adhesives and Sealants Market
Adhesives & Sealants
Asia-Pacific Waterproofing Products Market
Adhesives & Sealants
Global Anti-Tack Agents Market
Adhesives & Sealants
Global Medical Adhesives and Sealants Market
Adhesives & Sealants
Global Bone Glue Market
Adhesives & Sealants
Middle-East and Africa Polyurethane (PU) Adhesives Market