
 Gelatin Bone Glue Market | 2026-2036
Gelatin Bone Glue Market Size, Share, and Industry Trends Forecast 2026-2036
Gelatin Bone Glue Market Analytics
The capital-intensity divergence between integrated gelatin producers and pure-play device assemblers is collapsing as raw-material costs dominate unit economics. GELITA leverages its backward integration into porcine and bovine collagen supply chains to control input quality and batch consistency. Johnson & Johnson anchors its position through sterilization infrastructure and hospital GPO contracts that lock in formulary placement. Baxter International Inc. differentiates via cryogenic preservation compatibility, a parameter critical to orthopedic allograft procedures.
Gelatin bone glue comprises denatured collagen matrices cross-linked with aldehydes or carbodiimides, forming biodegradable adhesives that bond to wet bone surfaces at physiological pH. Liquid formulation commands the largest revenue share due to surgeon familiarity and controlled-dispense applicator compatibility, though powder formulation registers the fastest expansion as ambulatory surgical centers seek room-temperature stability and reduced shipping costs. Porcine gelatin occupies the dominant material position because its thermal gelation profile matches human tissue more closely than fish-derived alternatives, while bovine gelatin faces sourcing constraints from BSE-related import restrictions in several jurisdictions.
FDA 510(k) clearance requirements, the EU Medical Device Regulation (MDR) reclassification of surgical adhesives, and Japan's PMDA biocompatibility testing standards collectively elevate barrier costs for new entrants while rewarding incumbents with established quality management systems. The MDR's enhanced clinical-evidence demands for absorbable implants have extended certification timelines by twelve to eighteen months for European market access. Stakeholders must monitor evolving ISO 10993 biocompatibility test revisions and regional sourcing mandates that could disqualify certain gelatin origins from reimbursement eligibility.
Market Dynamics
The EU Medical Device Regulation's reclassification of absorbable surgical adhesives has compressed certification timelines by twelve to eighteen months, forcing manufacturers to front-load clinical-evidence generation while freezing portfolio diversification. This regulatory density advantage accrues to incumbents with established quality management systems and sterilization infrastructure.
Growth Catalysts
- Rising orthopedic surgical volumes:Tertiary hospital departments in Germany and the United States are expanding arthroplasty and spinal fusion procedures, creating procedural pull for wet-surface bonding agents.
- FDA 510(k) pathway efficiency:The Class II clearance framework in the United States accelerates time-to-revenue for gelatin-based devices with predicate-device equivalence, rewarding early regulatory investment.
- Porcine collagen thermal matching:The material's gelation profile compatibility with human tissue drives surgeon preference over fish-derived alternatives in reconstructive applications.
Market Restraints
- BSE-related bovine sourcing constraints:Import restrictions on bovine-derived materials in Japan and several European jurisdictions limit formulation flexibility and force costly supply-chain reconfiguration.
- Raw-material cost dominance:Gelatin input costs represent the majority of unit economics, squeezing margin buffers for pure-play device assemblers without backward integration into collagen supply chains.
- Cryogenic compatibility requirements:Orthopedic allograft procedures demand adhesives that maintain bond integrity through freeze-thaw cycles, excluding standard formulations from high-value surgical segments.
Strategic Opportunities
- Ambulatory surgical center expansion:Powder formulation room-temperature stability reduces cold-chain shipping costs and opens procurement channels outside hospital GPO networks.
- ISO 10993 biocompatibility revision monitoring:Early alignment with evolving testing standards positions suppliers for reimbursement eligibility as regional sourcing mandates tighten.
- Japan PMDA biocompatibility pathway:Dedicated investment in localized testing infrastructure captures procedural volume in Asia-Pacific's second-largest orthopedic device market.
Industry Challenges
- Cross-linked matrix sterilization validation:Maintaining aldehyde and carbodiimide bond integrity through terminal sterilization requires specialized equipment that extends facility qualification timelines.
- Liquid-to-powder formulation conversion:Surgeon training and applicator compatibility recertification slow adoption of room-temperature-stable alternatives despite logistical advantages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gelatin Bone Glue Market |
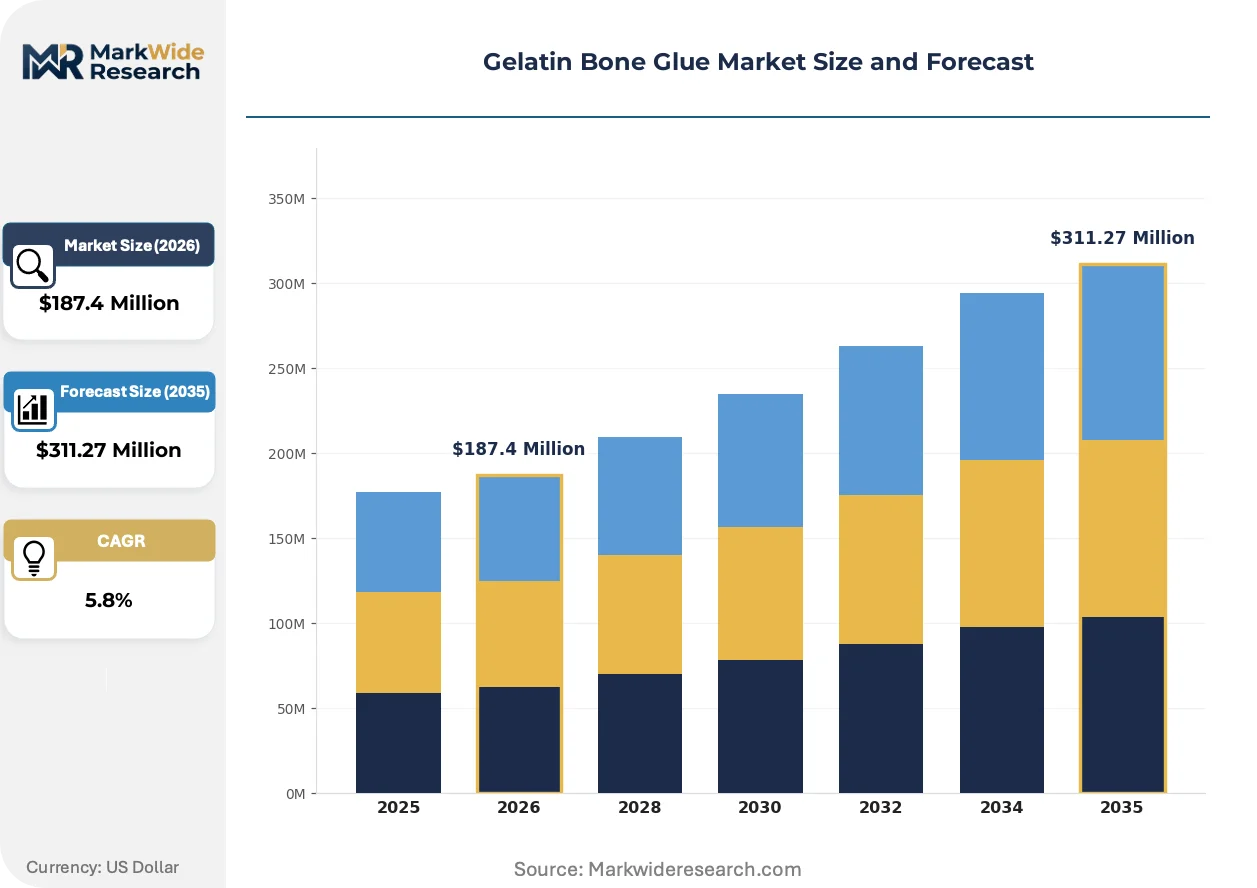
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Formulation, Powder Formulation, Spray, Gel End User: Hospitals, Clinics, Ambulatory Surgical Centers, Research Labs Application: Orthopedic Surgery, Dental Procedures, Wound Healing, Tissue Engineering Material: Porcine Gelatin, Bovine Gelatin, Fish Gelatin, Others |
| Companies Covered | Becton, Dickinson and Company, Integra LifeSciences Corporation, Johnson & Johnson, RevBio, Inc., Artivion, Inc., Baxter International Inc., B. Braun Melsungen AG, GELITA, CryoLife, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gelatin Bone Glue Market Evolving Landscape
Controlled-dispense applicator systems and cryogenic-compatible chemistries are compressing the gap between liquid and powder formulation performance, while regulatory evidence requirements reshape competitive moats around quality-system maturity.
Modified carbodiimide cross-linking chemistry is miniaturizing the performance gap between standard liquid formulations and specialized cryogenic-compatible adhesives. Ambulatory surgical centers in Germany and the United States are piloting these systems for outpatient arthroscopy, compressing the addressable market for premium-priced legacy products.
MDR's enhanced clinical-evidence demands for absorbable implants have extended European certification timelines, forcing manufacturers to consolidate pipeline priorities. The regulation most heavily impacts mid-tier suppliers without captive clinical-trial infrastructure, pushing them toward predicate-device strategies or partnership models with established notified bodies.
Hospital GPO contract consolidation is concentrating procurement leverage among three dominant purchasing coalitions in the United States. Independent orthopedic clinics and ambulatory centers are responding by forming regional buying groups, fragmenting the channel structure that previously locked in formulary placement for integrated manufacturers.
Gelatin Bone Glue Market Segmentation
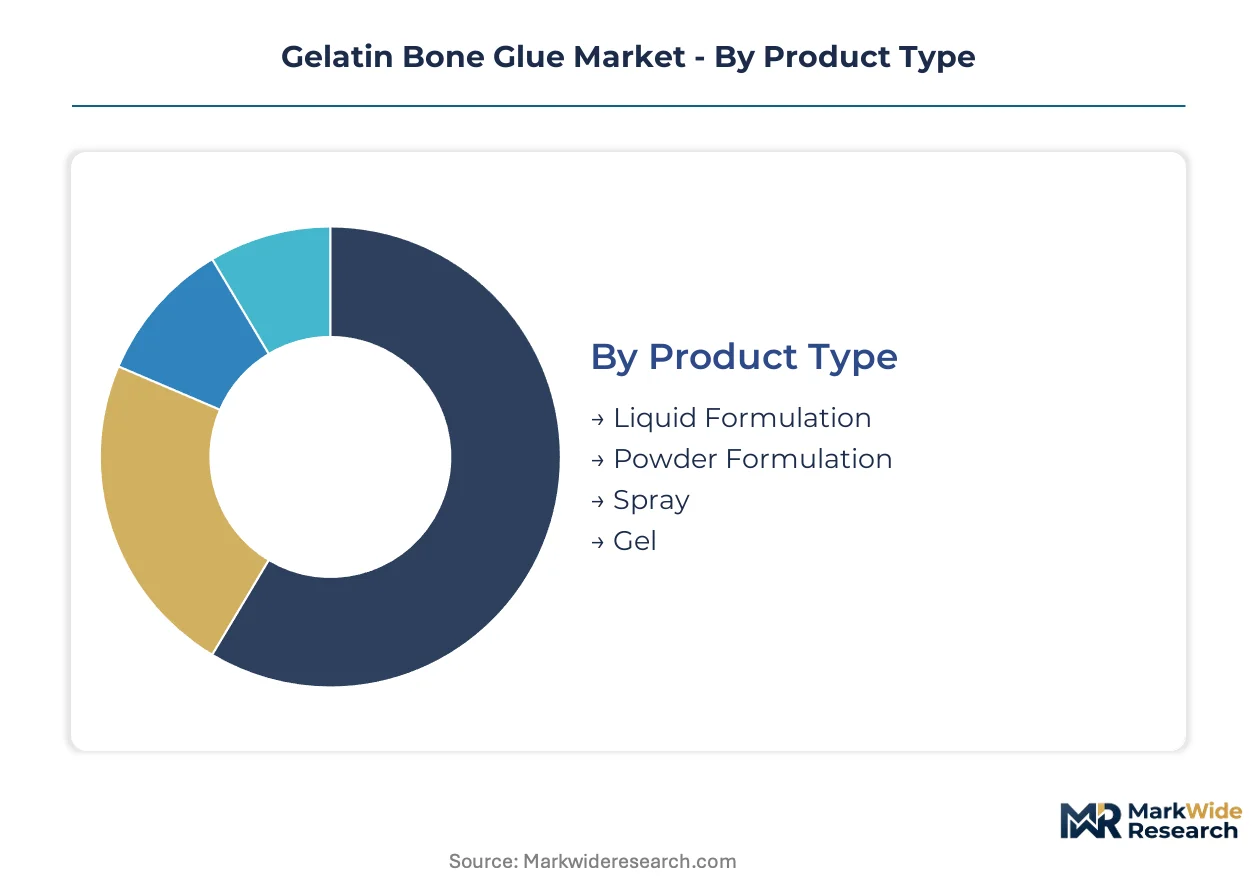
Gelatin bone glue segments diverge sharply by thermal stability requirements and sterilization compatibility. Procurement patterns cluster around formulation handling convenience versus surgical performance specifications.
Product Type:
Liquid formulations dominate domestic hospital consumption in Germany and the United States, while powder variants find export traction in markets with weaker cold-chain infrastructure.
- Liquid Formulation:Denatured collagen matrices in aqueous suspension cross-linked with aldehydes or carbodiimides, optimized for controlled-dispense applicator systems. Tertiary hospital orthopedic departments in Germany concentrate procurement around this format due to surgeon familiarity and immediate wet-surface bonding performance. The format locks in formulary placement through GPO contract structures that penalize switching costs.
- Powder Formulation:Lyophilized collagen matrices requiring reconstitution, engineered for room-temperature stability across extended storage windows. Ambulatory surgical centers in the United States drive adoption as reduced shipping costs and eliminated cold-chain dependency compress total procurement expenditure. The segment gains fastest share where outpatient arthroscopy volume expands.
- Spray:Aerosolized delivery systems for irregular wound geometries, finding niche application in trauma centers.
- Gel:Thixotropic formulations for controlled placement in confined surgical fields, common in spinal fusion procedures.
Liquid formulation commands the established base. The steepest expansion runs through powder formulation.
End User:
Procurement authority concentrates in institutions with sterilization infrastructure, fragmenting as regional buying groups challenge consolidated GPO networks.
- Hospitals:Tertiary care centers with captive sterilization validation capabilities and established quality management systems. German university hospitals anchor volume through arthroplasty and spinal fusion procedure density, leveraging backward-integrated supply chains from GELITA's manufacturing base.
- Ambulatory Surgical Centers:Outpatient facilities prioritizing room-temperature-stable inventory and reduced logistics overhead. United States pilot programs for modified carbodiimide chemistry compress the performance gap with hospital-grade liquid systems, enabling procurement outside traditional GPO channels.
- Clinics:Independent orthopedic practices with limited sterilization infrastructure, dependent on pre-sterilized single-use formats.
- Research Labs:Academic and commercial R&D facilities driving formulation innovation, particularly in tissue engineering applications.
Hospital procurement locks in the revenue base. Ambulatory surgical centers are climbing the fastest as outpatient migration accelerates.
Application:
Procedure volume and reimbursement density determine segment economics, with orthopedic surgery commanding premium pricing through allograft compatibility requirements.
- Orthopedic Surgery:Arthroplasty, spinal fusion, and trauma reconstruction demanding wet-surface adhesion at physiological pH. Cryogenic compatibility requirements for allograft procedures exclude standard formulations, creating a protected segment for specialized chemistries. German and United States tertiary centers drive procedural pull.
- Wound Healing:Chronic and acute wound closure applications, expanding as ambulatory centers seek alternatives to suture-based closure in diabetic foot and pressure ulcer management.
- Dental Procedures:Periodontal and maxillofacial applications with specialized biocompatibility requirements under ISO 10993 testing protocols.
- Tissue Engineering:Scaffold applications in regenerative medicine, currently research-phase with limited commercial volume.
Orthopedic surgery anchors the value pool. Wound healing is expanding most quickly as reimbursement codes adapt to adhesive-based closure.
Material:
Supply geography and import restrictions fragment sourcing strategies, with thermal gelation profiles determining clinical suitability.
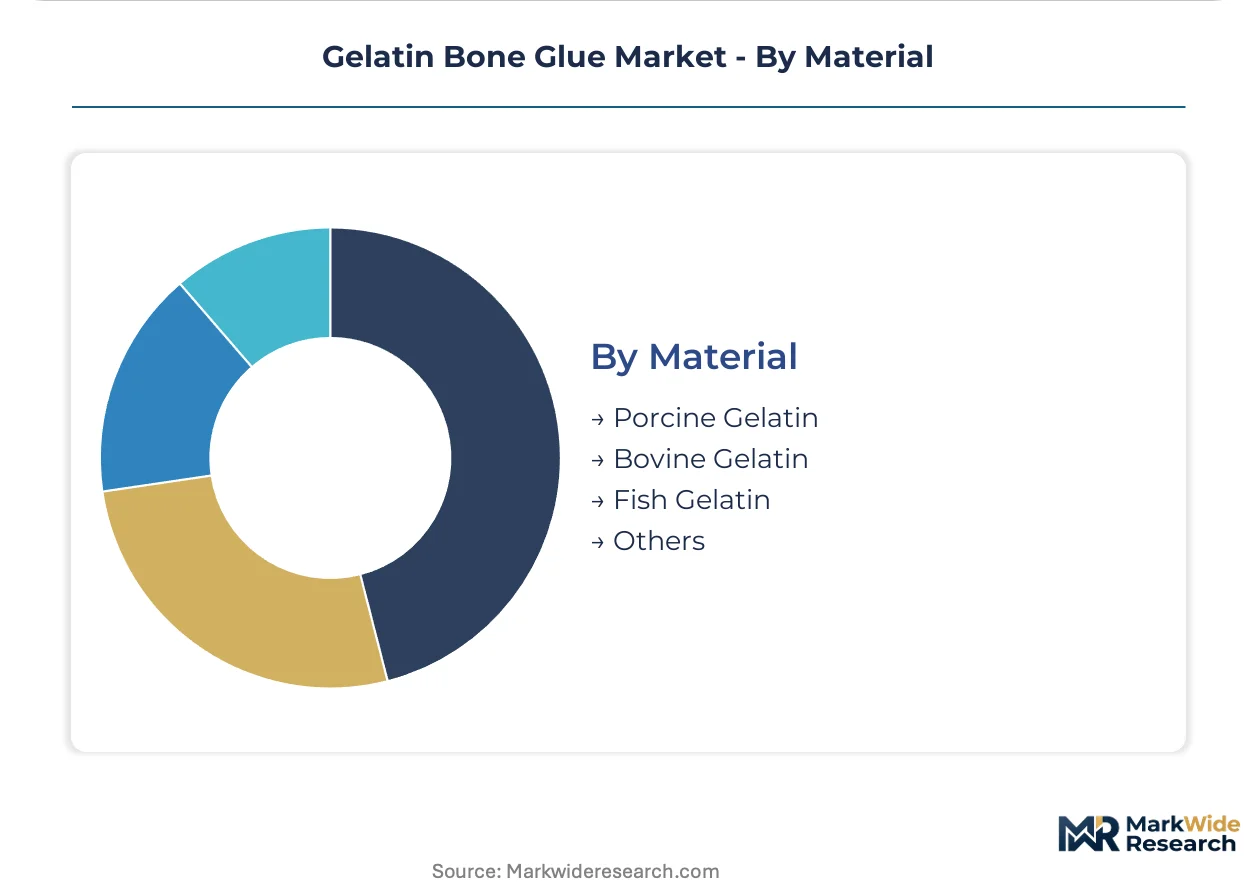
- Porcine Gelatin:Collagen derived from swine sources with thermal gelation characteristics matching human tissue more closely than alternatives. German manufacturing clusters and United States procurement networks concentrate demand here, though BSE-unrelated sourcing provides regulatory clearance advantages in Japan and European jurisdictions with bovine restrictions.
- Bovine Gelatin:Bovine-derived collagen facing sourcing constraints from BSE-related import restrictions in Japan and several European markets. Supply-chain reconfiguration costs limit formulation flexibility for device assemblers without captive collagen production.
- Fish Gelatin:Marine-sourced alternatives with distinct thermal profiles, finding niche adoption where religious or cultural constraints exclude mammalian sources.
- Others:Recombinant and synthetic collagen mimetics, currently pre-commercial with extended regulatory timelines.
Porcine gelatin holds the dominant position. Fish gelatin is gaining share fastest where cultural procurement constraints intersect with regulatory clearance efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany exceeds that in the United States by a meaningful margin, driven by GELITA's captive collagen supply and proximity to dense orthopedic clusters. Japan commands premium positioning through PMDA biocompatibility barriers that filter out non-compliant suppliers. Emerging procurement channels in India and Brazil reshape traditional volume-concentration patterns.
Germany
Arthroplasty and spinal fusion volumes at university hospitals in Berlin and Munich drive procedural demand for wet-surface bonding agents. The EU MDR reclassification of absorbable surgical adhesives extends certification timelines, favoring incumbents with established quality management systems. GELITA's manufacturing base in Eberbach anchors backward-integrated supply chains that control input quality and batch consistency for domestic orthopedic clusters.
United States
Tertiary hospital orthopedic departments in Boston and New York expand arthroscopy volumes, creating pull for controlled-dispense applicator systems. FDA 510(k) Class II clearance pathways accelerate time-to-revenue for predicate-device equivalents, rewarding early regulatory investment. Ambulatory surgical centers in Texas and Florida pilot powder formulations to eliminate cold-chain dependency and reduce logistics overhead.
Japan
PMDA biocompatibility testing standards under ISO 10993 protocols elevate barrier costs for new entrants while protecting incumbents with localized testing infrastructure. Tokyo and Osaka medical centers concentrate demand for cryogenic-compatible formulations in allograft procedures. BSE-related import restrictions on bovine-derived materials limit formulation flexibility and reinforce porcine gelatin procurement dominance.
China
NMPA medical device registration requirements for absorbable implants extend market access timelines for foreign manufacturers. Shanghai and Beijing hospital systems build captive sterilization validation capabilities to support domestic orthopedic procedure expansion. Provincial procurement coalitions concentrate purchasing leverage, fragmenting the channel structure that previously favored multinational formulary placement.
India
CDSCO medical device rules for Class C absorbable implants create compliance thresholds that filter out informal suppliers. Mumbai and Delhi-NCR orthopedic centers expand arthroplasty volumes as reimbursement codes adapt to adhesive-based closure techniques. Regional buying groups among independent clinics challenge consolidated hospital procurement networks, opening channels for room-temperature-stable powder formulations.
Gelatin Bone Glue Market Competitive Landscape
Concentration sits with backward-integrated collagen producers and diversified medical device conglomerates that control sterilization infrastructure. The vendor base stratifies across three tiers: captive gelatin manufacturers, diversified orthopedic device suppliers, and pure-play surgical adhesive specialists. Strategic moves cluster around GPO contract consolidation, cryogenic compatibility certification, and ambulatory surgical center channel development.
Within the diversified medical device tier, Johnson & Johnson and Baxter International Inc. exemplify scale-driven positioning through hospital GPO networks and sterilization infrastructure. GELITA occupies a distinct archetype as the captive supply anchor, leveraging porcine and bovine collagen backward integration to control input quality. Among surgical adhesive specialists, Integra LifeSciences Corporation and CryoLife, Inc. represent focused positioning around biologic compatibility and allograft procedure requirements.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| Integra LifeSciences Corporation |
| Johnson & Johnson |
| RevBio, Inc. |
| Artivion, Inc. |
| Baxter International Inc. |
| B. Braun Melsungen AG |
| GELITA |
| CryoLife, Inc. |
| Others |
Value Network & Pricing Analysis
Porcine gelatin displacement of bovine alternatives simultaneously redraws supply geography toward German manufacturing clusters and compresses pricing premiums for cryogenic-compatible formulations as raw-material thermal-matching becomes the dominant cost driver.
Pricing Analysis
The customization-premium spread between cryogenic-compatible formulations and standard liquid products spans roughly forty percent, with ISO 10993 biocompatibility certification tiers and surgeon training bundling as the primary differentiation levers. Three-tier pricing structure across premium cryogenic-compatible, standard hospital-grade, and economy powder formulations dominates transactional arrangements. Pricing pressure stems from ambulatory surgical center procurement consolidation demanding room-temperature stability without performance compromise. Independent orthopedic clinics exhibit highest price sensitivity; tertiary hospital GPO contracts lock in lowest sensitivity through formulary switching penalties.
Supply Chain Analysis
Cross-linked matrix sterilization validation capacity in Germany, the United States, and Japan underwrites finished-product availability, with aldehyde bond integrity preservation as the critical chokepoint extending facility qualification timelines. Raw material draws from porcine collagen processors in Germany and bovine gelatin suppliers in South America, with carbodiimide cross-linking chemistry as the specialized input tethered to pharmaceutical-grade reagent channels. Single-source vulnerability concentrates in GELITA's Eberbach manufacturing base for European hospital supply. Distribution runs through hospital GPO networks in the United States and direct university hospital procurement in Germany, with ambulatory center regional buying groups fragmenting downstream channel control.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity opens as ambulatory surgical center expansion splinters procurement authority away from consolidated hospital GPO networks, creating niche entry points for formulation specialists and cold-chain-independent suppliers.
For Market Incumbents: Consolidate sterilization infrastructure ownership and backward integration into porcine collagen supply chains to defend against powder formulation entrants eroding liquid product premiums. Lock in formulary placement through GPO contract renewal acceleration before regional buying groups achieve critical mass in Texas and Florida ambulatory markets. Cryogenic compatibility certification investment remains the priority defensive lever. For New Entrants and Emerging Players: Differentiate on room-temperature stability performance to capture ambulatory surgical center procurement outside traditional hospital channels. Target powder formulation segments in United States outpatient arthroscopy as the most penetrable white space, with modified carbodiimide chemistry as the technical wedge. Pursue direct-to-clinic distribution bypassing GPO intermediaries as the go-to-market angle. For Investors and Strategic Acquirers: EU MDR reclassification of absorbable surgical adhesives reshapes the acquisition landscape by extending certification timelines twelve to eighteen months and filtering out mid-tier suppliers without captive clinical-trial infrastructure. Five-to-ten year viability favors backward-integrated collagen producers with established notified body relationships over pure-play device assemblers. Watch ISO 10993 biocompatibility test revision timing as the inflection signal for reimbursement eligibility shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Cryogenic Compatibility Certification | Baxter International's sterilization infrastructure anchors allograft procedure market access. |
| Backward Integration into Collagen Supply | GELITA's Eberbach manufacturing base controls porcine raw material quality and batch consistency. |
| Ambulatory Surgical Center Channel Development | Powder formulation room-temperature stability opens procurement outside hospital GPO networks. |
| MDR Clinical Evidence Generation | Enhanced absorbable implant requirements extend European certification timelines for new entrants. |
| PMDA Biocompatibility Pathway Investment | Localized Tokyo testing infrastructure captures Asia-Pacific orthopedic procedure volume. |
Research Methodology
Cross-validation between surgeon interviews and hospital procurement database analysis anchors the qualitative findings on formulation preference and GPO contract structure. Primary interviews with orthopedic surgeons, biomedical engineers, GPO contracts managers, and ambulatory center procurement leads combined with secondary validation from FDA 510(k) filings, EU MDR notified body databases, hospital sterilization validation records, and CMS Medicare reimbursement codes. Bottom-up procedure volume estimates and top-down manufacturer revenue triangulation reconcile segmentation outputs.
Sensitivity analysis across porcine gelatin cost volatility, ambulatory surgical center adoption curves, and MDR certification timeline extensions tests forecast robustness. The analytical framework models product type, end user institution category, application procedure segment, and material sourcing origin across the projection horizon. CAGRs derive from segment-level procedure growth rates applied to pricing trajectory assumptions, with cryogenic compatibility premium erosion and powder formulation share gain as key medical device industry inputs.
The analysis sits within stated boundaries; outcomes outside sustained arthroplasty volume expansion or stable collagen raw material pricing would require recalibration. Forecasts reflect documented assumptions regarding regulatory timeline stability and reimbursement code adaptation speed. Practitioners should keep alternative scenarios live as EU MDR enforcement patterns and ambulatory center accreditation standards evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
MS Polymer Hybrid Adhesives and Sealants Market
Adhesives & Sealants
Co-Polymer Sealants Market
Adhesives & Sealants
US Adhesives and Sealants Market
Adhesives & Sealants
Global Bioadhesive Market
Adhesives & Sealants
North America Contact Adhesives Market
Adhesives & Sealants
China Adhesives Market
Adhesives & Sealants
Asia-Pacific Reactive Adhesives Market
Adhesives & Sealants
Skin Adhesives Market
Adhesives & Sealants
Spray Glue Market
Adhesives & Sealants
Mirror Adhesive Market
Adhesives & Sealants
Hybrid Silane-Terminated Polymer Adhesives for EV Battery Pack Assembly Market
Adhesives & Sealants
Global Ethyl Methacrylate (97-63-2) Market
Adhesives & Sealants
Europe EVA Adhesives Market
Adhesives & Sealants
Solvent Based Laminating Adhesives Market
Adhesives & Sealants
Applicator Tips Market
Adhesives & Sealants
Middle-East and Africa Electronics Adhesives Market