
 China Adhesives Market | 2026-2036
China Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
China Adhesives Market Outlook
Asset-light leasing models for polymer mixing equipment is narrowing the capital barrier for mid-scale entrants in the China adhesives sector. Tex Year Group leverages captive resin supply to sustain margin stability across southern provinces. Hubei Huitian New Materials anchors its position through R&D intensity in high-temperature automotive grades. Kangda New Materials differentiates via water-based technology leadership serving packaging converters in the Pearl River Delta.
Adhesives are polymeric substances formulated to bond substrates through surface attachment and internal cohesion, with specifications ranging from shear strengths of 5 MPa for pressure-sensitive tapes to 40 MPa for structural epoxies cured at elevated temperatures. Their primary industrial purpose is to replace mechanical fasteners in assemblies where weight reduction, stress distribution, or sealing integrity matters. Epoxy formulations dominate structural bonding in wind turbine blade manufacturing where load-bearing requirements are extreme. Water-based acrylics lead packaging applications as food-contact regulations tighten under GB standards. Reactive polyurethane systems represent the fastest-growing technology segment in automotive assembly where cure speed determines line throughput.
China's MIIT enforces GB 33372 limits on solvent-based adhesive volatile organic compound content, pushing manufacturers toward water-based and hot melt platforms. SAMR oversees product quality certification under强制性产品认证 rules that govern construction-grade adhesive market access. The country's dual carbon goals from MEE are accelerating energy audits at polymer production facilities. Stakeholders must monitor how provincial environmental enforcement variance between Jiangsu and Guangdong affects formulation compliance costs and regional supply allocation.
Market Dynamics
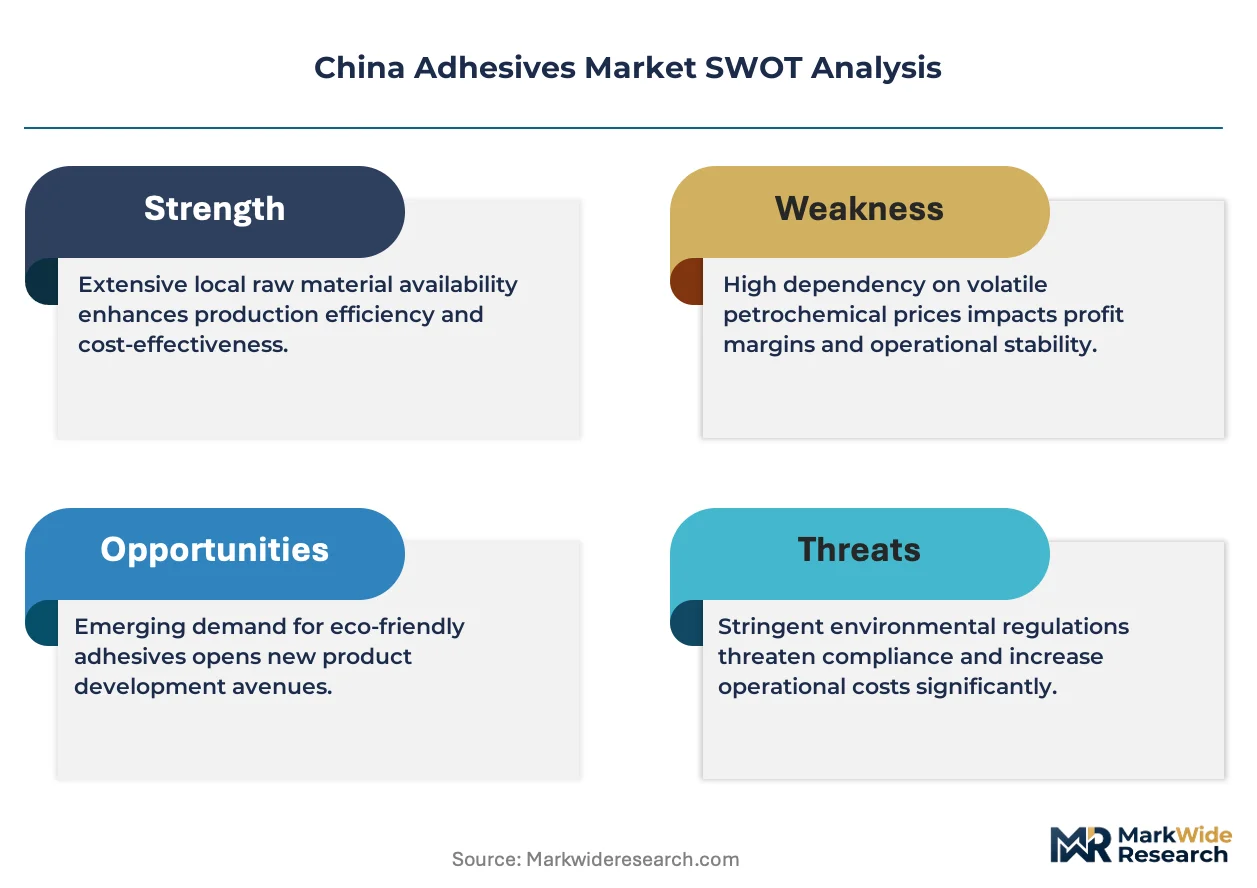
China's GB 33372 VOC emission limits are compressing solvent-based formulation margins while redirecting capital toward water-based and hot-melt platforms across the Yangtze River Delta manufacturing belt.
Growth Catalysts
- Electric vehicle battery assembly:Automotive OEMs in Shanghai and Guangzhou are expanding structural bonding applications in battery pack manufacturing, driving demand for reactive polyurethane systems with rapid cure profiles.
- GB standards tightening:MIIT enforcement of volatile organic compound limits is accelerating manufacturer migration from solvent-based to compliant water-based acrylic and hot-melt adhesive platforms.
- Wind turbine manufacturing:Load-bearing epoxy formulations are capturing expanded share in blade assembly applications as domestic turbine production scales in coastal provinces.
Market Restraints
- Petrochemical feedstock volatility:Crude oil price fluctuations transmit directly to epoxy resin and polyurethane precursor costs, compressing formulation margins for non-integrated producers.
- Specialty additive import dependence:Curing agents and performance modifiers concentrate among Japanese and German suppliers, exposing domestic formulators to currency and logistics risk.
- Cure speed limitations:Water-based acrylics cannot match hot-melt line speeds in high-throughput packaging applications, constraining penetration in Pearl River Delta converter operations.
Strategic Opportunities
- Central China manufacturing migration:Henan and Hubei provinces offer underpenetrated demand as electronics assembly shifts inland from coastal cost centers.
- SAMR certification acceleration:Streamlined强制性产品认证 pathways for construction-grade adhesives create first-mover advantage for compliant domestic producers in infrastructure applications.
- UV-curable technology convergence:Combination of LED curing hardware with acrylate formulations enables energy-efficient bonding in medical device assembly, opening pharmaceutical packaging verticals.
Industry Challenges
- Polymer chemist talent scarcity:Formulation expertise in high-temperature automotive grades concentrates among senior researchers at state-owned institutes, constraining mid-scale competitor R&D scaling.
- Dual carbon audit compliance:MEE energy audits at polymer production facilities require capital-intensive process heat recovery and solvent recovery system upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Adhesives Market |
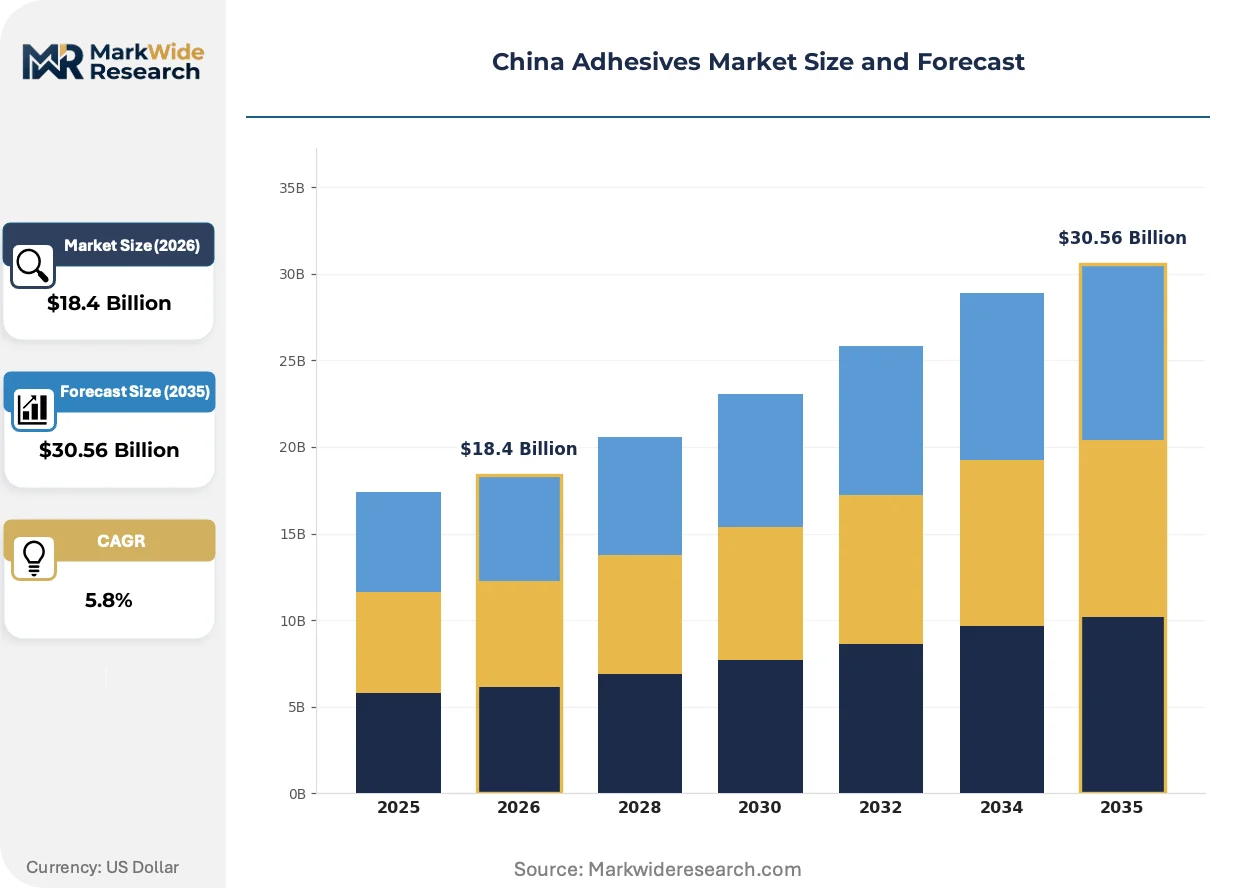
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $30.56 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Silicone, Acrylic End User: Automotive, Construction, Packaging, Electronics Application: Bonding, Coating, Sealing, Assembly Technology: Solvent-based, Water-based, Hot Melt, Reactive |
| Companies Covered | Tex Year Group, Guibao Technology, Kangda New Materials, Hubei Huitian New Materials, Antai New Materials, Fokis New Materials, Sanvo Chemical, Beijing Comens New Materials, Comens New Materials, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Adhesives Market Strategic Shifts
Formulation chemistry is converging with process automation as manufacturers seek cure profiles that match robotic assembly speeds while navigating tightening environmental compliance frameworks.
Hybrid epoxy-silane formulations are hybridizing structural bonding capabilities with flexible sealing performance. Wind turbine blade manufacturers in Jiangsu and Zhejiang are adopting these systems at accelerating rates to reduce mechanical fastener counts. The technology is hybridizing previously separate adhesive and sealant procurement categories into single-specification platforms.
GB 33372-2020 VOC content limits are forcing solvent-based producers toward water-based platform investments. MIIT enforcement variance between Jiangsu and Guangdong provinces is creating regional formulation compliance cost differentials. Packaging converters in the Pearl River Delta are responding fastest through hot-melt system conversions.
Specification bundling is consolidating procurement decisions at electronics contract manufacturers. Direct adhesive supply agreements are displacing distributor-mediated purchasing in Yangtze River Delta clusters. This pattern is most visible among smartphone assembly operations where line certification requirements favor single-source technical partnerships over multi-vendor sourcing.
China Adhesives Market Segmentation
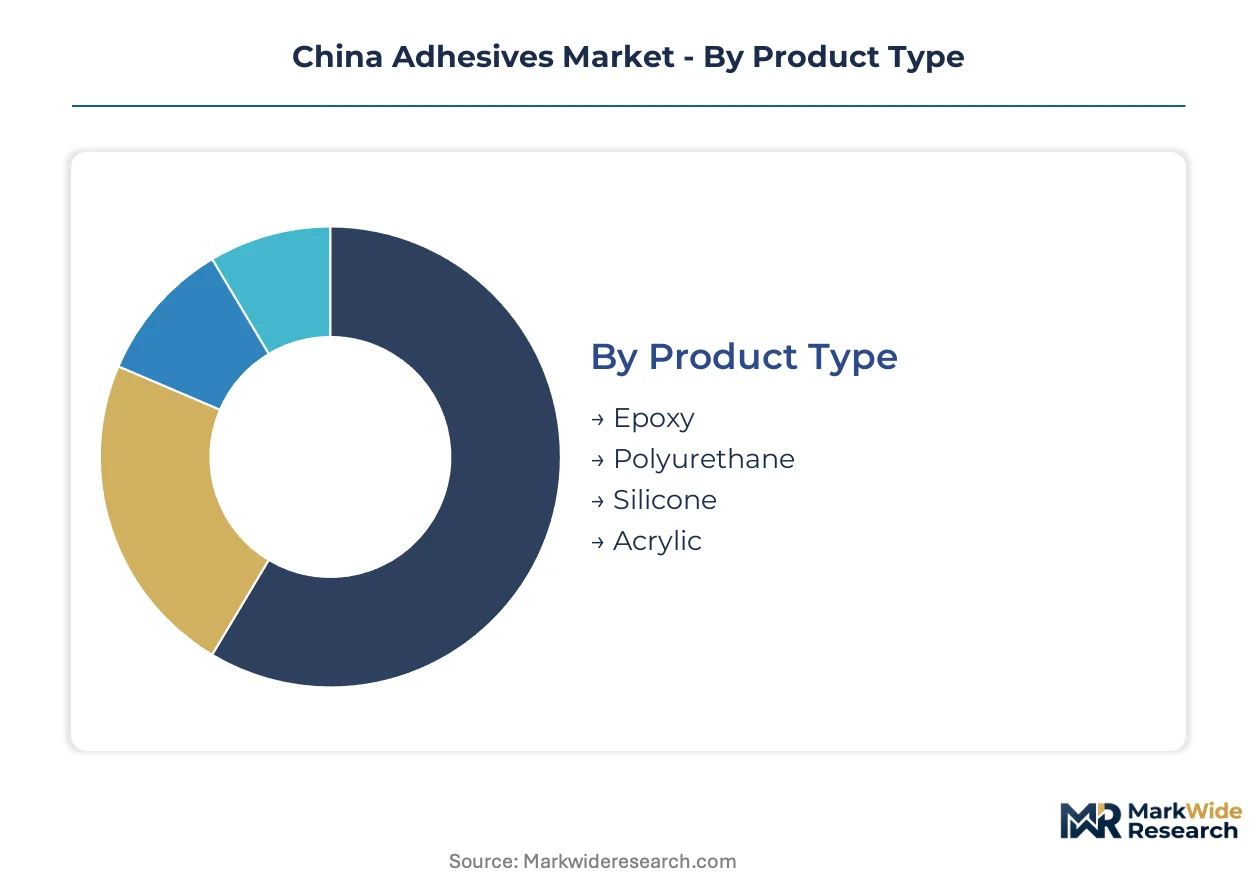
Adhesive formulation diversity across China's industrial base demands precise segment mapping. End-use specifications from Shanghai automotive plants to Shenzhen electronics clusters drive divergent technical requirements.
Product Type:
Epoxy through acrylic formulations span structural load-bearing to flexible pressure-sensitive applications across coastal manufacturing belts.
- Epoxy:Two-part thermosetting systems cure through amine or anhydride crosslinking to achieve shear strengths exceeding structural thresholds. Wind turbine blade manufacturers in Jiangsu and Zhejiang specify these grades for root-to-hub bonding where cyclic loading resistance determines 25-year service life.
- Polyurethane:Reactive systems polymerize through isocyanate-hydroxyl reactions, delivering toughness across temperature extremes. Battery pack assemblers in Guangzhou favor rapid-cure variants for module-to-housing attachment where line throughput constraints dominate.
- Silicone:Room-temperature-vulcanizing elastomers maintain flexibility across thermal cycling ranges for electronics potting and automotive gasketing.
- Acrylic:Water-dispersed or solvent-borne formulations dominate pressure-sensitive tape production for consumer goods packaging in the Pearl River Delta.
Established volume favors epoxy in infrastructure-scale bonding; emerging adoption favors polyurethane in electric vehicle platforms.
End User:
Customer concentration patterns split between capital-intensive OEMs and specification-driven contract manufacturers.
- Automotive:OEM assembly plants in Shanghai and Guangzhou specify structural adhesives for body-in-white bonding and battery thermal management. GB standards compliance adds formulation certification layers absent in export-only supply.
- Construction:Infrastructure-grade products face SAMR强制性产品认证 requirements for structural glazing and cladding attachment. Provincial enforcement variance between Jiangsu and Guangdong affects market access timelines.
- Packaging:Converter operations in the Pearl River Delta prioritize hot-melt line speeds over bond strength for folding carton and flexible film applications.
- Electronics:Contract manufacturers in the Yangtze River Delta demand ultra-low outgassing grades for smartphone display lamination and semiconductor encapsulation.
Construction-grade certification barriers protect incumbents; electronics contract manufacturing offers volume scaling for compliant entrants.
Application:
Functional purpose determines formulation chemistry selection and curing equipment capital requirements.
- Bonding:Structural load transfer applications specify epoxies and toughened acrylics for permanent substrate attachment. Wind turbine blade root joints represent the most demanding specification tier.
- Coating:Protective film formation demands controlled viscosity and sag resistance for corrosion protection in marine and industrial environments.
- Sealing:Gap-filling elastomers accommodate joint movement in automotive powertrain and building envelope applications. Hybrid epoxy-silane systems are displacing separate adhesive and sealant specifications.
- Assembly:Temporary fixturing through pressure-sensitive or cyanoacrylate platforms enables component positioning before permanent curing.
Sealing applications gain specification bundling momentum; bonding retains premium pricing power.
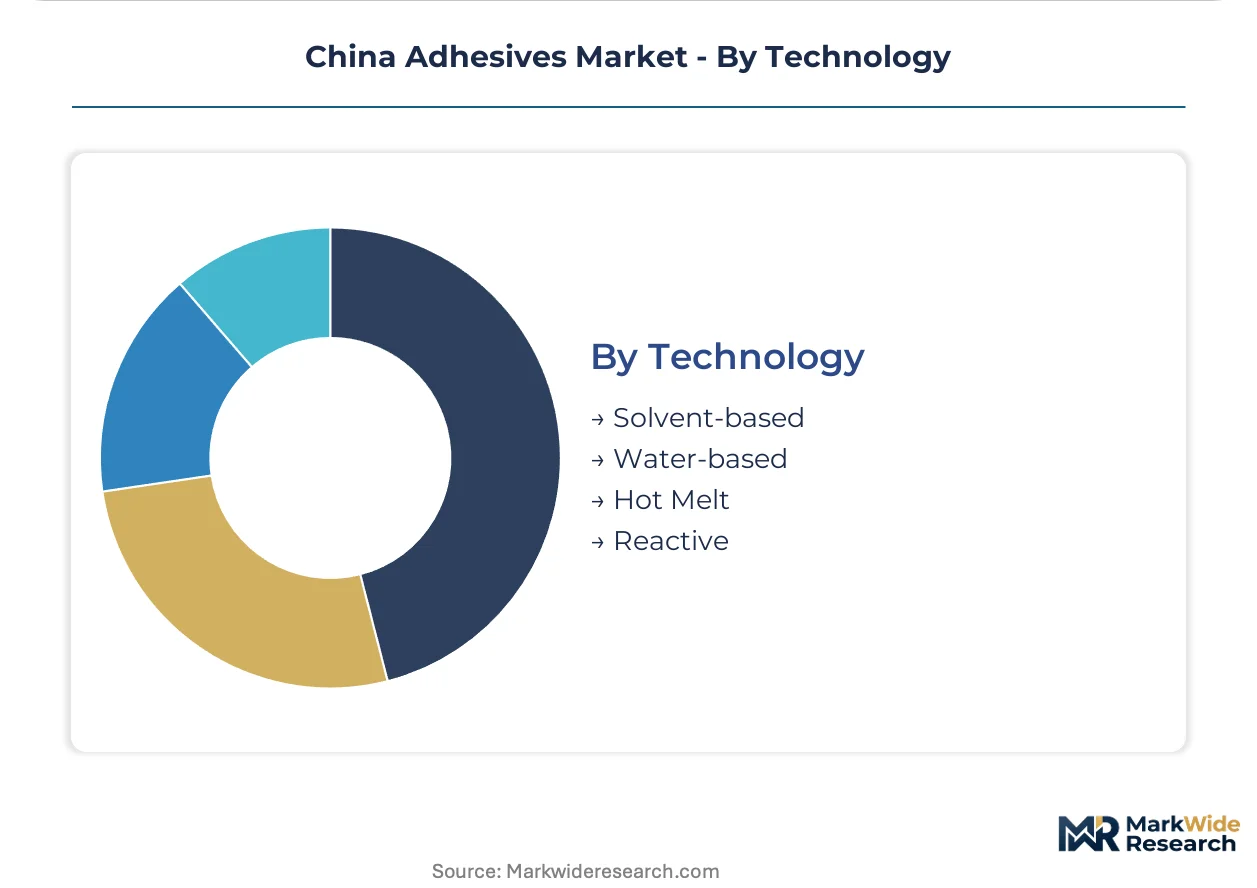
Technology:
Environmental compliance pressure from MIIT enforcement is restructuring platform economics across formulation investments.
- Solvent-based:Traditional systems face margin compression under GB 33372 VOC content limits. Remaining demand concentrates in specialty automotive refinish and industrial maintenance where performance specifications resist substitution.
- Water-based:Acrylic dispersions dominate packaging and wood bonding applications. Cure speed limitations versus hot-melt alternatives constrain penetration in high-throughput converter operations.
- Hot Melt:Thermoplastic EVA and polyolefin formulations deliver instant green strength for packaging and hygiene product assembly. The technology represents the steepest expansion trajectory in Pearl River Delta manufacturing migration.
- Reactive:Two-component polyurethane and epoxy systems command structural applications where cured properties justify mixing equipment and pot-life management complexity.
Reactive systems retain structural premium positioning; water-based platforms face hot-melt displacement in packaging speed races.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the Yangtze River Delta while Pearl River Delta converters absorb margin pressure from hot-melt equipment conversion costs. Provincial enforcement variance on GB 33372 VOC limits creates arbitrage opportunities between Jiangsu and Guangdong formulation sourcing.
Yangtze River Delta
Automotive OEM assembly plants and electronics contract manufacturers anchor adhesive consumption in Shanghai, Suzhou, and Hangzhou. MIIT enforcement of GB 33372 standards is tightest in Jiangsu, accelerating water-based platform investments. Battery pack bonding operations in Ningbo and Changzhou specify rapid-cure polyurethane systems for electric vehicle production lines.
Pearl River Delta
Packaging converters in Shenzhen and Dongguan prioritize hot-melt line speeds over bond strength for folding carton applications. Guangdong provincial environmental enforcement lags Jiangsu by 12-18 months on solvent-based phase-out timelines. Smartphone assembly clusters in Huizhou demand ultra-low outgassing grades for display lamination processes.
Beijing-Tianjin-Hebei
Wind turbine blade manufacturing in Tianjin and Cangzhou specifies load-bearing epoxy formulations for root-to-hub bonding. MEE dual carbon audits concentrate on polymer production facilities in Hebei industrial zones. Infrastructure-grade construction adhesives face SAMR强制性产品认证 bottlenecks in Beijing market access.
Sichuan-Chongqing
Electronics assembly migration from coastal provinces is expanding adhesive demand in Chengdu and Chongqing manufacturing parks. Western China logistics costs elevate formulation prices 8-12% versus Yangtze River Delta sourcing. Local formulators lack curing agent supply chain integration, exposing margins to Japanese supplier currency risk.
Shandong Peninsula
Petrochemical feedstock integration in Qingdao and Yantai supports epoxy resin production for domestic formulation supply. Provincial industrial policy prioritizes adhesive-grade polymer capacity expansion through 2027. Coastal wind turbine installation projects in Weihai are adopting hybrid epoxy-silane systems for blade assembly.
China Adhesives Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in resin and curing agent supply. The vendor base arranges across three tiers: multinational formulation houses with full technology portfolios, domestic integrated producers with captive resin supply, and regional formulators serving single-industry verticals. Strategic moves concentrate on backward integration into epoxy resin production and SAMR certification acceleration for construction-grade market access.
Among domestic integrated producers, Tex Year Group anchors the southern province supply position through captive resin operations. Hubei Huitian New Materials occupies a position exemplifying R&D-intensive specialization in high-temperature automotive grades. Kangda New Materials represents water-based technology leadership serving packaging converters. These three archetypes—integrated supply, R&D-driven specification, and platform technology—define competitive positioning vectors for mid-scale entrants.
| Leading Market Players |
|---|
| Tex Year Group |
| Guibao Technology |
| Kangda New Materials |
| Hubei Huitian New Materials |
| Antai New Materials |
| Fokis New Materials |
| Sanvo Chemical |
| Beijing Comens New Materials |
| Comens New Materials |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in epoxy resin production across Shandong Peninsula is compressing formulation margins while concentrating pricing power among integrated producers with captive feedstock supply. Utilization rates below 70% at non-integrated facilities are forcing spot-market discounting, whereas backward-integrated players leverage in-house polymer capacity to maintain stable contract pricing with Yangtze River Delta automotive OEMs.
Pricing Analysis
The customization-premium spread between configured-to-order structural grades and standard packaging formulations runs 40-60% across domestic supply. Pricing stratifies across premium SAMR-certified construction grades, standard industrial formulations, and economy packaging adhesives. Cost compression in solvent-based tiers is intensifying because GB 33372 compliance investments are not fully recoverable through price premiums. Contract manufacturers in electronics assembly exhibit the highest price sensitivity due to specification bundling and direct supplier negotiations, while wind turbine OEMs prioritize performance over cost in root-bonding applications.
Supply Chain Analysis
Supplier-financing through 90-120 day payment terms and supply-chain finance facilities has become standard for mid-scale formulators sourcing curing agents from Japanese specialty chemical houses. Feedstock supply concentrates in China, South Korea, and Japan for epoxy resins and polyurethane precursors. Formulation chemistry draws from petrochemical derivatives, amine curing agents, and performance-modifying silanes. Single-source vulnerability in specialty additive supply exposes domestic producers to yen-denominated cost volatility. Distribution runs through direct technical partnerships with automotive OEMs and electronics contract manufacturers, bypassing traditional distributor channels in high-specification segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's adhesives sector is a high-growth disruption driven by electric vehicle platform expansion and MIIT environmental enforcement tightening formulation compliance requirements.
For Market Incumbents: Build certification moats through accelerated SAMR强制性产品认证 pathways for construction-grade products before provincial enforcement variance narrows. Defensive consolidation should prioritize captive curing agent supply agreements with Japanese suppliers to hedge currency exposure. Threat of water-based platform substitution by hot-melt alternatives in Pearl River Delta packaging demands line-speed matching R&D investment. For New Entrants and Emerging Players: Build out white-space positions in Central China electronics assembly migration to Henan and Hubei provinces where incumbent coverage remains thin. The most penetrable segment is UV-curable medical device bonding where pharmaceutical packaging verticals lack established supplier relationships. Go-to-market execution should emphasize asset-light polymer mixing equipment leasing to bypass capital barriers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated producers with captive resin supply and long-term automotive OEM contracts. Long-term viability across the projection horizon favors targets with dual carbon audit compliance already achieved and GB standards certification in place. Monitor MIIT enforcement variance between Jiangsu and Guangdong as the inflection signal for regional margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epoxy Resin | Captive Shandong Peninsula feedstock supply insulates margin from petrochemical volatility. |
| SAMR Certification Acceleration | First-mover强制性产品认证 unlocks Beijing-Tianjin-Hebei infrastructure-grade construction adhesive access. |
| Hot-Melt Platform Conversion | Pearl River Delta packaging converter demand shifts toward instant green-strength thermoplastic systems. |
| UV-Curable Technology Partnership | LED curing hardware convergence opens pharmaceutical packaging and medical device assembly verticals. |
| Central China Manufacturing Migration | Chengdu and Chongqing electronics parks offer underpenetrated demand as coastal costs rise. |
Study Parameters
A spread of perspectives from adhesive formulator R&D directors, automotive OEM procurement managers, electronics contract manufacturer supply chain leads, and MIIT regulatory affairs specialists converged on the working assumptions. Primary interview insights combined with secondary validation from customs trade data, SEC filings of listed chemical producers, MIIT policy circulars, and SAMR certification databases. Bottom-up demand modeling across end-use segments triangulated against top-down polymer consumption estimates.
Demand-supply-balance dynamics anchored the analytical framework across the analysis window, with segmentation modeled by formulation chemistry, technology platform, end-use industry, and regional production cluster. CAGRs derived from installed capacity expansion timelines, electric vehicle production forecasts, and wind turbine installation pipelines. Industry-specific inputs included GB standards compliance cost trajectories and provincial environmental enforcement schedules.
Practitioners should monitor crude oil price volatility, yen-renminbi exchange rate movements, and MIIT enforcement variance across provinces for early signals. Forecasts reflect assumptions on electric vehicle adoption curves, dual carbon audit implementation timelines, and curing agent supply chain stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
United States Construction Adhesives and Sealants Market
Adhesives & Sealants
Silane Coupling Agents Market
Adhesives & Sealants
Adhesives and Sealants for Handheld Devices Market
Adhesives & Sealants
Urea Formaldehyde Concrete Market
Adhesives & Sealants
Europe Automotive Adhesives and Sealants Market
Adhesives & Sealants
Metal Glue Market
Adhesives & Sealants
Europe, Middle-East and Africa Hot-Melt Adhesives Market
Adhesives & Sealants
Conductive Glue Market
Adhesives & Sealants
Elastic Bonding Adhesive and Sealant Market
Adhesives & Sealants
Europe Adhesives and Sealants Market
Adhesives & Sealants
Lamination Adhesive Market
Adhesives & Sealants
Global Stone and Tile Adhesives and Sealants Market
Adhesives & Sealants
Skin Adhesives Market
Adhesives & Sealants
South America Contact Adhesives Market
Adhesives & Sealants
Europe Reactive Adhesives Market
Adhesives & Sealants
Debonding-on-Demand Adhesive Tapes for Electronics Dismantling Market