
 Polyurethane Adhesives and Sealants Market | 2026-2036
Polyurethane Adhesives and Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
Polyurethane Adhesives and Sealants Market Outlook
Epoxy is restructuring polyurethane economics in aerospace structural bonding as OEMs seek weight reduction and fatigue resistance. Henkel AG & Co. KGaA leverages its European formulation network to supply Airbus tier-1 facilities. 3M Company anchors North American demand through patented moisture-cure technologies. BASF SE competes on aromatic isocyanate feedstock integration.
Polyurethane adhesives and sealants are reaction products of polyols and isocyanates cured through moisture or heat activation, delivering tensile shear strengths exceeding 10 MPa for structural load-bearing joints. Their primary commercial purpose centers on bonding dissimilar substrates—metals to composites, glass to plastics—where thermal expansion mismatches demand flexible yet durable interfaces. Neutral cure formulations lead volume in electronics encapsulation due to non-corrosive byproducts protecting copper traces. Construction joints represent the fastest-growing application as prefabricated building modules require field-applied structural sealing. Liquid form dominates automotive assembly lines for robotic dispensing precision.
EPA regulates VOC emissions from adhesive formulations under 40 CFR 59, while REACH restricts aromatic isocyanate concentrations in European consumer-grade products. OSHA mandates respiratory protection standards during polyurethane spray application, elevating capital costs for smaller applicators. Stakeholders must monitor feedstock volatility in propylene oxide and MDI supply chains while positioning for low-monomer formulations ahead of tightening occupational exposure limits.
Market Dynamics
Automotive lightweighting mandates are compressing bonding cycles and favoring rapid-cure polyurethane systems over mechanical fasteners in structural assembly operations. Tier-1 suppliers now specify adhesives with sub-60-second fixture times to match robotic line speeds.
Growth Catalysts
- REACH low-VOC mandates:European reformulation requirements are accelerating waterborne and hot-melt polyurethane development for construction and consumer applications. German automotive OEMs now require sub-50 g/L VOC content in assembly adhesives.
- Prefabricated construction modules:Offsite building manufacturing in the United States and Canada demands field-applied structural sealants with 600% elongation for thermal movement accommodation. Factory-to-site logistics favor single-component moisture-cure systems.
- Wind turbine blade bonding:Rotor diameters exceeding 120 meters require polyurethane systems with fatigue resistance superior to epoxy alternatives. Blade manufacturers in Denmark and Spain specify full-scale structural adhesives for shear web-to-skin joints.
Market Restraints
- MDI feedstock concentration:Methylene diphenyl diisocyanate production clusters in the US Gulf Coast and Northeast China, exposing formulators to force majeure disruptions from hurricanes or energy rationing.
- Epoxy substitution in aerospace:Primary structural bonding in commercial aviation retains epoxy dominance due to 180°C service temperature requirements that exceed aliphatic polyurethane limits.
- OSHA respiratory protection mandates:Spray-applied polyurethane foam operations require supplied-air respirators and enclosed spray booths, elevating capital barriers for smaller construction applicators.
Strategic Opportunities
- India PLI scheme for electric vehicles:Domestic battery pack assembly incentives create demand for thermal management adhesives with flame-retardant properties. Local formulators can supply cell-to-cell bonding for two-wheeler and three-wheeler platforms.
- UV-LED cure convergence:Hybrid systems combining moisture-cure backbone with ultraviolet surface tack elimination enable instant handling strength for electronics assembly. Japanese consumer electronics manufacturers pilot this for smartphone display bonding.
- Direct-to-contractor distribution:Construction sealant manufacturers bypass traditional distributor markup through mobile-enabled ordering platforms. Brazilian residential builders now source 30-liter pails via app-based procurement with same-day jobsite delivery.
Industry Challenges
- Formulation chemist scarcity:Expertise in isocyanate-polyol stoichiometry and catalyst latency tuning concentrates among aging specialists in European and North American R&D centers.
- Dual certification timelines:Automotive adhesives require simultaneous FMVSS 302 flammability approval and OEM-specific crash-performance validation, extending product qualification to 24-36 months.
- Legacy equipment incompatibility:Hot-melt reactive polyurethane systems demand heated hoses and precision gear pumps that retrofit poorly into existing solvent-borne adhesive dispensing infrastructure at mid-sized furniture manufacturers.
Report Scope
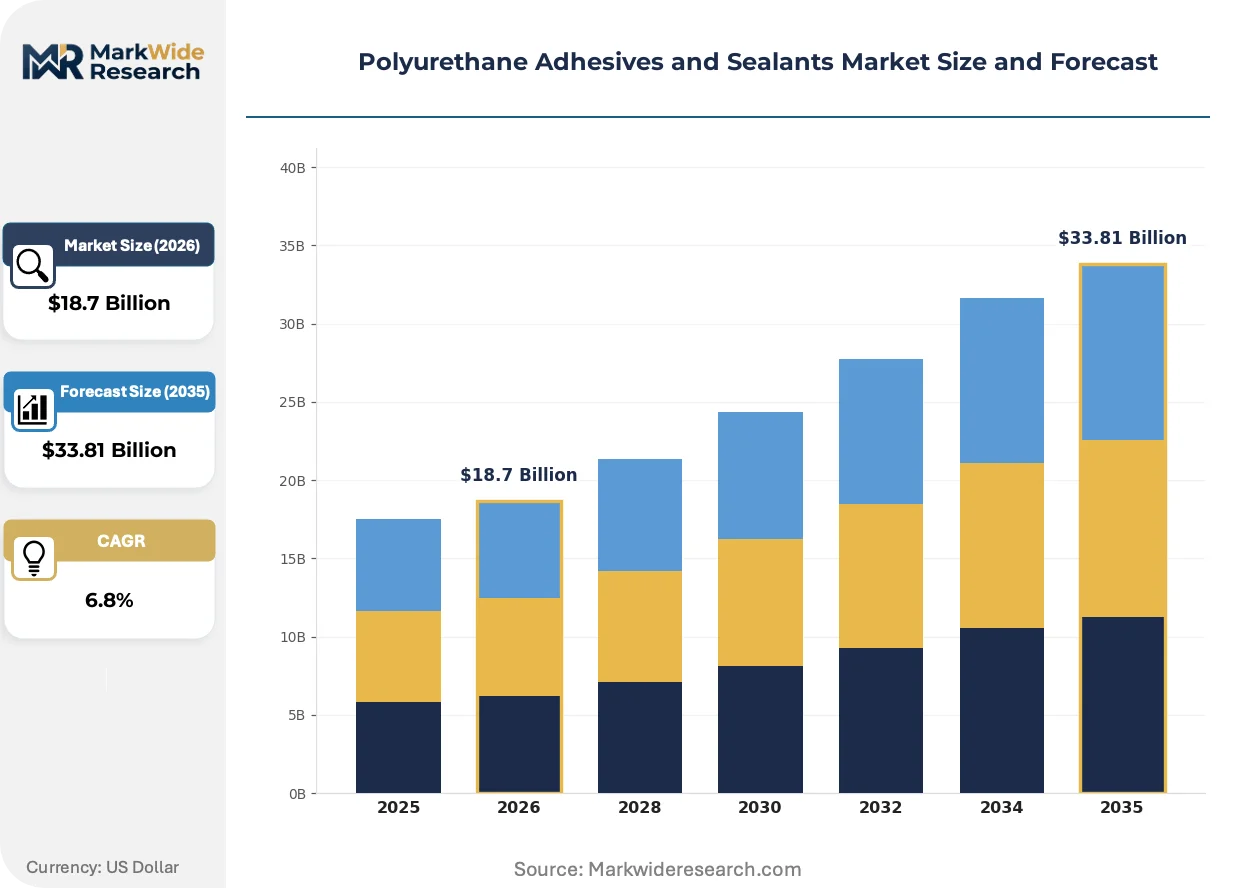
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyurethane Adhesives and Sealants Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
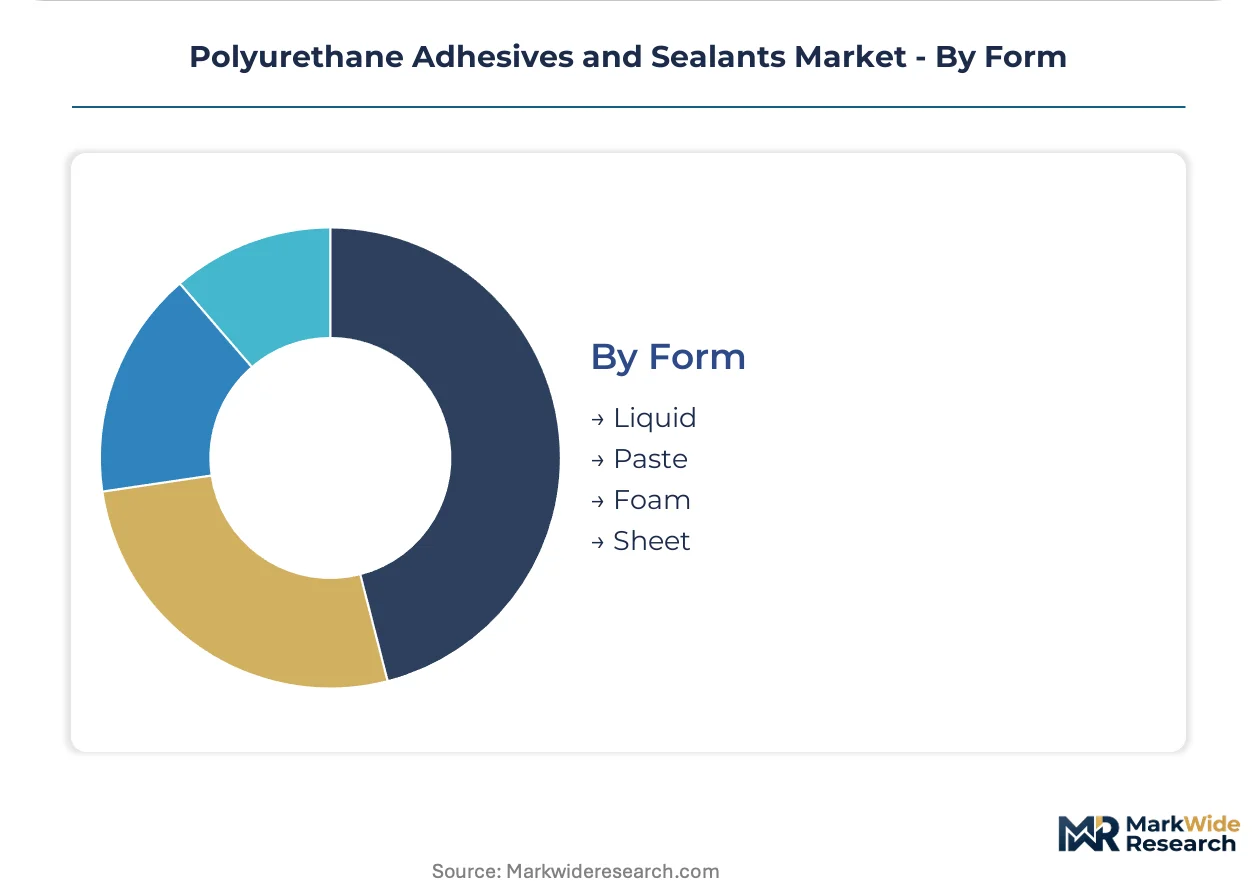
| Segmentation | Product Type: Neutral Cure, Polyether, Polyisocyanate, Aromatic End User: Construction, Automotive, Aerospace, Electronics Application: Woodworking, Automotive Assembly, Packaging, Construction Joints Form: Liquid, Paste, Foam, Sheet |
| Companies Covered | Henkel AG & Co. KGaA, 3M Company, Sika AG, H.B. Fuller Company, Arkema (Bostik), Dow Inc., BASF SE, Huntsman Corporation, MAPEI S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyurethane Adhesives and Sealants Market Strategic Shifts
Formulation chemistry is pivoting toward bio-based feedstocks and energy-efficient cure mechanisms as sustainability metrics penetrate procurement specifications across transportation and building sectors.
Silane-terminated polyurethane hybrids are overtaking conventional silyl-modified polymers in flooring adhesive applications. German parquet installers specify these systems for rapid green-strength development on heated screeds. The technology is compressing installation cycle times from 48 hours to 6 hours in renovation projects.
EPA 40 CFR 59 Subpart M has tightened VOC content limits for architectural sealants to 250 g/L, effective across 50 states. Formulators are eliminating aromatic solvents in favor of acetate esters and exempt compounds. California's South Coast Air Quality Management District enforces additional 100 g/L limits, creating a bifurcated compliance landscape.
Buyers in the commercial roofing sector now specify performance warranties rather than material specifications, transferring durability risk to adhesive manufacturers. This unbundling of product and service contracts favors suppliers with in-house inspection and remediation capabilities. The shift is most visible in the United Kingdom following Building Safety Act 2022 accountability reforms.
Polyurethane Adhesives and Sealants Market Segmentation
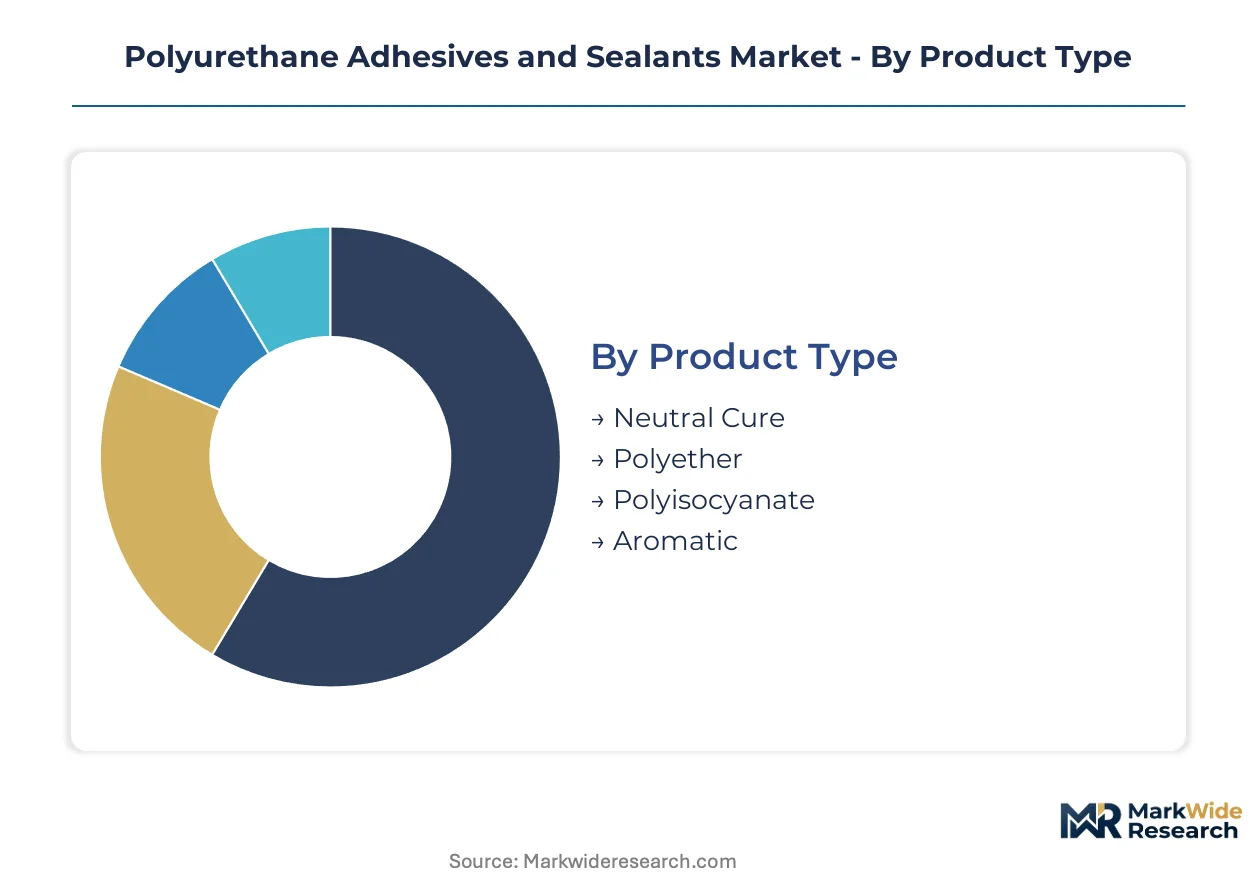
Polyurethane adhesive formulations diverge sharply in cure chemistry, mechanical performance, and regulatory compliance profiles. Each segment commands distinct supply chain configurations and end-user qualification requirements that reshape competitive positioning across application verticals.
Product Type:
Supply concentration in aromatic isocyanate feedstocks tilts formulation economics toward polyether and polyisocyanate variants with backward-integrated raw material security.
- Neutral Cure:Formulations release non-corrosive alcohol byproducts during moisture activation, protecting sensitive copper traces in electronics encapsulation. Demand concentrates in Japanese and South Korean consumer electronics manufacturing where RoHS compliance mandates eliminate acidic cure alternatives.
- Polyether:Backbone structures deliver hydrolytic stability and low-temperature flexibility for outdoor construction joints. German and Nordic building envelope specifications favor these systems for freeze-thaw cycling resistance in curtain wall installations.
- Polyisocyanate:Crosslinking agents enable rapid cure kinetics for automotive robotic dispensing lines. Tier-1 suppliers in Stuttgart's manufacturing corridor specify sub-60-second fixture times.
- Aromatic:MDI-based systems provide cost-efficient structural bonding with elevated temperature resistance. Feedstock concentration on the US Gulf Coast exposes formulators to hurricane-related supply disruptions.
Today's leader: Polyether. Tomorrow's challenger: Neutral Cure.
End User:
Application-driven cost tiers separate commodity construction volumes from aerospace qualification premiums requiring 24-36 month certification cycles.
- Construction:Prefabricated module bonding and field-applied structural sealing demand 600% elongation for thermal movement accommodation. Offsite manufacturing in the United States and Canada favors single-component moisture-cure logistics.
- Automotive:Lightweighting mandates compress bonding cycles as OEMs replace mechanical fasteners with rapid-cure systems. German OEMs now require sub-50 g/L VOC content in assembly adhesives under REACH low-VOC mandates.
- Aerospace:Primary structural bonding retains epoxy dominance due to 180°C service temperature requirements exceeding aliphatic polyurethane limits. Henkel supplies Airbus tier-1 facilities through European formulation networks.
- Electronics:Thermal management adhesives with flame-retardant properties gain traction in India's PLI-supported electric vehicle battery pack assembly. Local formulators target two-wheeler and three-wheeler cell-to-cell bonding.
Construction commands current volume. Automotive climbs fastest on lightweighting intensity.
Application:
Customer type stratification separates high-volume robotic dispensing from artisanal manual application with diverging equipment and training requirements.
- Woodworking:Hot-melt reactive systems demand heated hoses and precision gear pumps that retrofit poorly into existing solvent-borne infrastructure at mid-sized furniture manufacturers. Silane-terminated hybrids compress installation cycles from 48 hours to 6 hours on heated screeds.
- Automotive Assembly:Liquid form dominates for robotic dispensing precision on structural bonding lines. Tier-1 suppliers specify adhesives matching robotic line speeds with instant handling strength requirements.
- Packaging:Flexible packaging laminations favor moisture-cure systems for film-to-film adhesion with food-contact compliance. Japanese consumer electronics manufacturers pilot UV-LED hybrid systems for smartphone display bonding.
- Construction Joints:Factory-to-site logistics favor single-component moisture-cure systems for prefabricated module sealing. Brazilian residential builders source 30-liter pails via app-based procurement with same-day jobsite delivery.
Automotive Assembly leads premium pricing. Construction Joints expand most quickly on modular building adoption.
Form:
Maturity gradients separate established liquid dispensing infrastructure from emerging foam and sheet formats requiring capital equipment transitions.
- Liquid:Dominates automotive assembly lines for robotic precision in structural bonding operations. Pump and meter mixing equipment represents sunk cost barriers for format switching.
- Paste:Thixotropic formulations enable vertical application in construction joints without sag. Manual and trowel application persists in renovation segments with lower automation penetration.
- Foam:Spray-applied operations require supplied-air respirators and enclosed spray booths under OSHA mandates, elevating capital barriers for smaller construction applicators.
- Sheet:Pre-cured adhesive films enable clean room electronics assembly with controlled thickness uniformity. Emerging format for display bonding in Japanese consumer electronics manufacturing.
Liquid holds installed base dominance. Sheet gains share fastest on clean room precision requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive manufacturing corridor around Stuttgart and Wolfsburg anchors polyurethane adhesive demand through lightweight vehicle assembly expansion. Regional differentiation stems from regulatory stringency, feedstock access, and end-use industrial clustering.
United States
Wind turbine blade manufacturers in Texas and Iowa specify polyurethane structural adhesives for rotor diameters exceeding 120 meters. EPA 40 CFR 59 Subpart M enforces 250 g/L VOC limits for architectural sealants nationwide. MDI feedstock concentration on the US Gulf Coast exposes formulators to hurricane-related supply disruptions.
Germany
REACH low-VOC mandates push reformulation toward waterborne and hot-melt polyurethane systems for construction applications. German automotive OEMs now require sub-50 g/L VOC content in assembly adhesives. Stuttgart's manufacturing corridor concentrates tier-1 supplier demand for sub-60-second fixture time adhesives.
China
Construction joint applications expand rapidly as prefabricated building modules demand field-applied structural sealants with 600% elongation. MIIT oversees industrial chemical standards while provincial energy rationing periodically disrupts MDI production in Northeast China clusters. Yangtze River Delta manufacturers pilot UV-LED hybrid cure systems for electronics assembly.
India
The PLI scheme for electric vehicles creates demand for thermal management adhesives with flame-retardant properties in battery pack assembly. BIS certification requirements govern construction chemical imports. Local formulators in Maharashtra and Gujarat target cell-to-cell bonding for two-wheeler and three-wheeler EV platforms.
Japan
Consumer electronics manufacturers pilot silane-terminated polyurethane hybrids for smartphone display bonding with instant handling strength. METI promotes low-carbon material innovation through national technology roadmaps. Kanto region clean room assemblers adopt pre-cured adhesive sheet formats for controlled thickness uniformity.
Polyurethane Adhesives and Sealants Market Competitive Environment
Global majors compete with regional champions across formulation expertise and feedstock integration. The vendor base separates into three tiers: multinational chemical conglomerates with aromatic isocyanate backward integration, mid-sized European specialists with automotive qualification depth, and emerging Asian formulators targeting cost-sensitive construction volumes. Consolidation pressure concentrates among feedstock-integrated players seeking geographic expansion through distribution partnerships. Technology licensing agreements accelerate waterborne formulation access for regional champions lacking in-house R&D scale.
Within the multinational tier, Henkel AG & Co. KGaA, 3M Company, and BASF SE exemplify divergent strategic positions. Henkel occupies a position anchored in European automotive qualification networks. 3M represents the patented technology archetype with moisture-cure intellectual property depth. BASF sits within the feedstock-integrated segment with aromatic isocyanate production capabilities. These three entities collectively illustrate how competitive advantage fragments across formulation know-how, regulatory compliance infrastructure, and raw material security rather than concentrating in any single capability dimension.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| 3M Company |
| Sika AG |
| H.B. Fuller Company |
| Arkema (Bostik) |
| Dow Inc. |
| BASF SE |
| Huntsman Corporation |
| MAPEI S.p.A. |
| Others |
Value Chain & Pricing Dynamics
German automotive OEM procurement mandates for sub-50 g/L VOC adhesives force formulators to absorb reformulation costs while maintaining supply continuity to Stuttgart's manufacturing corridor. This specification compression reshapes supplier economics as backward-integrated majors capture margin from specialty houses lacking aromatic isocyanate captive supply.
Pricing Analysis
MDI and polyol feedstock volatility passes through to adhesive pricing on quarterly contract resets, with aromatic isocyanate tiers commanding premium stability over aliphatic alternatives. Three-tier pricing structure across automotive-qualified, construction-standard, and economy industrial grades reflects certification depth and crash-test validation investment. Pricing pressure stems from epoxy substitution in aerospace structural bonding as OEMs prioritize 180°C service temperature performance. Construction contractors exhibit highest price sensitivity, while automotive tier-1 suppliers accept premium positioning for sub-60-second fixture guarantees.
Supply Chain Analysis
Aromatic isocyanate production rests on MDI manufacturing clusters in the United States Gulf Coast, Northeast China, and the German industrial heartland. Propylene oxide polyols, tin catalysts, and silane crosslinkers constitute critical formulation dependencies with limited dual-sourcing options. Hurricane exposure at Texas petrochemical complexes and provincial energy rationing in China create force majeure vulnerabilities that propagate through quarterly allocation protocols. Distribution runs through regional chemical distributors for construction volumes, while automotive adhesives ship direct-to-plant via dedicated tanker contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polyurethane adhesives function as a stable compounder anchored by irreversible automotive lightweighting trends that permanently displace mechanical fasteners. Bonding cycle compression and VOC regulatory tightening sustain formulation premium capture across the projection horizon.
For Market Incumbents: To counter epoxy displacement in aerospace primary structures, prioritize aliphatic polyurethane thermal stability R&D while securing MDI backward integration through Gulf Coast production hedging. Channel control investments in direct-to-contractor platforms defend margin position against distributor disintermediation in Brazilian and Indian construction markets. For New Entrants and Emerging Players: Mobile-enabled procurement platforms targeting mid-sized furniture manufacturers offer the most penetrable entry vector, as legacy solvent-borne equipment incompatibility strands incumbents with retrofit cost disadvantages. Silane-terminated hybrid formulations for heated screed flooring applications provide technical differentiation with compressed 6-hour installation cycles versus conventional 48-hour alternatives. For Investors and Strategic Acquirers: Asymmetric upside sits with European mid-cap specialists possessing automotive crash-test qualification depth but lacking feedstock integration. Five-to-ten year viability hinges on waterborne formulation transition completion ahead of REACH occupational exposure limit tightening. Watch MDI spot price spreads versus contract indices as margin inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MDI Feedstock | Captive aromatic isocyanate supply insulates margin from Gulf Coast hurricane disruptions and Chinese energy rationing. |
| Waterborne Formulation Transition | REACH sub-50 g/L VOC mandates in German automotive assembly require reformulation investment ahead of tightening limits. |
| Direct-to-Contractor Distribution Platform | App-based procurement with same-day delivery bypasses traditional distributor markup in Brazilian residential construction. |
| UV-LED Hybrid Cure Development | Japanese consumer electronics manufacturers pilot instant-handling-strength systems for smartphone display bonding applications. |
| Automotive Crash-Test Qualification Investment | Simultaneous FMVSS 302 and OEM-specific validation creates 24-36 month barriers protecting qualified supplier positions. |
Study Parameters
Direct dialogue with polyurethane formulator R&D directors, automotive tier-1 procurement managers, construction chemical distributors, and regulatory compliance officers grounded qualitative assessment. Secondary validation drew from EPA 40 CFR 59 filings, ECHA REACH registration databases, ACC chemical trade data, and SEC 10-K disclosures from listed adhesive manufacturers. Bottom-up segment sizing triangulated against top-down macro demand indicators from automotive production and construction spending databases.
Market value and volume estimates emerged from modeling cure chemistry, end-use industry, and regional regulatory cluster segmentation across the projection horizon. CAGRs derived from elasticity-adjusted demand curves incorporating automotive lightweighting intensity, prefabricated construction adoption rates, and EV battery pack assembly growth. Feedstock price scenarios and occupational exposure limit tightening trajectories informed scenario-weighted outcomes.
The model assumes a particular technology adoption path; alternative pathways for UV-LED hybrid cure systems or bio-based polyol feedstocks would alter the outlook for moisture-cure dominance. Forecasts embed assumptions regarding MDI supply continuity and REACH enforcement stringency. A small set of triggers—MDI force majeure events, automotive OEM insolvency cascades, and sudden epoxy price collapses—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
South Korea Sealants Market
Adhesives & Sealants
Global Self-Adhesive Vinyl Films Market
Adhesives & Sealants
Middle-East and Africa Reactive Adhesives Market
Adhesives & Sealants
Wood Glue Market
Adhesives & Sealants
Dental Impression Tray Adhesives Market
Adhesives & Sealants
Global Underfill Material Market
Adhesives & Sealants
Asia-Pacific Acrylic Adhesives Market
Adhesives & Sealants
Middle East and Africa Epoxy Curing Agents Market
Adhesives & Sealants
Global Contact Adhesives Market
Adhesives & Sealants
Global Adhesives Market
Adhesives & Sealants
Germany Adhesives Market
Adhesives & Sealants
APAC Polyurethane Hot-Melt Adhesives Market
Adhesives & Sealants
High Temperature Adhesives Market
Adhesives & Sealants
Silicone Sealants Market
Adhesives & Sealants
Europe Contact Adhesives Market
Adhesives & Sealants
Silane Coupling Agents Market