
 Global Adhesion Promoter Market | 2026-2036
Global Adhesion Promoter Market Size, Share, and Industry Trends Forecast 2026-2036
Global Adhesion Promoter Market Intelligence
The substitution of aluminum and steel with carbon fiber composites in aerospace and automotive applications is rebalancing product economics for adhesion promoters. This shift requires advanced formulations to bond dissimilar substrates effectively. Dow Chemical Company leverages its extensive polymer science portfolio to serve these advanced material applications. Evonik Industries AG specializes in silane-based promoters, critical for fiberglass and composite bonding, while BASF SE competes with a broad chemical offering across multiple end-user industries.
An adhesion promoter is a chemical coupling agent designed to create a stable bond between a substrate and a subsequent coating or adhesive layer. These bifunctional molecules, often featuring organofunctional and hydrolyzable groups, enhance bond durability under thermal and environmental stress. Silane coupling agents represent the largest product type due to their versatility with glass and metal substrates. Within applications, automotive components and electronics manufacturing show high demand for specialized promoters that ensure long-term performance and reliability.
Regulatory frameworks significantly influence formulation strategies. The European Union's REACH and RoHS directives restrict specific chemical substances, while US EPA rules limit volatile organic compound (VOC) content in coatings and adhesives. In China, GB standards dictate performance and safety criteria for materials used in construction and automotive sectors. Formulators must therefore balance performance requirements with an increasingly complex and divergent set of international chemical compliance mandates.
Market Dynamics
The drive for lightweighting in automotive and aerospace industries, coupled with stringent chemical regulations like the EU's REACH, is the central force shaping the adhesion promoter market. This necessitates advanced formulations for bonding dissimilar, high-performance materials like composites and alloys.
Growth Catalysts
- Carbon Fiber Composites:The substitution of metals with carbon fiber reinforced plastics in aerospace and performance automotive applications requires new classes of adhesion promoters to ensure durable bonding between the composite matrix and other structural components.
- Electronics Manufacturing:Expansion of the electronics sector, particularly for flexible displays and multi-layer printed circuit boards in China, creates demand for specialized promoters that ensure adhesion and reliability under thermal stress.
- Automotive Efficiency Mandates:Fuel economy standards from the US EPA and similar European regulations incentivize the use of lightweight materials, indirectly boosting the need for adhesion promoters that enable multi-material vehicle body construction.
Market Restraints
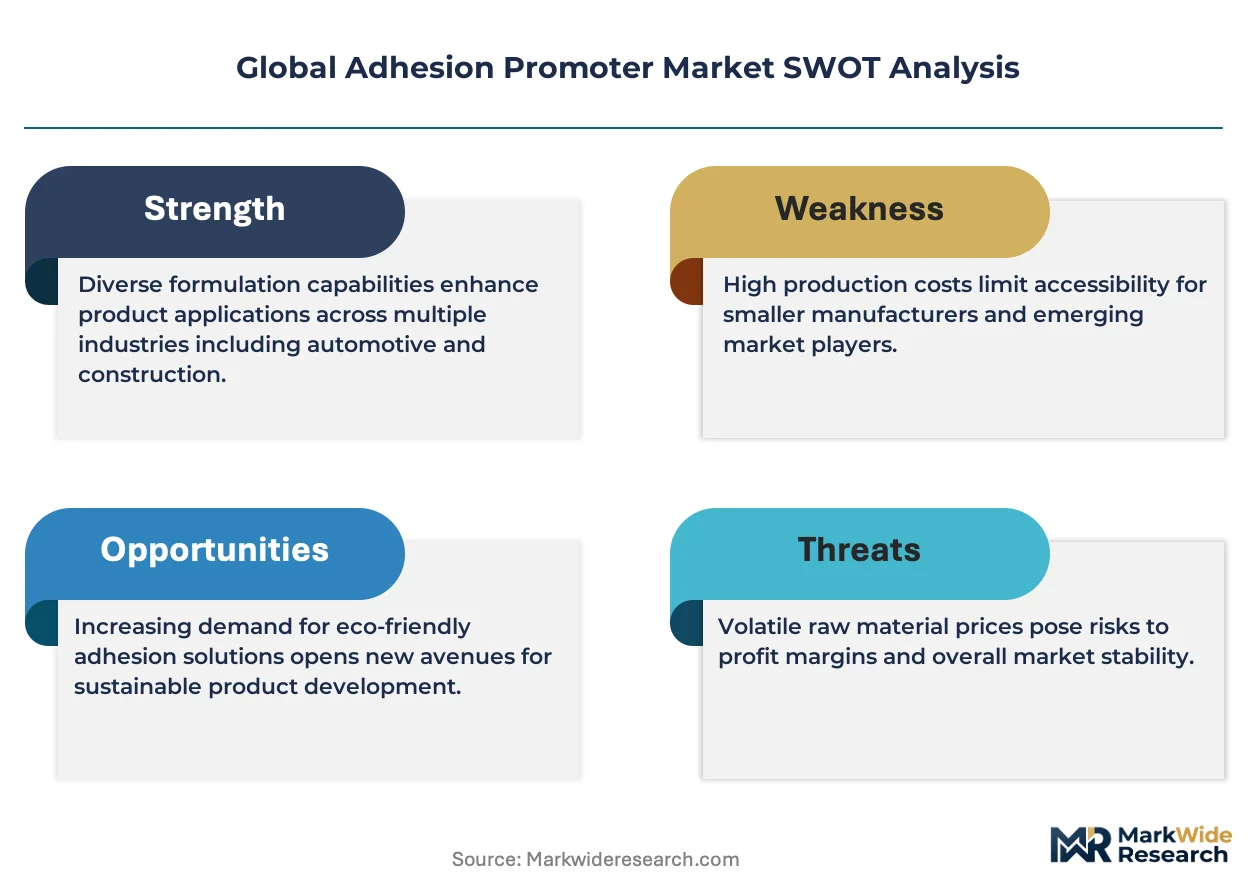
- Raw Material Volatility:Fluctuations in the cost and availability of key precursors, such as organofunctional silanes and titanates, create pricing instability and margin pressure for adhesion promoter manufacturers, impacting overall product economics.
- Performance Under Stress:Certain promoter chemistries exhibit degradation in bond strength when subjected to high humidity and extreme thermal cycling, a critical limitation for applications in demanding aerospace and automotive electronics environments.
- Divergent Regulatory Frameworks:The lack of harmonization between chemical control laws like the EU's REACH and China's MEE regulations complicates global supply chain management and increases the cost and time required for product registration.
Strategic Opportunities
- Bio-Based Formulations:Developing adhesion promoters derived from renewable feedstocks presents a significant opportunity to meet corporate sustainability goals and capture demand from customers seeking to reduce their environmental footprint, aligning with policies like the EU Green Deal.
- Emerging Geographic Markets:The industrialization and infrastructure growth in Southeast Asia and India create new demand centers for adhesion promoters in construction, automotive manufacturing, and packaging, offering avenues for market expansion.
- Nanotechnology Integration:Incorporating nanoparticles into promoter formulations can create multifunctional agents with enhanced thermal conductivity or self-healing capabilities, opening new applications in advanced electronics and smart coatings.
Industry Challenges
- Complex Compliance Pathways:Navigating the lengthy and expensive chemical registration processes mandated by regulatory bodies such as the European Chemicals Agency (ECHA) can significantly delay the introduction of innovative formulations to the market.
- Supply Chain Adaptation:Reformulating product lines to exclude substances restricted by regulations like RoHS while maintaining performance parity is a major technical and logistical challenge for global manufacturers sourcing materials from diverse regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Adhesion Promoter Market |
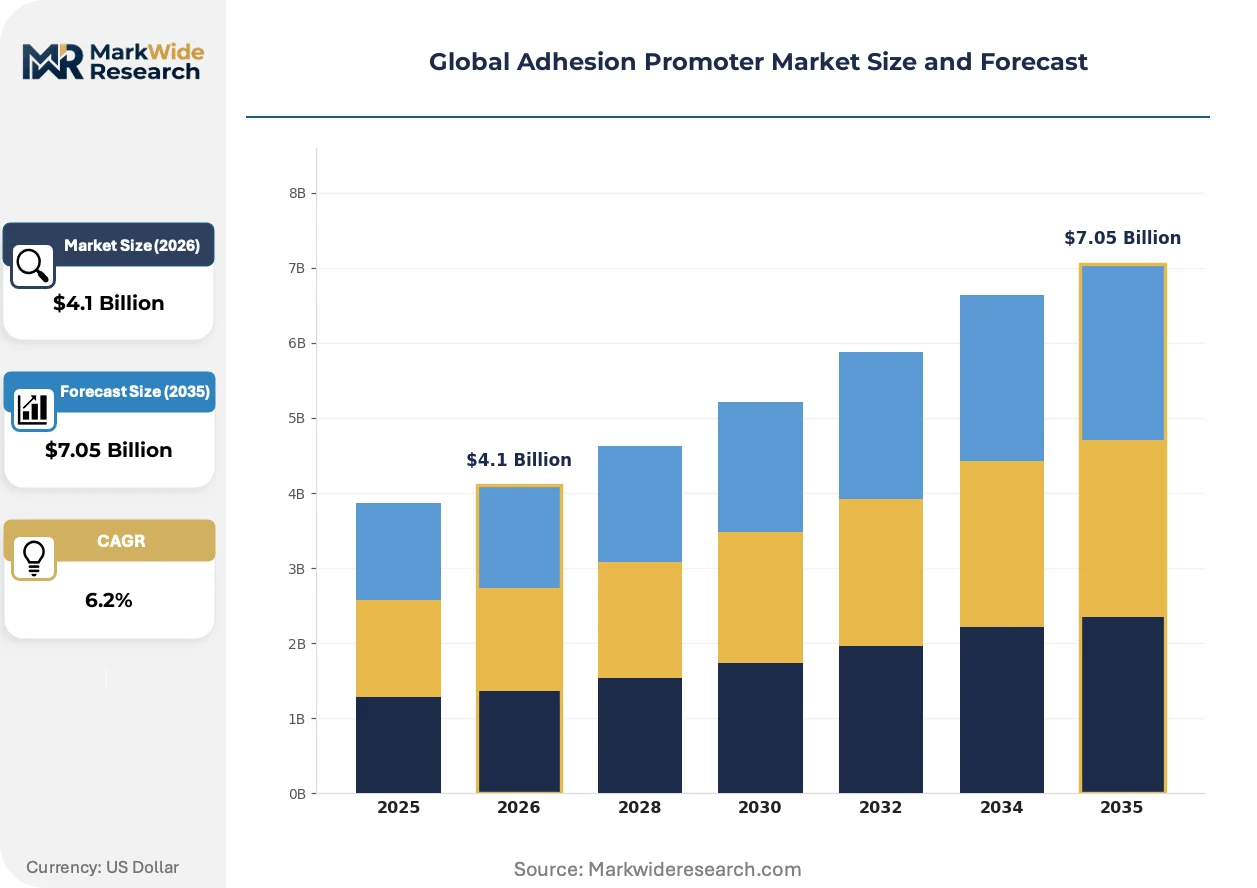
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $7.05 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silane Coupling Agents, Titanate Coupling Agents, Zirconate Coupling Agents, Phosphonate Coupling Agents, Others Technology: Priming, Surface Treatment, Coating, Plasma Activation, Laser Activation Application: Electronics Manufacturing, Packaging Solutions, Automotive Components, Construction Materials, Textile Finishing End User Industry: Consumer Goods Manufacturers, Aerospace Assemblers, Printing Services, Marine Engineering, Appliance Makers |
| Companies Covered | Momentive Performance Materials, BASF SE, Dow Chemical Company, 3M Company, Eastman Chemical Company, Arkema SA, Evonik Industries AG, Air Products and Chemicals, Inc., Akzo Nobel N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Adhesion Promoter Market Strategic Shifts & Innovations
A fundamental shift toward sustainable chemistry and high-performance materials is driving innovation in the adhesion promoter market. Formulators are developing novel solutions to meet demands from advanced sectors while navigating a complex web of global environmental regulations.
Functional silane technology designed for electric vehicle battery packs is a key development. These specialized promoters enhance the bond between electrode materials, separators, and current collectors within lithium-ion cells. EV and energy storage system manufacturers are increasingly specifying these materials, and this technology is electrifying the battery supply chain by enabling higher energy densities and extending cycle life.
China's GB standards for materials used in automotive and construction industries are becoming progressively more stringent on chemical content and durability. This trend compels global and domestic manufacturers to reformulate products specifically for the Chinese market, often creating distinct product grades. The electronics sector is most affected, requiring promoters that satisfy both high-performance needs and strict substance restrictions from the Ministry of Ecology and Environment (MEE).
OEM procurement in the aerospace and high-end automotive sectors is evolving from transactional purchasing toward collaborative development. Instead of buying commodity promoters, these customers now engage suppliers in co-development partnerships to create bespoke formulations for specific composite-to-metal or plastic-to-glass joints. This demand for application-specific solutions is most pronounced in North America and Europe, where advanced manufacturing is concentrated.
Global Adhesion Promoter Market Segmentation
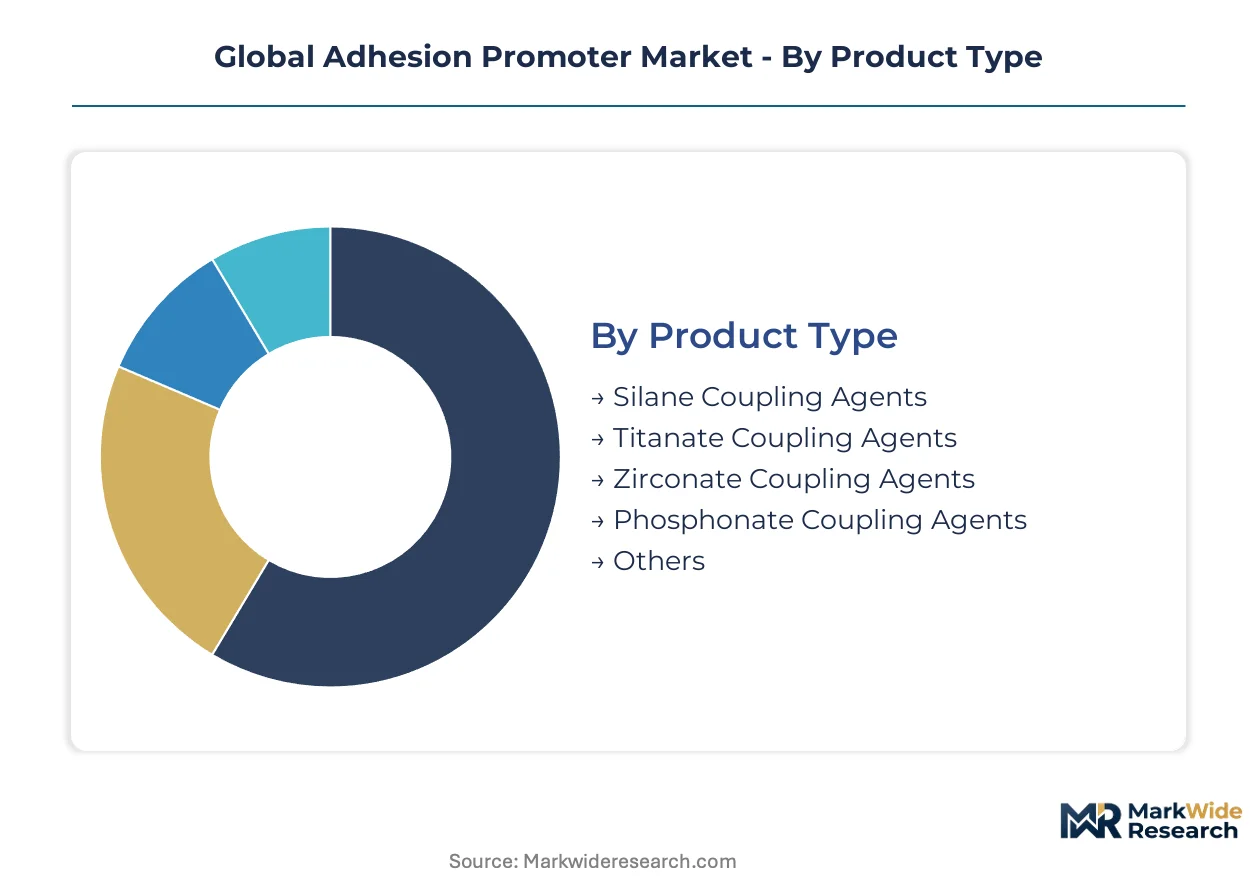
Understanding the Global Adhesion Promoter Market through segmentation reveals how diverse chemistries and application methods address specific industry needs. This granular view helps stakeholders identify pockets of innovation, understand regulatory impacts, and pinpoint high-growth areas within the complex material science landscape.
Product Type:
The selection of adhesion promoter product types often hinges on the substrate's lifecycle and the need for enhanced durability during upgrades or material replacements.
- Silane Coupling Agents:These bifunctional molecules are critical for creating stable bonds between inorganic substrates like glass and metals, and organic polymers. Demand concentrates heavily in electronics manufacturing and automotive components, driven by the need for long-term reliability under thermal stress.
- Titanate Coupling Agents:As organometallic compounds, titanates are particularly effective in improving adhesion and dispersion of inorganic fillers in polymers, often used for high-temperature applications. Their demand is significant in advanced composites and performance coatings for improved thermal stability.
- Zirconate Coupling Agents:These zirconium-based promoters enhance adhesion in challenging systems, including those with high moisture content.
- Phosphonate Coupling Agents:Phosphorus-containing compounds primarily improve bonding to metal oxide surfaces and certain plastics.
- Others:This category encompasses various specialized chemical coupling agents tailored for niche applications and unique material combinations.
Silane Coupling Agents sits at the top of the volume ranking, with Titanate Coupling Agents climbing the fastest.
Technology:
The technology employed for adhesion promotion often correlates with the required performance level and associated processing costs.
- Priming:This involves pre-treating a substrate surface with a dilute solution of an adhesion promoter before applying an adhesive or coating. Priming is a foundational method, widely used in construction materials and general manufacturing for cost-effective bond enhancement.
- Plasma Activation:A gas-phase surface modification technique that uses plasma to clean, etch, and functionalize substrate surfaces for improved adhesion without wet chemicals. This advanced technology sees demand in flexible electronics and medical devices for ultra-fine surface preparation.
- Surface Treatment:This broad category includes chemical or mechanical alterations of a substrate surface to improve its wettability and reactivity for better bonding.
- Coating:Adhesion promoters are directly incorporated into coating formulations to enhance their adherence to the underlying substrate.
- Laser Activation:Utilizes precise laser energy to modify a substrate's surface, creating reactive sites that improve subsequent bonding.
Supply concentration for these technologies varies, with traditional priming approaches widely available and specialized plasma activation services more geographically constrained.
Application:
Different applications demand specific adhesion promoter characteristics tailored to the end-user's performance and regulatory requirements.
- Electronics Manufacturing:Promoters ensure reliable bonds in printed circuit boards, flexible displays, and semiconductor packaging, vital for device longevity. This application sees high demand in China's expansive electronics sector, driven by the need for reliability under thermal stress.
- Automotive Components:Essential for bonding dissimilar materials, such as carbon fiber composites to metals, to achieve lightweighting goals in vehicle construction. Demand is pronounced in Europe and North America, influenced by stringent fuel efficiency mandates.
- Packaging Solutions:Enhances bond strength and durability for flexible packaging films, laminates, and other protective materials.
- Construction Materials:Improves the adhesion of various coatings, sealants, and adhesives used in building and infrastructure projects.
- Textile Finishing:Promotes the adhesion of functional coatings to fabrics, enhancing properties like water repellency or flame retardancy.
Electronics Manufacturing and Automotive Components applications exhibit high maturity with continuous innovation, while Textile Finishing represents a segment with evolving functional demands.
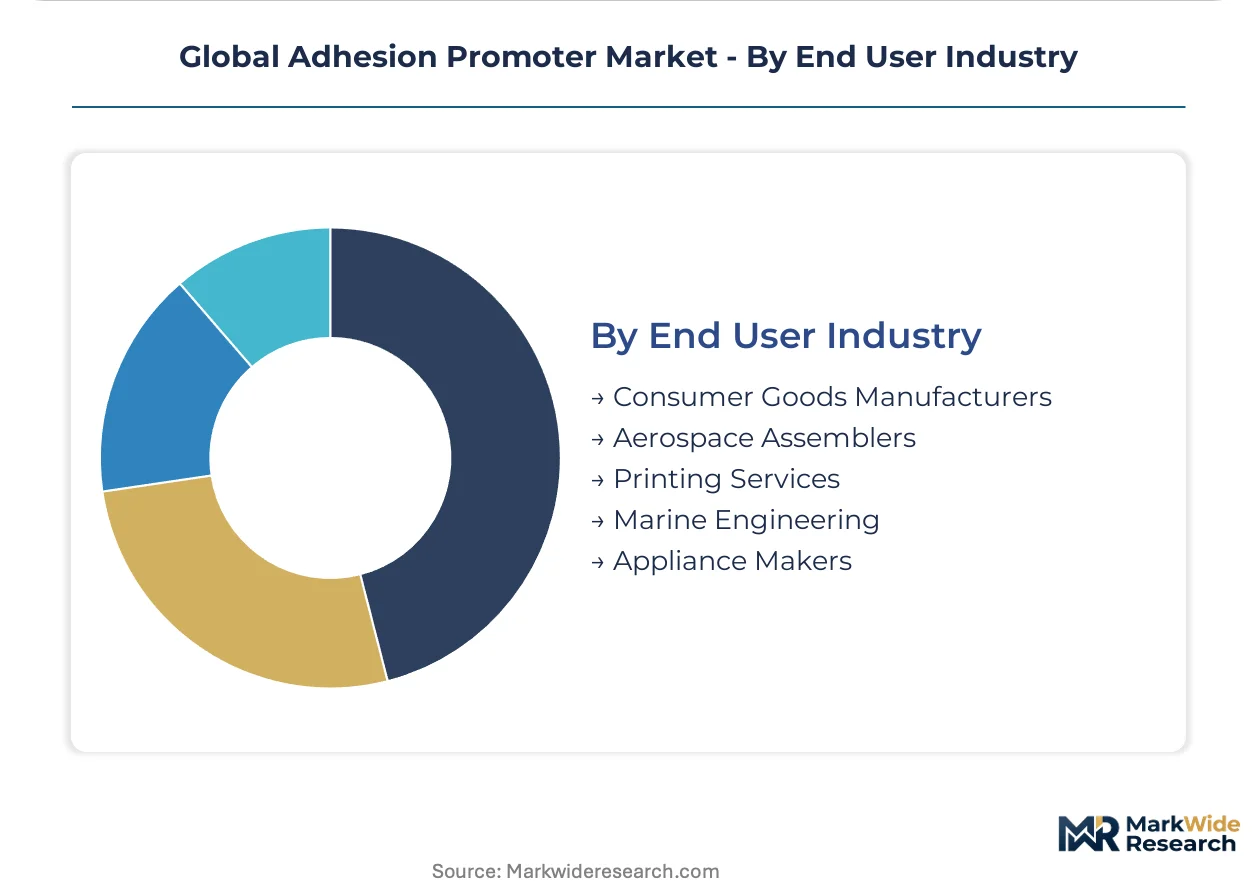
End User Industry:
The volume of adhesion promoter consumption varies significantly across end-user industries, reflecting their production scales and material requirements.
- Aerospace Assemblers:Require high-performance adhesion promoters for critical composite-to-metal bonding in aircraft structures and components. This industry, concentrated in North America and Europe, demands solutions meeting stringent safety and durability standards.
- Consumer Goods Manufacturers:Utilize promoters for bonding diverse materials like plastics, metals, and glass in a wide array of products, from household items to personal electronics. Mass production volumes and cost efficiency drive demand, particularly across the Asia-Pacific region.
- Printing Services:Employ adhesion promoters to ensure robust ink adhesion to various substrates, including plastics and metals, for labels and packaging.
- Marine Engineering:Demands robust promoters for bonding components in harsh saltwater environments, ensuring long-term structural integrity.
- Appliance Makers:Use adhesion promoters to securely bond internal and external components in both household and commercial appliances.
Aerospace Assemblers typically prioritize high-performance, higher-margin solutions, whereas Consumer Goods Manufacturers often seek cost-effective, high-volume formulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's expansive manufacturing base anchors significant demand for adhesion promoters globally. This region drives consumption across diverse sectors, including electronics and automotive production. Regulatory shifts and sustainability goals increasingly influence product development and market dynamics across key industrial nations.
China
Demand for specialized adhesion promoters stems from China's robust electronics manufacturing and automotive production sectors. The Ministry of Ecology and Environment (MEE) regulations and GB standards influence product formulation, emphasizing lower VOC content and safer chemical profiles. Industrial clusters in the Yangtze River Delta continue to drive innovation in multi-layer printed circuit boards and electric vehicle components.
United States
The United States aerospace and automotive industries require high-performance adhesion promoters for lightweighting initiatives. US EPA rules and stringent safety standards govern the chemical composition and application of these materials. Automotive manufacturing hubs in Michigan and aerospace clusters in Washington state fuel demand for advanced bonding solutions.
Germany
Germany's advanced automotive and aerospace sectors generate substantial demand for adhesion promoters that bond dissimilar high-performance materials. European Union regulations like REACH and RoHS dictate strict compliance for chemical substances used in these applications. The Bavaria region, with its strong automotive and engineering base, remains a significant consumer of specialized formulations.
Japan
Japanese electronics and automotive manufacturers seek adhesion promoters for flexible displays, battery packs, and lightweight vehicle components. Compliance with JIS standards ensures product quality and performance in these precision industries. Technology clusters in the Tokyo metropolitan area and manufacturing centers in Nagoya drive continuous innovation in material science.
India
India's expanding construction and automotive industries present a growing market for adhesion promoters. Government initiatives, such as the Production Linked Incentive (PLI) scheme, support domestic manufacturing and material innovation. Major industrial zones in Maharashtra and Tamil Nadu are experiencing increased consumption for infrastructure projects and vehicle production.
Global Adhesion Promoter Market Key Industry Players
Global majors compete with regional champions across product specialization and geographic reach within the adhesion promoter market. The industry structure features large diversified chemical companies alongside specialized material science firms. Dominant competitive moves include strategic partnerships for co-development and continuous portfolio diversification to meet evolving application needs.
Diversified chemical giants like Dow Chemical Company and BASF SE exemplify broad portfolio strategies, serving multiple end-user industries with a wide range of chemical solutions. Evonik Industries AG occupies a position as a specialist, focusing on silane-based promoters critical for composite bonding applications. These companies anchor innovation by developing bespoke formulations for advanced materials and complex bonding challenges in key industrial sectors.
| Leading Market Players |
|---|
| Momentive Performance Materials |
| BASF SE |
| Dow Chemical Company |
| 3M Company |
| Eastman Chemical Company |
| Arkema SA |
| Evonik Industries AG |
| Air Products and Chemicals, Inc. |
| Akzo Nobel N.V. |
| Others |
Cost & Logistics Intelligence
Organofunctional silane prices, influenced by petrochemical feedstock costs, cascade through the adhesion promoter supply chain, directly impacting pricing tiers for both commodity and specialized formulations. This volatility shapes procurement decisions for end-user industries.
Pricing Analysis
Input-cost pass-through mechanisms dictate that fluctuations in key precursors, such as organofunctional silanes and titanates, directly influence adhesion promoter pricing. Value-based pricing models apply to highly specialized formulations for aerospace, while transactional pricing dominates commodity-grade products. Price differentiation stems from performance quality and specific regulatory certifications like REACH compliance. Pricing softness affects standard grades due to intense competition, with Consumer Goods Manufacturers exhibiting the highest price sensitivity.
Supply Chain Analysis
Direct-to-OEM channels distribute highly customized adhesion promoters to advanced manufacturing sectors in North America and Europe. Supply concentration for critical precursors like organofunctional silanes and zirconium compounds centers predominantly in China and Germany. The supply chain relies on diverse chemical feedstocks. Divergent regulatory frameworks, such as the EU's REACH and China's MEE standards, present a significant structural risk, complicating global product distribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The adhesion promoter market is evolving into a late-cycle quality story, driven by the increasing demand for high-performance bonding solutions in multi-material assemblies for lightweighting initiatives.
For Market Incumbents: Extend existing polymer science portfolios to develop advanced, application-specific formulations for demanding sectors like electric vehicle battery packs. This strategy helps mitigate the threat of regulatory restrictions on conventional chemistries, leveraging extensive R&D capabilities. Incumbents should deepen co-development partnerships with aerospace and automotive OEMs, ensuring long-term contractual stability.
For New Entrants and Emerging Players: The EU Green Deal in Europe opens a window for bio-based adhesion promoter formulations, targeting environmentally conscious manufacturers. New entrants should focus on white-space opportunities in sustainable packaging solutions and nanotechnology-integrated promoters for advanced electronics. The most penetrable segment involves niche applications requiring rapid prototyping and specialized performance, allowing for a go-to-market strategy centered on innovation and agility.
For Investors and Strategic Acquirers: Consolidation pressure builds where high R&D costs for advanced material science and complex global compliance pathways restrict smaller players. Long-term viability for adhesion promoters remains strong, given their essential role in lightweighting and electronics manufacturing over the next decade. Acquisition targets should be specialized material science firms with strong intellectual property in bio-based or nanotechnology-enhanced formulations. Increased M&A activity for companies with robust low-VOC chemistry portfolios signals market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Bio-based Formulation Development | Addresses EU Green Deal mandates and consumer sustainability preferences. |
| Co-development Partnerships | Secures long-term contracts with aerospace and automotive OEMs for bespoke solutions. |
| Nanotechnology Integration | Enhances performance for advanced electronics and smart coatings applications. |
| Global Regulatory Compliance Centers | Navigates divergent chemical control laws across major industrial regions. |
| Capacity Expansion in Southeast Asia | Capitalizes on industrialization and infrastructure growth in emerging markets. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region. The approach combines in-depth interviews with R&D directors at chemical companies, procurement managers at automotive OEMs, electronics manufacturing engineers, and regulatory compliance specialists. Secondary validation draws from industry association reports, national chemical inventories, and corporate financial filings. Bottom-up and top-down triangulation ensures data consistency.
Rate-of-change decomposition analyzes market dynamics by breaking down growth into volume and price components across the analysis window. Segmentation dimensions modeled include product type, technology, application, end-user industry, and regulatory compliance tier. Compound Annual Growth Rates were derived from historical trends, projected demand drivers, and technological adoption rates. Forecast inputs include lightweighting material adoption rates and electric vehicle battery production forecasts.
Revisions become necessary when significant shifts in global trade policies or unforeseen technological breakthroughs materialize. Forecasts reflect assumptions regarding economic stability and regulatory evolution. Geopolitical instability affecting raw material supply or rapid changes in environmental regulations represent key risk factors. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Rubber Repair Adhesives Market
Adhesives & Sealants
Adhesives and Sealants Distribution Market
Adhesives & Sealants
UV Adhesives Market
Adhesives & Sealants
Lignin for Adhesives Market
Adhesives & Sealants
Brazil Sealants Market
Adhesives & Sealants
Animal Glue Market
Adhesives & Sealants
Global Glass Bonding Adhesive Market
Adhesives & Sealants
Structural Sealants Market
Adhesives & Sealants
Roofing Adhesive Market
Adhesives & Sealants
Asia-Pacific Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Textile Binders Market
Adhesives & Sealants
Active Metal Brazing (AMB) Paste Market
Adhesives & Sealants
Electrical Insulation Tape Market
Adhesives & Sealants
Ocular Sealants and Glues Market
Adhesives & Sealants
South Korea Adhesives Market
Adhesives & Sealants
Middle-East and Africa Acrylic Adhesives Market