
 Global Dimer Acid Market | 2026-2036
Global Dimer Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dimer Acid Market Foresight
Specialty chemical distribution between European traders and Asian manufacturing hubs is narrowing as procurement patterns consolidate around fewer qualified suppliers. BASF leverages its integrated oleochemicals platform to sustain long-term feedstock security for dimer acid derivatives. Croda International anchors premium-grade supply through controlled access to tropical oilseed sources. Emery Oleochemicals competes on manufacturing scale across Malaysian and Indonesian production assets.
Dimer acid comprises a dicarboxylic acid produced through thermal or catalytic dimerization of unsaturated fatty acids, typically containing C36 chains with viscosities ranging from 7,000 to 15,000 mPa·s at room temperature. Manufacturers deploy it primarily as a building block for polyamide resins, synthetic lubricants, and corrosion-resistant coatings where enhanced thermal stability and hydrophobicity prove critical. Polyamide applications dominate value capture due to established demand from hot-melt adhesives and flexible packaging laminates. Alkyd resin formulations retain steady volume in decorative coatings despite slower growth, while polyurethane segments attract investment from construction sealant specialists seeking renewable polyol precursors.
REACH registration requirements in Europe and EPA Toxic Substances Control Act oversight in the United States elevate compliance costs for importers of unrefined dimer acid fractions. China's GB standards for industrial chemicals and SAMR quality certification protocols further fragment market access for non-domestic producers. Stakeholders must monitor evolving bio-preferred procurement mandates from the USDA and EU Green Deal circular economy directives that are redirecting polymer formulation specifications toward verified renewable content thresholds.
Market Dynamics
Polyamide resin formulators in coastal China are consolidating feedstock procurement around fewer qualified dimer acid suppliers as environmental compliance tightens and bio-preferred content mandates from the USDA and EU Green Deal redirect polymer specifications toward verified renewable thresholds.
Growth Catalysts
- EU Green Deal circular economy directives:Verified renewable content thresholds are redirecting polymer formulation specifications toward bio-based dimer acid derivatives in flexible packaging laminates.
- Hot-melt adhesives sector:Established demand from flexible packaging applications sustains value capture for polyamide resin manufacturers scaling dimerized fatty acid output.
- Construction sealant specialists:Investment flows into polyurethane segments seeking renewable polyol precursors derived from dimer acid feedstock.
Market Restraints
- Crude tall oil fatty acid volatility:Input cost fluctuations for unsaturated C18 feedstock compress margin predictability for non-integrated dimer acid producers.
- Malaysian and Indonesian concentration:Palm oil derivative supply chains cluster production assets, exposing buyers to regional weather and trade policy disruptions.
- REACH registration compliance:ECHA documentation requirements elevate entry costs for importers of unrefined dimer acid fractions into European markets.
Strategic Opportunities
- India's industrial chemical sector:Underpenetrated polyamide resin capacity offers first-mover positioning for dimer acid suppliers meeting BIS quality protocols.
- Corrosion-resistant marine coatings:Enhanced thermal stability and hydrophobicity properties open specification wins in shipbuilding maintenance cycles.
- USDA BioPreferred program expansion:Federal procurement mandates create certified demand channels for bio-based curing agents in infrastructure coatings.
Industry Challenges
- Catalytic dimerization process engineering:Talent scarcity in thermal polymerization optimization limits yield improvements at existing facilities.
- GB standards harmonization:SAMR certification timelines for industrial chemicals fragment market access and extend qualification cycles for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dimer Acid Market |
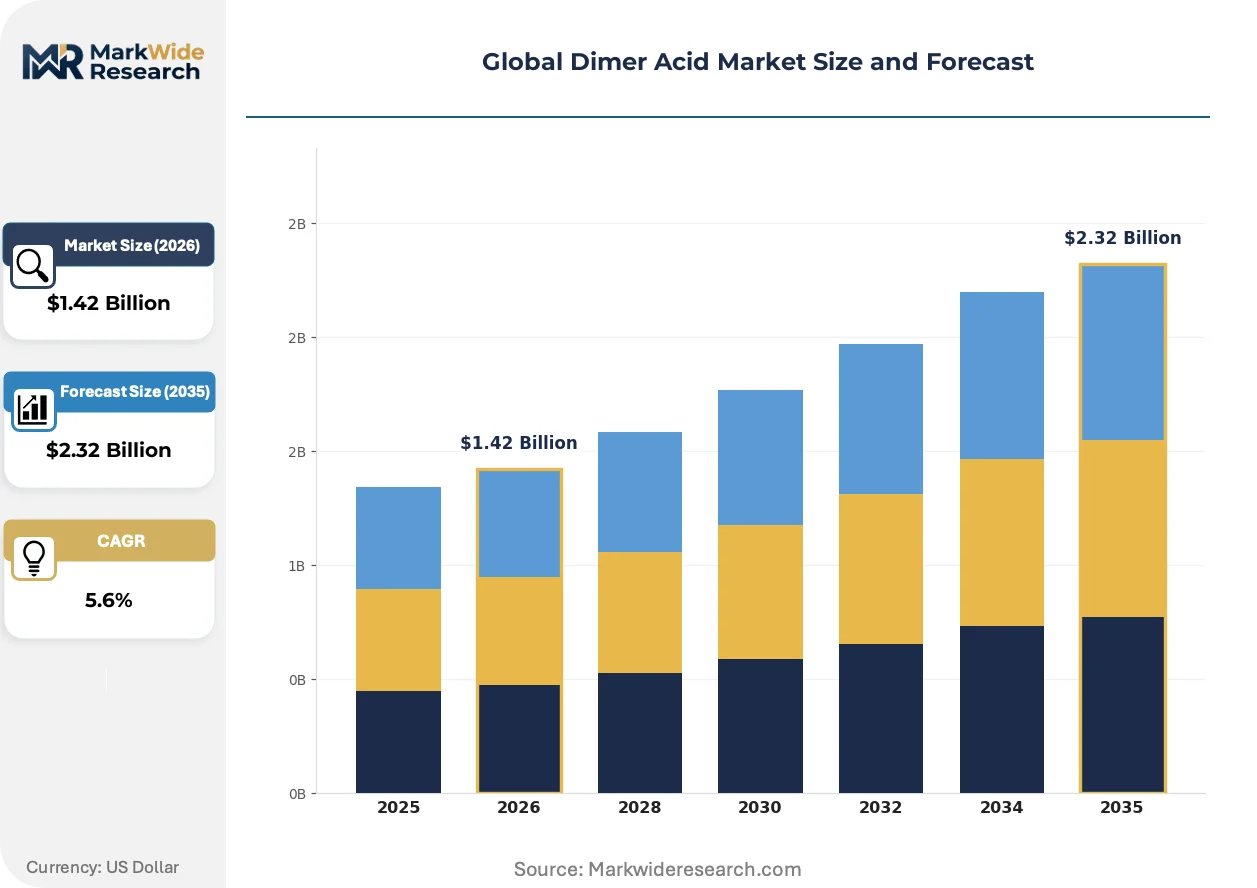
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.32 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyamide, Alkyd Resin, Polyester, Epoxy, Polyurethane Application: Adhesives, Coatings, Lubricants, Plasticizers, Sealants End Use Industry: Pulp & Paper, Paints & Inks, Textiles, Chemical Processing Packaging Type: Drums, Bulk Bags, Jerricans, IBC Containers |
| Companies Covered | BASF, Croda International, Oleon N.V, Emery Oleochemicals, Harima Chemicals, Aturex Group, Florachem Corp., Anqing Hongyu Chemical Co., Ltd, Kraton Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dimer Acid Market Shifts & Advancements
Enzymatic dimerization pathways and precision hydrogenation techniques are compressing energy intensity in dimer acid production while regulatory pressure on petrochemical alternatives accelerates specification shifts across adhesive and coating value chains.
Membrane separation technology for fractionating C36 dimer acid from monomer and trimer byproducts is rendering obsolete energy-intensive vacuum distillation sequences in Malaysian oleochemical complexes. Specialty lubricant blenders in Germany and Japan are piloting these membranes at commercial scale. The process intensification is enabling smaller-batch, higher-purity output that matches performance specifications previously requiring multi-stage refining.
REACH authorization requirements for Substances of Very High Concern are compelling European polyamide resin formulators to document full supply chain provenance for dimer acid feedstock. The industrial consequence is a tiered supplier qualification system separating integrated oleochemical producers from merchant traders. Hot-melt adhesive manufacturers in Italy and Poland are consolidating procurement around pre-registered sources to avoid use restriction deadlines.
Specification-driven procurement is consolidating buyer power among large polyamide compounders who now mandate certificate-of-origin documentation and carbon intensity disclosures from dimer acid vendors. Regional chemical distributors in China's Shandong and Jiangsu provinces are being disintermediated as coastal processing clusters source directly from Malaysian and Indonesian production assets. The compression is most visible in synthetic lubricant supply chains where end-users require batch-level traceability incompatible with traditional trader intermediation.
Global Dimer Acid Market Segmentation
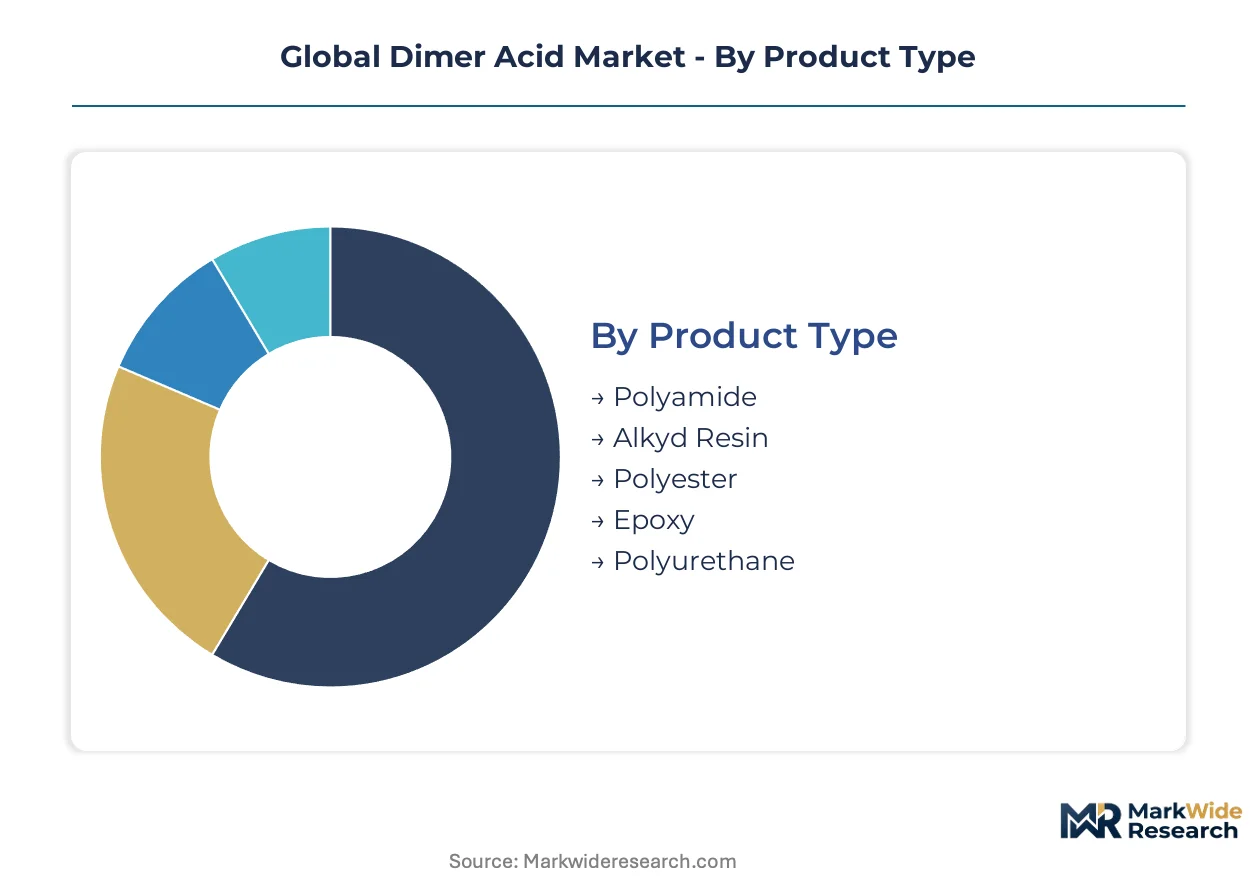
Dimer acid derivatives serve divergent performance requirements across adhesive, coating, and lubricant formulations, necessitating precise grade matching to end-use thermal stability and hydrophobicity specifications. Procurement complexity intensifies where REACH-registered feedstock must interface with SAMR-certified downstream processing in cross-border supply chains.
Product Type:
After-sales technical support intensity varies sharply across dimer acid derivative categories, with polyamide resin formulators demanding sustained formulation troubleshooting that alkyd and epoxy producers rarely require.
- Polyamide:C36 dicarboxylic acid chains with 7,000-15,000 mPa·s viscosity anchor hot-melt adhesive applications where thermal stability governs flexible packaging laminate performance. Demand concentrates in China's Shandong coastal clusters as domestic epoxy coating formulators shift toward bio-based curing agents under tightening environmental compliance. Polyamide holds the largest share; momentum sits with polyurethane.
- Alkyd Resin:Modified drying oil structures retain steady decorative coatings volume despite slower growth trajectories in European architectural markets. Italian and Polish manufacturers consolidate procurement around pre-registered REACH sources to avoid use restriction deadlines.
- Polyester:Saturated backbone variants serve synthetic lubricant base stock applications requiring oxidative stability at elevated operating temperatures.
- Epoxy:Bio-based curing agent specifications from USDA BioPreferred program expansion redirect polymer formulation requirements toward verified renewable content thresholds.
- Polyurethane:Renewable polyol precursors attract construction sealant specialist investment seeking hydrophobic performance in infrastructure expansion markets.
Polyamide dominates value capture through established flexible packaging demand; polyurethane climbs fastest on construction sealant renewable polyol substitution.
Application:
Cost tier stratification separates specification-grade adhesive formulations from commodity lubricant blending, with coatings occupying intermediate value positioning.
- Adhesives:Hot-melt formulations for flexible packaging laminates represent the most technically demanding segment, requiring batch-level traceability incompatible with traditional trader intermediation. German and Japanese specialty lubricant blenders pilot membrane separation technology at commercial scale to match performance specifications.
- Coatings:Corrosion-resistant marine applications leverage enhanced thermal stability and hydrophobicity for shipbuilding maintenance cycles in coastal Chinese processing clusters. Marine specification wins open first-mover positioning for suppliers meeting stringent salt-spray performance protocols.
- Lubricants:Synthetic base stocks compete with petroleum-derived alternatives on oxidative stability metrics in high-temperature industrial applications.
- Plasticizers:Polymer compatibility requirements in flexible PVC compounds drive specification matching to plasticizer efficiency ratios.
- Sealants:Construction applications demand renewable polyol precursors as federal procurement mandates create certified demand channels under USDA BioPreferred program expansion.
Adhesives command premium pricing through technical complexity; sealants gain share fastest on federal bio-preferred procurement mandates.
End Use Industry:
Customer type concentration divides between integrated chemical processors with captive dimer acid requirements and merchant compounders dependent on qualified supplier networks.
- Pulp & Paper:Sizing and coating applications utilize dimer acid derivatives for hydrophobic fiber treatment in high-speed paper machine operations.
- Paints & Inks:Decorative and industrial coating formulators in Italy and Poland consolidate procurement around pre-registered REACH sources to avoid use restriction deadlines.
- Textiles:Fiber lubricant and softener applications require low-color, low-odor dimer acid grades for premium fabric finishing.
- Chemical Processing:Intermediate manufacturing for downstream specialty chemicals concentrates in Malaysia and Indonesian production assets, exposing buyers to regional weather and trade policy disruptions.
Paints & Inks represents the largest application volume; chemical processing expands most quickly on downstream specialty chemical derivative demand.
Packaging Type:
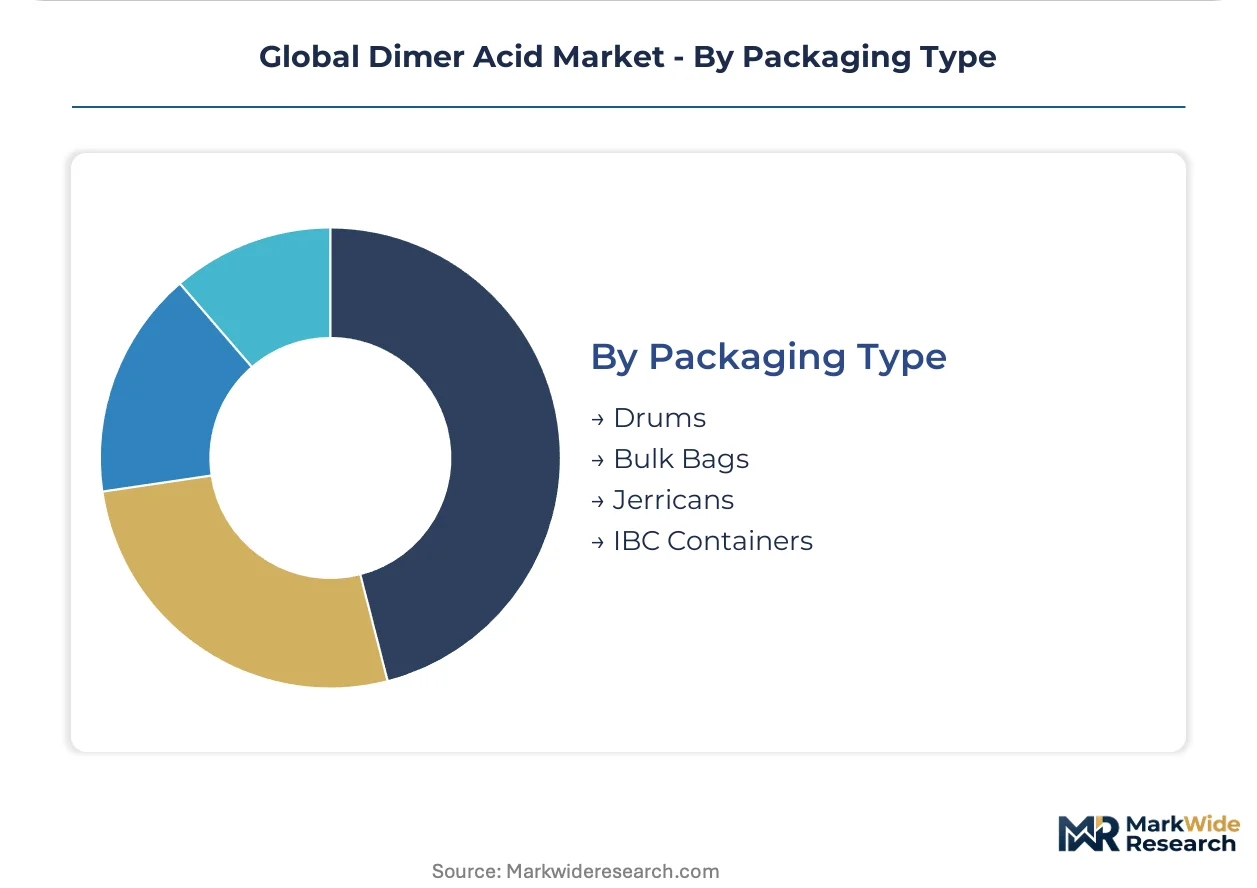
Supply concentration in Malaysian and Indonesian oleochemical complexes dictates bulk logistics optimization for drum and IBC container shipments to coastal Chinese processing clusters.
- Drums:Standard 200-liter steel containers serve mid-volume adhesive and coating formulators requiring frequent batch rotation.
- Bulk Bags:Powdered dimer acid derivatives for polyamide resin compounders enable pneumatic conveying integration.
- Jerricans:20-25 liter polyethylene containers address laboratory-scale formulation development and sample distribution requirements.
- IBC Containers:Intermediate bulk containers optimize logistics for high-volume synthetic lubricant blenders in Germany and Japan piloting membrane separation technology at commercial scale.
Drums retain the largest installed base; IBC containers climb fastest on logistics optimization for high-volume coastal cluster deliveries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysian and Indonesian oleochemical complexes command feedstock pricing leverage over European polyamide formulators, while Chinese coastal processors arbitrage regional cost differentials through direct procurement from Southeast Asian production assets.
China
Shandong and Jiangsu coastal clusters scale dimerized fatty acid output for domestic adhesives and synthetic lubricant supply chains as epoxy coating formulators shift toward bio-based curing agents. SAMR quality certification protocols and GB standards for industrial chemicals fragment market access for non-domestic producers. Qingdao chemical processing hubs consolidate procurement around fewer qualified suppliers under tightening environmental compliance.
United States
USDA BioPreferred program expansion creates certified demand channels for bio-based curing agents in infrastructure coatings and construction sealant applications. EPA Toxic Substances Control Act oversight elevates compliance costs for importers of unrefined dimer acid fractions. Gulf Coast petrochemical corridors attract specialty chemical distributors seeking backward integration into oleochemical feedstock security.
Germany
Specialty lubricant blenders in industrial Ruhr regions pilot membrane separation technology at commercial scale to match performance specifications previously requiring multi-stage refining. ECHA REACH authorization requirements for Substances of Very High Concern compel polyamide resin formulators to document full supply chain provenance. Bavarian adhesive compounders consolidate procurement around pre-registered sources to avoid use restriction deadlines.
India
Underpenetrated polyamide resin capacity in Maharashtra and Gujarat offers first-mover positioning for dimer acid suppliers meeting BIS quality protocols. Central government PLI scheme incentives for specialty chemicals redirect domestic formulation specifications toward verified renewable content thresholds. Mumbai-Pune chemical belts attract merchant traders disintermediated from Chinese coastal cluster procurement.
Japan
Osaka-based hot-melt adhesive manufacturers mandate certificate-of-origin documentation and carbon intensity disclosures from Southeast Asian dimer acid vendors. METI industrial standards for bio-based polymers accelerate specification shifts in flexible packaging laminate applications. Nagoya synthetic lubricant blenders source directly from Malaysian production assets, bypassing regional chemical distributors.
Global Dimer Acid Market Competitive Landscape
Integrated oleochemical majors and merchant specialty chemical distributors split the market along feedstock security lines. BASF anchors the integrated archetype through captive oleochemicals platforms, while Croda International and Emery Oleochemicals occupy positions between plantation-source control and derivative manufacturing scale. Competitive moves concentrate on backward integration into tropical oilseed sourcing and membrane separation technology licensing for yield optimization.
Within the integrated-tier, BASF exemplifies the oleochemicals-to-derivatives model through its German headquarters and multinational corporate structure. Croda International represents the premium-grade supply archetype through its UK-based public limited company status. Emery Oleochemicals occupies the Southeast Asian manufacturing scale position as a Malaysian production asset operator. These three anchors illustrate the strategic divergence between European formulation proximity and Asian feedstock concentration.
| Leading Market Players |
|---|
| BASF |
| Croda International |
| Oleon N.V |
| Emery Oleochemicals |
| Harima Chemicals |
| Aturex Group |
| Florachem Corp. |
| Anqing Hongyu Chemical Co., Ltd |
| Kraton Corporation |
| Others |
Supply & Pricing Matrix
The Singapore-Jakarta freight corridor anchors dimer acid logistics cost dynamics, with container rate volatility compressing margins for European polyamide formulators while enabling Chinese coastal processors to arbitrage regional price differentials through direct procurement from Malaysian and Indonesian production assets.
Pricing Analysis
The customization-premium spread between configured-to-order polyamide resin grades and standard alkyd formulations runs wide, with certification-grade dimer acid commanding substantial markups over commodity lubricant base stocks. Price differentiation hinges on REACH registration status and batch-level carbon intensity documentation, with Italian adhesive compounders least sensitive to cost and Southeast Asian merchant traders most exposed to margin compression. Pricing pressure stems from crude tall oil fatty acid input volatility, eroding predictability for non-integrated producers dependent on spot market C18 feedstock procurement.
Supply Chain Analysis
Tariff exposure between Southeast Asian oleochemical exporters and European downstream formulators dominates supply chain risk assessment for dimer acid derivatives. Production gravity centers on Malaysia, Indonesia, and coastal China, with palm oil derivative supply chains drawing from tropical oilseed plantations, catalytic dimerization catalysts, and membrane separation equipment. Single-source vulnerability concentrates in Malaysian production assets, where regional weather disruptions and trade policy shifts propagate through polyamide resin supply chains. Distribution runs through direct procurement relationships between integrated producers and large compounders, disintermediating traditional regional chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dimer acid market sits at a platform-economics inflection where specification-grade procurement platforms and certificate-of-origin documentation systems are redefining competitive moats around feedstock traceability and regulatory pre-registration.
For Market Incumbents: Insulate polyamide resin market share through captive oleochemicals integration and accelerated membrane separation technology licensing to offset yield disadvantages against emerging enzymatic dimerization pathways. BASF and Croda International should consolidate procurement platform access in China's Shandong coastal clusters before SAMR certification timelines harden supplier qualification barriers. For New Entrants and Emerging Players: Underpenetrated polyamide resin capacity in Maharashtra and Gujarat chemical belts represents the most penetrable entry point for dimer acid suppliers meeting BIS quality protocols. Construction sealant specialists seeking renewable polyol precursors offer a secondary white-space target, with federal procurement mandates under USDA BioPreferred program expansion creating certified demand channels. A technical service-led go-to-market approach addressing formulation troubleshooting gaps will differentiate against established traders lacking application engineering depth. For Investors and Strategic Acquirers: Integrated oleochemical-to-derivatives operators with captive tropical oilseed sourcing and REACH-registered product portfolios represent the highest-conviction acquisition target archetype. Long-term viability across the analysis window rests on backward integration depth and regulatory pre-registration asset bases rather than merchant trading scale. The signal to watch is consolidation velocity among Italian and Polish hot-melt adhesive manufacturers consolidating procurement around pre-registered sources ahead of ECHA use restriction deadlines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tropical Oilseed Sourcing | Captive feedstock security insulates BASF and Croda International from crude tall oil fatty acid spot volatility. |
| Membrane Separation Technology Licensing | Process intensification enables German and Japanese lubricant blenders to match multi-stage refining performance at reduced energy intensity. |
| REACH Pre-Registration Asset Acquisition | Pre-registered dimer acid sources command procurement consolidation from Italian adhesive compounders avoiding use restriction deadlines. |
| Direct Procurement Platform Development | Bypassing regional distributors in Shandong and Jiangsu provinces captures margin compression from specification-driven buyer power concentration. |
| Enzymatic Dimerization R&D Partnership | Collaboration with biotechnology specialists addresses talent scarcity in thermal polymerization optimization limiting yield improvements. |
Research Methodology
Cross-validation between primary interviews with polyamide resin plant managers, procurement leads at flexible packaging OEMs, and specialty lubricant technical R&D directors anchors the qualitative findings. Secondary validation draws from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings of listed oleochemical producers, and ECHA REACH registration databases. Bottom-up segmentation modeling triangulates against top-down market sizing from production capacity assessments across Malaysian and Indonesian oleochemical complexes.
Calibration against historical capacity utilization rates and feedstock cost pass-through elasticities informs the analytical framework across the analysis window. Segmentation dimensions include product grade tier, end-use industry, packaging format, and regional production hub clustering. CAGRs derive from elasticity-adjusted demand projections incorporating polyamide resin capacity expansion timelines and bio-preferred procurement mandate adoption curves. Industry-specific inputs capture catalytic dimerization yield improvement trajectories and membrane separation technology commercialization rates.
Macroeconomic conditions sit as an overlay; deviation in palm oil futures volatility, container freight rates, and EU Green Deal implementation pacing would shift the trajectory. Forecasts reflect documented assumptions around regulatory timeline adherence and technology licensing velocity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Solvent-Borne Adhesives Market
Adhesives & Sealants
US Adhesives and Sealants Market
Adhesives & Sealants
Two Component Adhesive Market
Adhesives & Sealants
Adhesive Resin Market
Adhesives & Sealants
Southeast Asia Adhesives and Sealants Market
Adhesives & Sealants
Malaysia Sealants Market
Adhesives & Sealants
Global Electronics Adhesives Market
Adhesives & Sealants
Correction Fluid and Tape Market
Adhesives & Sealants
Aviation Adhesives and Sealants Market
Adhesives & Sealants
Hydrophobic Pore-Blocking Agents for Waterproof Concrete Market
Adhesives & Sealants
Silane Coupling Agents Market
Adhesives & Sealants
Carpet Adhesive Market
Adhesives & Sealants
Rubber-Based Adhesives Market
Adhesives & Sealants
North America Flock Adhesives Market
Adhesives & Sealants
Leather Glue Market
Adhesives & Sealants
Middle-East and Africa Acrylic Adhesives Market