
 De-Seamable Adhesives Market | 2026-2036
De-Seamable Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
De-Seamable Adhesives Market Outlook
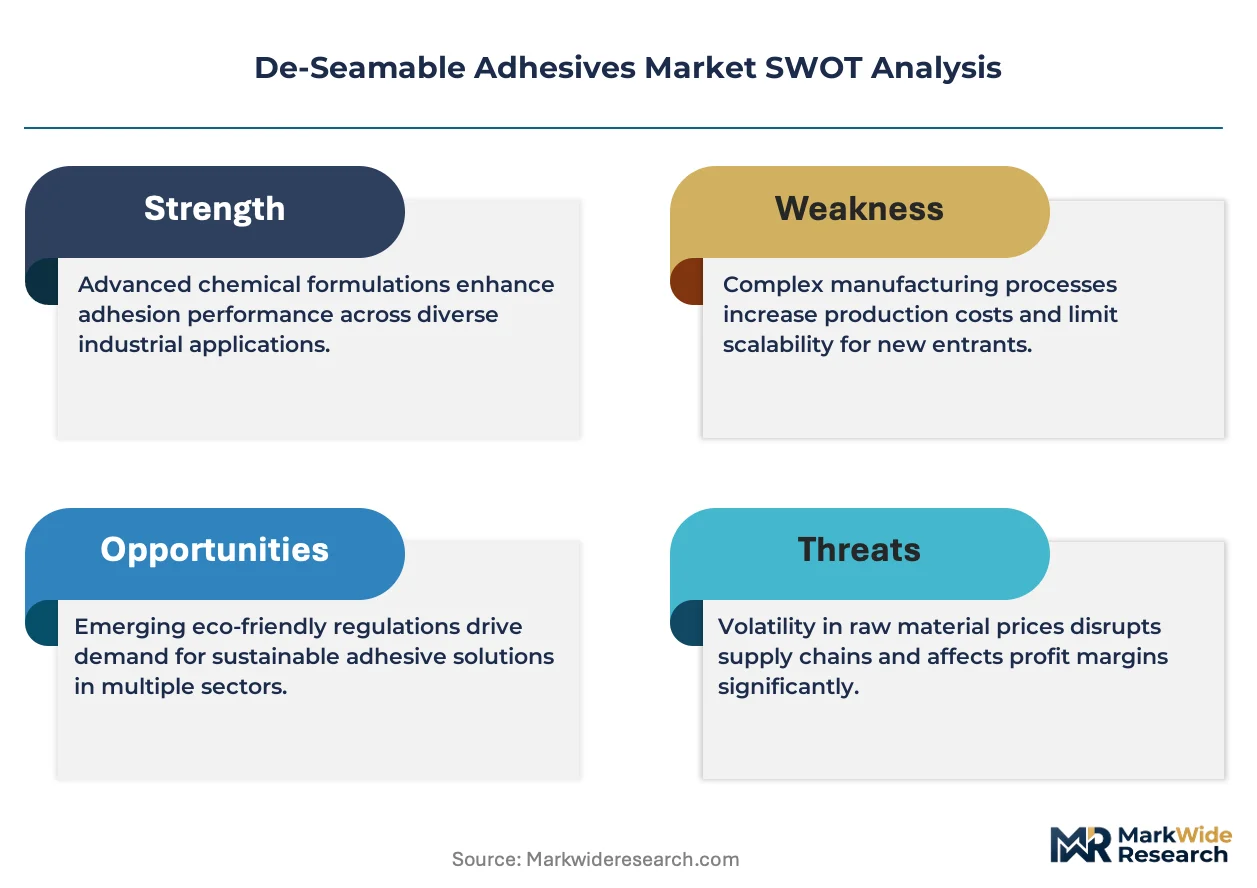
The EU Green Deal is decoupling adhesive permanence from industrial bonding requirements across European manufacturing. 3M leverages its materials science depth to develop reversible acrylic platforms for automotive assembly. Henkel AG & Co. KGaA anchors its position through reactive polyurethane systems that sustain structural integrity yet permit controlled debonding under thermal trigger. Nitto Denko Corporation specializes in pressure-sensitive tapes that dominate electronics disassembly workflows in East Asian supply chains.
De-seamable adhesives are engineered bonding agents formulated with cleavable linkages or thermally reversible chemistries that fracture at defined temperature thresholds or chemical exposure levels, enabling non-destructive separation of joined substrates without mechanical damage. These materials serve the primary industrial purpose of facilitating repair, recycling, and remanufacturing operations where permanent adhesion would create material waste or prevent component recovery. Pressure sensitive adhesives command the largest share of current volume due to their existing integration into electronics and packaging rework processes, while UV-cured technology represents the fastest-expanding segment as manufacturers seek instant processability combined with on-demand reversibility. Hot melt formulations retain mature status in furniture and packaging applications where thermal debonding aligns with established production temperatures.
The European Chemicals Agency (ECHA) evaluates substance restrictions under REACH that directly influence adhesive monomer selection and cleavable additive approval timelines. The EPA oversees volatile organic compound thresholds that shape water-based and solvent-free technology migration in U.S. manufacturing facilities. Japan's METI promotes circular material standards through its resource efficiency frameworks, creating parallel compliance pathways for exporters. Stakeholders must monitor how divergent chemical registration requirements across these jurisdictions fragment formulation strategies and determine whether regional product variants or unified global platforms offer superior economic returns.
Market Dynamics
The EU Green Deal's circular economy mandates are forcing adhesive formulators to abandon permanent chemistries in favor of reversible bonding systems that enable component recovery at end-of-life.
Growth Catalysts
- REACH substance restrictions:ECHA's evolving substance restrictions under REACH are accelerating R&D investment in cleavable adhesive platforms that avoid restricted monomers while maintaining bond integrity.
- Automotive lightweighting:OEMs in Germany and France are integrating de-seamable joints into multi-material vehicle architectures to satisfy recycling quotas without sacrificing structural performance.
- Electronics rework demand:Pressure-sensitive adhesive volumes are expanding in East Asian supply chains where device refurbishment and component harvesting require clean substrate separation.
Market Restraints
- Specialized monomer costs:Cleavable linker chemistries and thermally reversible additives command premium pricing that compresses margins for mid-tier formulators serving price-sensitive packaging segments.
- Regional regulatory fragmentation:Divergent chemical registration timelines between ECHA's REACH, EPA's VOC thresholds, and Japan's METI circular material standards force costly regional product variants.
- Performance trade-offs:Reversible bond architectures currently exhibit lower shear strength and moisture resistance than permanent epoxy or urethane alternatives in structural automotive applications.
Strategic Opportunities
- India's PLI scheme:Production-linked incentives for domestic electronics manufacturing are creating first-mover advantages for adhesive suppliers offering rework-compatible bonding solutions to contract assemblers.
- UV-cured technology convergence:Instant processability combined with on-demand reversibility is opening premium positioning in medical device assembly where sterilization cycles require bond fracture without substrate damage.
- Remanufacturing service channels:Direct technical partnerships with independent repair networks and OEM-authorized remanufacturing facilities are bypassing traditional distributor relationships in industrial equipment markets.
Industry Challenges
- Formulation chemistry expertise:Scarce talent pools in dynamic covalent chemistry and stimuli-responsive polymer design are constraining product development velocity for specialized adhesive houses.
- Joint performance certification:Extended validation timelines for reversible bonds under OEM structural specifications delay commercial adoption in safety-critical automotive and aerospace assemblies.
- Legacy adhesive removal:Retrofitting existing manufacturing lines designed for permanent bonding systems requires capital-intensive process reengineering and operator retraining programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | De-Seamable Adhesives Market |
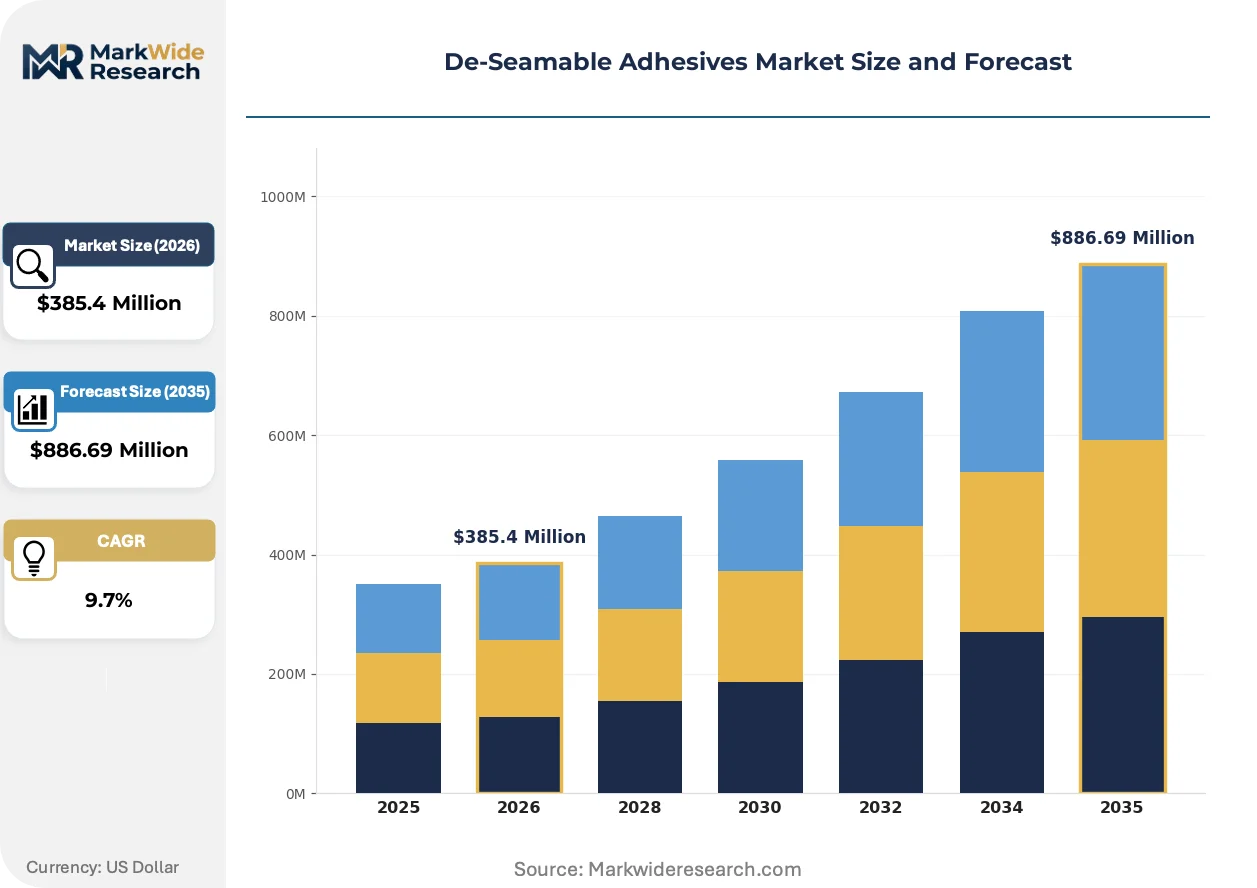
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $886.69 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hot Melt, Pressure Sensitive, Thermosetting, Solvent Based Application: Automotive, Electronics, Packaging, Furniture End User: Manufacturers, Retailers, Contractors, DIY Consumers Technology: Water-Based, Solvent-Free, Reactive, UV-Cured |
| Companies Covered | 3M, Tesa SE, Nitto Denko Corporation, Henkel AG & Co. KGaA, Conagen Inc., ATSP Innovations, Zentraxa, ALFA Klebstoffe AG, Fielco Adhesives LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
De-Seamable Adhesives Market Strategic Shifts
Reversible chemistries are migrating from niche electronics applications into structural industrial bonding as regulatory mandates harden and remanufacturing economics improve.
Photocleavable adhesive platforms incorporating o-nitrobenzyl ester linkages are converging with precision electronics assembly workflows. Medical device manufacturers in Switzerland and Germany are adopting these systems for temporary fixation of components during multi-stage fabrication processes. The technology is converging with automated dispensing equipment to enable sub-micron alignment accuracy followed by clean UV-triggered release.
Japan's METI resource efficiency frameworks are mandating material recovery rates that exceed what mechanical disassembly can achieve. The policy is compelling adhesive suppliers to document reversible bond performance under standardized thermal and chemical trigger conditions. Electronics assemblers in South Korea and Taiwan are responding by qualifying hot-melt formulations with defined melting point windows that align with automated rework stations.
Buyer consolidation among tier-one automotive suppliers is compressing qualification timelines and demanding technical support integration. Procurement teams at German and French OEMs are unbundling adhesive supply from application engineering services, selecting separate vendors for material and process optimization. This pattern is most visible in battery pack assembly where cell-to-cell bonding requires customized debonding protocols for warranty repair and second-life recovery operations.
De-Seamable Adhesives Market Segmentation
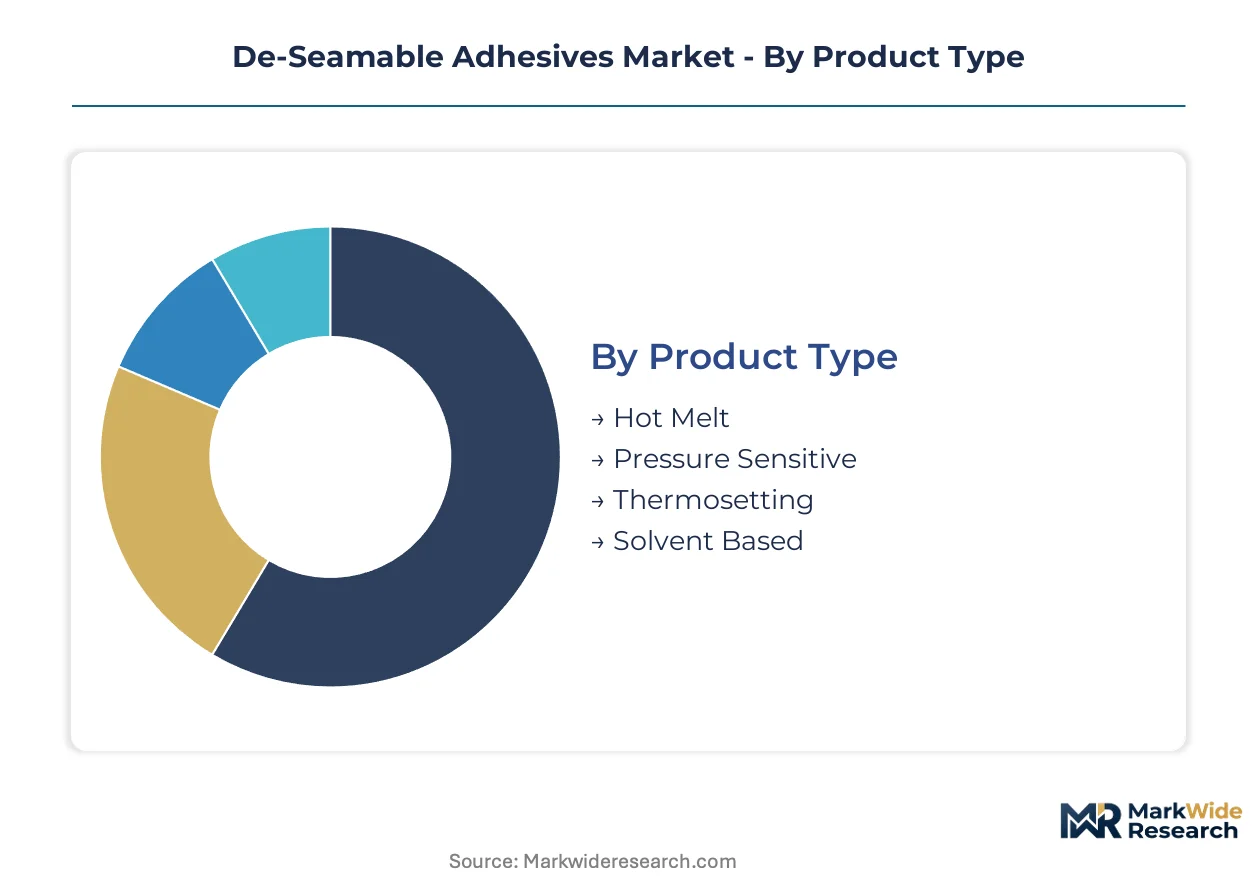
De-seamable adhesive formulations diverge sharply in their integration depth across industrial workflows. Some segments function as standalone bonding layers applied at discrete process stages, while others embed directly into substrate manufacturing or automated assembly systems.
Product Type:
Hot Melt and Pressure Sensitive formulations dominate standalone application scenarios where thermal or mechanical release triggers operate independently of substrate chemistry. Thermosetting and Solvent Based systems embed more deeply, requiring coordinated cure cycles and controlled debonding environments.
- Hot Melt:Thermoplastic polymers with defined melting point windows enable clean separation at established production temperatures. Furniture manufacturers in Germany and packaging converters in the Netherlands favor these systems for established rework infrastructure compatibility.
- Pressure Sensitive:Viscoelastic layers bonded through surface contact alone dominate electronics disassembly workflows. Device refurbishment operations in Taiwan and South Korea concentrate demand for clean substrate separation without thermal exposure.
- Thermosetting:Cross-linked networks with cleavable linkages sustain structural loads yet fracture under chemical trigger.
- Solvent Based:Traditional carrier systems retain niche status where moisture sensitivity prohibits water-based alternatives.
Volume placements concentrate in Pressure Sensitive; the faster expansion belongs to Hot Melt.
Application:
Cost tier stratification separates premium structural bonding from economy-grade temporary fixation. Automotive and Electronics applications command formulation premiums for certified reversibility, while Packaging and Furniture segments prioritize unit economics over specialized debonding performance.
- Automotive:Multi-material vehicle architectures in Germany and France require reversible joints that satisfy end-of-life recycling quotas without compromising crashworthiness. OEM qualification timelines extend 18-24 months for structural adhesive approval.
- Electronics:Component harvesting and device refurbishment drive specification of clean-release bonding layers. Contract assemblers in South Korea and Taiwan integrate pressure-sensitive tapes into automated rework station workflows.
- Packaging:Cost-sensitive segments favor hot-melt reversibility for carton rework and label repositioning.
- Furniture:Thermal debonding aligns with established upholstery and casegoods manufacturing temperatures.
Automotive commands the premium tier; Electronics shows the steepest expansion trajectory.
End User:
Customer type determines technical support intensity and specification authority. Manufacturers and Contractors embed adhesive selection into capital equipment decisions, while Retailers and DIY Consumers operate through distribution channels with limited formulation guidance.
- Manufacturers:OEMs and tier suppliers in Germany's automotive cluster specify customized debonding protocols for battery pack assembly and lightweight body-in-white construction.
- Contractors:Industrial equipment installers in France require on-site technical partnerships for joint performance validation.
- Retailers:Packaging converters in the Netherlands source through distributor networks with standardized thermal trigger specifications.
- DIY Consumers:Furniture assembly kits in Switzerland include reversible hot-melt sticks for consumer-level disassembly.
Manufacturers anchor specification authority; Contractors represent the fastest-climbing customer segment.
Technology:
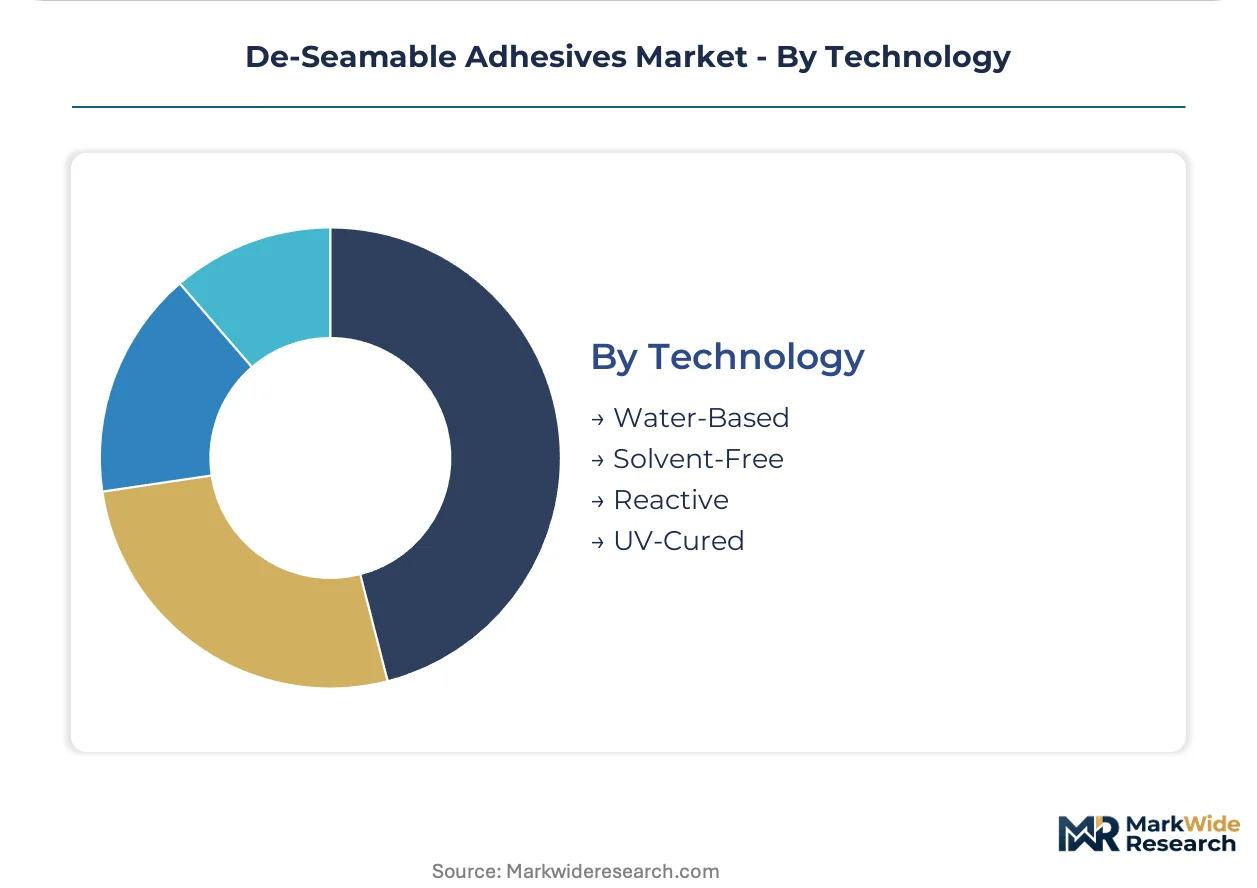
Maturity gradients separate established water-based platforms from emerging reactive and UV-cured systems. Water-Based and Solvent-Free technologies retain process familiarity, while Reactive and UV-Cured chemistries demand capital investment in dispensing and cure equipment.
- Water-Based:EPA VOC thresholds in U.S. manufacturing facilities accelerate migration from solvent carriers. Established dispersion technology supports packaging and furniture applications with minimal process reengineering.
- UV-Cured:Instant polymerization combined with photocleavable linkages enables medical device temporary fixation in Swiss and German fabrication workflows. Automated dispensing equipment achieves sub-micron alignment accuracy followed by clean release.
- Solvent-Free:Hot-melt and reactive systems eliminate carrier evaporation for simplified emissions compliance.
- Reactive:Two-component polyurethane and epoxy platforms with thermally reversible additives sustain structural integrity yet permit controlled debonding.
Water-Based retains volume leadership; UV-Cured gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors European demand for de-seamable adhesives as German OEMs integrate reversible bonding into electric vehicle architectures. The city's automotive cluster drives specification authority for cleavable adhesive platforms across multi-material vehicle construction.
Germany
Battery pack assembly and lightweight body-in-white construction dominate adhesive demand from Stuttgart and Munich manufacturers. The EU Green Deal's circular economy mandates compel OEMs to certify reversible joints for end-of-life disassembly. Tier suppliers in Baden-Württemberg now specify thermal-trigger debonding protocols for warranty repair operations.
United States
EPA VOC thresholds accelerate water-based adhesive migration in Michigan and Ohio automotive plants. Electronics refurbishment hubs in Texas and California concentrate pressure-sensitive tape demand for device component harvesting. Medical device manufacturers in Minnesota adopt UV-cured photocleavable systems for temporary fixation during multi-stage fabrication.
Japan
METI resource efficiency frameworks mandate material recovery rates exceeding mechanical disassembly capabilities. Electronics assemblers in Osaka and Nagoya qualify hot-melt formulations with defined melting point windows for automated rework stations. Automotive suppliers in Toyota City integrate thermally reversible additives into structural bonding systems.
South Korea
Contract electronics manufacturers in Suwon and Gwangju drive specification of clean-release bonding layers for smartphone refurbishment. The country's national environmental regulator enforces extended producer responsibility schemes that elevate reversible adhesive economics. Display panel fabricators in Gumi adopt pressure-sensitive platforms for defect repair without substrate damage.
Switzerland
Precision medical device manufacturers in Basel and Zurich leverage photocleavable o-nitrobenzyl ester systems for sub-micron component alignment. Swissmedic regulations govern temporary adhesive fixation in implantable device assembly workflows. Watchmaking clusters in Geneva integrate reversible bonding for luxury goods repair and component recovery.
De-Seamable Adhesives Market Competitive Environment
Premium-margin players sit above commodity-margin players across formulation complexity and certification depth. The vendor base stratifies between diversified materials conglomerates with captive R&D infrastructure and specialized adhesive houses focused on stimuli-responsive chemistries. Three archetypes dominate: integrated materials science platforms, reactive chemistry specialists, and pressure-sensitive tape manufacturers. Consolidation pressure intensifies as tier-one automotive suppliers compress qualification timelines and unbundle material supply from application engineering services.
Within the diversified materials tier, 3M and Henkel AG & Co. KGaA exemplify scale-driven positions anchored by vertical control over polymer synthesis and regulatory compliance infrastructure. Nitto Denko Corporation occupies a specialist position in pressure-sensitive platforms for electronics disassembly workflows. These three entities represent distinct competitive vectors: materials breadth, reactive formulation depth, and precision coating technology respectively.
| Leading Market Players |
|---|
| 3M |
| Tesa SE |
| Nitto Denko Corporation |
| Henkel AG & Co. KGaA |
| Conagen Inc. |
| ATSP Innovations |
| Zentraxa |
| ALFA Klebstoffe AG |
| Fielco Adhesives LLC |
| Others |
Value Chain & Pricing Dynamics
Petrochemical feedstock indices for acrylic monomers and isocyanate precursors cascade through three distinct pricing tiers, with German automotive OEMs absorbing premium formulations while Asian electronics assemblers negotiate volume-driven standard-grade contracts.
Pricing Analysis
Outcome-based pricing anchored to end-of-life material recovery value dominates structural automotive applications, where OEMs pay premiums for certified reversible bonds that satisfy EU Green Deal recycling quotas. Price differentiation rests on ECHA REACH compliance tier and thermal-trigger precision grade, with medical device manufacturers in Switzerland least sensitive and packaging converters in the Netherlands most sensitive. Cost compression in standard-grade pressure-sensitive tapes is intensifying as Taiwanese contract assemblers consolidate procurement volumes.
Supply Chain Analysis
Workforce availability for dynamic covalent chemistry synthesis concentrates in Germany, Japan, and the United States, where specialized polymer engineering talent commands recruitment premiums. Raw material sourcing draws from petrochemical complexes in the US Gulf Coast, European naphtha crackers, and Asian acrylic acid producers. Single-source vulnerability for photocleavable linker compounds creates supply chain risk. Distribution runs through authorized technical distributors serving OEM specification teams and direct mill-to-plant contracts for high-volume electronics assemblers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating as tier-one automotive suppliers compress qualification timelines and unbundle material supply from application engineering services, forcing mid-tier formulators without captive R&D infrastructure toward exit or acquisition.
For Market Incumbents: Acquire stimuli-responsive polymer patent portfolios to secure exclusivity on thermally reversible chemistries before REACH substance restrictions accelerate. Backward integration into cleavable linker synthesis reduces exposure to specialized monomer cost volatility. OEM procurement unbundling threatens margin capture for pure material suppliers lacking application engineering capabilities. For New Entrants and Emerging Players: India's PLI scheme for domestic electronics manufacturing opens a window for rework-compatible adhesive qualification before incumbent distributors establish technical partnerships. Target India's contract assembly sector through direct mill relationships bypassing established distributor networks. UV-cured photocleavable platforms for medical device temporary fixation offer the most penetrable premium segment with shorter validation cycles than automotive structural applications. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized adhesive houses with ECHA pre-registered substance portfolios in Germany and Switzerland, where regulatory compliance assets compound in value. Long-term viability hinges on circular economy mandate durability across European and East Asian jurisdictions. Watch for METI enforcement intensity in Japan as the inflection signal for Asia-Pacific demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cleavable Linker Synthesis | Captive supply of thermally reversible additives reduces ECHA-regulated monomer cost exposure for German formulators. |
| UV-Cured Photocleavable Platform Launch | Swiss medical device manufacturers adopt o-nitrobenzyl ester systems for sub-micron alignment accuracy in implantable assembly. |
| Long-Term Supply Agreement with Tier-One Automotive | Battery pack assembly contracts with Stuttgart OEMs embed customized debonding protocols for warranty repair operations. |
| Joint Venture with Electronics Rework Station Manufacturer | Taiwanese and South Korean automated rework workflows integrate pressure-sensitive tape specifications directly into equipment design. |
| Green Manufacturing Transition to Water-Based Platforms | EPA VOC threshold compliance in Michigan and Ohio automotive plants accelerates solvent-free formulation migration. |
Study Parameters
Trade publications, ECHA substance registration databases, and automotive OEM technical specifications formed the secondary backbone, supplemented by customs records tracking acrylic monomer and isocyanate precursor flows. Primary interviews with adhesive R&D directors, tier supplier procurement managers, electronics contract assembler quality leads, and ECHA regulatory affairs consultants validated formulation claims and qualification timelines. Bottom-up volume estimates from end-use application sizing and top-down cross-checks against petrochemical feedstock demand established market magnitude ranges.
Bottom-up modeling built from segment-level adhesive consumption rates applied across vehicle production counts, electronics assembly volumes, and medical device fabrication data, while top-down verification tested aggregate figures against chemical industry association reports. Segmentation dimensions included product type, application sector, end-user category, and technology platform across the projection horizon. CAGRs derived from slope analysis of technology adoption curves and regulatory mandate implementation schedules, with UV-cured platform penetration and EU Green Deal compliance deadlines as primary forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for photocleavable adhesive platforms would alter the outlook if medical device manufacturers delay validation timelines. Forecasts reflect assumptions about ECHA enforcement consistency, METI resource efficiency framework durability, and automotive OEM recycling quota stringency. Material deviation in regulatory trigger implementation or reversible bond performance certification delays warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Spain Sealants Market
Adhesives & Sealants
Industrial Adhesives Market
Adhesives & Sealants
North America Sealants Market
Adhesives & Sealants
United Kingdom Sealants Market
Adhesives & Sealants
Global Non-Woven Adhesives Market
Adhesives & Sealants
Structural Adhesives Market
Adhesives & Sealants
Anti-Adhesion Products Market
Adhesives & Sealants
Two Component Adhesive Market
Adhesives & Sealants
Global Hygiene Adhesives Market
Adhesives & Sealants
India Adhesives and Sealants Market
Adhesives & Sealants
Global Methyl Methacrylate (MMA) Adhesive Market
Adhesives & Sealants
Middle East & Africa Adhesives and Sealants Market
Adhesives & Sealants
Asia-Pacific Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Paper-Backing Abrasive Adhesive Discs Market
Adhesives & Sealants
North America Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Fibrin Glue Market