
 Europe Hot-Melt Adhesives Market | 2026-2036
Europe Hot-Melt Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Hot-Melt Adhesives Market Foresight
The Europe hot-melt adhesives landscape is restructuring around a widening split between premium reactive systems and commodity ethylene-vinyl acetate grades. Henkel AG & Co. KGaA leverages its captive resin technology to dominate high-performance automotive bonding, while H.B. Fuller Company anchors its position through deep distribution control across Southern European packaging markets. Arkema Group differentiates via specialized polyamide formulations targeting aerospace and electronics sub-assembly applications.
Hot-melt adhesives are thermoplastic polymer systems formulated from ethylene-vinyl acetate, polyamides, polyesters, or styrenic block copolymers that liquefy upon heating above their softening point and solidify on cooling to form mechanical bonds without solvent carriers, typically applied between 120°C and 200°C for industrial joining, sealing, and surface protection. Ethylene-vinyl acetate remains the mature volume leader but faces margin compression as reactive hot-melt technology captures premium share in automotive and construction end uses where durability and heat resistance command price premiums. Styrenic block copolymers occupy a specialized niche in pressure-sensitive furniture and consumer goods assembly where low-temperature application and clean removability define specification requirements.
REACH registration requirements and the EU Green Deal carbon-border adjustments are forcing reformulation toward bio-based feedstocks and reduced-hazard classifications, with ECHA substance evaluations directly constraining certain phthalate and rosin ester chemistries. The EU F-Gas Regulation and evolving Ecodesign standards further tighten thermal performance benchmarks for adhesives deployed in insulation and appliance manufacturing. Stakeholders must monitor how the EU AI Act and incoming digital product passport requirements reshape traceability obligations across adhesive supply chains.
Market Dynamics
REACH substance evaluations and EU Green Deal carbon-border adjustments are forcing adhesive formulators to abandon phthalate plasticizers and rosin ester tackifiers in favor of bio-based polyamides and reduced-VOC styrenic block copolymers.
Growth Catalysts
- EU F-Gas Regulation:Thermal insulation manufacturers across Germany and France are switching to hot-melt systems that eliminate solvent-based alternatives, expanding specification opportunities for high-performance grades.
- Corrugated packaging lines:E-commerce fulfillment centers in the Netherlands and Belgium are retrofitting automated case-sealing equipment, driving procurement of fast-setting ethylene-vinyl acetate formulations.
- Digital product passports:The incoming EU traceability mandate is compelling automotive OEMs in Stuttgart and Wolfsburg to demand batch-level adhesive provenance, favoring suppliers with integrated resin production.
Market Restraints
- Crude oil derivative volatility:Ethylene and vinyl acetate monomer costs fluctuate with naphtha cracking margins, compressing formulator margins on commodity EVA grades.
- Specialty polyamide concentration:Caprolactam supply for reactive hot-melt feedstocks concentrates among three European polymer producers, creating input bottleneck risk.
- Water-based acrylic substitution:Food packaging converters in Northern Italy are piloting aqueous systems for label applications, threatening pressure-sensitive hot-melt volume in consumer goods.
Strategic Opportunities
- Poland and Czech Republic industrial corridors:Furniture manufacturing clusters near Poznan and Ostrava remain underpenetrated by technical-grade reactive systems, offering first-mover positioning for localized blending operations.
- Aerospace sub-assembly:Specialized polyamide formulations for carbon-fiber bonding in Toulouse and Hamburg assembly plants command certification premiums above standard automotive specifications.
- CSRD disclosure mandates:Scope 3 emissions reporting requirements are pushing packaging converters toward suppliers with verified bio-based content, creating preference windows for certified sustainable feedstocks.
Industry Challenges
- Polymer rheology expertise:Formulation chemists capable of tuning open-time and set-speed for automated dispensing equipment remain scarce across Central European manufacturing regions.
- CE marking documentation:Construction adhesive certifications under harmonized EN standards require 18-24 month validation cycles, delaying new product commercialization in building applications.
- Legacy dispensing infrastructure:Southern European packaging converters operate tank-based hot-melt systems incompatible with low-temperature styrenic block copolymer grades, forcing capital-intensive equipment replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Hot-Melt Adhesives Market |
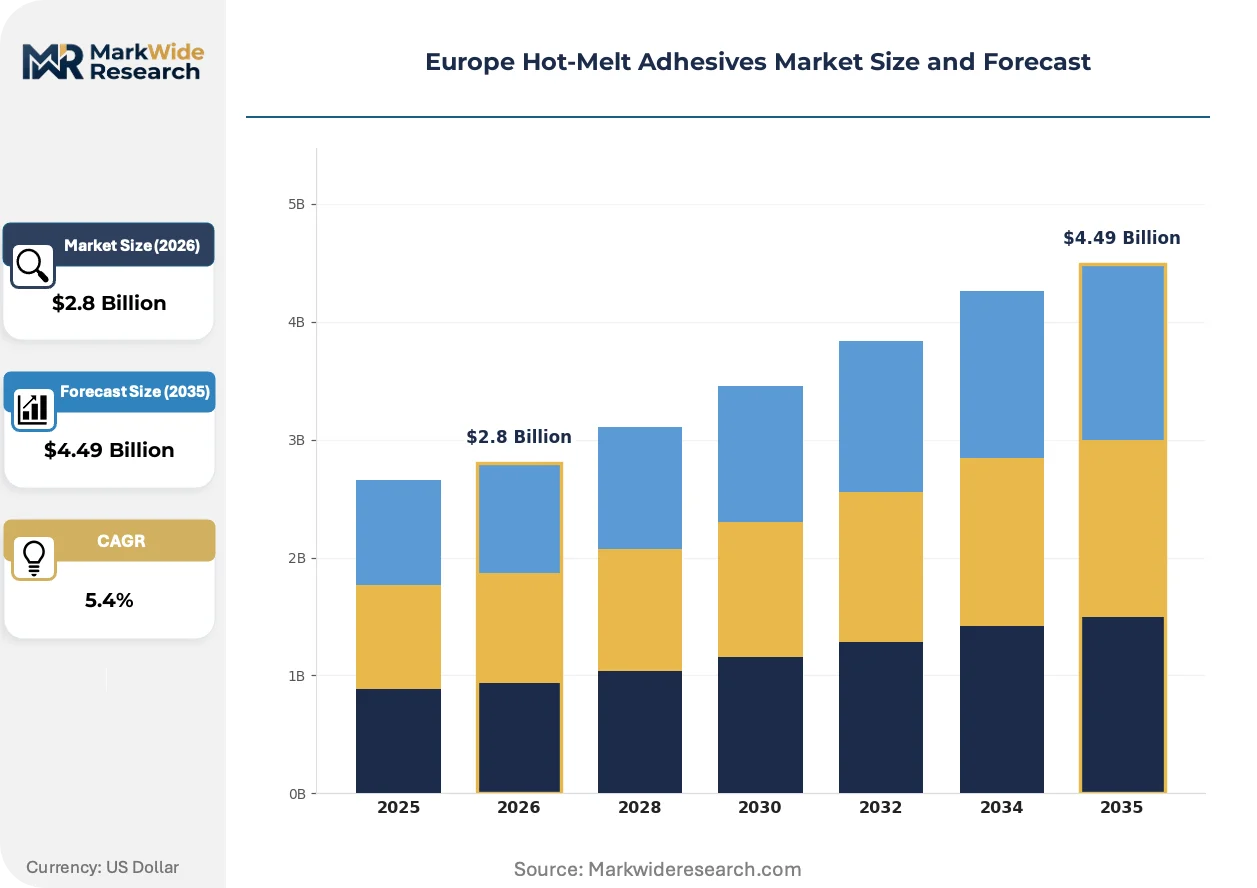
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ethylene-Vinyl Acetate, Styrenic Block Copolymers, Polyamides, Polyesters End User: Packaging, Automotive, Furniture, Construction Application: Sealing, Bonding, Coating, Surface Protection Technology: Hot Melt, Reactive Hot Melt, Non-Toxic, Low Temperature |
| Companies Covered | Henkel AG & Co. KGaA, H.B. Fuller Company, Arkema Group, 3M, Sika AG, Jowat SE, Dow, Buhnen GmbH & Co. KG, KLEBCHEMIE M. G. Becker GmbH & Co. KG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Hot-Melt Adhesives Market Shifts & Advancements
Reactive polyurethane hot-melt technology is compressing the performance gap between thermoplastic convenience and structural epoxy durability, while regulatory digitization and procurement centralization are rewiring how specifications get set and enforced across European industrial buyers.
Moisture-curing reactive hot-melt systems are rewriting competitive positioning in automotive interior bonding. These materials combine initial thermoplastic tack with post-cure crosslinking, delivering heat resistance above 120°C for under-hood applications. BMW and Mercedes-Benz assembly plants in Bavaria and Baden-Württemberg are qualifying these systems for instrument panel lamination, displacing two-part polyurethane adhesives that require mixing equipment and pot-life management.
REACH authorization procedures for diisocyanates are forcing construction adhesive formulators to invest in aliphatic prepolymer alternatives. The ECHA restriction on respiratory sensitizers entered full enforcement in 2023, requiring professional training certification for applicators. German flooring installation contractors are migrating toward silane-terminated polymer hybrids, though hot-melt polyurethanes retain share in prefabricated building element manufacturing where factory-controlled conditions limit exposure risk.
Consolidated procurement through pan-European packaging groups is compressing supplier margins while elevating technical service requirements. Smaller national distributors in Spain and Portugal are losing specification influence as multinational converters centralize adhesive selection at headquarters level. Technical-grade formulators now compete on formulation customization speed and on-site dispensing optimization rather than price alone, with automotive tier-one suppliers in the Rhine-Ruhr corridor demanding 48-hour rheology adjustment turnaround.
Europe Hot-Melt Adhesives Market Segmentation
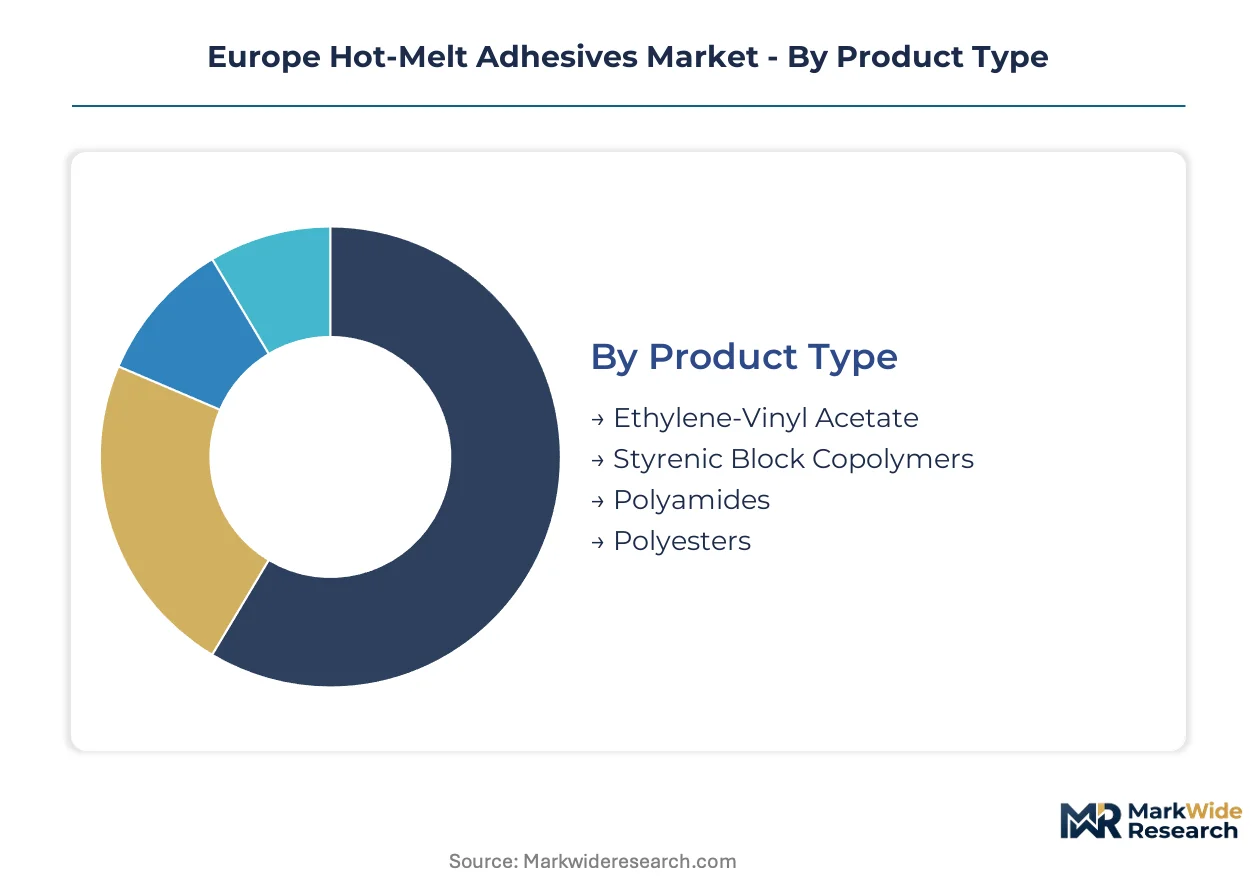
Hot-melt adhesive specifications diverge sharply across European end uses, with REACH substance restrictions and CE marking requirements creating tiered compliance burdens that reshape procurement priorities. Formulators must align polymer chemistry with application thermal profiles and regulatory exposure classifications to maintain market access.
Product Type:
REACH authorization tiers separate commodity thermoplastics from specialty reactive systems requiring diisocyanate handling certification and respiratory protection protocols.
- Ethylene-Vinyl Acetate:Copolymer formulations with vinyl acetate content ranging from 18% to 40% dominate corrugated packaging and bookbinding applications. German e-commerce fulfillment centers in Leipzig and Dortmund specify fast-setting grades with open times under 10 seconds for automated case sealing at line speeds exceeding 200 units per minute.
- Styrenic Block Copolymers:Hydrogenated midblock structures deliver pressure-sensitive adhesion with clean removability for consumer goods labeling. French furniture manufacturers near Lille favor low-temperature application grades that reduce energy consumption on legacy dispensing equipment while maintaining peel strength above 2 N/cm.
- Polyamides:Dimer acid-based formulations serve high-temperature automotive under-hood bonding with service temperatures exceeding 150°C.
- Polyesters:Saturated copolyester hot melts target flexible packaging lamination where FDA and EU 10/2011 food contact compliance is mandatory.
Ethylene-vinyl acetate sits at the top of the volume ranking, with reactive polyurethane systems climbing the fastest as automotive OEMs substitute two-part epoxies.
End User:
Customer scale and specification authority concentrate adhesive demand across four industrial clusters with diverging technical service requirements.
- Packaging:Pan-European converters in the Netherlands and Belgium centralize procurement decisions, demanding batch-level traceability for digital product passport compliance. Automated case and carton sealing lines specify ethylene-vinyl acetate with precise viscosity control across 150°C to 180°C application windows.
- Automotive:Tier-one suppliers in Stuttgart and Wolfsburg require 48-hour formulation adjustment turnaround for instrument panel lamination and trim attachment. Moisture-curing reactive hot melts are displacing two-part polyurethanes in BMW and Mercedes-Benz assembly plants.
- Furniture:Polish manufacturing clusters near Poznan drive specification for edgebanding and veneer bonding with low-VOC emissions profiles.
- Construction:German flooring contractors migrate toward silane-terminated alternatives as ECHA diisocyanate restrictions enter full enforcement.
Packaging commands the largest volume position, with automotive applications expanding most quickly on reactive technology adoption.
Application:
Functional performance requirements dictate polymer selection, with thermal cycling resistance and substrate compatibility defining specification tiers.
- Sealing:Corrugated board and flexible packaging lines prioritize fast green strength development. Belgian converters specify ethylene-vinyl acetate with set speeds under 3 seconds to maintain line efficiency on high-speed case formers.
- Bonding:Structural assembly in automotive and furniture applications demands lap shear strength above 5 MPa. Reactive polyurethane systems deliver post-cure crosslinking for heat resistance exceeding 120°C in under-hood environments.
- Coating:Protective barrier applications in appliance manufacturing require uniform film formation without solvent carriers.
- Surface Protection:Temporary masking and handling protection for electronics and glass substrates utilize low-tack pressure-sensitive formulations.
Sealing represents the highest-volume application, with bonding gaining share fastest on automotive structural adhesive substitution.
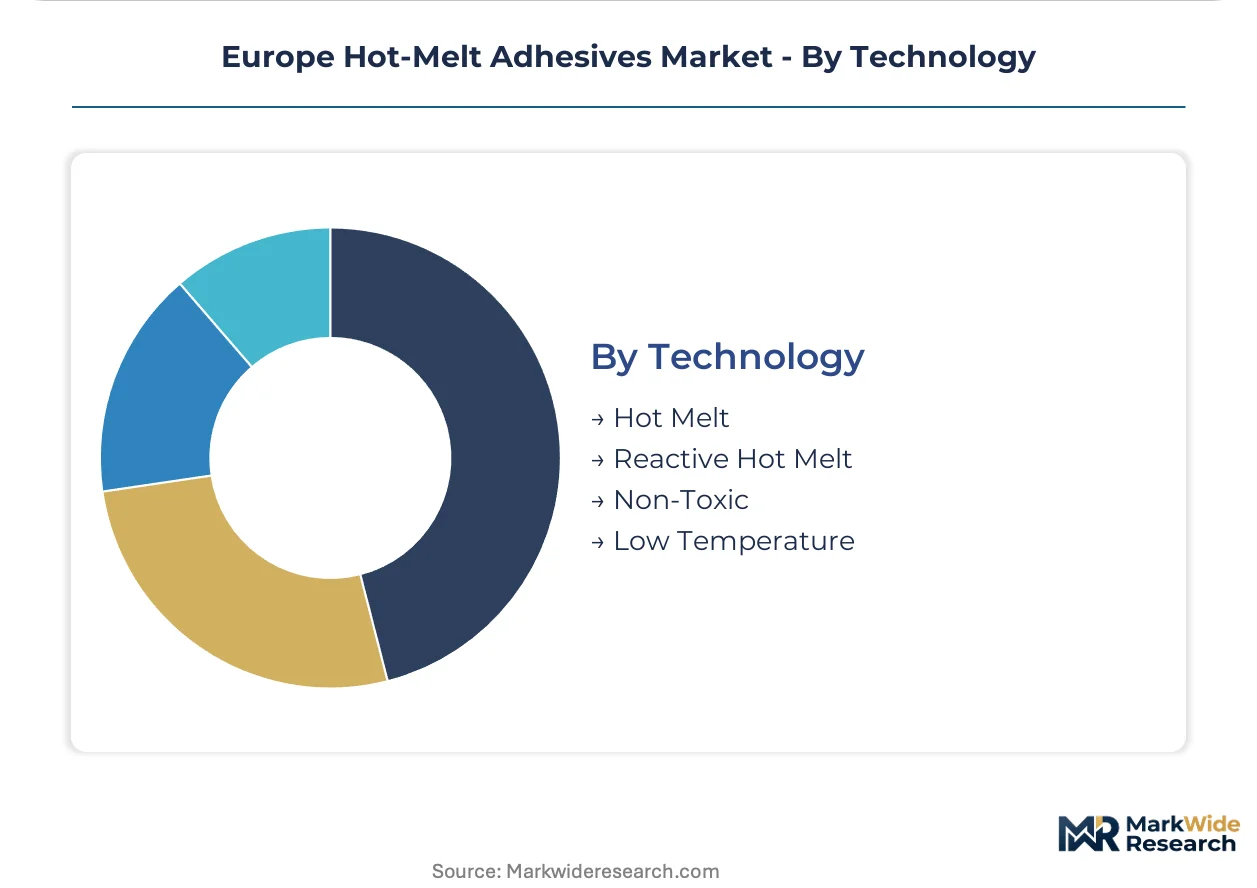
Technology:
Formulation complexity separates established thermoplastic convenience from emerging reactive performance tiers with extended cure requirements.
- Hot Melt:Conventional thermoplastic systems remain the volume foundation across packaging and consumer goods assembly. Physical solidification on cooling eliminates cure time constraints but limits service temperature resistance.
- Reactive Hot Melt:Moisture-curing polyurethane technology combines initial thermoplastic tack with post-application crosslinking. Bavarian automotive plants qualify these systems for dashboard lamination where heat and humidity resistance commands specification premiums.
- Non-Toxic:Reduced-hazard formulations exclude phthalate plasticizers and rosin ester tackifiers under REACH substance evaluations.
- Low Temperature:Styrenic block copolymer grades enable application below 130°C, reducing energy consumption and thermal degradation risk on heat-sensitive substrates.
Conventional hot melt technology anchors volume consumption, with reactive systems showing the steepest expansion trajectory on automotive qualification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands the largest share of European hot-melt adhesive consumption, while France and the Netherlands concentrate packaging demand through automated fulfillment corridors. Industrial clusters across Central and Eastern Europe are expanding technical-grade procurement as automotive and furniture manufacturing relocates eastward.
Germany
Automotive OEMs in Stuttgart and Wolfsburg drive specification for moisture-curing reactive hot melts in instrument panel lamination. ECHA diisocyanate restrictions under REACH entered full enforcement in 2023, compelling flooring contractors toward silane-terminated alternatives. The Rhine-Ruhr corridor anchors packaging converter procurement, where pan-European groups centralize adhesive selection at headquarters level.
France
Furniture manufacturers near Lille favor low-temperature styrenic block copolymer grades that reduce energy consumption on legacy dispensing equipment. The EU Green Deal carbon-border adjustments pressure formulators toward bio-based polyamide feedstocks. Aerospace sub-assembly plants in Toulouse command certification premiums for specialized carbon-fiber bonding formulations.
Netherlands
E-commerce fulfillment centers in Rotterdam and Venlo retrofit automated case-sealing equipment, driving procurement of fast-setting ethylene-vinyl acetate with open times under 10 seconds. CSRD disclosure mandates push packaging converters toward suppliers with verified bio-based content. Belgian corrugated board lines across the border specify identical viscosity control standards.
Poland
Furniture manufacturing clusters near Poznan remain underpenetrated by technical-grade reactive systems, offering first-mover positioning for localized blending operations. Polish converters face delayed REACH compliance timelines compared to Western counterparts. The Poznan-Ostrava industrial corridor attracts adhesive distributors seeking proximity to under-served assembly operations.
Italy
Food packaging converters in Northern Italy pilot aqueous acrylic systems for label applications, threatening pressure-sensitive hot-melt volume in consumer goods. CE marking documentation under harmonized EN standards requires 18-24 month validation cycles for construction adhesives. Southern packaging converters operate tank-based hot-melt systems incompatible with low-temperature grades, forcing capital-intensive equipment replacement.
Europe Hot-Melt Adhesives Market Competitive Landscape
Top-tier vendors anchor high-performance automotive and aerospace bonding, while mid-scale formulators compete on packaging customization speed and regional distribution density. The vendor base separates into three strategic archetypes: integrated resin producers with captive technology, formulation specialists serving single end-use verticals, and distribution-heavy players controlling Southern European specification influence. Capacity expansion and backward integration into key feedstocks represent the dominant competitive moves.
Among Germany-based integrated producers, Henkel AG & Co. KGaA exemplifies the captive-resin archetype, while H.B. Fuller Company occupies a position emphasizing distribution control across packaging markets. Arkema Group sits within the specialty formulation tier, representing differentiated positioning through polymer chemistry expertise. These three anchors illustrate how competitive advantage in European hot-melt adhesives flows from either upstream feedstock control or downstream specification authority.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| H.B. Fuller Company |
| Arkema Group |
| 3M |
| Sika AG |
| Jowat SE |
| Dow |
| Buhnen GmbH & Co. KG |
| KLEBCHEMIE M. G. Becker GmbH & Co. KG |
| Others |
Supply & Pricing Matrix
Caprolactam feedstock costs cascade through reactive hot-melt formulations, compressing margins at German automotive tier-one suppliers while elevating price floors for certified low-VOC grades destined for French furniture clusters under EU Green Deal carbon-border adjustments.
Pricing Analysis
Capacity additions in Central European polymer production are reshaping price floors for commodity ethylene-vinyl acetate grades. Three-tier pricing structure across premium reactive systems, standard thermoplastics, and economy packaging grades separates automotive specification premiums from corrugated board commodity volumes. Price differentiation hinges on REACH certification tier and volume scale, with pan-European packaging converters extracting leverage through consolidated procurement. Cost compression in standard EVA grades is intensifying because naphtha derivative volatility feeds directly into formulator margins. Small-scale Polish furniture manufacturers exhibit highest price sensitivity; aerospace sub-assembly plants in Toulouse show least.
Supply Chain Analysis
Single-source vulnerability sits with German, Belgian, and Dutch resin production clusters for specialty polyamide feedstocks. European hot-melt formulation draws from caprolactam, ethylene, vinyl acetate monomer, and dimer acid inputs. Supply chain risk centers on regulatory restriction: ECHA substance evaluations threaten phthalate and rosin ester supply continuity. Distribution runs through pan-European packaging groups headquartered in the Netherlands and Belgium, with technical-grade automotive specifications controlled by direct supplier-OEM relationships in Stuttgart and Wolfsburg.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe hot-melt adhesives market functions as a geographic-arbitrage play where delayed REACH compliance timelines in Poland and Czech Republic against Western European carbon-border enforcement create 18-24 month cost windows for localized blending investments.
For Market Incumbents: Anticipate water-based acrylic substitution threats in Northern Italian food packaging by accelerating bio-based polyamide certification investments. Backward integration into captive caprolactam supply secures margin defense against commodity EVA price erosion. Prioritize 48-hour rheology adjustment capabilities for automotive tier-one suppliers in the Rhine-Ruhr corridor. For New Entrants and Emerging Players: Regional distributors in Southern Europe represent the most accessible channel partner type for specification influence recovery. Poland and Czech Republic furniture manufacturing clusters offer underpenetrated white-space for technical-grade reactive systems. Pilot localized blending operations near Poznan and Ostrava with CSRD-aligned bio-content verification as the lead go-to-market angle. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale formulators lack integrated resin production and face pan-European procurement centralization. Long-term viability favors specialists with captive polymer chemistry expertise and automotive qualification track records. Watch ECHA authorization timelines for diisocyanate alternatives as inflection signal for reactive polyurethane system valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Caprolactam | Henkel and Arkema anchor margin control through captive feedstock supply for automotive reactive systems. |
| Green Manufacturing Transition | Bio-based polyamide certification under EU Green Deal opens preference windows with CSRD-reporting packaging converters. |
| Long-term Supply Agreement | Pan-European packaging groups in Rotterdam and Venlo lock in viscosity-standardized EVA volumes for automated fulfillment lines. |
| Joint Venture | Polish distributors partner with German formulators to bypass delayed REACH compliance barriers near Poznan manufacturing clusters. |
| Geographic Expansion | Toulouse and Hamburg aerospace sub-assembly plants command certification premiums above standard automotive specifications. |
Research Methodology
Multiple input streams — primary interviews with adhesive formulators, automotive procurement leads, and packaging converter technical directors; secondary validation through ECHA substance databases, Cefic chemical trade reports, and SEC filings from listed suppliers; customs and trade flow data — were reconciled through bottom-up and top-down triangulation.
Segment-level volume and value outputs across the projection horizon reflect reconciliation of polymer grade tier, end-use industry vertical, application thermal profile, and regional production hub clustering. CAGRs were derived from modeled segment trajectories incorporating REACH compliance cost pass-through assumptions and automotive reactive system substitution curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA authorization timelines, EU carbon-border adjustment implementation pace, and caprolactam supply concentration disruptions. Forecasts reflect documented assumptions about regulatory enforcement consistency and feedstock price correlation structures. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Polyurethane Adhesives and Sealants Market
Adhesives & Sealants
Polyester Hot Melt Adhesives Market
Adhesives & Sealants
Global Electronics Adhesives Market
Adhesives & Sealants
Global Adhesion Barrier Market
Adhesives & Sealants
Carpet Adhesive Market
Adhesives & Sealants
Active Metal Brazing (AMB) Paste Market
Adhesives & Sealants
Asia-Pacific Waterproofing Products Market
Adhesives & Sealants
Acrylate Oligomer Market
Adhesives & Sealants
Global Isononyl Acrylate Market
Adhesives & Sealants
Global Methyl Methacrylate (MMA) Adhesive Market
Adhesives & Sealants
Wood to Metal Glue Market
Adhesives & Sealants
Global Construction Adhesives Market
Adhesives & Sealants
Correction Fluid and Tape Market
Adhesives & Sealants
Europe Polyurethane Adhesives Market
Adhesives & Sealants
Japan Sealants Market
Adhesives & Sealants
South America Acrylic Adhesives Market