
 Global Anti-Tack Agents Market | 2026-2036
Global Anti-Tack Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Global Anti-Tack Agents Market Foresight
Specialty tire compounders is collapsing as the dominant buyer archetype for anti-tack agents as pharmaceutical packaging converters and electronics assemblers expand their purchasing volumes. Evonik Industries AG leverages its silicone chemistry platform to supply high-purity release agents for medical-grade rubber applications. Hallstar Company anchors North American supply chains through backward integration into ester-based formulations. Lion Specialty Chemicals Co., Ltd. competes aggressively across Asia with tailored emulsion grades for latex dipping operations.
Anti-tack agents are surface-active compounds, typically comprising metallic stearates, silicone dispersions, or wax emulsions, applied at concentrations between 0.5% and 3.0% to prevent adhesion between uncured rubber layers or sticky polymer films during processing and storage. Their primary purpose is to enable clean demolding, prevent blocking in rolled goods, and maintain dimensional stability through downstream handling. Wax-based and silicone-based product types command the largest volume shares, though modified starch variants are gaining traction in food-contact packaging where FDA and EFSA migration limits apply. Among applications, rubber processing and coating films represent the deepest margin pools, while textile treatments and printing inks remain fragmented with lower pricing power.
EPA oversight of volatile organic compound emissions and REACH registration requirements for stearate salts are elevating compliance costs for legacy formulations, favoring suppliers with robust toxicology dossiers and sustainable chemistry portfolios. China's GB standards for food-contact materials and Japan's METI chemical substance reporting rules add further layer-specific obligations for cross-border suppliers. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether regional formulation customization or unified global product platforms offer superior returns.
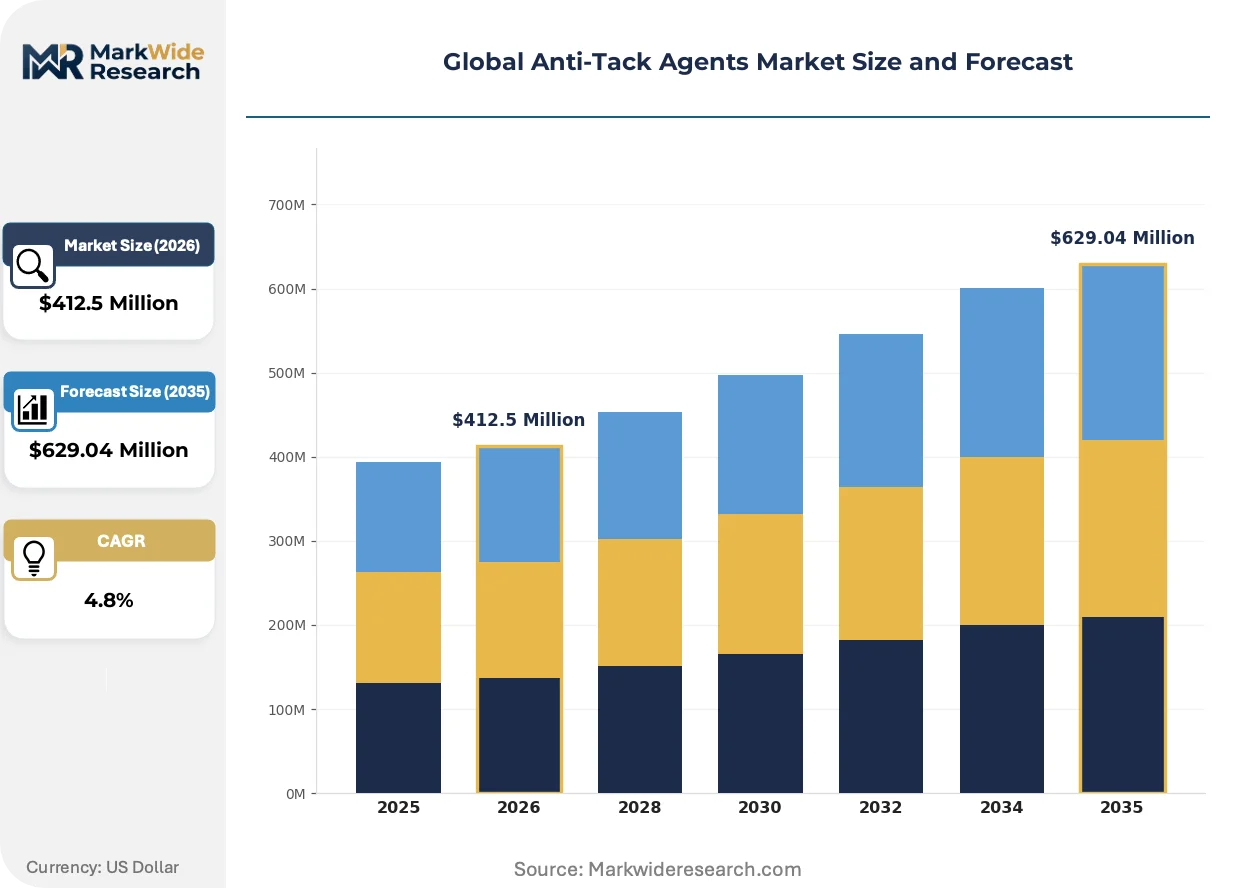
Market Dynamics
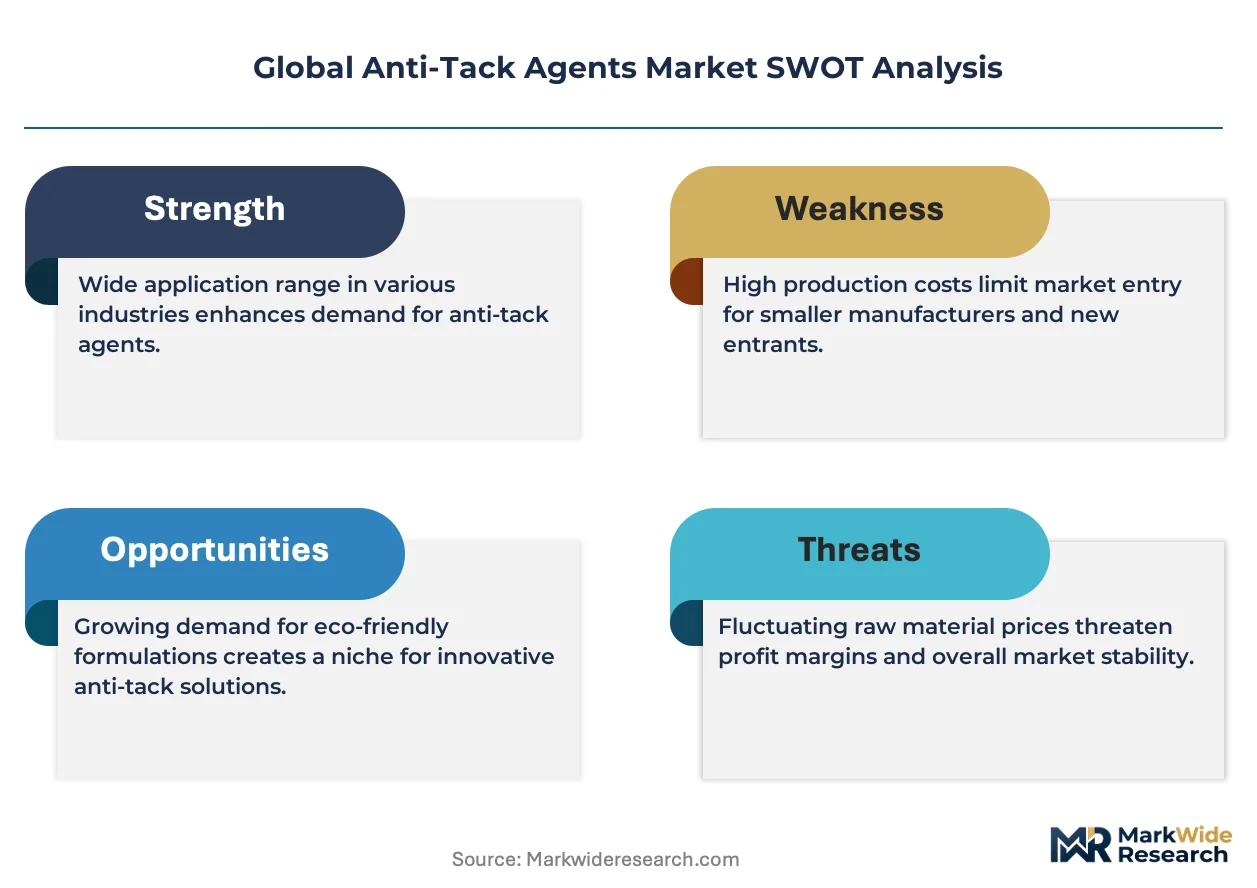
REACH registration requirements for stearate salts and EPA volatile organic compound emission limits are forcing formulators to abandon legacy metallic stearate chemistries in favor of silicone-based and modified starch alternatives, compressing margins for suppliers lacking toxicology dossiers while opening premium positioning for compliant portfolios.
Growth Catalysts
- China's tire production scaling:Domestic rubber processors in Shandong and Jiangsu provinces are expanding anti-tack agent consumption to support mold release efficiency in high-volume tire manufacturing operations.
- REACH compliance migration:European formulators are reformulating toward silicone dispersions and modified starches to meet ECHA registration deadlines for legacy metallic stearate chemistries.
- Medical-grade rubber demand:Pharmaceutical packaging converters require high-purity release agents for syringe stoppers and vial seals, creating specification premiums for ultra-low residue formulations.
Market Restraints
- Palm oil and tallow feedstock volatility:Metallic stearate producers face margin compression from fluctuating oleochemical input costs tied to Southeast Asian agricultural commodity markets.
- Silicone supply concentration:Specialty silicone fluid production concentrates among German and Japanese chemical conglomerates, exposing compounders to allocation risk during supply disruptions.
- Modified starch performance ceiling:Food-contact packaging applications encounter technical limitations in high-temperature rubber processing where thermal stability requirements exceed starch degradation thresholds.
Strategic Opportunities
- India tire manufacturing expansion:Domestic producers under the PLI scheme are upgrading compounding facilities, creating demand for emulsion-grade anti-tack agents tailored to tropical humidity conditions.
- Electronics assembly films:Flexible circuit board manufacturers require ultra-clean release coatings for polyimide film handling, opening specification-driven margins in semiconductor supply chains.
- Japan METI chemical reporting alignment:Suppliers with pre-registered substance dossiers gain accelerated market access versus competitors facing extended compliance timelines.
Industry Challenges
- Formulation toxicology expertise scarcity:REACH-compliant safety data sheet preparation and substance volume tracking require specialized regulatory affairs capabilities that mid-tier compounders struggle to staff.
- Multi-jurisdiction certification timelines:Simultaneous FDA food-contact notification, EFSA migration testing, and China GB standard compliance extend product launch cycles by 18-24 months for global platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Anti-Tack Agents Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $629.04 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone-Based, Wax-Based, Polyethylene, Modified Starch, Polypropylene, Calcium Carbonate Application: Adhesives, Printing Inks, Food Packaging, Coating Films, Rubber Processing, Textile Treatments End User Industry: Pulp & Paper, Packaging Manufacturers, Textile Mills, Paint & Coatings, Automotive Component Fabricators, Electronics Assembly Form: Liquid, Powder, Emulsion, Paste, Granules |
| Companies Covered | Hallstar Company, Chem-Trend L.P., Evonik Industries AG, Blachford Inc., Lion Specialty Chemicals Co., Ltd., Wacker Chemie AG, Struktol Company of America, SASCO Chemical Group, Croda International Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Anti-Tack Agents Market Shifts & Advancements
Formulation chemistry is pivoting toward bio-derived and silicone-based platforms as regulatory pressure compounds performance requirements across tire, medical, and electronics end-uses. Three developments are restructuring competitive positioning.
Modified starch dispersions are supplanting metallic stearates in food-contact packaging applications where FDA and EFSA migration limits apply. Latex dipping operations for glove manufacturing are adopting these formulations at accelerating rates. The shift is compressing volume share for legacy stearate suppliers while elevating pricing power for starch technology licensors.
EPA oversight of volatile organic compound emissions from solvent-based anti-tack coatings is compelling rubber processors to convert toward waterborne emulsion systems. Tire manufacturers in Ohio and South Carolina facilities are leading this transition to avoid air permitting complications. The regulatory pressure is favoring suppliers with established aqueous formulation expertise over solvent-based legacy players.
Specification-driven procurement now dominates medical-grade rubber applications where pharmaceutical packaging converters require batch-level residue documentation. Buyers are consolidating supplier relationships around vendors with integrated analytical testing capabilities. This concentration is most visible in German and Swiss medical device supply chains where OEM audit requirements have intensified.
Global Anti-Tack Agents Market Segmentation
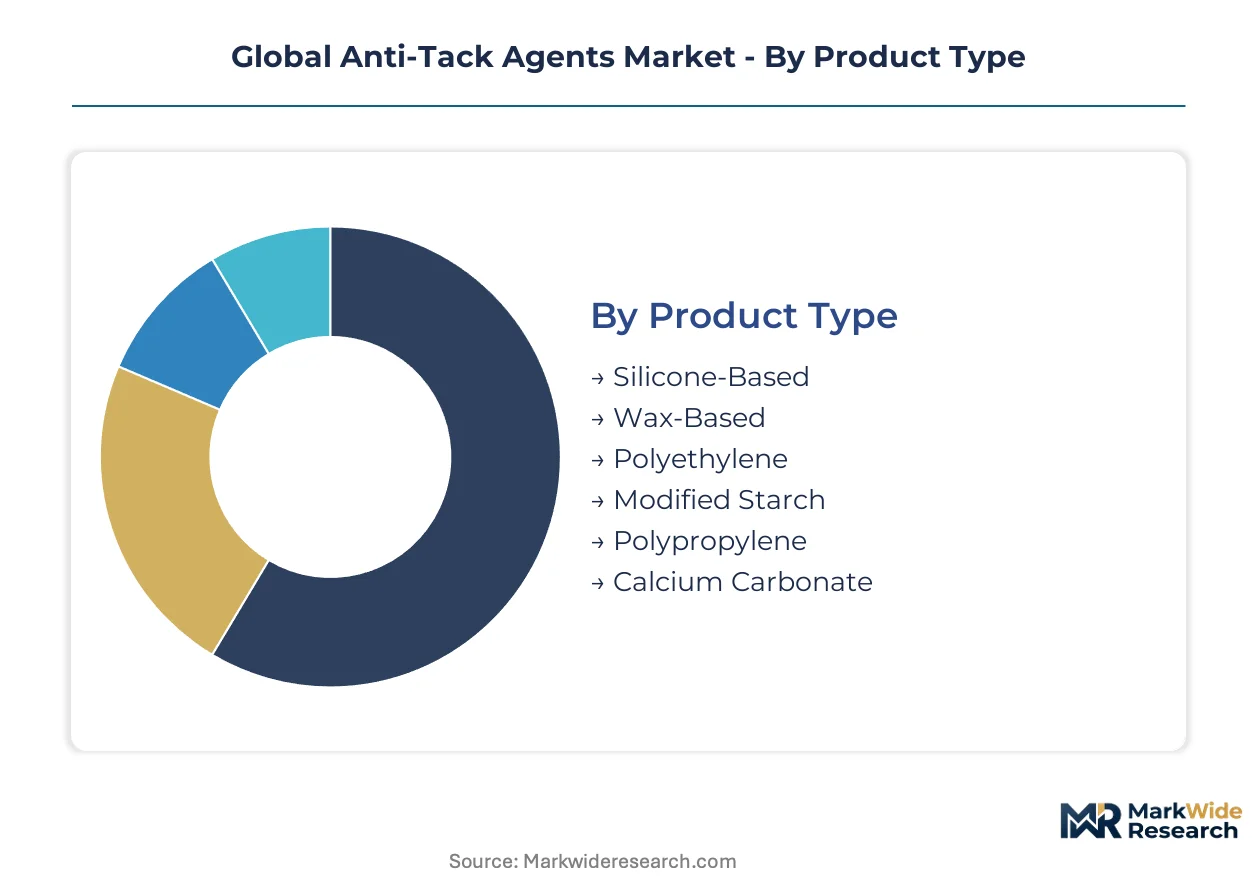
Segmentation in anti-tack agents reveals how formulation chemistry, application requirements, and regulatory constraints create distinct margin pools. Suppliers must align product architectures with specific end-use specifications rather than pursuing universal platforms.
Product Type:
Margin concentration follows regulatory compliance intensity, with premium pricing available in medical-grade and food-contact segments where residue limits are tightest.
- Silicone-Based:These formulations comprise polydimethylsiloxane dispersions and emulsions delivering thermal stability above 200°C. Pharmaceutical packaging converters in Germany and Switzerland specify ultra-low residue grades for syringe stopper production, with batch-level documentation requirements creating specification premiums.
- Wax-Based:Paraffin and microcrystalline wax emulsions dominate tire mold release applications where cost efficiency outweighs extreme temperature demands. Shandong and Jiangsu province rubber processors in China consume these grades at scale for high-volume tire manufacturing.
- Polyethylene:Low-density polyethylene dispersions serve general-purpose rubber processing with moderate thermal requirements.
- Modified Starch:Bio-derived alternatives are displacing metallic stearates in FDA and EFSA-regulated food-contact packaging where migration limits apply.
- Polypropylene:Higher melting point than polyethylene, suited to automotive underhood rubber components.
- Calcium Carbonate:Lowest-cost option for non-critical applications with minimal performance specifications.
The dominant share belongs to wax-based formulations, while modified starch is closing the gap fastest on regulatory tailwinds.
Application:
Volume flows toward processing-intensive segments where anti-tack agents prevent material losses and quality defects during high-speed operations.
- Rubber Processing:Tire and industrial rubber manufacturers apply these agents at 0.5-3.0% concentrations to prevent uncured layer adhesion and enable clean mold release. Ohio and South Carolina facilities are converting from solvent-based to waterborne systems under EPA volatile organic compound pressure.
- Coating Films:Polyimide and polyester film manufacturers require ultra-clean release coatings for flexible circuit board production. Semiconductor supply chains in Japan and South Korea specify sub-ppm residue tolerances.
- Adhesives:Pressure-sensitive adhesive producers use anti-tack agents to control tack buildup during coating operations.
- Printing Inks:Offset and flexographic ink formulators prevent blocking in rolled substrates.
- Food Packaging:Converters face FDA and EFSA migration limits driving starch-based adoption.
- Textile Treatments:Fiber and fabric processors prevent adhesion during finishing operations, though pricing power remains limited.
Rubber processing commands the deepest margin pool, with coating films expanding most quickly on electronics demand.
End User Industry:
Procurement sophistication varies sharply, with automotive and electronics buyers imposing qualification protocols that exclude commodity suppliers.
- Automotive Component Fabricators:Tier-1 suppliers to German and Japanese OEMs enforce IATF 16949 quality systems with approved vendor lists. Michigan and Bavaria-based compounders specify silicone-based agents for underhood applications exceeding 150°C service temperatures.
- Electronics Assembly:Flexible circuit board and display film manufacturers require ionic purity below 10 ppm. South Korean and Taiwanese semiconductor material suppliers conduct quarterly supplier audits with batch traceability mandates.
- Packaging Manufacturers:Pharmaceutical and food-contact converters drive specification intensity in medical-grade segments.
- Pulp & Paper:Release coatings for specialty paper grades face moderate technical barriers.
- Textile Mills:Fragmented buyer base with limited pricing power for suppliers.
- Paint & Coatings:Niche applications in specialty industrial coatings.
Automotive component fabricators retain the dominant procurement volume, while electronics assembly is climbing the fastest on semiconductor supply chain expansion.
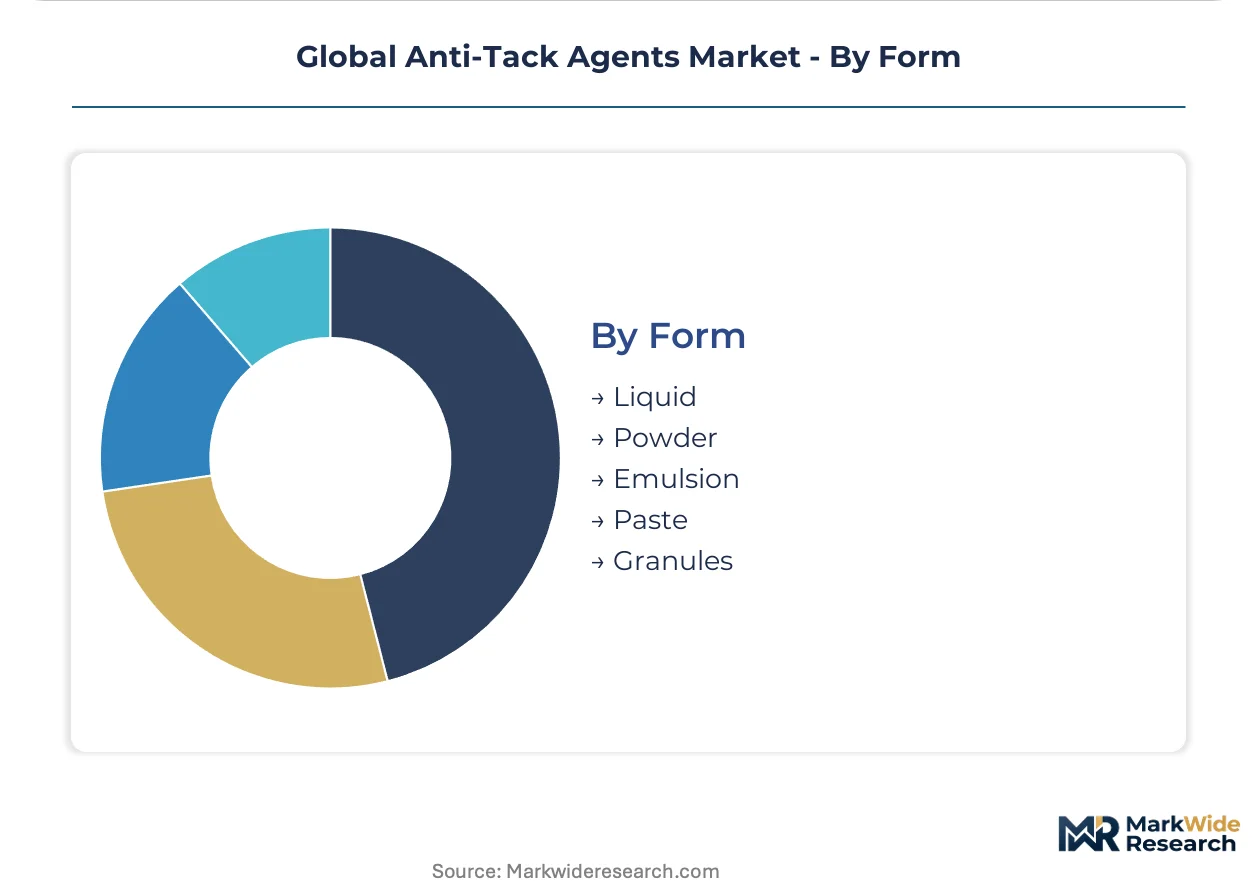
Form:
Physical form selection determines application equipment compatibility and environmental compliance pathways.
- Emulsion:Water-based systems are displacing solvent carriers under EPA and REACH volatile organic compound restrictions. Tire manufacturers in the US and EU are mandating aqueous grades for air permitting compliance.
- Liquid:Solvent-borne formulations retain position in high-speed coating operations where drying speed is critical.
- Powder:Dry-blend applications in rubber compounding where moisture sensitivity is a concern.
- Paste:High-viscosity systems for specialized dipping operations.
- Granules:Dust-free handling for automated feeding systems in large-scale rubber processing.
Emulsion forms hold the dominant position, with powder gaining share fastest in humidity-sensitive tropical processing environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Qingdao port complex in Shandong province anchors China's rubber chemical import infrastructure, handling specialized additive cargoes that feed tire manufacturing clusters along the Yellow Sea coast. This maritime gateway underwrites the country's dominant position in anti-tack agent consumption.
United States
Ohio and South Carolina tire plants are converting from solvent-based to waterborne anti-tack systems under EPA volatile organic compound emission limits. The EPA's National Emission Standards for Hazardous Air Pollutants are accelerating this transition. Akron, Ohio remains the historic center of rubber chemical formulation expertise, though production activity has shifted toward the Southeast.
Germany
Pharmaceutical packaging converters in the Rhine-Ruhr region specify ultra-low residue silicone grades for medical-grade rubber applications. REACH registration deadlines for stearate salts are forcing compounders toward compliant alternatives. Leverkusen and Ludwigshafen host integrated chemical parks where release agent producers co-locate with polymer suppliers.
China
Shandong and Jiangsu province rubber processors are scaling anti-tack agent consumption to match tire production growth. GB standards for food-contact materials are tightening migration limits for packaging applications. The Yangtze River Delta concentration of latex dipping operations for glove manufacturing is driving emulsion-grade demand.
Japan
Flexible circuit board manufacturers in the Kanto region require ionic-purity specifications below 10 ppm for polyimide film release coatings. METI chemical substance reporting rules are accelerating compliance timelines for imported formulations. The Nagoya automotive supplier corridor specifies silicone-based agents for underhood components exceeding 150°C service temperatures.
India
Domestic tire producers under the PLI scheme are upgrading compounding facilities with emulsion-grade anti-tack systems. BIS certification requirements for rubber processing chemicals are elevating quality standards. Tamil Nadu and Gujarat state manufacturing zones are attracting formulation investments to serve tropical humidity processing conditions.
Global Anti-Tack Agents Market Competitive Landscape
Listed leaders compete with private specialists across formulation chemistry platforms, creating a tiered structure where scale-driven commodity suppliers coexist with premium-positioned technology licensors. The vendor base spans German and Japanese chemical conglomerates, North American specialty compounders, and Asian emulsion specialists. Three archetypes dominate: integrated silicone chemistry platforms, backward-integrated ester formulators, and regional emulsion-grade tailors. Capacity expansion in aqueous systems and portfolio diversification toward medical-grade specifications represent the dominant competitive moves.
Among the integrated chemical platforms, Evonik Industries AG exemplifies the silicone chemistry archetype with its polydimethylsiloxane expertise, while Hallstar Company anchors North American supply chain positioning through its ester-based formulation heritage. Lion Specialty Chemicals Co., Ltd. occupies a position within the Asia-Pacific emulsion specialization tier, serving latex dipping and tropical processing applications. These three entities represent distinct strategic postures: technology licensing leverage, regional supply chain control, and application-specific tailoring respectively.
| Leading Market Players |
|---|
| Hallstar Company |
| Chem-Trend L.P. |
| Evonik Industries AG |
| Blachford Inc. |
| Lion Specialty Chemicals Co., Ltd. |
| Wacker Chemie AG |
| Struktol Company of America |
| SASCO Chemical Group |
| Croda International Plc |
| Others |
Supply & Pricing Matrix
REACH registration deadlines for stearate salts simultaneously gate supplier qualification and stratify price tiers, forcing compounders to absorb toxicology dossier costs while extracting premiums from compliant silicone and modified starch alternatives. This regulatory threshold compresses margins for legacy metallic stearate producers while elevating pricing power for portfolios with pre-registered substance volumes.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates medical-grade silicone formulations with batch-level residue documentation from general-purpose wax emulsions and commodity calcium carbonate fillers. Price differentiation hinges on certification intensity—FDA food-contact notification and EFSA migration testing add 18-24 month compliance costs—and volume scale, with tire manufacturers in Shandong province commanding steep discounts against pharmaceutical packaging converters in Germany. Cost compression in standard-tier wax emulsions is intensifying because palm oil and tallow feedstock volatility from Southeast Asian agricultural markets erodes producer margins. Automotive component fabricators prove least price-sensitive due to IATF 16949 vendor-list lock-in, while textile mills and pulp processors exhibit highest sensitivity with minimal specification barriers.
Supply Chain Analysis
Container availability fluctuations on Asia-Europe trade lanes and Qingdao port congestion periodically disrupt inbound logistics for German and Japanese silicone fluid shipments. Supply concentrates in China for wax emulsions and modified starches, Germany for high-purity silicone dispersions, and Japan for specialty emulsion grades—each drawing from distinct oleochemical and petrochemical feedstock bases. Raw material dependencies span Southeast Asian palm oil derivatives, North Sea paraffin streams, and specialty silicone fluids from Rhineland chemical parks. Single-source vulnerability concentrates in German and Japanese silicone fluid production, exposing compounders to allocation risk during supply disruptions. Distribution runs through regional blending facilities co-located with tire manufacturing clusters in Shandong, Ohio, and Bavaria.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face a substitution defense against accelerating adoption of modified starch alternatives in food-contact packaging, where FDA and EFSA migration limits are displacing legacy metallic stearate volumes. Survival requires simultaneous cost discipline in commodity tiers and premium capture in medical-grade specifications.
For Market Incumbents: Shield medical-grade silicone positions through backward integration into polydimethylsiloxane production and captive analytical testing capabilities for batch-level residue documentation. Accelerate aqueous emulsion capacity in Ohio and South Carolina to capture EPA-driven solvent-to-waterborne conversions among tire manufacturers. The priority lever rests on toxicology dossier depth—suppliers lacking REACH-compliant safety data sheet preparation capabilities face forced exit as ECHA registration deadlines harden.
For New Entrants and Emerging Players: Anchor in India's PLI-scheme tire manufacturing expansion, where domestic compounding facility upgrades create demand for emulsion-grade anti-tack agents tailored to tropical humidity conditions. Target flexible circuit board release coatings for polyimide film handling in South Korea and Taiwan, where sub-ppm ionic purity specifications exclude legacy commodity suppliers. The most penetrable entry point lies in BIS-certified formulations for Tamil Nadu and Gujarat state manufacturing zones, leveraging local blending partnerships to bypass multi-year FDA and EFSA approval timelines.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with orphaned anti-tack agent divisions lacking medical-grade certification focus—assets where pharmaceutical packaging converter relationships remain underdeveloped. Long-term viability favors suppliers with integrated silicone chemistry platforms and pre-registered REACH substance dossiers, positioned to consolidate share as regulatory compliance costs accelerate mid-tier compounder exits. The signal to watch is ECHA registration deadline enforcement intensity; material acceleration in compliance audits would trigger distressed asset availability and reshape competitive concentration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Fluid Production | Captive supply of polydimethylsiloxane insulates Evonik and Wacker from German-Japanese allocation risk during disruptions. |
| Medical-Grade Certification Investment | FDA food-contact notification and EFSA migration testing unlock pharmaceutical packaging converter premiums in Rhine-Ruhr clusters. |
| Aqueous Emulsion Capacity Expansion | Ohio and South Carolina facility additions capture EPA-driven solvent-to-waterborne conversions among tire manufacturers. |
| Regional Blending Joint Venture | Co-location with Shandong tire clusters reduces Qingdao port dependency and accelerates delivery to Jiangsu processors. |
| Modified Starch Technology Licensing | Technology transfer agreements displace metallic stearates in FDA-regulated food-contact packaging applications. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with tire compound procurement managers, pharmaceutical packaging converter technical directors, rubber processing plant engineers, and specialty chemical distribution channel partners. Secondary validation drew from customs and trade data, ECHA registration databases, SEC 10-K filings from listed chemical conglomerates, and GB standard documentation for food-contact materials. Bottom-up volume estimates from end-use consumption patterns were triangulated against top-down supplier capacity assessments across the analysis window.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning formulation chemistry grade, end-use industry intensity, physical form compatibility, and regional regulatory cluster alignment. CAGRs were derived from regression-based demand elasticity modeling against tire production indices, electronics assembly output, and packaging converter capacity expansion. Industry-specific forecast inputs included REACH registration timeline enforcement probabilities and EPA National Emission Standards for Hazardous Air Pollutants implementation pace.
Decision-makers should treat outputs as directional under base assumptions of sustained regulatory enforcement intensity and stable oleochemical feedstock availability; material deviation would warrant model refresh. Specific risks that could revise trajectories include abrupt REACH registration deadline extensions, palm oil supply shocks from Southeast Asian climate events, or accelerated modified starch performance breakthroughs exceeding thermal stability thresholds. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
High Temperature Adhesives Market
Adhesives & Sealants
Debonding-on-Demand Adhesive Tapes for Electronics Dismantling Market
Adhesives & Sealants
Metal Glue Market
Adhesives & Sealants
India Waterproofing Solutions Market
Adhesives & Sealants
Dural Sealant Market
Adhesives & Sealants
Japan Sealants Market
Adhesives & Sealants
Hybrid Silane-Terminated Polymer Adhesives for EV Battery Pack Assembly Market
Adhesives & Sealants
Elastic Bonding Adhesive and Sealant Market
Adhesives & Sealants
High Temperature Sealants Market
Adhesives & Sealants
United Kingdom Adhesives Market
Adhesives & Sealants
Europe Adhesives Market
Adhesives & Sealants
Acrylates Copolymer Market
Adhesives & Sealants
France Sealants Market
Adhesives & Sealants
Semiconductor Packaging Adhesives Market
Adhesives & Sealants
Global Adhesion Promoter Market
Adhesives & Sealants
Adhesive Primer Market