
 India Adhesives and Sealants Market | 2026-2036
India Adhesives and Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
India Adhesives and Sealants Market Foresight
Western India is fragmenting as the dominant adhesive manufacturing belt, with Gujarat and Maharashtra adding solvent-based and hot-melt capacity to serve automotive and packaging OEMs. Pidilite Industries Limited anchors the consumer and industrial segments through its Fevicol brand architecture and deep distribution into tier-2 and tier-3 towns. Henkel Adhesives Technologies India Private Limited competes on automated dispensing technologies for electronics and automotive assembly lines. Dow Inc. specializes in high-performance silicone and polyurethane platforms for construction and infrastructure projects.
Adhesives and sealants comprise formulated polymer systems—acrylics, polyurethanes, silicones, epoxies, and rubber-based compounds—engineered to bond, seal, or coat substrates through mechanical interlocking, chemical crosslinking, or surface energy modification; tensile shear strengths range from 0.1 MPa for pressure-sensitive tapes to 40 MPa for structural epoxies, with cure mechanisms spanning moisture, heat, UV, and two-part catalytic reactions. Water-based formulations now lead volume share in woodworking and packaging applications, while reactive systems command margin pools in electronics and automotive structural bonding where thermal cycling resistance and dielectric properties are specified. Hot-melt adhesives sustain double-digit growth trajectories in e-commerce packaging fulfillment centers, displacing solvent-based alternatives under BIS VOC emission limits.
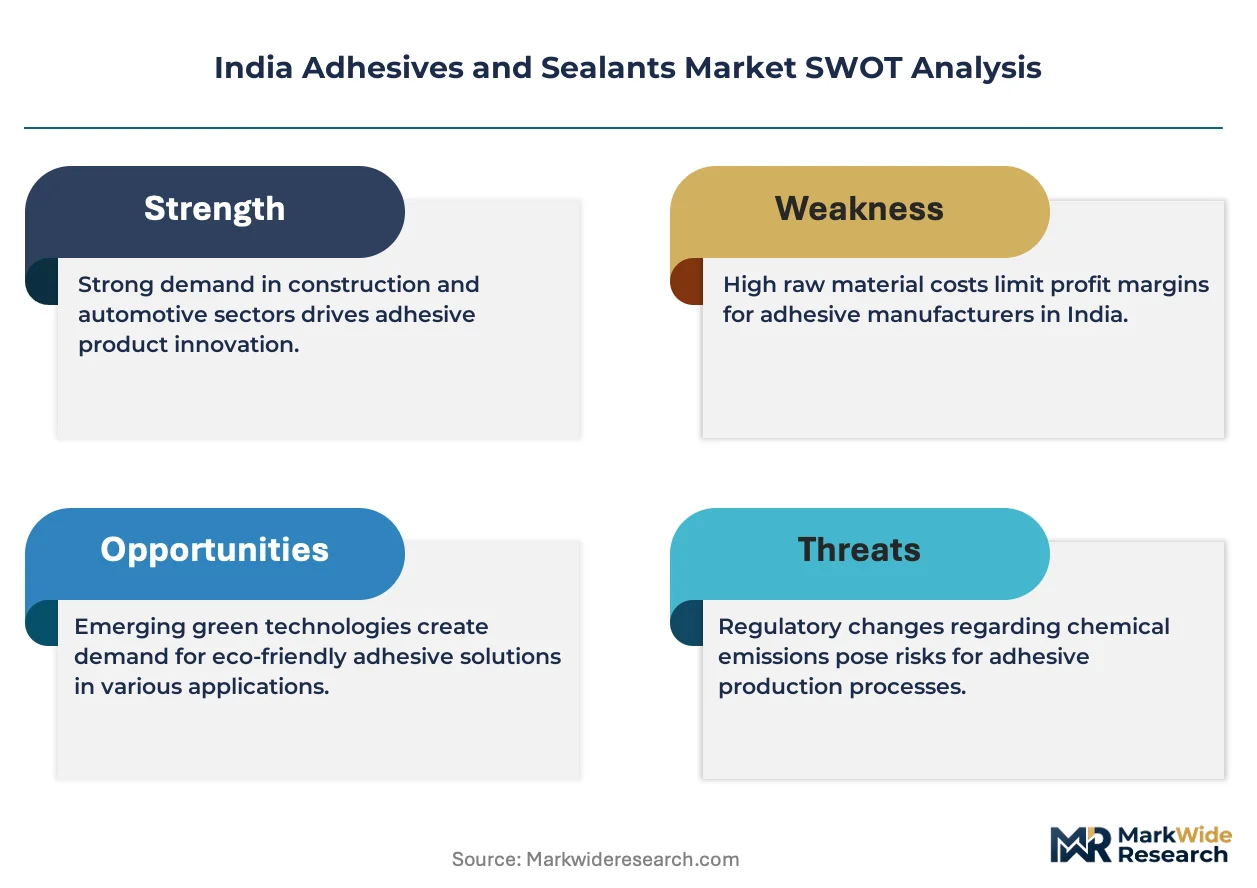
BIS mandates on formaldehyde and VOC content in interior-grade adhesives, alongside CDSCO scrutiny of medical-device bonding agents, are forcing reformulation investments across domestic and multinational manufacturers. The PLI scheme for specialty chemicals and advanced materials is channeling capital toward domestic resin synthesis and captive monomer production. Stakeholders must monitor BIS standard revisions for construction adhesives and the pace of state-level enforcement of green building codes in Maharashtra and Tamil Nadu to anticipate specification shifts in public infrastructure procurement.
Market Dynamics
BIS certification mandates on VOC emissions and formaldehyde content are forcing wholesale reformulation of adhesive portfolios across Indian manufacturing, compressing solvent-based margins while accelerating water-based and hot-melt capacity investments in Gujarat and Maharashtra industrial corridors.
Growth Catalysts
- PLI scheme for specialty chemicals:Capital subsidies are channeling domestic investment toward captive resin synthesis and monomer production, reducing import dependency for polyurethane precursors and acrylic emulsions.
- Automotive OEM clustering:Maharashtra and Tamil Nadu assembly plants are specifying reactive adhesive systems for lightweighting applications, pulling demand for structural bonding agents with thermal cycling resistance.
- E-commerce packaging fulfillment:Hot-melt adhesive consumption is accelerating in automated carton sealing operations across western India distribution centers, displacing tape-based closures under BIS emission limits.
Market Restraints
- Petrochemical feedstock volatility:Crude-linked propylene and isocyanate price swings compress formulation margins for domestic polyurethane producers lacking backward integration into basic chemicals.
- Import concentration in specialty silicones:High-performance construction sealants rely on Dow and Wacker supply from Germany and the US, exposing infrastructure projects to currency and freight cost shocks.
- Cure speed limitations in moisture-cured systems:Humidity-dependent curing restricts polyurethane adhesive deployment in arid Rajasthan and Gujarat interior markets during dry seasons.
Strategic Opportunities
- Tier-2 and tier-3 woodworking penetration:Fevicol's distribution model demonstrates latent demand in Madhya Pradesh and Uttar Pradesh furniture clusters currently served by unorganized animal glue suppliers.
- Medical device bonding certification:CDSCO scrutiny of cyanoacrylate and UV-cure systems for surgical instruments creates first-mover advantage for domestic manufacturers achieving ISO 10993 biocompatibility.
- Green building code enforcement:Maharashtra and Tamil Nadu state-level mandates for low-VOC interior materials are specification-forcing water-based systems into public infrastructure procurement.
Industry Challenges
- Polymer chemist talent scarcity:Formulation expertise in reactive hot-melt and UV-cure chemistry concentrates with multinational R&D centers, constraining domestic mid-tier technical service capabilities.
- BIS testing timeline compression:Certification backlog for new water-based construction adhesive formulations delays product launches by 8-14 months against fast-moving project deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Adhesives and Sealants Market |
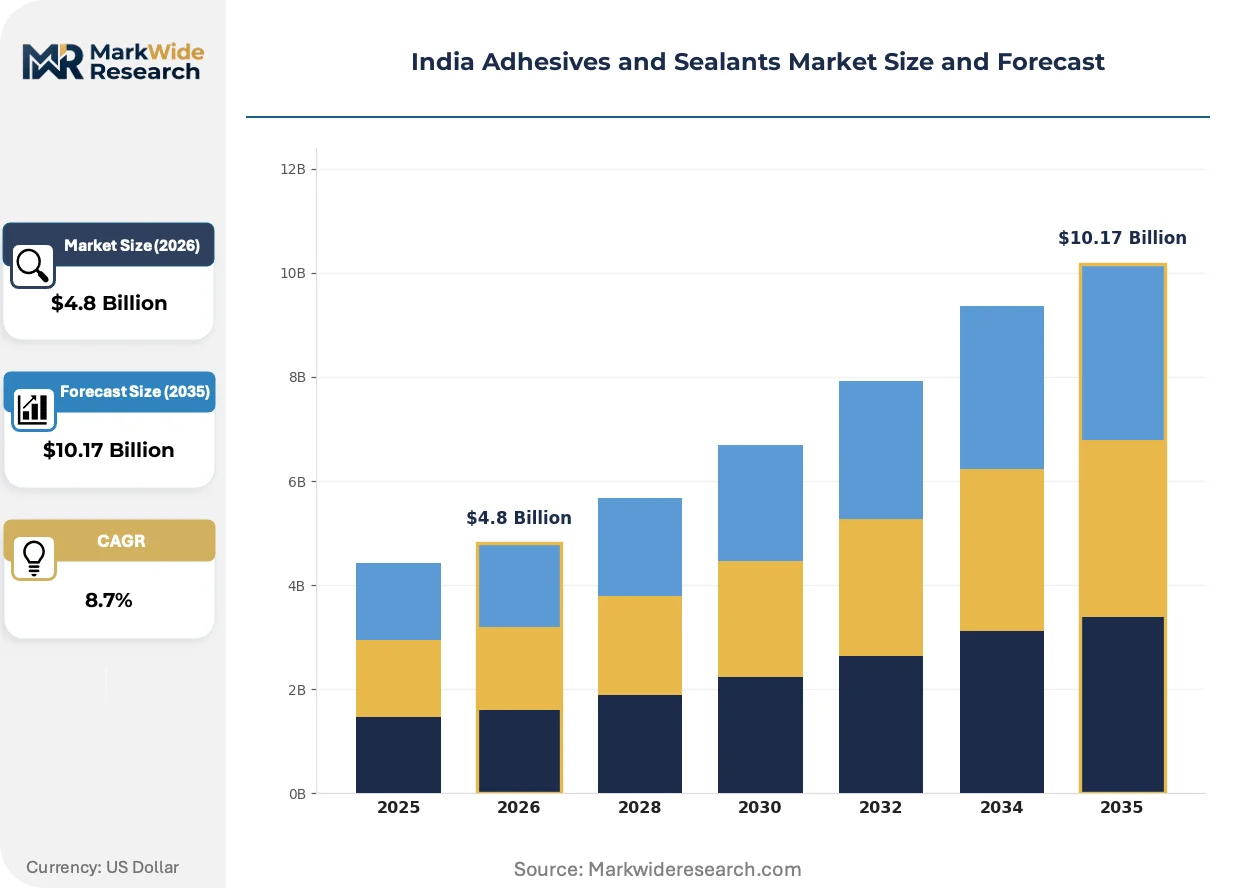
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based, Solvent-Based, Hot Melt, Reactive End User: Construction, Automotive, Electronics, Packaging Application: Woodworking, Bonding, Coating, Surface Treatment Technology: Manual, Automated, Spray, Extrusion |
| Companies Covered | 3M, Dow Inc., Pidilite Industries Limited, HP Adhesives Limited, BASF SE, Henkel Adhesives Technologies India Private Limited, H.B. Fuller Company, Astral Adhesives, Sika AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Adhesives and Sealants Market Shifts & Advancements
Reformulation chemistry, regulatory enforcement mechanics, and procurement digitization are converging to restructure competitive advantage in Indian adhesive supply, favoring manufacturers with integrated testing laboratories and direct OEM technical service relationships.
Hybrid polyurethane-acrylic emulsion technology is hybridizing performance characteristics for woodworking and packaging applications, combining the fast tack of acrylics with the bond strength and water resistance of polyurethanes. Mid-tier furniture manufacturers in Pune and Ahmedabad are piloting these systems at scale. This convergence is hybridizing the traditional segmentation between commodity water-based and premium reactive product lines, compressing price stratification in the industrial maintenance segment.
BIS IS 15495:2019 VOC limits for interior-grade adhesives are tightening enforcement through third-party laboratory audit requirements, forcing solvent-based manufacturers to either reformulate or exit the formaldehyde-emitting plywood lamination market. The construction adhesives segment faces the steepest compliance burden, with Maharashtra state public works departments now requiring BIS certification documentation in tender submissions. Domestic producers are responding by accelerating water-based polyurethane pilot lines in Ankleshwar and Vapi chemical zones.
Direct technical service contracts between adhesive formulators and automotive Tier-1 suppliers are displacing distributor-mediated procurement in chassis and interior assembly applications. Engineers at seating and trim suppliers now specify cure profiles and dispensing equipment jointly with adhesive technical teams, bypassing traditional trading house relationships. This pattern concentrates in Chennai and Pune automotive corridors where just-in-sequence delivery requirements demand real-time viscosity monitoring and lot traceability integration with OEM ERP systems.
India Adhesives and Sealants Market Segmentation
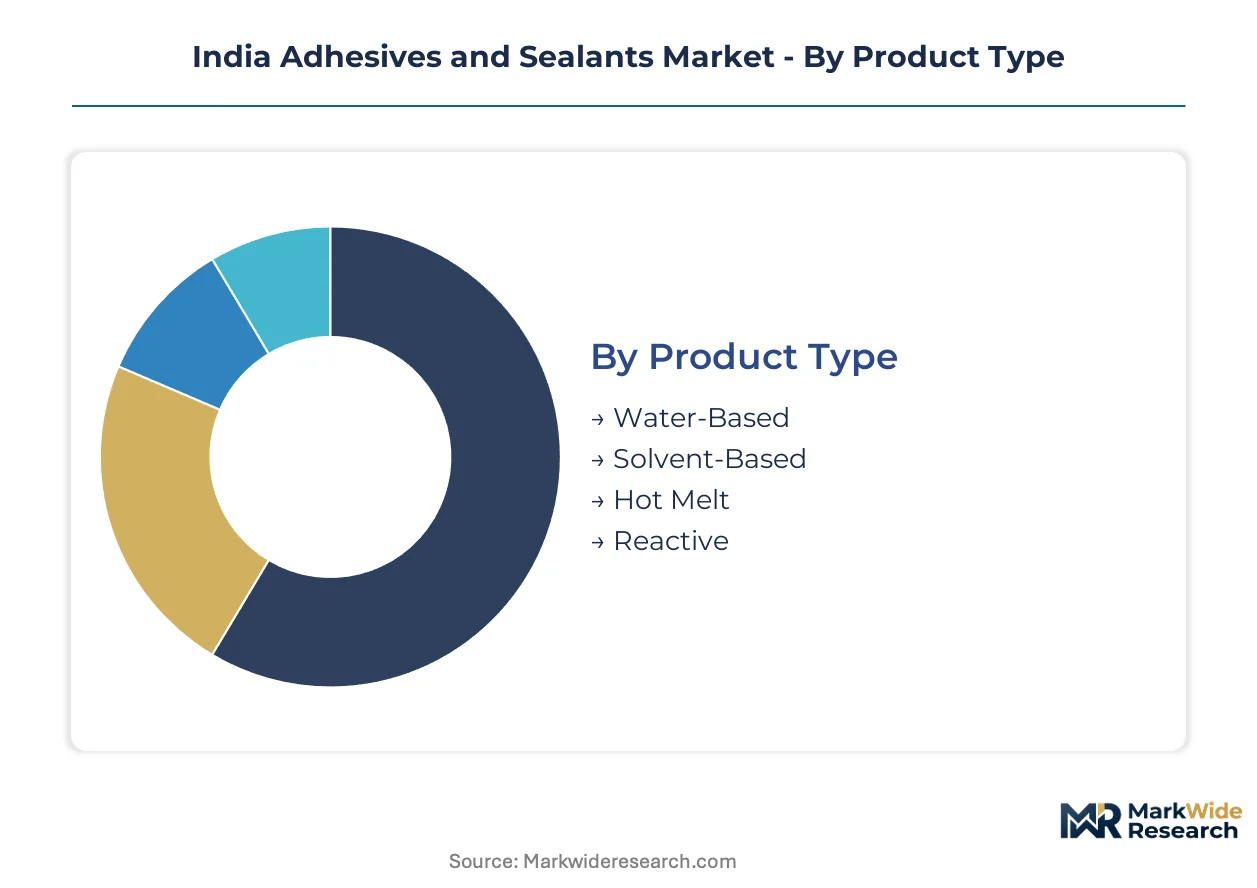
Adhesive procurement in India fragments across formulation chemistry, end-use specifications, and application methods. Each segmentation dimension carries distinct margin structures and regulatory exposure that shape manufacturer portfolio decisions.
Product Type:
Cost tier differentiation separates commodity formulations from specialty reactive systems, with BIS compliance costs acting as a selective filter on viable chemistry platforms.
- Water-Based:Acrylic and polyurethane emulsion systems dominate woodworking and packaging volume. Maharashtra furniture clusters and Gujarat corrugated board plants are specifying these for BIS VOC compliance in interior-grade applications.
- Hot Melt:Ethylene-vinyl acetate and polyolefin formulations cure through thermal cycling without solvent emissions. E-commerce fulfillment centers across western India are displacing tape closures with automated hot-melt carton sealing under tightening emission limits.
- Solvent-Based:Neoprene and SBR rubber solutions retain niche construction penetration where rapid tack and open time are specified, though BIS formaldehyde limits are compressing addressable market scope.
- Reactive:Two-part epoxies and polyurethanes achieve structural bond strengths above 20 MPa for automotive lightweighting and electronics potting applications in Chennai and Pune industrial corridors.
Water-based systems hold installed capacity across Ankleshwar and Vapi chemical zones. Hot melt is rotating up the share rankings in packaging procurement.
End User:
Application maturity varies sharply across customer verticals, with infrastructure and mobility sectors driving specification intensity while consumer packaging emphasizes throughput economics.
- Construction:Structural bonding agents and sealant systems face Maharashtra and Tamil Nadu green building code enforcement for low-VOC interior materials in public infrastructure tenders.
- Automotive:Reactive adhesive systems for chassis, trim, and battery pack assembly are specified by Pune and Chennai OEM clusters demanding thermal cycling resistance and dielectric stability.
- Electronics:UV-cure and cyanoacrylate platforms for PCB potting and component bonding concentrate in Bengaluru and Noida assembly operations.
- Packaging:Pressure-sensitive and hot-melt systems sustain carton sealing and label adhesion across western India conversion hubs serving FMCG distribution networks.
Construction maintains specification authority through BIS certification requirements. Electronics is rotating up the share rankings as domestic device assembly expands.
Application:
Functional purpose determines cure mechanism selection and performance testing protocols, with structural loads demanding validated shear strength versus cosmetic bonding emphasizing aesthetic finish.
- Bonding:Load-bearing adhesive joints in automotive and construction applications require validated tensile shear performance, with Chennai Tier-1 suppliers integrating real-time viscosity monitoring into just-in-sequence delivery systems.
- Woodworking:Plywood lamination and furniture assembly in Madhya Pradesh and Uttar Pradesh clusters are transitioning from animal glue to synthetic emulsion systems under formaldehyde emission scrutiny.
- Coating:Protective adhesive films and barrier layers serve electronics and medical device applications requiring ISO 10993 biocompatibility certification for CDSCO compliance.
- Surface Treatment:Primer and adhesion promoter systems modify substrate energy for challenging bonds in Gujarat automotive painting operations and Maharashtra marine construction.
Bonding commands the steepest performance validation requirements. Woodworking is rotating up the share rankings as unorganized sector formalization accelerates.
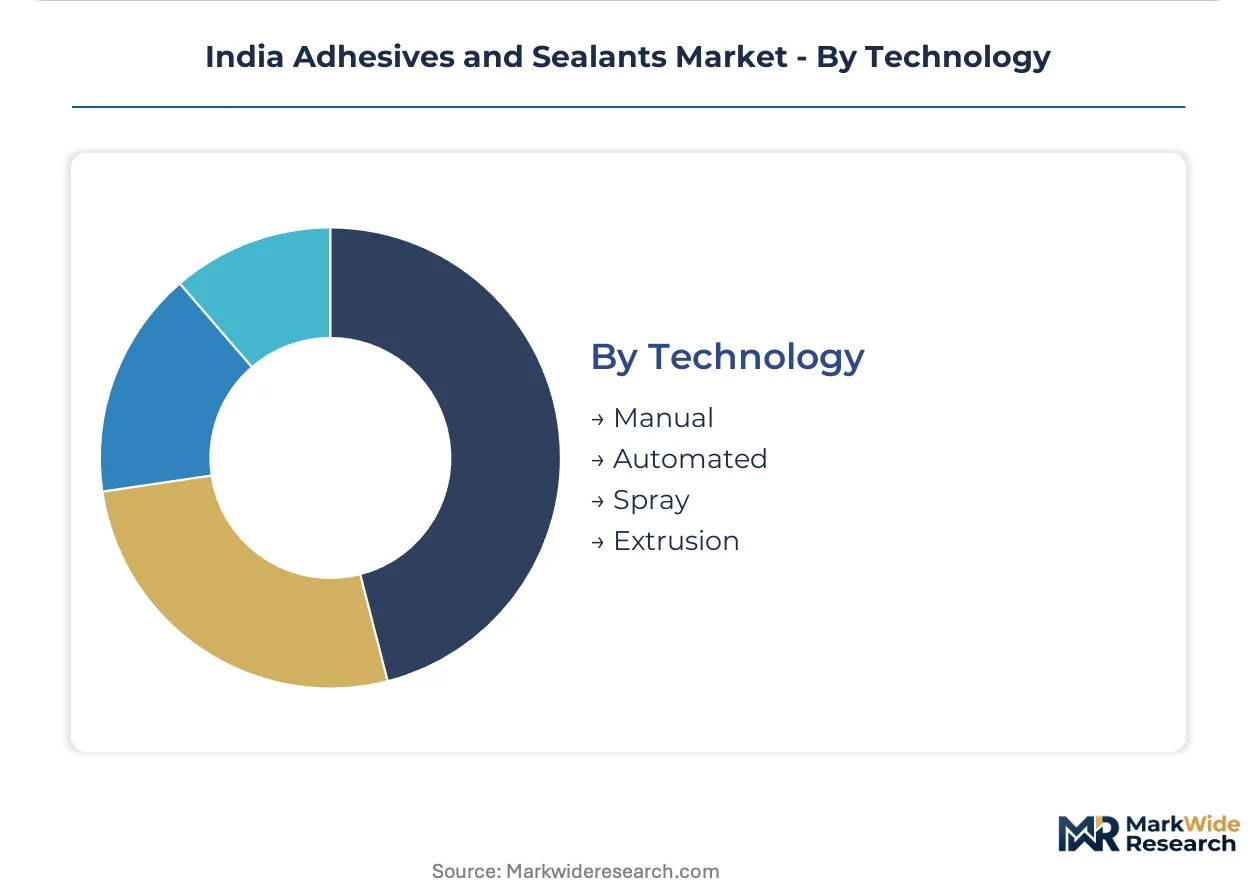
Technology:
Dispensing method selection reflects customer scale and precision requirements, with automation penetration concentrated in OEM direct procurement relationships.
- Automated:Robotic dispensing with closed-loop viscosity control serves Chennai and Pune automotive assembly lines where lot traceability must integrate with OEM ERP systems.
- Manual:Brush and roller application persists in tier-2 woodworking shops and construction sites across Rajasthan and Gujarat interior markets where capital constraints limit equipment investment.
- Spray:Aerosol and pressure-fed coating systems achieve uniform thin-film coverage in electronics conformal coating and large-area construction sealant applications.
- Extrusion:Bead and ribbon deposition of hot-melt and reactive systems supports packaging line speeds and construction joint filling in high-volume western India operations.
Manual application retains volume share in fragmented downstream channels. Automated dispensing is rotating up the share rankings as OEM technical service contracts displace distributor mediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Western India consumes structural bonding agents for automotive and construction applications, while southern states concentrate electronics-grade reactive systems and northern clusters absorb commodity woodworking formulations.
Maharashtra
Pune and Mumbai automotive OEMs specify reactive polyurethane systems for lightweighting chassis and battery pack assemblies. BIS certification requirements for construction adhesives now appear in state public works tender documentation. The Mumbai-Thane industrial corridor hosts expanding water-based polyurethane pilot lines serving green building code compliance.
Gujarat
Ankleshwar and Vapi chemical zones process bulk volumes of hot-melt adhesives for e-commerce packaging fulfillment centers. PLI scheme subsidies for specialty chemicals attract domestic resin synthesis investments. The Ahmedabad-Vadodara belt anchors solvent-to-water-based reformulation capacity under tightening VOC emission limits.
Tamil Nadu
Chennai automotive Tier-1 suppliers integrate automated dispensing systems with real-time viscosity monitoring for just-in-sequence delivery. State-level green building codes mandate low-VOC interior materials in public infrastructure procurement. The Sriperumbudur-Oragadam belt concentrates electronics potting and conformal coating operations.
Karnataka
Bengaluru electronics assembly operations consume UV-cure and cyanoacrylate platforms for PCB bonding and component mounting. CDSCO scrutiny of medical-device bonding agents creates compliance pathways for ISO 10993-certified domestic manufacturers. The Peenya industrial area hosts packaging conversion hubs serving southern FMCG distribution networks.
Uttar Pradesh
Kanpur and Moradabad furniture clusters transition from animal glue to synthetic emulsion systems under formaldehyde emission scrutiny. Unorganized sector formalization accelerates demand for BIS-certified woodworking adhesives. The Noida-Greater Noida corridor absorbs electronics-grade reactive systems from neighboring Delhi-NCR suppliers.
India Adhesives and Sealants Market Competitive Landscape
Capability concentration sits with multinational technology licensors; scale advantage sits with domestic distributors with deep tier-2 and tier-3 penetration. The market structures around three tiers: integrated resin producers with captive monomer supply, formulation specialists serving OEM direct procurement, and trading houses mediating commodity spot volumes. Dominant competitive moves include backward integration into basic chemicals and technical service contracts displacing distributor relationships in automotive corridors.
Within the domestic formulation tier, Pidilite Industries Limited anchors consumer and industrial segments through established distribution architecture. Henkel Adhesives Technologies India Private Limited occupies a position among multinational technology providers competing on automated dispensing integration. Dow Inc. exemplifies the integrated resin producer archetype with high-performance silicone and polyurethane platforms. These three represent distinct capability vectors: distribution density, technical service depth, and materials science integration.
| Leading Market Players |
|---|
| 3M |
| Dow Inc. |
| Pidilite Industries Limited |
| HP Adhesives Limited |
| BASF SE |
| Henkel Adhesives Technologies India Private Limited |
| H.B. Fuller Company |
| Astral Adhesives |
| Sika AG |
| Others |
Supply & Pricing Matrix
Overcapacity in Gujarat and Maharashtra hot-melt adhesive plants is compressing spot pricing for commodity packaging formulations while tightening margins on water-based polyurethane systems. This utilization asymmetry rewards integrated producers with captive resin synthesis and pressures trading houses dependent on imported feedstock.
Pricing Analysis
Long-term offtake contracts dominate procurement between automotive OEMs and reactive adhesive suppliers in Pune and Chennai corridors, insulating these relationships from propylene price volatility. Three-tier pricing structure across premium, standard, and economy levels separates BIS-certified construction sealants from uncertified woodworking emulsions and unbranded animal glue substitutes. Cost compression in solvent-based tiers is intensifying because BIS formaldehyde limits are forcing reformulation investments. Small furniture manufacturers in Uttar Pradesh and Madhya Pradesh exhibit highest price sensitivity, while Tier-1 automotive suppliers prioritize thermal cycling performance over unit cost.
Supply Chain Analysis
Upstream propylene and isocyanate feedstock draws from Saudi Arabia, South Korea, and Singapore, exposing domestic polyurethane producers to freight cost shocks and currency volatility. Acrylic emulsion monomers and specialty silicone precursors rest on Dow and Wacker supply from Germany and the US, creating single-source vulnerability for high-performance construction sealants. Distribution runs through Pidilite's tier-2 and tier-3 network for consumer woodworking adhesives, while direct technical service contracts serve automotive and electronics OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment story where BIS certification timelines and CDSCO medical-device pathways create switching costs that cement incumbent positions. The moat deepens through distribution density and formulation expertise concentration.
For Market Incumbents: Build regulatory-entrenchment moats by accelerating captive resin synthesis investments under PLI scheme subsidies and securing advance BIS certification for water-based construction adhesive portfolios. Capacity addition in Ankleshwar and Vapi chemical zones defends against import substitution. Threats from unorganized animal glue suppliers in northern woodworking clusters require channel control reinforcement through tier-3 distribution expansion. For New Entrants and Emerging Players: Kanpur and Moradabad furniture clusters represent the most penetrable white-space target, where formaldehyde emission scrutiny is displacing unorganized suppliers. Medical-device bonding certification under CDSCO scrutiny offers first-mover advantage for ISO 10993-compliant UV-cure and cyanoacrylate platforms. Go-to-market execution should anchor on direct technical service relationships with automotive Tier-1 suppliers in Chennai and Pune, bypassing distributor mediation. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among formulation specialists serving OEM direct procurement with integrated dispensing equipment and real-time viscosity monitoring services. Long-term viability across the projection horizon favors integrated resin producers with backward integration into basic chemicals. Acquisition targets should emphasize domestic manufacturers achieving BIS certification backlog clearance. The signal to watch is Maharashtra and Tamil Nadu state-level enforcement velocity for green building codes in public infrastructure tenders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Basic Chemicals | PLI scheme subsidies for captive propylene and isocyanate synthesis reduce import dependency for Maharashtra and Gujarat producers. |
| BIS Certification Acceleration | Third-party laboratory audit completion for water-based construction adhesives unlocks Maharashtra public works tender participation. |
| Direct Technical Service Contracts | Automotive Tier-1 suppliers in Chennai and Pune now specify cure profiles jointly with adhesive technical teams. |
| Tier-3 Distribution Expansion | Fevicol's model demonstrates latent demand in Madhya Pradesh and Uttar Pradesh furniture clusters beyond organized retail. |
| Medical-Device Bonding Certification | CDSCO scrutiny of cyanoacrylate systems for surgical instruments creates compliance pathways for ISO 10993-certified domestic manufacturers. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across the analysis window, combining structured interviews with plant managers at Ankleshwar and Vapi chemical zones, procurement leads at Pune and Chennai automotive Tier-1 suppliers, distribution channel partners in tier-2 woodworking markets, and technical R&D directors at multinational formulation centers. Secondary validation drew from BIS certification databases, CDSCO medical-device filings, customs and trade data on propylene and isocyanate imports, and PLI scheme disbursement records. Bottom-up volume estimates from end-use consumption patterns were triangulated against top-down capacity assessments from chemical zone regulatory filings.
Calibration against historical BIS standard revision timelines and state-level green building code adoption curves anchored the projection framework. Segmentation dimensions modeled include formulation chemistry, end-use vertical, application method, and regional production hub. CAGRs were derived from elasticity-adjusted demand curves incorporating automotive lightweighting content-per-vehicle trajectories and e-commerce packaging fulfillment center expansion rates. Industry-specific inputs encompassed PLI scheme subsidy disbursement velocity and CDSCO medical-device approval pathway timelines.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Saudi and Singaporean petrochemical exporters would shift outcomes through feedstock price compression. Cross-checking against BIS certification backlog clearance rates and Maharashtra public works tender award volumes is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Dural Sealant Market
Adhesives & Sealants
Anaerobic Adhesives and Sealants Market
Adhesives & Sealants
Polyurethane (PU) Adhesives Market
Adhesives & Sealants
South Africa Sealants Market
Adhesives & Sealants
France Sealants Market
Adhesives & Sealants
Tile Adhesive Market
Adhesives & Sealants
Construction Adhesives and Sealants Chemical Market
Adhesives & Sealants
North America & Europe Adhesives and Sealants Market
Adhesives & Sealants
Die Attach Materials Market
Adhesives & Sealants
Asia-Pacific Electronics Adhesives Market
Adhesives & Sealants
Global Contact Adhesives Market
Adhesives & Sealants
Heat Resistant Sealant Market
Adhesives & Sealants
Saudi Arabia Sealants Market
Adhesives & Sealants
North America Adhesives and Sealants Market
Adhesives & Sealants
Global Construction Adhesive Tapes Market
Adhesives & Sealants
Adhesive Primer Market