
 Global Chlorinated Polyethylene Market | 2026-2036
Global Chlorinated Polyethylene Market Size, Share, and Industry Trends Forecast 2026-2036
Global Chlorinated Polyethylene Market Foresight
Multi-source procurement for chlorinated polyethylene resin is rebalancing toward regional supply bases as freight volatility and tariff exposure reshape compounder strategies. Dow leverages its integrated chlor-alkali footprint to sustain cost-advantaged CPE production across North American wire and cable accounts. Shandong Gaoxin Chemical anchors its position through captive chlorine sourcing and dedicated resin lines serving domestic impact modifier demand. Resonac Holdings Corporation differentiates via high-purity CPE grades aligned to Japanese electrical standards.
Chlorinated polyethylene is a thermoplastic elastomer produced by chlorinating high-density polyethylene, typically achieving chlorine content between 25% and 40% by weight to balance rubber-like flexibility with polyolefin processability. The material functions primarily as an impact modifier for rigid PVC and as a base polymer for wire jacketing requiring oil resistance and flame retardancy. CPE resin commands the largest volume share within product type segmentation, though CPE masterbatch is gaining traction among compounders seeking reduced dust exposure and tighter dispersion control in extrusion operations. Wire and cable insulation leads application segmentation by value, while elastomer modifiers represent the fastest-growing category as automotive coolant hose specifications tighten.
China's SAMR enforces GB standards governing halogen content and smoke density in building wire applications, directly influencing CPE formulation choices for domestic electrical accounts. REACH registration requirements in Europe constrain import volumes of unregistered CPE grades, channeling demand toward established EU-located compounders with full substance dossiers. EPA TSCA Section 5 scrutiny on new chlorinated polymer variants adds compliance lead time for innovators targeting US industrial rubber segments. Stakeholders must monitor how China's dual carbon goals reshape chlorine electrolysis economics and thus CPE resin feedstock availability.
Market Dynamics
Chlorinated polyethylene demand pivots on chlorine feedstock economics and regional electrolysis capacity, with China's dual carbon goals compressing chlor-alkali output and redirecting resin supply chains toward Middle Eastern and US Gulf Coast chlorine sources.
Growth Catalysts
- Automotive coolant hose specifications:Tighter elastomer performance standards in powertrain thermal management are pulling CPE into hose compound formulations as a primary base polymer.
- GB standards on halogen-free flame retardancy:China's SAMR mandates on building wire smoke density are forcing domestic electrical compounders toward CPE-modified PVC systems.
- Wire harness electrification:Utility grid hardening and EV platform voltage escalation are expanding oil-resistant jacketing demand across automotive and infrastructure cable accounts.
Market Restraints
- Chlorine feedstock volatility:European chlor-alkali curtailments under EU ETS carbon pricing have destabilized CPE resin cost structures for continental compounders.
- REACH registration barriers:Unregistered CPE grades face exclusion from EU industrial rubber segments, channeling volume toward established registrants with full substance dossiers.
- Thermoplastic polyurethane substitution:TPU elastomers are capturing select wire jacketing applications where abrasion resistance and flex fatigue performance outweigh CPE cost advantages.
Strategic Opportunities
- Indian electrical infrastructure buildout:BIS certification pathways for halogenated cable compounds remain underdeveloped, creating first-mover positioning for CPE-registered suppliers.
- CPE masterbatch format expansion:Dust-reduced pelletized concentrates are opening specification doors among Japanese automotive wire harness compounders seeking cleaner extrusion floors.
- US IRA domestic content incentives:Utility-scale solar and EV charging infrastructure procurement rules are favoring North American-sourced wire insulation polymers.
Industry Challenges
- Chlor-alkali process engineering expertise:CPE resin production requires specialized membrane cell operation skills that are concentrating among legacy chlor-alkali operators.
- EPA TSCA Section 5 compliance timelines:New chlorinated polymer variant introductions face extended pre-manufacture notification review periods, delaying formulation innovation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Chlorinated Polyethylene Market |
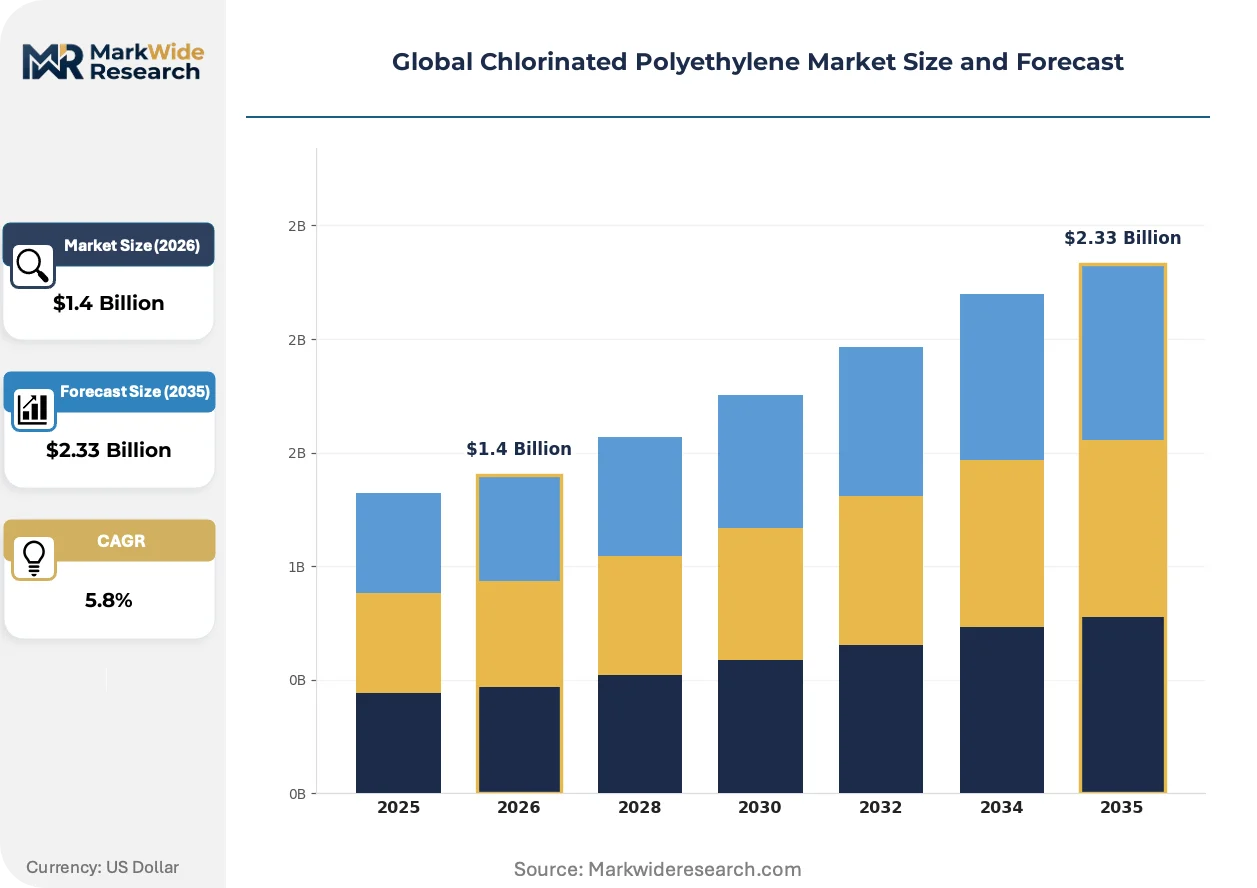
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.33 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
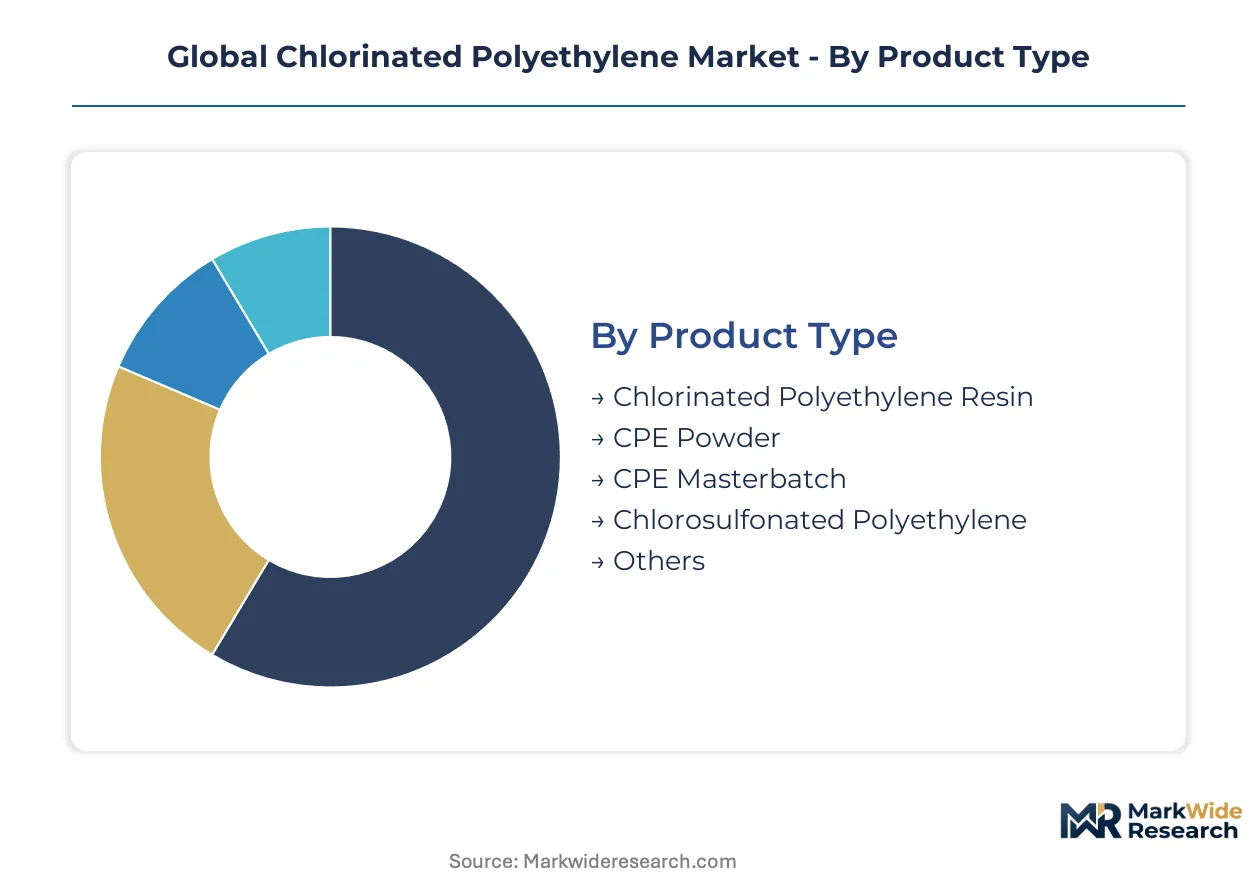
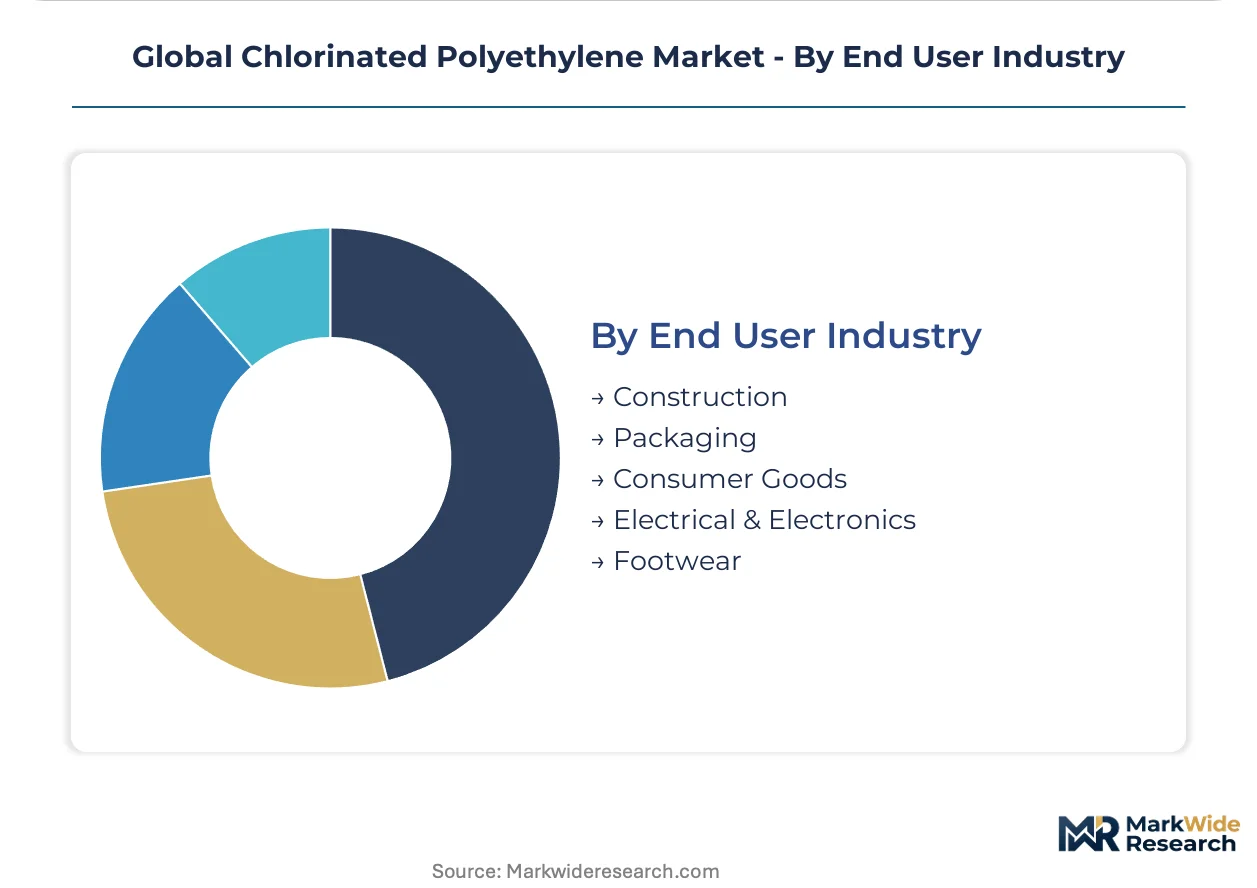
| Segmentation | Product Type: Chlorinated Polyethylene Resin, CPE Powder, CPE Masterbatch, Chlorosulfonated Polyethylene, Others Form: Powder, Granules, Pellets, Flakes Application: Wire & Cable Insulation, Elastomer Modifiers, Impact Modifiers, Adhesives & Sealants, Coatings End User Industry: Construction, Packaging, Consumer Goods, Electrical & Electronics, Footwear |
| Companies Covered | Weifang Yaxing Chemical Co. Ltd., Shandong Gaoxin Chemical Co. Ltd., Dow, Hangzhou Keli Chemical Co. Ltd., Jiangsu Tianteng Chemical Industry Co. Ltd., Resonac Holdings Corporation, Sundow Polymers Co. Ltd., Aurora Plastics LLC, Showa Denko K.K., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Chlorinated Polyethylene Market Shifts & Advancements
Chlorinated polyethylene compound development is pivoting toward dispersion efficiency and regulatory pre-certification as wire and cable accounts consolidate supplier bases and automotive OEMs tighten material qualification windows.
High-shear CPE masterbatch production is electrifying compounder extrusion economics by eliminating powder handling infrastructure and reducing dispersion variability in multi-layer cable constructions. Tier-1 automotive harness suppliers in Germany and Japan are adopting these concentrates for just-in-time compound delivery. The format shift is compressing minimum order quantities and enabling toll-compounding relationships that bypass traditional resin merchant channels.
REACH Annex XVII restrictions on persistent organic pollutants are forcing European CPE compounders to document chlorine sourcing chain-of-custody and byproduct speciation. ECHA guidance on chlorinated polymer environmental fate is elevating analytical testing burdens for import-dependent compounders. The regulatory pressure is accelerating registration dossier investments among established EU-located resin producers while marginalizing unregistered Asian export grades.
Compounders are consolidating resin procurement around qualified supplier lists as automotive OEMs compress material approval cycles from 18 months to 9 months for platform launches. Direct mill relationships are displacing distributor intermediaries for volume wire and cable accounts in the US Midwest and East China chemical corridors. The channel compression is most visible among utility cable manufacturers seeking single-source accountability for flame-retardant performance certification.
Global Chlorinated Polyethylene Market Segmentation
Chlorinated polyethylene procurement decisions hinge on chlorine content precision, dispersion efficiency, and regulatory pre-certification status across wire harness and PVC compounding accounts. Compounders segment demand by technical specification depth rather than commodity grade availability, with automotive OEMs imposing tighter qualification windows than construction material distributors.
Product Type:
Buyers prioritize chlorine content consistency and REACH dossier completeness when selecting resin formats for regulated electrical applications.
- Chlorinated Polyethylene Resin:Base polymer grades with 25-40% chlorine content by weight deliver balanced rubber-like flexibility and polyolefin processability. Wire and cable manufacturers in Germany and Japan specify these resins for oil-resistant jacketing in EV platform harnesses, with SAMR GB standards on halogen-free flame retardancy redirecting Chinese domestic formulation strategies.
- CPE Masterbatch:High-shear pelletized concentrates eliminate powder handling infrastructure and reduce dispersion variability in multi-layer cable constructions. Tier-1 automotive harness suppliers adopt these formats for just-in-time compound delivery, compressing minimum order quantities and enabling toll-compounding relationships.
- CPE Powder:Standard pulverized grades serve rigid PVC impact modification where dust exposure controls are already installed.
- Chlorosulfonated Polyethylene:Sulfonated variants command specification in offshore cable sheathing requiring enhanced ozone resistance.
- Others:Specialty chlorinated polyolefins address niche adhesive formulations in industrial tape applications.
CPE Resin leads on scale; CPE Masterbatch leads on momentum.
Form:
Extrusion floor cleanliness requirements and bulk handling economics determine format selection across compounder facility types.
- Powder:Fine particulate grades dominate legacy PVC compounding operations with established dust collection infrastructure. Construction material producers in East China chemical corridors continue specifying powder for cost-optimized rigid PVC impact modification.
- Pellets:Dust-reduced spherical formats open specification doors among Japanese automotive wire harness compounders seeking cleaner extrusion floors and tighter dispersion control.
- Granules:Intermediate sizing serves mid-volume compounders balancing handling efficiency with melt processing uniformity.
- Flakes:Thin compressed sheets facilitate rapid dissolution in solvent-based adhesive formulations.
Powder maintains volume dominance; Pellets are climbing the fastest on regulatory pressure.
Application:
Performance certification requirements and flame-retardant specification depth differentiate application-tier profitability.
- Wire & Cable Insulation:Oil-resistant jacketing compounds for utility grid hardening and EV platform voltage escalation. US IRA domestic content incentives favor North American-sourced insulation polymers for utility-scale solar and charging infrastructure procurement.
- Elastomer Modifiers:Base polymer functions in automotive coolant hose compounds as powertrain thermal management specifications tighten. TPU substitution pressure in select abrasion-critical applications constrains expansion in premium wire jacketing.
- Impact Modifiers:Primary function for rigid PVC window profile and siding durability across construction cycles.
- Adhesives & Sealants:Chlorinated polyolefin tackifiers bond low-surface-energy substrates in automotive assembly.
- Coatings:Corrosion-resistant industrial finishes protect chemical processing equipment in chlor-alkali plant environments.
Wire & Cable Insulation leads on scale; Elastomer Modifiers lead on momentum.
End User Industry:
Regulatory exposure intensity and material qualification cycle length shape industry-specific pricing tolerance.
- Electrical & Electronics:Building wire and automotive harness accounts consolidate supplier bases around qualified lists as OEMs compress material approval cycles from 18 months to 9 months. REACH Annex XVII restrictions on persistent organic pollutants force documentation of chlorine sourcing chain-of-custody.
- Construction:Rigid PVC compounding for window profiles and siding drives volume demand, with Indian electrical infrastructure buildout creating first-mover positioning for BIS-registered halogenated cable compound suppliers.
- Automotive:Coolant hose and wire jacketing specifications pull CPE into thermal management and electrification platforms.
- Packaging:Limited penetration in film modification where clarity requirements favor alternative elastomers.
- Consumer Goods:Occasional specification in flexible household product components.
- Footwear:Niche adoption in industrial safety boot soling compounds.
Electrical & Electronics leads on scale; Construction leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Weifang and Hangzhou chemical corridors anchor global chlorinated polyethylene resin capacity, with East China compounders serving domestic wire harness and PVC impact modifier demand under tightening environmental compliance mandates.
China
Weifang and Hangzhou chemical corridors concentrate domestic CPE resin capacity serving wire harness and rigid PVC modifier demand. SAMR enforces GB standards on halogen-free flame retardancy and smoke density in building wire applications. Shandong and Zhejiang province compounders are redirecting formulation strategies toward compliant CPE-modified PVC systems for electrical accounts.
United States
Utility grid hardening and EV platform voltage escalation drive oil-resistant jacketing demand across automotive and infrastructure cable accounts. EPA TSCA Section 5 scrutiny adds compliance lead time for new chlorinated polymer variants targeting industrial rubber segments. US Gulf Coast chlorine sources are gaining traction as freight volatility reshapes compounder procurement strategies.
Germany
Tier-1 automotive harness suppliers adopt high-shear CPE masterbatch formats for just-in-time compound delivery and cleaner extrusion floors. REACH Annex XVII restrictions on persistent organic pollutants force documentation of chlorine sourcing chain-of-custody. ECHA guidance elevates analytical testing burdens for import-dependent compounders across the Rhine-Ruhr industrial region.
Japan
Japanese electrical standards drive specification for high-purity CPE grades in automotive wire harness and coolant hose applications. METI oversees industrial chemical compliance frameworks affecting chlorinated polymer import and formulation. Resonac Holdings Corporation and Showa Denko K.K. anchor domestic supply positioning through specialized resin production.
India
BIS certification pathways for halogenated cable compounds remain underdeveloped, creating first-mover positioning for CPE-registered suppliers. CEA mandates on electrical infrastructure safety influence material selection for utility-scale projects. Maharashtra and Gujarat industrial corridors are emerging as procurement destinations for construction and electrical compounders.
Global Chlorinated Polyethylene Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue masterbatch format specialization and toll-compounding partnerships. The vendor base clusters around integrated chlor-alkali operators and regional compounders with captive chlorine sourcing. Three archetypes dominate: membrane cell-integrated resin producers, dispersion-optimized masterbatch specialists, and regional toll compounders serving automotive wire harness accounts. Capacity expansion and REACH dossier investment represent the dominant competitive moves as regulatory barriers harden.
Within the integrated producer tier, Dow exemplifies membrane cell-anchored positioning across North American wire and cable accounts. Shandong Gaoxin Chemical Co. Ltd. and Weifang Yaxing Chemical Co. Ltd. represent Chinese resin specialists with captive chlorine sourcing and dedicated lines serving domestic impact modifier demand. Resonac Holdings Corporation occupies a position aligned to Japanese electrical standards and high-purity grade specifications.
| Leading Market Players |
|---|
| Weifang Yaxing Chemical Co. Ltd. |
| Shandong Gaoxin Chemical Co. Ltd. |
| Dow |
| Hangzhou Keli Chemical Co. Ltd. |
| Jiangsu Tianteng Chemical Industry Co. Ltd. |
| Resonac Holdings Corporation |
| Sundow Polymers Co. Ltd. |
| Aurora Plastics LLC |
| Showa Denko K.K. |
| Others |
Supply & Pricing Matrix
China's dual carbon goals gating chlor-alkali capacity expansion have bifurcated the CPE market into REACH-registered premium supply and unregistered spot-grade alternatives, with compounders paying tiered access premiums for qualified resin streams serving automotive wire harness accounts.
Pricing Analysis
Chlorine feedstock pass-through from membrane cell electrolysis operations dominates CPE resin pricing structures, with European compounders absorbing carbon pricing surcharges under EU ETS that widen spreads against US Gulf Coast and Middle Eastern supply. Three-tier pricing structure across high-purity automotive grades, standard wire and cable resins, and unregistered powder modifiers captures differentiation through REACH dossier completeness and chlorine content precision. Cost compression in standard-grade CPE is intensifying as Shandong and Zhejiang producers expand captive chlorine capacity. Construction material distributors exhibit highest price sensitivity due to specification flexibility, while Tier-1 automotive harness suppliers prioritize qualification security over unit cost.
Supply Chain Analysis
Membrane cell engineering expertise shortages in Weifang, Hangzhou, and the US Gulf Coast chemical corridors are concentrating qualified CPE resin production among legacy chlor-alkali operators with captive chlorine sourcing. Feedstock dependencies span high-density polyethylene resin, liquid chlorine, and hydrochloric acid for chlorination control. Single-source vulnerability characterizes East China supply concentration, where environmental compliance inspections periodically interrupt resin output. Distribution runs through direct mill relationships displacing distributor intermediaries for volume wire and cable accounts, with toll-compounding partnerships emerging as an alternative channel for masterbatch formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in chlorinated polyethylene hinges on upstream chlorine cost control and masterbatch format premiumization, with integrated producers capturing spread widening as regulatory barriers harden against unregistered import competition.
For Market Incumbents: Acquire membrane cell chlor-alkali assets in North America or the Middle East to secure cost-advantaged chlorine feedstock against European carbon pricing exposure. Deepen REACH dossier investments to defend registered-grade pricing premiums against emerging Indian and Southeast Asian compounders seeking EU market access. Prioritize masterbatch production line expansion to capture automotive specification shifts toward dust-reduced pellet formats. For New Entrants and Emerging Players: Enter via BIS certification pathways for halogenated cable compounds in Maharashtra and Gujarat industrial corridors, where electrical infrastructure buildout outpaces domestic CPE supply. Target Indian utility-scale solar and grid hardening projects seeking qualified insulation polymer suppliers. Pursue toll-compounding partnerships with established resin producers to bypass capital-intensive membrane cell investments. For Investors and Strategic Acquirers: Roll-up economics work for regional CPE compounders with captive chlorine sourcing and automotive qualification history because regulatory barriers and OEM consolidation are compressing viable supplier counts to single-digit levels. Five-to-ten-year viability favors integrated producers with backward control over chlor-alkali feedstock. Watch for EPA TSCA Section 5 pre-manufacture notification approvals as signal of formulation innovation cycles resuming.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlor-Alkali | Dow and Shandong Gaoxin anchor cost positions through captive chlorine membrane cell operations. |
| REACH Dossier Investment | Resonac Holdings and EU-located compounders secure registered-grade premium access against unregistered Asian exports. |
| Masterbatch Format Expansion | High-shear pellet production opens Japanese automotive harness specifications demanding cleaner extrusion floors. |
| Long-term Supply Agreement | Utility cable manufacturers consolidate procurement around single-source accountability for flame-retardant certification. |
| Joint Venture | Toll-compounding partnerships enable regional entrants to serve automotive wire accounts without resin production assets. |
Research Methodology
Multiple input streams — technical interviews with chlor-alkali plant managers and wire compound procurement leads, customs and trade flow databases, and SEC 10-K chemical segment disclosures — were reconciled through bottom-up resin capacity modeling and top-down end-use demand estimation across the analysis window.
Historical production and trade volumes were cross-referenced against panel input from membrane cell operators and automotive harness Tier-1 suppliers to derive segment-specific growth trajectories. The forecast framework models chlorine content tiers, wire and cable versus elastomer modifier applications, and regional production hub clusters. CAGRs were computed from reconciled volume and value outputs. Key inputs include SAMR GB standard implementation timelines and EPA TSCA Section 5 review period assumptions.
Inputs from ECHA registration databases and Indian BIS certification records were available through the study window; gaps in Chinese provincial environmental inspection reporting introduce uncertainty bands around East China capacity utilization assumptions. Forecasts reflect documented assumptions regarding chlorine electrolysis economics and automotive OEM qualification cycle compression. Material deviation in EPA pre-manufacture notification timelines or EU ETS carbon price trajectories warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Asia-Pacific Polyvinylpyrrolidone (PVP) Market
Polymers & Resins
Global Polyol and Polyurethane Market
Polymers & Resins
Resorbable Polymers Market
Polymers & Resins
South America Polymer Emulsion Market
Polymers & Resins
Synthetic and Bio Emulsion Polymers Market
Polymers & Resins
Global Alkyd Resin Market
Polymers & Resins
Thermoplastics Market
Polymers & Resins
Asia-Pacific Geopolymer Market
Polymers & Resins
Global Polyethylene (PE) Foam Market
Polymers & Resins
Polybutylene Succinate (PBS) Market
Polymers & Resins
Polymer Colloids Market
Polymers & Resins
Copolyesters Market
Polymers & Resins
Neoprene Market
Polymers & Resins
US Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
North America Polyvinylpyrrolidone (PVP) Market
Polymers & Resins
EVA Copolymer Market