
 Chlorella Market | 2026-2036
Chlorella Market Size, Share, and Industry Trends Forecast 2026-2036
Chlorella Market Intelligence
The customer base for chlorella is broadening from large-scale supplement manufacturers to include a wider array of niche nutraceutical and functional food brands. Sun Chlorella Corp leverages its strong brand recognition and direct-to-consumer channels. Taiwan Chlorella Manufacturing Company operates with significant production scale, supplying bulk ingredients globally. E.I.D. Parry (India) Limited positions itself as a diversified producer within the broader microalgae sector.
Chlorella is a genus of single-celled green algae cultivated in freshwater ponds for its dense nutritional content. Its commercial viability often requires processing to break the tough outer cell wall, a step critical for human digestibility. Powder and tablet forms command the market, primarily serving the dietary supplements application. While supplements constitute the core value segment, the animal feed application is expanding as a high-volume outlet for chlorella biomass.
Market access is governed by food safety authorities like the US Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA). These bodies review safety data and regulate health claims, influencing consumer trust and product positioning. Stakeholder success will depend on investments in strain optimization and cultivation technologies to improve yields and nutrient profiles.
Market Dynamics
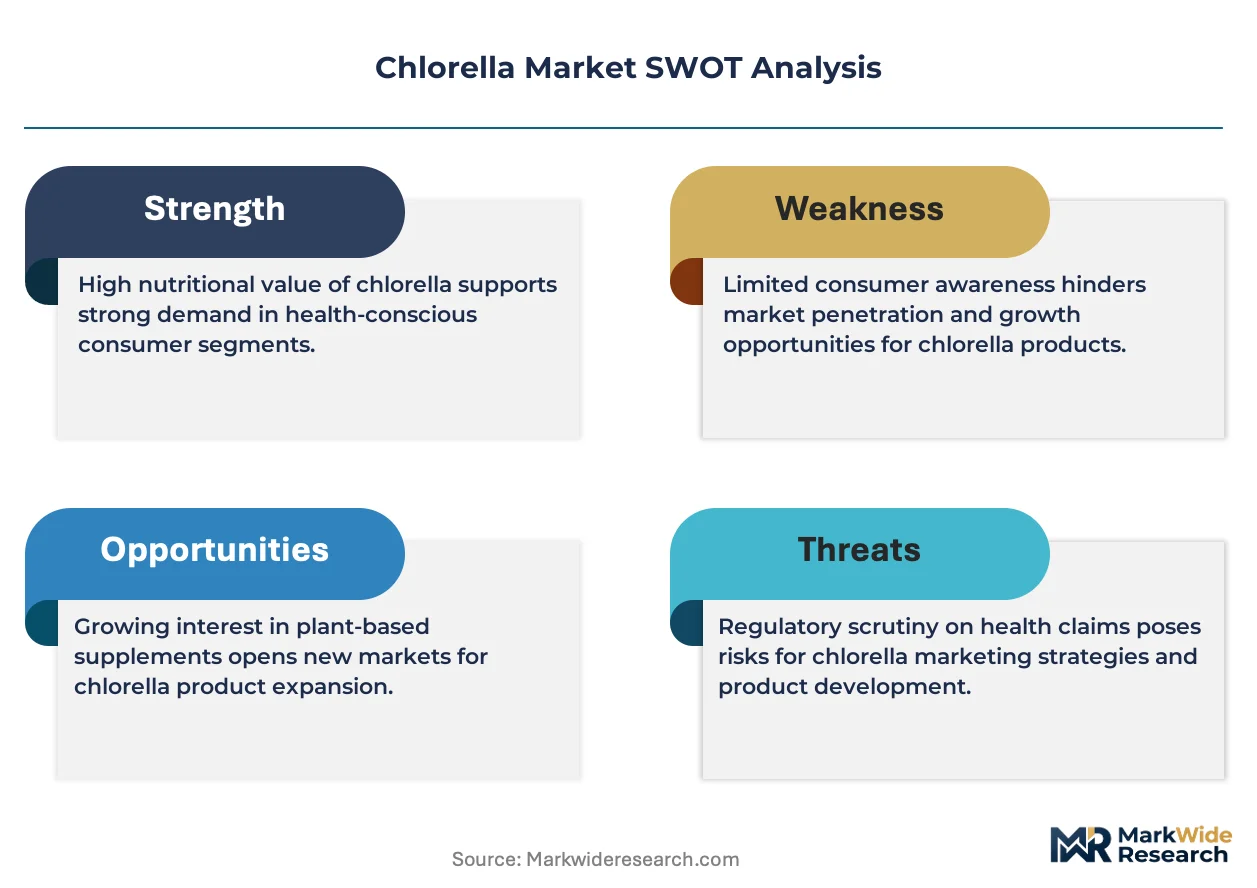
The central force shaping the chlorella market is the convergence of consumer demand for plant-based nutrition with the industrial challenge of achieving consistent, bioavailable, and cost-effective production at scale, all under increasing regulatory scrutiny over health claims.
Growth Catalysts
- Plant-Based Protein Demand:The sustained consumer shift toward vegan and vegetarian diets, particularly in North America and Europe, creates a primary demand pull for chlorella as a nutrient-dense, whole-food ingredient in supplements and functional foods.
- Regulatory Clearances:The FDA's issuance of Generally Recognized as Safe (GRAS) notices for specific chlorella ingredients provides a clear pathway for inclusion in food and beverage products in the United States, boosting formulator confidence.
- Aquaculture Feed Application:Expansion into aquaculture is creating a high-volume demand stream, where chlorella serves as a sustainable feed ingredient that improves growth rates and disease resistance in fish and shrimp farming operations.
Market Restraints
- High Production Costs:The cultivation, harvesting, and essential cell-wall-breaking processing steps are energy and capital-intensive, leading to a high unit cost that can limit its use in price-sensitive food and feed applications.
- Substitution from Spirulina:Spirulina, another microalga, presents a significant substitution threat due to its similar nutritional profile, lower production costs, and established presence in the dietary supplement market, creating direct competition.
- Strict Health Claim Regulations:In the European Union, the European Food Safety Authority (EFSA) maintains a stringent process for approving health claims, which restricts marketing language and can limit the perceived value proposition for consumers.
Strategic Opportunities
- Functional Beverage Fortification:There is a significant opportunity to incorporate chlorella into functional beverages like smoothies, green juices, and plant-based milks, capitalizing on consumer interest in convenient, nutrient-dense products.
- Strain Optimization through Biotechnology:Investment in genetic engineering and selective breeding can develop new chlorella strains with higher yields, enhanced nutrient profiles like increased protein or omega-3 content, or improved digestibility.
- Geographic Expansion in Latin America:Markets such as Brazil and Mexico represent underpenetrated regions where a growing middle class and increasing health consciousness offer new growth potential for chlorella supplement and food brands.
Industry Challenges
- Quality and Purity Standardization:A lack of universally accepted standards for chlorella purity, heavy metal content, and nutrient levels creates inconsistency across suppliers, posing a challenge for brands that require uniform ingredient specifications.
- Contamination Management in Open Ponds:Cultivation in open pond systems, while cost-effective, is vulnerable to contamination from other microorganisms and environmental pollutants, demanding rigorous and costly quality control protocols to ensure product safety.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chlorella Market |
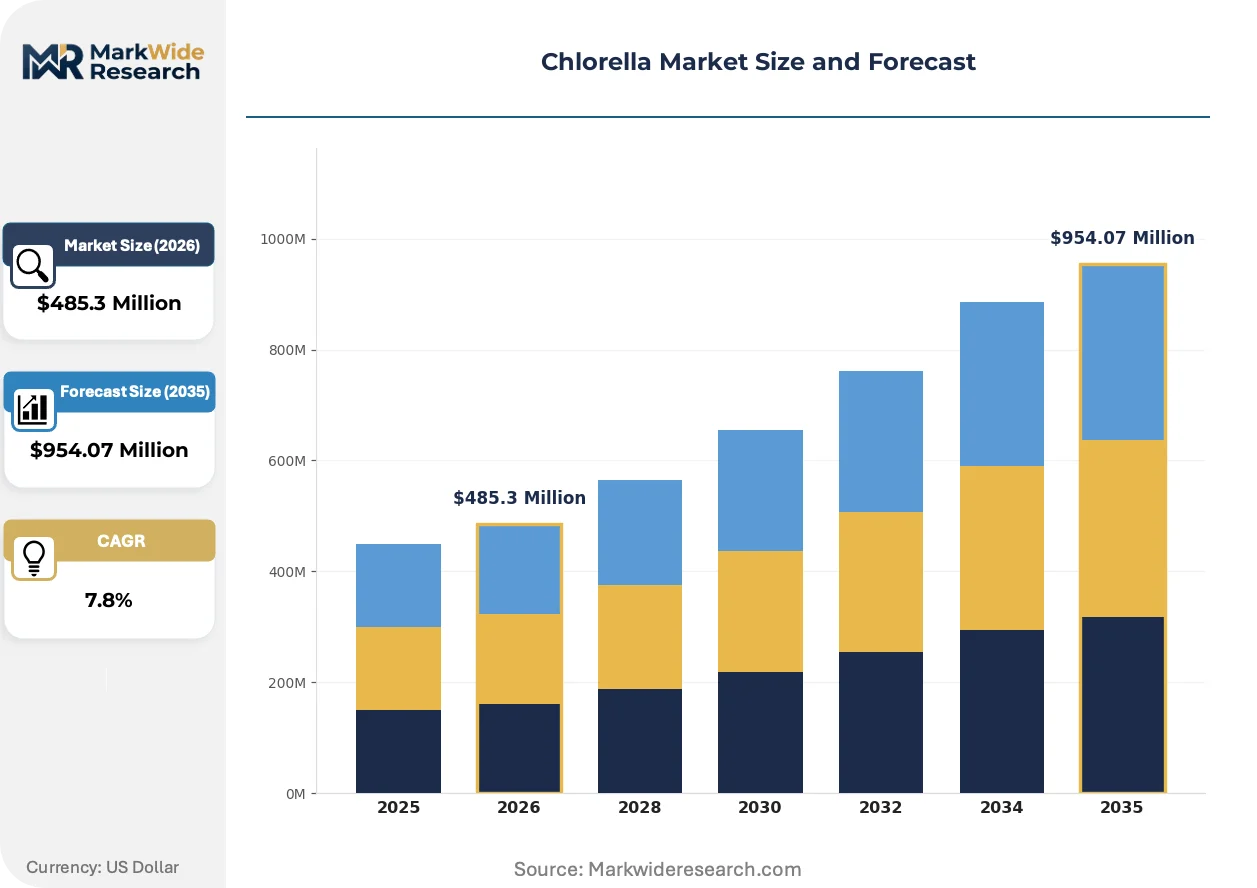
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $954.07 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Powder, Capsules, Extracts Application: Dietary Supplements, Animal Feed, Cosmetics, Fertilizers End User: Nutritionists, Pet Food Manufacturers, Skincare Brands, Agricultural Firms Distribution Channel: Pharmacies, Online Retailers, Health Food Stores, Direct Sales |
| Companies Covered | E.I.D. Parry (India) Limited, Yaeyama Chlorella, Sun Chlorella Corp, Tianjin Norland Biotech Co. Ltd, Fuqing King Dnarmsa Spirulina Co. Ltd, Phycom BV, Taiwan Chlorella Manufacturing Company, International Chlorella, Aliga Microalgae, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chlorella Market Strategic Shifts & Innovations
The market's evolution reflects a shift from a niche health supplement to a standardized functional ingredient platform. This transition is driven by processing innovations that improve bioavailability, evolving regulatory frameworks for novel foods, and more sophisticated, specification-based procurement from buyers.
Advanced cell-wall disruption technologies, such as enzymatic hydrolysis and high-pressure jet spraying, are becoming critical for product efficacy. Nutraceutical and functional food manufacturers are the primary adopters, seeking to guarantee the digestibility and nutrient accessibility of the chlorella in their final products. This technological shift is absorbing the historical bioavailability challenges, enabling formulators to use chlorella more reliably in complex products like protein bars and ready-to-drink beverages.
Europe's Novel Food Regulation (Regulation (EU) 2015/2283) establishes a rigorous pre-market safety assessment for new food ingredients, including novel strains or extracts of chlorella. This framework creates a significant compliance hurdle, favoring established producers who possess the capital and data required for an EFSA submission. The dietary supplements segment is most impacted, with suppliers investing heavily in toxicological studies to secure market access within the EU.
A notable demand-side shift is occurring from purchasing undifferentiated bulk powder to sourcing certified grades of chlorella based on specific attributes. This disrupts the commodity-driven model, as procurement now prioritizes factors like organic certification under USDA or EU rules, or verified levels of Chlorella Growth Factor (CGF). This trend is most visible in the North American and Japanese health food markets, where ingredient transparency is a primary purchasing driver.
Chlorella Market Segmentation
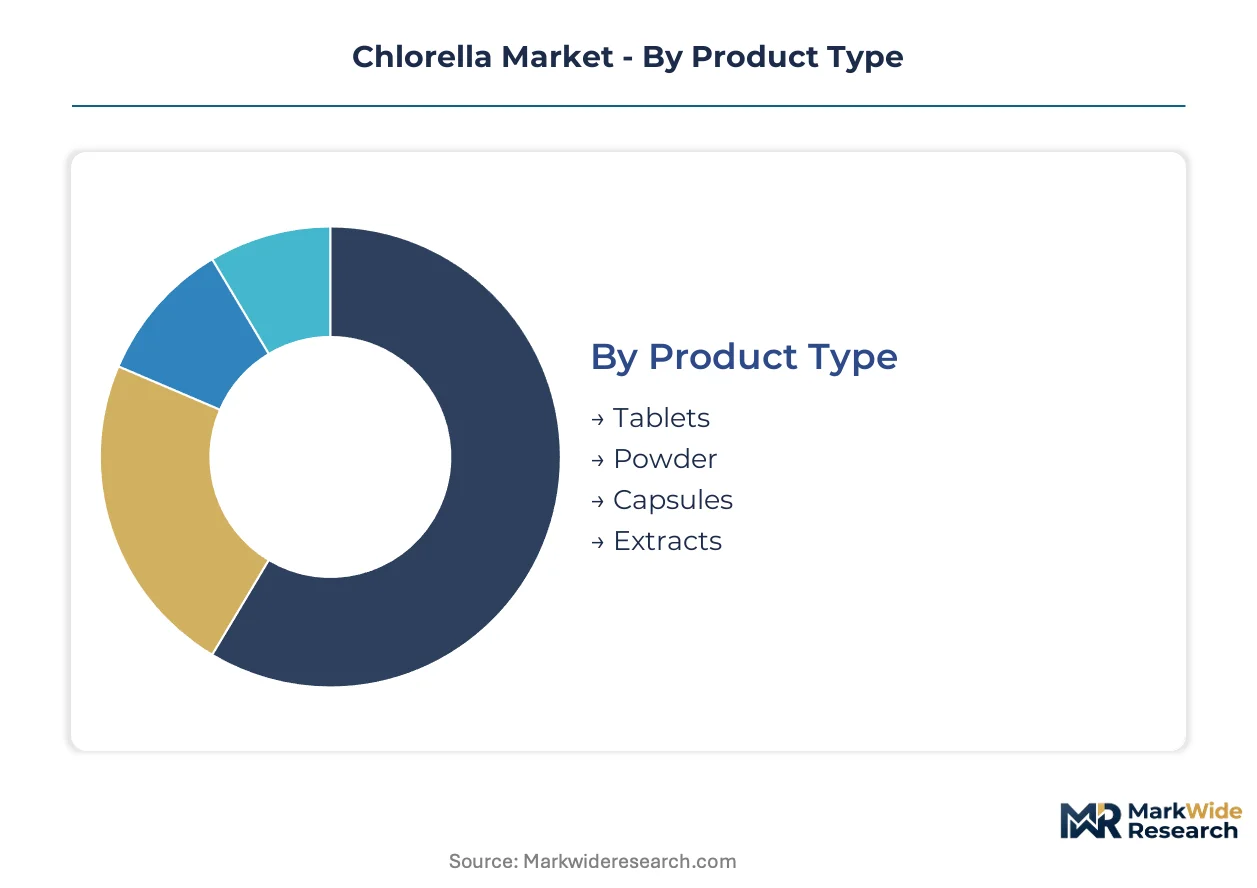
Understanding the Chlorella Market through segmentation reveals distinct demand patterns and supply chain dynamics. This granular analysis helps stakeholders identify high-growth segments and tailor product development and market entry strategies. Each segment possesses unique characteristics influencing its commercial viability and strategic importance within the broader chlorella ecosystem.
Product Type:
The product type segmentation highlights the balance between high-volume commodity forms and specialized, higher-value offerings.
- Powder:This form represents bulk chlorella biomass, typically processed for digestibility and offered as a raw ingredient. Demand is strong from large-scale supplement manufacturers and functional food producers seeking versatile, cost-effective nutrient fortification.
- Tablets:Compressed chlorella powder provides a convenient, pre-dosed format for direct consumer consumption. This product type commands significant demand from individual health-conscious consumers in markets like Japan and the United States, valuing ease of use and precise nutrient intake.
- Capsules:Encapsulated chlorella powder offers another convenient dosage form, often preferred for specific dietary supplement formulations.
- Extracts:Concentrated forms of chlorella compounds, such as Chlorella Growth Factor (CGF), target specific functional benefits in high-end nutraceuticals.
Mature deployment sits with Tablets. Newer deployment is concentrated in Extracts.
Application:
Segmentation by application clarifies where chlorella's nutritional and functional properties are most effectively utilized by various industries.
- Dietary Supplements:Chlorella serves as a nutrient-dense ingredient in capsules, tablets, and powders marketed for overall health and wellness. This segment draws significant demand from consumers globally, especially those pursuing plant-based nutrition and detoxification benefits.
- Animal Feed:Chlorella biomass is incorporated into feed formulations for livestock and aquaculture, enhancing growth rates and immune function. This application represents a high-volume outlet, particularly in fish and shrimp farming operations seeking sustainable protein sources.
- Cosmetics:Chlorella finds use in skincare products for its antioxidant and skin-rejuvenating properties.
- Fertilizers:Chlorella biomass can enrich soil composition and promote plant growth in agricultural settings.
The segment for Dietary Supplements exhibits steady demand, while Animal Feed demonstrates significant expansion.
End User:
The end-user segmentation identifies the primary commercial entities procuring chlorella ingredients for their specific product lines.
- Nutritionists:These professionals recommend chlorella products to clients for dietary enhancement and specific health goals. Their recommendations influence consumer purchasing decisions for high-quality chlorella supplements.
- Pet Food Manufacturers:Companies producing pet food integrate chlorella to boost nutritional content and appeal to health-conscious pet owners. This segment values chlorella for its protein content and beneficial micronutrients.
- Skincare Brands:Cosmetic companies formulate chlorella into various topical products, leveraging its perceived anti-aging and purifying attributes.
- Agricultural Firms:Businesses involved in crop cultivation and soil management utilize chlorella-based products to improve soil fertility and plant vitality.
Demand from Nutritionists remains foundational, with Agricultural Firms showing emergent interest.
Distribution Channel:
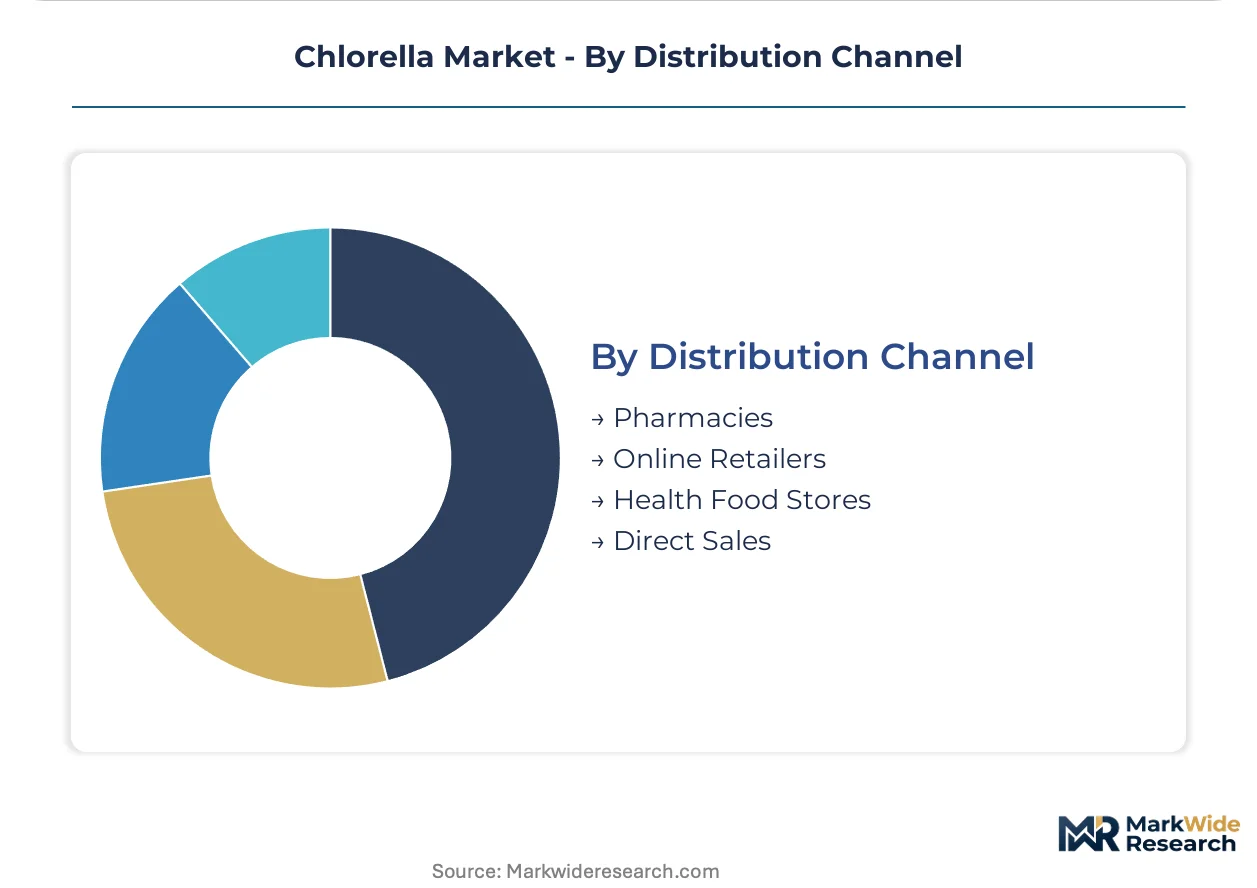
The distribution channel segmentation outlines the primary avenues through which chlorella products reach their target consumers and businesses.
- Online Retailers:E-commerce platforms provide broad access to chlorella products for a global consumer base, offering convenience and comparative shopping. This channel benefits from the increasing shift towards digital purchasing and direct-to-consumer models.
- Health Food Stores:Specialized retail outlets cater to consumers actively seeking natural health products and organic ingredients. These stores often provide informed staff and a curated selection of chlorella brands, appealing to discerning buyers.
- Pharmacies:Retail pharmacies offer chlorella products, often positioning them as health supplements alongside other vitamins and minerals.
- Direct Sales:Some chlorella producers engage in direct-to-consumer sales, leveraging brand loyalty and specialized product offerings.
The Online Retailers channel provides broad access, whereas Health Food Stores caters to specialized buyer needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumer demand for chlorella concentrates in health-conscious markets globally, driving regional growth across diverse applications. This demand is strong in areas with established dietary supplement markets and a preference for plant-based nutrition. Regulatory frameworks significantly influence market access.
United States
Demand for chlorella in the United States stems from its use in dietary supplements and functional foods, driven by plant-based protein trends. The FDA's GRAS notices provide a clear regulatory pathway for chlorella inclusion. Formulators in California's nutraceutical hub actively integrate chlorella into new product lines.
Japan
Japanese consumers show high demand for chlorella, especially in tablet form, valuing its traditional use and perceived health benefits. The Ministry of Health, Labour and Welfare (MHLW) oversees food additive regulations, ensuring product safety. Manufacturers in Tokyo and Osaka focus on direct-to-consumer sales.
Germany
German demand for chlorella is expanding through the European plant-based nutrition movement and functional beverage fortification. The European Food Safety Authority (EFSA) maintains stringent novel food regulations, impacting market entry. Companies in Bavaria's food processing clusters are exploring chlorella integration into innovative food and drink formulations.
India
India's chlorella market experiences growth from increasing health awareness and expansion of the aquaculture feed sector. The Food Safety and Standards Authority of India (FSSAI) regulates food ingredients, ensuring compliance for chlorella-derived products. Producers in southern states, like Tamil Nadu, invest in microalgae cultivation facilities.
China
China presents a substantial market for chlorella, driven by its large population and rising interest in natural health supplements and aquaculture feed. The National Health Commission (NHC) sets standards for food ingredients, influencing chlorella product development. Cultivation operations in coastal provinces, such as Shandong, scale up production to meet domestic consumption.
Chlorella Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue niche nutraceutical and functional food applications. The chlorella market exhibits a tiered structure, with large-scale bulk ingredient suppliers coexisting with specialized brand-focused firms. Strategic archetypes include vertically integrated cultivators, bulk ingredient processors, and consumer-facing brand owners that prioritize transparency. Companies primarily engage in capacity expansion and strategic partnerships to secure raw material supply and broaden market reach.
Within the bulk ingredient supplier archetype, Taiwan Chlorella Manufacturing Company operates with significant production scale, supplying biomass globally. Sun Chlorella Corp exemplifies a consumer-facing brand, leveraging strong recognition and direct-to-consumer channels in key markets like Japan and the United States. E.I.D. Parry (India) Limited represents a diversified producer within the broader microalgae sector, positioning itself across various applications including animal feed. These companies anchor different segments of the value chain, from raw material supply to finished product distribution.
| Leading Market Players |
|---|
| E.I.D. Parry (India) Limited |
| Yaeyama Chlorella |
| Sun Chlorella Corp |
| Tianjin Norland Biotech Co. Ltd |
| Fuqing King Dnarmsa Spirulina Co. Ltd |
| Phycom BV |
| Taiwan Chlorella Manufacturing Company |
| International Chlorella |
| Aliga Microalgae |
| Others |
Cost & Logistics Intelligence
Organic certification and verified Chlorella Growth Factor levels drive a significant tier divergence in the chlorella market, dictating premium pricing for specialized products and shaping supply chains towards either high-volume commodity production or niche, quality-controlled cultivation. This bifurcation directly impacts market access and competitive strategies.
Pricing Analysis
The chlorella market exhibits a clear volume-versus-margin split, with high-volume bulk powder segments operating on tighter margins compared to premium-priced extracts and certified consumer tablets. Pricing stratifies across premium, standard, and economy tiers, influenced by quality grade, organic certification, and specific nutrient profiles. Pricing softness stems from competition with lower-cost spirulina, particularly in bulk applications. Animal feed manufacturers represent the most price-sensitive buyers, while nutraceutical brands prioritize specific attributes over cost.
Supply Chain Analysis
Regional distribution centers facilitate global access for chlorella, particularly for bulk ingredients, operating on a hub-and-spoke model from key production regions. Supply concentrates in China, Taiwan, and India, with these countries dominating cultivation and initial processing, relying on consistent access to freshwater and specialized nutrient media. Contamination management in open pond systems presents a structural risk, necessitating stringent quality control protocols. Distribution runs through both direct-to-consumer channels for branded supplements and business-to-business sales for bulk biomass.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The chlorella market is navigating a technology-transition phase, with advanced cell-wall disruption technologies like enzymatic hydrolysis displacing traditional processing methods. This shift enables greater bioavailability and broader application in functional foods.
For Market Incumbents: Anticipate increasing regulatory scrutiny, especially from the European Food Safety Authority, by pre-emptively investing in robust toxicological studies for novel chlorella strains. Secure long-term supply agreements for quality raw materials to mitigate commodity price volatility and counter substitution threats from spirulina. Invest in strain optimization through biotechnology to improve yields and nutrient profiles, ensuring a competitive edge. Diversify product offerings beyond bulk powder into higher-margin extracts and functional food ingredients.
For New Entrants and Emerging Players: FDA's GRAS notices in the United States open a window for novel chlorella formulations in functional foods and beverages. Target underpenetrated segments like premium pet food and specialized sports nutrition products, emphasizing unique nutrient profiles. Leverage online retail channels and direct-to-consumer models to build brand recognition with transparent sourcing and clear health benefit claims. Focus on incorporating chlorella into convenient, ready-to-drink functional beverages.
For Investors and Strategic Acquirers: Exit pathways favor specialized nutraceutical firms with strong brand recognition or vertically integrated cultivators possessing proprietary technology. The market demonstrates long-term viability driven by sustained consumer demand for plant-based nutrition and functional ingredients over the next 5-10 years. Target companies with robust R&D in strain optimization or advanced cell-wall disruption technologies. A signal to watch is the acquisition of niche chlorella brands by larger food and beverage conglomerates.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Asia | Secures raw material supply for growing global demand for chlorella. |
| Biotechnology Investment for Strain Optimization | Enhances chlorella nutrient profiles and improves cultivation yield efficiency. |
| Partnerships with Functional Food Brands | Broadens chlorella application in high-growth consumer segments like beverages. |
| Investment in Advanced Cell-Wall Disruption | Improves chlorella bioavailability, enhancing product efficacy for consumers. |
| Organic Certification Pathway Development | Meets consumer demand for transparent and clean label chlorella ingredients. |
Research Approach
FDA GRAS notices, EFSA Novel Food Regulations, and FSSAI guidelines formed the secondary backbone for market sizing and regulatory analysis. Primary interviews with nutraceutical product developers, aquaculture farm managers, chlorella cultivation engineers, and dietary supplement brand managers provided qualitative insights. This approach combined bottom-up market data with top-down industry perspectives, ensuring comprehensive data triangulation.
Historical trendline analysis established baseline market performance and growth trajectories across the analysis window. The analytical framework modeled dimensions including product type, application, end user, and key geographic regions. Compound annual growth rates were derived through a combination of regression analysis and expert consensus from primary interviews. Forecast inputs incorporated chlorella cultivation yields and evolving plant-based protein consumption rates.
The model assumes a particular technology adoption path; alternative pathways for advanced cell-wall disruption technologies would alter the outlook. Forecasts reflect documented assumptions, but unforeseen regulatory shifts or rapid substitution by novel microalgae could introduce variability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Biotechnology
Microalgae Market
Food Biotechnology
Trypsin Market
Food Biotechnology
Apigenin Market
Food Biotechnology
Global Feed Enzymes Market
Food Biotechnology
Asia Pacific Eubiotics Market
Food Biotechnology
Perilla Protein Market
Food Biotechnology
South America Feed Prebiotics Market
Food Biotechnology
Global Food Biotechnology Market
Food Biotechnology
Global GMO Testing Market
Food Biotechnology
Direct-Fed Microbial Products Market
Food Biotechnology
Biotech Flavors Market
Food Biotechnology
Genistein Market
Food Biotechnology
Fruit and Vegetable-Derived Enzymes Market
Food Biotechnology
Glucose Oxidase Market
Food Biotechnology
North America Eubiotics Market
Food Biotechnology
Pullulanase Market