
 Fruit and Vegetable-Derived Enzymes Market | 2026-2036
Fruit and Vegetable-Derived Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
Fruit and Vegetable-Derived Enzymes Market Analytics
Capital-intensity divergence between integrated biotech platforms and commodity enzyme blenders is reorganizing competitive tiers in this sector. Novozymes A/S leverages its Danish fermentation infrastructure to dominate high-purity pectinase output. Koninklijke DSM N.V. anchors its position through backward integration into strain development and regulatory dossier accumulation. Associated British Foods Plc competes on beverage-sector channel control, extending formulation partnerships with multinational juice processors.
Fruit and vegetable-derived enzymes comprise biocatalysts extracted from plant tissues through aqueous or solvent-based isolation, typically standardized by activity units per gram for industrial dosing consistency. These enzymes cleave polysaccharide substrates to reduce viscosity, enhance extraction yields, or modify texture in downstream processing. Pectinase commands the largest revenue pool given its indispensability in fruit juice depectinization, though cellulase is gaining share as plant-based beverage formulations multiply. The application split tilts toward beverages, where margin pools concentrate around enzyme suppliers offering processing-condition guarantees, while pharmaceutical-grade protease remains a premium niche with lengthy qualification cycles.
The EU Green Deal and REACH frameworks restrict petrochemical-derived processing aids, directly expanding addressable demand for botanical enzyme alternatives. FDA GRAS self-determination pathways and EFSA novel food assessments govern market access for new enzyme preparations in food and nutraceutical channels. Stakeholders must monitor regulatory divergence between jurisdictions on enzyme labeling, organic compatibility, and processing aid status to avoid formulation lock-in.
Market Dynamics
EU Green Deal enforcement is compressing petrochemical processing aid permits while beverage manufacturers accelerate enzyme substitution timelines to maintain production continuity.
Growth Catalysts
- EU F-Gas Regulation phase-down:Refrigeration-dependent fruit processors in Germany and Spain face equipment replacement deadlines that favor ambient-temperature enzymatic clarification over cold-settling methods.
- Plant-based beverage proliferation:Oat, almond, and coconut milk processors require cellulase-pectinase blends to achieve mouthfeel parity with dairy, expanding addressable enzyme volumes beyond traditional juice applications.
- REACH authorization restrictions:Petrochemical-derived fining agents face sunset dates that redirect formulation R&D budgets toward botanical enzyme alternatives with established safety dossiers.
Market Restraints
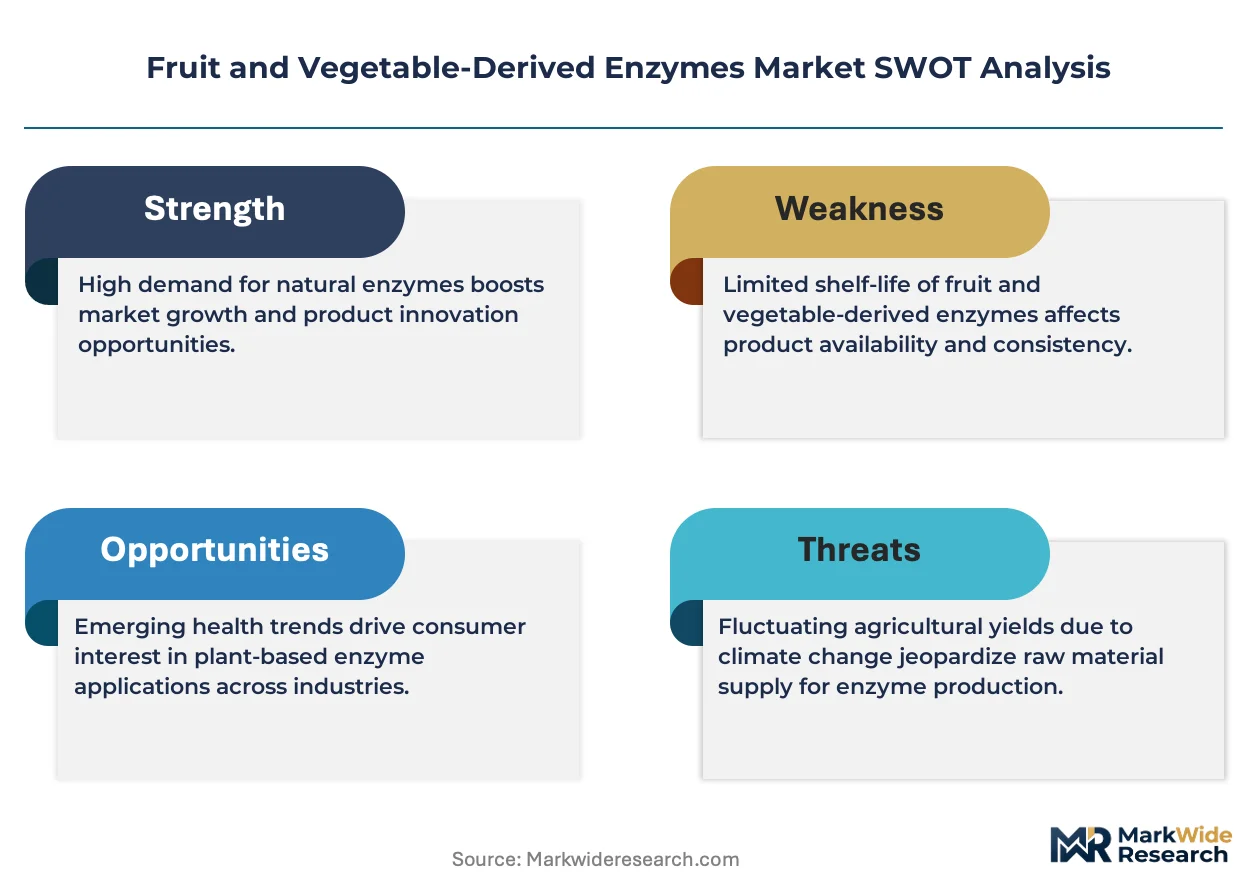
- Agricultural feedstock volatility:Citrus peel and pineapple stem supply concentrates in tropical regions exposed to climate-induced harvest variability, compressing pectinase and bromelain margin predictability.
- Fermentation capacity concentration:Contract manufacturing for high-activity enzyme concentrates clusters around Danish and Dutch industrial biotech corridors, creating single-source exposure for mid-tier blenders.
- Thermal stability limitations:Native plant-derived enzymes denature above 60°C, forcing processors to maintain parallel cold-chain infrastructure that petrochemical alternatives bypass.
Strategic Opportunities
- Indian pharmaceutical-grade protease qualification:CDSCO's abbreviated pathway for enzymes with USP-NF monographs offers faster market entry for suppliers targeting digestive health formulations.
- Precision fermentation convergence:Cell-free enzyme production platforms combining synthetic biology with plant-origin gene templates promise batch consistency unavailable in agricultural extraction.
- Direct-to-processor digital channels:Specialty enzyme distributors are bypassing traditional ingredient houses to sell standardized activity units through B2B platforms with real-time dosing calculators.
Industry Challenges
- Strain development talent scarcity:Industrial microbiologists capable of optimizing plant-origin enzyme expression in heterologous hosts command premium compensation that stretches R&D budgets at mid-scale suppliers.
- Organic certification compatibility:USDA Organic and EU Organic processing aid lists maintain divergent permitted enzyme categories, forcing dual-track formulation development for exporters.
- Legacy equipment retrofit costs:Juice processors operating 1990s-era depectinization tanks face capital expenditure requirements to install temperature-controlled enzymatic reaction vessels with automated dosing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fruit and Vegetable-Derived Enzymes Market |
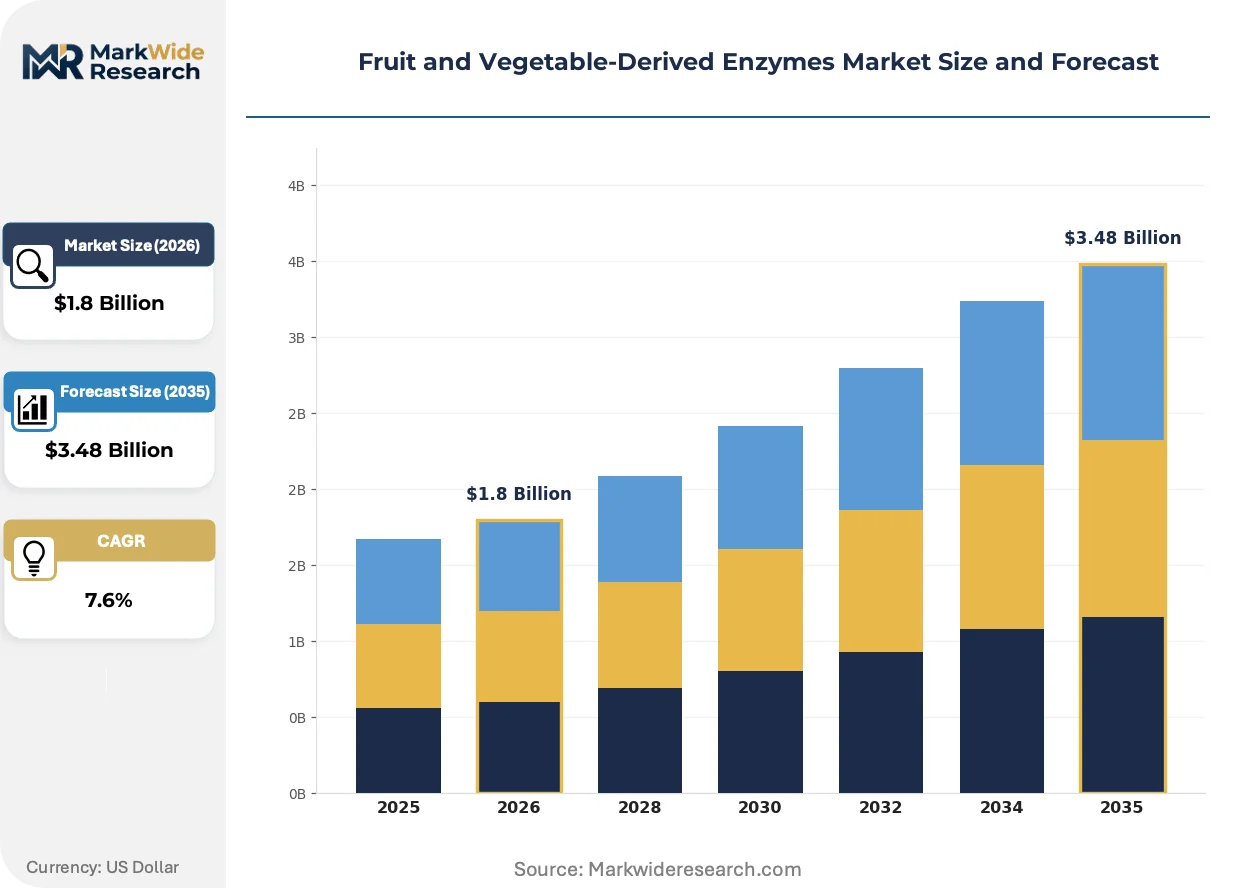
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pectinase, Amylase, Cellulase, Protease Application: Beverages, Bakery, Dairy, Pharmaceuticals End User: Food Industry, Beverage Industry, Nutraceuticals, Cosmetics Form: Liquid, Powder, Granules, Concentrate |
| Companies Covered | Novozymes A/S, Koninklijke DSM N.V., E. I. du Pont de Nemours and Company, Associated British Foods Plc, Advanced Enzymes, Amano Enzyme, AB Enzymes, Sunson Industry Group, Biocatalysts, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fruit and Vegetable-Derived Enzymes Market Evolving Landscape
Biocatalysis platforms are fragmenting from commodity pectinase supply toward application-specific enzyme cocktails with embedded process guarantees, compressing traditional blending margins while opening formulation partnership revenue.
Immobilized enzyme carrier technology is fragmenting batch processing economics. Fruit juice manufacturers in California and São Paulo adopt magnetic nanoparticle-bound pectinase systems that enable enzyme recovery and reuse across multiple clarification cycles. This technology is fragmenting the conventional single-use enzyme dosing model that dominated beverage processing for three decades.
EFSA's 2023 updated guidance on food enzyme safety evaluation requires expanded toxicological datasets for novel preparations, extending qualification timelines for suppliers launching non-traditional botanical sources. The industrial consequence is a qualification bottleneck favoring incumbents with accumulated dossiers on papain and bromelain. Pharmaceutical-grade applications face the steepest documentation requirements, with novel protease entrants targeting wound debridement markets absorbing 18-24 month assessment delays.
Buyer concentration among multinational beverage conglomerates has compressed supplier negotiation cycles from annual to quarterly terms. Procurement teams at leading juice processors now demand pilot-scale validation data and processing-condition guarantees before contract execution. This shift is most visible in Germany's industrial biotech corridor, where enzyme suppliers maintain dedicated technical service laboratories to support real-time formulation adjustments during harvest-season intake variations.
Fruit and Vegetable-Derived Enzymes Market Segmentation
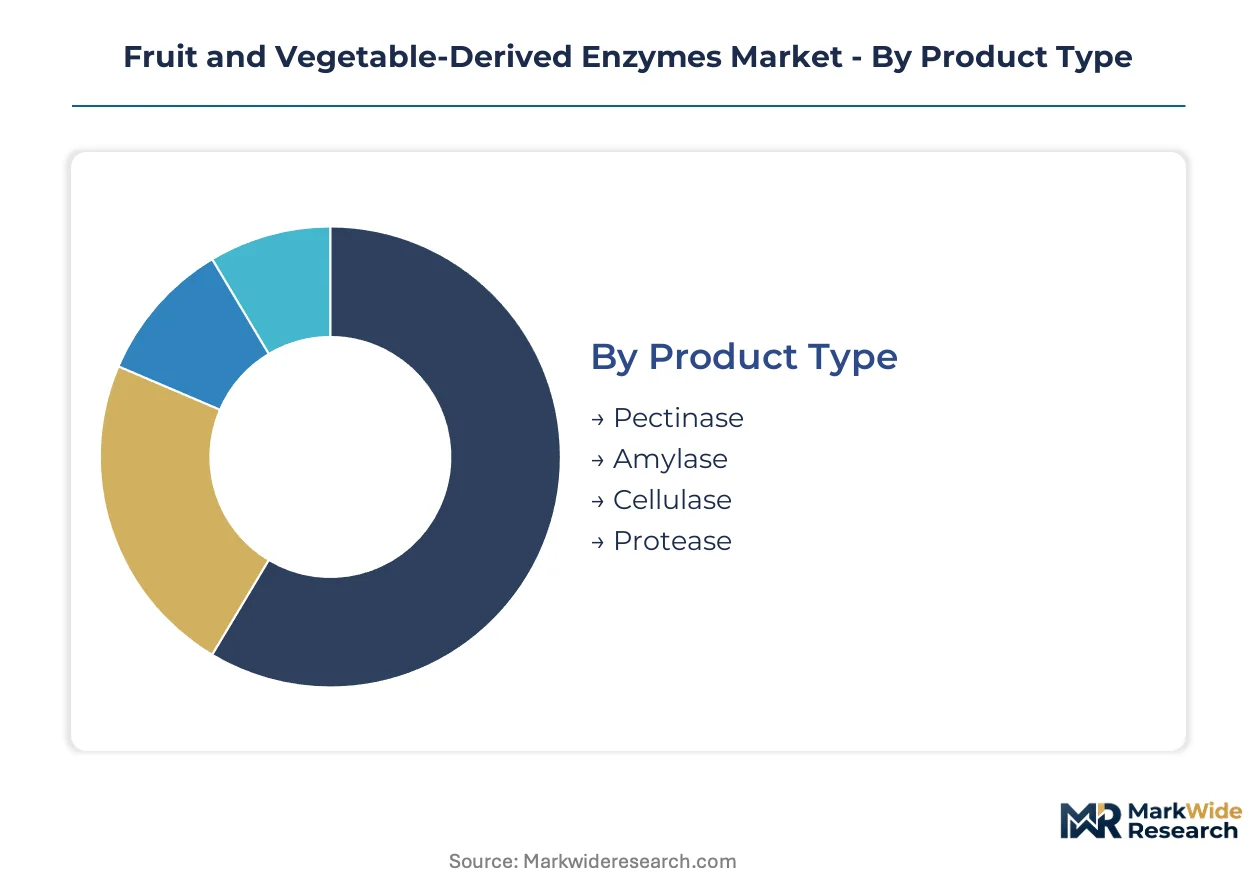
Segmentation in fruit and vegetable-derived enzymes reveals distinct margin pools and qualification barriers that determine supplier positioning. Each dimension—product chemistry, application protocol, customer vertical, and physical form—carries divergent regulatory exposure and substitution vulnerability.
Product Type:
Pectinase faces the most acute substitution pressure from synthetic fining agents, while protease maintains defensive moats through pharmaceutical-grade qualification complexity.
- Pectinase:Complex of polygalacturonase, pectin lyase, and pectinesterase enzymes that hydrolyze pectin chains to reduce juice viscosity and turbidity. Beverage manufacturers in Germany and Spain concentrate procurement around suppliers offering processing-condition guarantees for ambient-temperature clarification, driven by EU F-Gas Regulation phase-down deadlines.
- Cellulase:Endo- and exo-glucanase enzyme systems that cleave cellulose fibrils to enhance extraction yields and modify plant fiber texture. Oat, almond, and coconut milk processors in California and São Paulo drive demand for cellulase-pectinase blends to achieve mouthfeel parity with dairy alternatives.
- Amylase:Starch-hydrolyzing enzymes derived from malted grains and tropical fruit sources, standardized by dextrose equivalent production rates.
- Protease:Protein-cleaving biocatalysts including papain and bromelain with established USP-NF monographs, concentrated in wound debridement and digestive health formulations.
Pectinase retains volume leadership; cellulase holds the steepest expansion curve.
Application:
Cost tier stratification separates commodity beverage processing from premium pharmaceutical qualification cycles.
- Beverages:Juice clarification and plant-based milk processing dominate enzyme consumption volumes, with procurement teams demanding pilot-scale validation data and real-time formulation support during harvest-season intake variations.
- Pharmaceuticals:Protease applications for wound debridement and digestive health absorb 18-24 month EFSA assessment delays, creating qualification bottlenecks that favor incumbents with accumulated toxicological dossiers.
- Bakery:Amylase and xylanase blends for dough conditioning and shelf-life extension, constrained by thermal stability limitations above 60°C.
- Dairy:Lactase and lipase applications for reduced-lactose and flavor-modified products, facing competition from fermentation-derived alternatives.
Beverages command the largest procurement volumes; pharmaceuticals generate the highest margin per activity unit.
End User:
Customer type determines specification stringency, with nutraceuticals occupying the qualification-intensive middle ground between commodity food and premium cosmetic applications.
- Food Industry:Processors of canned fruits, jams, and prepared vegetables requiring standardized enzyme activity for viscosity control and texture modification.
- Beverage Industry:Multinational juice conglomerates with compressed negotiation cycles from annual to quarterly terms, demanding processing-condition guarantees.
- Nutraceuticals:Dietary supplement manufacturers targeting digestive health, subject to FDA GRAS self-determination and EFSA novel food assessments with divergent permitted enzyme categories.
- Cosmetics:Exfoliation and skin-conditioning applications utilizing bromelain and papain, constrained by organic certification compatibility requirements across USDA and EU Organic standards.
Food industry procurement concentrates on price-per-activity-unit; nutraceuticals absorb the longest qualification timelines.
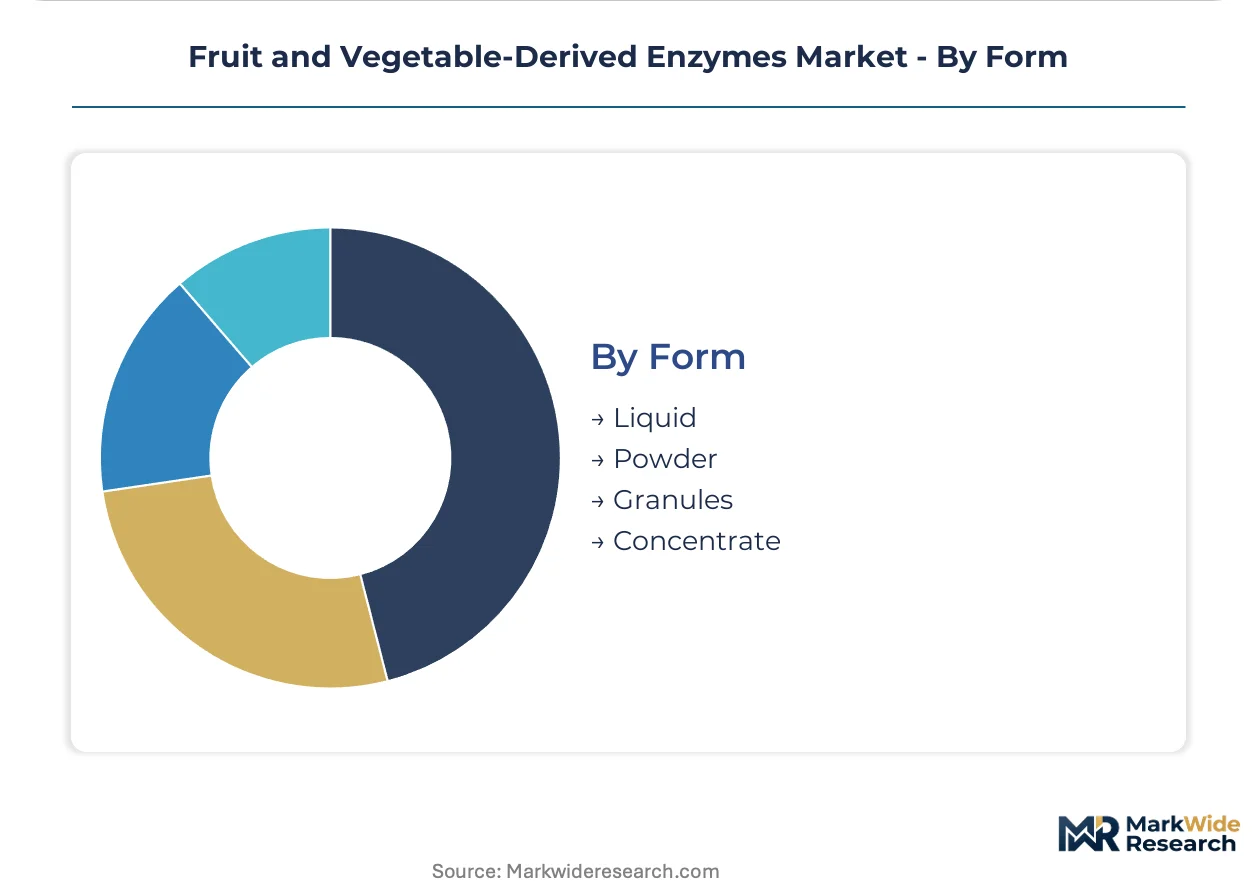
Form:
Supply concentration in Danish and Dutch fermentation corridors shapes availability of high-activity concentrates versus standardized liquid and powder formats.
- Liquid:Standardized enzyme solutions with defined activity units per milliliter, preferred by beverage processors for automated dosing systems and rapid dispersion in aqueous matrices.
- Powder:Spray-dried enzyme preparations with extended shelf stability, favored by bakery and dry-mix manufacturers for logistics efficiency and storage flexibility.
- Granules:Encapsulated enzyme particles for controlled-release applications in high-temperature processing environments.
- Concentrate:High-activity enzyme preparations requiring dilution prior to application, produced primarily through contract manufacturing at clustered industrial biotech facilities.
Liquid formulations dominate beverage channel volumes; concentrate supply tightens around single-source fermentation capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across geographies. German beverage processors absorb enzyme premiums for processing-condition guarantees, while Indian pharmaceutical formulators prioritize USP-NF monograph compliance over cost minimization. This bifurcation reshapes supplier geographic deployment.
Germany
Beverage manufacturers along the Rhine-Ruhr and Bavarian industrial corridors drive concentrated pectinase procurement for ambient-temperature juice clarification. The EU F-Gas Regulation phase-down accelerates substitution from cold-settling to enzymatic methods. Ingredient suppliers cluster around Frankfurt and Munich biotech corridors to deliver real-time formulation support during harvest-season intake variations.
United States
California and São Paulo-linked processors deploy cellulase-pectinase blends for oat and almond milk mouthfeel engineering. FDA GRAS self-determination pathways govern novel enzyme preparations faster than EFSA equivalents. Midwest beverage conglomerates compress supplier negotiation cycles to quarterly terms while demanding pilot-scale validation data.
India
Pharmaceutical-grade protease qualification for digestive health formulations absorbs disproportionate regulatory attention. CDSCO's abbreviated pathway for enzymes with USP-NF monographs offers faster market entry than full novel substance review. Maharashtra and Gujarat house contract manufacturing facilities serving both domestic nutraceutical brands and export markets.
Spain
Citrus processors in Valencia and Murcia face refrigeration equipment replacement deadlines under EU F-Gas Regulation enforcement. Ambient-temperature enzymatic clarification substitutes for cold-settling methods previously dependent on synthetic refrigerants. Local cooperatives source standardized pectinase activity units from Dutch fermentation corridors.
Netherlands
Industrial biotech infrastructure in the Randstad concentrates contract manufacturing for high-activity enzyme concentrates. REACH authorization restrictions on petrochemical-derived fining agents redirect formulation R&D budgets toward botanical alternatives. Eindhoven-region strain development facilities supply heterologous expression platforms for plant-origin enzyme production.
Fruit and Vegetable-Derived Enzymes Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Integrated fermentation platforms with captive strain development capabilities occupy the premium tier, while commodity blenders compete on standardized activity unit pricing. The market consolidates around three strategic archetypes: backward-integrated biotech platforms, beverage-sector channel specialists, and precision fermentation entrants. Dominant competitive moves include capacity expansion in Danish and Dutch industrial corridors and strategic partnerships with multinational juice processors for embedded formulation services.
Among integrated biotech platforms, Novozymes A/S and Koninklijke DSM N.V. exemplify the technology-leadership archetype through Danish fermentation infrastructure and regulatory dossier accumulation respectively. Associated British Foods Plc occupies a position within the channel-control segment, representing beverage-sector formulation partnership models. These three anchors illustrate how geographic concentration in Northern European biotech corridors combines with divergent strategic postures—platform integration versus sector specialization—to structure competitive tiers.
| Leading Market Players |
|---|
| Novozymes A/S |
| Koninklijke DSM N.V. |
| E. I. du Pont de Nemours and Company |
| Associated British Foods Plc |
| Advanced Enzymes |
| Amano Enzyme |
| AB Enzymes |
| Sunson Industry Group |
| Biocatalysts |
| Others |
Value Network & Pricing Analysis
Sixty-day enzyme concentrate lead times from Danish fermentation corridors compress pricing power toward contract manufacturers while amplifying margin volatility for mid-tier blenders lacking captive production. This inventory dynamic binds supply chain structure to buyer negotiation leverage, particularly as EU F-Gas Regulation deadlines force beverage processors toward guaranteed-delivery premiums.
Pricing Analysis
After-sales technical service contracts drive lifetime value more than upfront enzyme unit pricing, with beverage processors in Germany and Spain paying formulation-support premiums for ambient-temperature clarification guarantees. Three-tier pricing structure across pharmaceutical-grade, food-grade, and technical-grade activity standards separates margin pools, with USP-NF monograph compliance commanding the steepest premiums. Cost compression in commodity pectinase is intensifying because precision fermentation entrants promise batch consistency without agricultural feedstock exposure. Mid-tier blenders face the sharpest price sensitivity, while multinational juice conglomerates absorb service-bundled premiums for harvest-season responsiveness.
Supply Chain Analysis
Inventory concentration in Danish and Dutch industrial biotech corridors creates single-source exposure for high-activity concentrates, with 45-60 day replenishment cycles typical during peak harvest intake periods. Raw material dependencies center on tropical citrus peel and pineapple stem supplies from Brazil and Thailand, plus specialized fermentation media from German chemical suppliers. Single-source vulnerability concentrates around contract manufacturing agreements with limited geographic redundancy. Distribution runs through specialty ingredient houses and emerging B2B platforms with real-time dosing calculators, fragmenting traditional channel control.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a cyclical recovery phase as EU Green Deal enforcement compresses petrochemical processing aid permits and redirects formulation R&D budgets toward botanical alternatives. The recovery trajectory hinges on F-Gas Regulation substitution timelines across German and Spanish beverage processing corridors.
For Market Incumbents: Secure backward integration into strain development capabilities to defend against precision fermentation entrants promising batch consistency without agricultural extraction volatility. Accumulate EFSA toxicological dossiers on papain and bromelain to exploit qualification bottlenecks that delay novel protease competitors. Capacity addition in Dutch Randstad fermentation corridors reinforces supply security for high-activity concentrate output. For New Entrants and Emerging Players: Lead with CDSCO-abbreviated pathway strategies for pharmaceutical-grade protease targeting Indian digestive health formulations, where USP-NF monograph compliance accelerates market entry versus full novel substance review. Direct-to-processor digital channels with embedded dosing calculators offer the most penetrable go-to-market angle, bypassing entrenched ingredient house relationships in beverage sectors. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because buyer concentration among multinational beverage conglomerates compresses supplier margins and rewards scale economies in technical service infrastructure. Acquisition targets should feature captive fermentation capacity and accumulated regulatory dossiers. The signal to watch is precision fermentation platform maturation, which threatens agricultural extraction economics if cell-free production achieves cost parity.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Synthetic biology platforms combining plant-origin gene templates with cell-free production promise batch consistency unavailable in tropical agricultural extraction. |
| Backward Integration into Strain Development | Captive heterologous expression capabilities reduce single-source exposure to Danish and Dutch contract manufacturing clusters. |
| EFSA Dossier Accumulation | Expanded toxicological datasets on established enzymes exploit qualification bottlenecks that delay novel preparation entrants. |
| Direct-to-Processor Digital Channels | B2B platforms with real-time dosing calculators fragment traditional ingredient house control over beverage sector procurement. |
| Immobilized Enzyme Carrier Deployment | Magnetic nanoparticle-bound pectinase systems enable enzyme recovery and reuse, compressing conventional single-use dosing economics. |
Research Methodology
A standing panel of fermentation plant managers, beverage procurement directors, regulatory affairs specialists, and pharmaceutical formulators provided ongoing calibration across primary interview cycles. Secondary validation drew from EFSA guidance documents, FDA GRAS notifications, CDSCO enzyme monographs, EU F-Gas Regulation implementation reports, and customs trade data on tropical feedstock flows. Bottom-up enzyme activity unit demand modeling triangulated against top-down beverage processing capacity assessments.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include enzyme chemistry type, application protocol, end-user vertical, physical formulation, and regional regulatory cluster. CAGRs were derived from fitted growth curves incorporating F-Gas Regulation phase-down schedules and plant-based beverage proliferation rates. Industry-specific inputs encompassed harvest-season intake variation patterns and EFSA assessment timeline distributions.
Underlying assumptions cover EU Green Deal enforcement continuity, REACH authorization sunset adherence, and precision fermentation cost trajectory stability, with deviation risk concentrated in tropical feedstock climate volatility and strain development talent scarcity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Biotechnology
Pullulanase Market
Food Biotechnology
Papain Market
Food Biotechnology
Beta Lactoglobulin Protein Market
Food Biotechnology
Africa Eubiotics Market
Food Biotechnology
Lupin Protein Market
Food Biotechnology
Hemoglobin Feed Market
Food Biotechnology
Carbohydrate Enzyme Preparation Market
Food Biotechnology
Perilla Protein Market
Food Biotechnology
Casein Peptone Market
Food Biotechnology
Bangladesh Starch and Starch Derivative Market
Food Biotechnology
Cultured Meat Market
Food Biotechnology
Global Food Biotechnology Market
Food Biotechnology
Apigenin Market
Food Biotechnology
Glucose Oxidase Market
Food Biotechnology
Salmon Polynucleotide (PN) Market
Food Biotechnology
South America Feed Prebiotics Market