
 India Biomass Market | 2026-2036
India Biomass Market Size, Share, and Industry Trends Forecast 2026-2036
India Biomass Market Outlook
High-calorific-value pellet specifications is bifurcating the India biomass landscape into industrial-grade and rural thermal segments. NTPC Renewable Energy Limited leverages its utility-scale procurement muscle to lock in long-term agricultural residue supply contracts across Punjab and Haryana. Praj Industries Limited specializes in second-generation ethanol pathways from lignocellulosic feedstocks, sustaining its technology leadership in advanced biofuel processing. Godavari Biorefineries Limited anchors the western India market through integrated bagasse-to-power operations at its sugar complexes.
Biomass comprises organic matter derived from agricultural residues, forestry waste, energy crops, and biodegradable municipal streams, typically processed through combustion, gasification, or anaerobic biodigestion to release stored chemical energy as heat, electricity, or transport fuels. Agricultural residues dominate feedstock intake due to India's intensive cereal and sugarcane cultivation cycles, though energy crops represent the fastest-expanding input category as dedicated plantations scale in Gujarat and Tamil Nadu. Among applications, electricity generation commands the largest revenue pool through grid-connected cogeneration and independent power producer models, while transportation fuel absorbs disproportionate policy attention via ethanol blending mandates.
The Ministry of New and Renewable Energy shapes deployment velocity through biomass power and cogeneration targets, while the Central Electricity Authority enforces co-firing obligations for coal plants. BIS pellet standards and state-level pollution control board emission norms constrain equipment imports and on-site combustion performance. Stakeholders must track procurement cost spreads between imported biomass machinery and indigenized gasification systems to calibrate capital deployment timing.
Market Dynamics
The Ministry of New and Renewable Energy's co-firing mandate is compressing coal plant retrofit timelines while agricultural residue supply chains scramble to meet quality specifications. This regulatory pressure is forcing a bifurcation between industrial-grade pellet producers and informal rural thermal suppliers.
Growth Catalysts
- MNRE Co-firing Mandate:Coal-fired utilities must blend biomass pellets, creating guaranteed offtake for agricultural residue processors in Punjab and Haryana.
- BIS Pellet Standards:Uniform quality specifications enable equipment standardization and reduce combustion performance disputes between suppliers and power plants.
- Sugar Mill Cogeneration:Maharashtra's bagasse-based power complexes generate dispatchable renewable electricity with existing boiler infrastructure.
Market Restraints
- Feedstock Cost Volatility:Paddy straw and cotton stalk prices fluctuate with monsoon cycles and competing fodder demand from dairy cooperatives.
- Equipment Import Dependence:Gasification reactor vessels and densification presses concentrate among German and Italian OEMs, exposing projects to currency risk.
- Grid Integration Friction:State electricity distribution companies delay biomass power purchase agreement payments, squeezing independent producer cash flows.
Strategic Opportunities
- Second-generation Ethanol Pathways:Lignocellulosic conversion technologies unlock energy crop value from dedicated plantations scaling in Gujarat and Tamil Nadu.
- Cement Sector Substitution:Rajasthan and Madhya Pradesh clinker kilns represent untapped thermal demand for high-ash agricultural residue briquettes.
- PLI Scheme Alignment:Production-linked incentives for advanced biofuel equipment manufacturing reduce capital costs for domestic gasification system deployment.
Industry Challenges
- Combustion Engineering Talent Gap:Power plant operators lack training in biomass flame stability management and slagging prevention protocols.
- Storage and Handling Infrastructure:Seasonal harvest windows require covered warehousing investments that strain project developer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Biomass Market |
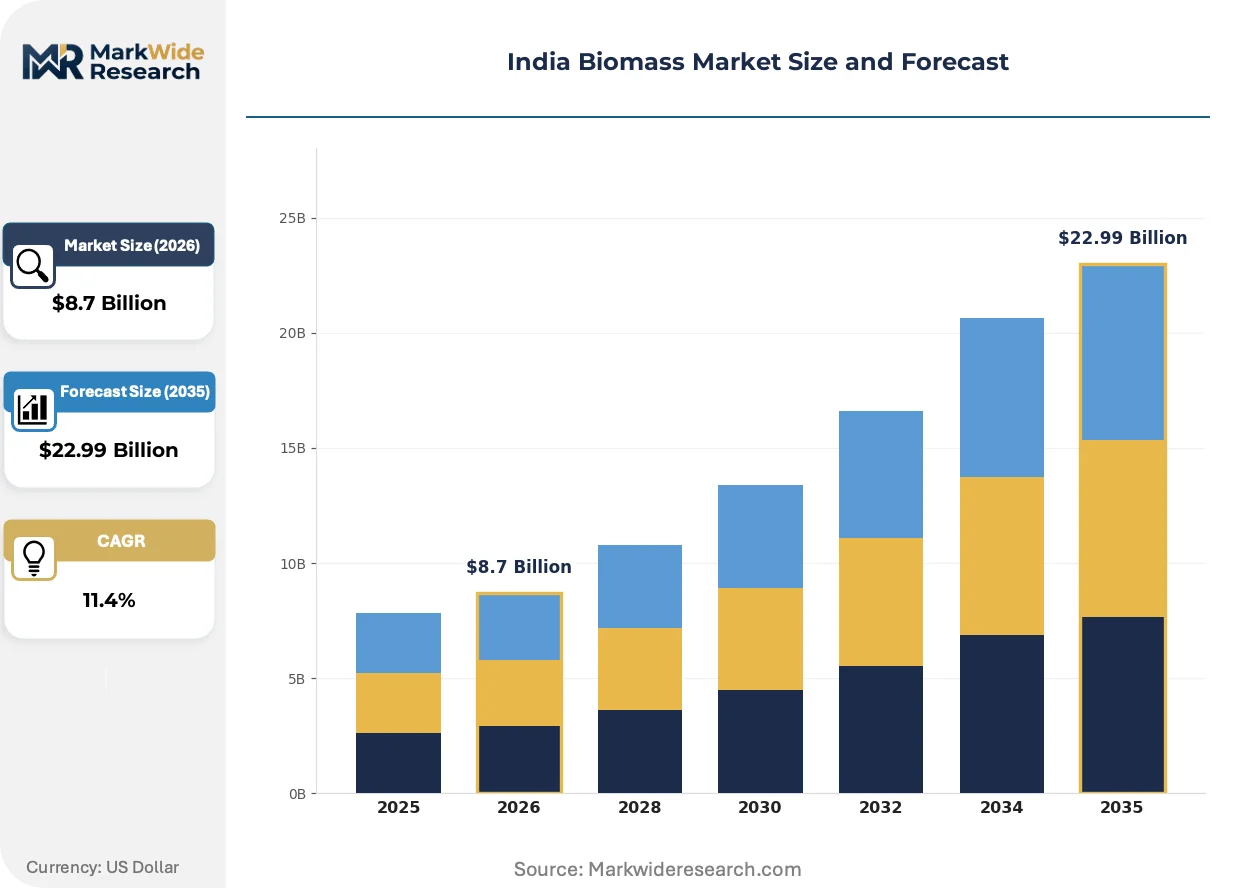
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Feedstock Type: Agricultural Residues, Forestry Residues, Energy Crops, Organic Waste Technology: Biodigestion, Gasification, Combustion, Pyrolysis Application: Electricity Generation, Heating, Transportation Fuel, Cooking Fuel End User: Industrial, Residential, Commercial, Agricultural |
| Companies Covered | Godavari Biorefineries Limited, NTPC Renewable Energy Limited, Praj Industries Limited, Emami Agrotech Limited, Gattuwala Energy Solutions Private Limited, Indian Oil Corporation Limited, Abellon Clean Energy, Altret Greenfuels Limited, Bharat Petroleum Corporation Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Biomass Market Strategic Shifts
Torrefaction and steam explosion pretreatment methods are upgrading agricultural residue fuel properties to match coal grindability indices. These thermochemical modifications expand addressable plant capacity beyond retrofitted boilers.
Torrefaction reactors operating at 250-300°C are supplanting raw pellet combustion in cement kiln calciners and circulating fluidized bed power units. ACC and Ambuja Cements have piloted torrefied paddy straw at Rajasthan facilities since 2023. The technology is enabling higher co-firing ratios without flame temperature penalties or ash fusion complications.
The Central Electricity Authority's 2022 co-firing notification mandates biomass blending percentages rising to 5-10% for designated coal units. This obligates NTPC and state gencos to execute long-term residue supply contracts with aggregator networks. Western and northern regional load dispatch centers face the steepest procurement ramps as their coal plant concentrations exceed national averages.
Power purchase agreements are migrating from cost-plus tariffs to competitive bidding formats that expose biomass generators to merchant price risk. Discoms in Maharashtra and Karnataka have unbundled renewable purchase obligations from must-run dispatch guarantees. Sugar mill cogenerators in the Marathwada belt now hedge electricity sales through day-ahead market exposure rather than fixed PPAs.
India Biomass Market Segmentation
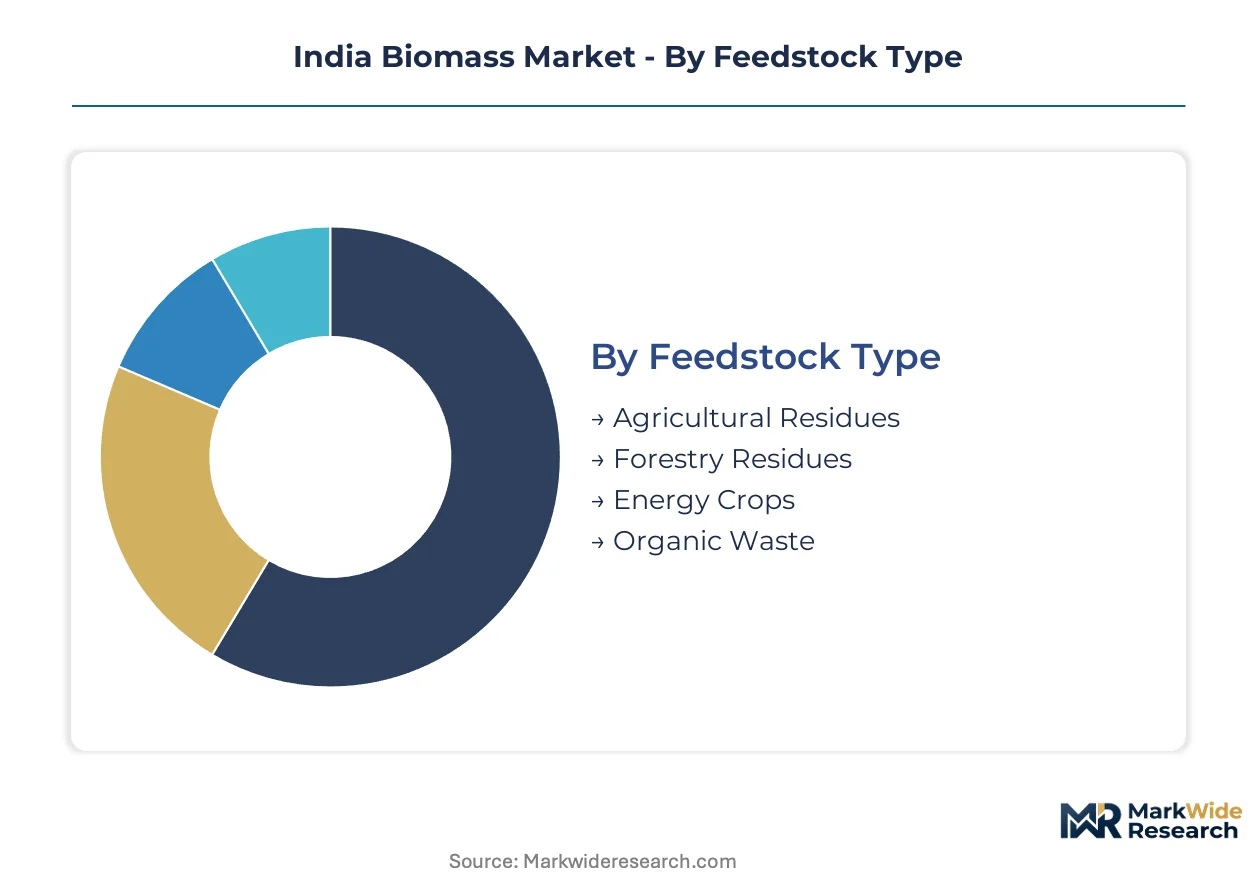
Biomass market segmentation reveals where substitution pressure from coal, natural gas, and electrification concentrates most intensely. Feedstock quality tiers and technology maturity gaps determine which segments attract capital versus which face margin compression.
Feedstock Type:
Agricultural residues face acute substitution threat from imported coal at cement kilns, while energy crops compete with food-grade land use.
- Agricultural Residues:Paddy straw, cotton stalk, and sugarcane bagasse constitute the dominant procurement category. Cement plants in Rajasthan and Madhya Pradesh source these residues as thermal coal substitutes under MNRE co-firing mandates. Price volatility from competing fodder demand constrains supply security.
- Energy Crops:Dedicated plantations of napier grass and bamboo scale across Gujarat and Tamil Nadu for lignocellulosic ethanol pathways. These crops command premium offtake contracts from second-generation biofuel processors seeking consistent quality specifications absent in seasonal agricultural waste.
- Forestry Residues:Sawmill waste and logging slash feed small-scale gasification units in Himalayan states with limited grid connectivity.
- Organic Waste:Municipal biodegradable streams and food processing effluent drive anaerobic biodigestion installations near urban centers.
Agricultural residues retain volume leadership; energy crops hold the steepest expansion curve.
Technology:
Technology choice hinges on feedstock moisture content and the calorific value threshold required by specific end-use applications.
- Combustion:Direct firing and co-firing configurations dominate grid-connected power generation. NTPC's coal plant retrofits in Punjab and Haryana deploy circulating fluidized bed boilers engineered for agricultural residue pellets meeting BIS standards. Ash fusion temperature mismatches limit co-firing ratios at subcritical units.
- Gasification:Partial oxidation reactors produce syngas for captive industrial thermal applications. Equipment import dependence on German and Italian OEMs exposes project developers to euro-rupee volatility and extended commissioning timelines.
- Biodigestion:Anaerobic digesters process high-moisture organic waste streams at dairies and food processing clusters.
- Pyrolysis:Thermochemical decomposition yields bio-oil and biochar from woody biomass in decentralized rural installations.
Combustion commands installed capacity leadership; gasification carries the most aggressive capacity addition pipeline.
Application:
Application segmentation tracks where policy mandates override market pricing versus where merchant economics prevail.
- Electricity Generation:Grid-connected cogeneration at sugar mills and independent power producer models absorb the largest capital deployment. Maharashtra's bagasse-based complexes leverage existing boiler infrastructure for dispatchable renewable output. Discom payment delays in Karnataka and Maharashtra squeeze independent producer cash flows.
- Transportation Fuel:Ethanol blending mandates drive disproportionate policy attention relative to current volume. Lignocellulosic conversion technologies unlock agricultural residue value beyond first-generation sugarcane molasses pathways.
- Heating:Industrial process heat applications at cement and textile plants expand as coal substitution accelerates.
- Cooking Fuel:Improved biomass cookstoves and biogas digesters serve rural households beyond LPG distribution networks.
Electricity generation anchors revenue concentration; transportation fuel exhibits the most policy-sensitive demand trajectory.
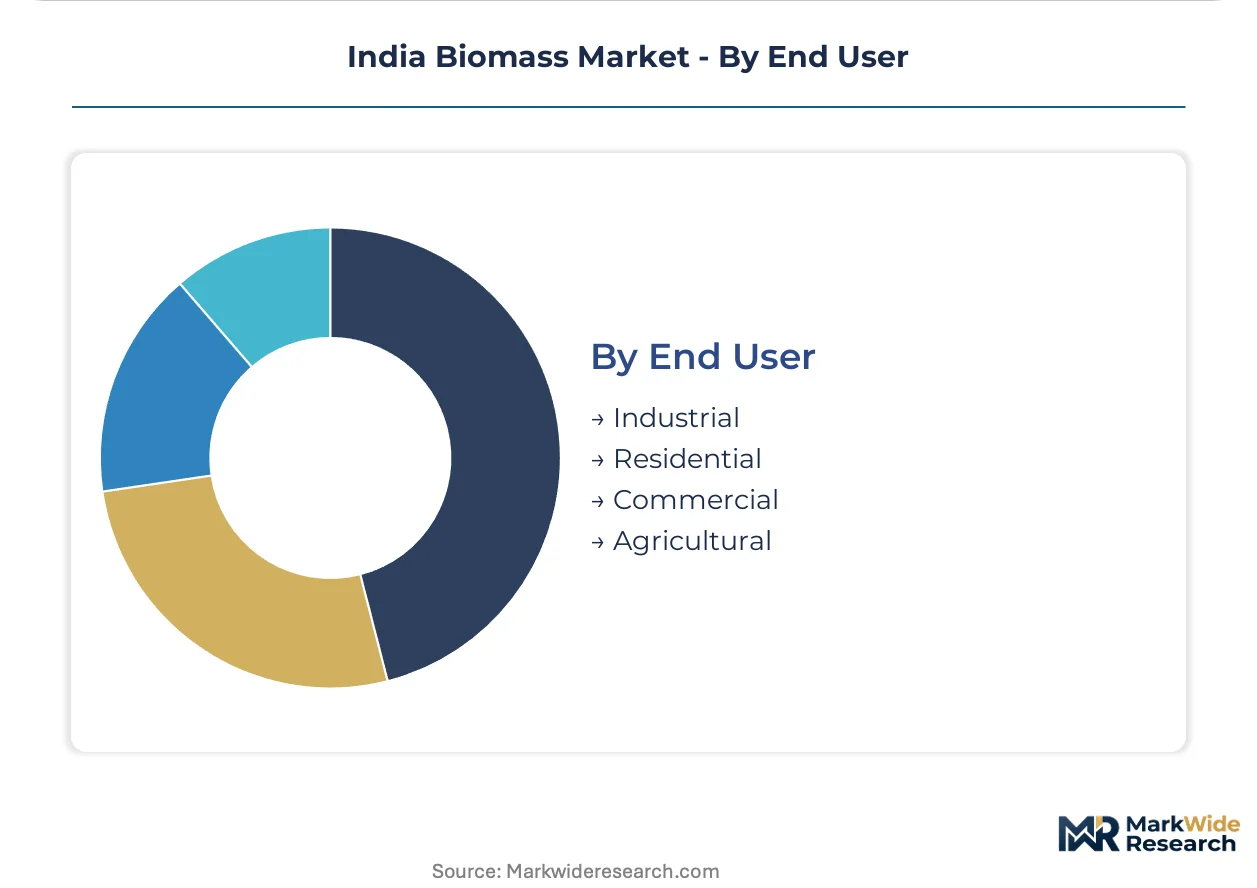
End User:
End user segmentation reflects divergent procurement sophistication between institutional buyers and fragmented household demand.
- Industrial:Cement kilns, textile dryers, and chemical process units purchase pelletized residues through annual contracts with quality enforcement. ACC and Ambuja Cements pilot torrefied paddy straw at Rajasthan facilities to achieve higher substitution ratios without flame stability penalties.
- Agricultural:Sugar mill cogenerators self-supply bagasse while selling surplus power to state grids under renewable purchase obligations. The Marathwada belt in Maharashtra clusters the densest installed cogeneration capacity.
- Commercial:Hotels, hospitals, and educational institutions deploy biodigestion systems for organic waste management with captive biogas utilization.
- Residential:Rural households rely on unprocessed agricultural residues for thermal cooking and heating with minimal value-added processing.
Industrial procurement dominates contract value; agricultural end users maintain the most integrated supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Agricultural residue availability clusters biomass procurement networks around Punjab and Haryana's paddy belt, Maharashtra's sugar complexes, and Gujarat's emerging energy crop plantations. State-level renewable purchase obligations and co-firing mandates reshape capital deployment across these zones.
Punjab and Haryana
Paddy straw surplus drives pellet production capacity concentrated around Ludhiana and Karnal. The Central Electricity Authority's co-firing notification obligates NTPC plants at Ropar and Jhajjar to procure agricultural residue pellets. Ambala and Patiala host aggregator networks consolidating farm-level collections into power-plant-ready fuel.
Maharashtra
Sugarcane bagasse anchors the western India cogeneration corridor through Solapur, Kolhapur, and Ahmednagar districts. State electricity distribution companies procure dispatchable renewable power under renewable purchase obligations. The Marathwada belt clusters the densest installed cogeneration capacity with surplus sales to Maharashtra State Electricity Distribution Company Limited.
Rajasthan
Cement kiln coal substitution creates thermal demand for high-ash agricultural residue briquettes around Chittorgarh and Nimbahera. MNRE co-firing mandates accelerate clinker calciner retrofits at ACC and Ambuja Cements facilities. Jodhpur and Udaipur serve as logistics hubs for residue aggregation from neighbouring Madhya Pradesh.
Gujarat
Dedicated napier grass and bamboo plantations scale across Kutch and Saurashtra for lignocellulosic ethanol pathways. Praj Industries Limited anchors advanced biofuel processing infrastructure at Savli near Vadodara. The state's petrochemical corridor provides syngas handling expertise transferable to biomass gasification projects.
Tamil Nadu
Energy crop trials concentrate around Coimbatore and Tiruppur districts with textile sector process heat demand nearby. State-level bioenergy policies promote captive power generation for dyeing and finishing units. Salem and Erode host equipment fabricators serving regional gasification reactor demand.
India Biomass Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, fragmenting competitive dynamics across equipment supply, fuel aggregation, and integrated processing. State-owned utilities leverage procurement scale to lock in residue supply contracts, while private refiners anchor advanced biofuel technology pathways. Three archetypes dominate: utility-backed aggregators, sugar-integrated cogenerators, and technology-specialized refiners. Competitive moves concentrate on long-term supply contracting, co-firing retrofit partnerships, and second-generation ethanol licensing.
Among utility-backed aggregators, NTPC Renewable Energy Limited occupies a position exemplifying procurement muscle applied to agricultural residue lock-in. Sugar-integrated operators find representation in Godavari Biorefineries Limited, anchoring western India through captive bagasse-to-power infrastructure. Technology-specialized refiners include Praj Industries Limited, exemplifying lignocellulosic conversion leadership without upstream feedstock ownership. These three illustrate how competitive position derives from supply chain control points rather than manufacturing scale alone.
| Leading Market Players |
|---|
| Godavari Biorefineries Limited |
| NTPC Renewable Energy Limited |
| Praj Industries Limited |
| Emami Agrotech Limited |
| Gattuwala Energy Solutions Private Limited |
| Indian Oil Corporation Limited |
| Abellon Clean Energy |
| Altret Greenfuels Limited |
| Bharat Petroleum Corporation Limited |
| Others |
Value Chain & Pricing Dynamics
Agricultural residue pellets displacing thermal coal at cement kilns and power plants simultaneously redraws procurement geography toward Punjab-Haryana paddy belts and compresses fuel cost spreads between biomass and fossil alternatives. This substitution dynamic concentrates pricing power with residue aggregators who control covered storage infrastructure and BIS-certified pellet quality.
Pricing Analysis
The Central Electricity Authority's co-firing notification dictates the pricing tier structure across Indian biomass markets. Three-tier pricing structure across premium torrefied pellets, standard BIS-certified pellets, and economy-grade briquettes stratifies procurement by combustion performance requirements. Cost compression in economy-grade agricultural residue briquettes is intensifying because cement kilns demand higher ash fusion thresholds. Price-sensitive independent power producers in Maharashtra and Karnataka gravitate toward standard-grade pellets, while least-sensitive cement majors in Rajasthan absorb premium torrefied product premiums for flame stability assurance.
Supply Chain Analysis
Punjab and Haryana anchor agricultural residue aggregation through Ludhiana-Karnal pellet production clusters. Equipment supply draws from German and Italian OEMs for gasification reactor vessels and densification presses. Single-source vulnerability concentrates in euro-denominated machinery imports exposed to currency volatility. Distribution runs through state electricity distribution company procurement channels and direct industrial offtake contracts with cement and textile process heat users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent biomass processors face substitution defense imperatives against imported coal price volatility and grid-scale solar-plus-storage combinations that erode dispatchable renewable premiums.
For Market Incumbents: Secure backward integration into covered warehousing infrastructure across Punjab and Haryana harvest windows to lock in feedstock cost predictability against monsoon-driven paddy straw price spikes. Deepen captive supply of torrefied pellet capacity to cement sector buyers who prioritize flame stability over unit fuel cost. For New Entrants and Emerging Players: Combustion engineering talent scarcity in biomass flame management and slagging prevention protocols opens white-space service opportunities. Target Rajasthan cement kiln retrofit advisory and operator training as the most penetrable segment. Pursue equipment-agnostic consulting contracts rather than capital-intensive pellet production entry. For Investors and Strategic Acquirers: The market sits at a policy-dependency phase that favors utility-backed aggregators with long-term offtake security. Five-to-ten-year viability hinges on co-firing mandate durability and ethanol blending trajectory. Acquisition target archetype: second-generation ethanol technology licensors with lignocellulosic conversion patents and Gujarat-Tamil Nadu energy crop plantation partnerships. Monitor Central Electricity Authority procurement enforcement consistency as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Residue Aggregation | Covered warehousing investments in Punjab-Haryana paddy belts secure feedstock cost predictability against monsoon volatility. |
| Torrefaction Capacity Buildout | Thermochemical upgrading enables higher coal substitution ratios at ACC and Ambuja Cements Rajasthan facilities without flame stability penalties. |
| Long-term Supply Agreement with State Gencos | NTPC Renewable Energy Limited leverages procurement scale to lock in multi-year agricultural residue offtake contracts. |
| Technology Licensing for Second-generation Ethanol | Praj Industries Limited monetizes lignocellulosic conversion patents through Gujarat and Tamil Nadu energy crop plantation partnerships. |
| Green Certification Program Alignment | BIS pellet standard compliance and MNRE co-firing mandate adherence qualify biomass generators for renewable purchase obligation credits. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with utility procurement officers at NTPC and state gencos, pellet plant operations managers in Ludhiana and Karnal, cement kiln fuel buyers at Rajasthan facilities, and agricultural residue aggregator network coordinators. Secondary validation drew from Central Electricity Authority co-firing notifications, MNRE biomass power targets, BIS pellet standards documentation, and state electricity regulatory commission tariff orders. Bottom-up feedstock availability modeling and top-down policy target reconciliation anchored market sizing triangulation.
Across the analysis window, volume and value projections segment by feedstock type, technology pathway, application end-use, and state-level regulatory cluster. CAGRs derive from feedstock cost trajectory modeling, equipment deployment pipeline assessment, and co-firing mandate compliance schedule analysis. Forecast inputs incorporate monsoon cycle variability impacts on paddy straw supply, euro-rupee exchange rate assumptions for gasification equipment imports, and state discom payment delay patterns affecting independent producer cash flow.
Underlying assumptions cover MNRE mandate enforcement continuity, BIS standard adoption rates, and cement sector coal substitution economics, with deviation risk concentrated in regulatory rollback scenarios, imported coal price collapse, and grid integration friction escalation. Recalibration cycles align with material shifts in Central Electricity Authority procurement guidelines, state renewable purchase obligation revisions, and second-generation ethanol commercialization milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Japan Biofertilizer Market
Bio-Agriculture
Global Citrus Bioflavonoids Market
Bio-Agriculture
North America Biological Organic Fertilizer Market
Bio-Agriculture
Biostimulants Market
Bio-Agriculture
Australia Biopesticides Market
Bio-Agriculture
North America Biofertilizer Market
Bio-Agriculture
France Biopesticides Market
Bio-Agriculture
Brazil Biopesticides Market
Bio-Agriculture
China Biofuels Market
Bio-Agriculture
Mycelium Market
Bio-Agriculture
Mycorrhiza-Based Biofertilizer Market
Bio-Agriculture
Bloodroot Market
Bio-Agriculture
US Biochar Market
Bio-Agriculture
Red Algae Market
Bio-Agriculture
Hydroponics Nutrients Market
Bio-Agriculture
Europe Bioethanol Market