
 Perilla Protein Market | 2026-2036
Perilla Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Perilla Protein Market Analytics
Chinese botanical extract capacity is decoupling from legacy soy-dominant supply chains as dedicated perilla processing lines come online. Xi'an Nutraonly Bio-Tech Co., Ltd. leverages its Shanxi province extraction infrastructure to anchor concentrate supply for European nutraceutical buyers. Botanic Healthcare competes through kosher and halal-certified isolate production. Hunan Nutramax Inc. dominates domestic Chinese distribution while extending R&D partnerships with Japanese functional food laboratories.
Perilla protein denotes the albumin and globulin fraction extracted from defatted Perilla frutescens seed meal, typically yielding 50-90% protein content depending on processing intensity, with a balanced essential amino acid profile distinguished by high methionine and cysteine levels relative to other oilseed proteins. Its primary commercial purpose centers on plant-based nutrition fortification where allergen-free positioning against soy and dairy expands addressable markets. Isolate grades command premium positioning in sports nutrition and clinical formulas where protein digestibility-corrected amino acid scores determine procurement decisions. Flour and whole seed segments sustain volume throughput in Asian traditional food applications and emerging pet food formulations. Concentrate grades occupy the fastest-expanding tier as cost-sensitive food manufacturers reformulate with partial meat and dairy replacement.
FDA GRAS self-affirmation pathways and EFSA Novel Food catalog listings shape transatlantic market access timelines for perilla protein ingredients. China's SAMR food production licensing and GB standards for plant protein powders govern domestic quality benchmarks and export eligibility. South Korea's MFDS health functional food codes create a regulated premium channel for perilla-derived omega-3 and protein composite claims. Stakeholders must monitor evolving protein content labeling thresholds and allergen risk assessments as regulatory divergence between jurisdictions intensifies compliance complexity.
Market Dynamics
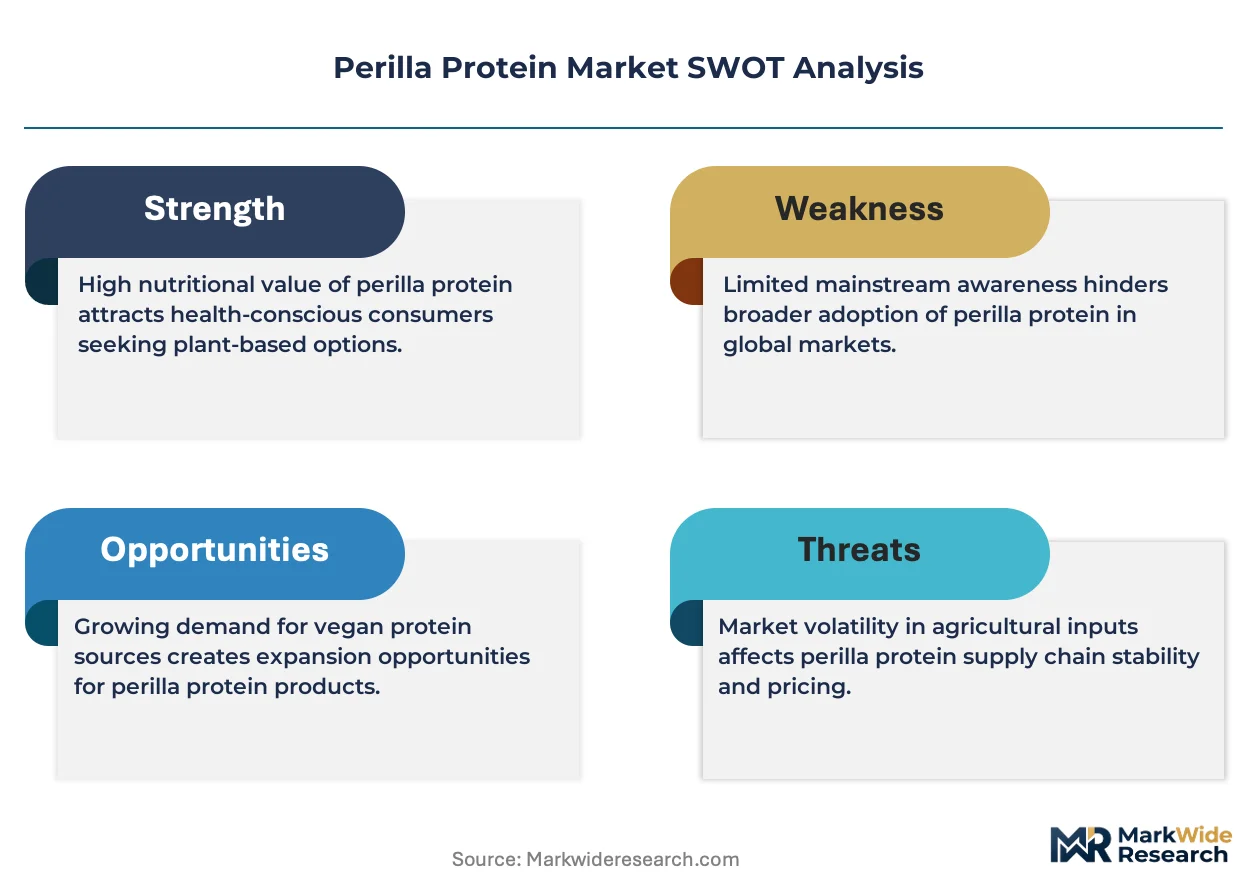
Clean-label protein sourcing is compressing procurement timelines for food manufacturers seeking allergen-free alternatives to soy and dairy isolates. Perilla protein's amino acid completeness positions it as a functional drop-in replacement where formulation flexibility commands premium pricing.
Growth Catalysts
- EU Novel Food Regulation streamlining:EFSA catalog listings for plant-derived ingredients accelerate approval timelines for German nutraceutical formulators developing omega-3 enriched supplements.
- Sports nutrition protein diversification:Clinical formula developers prioritize protein digestibility-corrected amino acid scores, expanding isolate-grade procurement for methionine-rich oilseed alternatives.
- South Korean traditional food modernization:MFDS health functional food codes create regulated premium channels for perilla-derived composite claims in functional food development.
Market Restraints
- Input cost volatility:Perilla seed oil extraction economics fluctuate with edible oil commodity cycles, squeezing meal availability for protein concentrate production.
- Supply concentration risk:Dedicated processing infrastructure clusters in Shanxi province and Hunan province, creating single-geography dependency for European export volumes.
- Regulatory friction:FDA GRAS self-affirmation pathways lack harmonization with EFSA Novel Food timelines, forcing dual-track compliance investments for transatlantic ingredient suppliers.
Strategic Opportunities
- Pet food formulation expansion:Premium companion animal nutrition brands in North America pilot perilla protein for hypoallergenic kibble applications where poultry and soy sensitivities drive ingredient substitution.
- Concentrate-grade cost positioning:Partial meat and dairy replacement in processed foods opens volume-tier procurement for 50-70% protein concentrates versus isolate premiums.
- Halal and kosher certification arbitrage:Botanic Healthcare's certified isolate production captures Middle Eastern and Israeli nutraceutical demand excluded from conventional soy supply chains.
Industry Challenges
- Specialized extraction talent scarcity:Defatted seed meal processing requires protein chemists conversant in oilseed fractionation, a skillset concentrated in legacy soy and rapeseed industries.
- Protein content labeling threshold divergence:China's GB standards, EU health claims regulation, and US FDA labeling rules create conflicting minimum thresholds for "high protein" positioning.
- Downstream integration complexity:Food manufacturers reformulating with perilla protein face sensory validation cycles for bitter compound masking and texture stabilization in finished goods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Perilla Protein Market |
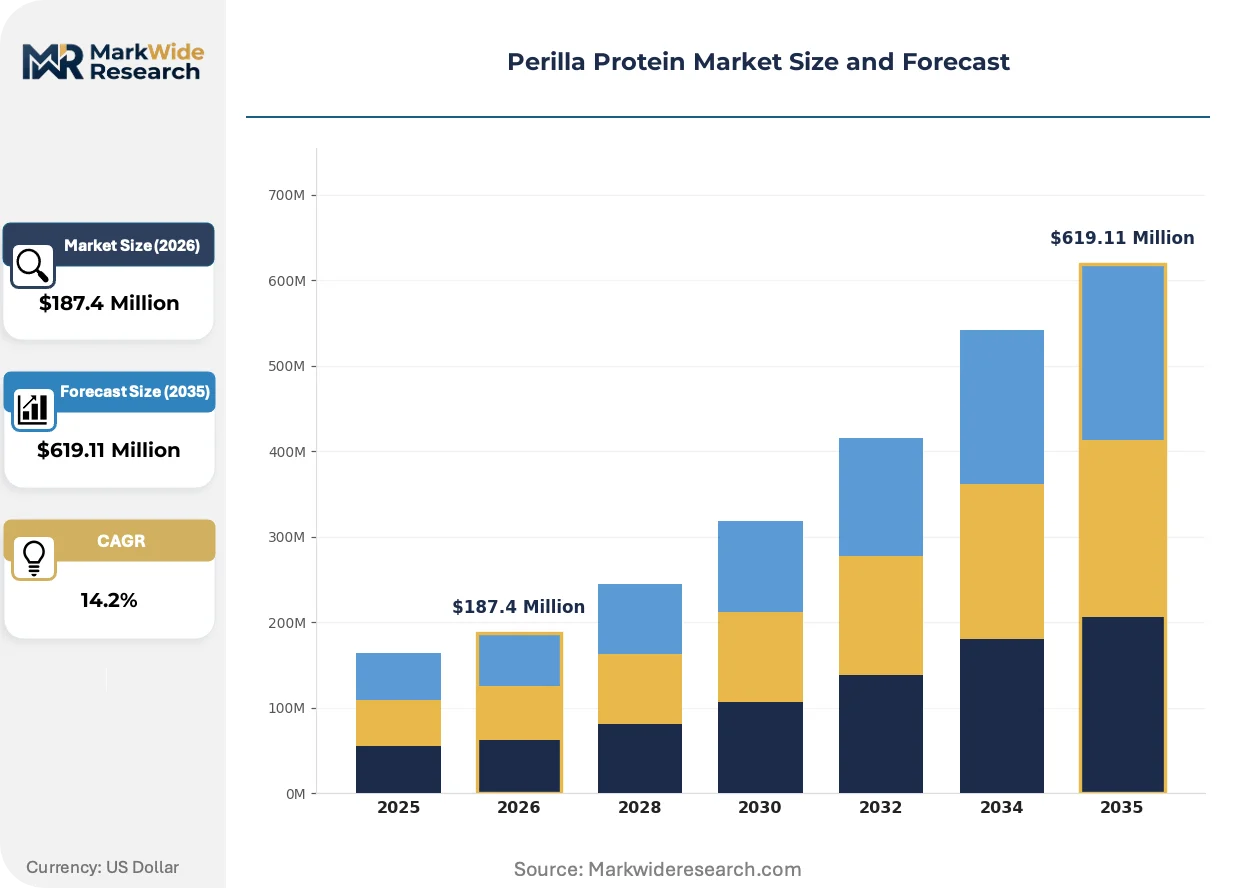
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
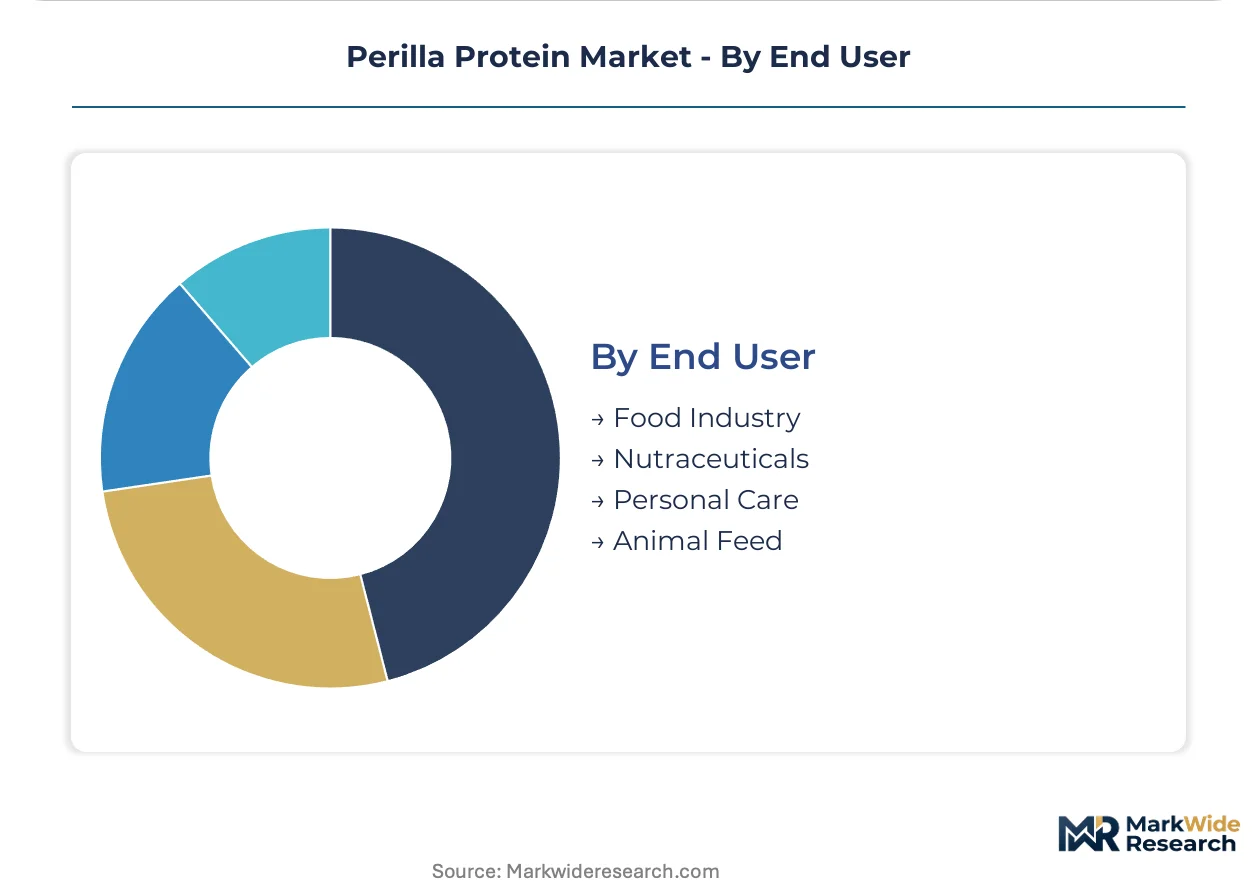
| Segmentation | Product Type: Concentrate, Isolate, Flour, Whole Seed Application: Nutritional Supplements, Food Additives, Pet Food, Cosmetics Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Health Food Outlets End User: Food Industry, Nutraceuticals, Personal Care, Animal Feed |
| Companies Covered | Xi'an Nutraonly Bio-Tech Co., Ltd., Botanic Healthcare, Botanic Innovations, Nutra Canada, Shanxi Jinjin Chemical Co., Ltd., Hebei Jiafeng Plant Oil Co., Ltd., Hunan Nutramax Inc., Shaanxi Guanjie Technology Co., Ltd., Shaanxi Jintai Biological Engineering Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Perilla Protein Market Evolving Landscape
Bioprocessing advances and regulatory convergence are reconfiguring how plant protein ingredients achieve commercial scale. Three developments dominate the current transformation window.
Membrane filtration technology is absorbing capital allocation from legacy solvent extraction methods in perilla protein concentrate production. European nutraceutical contract manufacturers deploy ceramic microfiltration systems to preserve heat-sensitive amino acid integrity. This shift is absorbing price premiums previously captured by spray-dried isolate grades.
EFSA Novel Food catalog harmonization with China's SAMR food production licensing is compressing dual-market entry timelines for ingredient suppliers. The industrial consequence is consolidated regulatory dossier preparation spanning GRAS self-affirmation and GB standard compliance simultaneously. Sports nutrition and clinical formula segments in Germany and South Korea are responding with accelerated formulation partnerships.
Direct-procurement relationships between food manufacturers and extraction facilities are displacing traditional ingredient distributor intermediaries. Large-scale bakery and meat-alternative producers in South Korea negotiate volume contracts directly with Shanxi province processors. This channel compression is most visible in clean-label reformulation projects where traceability documentation exceeds distributor capabilities.
Perilla Protein Market Segmentation
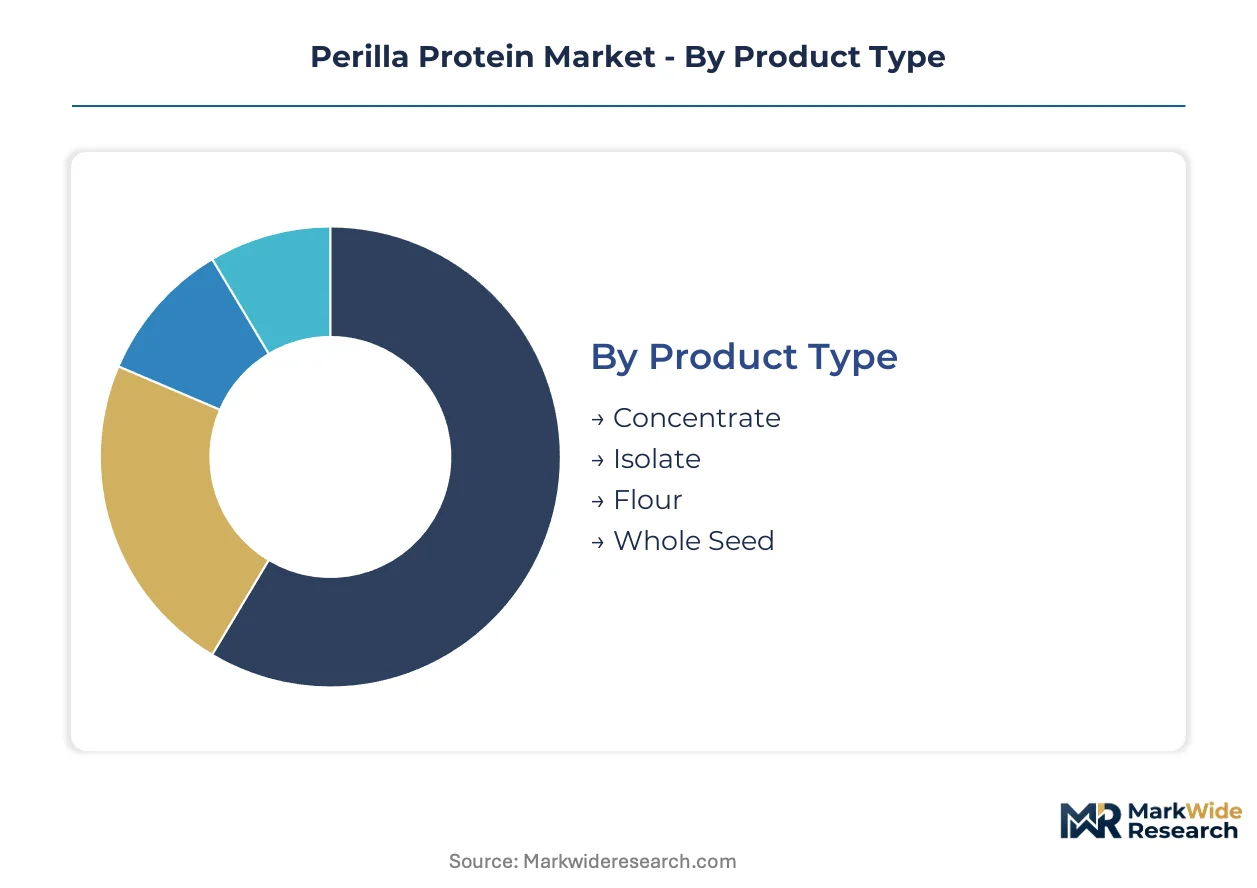
Perilla protein's commercial structure divides sharply between standalone nutritional ingredients and embedded food system components. Segmentation clarity determines procurement strategy for buyers navigating grade purity, application specificity, and channel access requirements.
Product Type:
Integration depth separates protein grades that function as standalone nutritional inputs from those embedded in complex food matrices.
- Concentrate:Defatted seed meal processed to 50-70% protein content retains functional fiber and lipid fractions for cost-sensitive meat and dairy partial replacement. South Korean bakery and meat-alternative manufacturers negotiate direct volume contracts with Shanxi province processors for reformulation projects requiring traceability documentation.
- Isolate:Refined to 90%+ protein through membrane filtration or solvent extraction, isolate grades target sports nutrition and clinical formulas where protein digestibility-corrected amino acid scores determine procurement. German nutraceutical formulators prioritize methionine-rich isolate for omega-3 enriched supplements under streamlined EFSA Novel Food pathways.
- Flour:Minimally processed whole seed meal maintains traditional food applications and emerging pet food formulations where complete nutritional matrices outweigh purity premiums.
- Whole Seed:Unfractionated perilla seed serves heritage Korean cuisine and specialty health food channels requiring intact ingredient storytelling.
Concentrate leads volumes today; isolate is gaining share fastest.
Application:
Cost tier stratification positions perilla protein across premium clinical segments down to commodity feed inputs.
- Nutritional Supplements:Capsule and powder formats leverage isolate-grade purity for methionine positioning against soy and dairy allergens. South Korea's MFDS health functional food codes create regulated premium channels for composite omega-3 and protein claims.
- Food Additives:Concentrate grades enable partial replacement in processed foods where manufacturers absorb sensory validation cycles for bitter compound masking.
- Pet Food:Hypoallergenic kibble applications in North America exploit perilla's poultry and soy sensitivity positioning for premium companion animal nutrition.
- Cosmetics:Protein hydrolysates enter topical formulations through personal care R&D pipelines in Japan and South Korea.
Nutritional supplements command highest margins; pet food is expanding most quickly.
Distribution Channel:
Customer type determines channel selection between institutional procurement and consumer-facing retail.
- Online Retail:Direct-to-consumer isolate sales bypass distributor markups for sports nutrition enthusiasts seeking allergen-free protein sourcing.
- Supermarkets:Mass-market flour and whole seed placement depends on Korean diaspora demand and clean-label trend adoption.
- Specialty Stores:Health food outlets curate premium isolate and concentrate grades for formulation-conscious consumers.
- Health Food Outlets:Professional-grade channels supply nutraceutical manufacturers and clinical formula developers with batch-certified ingredients.
Online retail captures fastest growth; supermarkets still move greatest tonnage.
End User:
Supply concentration varies dramatically across end-use sectors with divergent technical requirements and certification demands.
- Food Industry:Large-scale bakery and meat-alternative producers drive concentrate-grade volume through direct processor relationships.
- Nutraceuticals:EMA and EFSA regulatory compliance investments concentrate European demand among certified isolate suppliers.
- Personal Care:Cosmetic formulators in Japan and South Korea pilot protein hydrolysate applications with specialized extraction partners.
- Animal Feed:Pet food manufacturers represent the emerging volume tier for hypoallergenic protein diversification.
Food industry dominates procurement volumes; nutraceuticals shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's traditional food heritage drives premium perilla protein demand, while Germany's nutraceutical formulators exploit streamlined EU regulatory pathways to capture isolate-grade value.
South Korea
Domestic perilla consumption anchors functional food modernization as clean-label protein sourcing penetrates bakery and meat-alternative segments. MFDS health functional food codes create regulated premium channels for composite omega-3 and protein claims. Seoul Capital Area processors negotiate direct volume contracts with extraction facilities, compressing traditional distributor intermediaries.
Germany
Nutraceutical manufacturers prioritize methionine-rich isolate grades for sports nutrition and clinical formula applications. EFSA Novel Food catalog listings accelerate approval timelines for plant-derived ingredient formulations. Bavarian contract manufacturers deploy ceramic microfiltration systems to preserve heat-sensitive amino acid integrity in concentrate production.
China
Dedicated perilla processing infrastructure in Shanxi and Hunan provinces decouples botanical extract capacity from legacy soy-dominant supply chains. SAMR food production licensing and GB standards for plant protein powders govern domestic quality benchmarks and export eligibility. Xi'an extraction clusters anchor concentrate supply for European nutraceutical buyers through direct-procurement relationships.
United States
Pet food manufacturers pilot hypoallergenic kibble applications where poultry and soy sensitivities drive protein diversification. FDA GRAS self-affirmation pathways shape market access timelines, though lack of harmonization with EFSA Novel Food timelines forces dual-track compliance investments. Premium companion animal nutrition brands in Pacific Northwest test markets validate bitter compound masking protocols.
Japan
Functional food laboratories extend R&D partnerships with Chinese extraction facilities for protein hydrolysate development. METI standards and PMDA consultation pathways influence ingredient qualification for clinical formula segments. Osaka-based cosmetic formulators pilot topical applications through specialized personal care R&D pipelines.
Perilla Protein Market Competitive Landscape
Chinese producers anchor the volume tier; North American and European specialists hold premium positioning through certification arbitrage. Market structure concentrates around extraction infrastructure clusters with defunct seed meal processing capabilities, creating tiered competition between isolate-grade purifiers and concentrate-scale operators. Three archetypes dominate: Shanxi province infrastructure owners, kosher/halal-certified isolate specialists, and direct-procurement channel operators. Capacity expansion and strategic partnerships constitute the dominant competitive moves as players secure captive meal supply from oil extraction economics.
Within the infrastructure-owner archetype, Xi'an Nutraonly Bio-Tech Co., Ltd. and Hunan Nutramax Inc. represent the dominant extraction capacity position in Shanxi and Hunan provinces respectively. Botanic Healthcare occupies a certification-specialist position, with its company name signaling healthcare-aligned market positioning. These three entities exemplify the geographic and functional stratification shaping procurement relationships: Chinese infrastructure anchors concentrate supply, while certification holders capture premium isolate demand from regulated nutraceutical channels.
| Leading Market Players |
|---|
| Xi'an Nutraonly Bio-Tech Co., Ltd. |
| Botanic Healthcare |
| Botanic Innovations |
| Nutra Canada |
| Shanxi Jinjin Chemical Co., Ltd. |
| Hebei Jiafeng Plant Oil Co., Ltd. |
| Hunan Nutramax Inc. |
| Shaanxi Guanjie Technology Co., Ltd. |
| Shaanxi Jintai Biological Engineering Co., Ltd. |
| Others |
Value Network & Pricing Analysis
EU Novel Food Regulation compliance mandates gate qualified supply access and premium-tier pricing power for perilla protein isolate, forcing ingredient suppliers to absorb dual-track certification costs or forfeit European nutraceutical contracts. Shanxi province extraction clusters leverage membrane filtration investments to defend concentrate-grade margins against ceramic microfiltration displacement from Bavarian contract manufacturers.
Pricing Analysis
Capacity additions in Shanxi province are reshaping price floors for concentrate grades as dedicated perilla processing lines decouple from legacy soy-dominant infrastructure. Pricing stratifies across isolate, concentrate, and flour tiers where kosher and halal certification premiums capture Middle Eastern and Israeli nutraceutical demand excluded from conventional supply chains. Cost compression in concentrate segments intensifies because South Korean bakery and meat-alternative manufacturers negotiate direct volume contracts with extraction facilities. Food industry buyers exhibit highest price sensitivity; clinical formula developers in Germany show lowest sensitivity due to protein digestibility-corrected amino acid score requirements.
Supply Chain Analysis
China's SAMR food production licensing and GB standards for plant protein powders are reshaping sourcing requirements for export-eligible concentrate supply. Raw material flows draw from Shanxi and Hunan province perilla seed oil extraction economics, with defatted meal availability tethered to edible oil commodity cycles. Single-geography dependency for European export volumes creates structural vulnerability to regional logistics disruption or regulatory restriction. Distribution runs through direct-procurement relationships between large-scale food manufacturers and extraction facilities, displacing traditional ingredient distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EFSA Novel Food catalog harmonization with China's SAMR licensing compresses dual-market entry timelines for suppliers capable of consolidated regulatory dossier preparation.
For Market Incumbents: To counter membrane filtration technology absorbing price premiums from spray-dried isolate grades, Xi'an Nutraonly Bio-Tech Co., Ltd. and Hunan Nutramax Inc. should deepen backward integration into captive perilla seed oil extraction economics and secure kosher/halal certification arbitrage for Middle Eastern nutraceutical channels. Capacity addition in Shanxi province extraction infrastructure anchors volume defense against European ceramic microfiltration displacement. For New Entrants and Emerging Players: The premium-to-economy tier price-point gap in isolate grades creates entry opportunity for certified specialists targeting South Korea's MFDS health functional food codes and North American pet food hypoallergenic formulations. Pet food manufacturers represent the most penetrable segment due to poultry and soy sensitivity substitution demand. Go-to-market execution should prioritize direct-procurement channel relationships with Pacific Northwest premium companion animal nutrition brands. For Investors and Strategic Acquirers: Roll-up economics work for kosher/halal-certified isolate specialists because regulatory divergence between FDA GRAS self-affirmation and EFSA Novel Food timelines forces dual-track compliance investments that fragment the vendor base. Long-term viability centers on extraction infrastructure owners with defunct seed meal processing capabilities and established European nutraceutical buyer relationships. The signal to watch is EFSA catalog expansion accelerating approval timelines for German sports nutrition and clinical formula segments.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Technology Deployment | Ceramic microfiltration systems preserve heat-sensitive amino acid integrity for German nutraceutical formulators. |
| Dual-Certification Investment (Kosher/Halal) | Botanic Healthcare's certified isolate production captures Middle Eastern and Israeli demand excluded from soy chains. |
| Direct-Procurement Channel Establishment | Seoul Capital Area processors compress distributor intermediaries through volume contracts with Shanxi extraction facilities. |
| Regulatory Dossier Consolidation | Simultaneous GRAS self-affirmation and GB standard compliance accelerates transatlantic market access timelines. |
| Pet Food Formulation Partnerships | North American premium companion animal nutrition brands pilot hypoallergenic kibble applications for protein diversification. |
Research Methodology
Multiple input streams — primary interviews with extraction facility technical directors, nutraceutical formulation scientists, and pet food procurement managers; secondary validation through SAMR food production licensing records, EFSA Novel Food catalog listings, and customs/trade data — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured membrane filtration technology adoption patterns and direct-procurement relationship formation across South Korean and German buyer clusters. Secondary sources included FDA GRAS notification databases, MFDS health functional food code filings, and perilla seed oil extraction economics data from Shanxi and Hunan provincial industrial reports.
Data-stream reconciliation across product type, application, distribution channel, and end-user segmentation dimensions anchored the analytical framework throughout the projection horizon. CAGRs were derived from modeled volume and value outputs reflecting protein content labeling threshold divergence and regulatory friction intensity. Industry-specific forecast inputs incorporated EFSA Novel Food timeline acceleration assumptions and pet food hypoallergenic formulation adoption curves.
The model assumes a particular technology adoption path; alternative pathways for solvent extraction displacement by membrane filtration would alter the outlook for isolate-grade premium capture. Forecasts reflect assumptions regarding EU-China regulatory convergence and perilla seed oil commodity cycle stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Biotechnology
Asia Pacific Eubiotics Market
Food Biotechnology
Trypsin Market
Food Biotechnology
Fruit and Vegetable-Derived Enzymes Market
Food Biotechnology
Beta Lactoglobulin Protein Market
Food Biotechnology
Biopreservation Market
Food Biotechnology
Cultured Meat Market
Food Biotechnology
Beta-Propeller Phytases Market
Food Biotechnology
Global Food Biotechnology Market
Food Biotechnology
Hemoglobin Feed Market
Food Biotechnology
Global GMO Testing Market
Food Biotechnology
Salmon Polynucleotide (PN) Market
Food Biotechnology
South America Feed Prebiotics Market
Food Biotechnology
Prebiotics Market
Food Biotechnology
Research-Grade Proteins Market
Food Biotechnology
Papain Market
Food Biotechnology
Lupin Protein Market