
 Global GMO Testing Market | 2026-2036
Global GMO Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Global GMO Testing Market Foresight
Multi-source outsourcing of GMO testing is restructuring supply relationships across the agricultural value chain. Eurofins Scientific SE leverages its decentralized laboratory footprint to anchor regional compliance workflows. SGS SA competes through integrated sampling-to-certificate services that dominate port-of-entry workflows. Thermo Fisher Scientific Inc. differentiates by sustaining R&D intensity in next-generation sequencing platforms.
Genetically modified organism testing encompasses molecular analytical protocols designed to detect, identify, and quantify transgenic DNA sequences or expressed proteins in biological matrices, employing threshold sensitivities typically calibrated to 0.1% mass fraction for adventitious presence. The primary commercial purpose centers on verifying regulatory compliance for labeling, seed purity, and cross-contamination thresholds in commodity trade. Polymerase chain reaction methods occupy the largest volume share due to established ISO accreditation pathways and cost structures suited to high-throughput grain elevators. Next generation sequencing represents the fastest-expanding test type as multiplex detection capabilities reduce per-event marginal costs for complex stacked-trait varieties. DNA microarray applications concentrate in research laboratories where parallel screening of hundreds of genetic elements justifies platform capital investment.
The EPA regulates pesticidal traits in the United States through mandatory resistance management plans that cascade into seed testing obligations. EFSA and the EU Green Deal jointly enforce zero-tolerance thresholds for unapproved events, compelling exporters to maintain dual-certified laboratory networks. Seed companies and food testing labs must monitor evolving event-authorization calendars and synchronize assay development timelines with regulatory approval sequences.
Market Dynamics
Stacked-trait soybean varieties are proliferating faster than assay development cycles, forcing laboratories to multiplex detection protocols or risk losing export certification contracts in Brazil and the European Union.
Growth Catalysts
- EU Green Deal traceability mandates:The updated compliance thresholds for imported grain require event-specific documentation, compelling exporters to maintain certified testing relationships.
- Brazilian soybean export certification:ANVISA and MAPA now mandate multi-event screening for all bulk shipments, creating captive demand at port-of-entry laboratories.
- Next-generation sequencing platforms:Multiplex detection capabilities reduce per-event marginal costs, enabling high-throughput screening of complex stacked-trait varieties.
Market Restraints
- Reference material scarcity:Certified reference materials for novel stacked events command premiums and face six-month procurement lead times.
- Laboratory concentration in São Paulo and Rotterdam:Dual-hub dependency creates bottlenecks during peak harvest windows.
- PCR kit input volatility:Polymerase and fluorescent probe supply chains remain exposed to bioreagent manufacturing disruptions.
Strategic Opportunities
- India seed import regulations:FSSAI and CDSCO are harmonizing GMO detection requirements for cotton and soybean imports, opening laboratory accreditation demand.
- Digital chain-of-custody systems:Blockchain-integrated sampling workflows are displacing paper-based certificate transfers at Argentine grain elevators.
- EPA resistance management plans:Mandatory refuge monitoring creates recurring testing obligations for seed companies across corn-growing counties.
Industry Challenges
- Bioinformatics skill scarcity:NGS data interpretation requires computational biology expertise that outpaces university pipeline output.
- ISO 17025 accreditation timelines:Eighteen-month certification cycles delay market entry for emerging laboratory entrants.
- Legacy LIMS integration:Grain elevator operators face workflow friction when connecting new detection platforms to established inventory management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global GMO Testing Market |
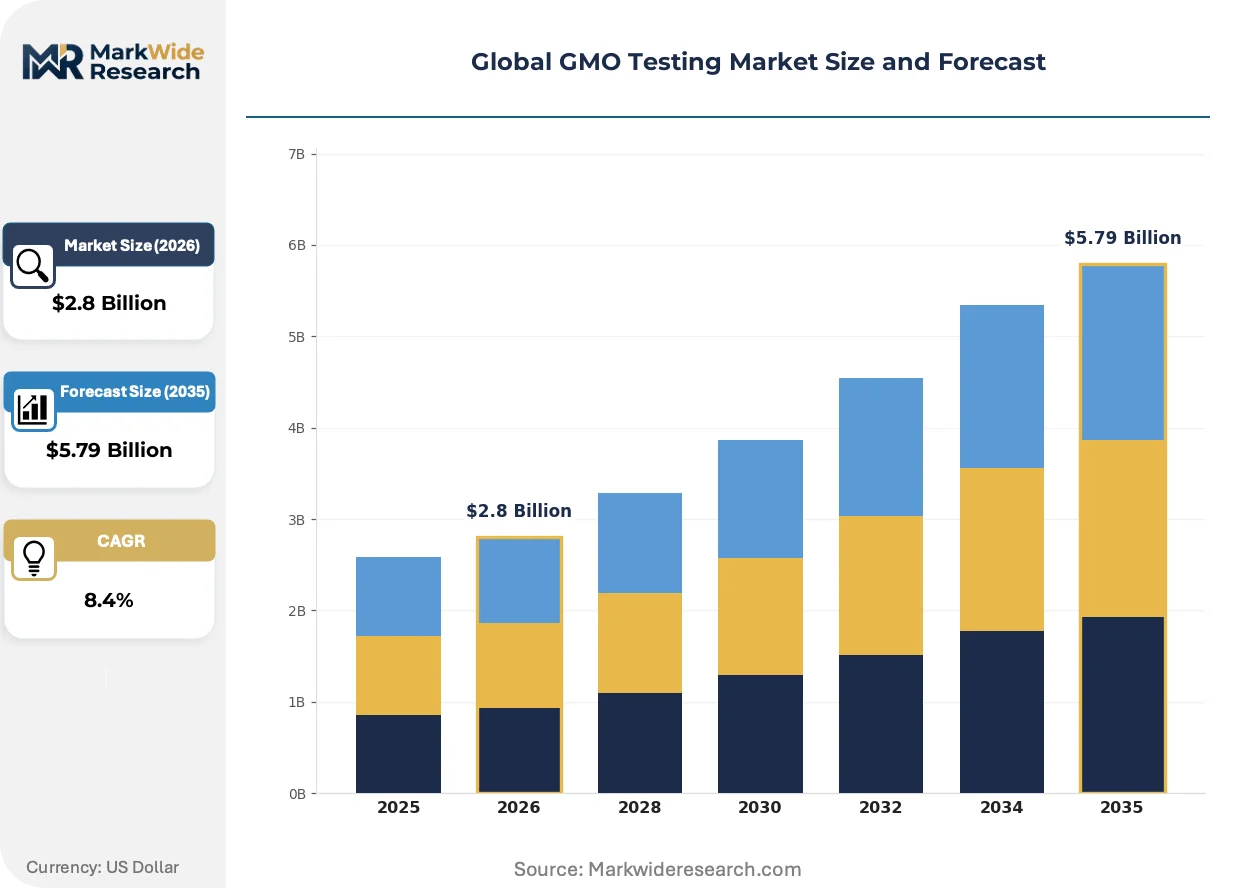
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Polymerase Chain Reaction, Enzyme-Linked Immunosorbent Assay, DNA Microarray, Southern Blotting, Next Generation Sequencing Sample Type: Corn, Soybean, Cotton, Canola, Sugar Beet, Papaya End User: Research Laboratories, Food Testing Labs, Regulatory Agencies, Seed Companies, Universities Application: Labeling Compliance, Crop Quality Control, Risk Assessment, Food Safety Testing, Trade Facilitation |
| Companies Covered | ALS Limited, Bio-Rad Laboratories Inc., Eurofins Scientific SE, QIAGEN N.V., Thermo Fisher Scientific Inc., SGS SA, Mérieux NutriSciences Corp., Neogen Corporation, Intertek Group plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global GMO Testing Market Shifts & Advancements
Detection methodology is bifurcating between high-throughput commodity screening and precision event identification, with platform choice increasingly dictated by trait complexity rather than sample volume alone.
Next-generation sequencing is rewriting the economics of stacked-trait verification. Seed companies in Iowa and Illinois are adopting NGS workflows for regulatory submission packages. The technology is compressing assay development timelines from twelve months to six weeks for novel events.
EFSA zero-tolerance enforcement for unapproved events is restructuring laboratory network geography. Exporters to the European Union must now maintain dual-certified facilities in both origin and destination jurisdictions. Brazilian grain traders are responding by pre-positioning mobile testing units at interior elevators before barge consolidation.
Buyer consolidation among multinational grain traders is concentrating procurement decisions at fewer headquarters locations. Long-term framework agreements are displacing spot-testing contracts at major port terminals. This pattern is most visible in Santos and Paranaguá, where three traders now account for the majority of certified volume.
Global GMO Testing Market Segmentation
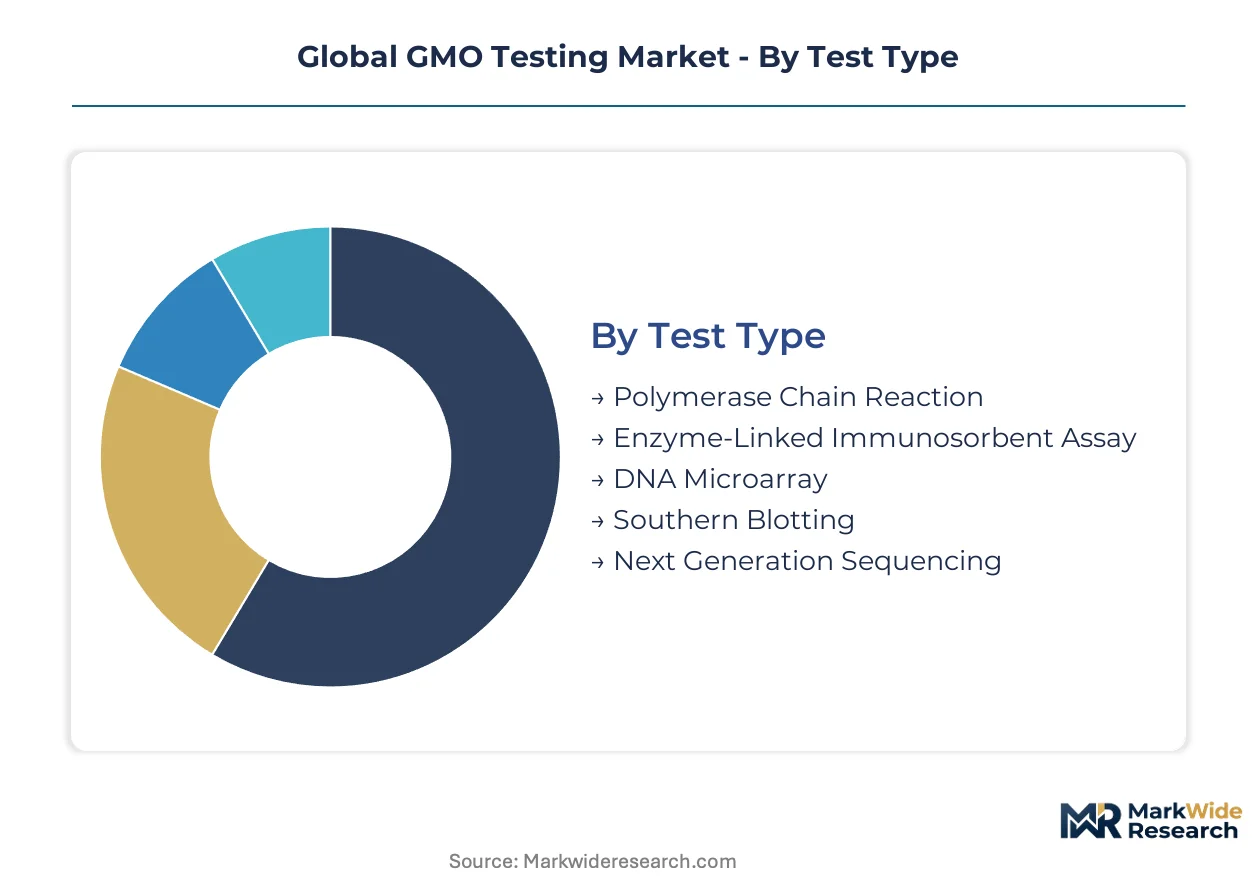
Segmentation in GMO testing maps directly to regulatory pathway requirements and commodity trade flows. Test methodology selection determines accreditation eligibility, while sample type and end-user concentration shape laboratory infrastructure investment decisions across major grain-exporting regions.
Test Type:
Standardization dominates at the high-throughput commodity tier, whereas customization intensity escalates with trait complexity and regulatory stringency.
- Polymerase Chain Reaction:Amplifies specific DNA sequences using Taq polymerase and fluorescent probe chemistries, achieving detection thresholds at 0.1% mass fraction. Demand concentrates in Brazilian port laboratories and US grain elevators where ISO 17025 accreditation pathways are mature and per-sample economics favor high-volume workflows.
- Next Generation Sequencing:Enables simultaneous detection of hundreds of genetic events through massively parallel sequencing, eliminating sequential assay development for novel stacked-trait varieties. Seed companies in Iowa and Illinois are adopting NGS for regulatory submission packages as EFSA zero-tolerance enforcement tightens documentation requirements for EU-bound shipments.
- Enzyme-Linked Immunosorbent Assay:Detects expressed transgenic proteins using antibody-antigen binding, deployed where rapid field screening precedes laboratory confirmation.
- DNA Microarray:Supports parallel screening of genetic elements in research settings requiring broad-spectrum event surveillance.
- Southern Blotting:Provides confirmatory identification of transgene insertion sites for regulatory dossier preparation.
Most installed capacity flows through Polymerase Chain Reaction. Expansion is steepest in Next Generation Sequencing.
Sample Type:
Volume concentration tracks global commodity export corridors, with regulatory calendar synchronization driving testing intensity variation across crop categories.
- Soybean:Stacked-trait varieties now dominate planted area in Brazil and Argentina, mandating multi-event screening protocols for ANVISA and MAPA export certification. Rotterdam and Santos port laboratories have expanded soybean-specific throughput capacity to match harvest window compression.
- Corn:EPA resistance management plans mandate refuge monitoring across Iowa, Illinois, and Nebraska counties, creating recurring testing obligations for seed companies. Trait complexity in corn exceeds soybean, with some varieties carrying eight or more stacked events.
- Cotton:Indian import regulations through FSSAI and CDSCO are harmonizing detection requirements for transgenic varieties, opening laboratory accreditation demand in Mumbai and Ahmedabad.
- Canola:Canadian export certification to EU and Chinese markets drives testing at Vancouver and Prince Rupert terminals.
- Sugar Beet:Herbicide-tolerant varieties require event-specific documentation for EU Green Deal compliance.
- Papaya:Virus-resistant transgenic varieties concentrate testing demand in Hawaiian export channels.
Soybean and corn together absorb the majority of laboratory throughput. Cotton is gaining share fastest as Indian import regulations mature.
End User:
Procurement authority concentrates at headquarters level for multinational traders, while seed companies maintain captive testing networks for resistance management compliance.
- Food Testing Labs:Eurofins and SGS operate decentralized networks anchored to port-of-entry workflows, with long-term framework agreements displacing spot contracts at Santos and Paranaguá.
- Seed Companies:Bayer and Corteva maintain in-house PCR capacity for EPA-mandated refuge monitoring, supplemented by third-party NGS for novel event characterization.
- Research Laboratories:DNA microarray and NGS platforms justify capital investment where parallel screening of hundreds of genetic elements supports trait discovery programs.
- Regulatory Agencies:ANVISA, MAPA, and EFSA operate reference laboratories for assay validation and dispute resolution.
- Universities:Support method development and bioinformatics training pipelines to address computational biology skill scarcity.
Food Testing Labs command the largest share of external service procurement. Seed Companies are expanding captive NGS capacity most aggressively.
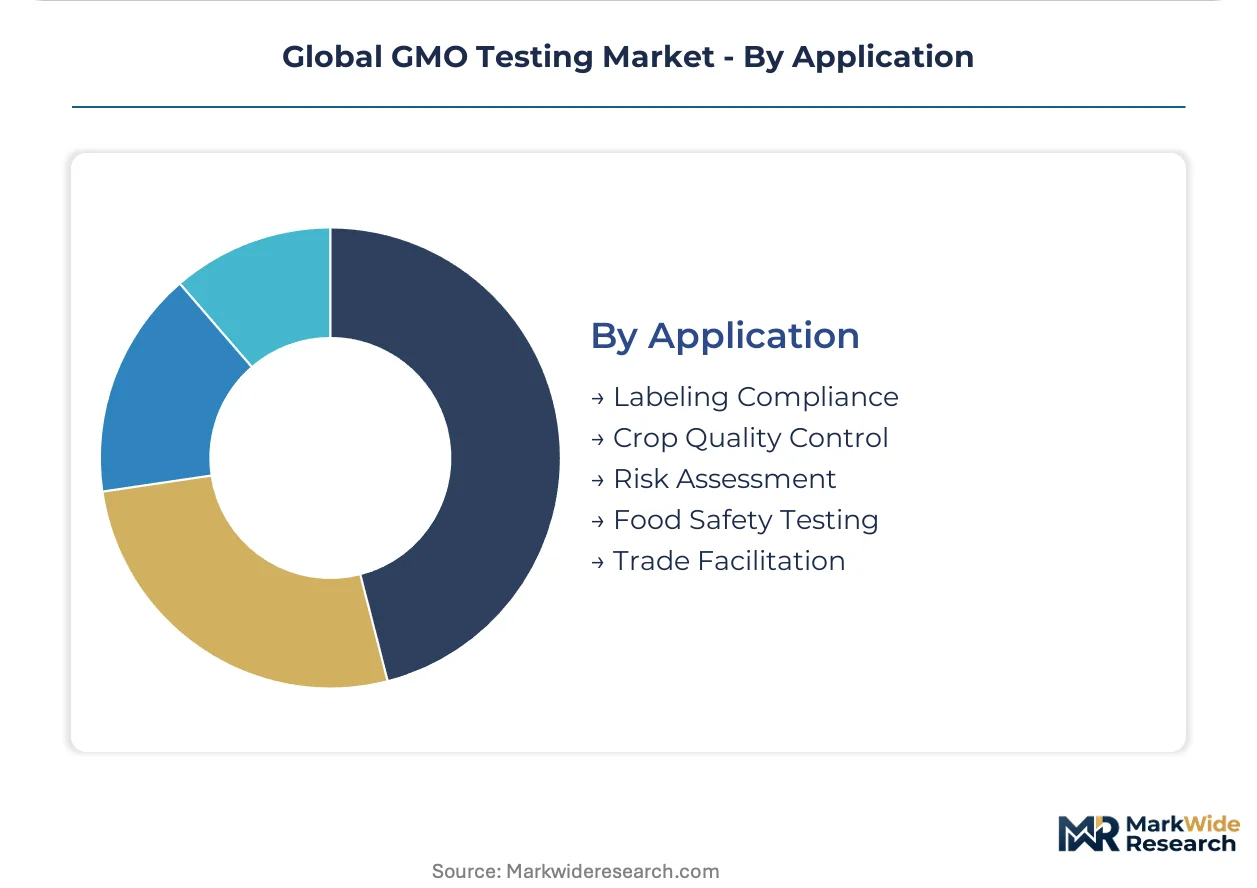
Application:
Regulatory mandate intensity varies by jurisdiction, with EU Green Deal traceability requirements imposing the strictest documentation burden on exporters.
- Labeling Compliance:EFSA enforces zero-tolerance thresholds for unapproved events, compelling dual-certified laboratory networks in both origin and destination jurisdictions. Brazilian grain traders pre-position mobile testing units at interior elevators before barge consolidation.
- Trade Facilitation:ANVISA and MAPA multi-event screening mandates for bulk soybean shipments create captive demand at Brazilian port laboratories, with certification delays triggering demurrage costs.
- Crop Quality Control:Seed purity verification supports identity preservation systems for non-GMO premium channels.
- Risk Assessment:Novel trait environmental impact studies require event-specific detection protocols for regulatory submission.
- Food Safety Testing:Allergenicity and toxicity screening of expressed proteins supports novel food authorizations.
Labeling Compliance drives the largest share of recurring testing volume. Trade Facilitation is expanding most quickly as Brazilian export certification requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rotterdam port laboratories anchor European compliance workflows for transgenic grain imports. São Paulo and Santos form the dominant South American testing cluster. Mumbai and Chicago concentrate specialized seed certification capacity.
Brazil
ANVISA and MAPA mandates for multi-event soybean screening drive port laboratory expansion. The updated export certification calendar compresses testing windows during harvest peaks. Santos and Paranaguá terminals now host mobile testing units pre-positioned before barge consolidation.
United States
EPA resistance management plans cascade into recurring refuge monitoring obligations across corn-growing counties. Seed companies maintain captive PCR capacity in Iowa and Illinois for regulatory submission packages. Chicago and Des Moines laboratories anchor the Midwest grain elevator testing network.
Germany
EFSA zero-tolerance enforcement for unapproved events compels dual-certified laboratory relationships. The EU Green Deal traceability mandates tighten documentation thresholds for imported grain. Hamburg port facilities coordinate with Rotterdam for transshipment certification workflows.
India
FSSAI and CDSCO harmonization of cotton and soybean import detection requirements opens accreditation demand. Seed import regulations now mandate event-specific documentation for transgenic varieties. Mumbai and Ahmedabad laboratories expand capacity to serve growing certification volume.
Netherlands
Rotterdam's position as Europe's largest grain port concentrates GMO testing infrastructure for EU-bound shipments. EFSA reference laboratory functions support dispute resolution across member states. The Randstad cluster integrates sampling-to-certificate services for multinational grain traders.
Global GMO Testing Market Competitive Landscape
Global majors compete with regional champions across certification workflow integration. The market structure concentrates around three tiers: multinational testing networks with port-of-entry dominance, specialized seed company captive laboratories, and emerging regional accreditation providers. Strategic archetypes include decentralized laboratory footprint operators, integrated sampling-to-certificate service providers, and platform technology specialists. Competitive moves center on long-term framework agreement displacement of spot contracts and NGS platform R&D intensity.
Within the multinational network tier, Eurofins Scientific SE and SGS SA exemplify divergent geographic anchoring strategies. Eurofins leverages decentralized laboratory positioning to capture regional compliance workflows. SGS dominates integrated sampling-to-certificate services at major port terminals. Thermo Fisher Scientific Inc. occupies the platform technology specialist position, sustaining instrument and reagent supply relationships across laboratory networks. These three represent distinct competitive vectors without implying specific market share or revenue figures.
| Leading Market Players |
|---|
| ALS Limited |
| Bio-Rad Laboratories Inc. |
| Eurofins Scientific SE |
| QIAGEN N.V. |
| Thermo Fisher Scientific Inc. |
| SGS SA |
| Mérieux NutriSciences Corp. |
| Neogen Corporation |
| Intertek Group plc |
| Others |
Supply & Pricing Matrix
Bioinformatics specialists in the Netherlands and Germany command wage premiums that compress pricing spreads between premium NGS workflows and standard PCR screening tiers. Labor-cost differentials between Rotterdam-certified analysts and São Paulo-based technicians create a three-tier pricing structure across premium, standard, and economy levels, with port-of-entry laboratories capturing margin advantages during harvest compression windows.
Pricing Analysis
Input-cost pass-through from bioreagent supply chains shapes contract structures across testing tiers. Per-sample transactional pricing dominates Brazilian port laboratories, with differentiation driven by ISO 17025 accreditation grade and volume scale commitments. Cost compression in economy-tier PCR screening is intensifying because fluorescent probe suppliers face manufacturing disruptions. Multinational grain traders exhibit lowest price sensitivity due to demurrage cost exposure, while regional seed distributors negotiate aggressively on per-event marginal rates.
Supply Chain Analysis
Certification and qualification gating through ISO 17025 accreditation timelines restricts viable supplier pools to established networks. Reagent manufacturing concentrates in Germany, the United States, and Singapore. Laboratory consumables draw from specialized polymerase suppliers, certified reference material producers, and sequencing platform OEMs. Single-source vulnerability persists for novel stacked-event reference materials. Distribution runs through port-terminal sampling workflows anchored to Santos, Rotterdam, and Vancouver consolidation points.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
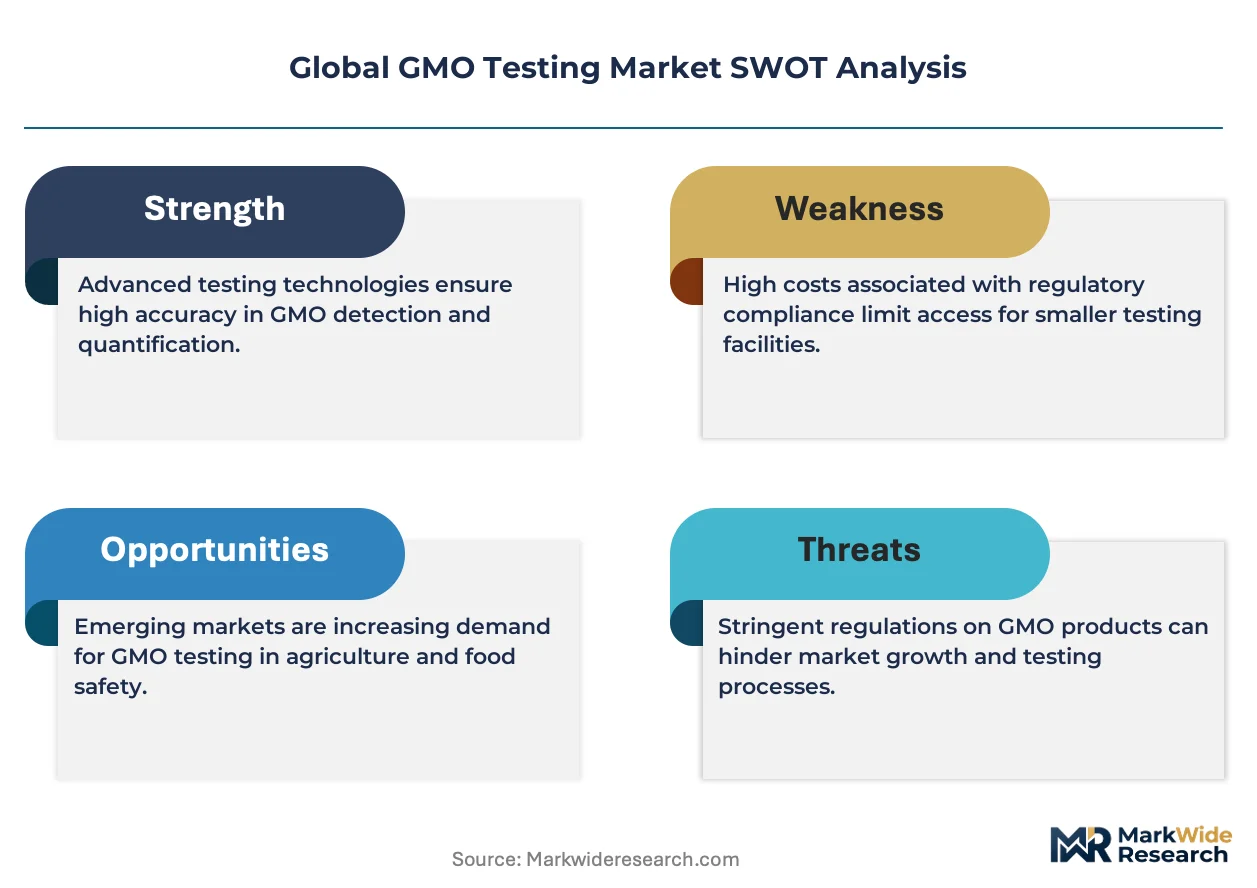
This market represents a late-cycle quality story as EU Green Deal traceability mandates shift procurement criteria toward dual-certified laboratory relationships over spot-testing economics.
For Market Incumbents: Deploy backward integration into reference material production to secure supply against six-month procurement lead times. Eurofins and SGS should expand mobile testing unit fleets at interior Brazilian elevators before barge consolidation. Captive NGS platform development counters Thermo Fisher's instrument-supply leverage. Defensive patent positioning around multiplex assay chemistries protects against emerging regional accreditation providers. For New Entrants and Emerging Players: Port-terminal sampling contractors represent the most accessible channel partner type for laboratory accreditation demand. Target Indian FSSAI and CDSCO harmonization timelines for cotton and soybean import certification. White-space exists in blockchain-integrated chain-of-custody systems displacing paper-based certificate transfers at Argentine grain elevators. Go-to-market through seed company captive outsourcing contracts for EPA-mandated refuge monitoring. For Investors and Strategic Acquirers: Valuations sit cheapest among regional accreditation providers with incomplete ISO 17025 certification timelines. Long-term viability over the projection horizon favors laboratories with dual-jurisdiction certification footprints serving EU-bound export corridors. Acquisition targets include bioinformatics-specialist firms addressing computational biology skill scarcity. The signal to watch is ANVISA and MAPA expansion of multi-event screening mandates beyond soybean into corn and cotton export channels.| Strategic Initiative | Industry Significance |
|---|---|
| NGS Platform R&D Intensity | Thermo Fisher sustains instrument supply relationships across laboratory networks. |
| Mobile Testing Unit Pre-positioning | Brazilian grain traders deploy units at interior elevators before barge consolidation. |
| Dual-Certification Network Expansion | Eurofins captures EFSA zero-tolerance enforcement workflows for EU-bound shipments. |
| Blockchain Chain-of-Custody Integration | Argentine grain elevators displace paper-based certificate transfers. |
| Reference Material Backward Integration | Laboratories secure supply against novel stacked-event procurement lead times. |
Research Methodology
Direct dialogue with GMO testing laboratory directors, seed company regulatory affairs managers, grain trader procurement leads, and bioinformatics platform engineers grounded qualitative insights. Secondary validation drew from EFSA guidance documents, ANVISA export certification bulletins, ISO 17025 accreditation registries, and EPA resistance management plan filings. Bottom-up and top-down triangulation reconciled laboratory throughput estimates with commodity trade flow data.
Segment-level projections across test type, sample type, end user, and application dimensions anchored the analytical framework throughout the forecast period. CAGRs were derived from regression analysis against regulatory calendar synchronization and stacked-trait variety approval trajectories. Industry-specific forecast inputs included EPA resistance management plan compliance rates and Brazilian harvest window compression patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EFSA event-authorization calendar shifts and bioreagent supply chain disruptions. A model refresh is warranted upon material change in ANVISA and MAPA export certification mandate scope.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Biotechnology
Asia Pacific Eubiotics Market
Food Biotechnology
Brown Algae Protein Market
Food Biotechnology
Biopreservation Market
Food Biotechnology
Lupin Protein Market
Food Biotechnology
Research-Grade Proteins Market
Food Biotechnology
Global Food Biotechnology Market
Food Biotechnology
Colostrum Market
Food Biotechnology
Chlorella Market
Food Biotechnology
Genistein Market
Food Biotechnology
Perilla Protein Market
Food Biotechnology
Fruit and Vegetable-Derived Enzymes Market
Food Biotechnology
Global Feed Enzymes Market
Food Biotechnology
Biotech Flavors Market
Food Biotechnology
Phycocyanin Market
Food Biotechnology
Pullulanase Market
Food Biotechnology
Carbohydrate Enzyme Preparation Market