
 Pullulanase Market | 2026-2036
Pullulanase Market Size, Share, and Industry Trends Forecast 2026-2036
Pullulanase Market Outlook
The food industry is pivoting toward higher-purity starch derivatives for clean-label applications, pulling pullulanase demand upward. Novozymes A/S leverages its global fermentation infrastructure to serve multinational food manufacturers. Shandong Longda Bio-Products Co., Ltd. anchors Chinese domestic supply with cost-competitive powder formulations. Amano Enzyme differentiates through specialized brewing-grade enzymes for craft and industrial beer segments.
Pullulanase is a debranching enzyme that hydrolyzes alpha-1,6-glycosidic linkages in pullulan, amylopectin, and related polysaccharides, typically operating at temperatures between 50°C and 65°C with pH optima near 5.0 to 6.0. Its primary industrial purpose is to improve starch conversion efficiency in glucose syrup production and to enhance fermentable sugar yields in brewing and bioethanol applications. Liquid form products dominate volume due to ease of dosing in continuous processing, while powder form commands premium positioning for long-haul distribution and tropical climates. The starch processing application generates the deepest margin pools, whereas biotechnology end-use is expanding fastest as cell-culture media formulations adopt plant-derived enzymatic inputs.
Food-grade enzyme standards from the FDA, EFSA safety evaluations under the EU Food Improvement Agent regulation, and China's national food safety GB standards collectively shape product registration pathways and manufacturing facility certifications. REACH compliance in Europe and EPA biotechnology oversight in the United States add compliance layers that filter out smaller producers. Stakeholders must monitor evolving enzyme labeling requirements and carbon-intensity disclosures that are beginning to influence procurement decisions in multinational food chains.
Market Dynamics
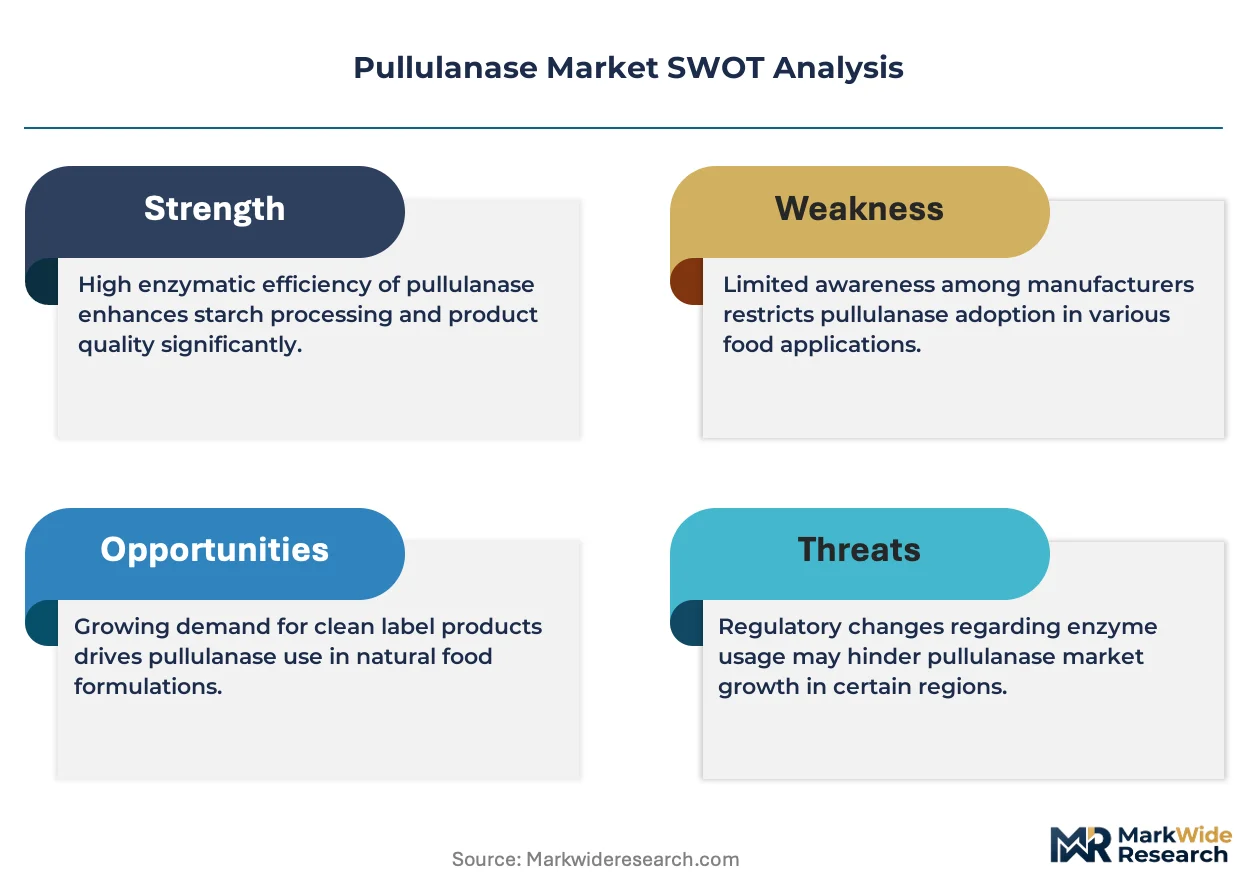
Enzymatic hydrolysis technology improvements are compressing production costs while starch processors demand higher-purity derivatives, creating a structural squeeze between input efficiency and output quality specifications.
Growth Catalysts
- Clean-label starch derivatives:Food manufacturers reformulate products to eliminate chemical modification labels, pulling pullulanase demand upward for enzymatic starch processing.
- China's national food safety GB standards:Stricter domestic enzyme certification requirements are consolidating supply toward certified producers with compliant fermentation infrastructure.
- Thermostable enzyme engineering:Protein engineering advances are extending operational temperature windows, reducing cooling costs in continuous glucose syrup production.
Market Restraints
- Fermentation input volatility:Corn steep liquor and yeast extract prices fluctuate with agricultural commodity cycles, squeezing margin predictability for enzyme manufacturers.
- REACH compliance layering:European chemical registration requirements impose documentation burdens that filter out smaller enzyme producers from EU market access.
- Acid hydrolysis substitution:Mineral acid processes retain cost advantages in price-sensitive starch processing segments, capping enzymatic penetration in emerging economies.
Strategic Opportunities
- Biotechnology cell-culture media:Plant-derived enzymatic inputs are displacing animal-origin components in biopharmaceutical manufacturing, opening premium positioning for food-grade pullulanase.
- India FSSAI enzyme regulations:New food safety standards for industrial enzymes create first-mover advantages for certified suppliers in a nascent regulatory framework.
- Continuous processing integration:Immobilized enzyme systems paired with membrane filtration are enabling closed-loop starch conversion with reduced water consumption.
Industry Challenges
- Fermentation scale-up expertise:Industrial microbiology talent scarcity constrains capacity expansion timelines for mid-tier enzyme producers.
- Dual carbon compliance documentation:China's MEE carbon-intensity disclosure requirements demand new data infrastructure that many facilities lack.
- Cross-border certification reciprocity:Non-recognition between FDA, EFSA, and GB standards forces redundant safety studies, extending product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pullulanase Market |
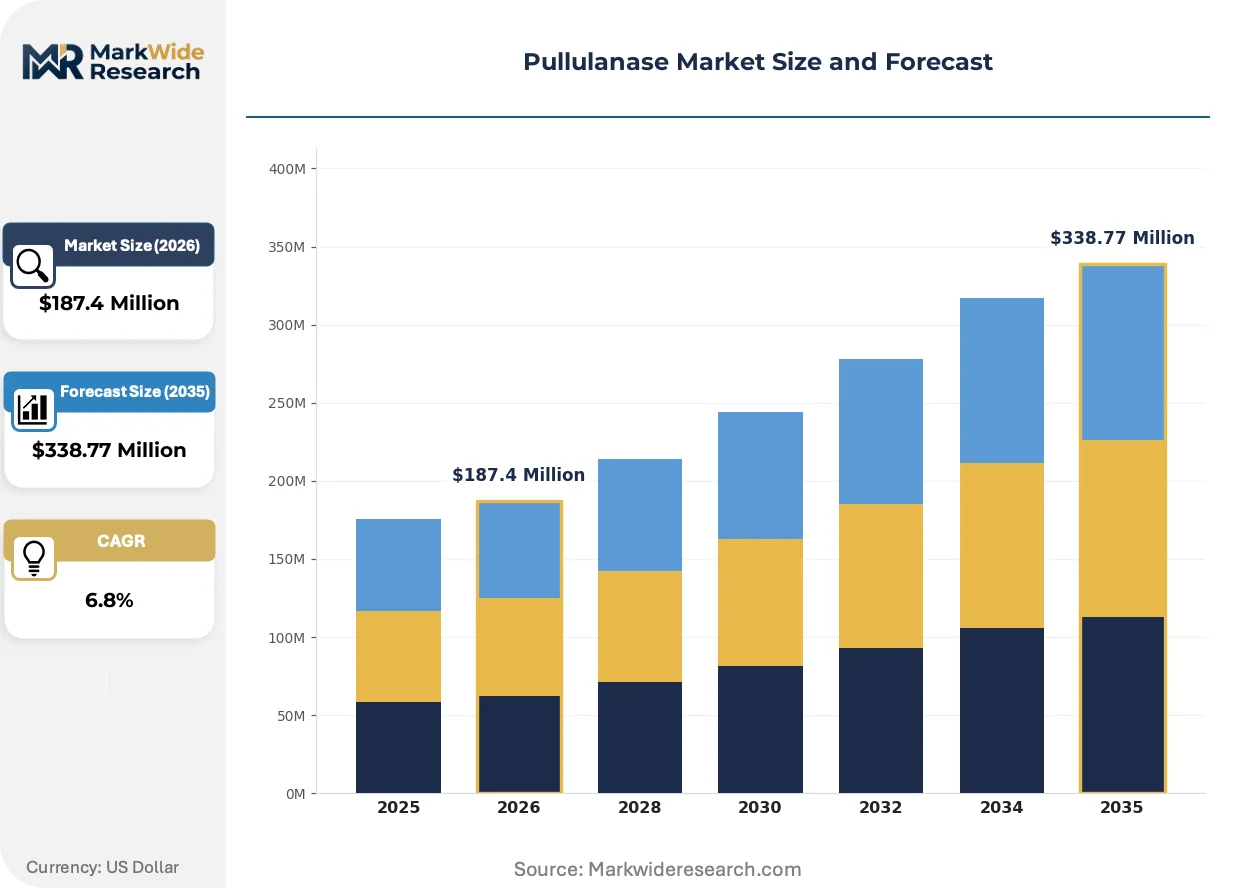
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Form, Powder Form, Granular Form, Tablets End User: Food Industry, Biotechnology, Pharmaceuticals, Animal Feed Application: Starch Processing, Brewing, Distillation, Decorations Technology: Enzymatic Hydrolysis, Genetic Engineering, Fermentation, Chemical Synthesis |
| Companies Covered | Sunson Industry Group Co., Ltd., Novozymes A/S, Shandong Longda Bio-Products Co., Ltd., Amano Enzyme, Genencor, Bestzyme, Biocatalysts Ltd., Xingtai Sinobest Biotech Co., Ltd., DuPont de Nemours, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pullulanase Market Strategic Shifts
Starch processing technology is fragmenting into specialized modular units that processors configure for specific derivative outputs, while regulatory pressure on carbon disclosure and clean-label sourcing accelerates investment in traceable enzymatic supply chains.
Cell-free enzyme production systems are modularizing pullulanase manufacturing by decoupling enzyme synthesis from living cell constraints. Biotech startups and contract manufacturers are adopting these systems to reduce batch-to-batch variability and accelerate strain optimization cycles. This technology is modularizing the traditional fermentation value chain, enabling distributed production nodes closer to starch processing clusters.
EFSA's Food Improvement Agent regulation is tightening safety evaluation protocols for enzymes used in novel food applications. The industrial consequence is extended dossier preparation timelines and higher toxicology study costs for manufacturers seeking expanded use authorizations. Starch processors targeting clean-label claims in EU markets are responding by demanding comprehensive enzyme supply chain documentation from certified suppliers.
Brewery technical buyers are consolidating enzyme procurement around integrated service contracts that bundle enzyme supply with application engineering support. Distributor margins are compressing as direct manufacturer relationships replace traditional chemical broker channels. This pattern is most visible in North American craft brewing clusters, where technical staff shortages drive preference for vendor-managed inventory and on-site troubleshooting services.
Pullulanase Market Segmentation
Pullulanase buyers face divergent operational constraints across formulation preferences, regulatory environments, and processing intensities. Segmentation reveals how enzyme suppliers must align product specifications with end-use technical requirements rather than pursuing undifferentiated volume strategies.
Product Type:
Liquid and powder formulations attract fundamentally different buyer profiles based on dosing infrastructure, distribution economics, and climate exposure.
- Liquid Form:Aqueous enzyme solutions enable precise metering in continuous starch hydrolysis systems. Demand concentrates in coastal Chinese glucose syrup plants where integrated dosing equipment minimizes handling losses.
- Powder Form:Spray-dried preparations with stabilizing carriers suit long-haul distribution to inland starch processors. Buyers in tropical Southeast Asian markets favor powder for reduced cold-chain dependency.
- Granular Form:Free-flowing granules with controlled particle size distribution serve small-batch brewing operations lacking liquid handling infrastructure.
- Tablets:Unit-dosed solid formulations address laboratory-scale biotechnology applications requiring exact enzyme quantities per reaction vessel.
Volume sits with liquid formulations; growth tilts toward powder as tropical starch processing expands.
End User:
Regulatory maturity and technical sophistication separate buyers, with food-grade certification requirements filtering supplier access.
- Food Industry:Starch processors and beverage manufacturers drive procurement scale. EFSA's Food Improvement Agent regulation and China's GB standards enforce dual certification burdens that consolidate supply toward established fermentation houses.
- Biotechnology:Cell-culture media manufacturers are displacing animal-derived inputs with plant-based enzymatic alternatives. FDA guidance on ancillary materials for biopharmaceutical production shapes supplier qualification protocols.
- Pharmaceuticals:Excipient-grade enzyme demand remains constrained by pharmacopeial monograph requirements and validated manufacturing process constraints.
- Animal Feed:Feed enzyme regulations under varying national veterinary product frameworks limit cross-border formulation standardization.
Food industry buyers command procurement scale; biotechnology applications are climbing the fastest.
Application:
Process intensity and margin structure differentiate application segments, with continuous versus batch operations driving divergent enzyme performance specifications.
- Starch Processing:Glucose syrup and maltodextrin production consumes pullulanase at industrial scale. Thermostable variants operating above 60°C reduce cooling energy in continuous liquefaction systems.
- Brewing:Craft and industrial breweries deploy debranching enzymes to maximize fermentable extract from adjunct starches. North American technical buyers increasingly bundle enzyme supply with application engineering support.
- Distillation:Fuel ethanol and spirits producers apply pullulanase alongside glucoamylase to boost fermentation efficiency.
- Decorations:Specialized food decoration manufacturers utilize pullulanase-modified starches for edible film and coating applications with precise optical properties.
Starch processing anchors volume; brewing shows the steepest expansion trajectory as craft segment technical staffing shortages deepen vendor service dependencies.
Technology:
Production method determines cost structure, batch consistency, and regulatory pathway complexity for enzyme manufacturers.
- Enzymatic Hydrolysis:Traditional fermentation-derived production dominates commercial supply. Corn steep liquor and yeast extract input costs fluctuate with agricultural commodity cycles, squeezing margin predictability.
- Genetic Engineering:Recombinant strain development enables thermostability and pH tolerance modifications. Protein engineering advances extend operational temperature windows, reducing processor cooling costs.
- Fermentation:Submerged and solid-state fermentation infrastructure requires industrial microbiology expertise that constrains capacity expansion timelines for mid-tier producers.
- Chemical Synthesis:Non-biological production routes remain experimental for complex enzymes, with peptide synthesis costs prohibitive at commercial scale.
Fermentation technology holds installed capacity; genetic engineering is gaining share fastest as strain optimization cycles accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones concentrate pullulanase fermentation capacity through tax incentives for biotechnology infrastructure. Shandong and Jiangsu provinces anchor domestic enzyme supply chains serving starch processors.
China
Shandong Longda Bio-Products and Sunson Industry Group dominate domestic glucose syrup enzyme supply. GB standards enforcement under SAMR consolidates production toward certified fermentation houses. Qingdao and Jinan clusters specialize in powder-form pullulanase for tropical export markets.
United States
FDA-regulated food-grade certification drives procurement from established fermentation infrastructure. EPA biotechnology oversight shapes strain development pathways for thermostable variants. Midwest corn belt processors in Iowa and Illinois integrate continuous dosing systems for fuel ethanol applications.
Germany
REACH compliance documentation filters smaller enzyme producers from EU market access. EFSA Food Improvement Agent regulation extends dossier timelines for novel starch processing applications. Bavarian industrial biotech clusters around Munich specialize in brewing-grade enzyme formulations.
India
FSSAI enzyme regulations create first-mover positioning for certified suppliers in nascent regulatory frameworks. Gujarat and Maharashtra starch processors adopt enzymatic hydrolysis for clean-label maltodextrin production. Mumbai-Pune industrial corridor attracts contract fermentation investments from multinational enzyme houses.
Japan
METI industrial biotechnology programs subsidize cell-free enzyme production system adoption. PMDA guidance on biopharmaceutical ancillary materials shapes supplier qualification for cell-culture media applications. Osaka-Kobe chemical clusters specialize in high-purity powder formulations for tropical distribution.
Pullulanase Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with multinational fermentation houses holding food-grade certification advantages and regional bio-product companies capturing cost-sensitive starch processing volume. The vendor base organizes around three archetypes: integrated enzyme platforms with global distribution, domestic Chinese fermentation specialists with powder-form expertise, and niche brewing-grade suppliers with application engineering capabilities. Competitive dynamics center on M&A consolidation of regional fermentation assets and strategic partnerships between enzyme suppliers and continuous processing equipment vendors.
Among Chinese domestic specialists, Shandong Longda Bio-Products Co., Ltd. and Sunson Industry Group Co., Ltd. exemplify the cost-competitive powder-form archetype serving tropical starch processing markets. Novozymes A/S occupies a position representing the integrated global platform model with multinational food manufacturer relationships. These three anchors illustrate the geographic bifurcation between Asia-Pacific fermentation scale and European branded enzyme expertise.
| Leading Market Players |
|---|
| Sunson Industry Group Co., Ltd. |
| Novozymes A/S |
| Shandong Longda Bio-Products Co., Ltd. |
| Amano Enzyme |
| Genencor |
| Bestzyme |
| Biocatalysts Ltd. |
| Xingtai Sinobest Biotech Co., Ltd. |
| DuPont de Nemours, Inc. |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between GB-standard-compliant fermentation houses and uncertified regional producers manifests in both pricing premiums and supply chain exclusion. Buyers in China's starch processing corridor pay elevated rates for documented cold-chain integrity, while tropical-market powder shipments command freight-adjusted premiums that reshape distributor selection criteria.
Pricing Analysis
Short lead-time premiums dominate contract negotiations, with certified Chinese fermentation houses charging spot premiums against quarterly offtake agreements. Three-tier pricing structure across premium, standard, and economy levels tracks EFSA/FDA dual certification status, with biotechnology-grade purity commanding the widest spreads. Cost compression in standard-grade liquid formulations is intensifying because corn steep liquor input volatility squeezes mid-tier producers. Starch processors in price-sensitive emerging markets exhibit highest price sensitivity; biopharmaceutical cell-culture media buyers show lowest.
Supply Chain Analysis
Direct-to-brewery channels handle North American craft segment demand, bypassing traditional chemical distributors. Fermentation capacity concentrates in China, Germany, and the United States, with Shandong and Jiangsu provinces anchoring powder-form export supply. Production draws from corn steep liquor, yeast extract, and specialized fermentation media that fluctuate with agricultural commodity cycles. Single-source vulnerability runs through thermostable strain IP held by limited protein engineering houses. Distribution runs through integrated service contracts bundling enzyme supply with application engineering.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cell-free enzyme production systems are displacing traditional fermentation, compressing timelines for strain optimization and reducing batch-to-batch variability that has constrained legacy suppliers.
For Market Incumbents: To counter cell-free production system entrants, deepen captive supply of fermentation media inputs through backward integration into corn processing byproducts. Secure GB-standard and EFSA dual certification for expanded use authorizations before dossier timelines extend further. Prioritize continuous processing equipment partnerships that embed pullulanase in closed-loop starch conversion systems. For New Entrants and Emerging Players: Begin with India's FSSAI enzyme regulation window, where certified supplier scarcity creates first-mover positioning before regulatory frameworks mature. Target biotechnology cell-culture media applications, where plant-derived enzymatic input displacement of animal-origin components offers premium pricing with lower volume scale requirements. Deploy contract fermentation partnerships to bypass industrial microbiology talent scarcity that constrains capacity expansion. For Investors and Strategic Acquirers: Re-rating potential sits with cell-free production system adopters given METI subsidy programs accelerating modular manufacturing adoption. Five-to-ten year viability favors enzyme suppliers with traceable supply chain documentation meeting multinational food chain carbon-intensity disclosure requirements. Watch for EFSA novel food application approvals as inflection indicators for expanded use authorization premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Cell-Free Production System Adoption | Decouples enzyme synthesis from living cell constraints, reducing batch variability for biopharmaceutical clients. |
| Dual Certification Investment | GB-standard and EFSA alignment opens multinational food manufacturer procurement pools. |
| Continuous Processing Integration | Immobilized enzyme systems with membrane filtration reduce water consumption for starch processors. |
| Backward Integration into Fermentation Media | Corn steep liquor supply control buffers margin predictability against agricultural commodity cycles. |
| Brewing-Grade Application Engineering Bundling | Vendor-managed inventory addresses technical staffing shortages in North American craft brewing clusters. |
Study Parameters
Multi-period observation of enzyme certification timelines, strain optimization cycles, and starch processor procurement patterns anchored the trend analysis, supplemented by interviews with fermentation plant managers, biotechnology procurement leads, regulatory affairs directors at enzyme houses, and brewery technical buyers. Secondary validation drew from SAMR GB standard filings, EFSA Food Improvement Agent dossiers, EPA biotechnology oversight records, and customs trade data for enzyme powder shipments. Bottom-up capacity modeling triangulated against top-down end-use demand segmentation.
Segment-weighting across product form, end-use industry, application intensity, and production technology shaped the analytical framework across the analysis window. CAGRs derived from installed fermentation capacity expansion trajectories, thermostable variant adoption curves, and cell-culture media formulation shifts. Modeled inputs included protein engineering advancement rates, clean-label starch derivative demand elasticity, and regulatory dossier approval timelines.
Underlying measurement precision varies by segment; starch processing volume estimates carry tighter precision than biotechnology application projections given disclosure practices. Forecasts reflect assumptions on GB standard enforcement intensity, REACH documentation burden stability, and fermentation input cost trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Biotechnology
Beta-Propeller Phytases Market
Food Biotechnology
Red Seaweed Extract Market
Food Biotechnology
Glucose Oxidase Market
Food Biotechnology
Global Genetically Modified (GMO) Food Market
Food Biotechnology
Flaxseed Gum Market
Food Biotechnology
Trypsin Market
Food Biotechnology
Beta Lactoglobulin Protein Market
Food Biotechnology
Africa Eubiotics Market
Food Biotechnology
Bovine Colostrum Market
Food Biotechnology
Carbohydrate Enzyme Preparation Market
Food Biotechnology
Biopreservation Market
Food Biotechnology
Zein Protein Market
Food Biotechnology
Salmon Polynucleotide (PN) Market
Food Biotechnology
Colostrum Market
Food Biotechnology
Biotech Flavors Market
Food Biotechnology
North America Eubiotics Market