
 Trypsin Market | 2026-2036
Trypsin Market Size, Share, and Industry Trends Forecast 2026-2036
Trypsin Market Insights
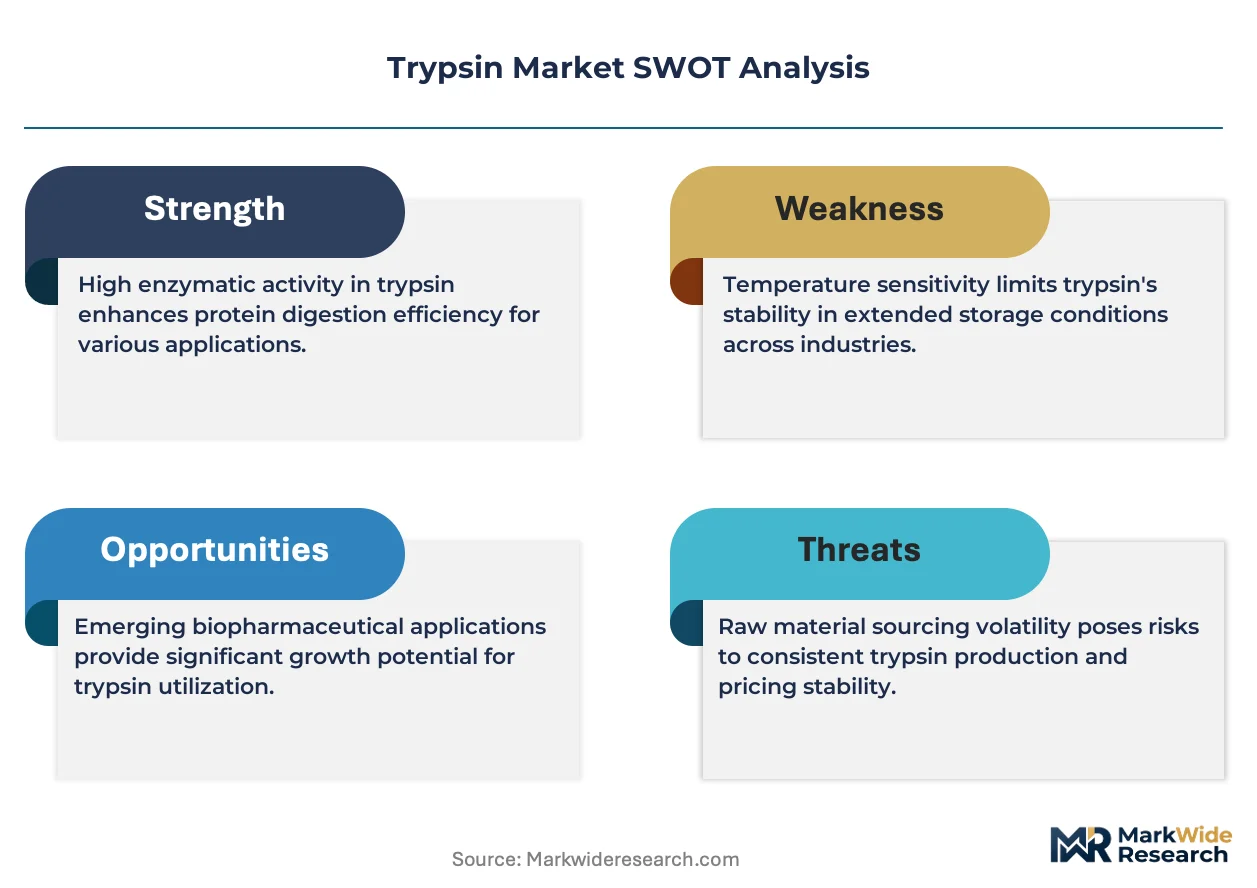
Pharmaceutical-grade trypsin certification is unwinding legacy supply arrangements across the industry. Merck KGaA leverages its integrated life sciences platform to control quality from fermentation through final formulation. Thermo Fisher Scientific anchors North American supply chains with deep distribution into academic and biopharma end users. Novozymes competes through specialized recombinant enzyme engineering that reduces batch-to-batch variability.
Trypsin is a serine protease enzyme derived from porcine or bovine pancreas, or produced recombinantly, that cleaves peptide chains at lysine and arginine residues; manufacturers typically characterize activity in USP units per milligram for standardization across cell culture and proteomics workflows. Recombinant trypsin leads product type expansion as animal-origin-free specifications displace conventional porcine-derived grades in regulated bioprocessing. Biotechnology and pharmaceutical applications capture the deepest margin pools, while diagnostics represents the fastest-growing application segment as mass spectrometry-based clinical assays proliferate.
FDA and EMA guidelines on animal-derived materials in biologics production shape sourcing decisions, compelling manufacturers to validate recombinant alternatives or secure TSE/BSE-compliant supply chains. ISO 13485 and GMP frameworks govern diagnostic-grade trypsin manufacturing, raising barriers for uncertified suppliers. Stakeholders must weigh recombinant conversion costs against long-term regulatory access advantages as pharmacopeial standards tighten.
Market Dynamics
The Trypsin Market is restructuring around animal-origin-free certification mandates, with recombinant production methods displacing conventional porcine-derived supply chains as biopharmaceutical manufacturers face intensified regulatory scrutiny over TSE/BSE compliance.
Growth Catalysts
- EMA/FDA TSE Guidelines:Regulatory pressure on animal-derived materials in biologics production is accelerating validation of recombinant alternatives across European and North American manufacturing facilities.
- Cell Culture Expansion:Biopharmaceutical contract manufacturers are scaling serum-free and chemically defined media formulations that require certified animal-origin-free enzymes.
- Mass Spectrometry Diagnostics:Clinical proteomics laboratories are adopting standardized trypsin digestion protocols for biomarker quantification in precision medicine workflows.
Market Restraints
- Porcine Pancreas Supply Concentration:Conventional trypsin production remains dependent on abattoir byproduct streams concentrated in specific geographic processing clusters.
- Recombinant Production Costs:Fermentation-based enzyme manufacturing requires substantially higher capital intensity and yield optimization compared to tissue extraction methods.
- ISO 13485 Certification Barriers:Diagnostic-grade manufacturing compliance creates multi-year qualification timelines that exclude smaller fermentation operators from regulated segments.
Strategic Opportunities
- India Biopharma Manufacturing:CDSCO-regulated facilities are expanding recombinant enzyme capacity to serve domestic biosimilar production and export markets.
- Single-Use Bioprocessing Convergence:Integration of disposable bioreactor systems with pre-qualified enzyme aliquots is reducing contamination risk in multi-product facilities.
- PLI Scheme Incentives:India's production-linked incentive framework for active pharmaceutical ingredients is attracting recombinant enzyme investment into specialized economic zones.
Industry Challenges
- Pharmacopeial Harmonization Delays:Divergent USP, EP, and JP monograph specifications for trypsin activity measurement complicate multi-territory product registration.
- Batch-to-Batch Variability Management:Recombinant enzyme producers must demonstrate equivalent kinetic performance to porcine-derived reference standards across varying fermentation conditions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trypsin Market |
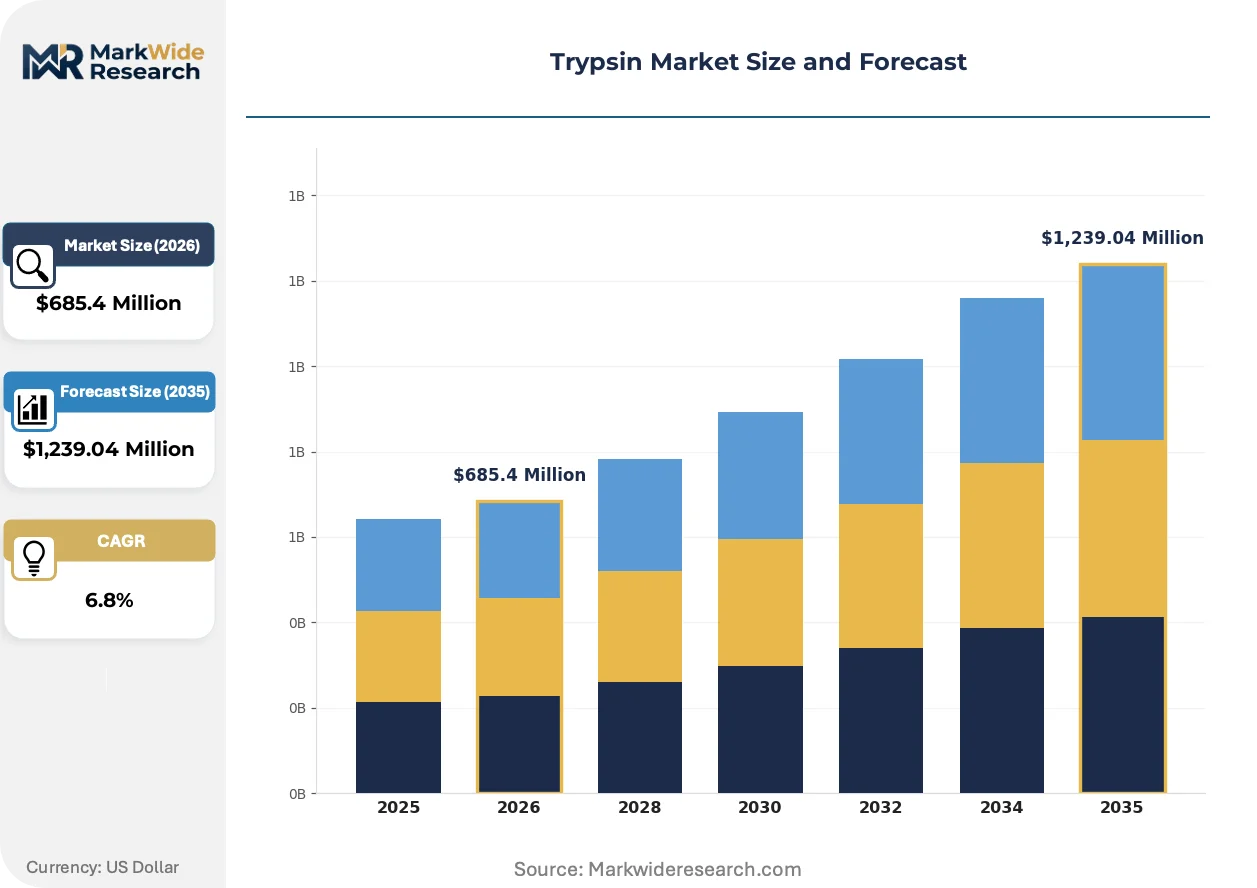
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Trypsin Powder, Trypsin Solution, Recombinant Trypsin, Trypsin Inhibitors Application: Biotechnology, Pharmaceuticals, Research, Diagnostics End User: Academic Institutions, Biotechnology Companies, Pharmaceutical Companies, Research Laboratories Distribution Channel: Online Distribution, Direct Sales, Distributors, Retailers |
| Companies Covered | Merck KGaA, Thermo Fisher Scientific, Novozymes, Sartorius AG, Promega Corporation, Agilent Technologies, Takara Bio, Corning Incorporated, Worthington Biochemical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trypsin Market Trends and Innovations
Enzyme engineering and regulatory compliance frameworks are actively restructuring competitive positioning in trypsin supply, with differentiation increasingly anchored to certification depth rather than unit pricing alone.
Recombinant trypsin expression systems utilizing microbial hosts are bifurcating the product landscape into animal-origin-free and conventional grades. Biopharmaceutical manufacturers with FDA-regulated biologics pipelines are mandating recombinant specifications in new facility designs. This technology shift is compressing margins for legacy porcine-derived suppliers while rewarding fermentation specialists with pharmacopeial-grade capabilities.
REACH authorization requirements for enzyme manufacturing intermediates are tightening supply chain documentation across European member states. ECHA's evolving substance evaluation protocols are extending registration timelines for imported animal-derived enzymes. German and Swiss bioprocessing clusters are responding by accelerating in-house recombinant production capacity to reduce import dependency.
Consolidated procurement by multi-site biopharmaceutical operators is displacing fragmented spot purchasing of research-grade enzymes. Large-scale contract manufacturers are negotiating multi-year supply agreements with guaranteed lot consistency and audit rights. This concentration pattern is most pronounced in United States coastal biotechnology corridors, where integrated CDMOs are absorbing smaller academic distributors into captive supply arrangements.
Trypsin Market Segmentation
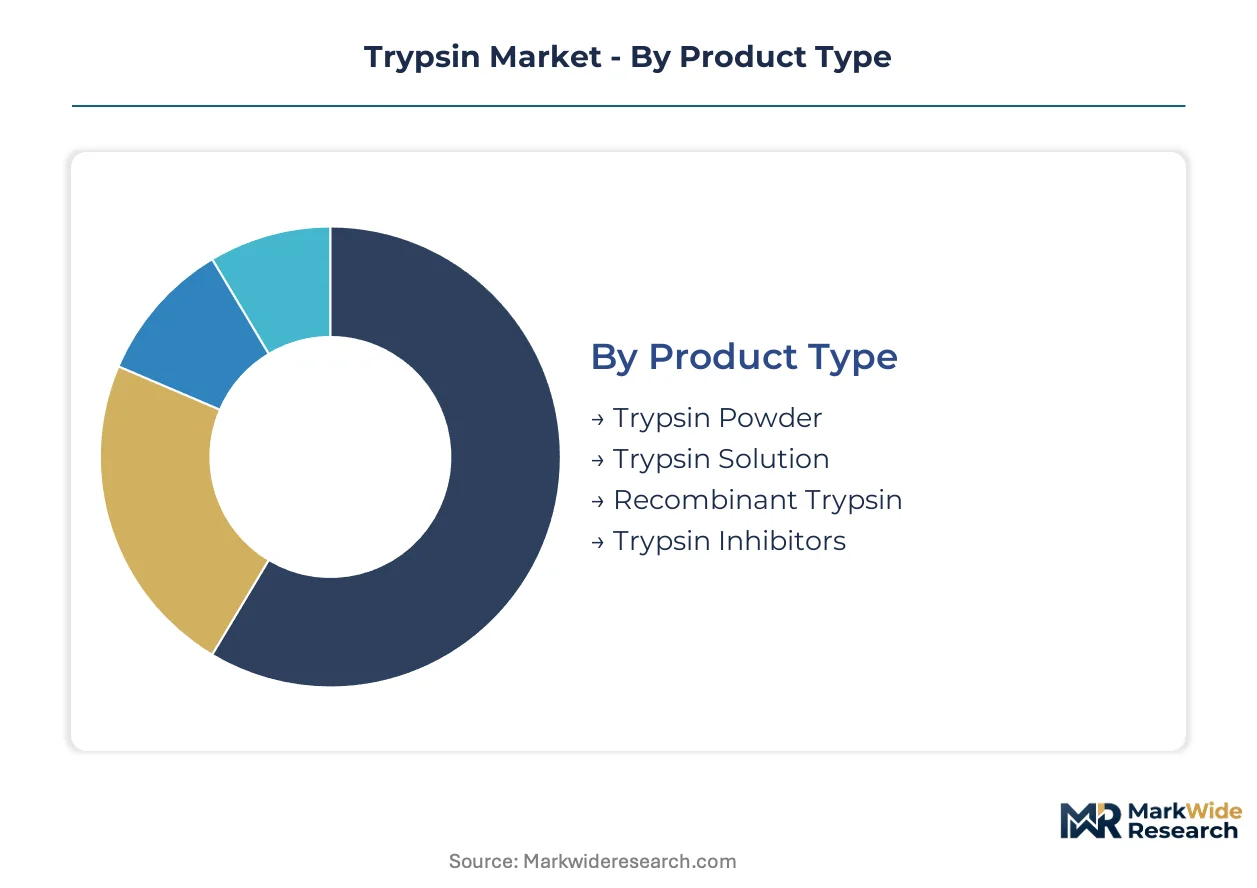
Trypsin market segmentation reflects divergent regulatory tolerances and technical specifications across bioprocessing workflows. Product form and origin certification determine access to regulated pharmaceutical channels versus research-grade procurement.
Product Type:
Recombinant alternatives are displacing animal-derived grades fastest in segments where TSE/BSE compliance is non-negotiable.
- Recombinant Trypsin:Microbial expression systems deliver animal-origin-free serine protease with equivalent kinetic activity to porcine-derived reference standards. Biopharmaceutical manufacturers in FDA-regulated facilities are mandating recombinant specifications for new biologics production lines.
- Trypsin Powder:Lyophilized formulations dominate bulk procurement for cell culture media preparation, with activity standardized in USP units per milligram. Powdered grades retain cost advantages in academic and early-stage research settings where animal-origin documentation requirements remain less stringent.
- Trypsin Solution:Ready-to-use liquid formulations reduce preparation time in high-throughput proteomics workflows. Solution stability and shipping constraints limit geographic distribution reach compared to dried formats.
- Trypsin Inhibitors:Soybean-derived and recombinant inhibitor proteins enable precise enzymatic quenching in cell dissociation protocols. Demand concentrates in stem cell and primary culture applications requiring gentle handling.
Trypsin Powder anchors the volume base while Recombinant Trypsin gains share at the steepest rate.
Application:
Margin structures diverge sharply between regulated therapeutic manufacturing and exploratory research use.
- Pharmaceuticals:GMP-grade trypsin for biologics production commands the deepest margin pools, with batch documentation extending back to fermentation or tissue extraction records. EMA and FDA inspections validate supplier qualification for multi-year manufacturing agreements.
- Diagnostics:Standardized digestion protocols for mass spectrometry-based clinical assays are expanding fastest among application segments. Clinical proteomics laboratories require lot-to-lot consistency for biomarker quantification reproducibility.
- Biotechnology:Cell culture applications span serum-free media development through commercial bioproduction, with enzyme specifications tightening as projects advance toward IND filing.
- Research:Academic proteomics and basic cell biology represent price-sensitive volume, with procurement fragmented across institutional purchasing cooperatives and individual laboratory spot buying.
Pharmaceuticals anchors the volume base while Diagnostics climbs the fastest.
End User:
Procurement sophistication and compliance burden scale with therapeutic pipeline exposure.
- Pharmaceutical Companies:Integrated biologics manufacturers operate captive supply agreements with guaranteed lot consistency and audit rights. Multi-site operators are consolidating vendor panels to reduce qualification overhead.
- Biotechnology Companies:Venture-funded cell therapy and gene therapy developers prioritize animal-origin-free specifications to preempt regulatory objections during BLA review. CDMO partnerships often dictate enzyme sourcing decisions.
- Academic Institutions:University core facilities balance cost constraints against reproducibility requirements, with funding agency mandates increasingly influencing sustainability and sourcing transparency preferences.
- Research Laboratories:Government and private research institutes represent fragmented demand with heterogeneous quality standards and procurement autonomy.
Pharmaceutical Companies anchors the volume base while Biotechnology Companies expands most quickly.
Distribution Channel:
Channel selection reflects order scale, technical support requirements, and geographic proximity to manufacturing clusters.
- Direct Sales:Large-volume pharmaceutical and biotechnology accounts negotiate multi-year supply agreements with dedicated technical service and custom formulation capabilities. Direct relationships enable rapid response to batch-specific queries during regulatory inspections.
- Distributors:Specialized life sciences distributors aggregate demand across mid-tier biotechnology companies and academic consortia, offering consolidated invoicing and regional inventory positioning. German and Swiss distribution hubs serve European bioprocessing corridors with reduced lead times.
- Online Distribution:E-commerce platforms capture research-grade and small-volume orders with transparent pricing and rapid fulfillment. Digital procurement is displacing traditional catalog sales in academic segments.
- Retailers:Limited to general laboratory supply houses serving educational and routine analytical applications with undifferentiated product grades.
Direct Sales anchors the volume base while Online Distribution gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German fermentation specialists export recombinant enzyme grades to FDA-regulated biopharmaceutical facilities across the United States, establishing the primary transatlantic trade corridor in high-purity trypsin supply.
United States
Contract manufacturing organizations in Massachusetts and California scale serum-free cell culture capacity for gene therapy production. FDA TSE/BSE guidelines compel biologics manufacturers to validate animal-origin-free enzyme specifications. The Boston-Cambridge biotechnology corridor concentrates demand for GMP-certified recombinant trypsin with full batch documentation.
Germany
REACH authorization requirements tighten supply chain documentation for enzyme manufacturing intermediates entering European member states. ECHA substance evaluation protocols extend registration timelines for imported animal-derived enzymes. The Rhine-Main bioprocessing cluster accelerates in-house recombinant fermentation capacity to reduce import dependency from non-EU sources.
Switzerland
Swissmedic inspections validate supplier qualification for multi-year manufacturing agreements with global biopharmaceutical headquarters. ISO 13485 certification requirements raise barriers for uncertified suppliers seeking diagnostic-grade market access. The Basel-Zurich life sciences corridor integrates disposable bioreactor systems with pre-qualified enzyme aliquots for multi-product facilities.
India
CDSCO-regulated facilities expand recombinant enzyme capacity to serve domestic biosimilar production and export markets. The PLI scheme for active pharmaceutical ingredients attracts fermentation investment into specialized economic zones. The Hyderabad-Bengaluru pharmaceutical corridor develops captive recombinant trypsin supply for contract research and manufacturing services.
Japan
PMDA guidelines on animal-derived materials in biologics production shape sourcing decisions for regenerative medicine applications. METI industrial policy supports microbial expression system development for enzyme manufacturing. The Kansai biocluster around Osaka advances chemically defined media formulations requiring certified animal-origin-free enzymes.
Trypsin Market Competitive Landscape
Listed leaders compete with private specialists across certification depth and geographic coverage, producing a tiered structure where public companies leverage capital markets for fermentation scale-up while family-owned entities retain niche pharmacopeial expertise. Three archetypes dominate: integrated life sciences platforms controlling quality from fermentation through formulation, specialized recombinant enzyme engineers reducing batch-to-batch variability, and regional distributors aggregating fragmented academic demand. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with fermentation specialists seeking CDMO alliances and distributors consolidating spot purchasing into multi-year agreements.
Within the integrated platform tier, Merck KGaA and Thermo Fisher Scientific exemplify capital-intensive players leveraging global distribution networks. Novozymes occupies a position among specialized recombinant enzyme engineers, representing the fermentation-focused archetype that competes through kinetic performance standardization. These three anchors illustrate how competitive positioning increasingly depends on certification depth and regulatory access rather than unit pricing alone.
| Leading Market Players |
|---|
| Merck KGaA |
| Thermo Fisher Scientific |
| Novozymes |
| Sartorius AG |
| Promega Corporation |
| Agilent Technologies |
| Takara Bio |
| Corning Incorporated |
| Worthington Biochemical Corporation |
| Others |
Pricing and Supply Chain Analysis
Recombinant trypsin substitution for porcine-derived grades redraws supply geography toward fermentation hubs in Germany and Switzerland while compressing pricing economics for legacy tissue-extraction suppliers facing EMA TSE compliance costs.
Pricing Analysis
Recombinant-grade premiums over porcine-derived standards range threefold based on pharmacopeial certification depth. Three-tier pricing structure across GMP-certified, diagnostic-grade, and research-grade levels separates biopharmaceutical manufacturers from clinical proteomics laboratories and academic buyers. Cost compression in research-grade powder formats intensifies as Indian fermentation capacity expands and spot purchasing consolidates. Biotechnology companies with BLA-track pipelines exhibit least price sensitivity due to regulatory audit requirements, while university core facilities drive hardest bargain on undifferentiated catalog grades.
Supply Chain Analysis
Germany and Switzerland anchor recombinant trypsin fermentation for FDA-regulated biopharmaceutical facilities across the United States. Porcine pancreas tissue draws from abattoir byproduct streams concentrated in specific geographic processing clusters. Single-source vulnerability concentrates in pancreatic tissue supply chains subject to animal health regulatory restrictions. Distribution runs through direct sales for pharmaceutical accounts and specialized life sciences distributors aggregating academic demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across FDA, EMA, and PMDA TSE guidelines creates specialization opportunities for fermentation specialists and regional certification experts serving distinct compliance jurisdictions.
For Market Incumbents: Consolidate multi-year supply agreements with audit rights and guaranteed lot consistency to lock out emerging recombinant competitors. Add fermentation capacity in Rhine-Main bioprocessing cluster to reduce import dependency exposure from non-EU sources. Deepen ISO 13485 certification barriers that exclude smaller operators from diagnostic-grade segments.
For New Entrants and Emerging Players: CDMO service-layer gaps in India biopharma manufacturing offer white-space targeting for recombinant enzyme production under PLI scheme incentives. Focus initial penetration on biosimilar contract research and manufacturing services in Hyderabad-Bengaluru corridor. Pursue technical partnership route with established German distributors lacking captive fermentation assets.
For Investors and Strategic Acquirers: EMA REACH authorization timeline extensions reshape the acquisition landscape toward EU-based fermentation assets with completed substance registrations. Five-to-ten year viability favors specialized recombinant enzyme engineers over legacy porcine-derived suppliers facing structural margin compression. Monitor CDSCO regulatory harmonization progress with FDA as inflection signal for Indian manufacturing export eligibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Recombinant Fermentation Scale-Up | Captures animal-origin-free demand from FDA-regulated gene therapy manufacturers in Boston-Cambridge corridor. |
| ISO 13485 Certification Investment | Unlocks diagnostic-grade market access blocked from uncertified suppliers by Swissmedic inspection requirements. |
| CDMO Partnership Formation | Integrates pre-qualified enzyme aliquots with disposable bioreactor systems in multi-product facilities. |
| Backward Integration into Microbial Expression | Reduces batch-to-batch variability through in-house strain engineering and yield optimization capabilities. |
| PLI Scheme Facility Establishment | Positions recombinant production within India's specialized economic zones for biosimilar export markets. |
Research Methodology
Initial hypotheses were tested against primary input from bioprocess development executives, regulatory affairs leads at EMA-inspected facilities, CDMO procurement managers, and academic core facility directors and refined through secondary validation across FDA 483 inspection databases, EMA GMP certificates, CDSCO manufacturing approvals, and pharmacopeial monograph revisions. Bottom-up enzyme volume estimates from fermentation capacity filings triangulated against top-down biopharmaceutical production forecasts.
Variance decomposition across product type, application, and end-user segments drove analytical framework construction over the projection horizon. CAGRs derived from segmented growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated cell culture media formulation trends and mass spectrometry diagnostics protocol standardization trajectories.
Underlying assumptions cover sustained EMA/FDA TSE guideline enforcement and recombinant yield optimization progress, with deviation risk concentrated in pharmacopeial harmonization delays and porcine tissue supply disruptions. Recalibration cycles align with material shifts in regulatory inspection intensity and CDSCO export clearance velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Biotechnology
Red Seaweed Extract Market
Food Biotechnology
Global Feed Enzymes Market
Food Biotechnology
Beta Lactoglobulin Protein Market
Food Biotechnology
Global Food Biotechnology Market
Food Biotechnology
Biotech Flavors Market
Food Biotechnology
Flaxseed Gum Market
Food Biotechnology
Global GMO Testing Market
Food Biotechnology
Cultured Meat Market
Food Biotechnology
Prebiotics Market
Food Biotechnology
Biopreservation Market
Food Biotechnology
Salmon Polynucleotide (PN) Market
Food Biotechnology
Glucose Oxidase Market
Food Biotechnology
Direct-Fed Microbial Products Market
Food Biotechnology
Brown Algae Protein Market
Food Biotechnology
Papain Market
Food Biotechnology
Carbohydrate Enzyme Preparation Market