
 Glucose Oxidase Market | 2026-2036
Glucose Oxidase Market Size, Share, and Industry Trends Forecast 2026-2036
Glucose Oxidase Market Analysis
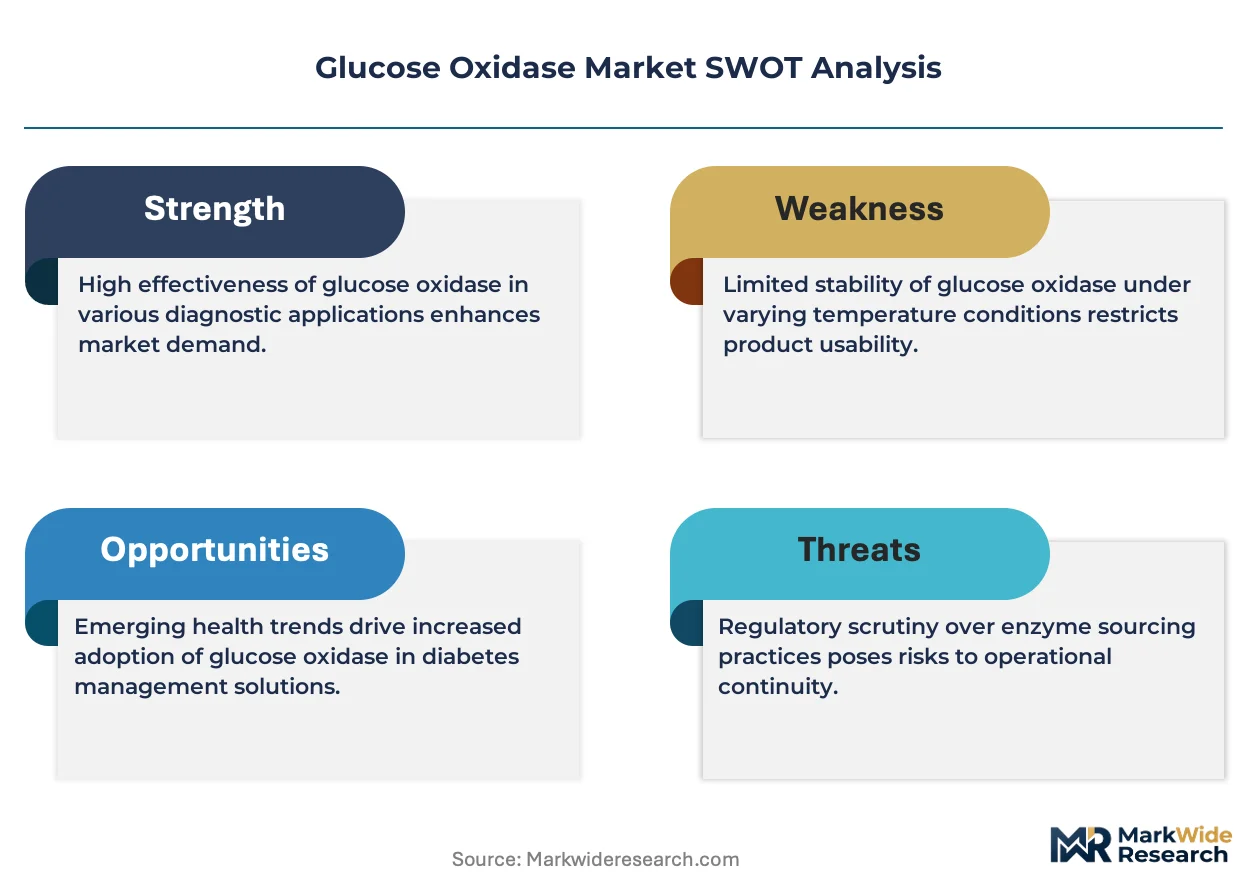
Specialized enzyme distribution networks serving pharmaceutical and diagnostic manufacturers is reshaping how glucose oxidase reaches end users. Novozymes leverages its global fermentation infrastructure to supply bulk industrial volumes across multiple continents. BBI Solutions anchors its position through deep specialization in diagnostic-grade enzyme formulations for biosensor applications. Royal DSM competes by extending its biotechnology portfolio into high-purity enzyme segments for regulated industries.
Glucose oxidase is a flavoprotein enzyme catalyzing the oxidation of beta-D-glucose to D-glucono-1,5-lactone and hydrogen peroxide, typically extracted from Aspergillus niger fermentation cultures with optimal activity near pH 5.5 and temperatures of 30-50 degrees Celsius. The enzyme serves as a critical biocatalyst in glucose detection systems, food preservation matrices, and pharmaceutical intermediate synthesis. Microbial-sourced glucose oxidase dominates production economics due to scalable fermentation yields and well-characterized expression systems, while diagnostic applications command premium pricing through stringent purity certifications. Powder formulations retain the largest volume share for industrial food processing, though liquid preparations are gaining traction in automated clinical analyzer installations.
FDA enzyme guidance documents and EPA manufacturing discharge standards shape production facility investments and quality management systems for US-based suppliers. REACH registration requirements and EMA pharmaceutical excipient monographs enforce batch-level traceability and contaminant thresholds across European supply chains. Stakeholders must monitor evolving enzyme classification frameworks in major jurisdictions to anticipate reformulation costs and market access conditions.
Market Dynamics
Diagnostic-grade purity thresholds are compressing supplier margins while consolidating procurement toward fermentation specialists with captive quality systems. Pharmaceutical and food safety regulators across multiple jurisdictions now mandate batch-level enzyme characterization that smaller extractors cannot sustain.
Growth Catalysts
- EMA Pharmaceutical Excipient Monographs:Tightened contaminant thresholds for parenteral-grade enzymes are filtering out commodity suppliers and redirecting diagnostic manufacturer contracts toward certified fermentation houses.
- Biosensor miniaturization:Point-of-care glucose monitoring devices require engineered enzyme variants with enhanced thermal stability, creating specification premiums for producers with protein engineering capabilities.
- Food preservation reformulation:Clean-label movement in processed foods is replacing synthetic antioxidants with glucose oxidase-catalyzed oxygen scavenging in bakery and dairy applications.
Market Restraints
- Aspergillus niger strain IP concentration:Foundational production organisms remain under patent thickets controlled by legacy fermentation houses, blocking new entrants from cost-competitive cultivation.
- REACH registration cost escalation:ECHA's updated data requirements for enzyme substances are imposing six-figure dossier preparation burdens that disproportionately burden mid-volume suppliers.
- Lyophilization energy intensity:Powder formulation production depends on freeze-drying cycles with spiking European electricity costs, compressing margins on industrial-grade shipments.
Strategic Opportunities
- Continuous processing adoption:Immobilized enzyme reactor technology enables real-time glucose monitoring in bioprocess control, opening pharmaceutical manufacturing applications beyond diagnostics.
- India's PLI scheme for biotechnology:Production-linked incentives for fermentation-based manufacturing are attracting capacity investments to serve Asian diagnostic reagent markets with reduced logistics exposure.
- Direct-to-laboratory distribution:Specialty enzyme distributors are bypassing traditional chemical intermediaries to capture margin and technical service relationships with hospital laboratory networks.
Industry Challenges
- Fermentation scale-up talent scarcity:Industrial microbiologists with Aspergillus cultivation expertise command premium compensation, constraining capacity expansion timelines for emerging producers.
- ISO 13485 certification timelines:Diagnostic-grade quality system implementation requires 18-24 month validation cycles that delay market entry for reformulated enzyme variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glucose Oxidase Market |
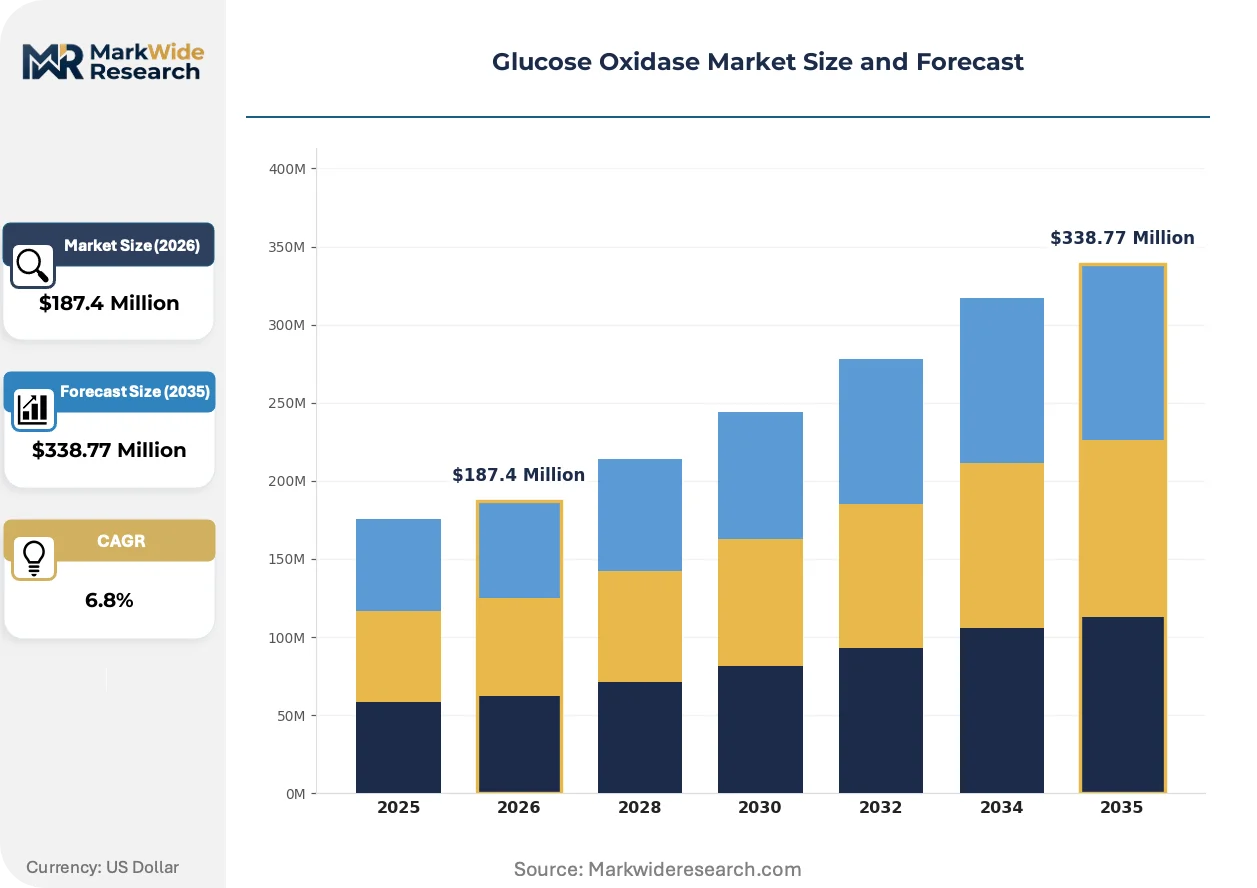
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microbial, Animal, Plant, Synthetic Application: Food & Beverage, Pharmaceuticals, Diagnostics, Biotechnology End User: Laboratories, Hospitals, Research Institutes, Food Manufacturers Form: Powder, Liquid, Tablets, Granules |
| Companies Covered | Royal DSM, BBI Solutions, Novozymes, Merck KGaA, AB Enzymes, Amano Enzyme Inc., Sigma-Aldrich, Biocatalysts, DuPont, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glucose Oxidase Market Emerging Trajectories
Enzyme engineering and regulatory data digitization are compressing product development cycles while fragmenting procurement relationships. Suppliers now compete on characterization depth rather than unit cost alone.
Recombinant glucose oxidase variants with engineered glycosylation patterns are rendering obsolete wild-type Aspergillus extracts in continuous monitoring applications. Biosensor manufacturers in Germany and the United States are qualifying these stabilized preparations for 90-day sensor lifespans. The technology is rendering obsolete batch-replacement service contracts that previously sustained aftermarket revenue streams.
REACH's 2023 updated guidance on enzyme substance characterization is forcing diagnostic reagent manufacturers to redesign supplier qualification protocols. ECHA's extended one-generation reproductive toxicity data requirements now apply to all enzymes above one-tonne annual volume. European contract manufacturers are consolidating procurement toward fermentation houses with existing mammalian toxicity dossiers.
Hospital laboratory networks are unbundling enzyme supply from analyzer maintenance contracts, creating direct purchasing relationships with specialty distributors. This disintermediation is compressing pricing for liquid formulations while elevating technical service expectations. The shift is most visible in United States health system consolidation, where centralized procurement offices now negotiate enzyme supply separately from capital equipment leases.
Glucose Oxidase Market Segmentation
Glucose oxidase procurement cycles vary dramatically across formulation types and end-use certifications, with diagnostic applications demanding 18-month validation timelines while food-grade volumes turn on quarterly contracts. Understanding these velocity differentials helps suppliers calibrate inventory and pricing structures to each segment's procurement rhythm.
Product Type:
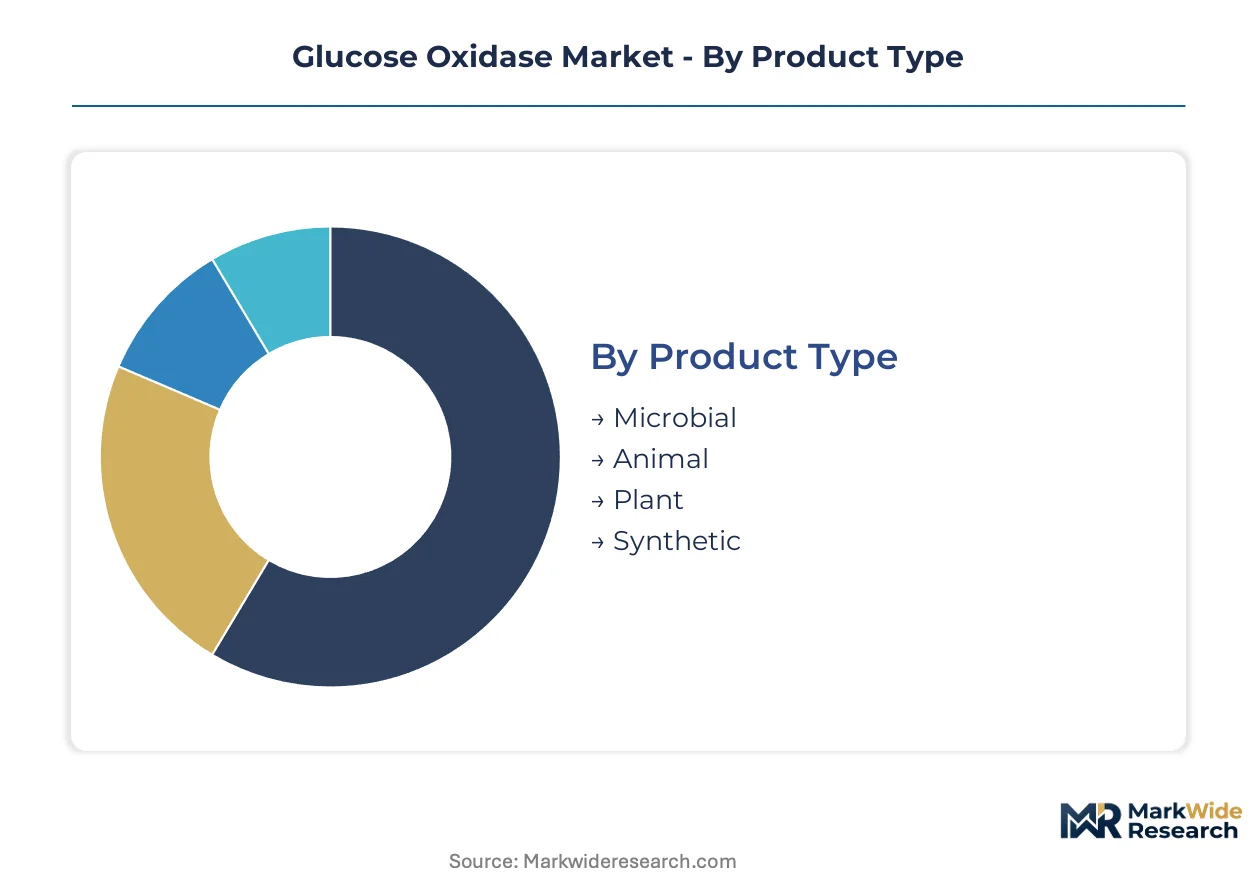
Cycle times stretch from multi-year strain development for microbial sources to rapid synthetic chemistry iterations, creating divergent capital recovery profiles across production modes.
- Microbial:Aspergillus niger fermentation extracts dominate commercial supply through scalable bioreactor yields and established downstream purification protocols. Diagnostic manufacturers in Germany and the United States concentrate procurement here due to batch-to-batch consistency requirements under FDA enzyme guidance and EMA pharmaceutical excipient monographs.
- Animal:Tissue-derived preparations from bovine or porcine sources persist in niche pharmaceutical applications requiring specific glycosylation patterns for parenteral compatibility. Supply constraints from TSE/BSE regulatory scrutiny have compressed volumes to specialty hormone synthesis and rare therapeutic enzyme replacement formulations.
- Plant:Extracts from sources such as Phaseolus vulgaris serve research-scale applications and clean-label food preservation markets seeking non-microbial provenance claims.
- Synthetic:Cell-free protein synthesis and engineered peptide assemblies enable rapid variant prototyping for biosensor calibration standards and academic research consumables.
Microbial sources anchor the volume base while synthetic formulations gain share at the steepest rate.
Application:
Margin structures stratify sharply across end-use certifications, with pharmaceutical and diagnostic grades commanding fivefold premiums over industrial food processing volumes.
- Food & Beverage:Oxygen scavenging in bakery matrices and dairy products drives bulk powder consumption, with clean-label reformulation accelerating substitution for synthetic antioxidants like BHT and TBHQ.
- Pharmaceuticals:High-purity formulations serve as biocatalysts in gluconic acid and antibiotic intermediate synthesis, with parenteral-grade specifications requiring endotoxin testing and viral clearance validation that only captive fermentation houses can sustain.
- Diagnostics:Biosensor and glucose meter reagent applications concentrate demand in liquid formulations with engineered thermal stability for point-of-care devices. EMA tightened contaminant thresholds and FDA enzyme classification evolution are filtering procurement toward certified suppliers with ISO 13485 quality systems.
- Biotechnology:Research-grade enzymes support cell culture glucose monitoring and bioprocess control applications, with immobilized reactor configurations enabling continuous processing adoption in pharmaceutical manufacturing.
Food and beverage applications anchor the volume base while diagnostics gains share through specification premiums on stabilized enzyme variants.
End User:
Procurement authority is fragmenting as hospital laboratory networks unbundle enzyme supply from analyzer maintenance contracts, creating direct purchasing relationships with specialty distributors.
- Laboratories:Clinical and research facilities drive demand for liquid formulations compatible with automated analyzer pipelines, with centralized procurement offices in United States health systems now negotiating enzyme supply separately from capital equipment leases.
- Hospitals:Point-of-care glucose monitoring programs require engineered enzyme variants with extended sensor lifespans, creating specification premiums for producers with protein engineering capabilities.
- Research Institutes:Academic and government laboratories consume research-grade preparations for assay development and publication-grade reproducibility studies.
- Food Manufacturers:Industrial bakeries and dairy processors procure bulk powder formulations through quarterly contracts tied to commodity input pricing indices.
Food manufacturers anchor the volume base while hospital networks gain procurement influence fastest through health system consolidation.
Form:
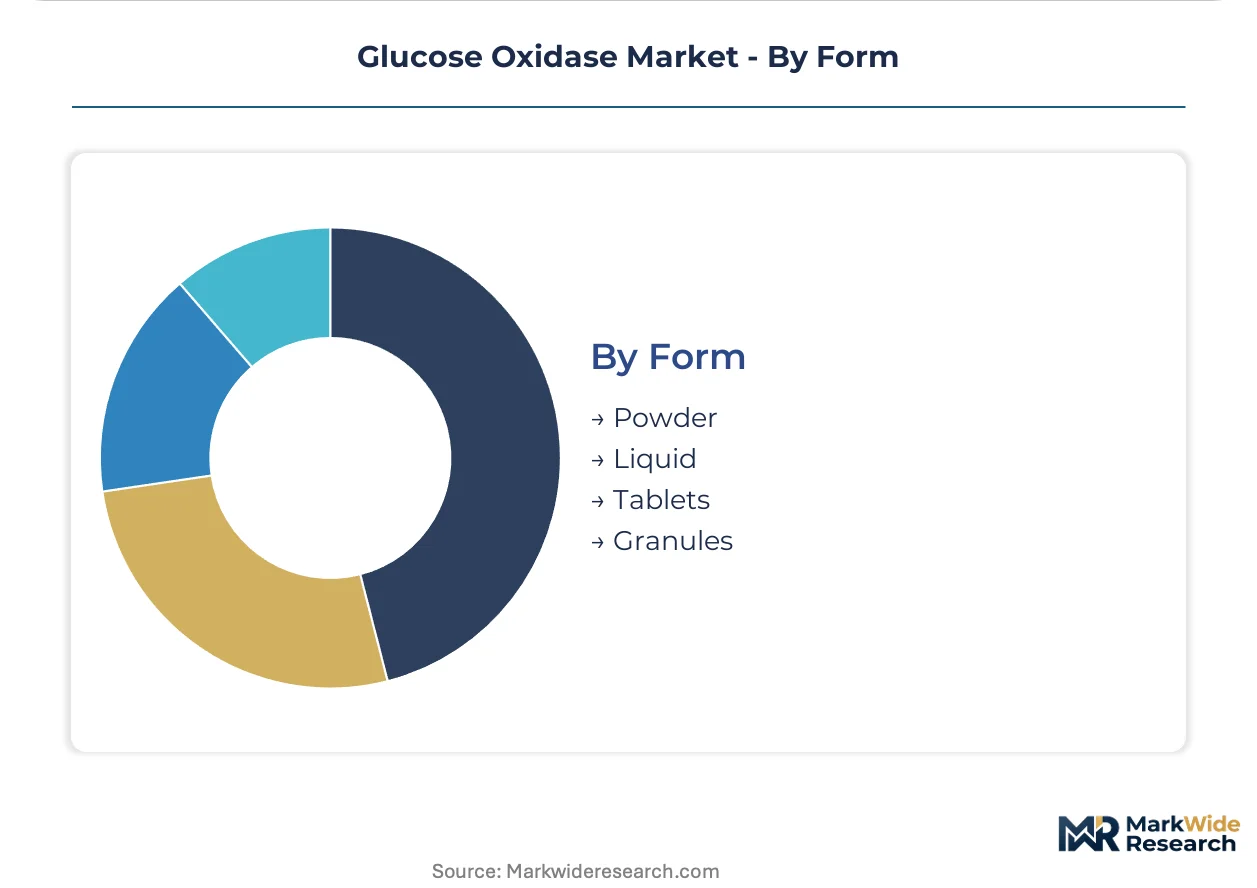
Logistics economics and shelf-stability requirements create distinct regional preferences, with powder formulations retaining dominance in industrial applications while liquid preparations penetrate automated clinical installations.
- Powder:Lyophilized preparations dominate food preservation and industrial biocatalysis due to extended ambient storage stability and freight cost efficiency. European electricity cost escalation has compressed margins on freeze-dried industrial-grade shipments.
- Liquid:Stabilized aqueous formulations serve automated clinical analyzers and point-of-care devices, with glycerol and buffer optimization extending refrigerated shelf life to 24 months.
- Tablets:Pre-measured solid doses support field-deployable glucose detection kits and educational laboratory settings requiring simplified handling protocols.
- Granules:Intermediate particle sizes bridge powder flowability and dissolution kinetics for specific food processing equipment configurations.
Powder formulations anchor the volume base while liquid preparations expand most quickly through clinical automation adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA enzyme classification standards and EMA pharmaceutical excipient monographs shape investment patterns across the dominant geographies. Diagnostic manufacturers cluster near regulatory hubs with established quality infrastructure. Fermentation capacity concentrates where electricity costs and strain IP access align favorably.
United States
Point-of-care glucose monitoring programs and hospital laboratory network consolidation drive specification premiums for engineered enzyme variants. FDA enzyme guidance documents mandate batch-level characterization that filters procurement toward certified fermentation houses. The diagnostics manufacturing belt spanning Massachusetts and North Carolina anchors domestic supply relationships with automated clinical analyzer producers.
Germany
Biosensor miniaturization programs and pharmaceutical biocatalysis applications sustain demand for high-purity formulations. REACH registration requirements and ECHA's updated enzyme substance characterization rules impose six-figure dossier burdens that consolidate procurement toward established suppliers. The industrial biotechnology corridor in Baden-Württemberg and North Rhine-Westphalia hosts specialized distributors serving diagnostic reagent manufacturers across the European Union.
China
Domestic diagnostic reagent production expansion and food preservation reformulation create volume demand for microbial-sourced preparations. NMPA pharmaceutical excipient standards and GB standards for food-grade enzymes enforce purity thresholds that redirect contracts toward captive fermentation operations. The Yangtze River Delta biotech clusters near Shanghai and Suzhou attract capacity investments targeting Asian hospital laboratory networks.
India
Production-linked incentives for fermentation-based manufacturing and import substitution in diagnostic reagents attract capacity buildout. CDSCO pharmaceutical-grade enzyme regulations and FSSAI food safety standards shape local quality system investments. The biotechnology corridor in Karnataka and Maharashtra hosts emerging suppliers targeting reduced logistics exposure to South Asian and Middle Eastern markets.
Japan
Aging demographics and point-of-care device proliferation sustain premium pricing for stabilized liquid formulations. PMDA pharmaceutical excipient requirements and METI industrial biotechnology promotion frameworks guide supplier qualification protocols. The Kansai region around Osaka retains specialized enzyme engineering capabilities for biosensor calibration standards and research consumables.
Glucose Oxidase Market Vendor Landscape
Fermentation specialists and diagnostic-grade formulators split the market through divergent capability investments. Three to five legacy houses control foundational Aspergillus niger strain IP, while mid-volume extractors compete on food-grade commodity volumes. Strategic consolidation centers on quality system certification attainment and direct-to-laboratory distribution channel development.
Within the premium-tier vector, Novozymes anchors global fermentation infrastructure across multiple continents. BBI Solutions exemplifies diagnostic-grade specialization through deep formulation expertise for biosensor applications. Royal DSM occupies a position extending biotechnology portfolios into high-purity enzyme segments for regulated industries. These three represent the archetype spectrum spanning scale, specialization, and portfolio breadth.
| Leading Market Players |
|---|
| Royal DSM |
| BBI Solutions |
| Novozymes |
| Merck KGaA |
| AB Enzymes |
| Amano Enzyme Inc. |
| Sigma-Aldrich |
| Biocatalysts |
| DuPont |
| Others |
Supply Flow & Price Mechanics
REACH registration cost escalation determines both the widening spread between diagnostic-grade and industrial-grade pricing tiers and the consolidation of supply relationships toward established fermentation houses with existing mammalian toxicity dossiers. ECHA's six-figure dossier preparation burdens compress margins for mid-volume suppliers while redirecting procurement toward certified producers capable of sustaining batch-level characterization investments.
Pricing Analysis
Configured-to-order pricing for engineered recombinant variants with enhanced thermal stability commands substantial premiums over standard Aspergillus niger extracts. The market operates on a contract-based long-term offtake structure with quality grade and ISO 13485 certification level as primary price differentiation drivers. Cost compression in industrial-grade powder formulations is intensifying because European electricity cost escalation has raised lyophilization expenses. Food manufacturers exhibit the highest price sensitivity due to quarterly contract indexing, while diagnostic reagent producers accept premium pricing for validated supply security.
Supply Chain Analysis
Extended payment terms from supply-chain finance facilities have become critical competitive tools for fermentation houses competing for diagnostic manufacturer contracts. Raw material sourcing draws from Aspergillus niger cultivation media, specialized filtration resins, and pharmaceutical-grade buffer systems anchored in Germany, the United States, and China's Yangtze River Delta biotech clusters. Single-source vulnerability around foundational strain IP controlled by legacy fermentation houses creates structural supply risk. Distribution runs through specialty enzyme distributors bypassing traditional chemical intermediaries to serve hospital laboratory networks directly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as hospital laboratory networks unbundle enzyme supply from analyzer maintenance contracts, creating niches for specialized distributors with technical service capabilities.
For Market Incumbents: Harden quality system certification moats by accelerating ISO 13485 validation cycles for engineered enzyme variants before emerging fermentation specialists achieve compliance. Deepen backward integration into Aspergillus niger strain development capabilities to reduce dependency on legacy IP holders. Defensive consolidation through captive supply relationships with diagnostic manufacturers facing EMA tightened contaminant thresholds will secure pricing power. For New Entrants and Emerging Players: India's biotechnology corridor underpenetration by established diagnostic-grade suppliers presents immediate white-space opportunity. Target food preservation reformulation demand in South Asian markets with clean-label positioning leveraging local fermentation capacity under PLI scheme incentives. Direct-to-laboratory distribution partnerships with hospital procurement offices offer the most penetrable go-to-market angle against incumbent chemical intermediary relationships. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated fermentation specialists with existing REACH dossiers and ISO 13485 quality systems. Long-term viability across the analysis window hinges on regulatory data digitization capabilities and protein engineering talent retention. Acquisition target archetype: mid-volume extractors with food-grade revenue bases and unfinished diagnostic-grade certification investments. Monitor ECHA enforcement patterns on enzyme substance characterization as the inflection indicator for procurement consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Processing Adoption | Immobilized enzyme reactor technology opens pharmaceutical manufacturing applications beyond diagnostics. |
| Regulatory Data Digitization | Batch-level traceability systems satisfy EMA pharmaceutical excipient monograph requirements. |
| Direct-to-Laboratory Distribution | Specialty distributors capture margin from hospital network procurement unbundling. |
| Strain Engineering Investment | Recombinant variant development addresses biosensor miniaturization thermal stability demands. |
| Quality System Certification | ISO 13485 validation enables diagnostic-grade contract access under FDA enzyme guidance. |
Methodological Framework
The analysis maps microbial, animal, plant, and synthetic production modes, each validated through fermentation process engineers, diagnostic reagent procurement managers, food manufacturing R&D directors, and hospital laboratory supply chain coordinators. Primary interview intelligence triangulates against FDA enzyme guidance documents, EMA pharmaceutical excipient monographs, REACH registration databases, and SEC filings from publicly traded biotechnology suppliers. Bottom-up volume modeling across formulation types and applications reconciles with top-down market sizing from trade flow analysis.
Assumptions held fixed include regulatory framework stability across major jurisdictions and continued Aspergillus niger dominance in commercial production economics. Variables tested include biosensor miniaturization adoption velocity, clean-label food preservation substitution rates, and hospital network consolidation patterns. Segmentation dimensions encompass product source, application certification grade, end-user procurement authority, and formulation type. CAGRs derive from elasticity-adjusted demand projections and capacity expansion timelines. Industry-specific inputs include fermentation yield improvement curves and lyophilization energy cost trajectories.
Practitioners should monitor ECHA enforcement intensity on enzyme substance characterization, FDA enzyme classification standard evolution, and European electricity cost volatility for early signals of forecast revision necessity. Assumptions underlying projections reflect current regulatory trajectories and technology adoption patterns. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Biotechnology
North America Eubiotics Market
Food Biotechnology
Biopreservation Market
Food Biotechnology
Colostrum Market
Food Biotechnology
Bangladesh Starch and Starch Derivative Market
Food Biotechnology
Africa Eubiotics Market
Food Biotechnology
Biotech Flavors Market
Food Biotechnology
Microalgae Market
Food Biotechnology
Beta-Propeller Phytases Market
Food Biotechnology
Non-Animal Alternative Testing Market
Food Biotechnology
Global Food Biotechnology Market
Food Biotechnology
Casein Peptone Market
Food Biotechnology
Apigenin Market
Food Biotechnology
Fruit and Vegetable-Derived Enzymes Market
Food Biotechnology
Chlorella Market
Food Biotechnology
Brown Algae Protein Market
Food Biotechnology
Genistein Market