
 Zein Protein Market | 2026-2036
Zein Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Zein Protein Market Analysis
Capital-intensity divergence between integrated grain processors and specialty ingredient startups is unwinding competitive stability in zein extraction. Roquette Frères leverages its European wet-milling infrastructure to sustain volume leadership in pharmaceutical-grade supply. BIOZEIN TECHNOLOGY CORP. LTD. anchors its position through proprietary solvent-free extraction patents that differentiate output for food coating segments. Cargill, Incorporated dominates upstream corn supply chains, extending cost advantages that smaller formulators struggle to match.
Zein protein constitutes a prolamin fraction extracted from maize endosperm, comprising roughly 45-50% glutamine and 20% leucine by amino acid profile, with industrial utility hinging on its film-forming and moisture-barrier properties. Powder and film forms command the widest commercial footprint, with film variants capturing premium margins in pharmaceutical coating where barrier performance determines dosage stability. Corn-derived zein retains overwhelming source dominance, though wheat and rice alternatives are gaining traction in allergen-sensitive formulation channels where label-clean requirements restrict maize declarations.
FDA excipient guidelines and EMA quality standards for pharmaceutical coatings directly shape purity thresholds and analytical certification burdens for zein suppliers seeking dual-market access. The EU Green Deal and REACH chemical safety protocols are simultaneously pressuring petrochemical coating alternatives while creating preferential procurement pathways for biodegradable plant-derived films. Stakeholders must monitor evolving pharmacopeial monograph revisions and bioplastics certification schemes to anticipate which delivery modes and source claims will unlock premium positioning.
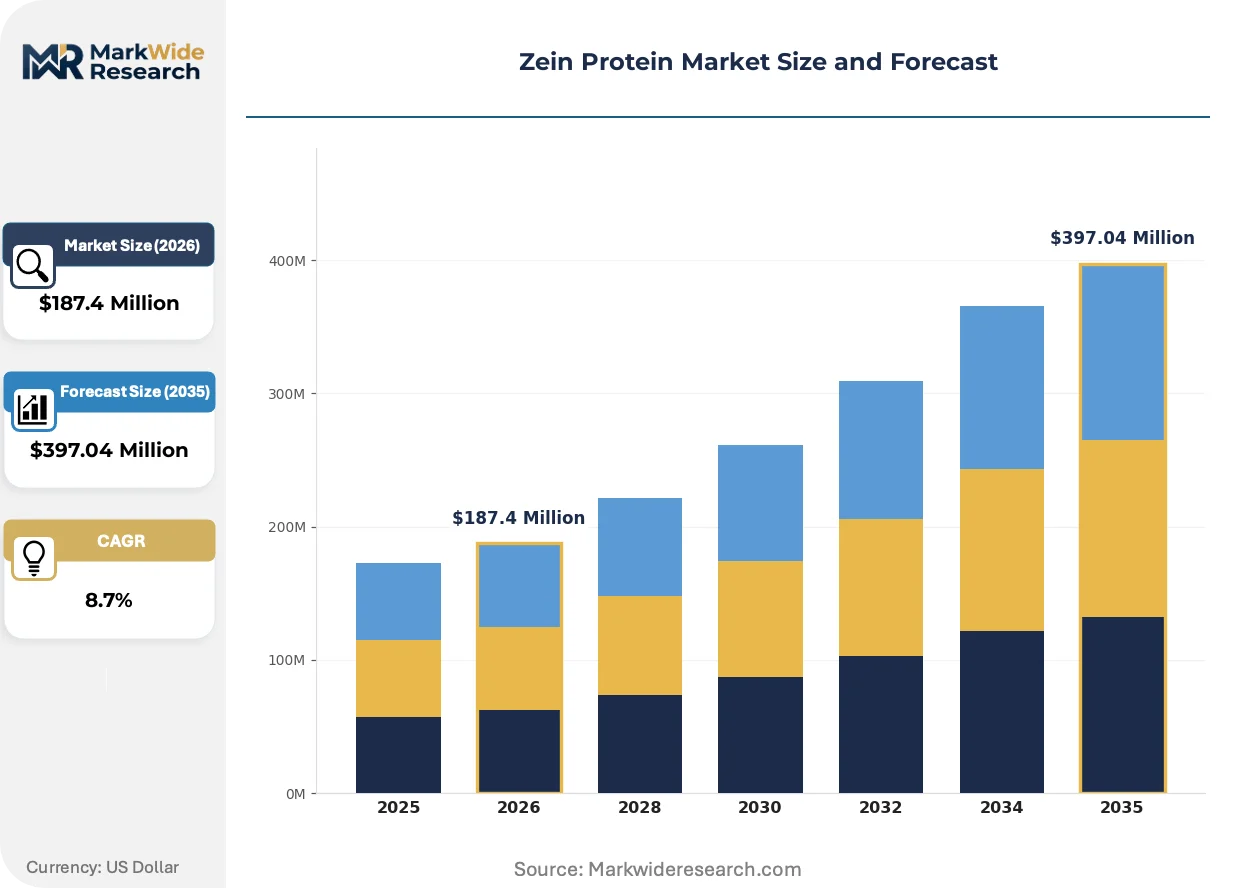
Market Dynamics
Pharmaceutical manufacturers are accelerating their shift from synthetic polymer coatings to plant-derived alternatives, compressing formulation timelines and rewriting supplier qualification protocols for excipient-grade zein.
Growth Catalysts
- EMA pharmaceutical coating standards:Tightening purity thresholds for biocompatible excipients are disqualifying petrochemical alternatives and opening procurement pathways for certified zein suppliers.
- Midwest corn processing concentration:Integrated wet-milling infrastructure in Iowa and Illinois delivers cost-competitive feedstock proximity that specialty extractors elsewhere cannot replicate.
- Solvent-free extraction patents:Proprietary aqueous processing technologies are eliminating residual solvent concerns that previously blocked food-grade applications in allergen-sensitive markets.
Market Restraints
- Maize price volatility:Corn futures fluctuation tied to ethanol policy and weather patterns injects input cost instability that squeezes margin predictability for non-integrated processors.
- Midwest supply concentration:Overwhelming dependence on United States corn belt extraction capacity creates geographic risk exposure for European and Asian formulators seeking dual-source security.
- Protein yield limitations:Zein constitutes only 2.5-3.0% of corn kernel mass, constraining volume scalability relative to soy or wheat protein alternatives.
Strategic Opportunities
- EU Green Deal bioplastics procurement:Mandatory biodegradable content thresholds in pharmaceutical and food packaging are creating preferential purchasing channels for plant-derived film formers.
- Wheat and rice zein variants:Allergen-free source diversification unlocks formulation access to clean-label segments where maize declarations face consumer rejection.
- Pharmacopeial monograph expansion:Emerging national drug compendia in India and Brazil are establishing new certification pathways for excipient-grade suppliers ahead of competitor entry.
Industry Challenges
- Pharmaceutical-grade certification timelines:FDA Type II drug master file preparation and EMA excipient quality data submission cycles extend 18-24 months, delaying revenue recognition for new entrants.
- Specialized extraction engineering talent:Scarce expertise in prolamin fractionation and solvent recovery system design limits operational scale-up for mid-cap processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zein Protein Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Food Products, Nutraceuticals, Pharmaceuticals, Biodegradable Plastics Form: Powder, Granules, Filaments, Films Source: Corn, Wheat, Rice, Others Delivery Mode: Direct Incorporation, Encapsulation, Coating, Spraying |
| Companies Covered | Global Protein Products Inc., Glanbia plc, Roquette Frères, Prairie Gold, BIOZEIN TECHNOLOGY CORP. LTD., Cargill, Incorporated, Archer Daniels Midland, Ingredion, Flo Enterprises LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zein Protein Market Emerging Trajectories
Active reformulation across pharmaceutical and food coating segments is dismantling established supply relationships and creating entry points for biotechnology-enabled zein variants with performance-tuned barrier properties.
Aqueous enzymatic extraction is supplanting conventional alcohol-based zein recovery in pharmaceutical-grade production. European coating houses are adopting the technology to eliminate residual solvent certification burdens. The shift is compressing supplier qualification timelines and enabling just-in-time excipient procurement models previously blocked by solvent-handling logistics.
REACH chemical safety protocols and the EU Green Deal are accelerating substitution mandates for petroleum-derived coating polymers. Industrial consequence includes mandatory biodegradability testing and carbon footprint disclosure for film-forming excipients. Pharmaceutical contract manufacturers in Germany and the Netherlands are responding by dual-sourcing zein alongside synthetic alternatives to hedge regulatory compliance risk.
Formulators are consolidating supplier relationships around integrated grain processors capable of delivering certified excipient-grade material with batch-level traceability. The concentration is displacing fragmented spot-market purchasing that dominated early zein adoption. United States-based drug manufacturers are driving this consolidation most visibly, leveraging proximity to Midwest extraction infrastructure to compress lead times and audit costs.
Zein Protein Market Segmentation
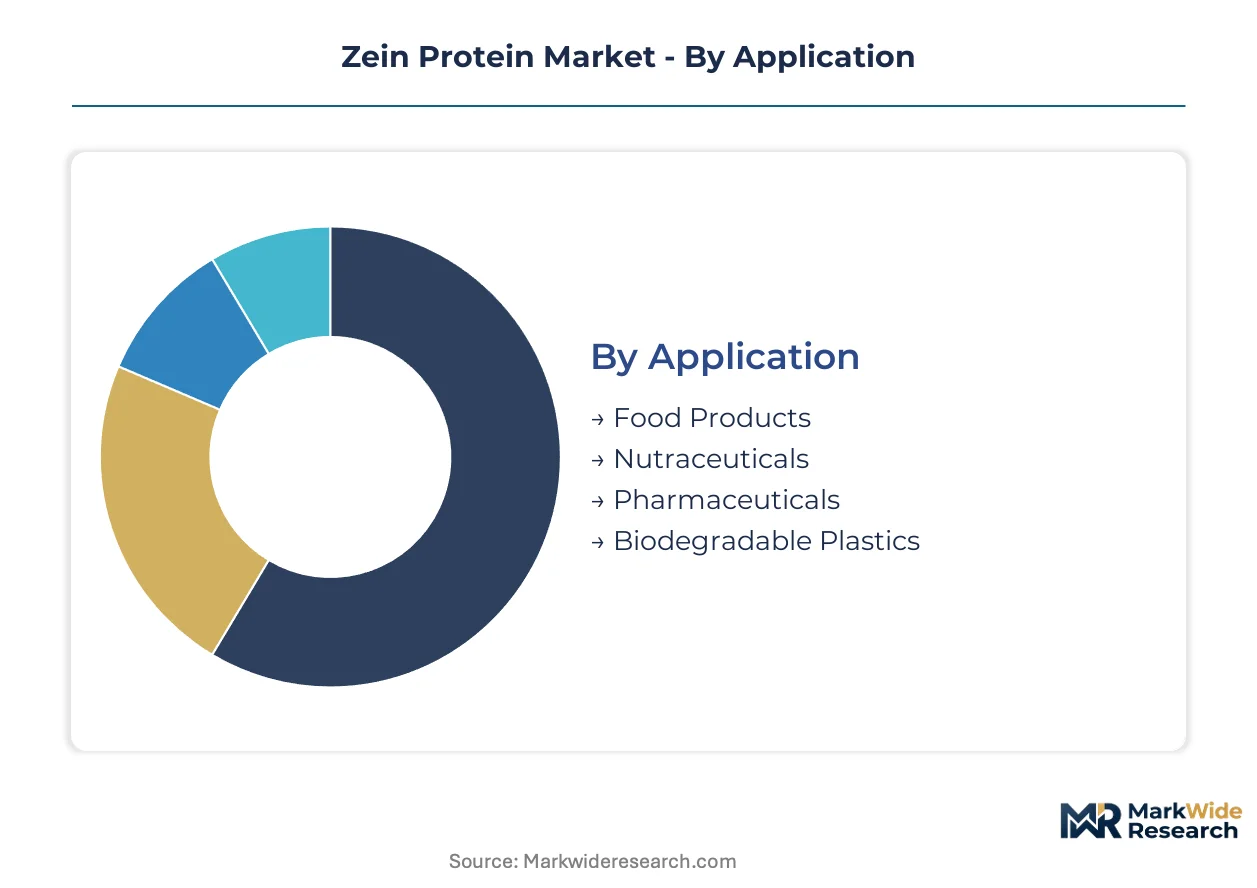
Zein protein's commercial value hinges on matching specific functional properties to end-use requirements across highly divergent regulatory environments. Segmentation reveals where formulation complexity and certification burdens concentrate margin capture.
Application:
Pharmaceutical encapsulation commands the steepest premium tiers due to FDA and EMA excipient qualification protocols that filter out commodity-grade suppliers.
- Pharmaceuticals:Drug manufacturers specify zein for enteric coatings and controlled-release matrices where moisture barrier performance determines dosage stability. EMA tightening of biocompatible excipient purity thresholds is disqualifying synthetic polymer alternatives and opening procurement pathways for certified suppliers in Germany and the Netherlands.
- Food Products:Edible coatings for nuts, candies, and fresh produce exploit zein's oxygen barrier and gloss properties. Clean-label momentum in United States retail channels is displacing shellac and petroleum-derived coatings, though allergen labeling requirements for maize-derived ingredients constrain formulation flexibility in European markets.
- Nutraceuticals:Dietary supplement encapsulation leverages zein's plant-based positioning for vegan capsule alternatives to gelatin.
- Biodegradable Plastics:Film formers for agricultural mulch and food service ware respond to EU Green Deal mandatory biodegradability thresholds.
Pharmaceuticals holds installed capacity. Biodegradable Plastics is rotating up the share rankings.
Form:
Physical configuration determines processing equipment compatibility and downstream value-add potential, with film variants requiring the most specialized extraction and casting infrastructure.
- Films:Cast or extruded sheets serve pharmaceutical tablet coating, food packaging laminates, and agricultural applications. European coating houses in the Netherlands and Germany are adopting aqueous enzymatic production to eliminate residual solvent certification burdens that previously blocked just-in-time procurement models.
- Powder:Spray-dried or precipitated particulates constitute the baseline commercial form for direct incorporation into food batters, pharmaceutical granulations, and bioplastic compounding. Midwest United States wet-milling clusters deliver cost-competitive powder volumes that specialty extractors elsewhere struggle to match on freight-adjusted terms.
- Granules:Agglomerated particles optimize flow properties for high-speed pharmaceutical tableting lines.
- Filaments:Extruded fibers enable textile and 3D printing feedstock applications where thermal processing tolerance matters.
Powder dominates volume throughput. Films is climbing the fastest on value per kilogram.
Source:
Botanical origin dictates allergen profile, amino acid composition, and supply chain geography, with maize retaining overwhelming production concentration despite emerging alternatives.
- Corn:Maize endosperm extraction yields the established commercial standard with 45-50% glutamine and 20% leucine amino acid profiles. Iowa and Illinois wet-milling infrastructure anchors global supply, though protein yield limitations at 2.5-3.0% of kernel mass constrain volume scalability relative to oilseed alternatives.
- Wheat:Triticum-derived zein fractions offer allergen-free positioning for clean-label formulations where maize declarations face consumer rejection in European and Japanese markets. Commercial scale remains limited by fractionation complexity and gluten co-extraction challenges.
- Rice:Oryza sativa sources provide hypoallergenic properties for infant nutrition and sensitive demographic segments.
- Others:Sorghum and millet prolamins occupy research-phase niches with unproven commercial extraction economics.
Corn holds installed capacity. Wheat is rotating up the share rankings.
Delivery Mode:
Integration method into final formulations determines equipment capital requirements and supplier technical service intensity, with encapsulation demanding the deepest application expertise.
- Encapsulation:Active ingredient entrapment within zein matrices protects probiotics, vitamins, and pharmaceuticals from gastric degradation. United States and German drug manufacturers are consolidating supplier relationships around integrated processors capable of batch-level traceability documentation for FDA Type II drug master file submissions.
- Coating:Pan or fluid-bed deposition creates functional barriers on tablets, confections, and agricultural seeds. The shift from synthetic polymers is compressing supplier qualification timelines as pharmaceutical contract manufacturers dual-source to hedge REACH compliance risk.
- Direct Incorporation:Dry blending into food batters or bioplastic resins minimizes processing steps but sacrifices barrier performance optimization.
- Spraying:Atomized application enables uniform thin-film deposition on irregular surfaces for fresh produce and nut coatings.
Coating holds installed capacity. Encapsulation is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power tilts toward United States processors commanding Midwest corn belt proximity, while European formulators absorb freight premiums and certification burdens for pharmaceutical-grade supply security.
United States
Pharmaceutical contract manufacturers in New Jersey and North Carolina drive excipient-grade zein procurement for enteric coating applications. FDA Type II drug master file requirements filter out non-integrated suppliers, consolidating purchasing around Iowa and Illinois wet-milling clusters. Cargill and Archer Daniels Midland anchor production capacity near Decatur, Illinois, where captive corn supply chains compress unit economics below import-parity levels for European competitors.
Germany
REACH chemical safety protocols and EU Green Deal biodegradability mandates are accelerating substitution away from petroleum-derived coating polymers. EMA tightening of biocompatible excipient purity thresholds opens procurement pathways for certified zein suppliers serving Heidelberg and Munich pharmaceutical manufacturing zones. Dutch and German coating houses are dual-sourcing to hedge compliance risk, creating demand pull for aqueous enzymatic extraction technologies that eliminate residual solvent certification burdens.
China
Domestic nutraceutical encapsulation demand is expanding as dietary supplement manufacturers seek plant-based alternatives to gelatin capsules. NMPA pharmacopeial standards for excipient-grade materials are evolving toward alignment with USP and EP monographs, extending certification timelines for new entrants. Shandong Province wet-milling infrastructure is scaling solvent-free extraction capacity to serve both domestic formulators and export markets requiring allergen-free source documentation.
India
CDSCO emerging national drug compendia revisions are establishing new certification pathways for excipient-grade suppliers ahead of competitor entry in controlled-release matrix applications. Maharashtra and Gujarat pharmaceutical manufacturing corridors are consolidating supplier relationships around integrated processors capable of batch-level traceability documentation. BIS quality standards for food-grade coatings are simultaneously displacing shellac in confectionery applications across Mumbai and Pune processing clusters.
Brazil
ANVISA pharmaceutical regulator guidelines on excipient safety are tightening purity requirements for biocompatible coating materials in São Paulo and Rio de Janeiro manufacturing zones. Corn-derived zein imports from United States suppliers dominate current supply, though domestic fractionation capacity is emerging near Campinas to reduce freight exposure. Clean-label momentum in retail confectionery channels is creating parallel demand for edible coating applications where allergen labeling requirements favor maize-derived alternatives over shellac.
Zein Protein Market Vendor Landscape
Concentration sits with integrated grain processors commanding captive corn supply chains and wet-milling infrastructure. The vendor base stratifies across three tiers: multinational agribusiness conglomerates with backward integration into upstream feedstock, European specialty ingredient houses leveraging pharmaceutical-grade certification assets, and regional fractionators competing on spot-market powder volumes. Dominant competitive moves include capacity expansion near Midwest corn processing clusters and technology licensing agreements for aqueous enzymatic extraction patents that bypass residual solvent regulatory burdens.
Within the integrated agribusiness tier, Cargill, Incorporated and Archer Daniels Midland exemplify scale-driven positioning through captive supply chain control over Iowa and Illinois corn belt infrastructure. Roquette Frères occupies a position within the European specialty ingredient archetype, leveraging pharmaceutical-grade certification assets to serve EMA-regulated coating houses in Germany and the Netherlands. BIOZEIN TECHNOLOGY CORP. LTD. represents the technology-differentiated segment, with its corporate name signaling proprietary extraction specialization that anchors positioning for food coating segments requiring solvent-free process claims.
| Leading Market Players |
|---|
| Global Protein Products Inc. |
| Glanbia plc |
| Roquette Frères |
| Prairie Gold |
| BIOZEIN TECHNOLOGY CORP. LTD. |
| Cargill, Incorporated |
| Archer Daniels Midland |
| Ingredion |
| Flo Enterprises LLC |
| Others |
Supply Flow & Price Mechanics
Midwest wet-milling capacity utilization above 85 percent compresses unit economics for Iowa and Illinois processors, creating price floors that non-integrated extractors in Europe and Asia cannot match without freight-adjusted premiums. This scale concentration locks pharmaceutical-grade supply around Cargill and Archer Daniels Midland infrastructure, while specialty aqueous enzymatic producers in Germany and China capture configured-to-order premiums for solvent-free certification.
Pricing Analysis
The customization-premium spread separates commodity powder volumes from pharmaceutical-grade film configurations, with FDA Type II drug master file documentation adding certification-tier premiums atop base extraction costs. Price differentiation hinges on purity grade and batch-level traceability, with EMA-regulated coating houses in Germany and the Netherlands absorbing the highest premiums for residual-solvent-free supply. Pricing pressure stems from maize futures volatility tied to ethanol policy shifts, squeezing margin predictability for non-integrated processors. Food-grade powder buyers in Brazil and India exhibit the greatest price sensitivity, while pharmaceutical contract manufacturers prioritize supply security over unit cost.
Supply Chain Analysis
The United States anchors global zein extraction through Iowa and Illinois wet-milling clusters, with China scaling Shandong Province capacity for domestic nutraceutical and export allergen-free markets. Germany and the Netherlands host European pharmaceutical coating demand but lack upstream corn fractionation infrastructure, creating import dependence. Raw material flows draw from corn belt harvests, aqueous enzymatic processing chemicals, and pharmaceutical-grade packaging films. Single-source vulnerability concentrates in Midwest supply geography, exposing European and Asian formulators to logistics disruption. Distribution runs through integrated processor direct contracts for pharmaceutical volumes, with spot-market powder trading serving food-grade applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Zein protein procurement is evolving into a service-attach market, with technical documentation, batch certification, and formulation support expanding faster than base extraction revenue. Pharmaceutical contract manufacturers now expect supplier-managed regulatory submission packages as standard contract terms.
For Market Incumbents: Consolidate supplier relationships around captive corn supply chains and aqueous enzymatic patent licensing to defend against European specialty houses eroding pharmaceutical-grade share. Add solvent-free capacity in Illinois or Iowa to preempt Shandong Province competitors from capturing EMA-regulated coating demand. Certification investment in emerging pharmacopeial monographs for India and Brazil locks in first-mover positioning ahead of CDSCO and ANVISA alignment with USP standards.
For New Entrants and Emerging Players: Lead with wheat and rice zein fractionation to penetrate European and Japanese clean-label segments where maize declarations face consumer rejection. Target Indian pharmaceutical manufacturing corridors in Maharashtra and Gujarat with batch-traceability documentation capabilities that domestic wet-millers lack. Position through aqueous enzymatic technology licensing rather than capital-intensive capacity buildout.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated processors with backward corn supply control and pharmaceutical-grade certification assets over standalone extraction technology plays. Long-term viability hinges on EMA and FDA excipient guideline convergence tightening purity thresholds that filter out commodity suppliers. Acquisition target archetype: regional wet-millers with underutilized fractionation capacity and latent pharmaceutical-grade certification pathways. Watch NMPA pharmacopeial alignment with USP and EP monographs as the inflection signal for Chinese market entry timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Adds solvent-free extraction lines near Decatur, Illinois to serve FDA-regulated pharmaceutical coating demand. |
| Backward Integration | Captures Iowa and Illinois corn supply chains to compress feedstock costs below import-parity levels for European competitors. |
| Green Manufacturing Transition | Deploys aqueous enzymatic processing to eliminate residual solvent certification burdens under REACH protocols. |
| Long-term Supply Agreement | Locks Heidelberg and Munich pharmaceutical manufacturers into multi-year excipient procurement with batch-traceability guarantees. |
| Joint Venture | Pairs Midwest wet-milling infrastructure with Dutch coating house formulation expertise for EMA-compliant film production. |
Methodological Framework
Initial hypotheses were tested against primary input from pharmaceutical procurement managers, food coating formulators, wet-milling operations directors, and regulatory affairs specialists, then refined through secondary validation. Primary fieldwork encompassed structured interviews across Iowa, Illinois, Germany, and Shandong Province processing clusters. Secondary sources included FDA Type II drug master file databases, EMA excipient quality data submissions, USP and EP pharmacopeial monographs, and customs trade records for corn-derived protein fractions. Bottom-up capacity modeling triangulated against top-down end-use demand segmentation across pharmaceutical, food, and biodegradable plastics applications.
Variance decomposition across the projection horizon isolates volume drivers (pharmaceutical encapsulation adoption, EU Green Deal bioplastics mandates) from price drivers (maize futures volatility, certification tier premiums). Segmentation dimensions encompass application type, physical form, botanical source, and delivery mode, with regional regulatory cluster effects modeled separately. CAGRs derive from fitted growth curves anchored to disclosed capacity expansion timelines and pharmacopeial monograph revision schedules. Industry-specific inputs include corn protein yield coefficients, solvent recovery system capital costs, and pharmaceutical-grade certification timeline distributions.
Forecasts assume regulatory continuity in FDA, EMA, NMPA, CDSCO, and ANVISA excipient frameworks; material policy shifts would require re-modeling. Specific risks include REACH chemical safety protocol expansion, ethanol policy-driven maize price spikes, and aqueous enzymatic patent litigation disrupting technology licensing channels. Recalibration cycles align with material shifts in pharmacopeial monograph revisions and bioplastics certification scheme updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Biotechnology
Glucose Oxidase Market
Food Biotechnology
Beta Lactoglobulin Protein Market
Food Biotechnology
South America Feed Prebiotics Market
Food Biotechnology
Cultured Meat Market
Food Biotechnology
Trans-Galactooligosaccharides Market
Food Biotechnology
Global Food Biotechnology Market
Food Biotechnology
North America Eubiotics Market
Food Biotechnology
Chlorella Market
Food Biotechnology
Asia Pacific Eubiotics Market
Food Biotechnology
Phycocyanin Market
Food Biotechnology
Bangladesh Starch and Starch Derivative Market
Food Biotechnology
Fruit and Vegetable-Derived Enzymes Market
Food Biotechnology
Salmon Polynucleotide (PN) Market
Food Biotechnology
Global Feed Enzymes Market
Food Biotechnology
Lupin Protein Market
Food Biotechnology
Bovine Colostrum Market