
 Asia Pacific Eubiotics Market | 2026-2036
Asia Pacific Eubiotics Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Eubiotics Market Outlook
Organic acids is pivoting toward probiotic blends as feed formulators seek pH stability and gut microbiome modulation in a single additive. Chr. Hansen A/S leverages its microbial strain library to dominate probiotic supply for ruminant applications across Australia and New Zealand. DSM Nutritional Products Inc sustains R&D intensity in enzyme thermostability, anchoring its position in Southeast Asian aquaculture feed mills. Biomin Holding GmbH specializes in mycotoxin-binding organic acid complexes, occupying a defensible niche in Vietnam's expanding swine sector.
Eubiotics comprise live microorganisms, fermentable fibers, short-chain fatty acids, and exogenous enzymes administered to modulate host gastrointestinal microbiota and enhance nutrient assimilation; formulations typically specify colony-forming units per gram for probiotics and minimum acid purity percentages for organic acid salts. Their primary commercial purpose centers on replacing sub-therapeutic antibiotics in animal production systems while maintaining feed conversion efficiency and reducing pathogenic load. Probiotics commands the largest revenue share due to established efficacy data in poultry gut health, though organic acids generates the fastest growth as Asian swine operations adopt acidification protocols to control post-weaning diarrhea. Enzymes concentrates margin pools in phytase and xylanase variants tailored to regional grain compositions, particularly corn-soy versus wheat-based diets prevalent across South Asia.
China's SAMR enforces GB standards for feed additive safety and residue limits, while India's FSSAI and BIS jointly regulate eubiotic quality thresholds for imported and domestic products; Australia's TGA and APVMA coordinate on veterinary probiotic registration pathways, creating a fragmented compliance landscape that favors manufacturers with multi-jurisdictional dossier expertise. The EU Green Deal's anticipated extraterritorial reach through supply chain due diligence requirements will pressure Southeast Asian exporters to certify deforestation-free sourcing for prebiotic substrates such as inulin and fructooligosaccharides. Stakeholders must monitor regulatory divergence between China's national standards and Codex Alimentarius guidelines to anticipate reformulation costs and market access barriers.
Market Dynamics
Livestock producers across Asia Pacific confront simultaneous pressure from antibiotic withdrawal mandates and feed conversion efficiency targets, forcing rapid reformulation of additive portfolios toward microbiome-modulating solutions.
Growth Catalysts
- China's GB standards for feed additive safety:Mandatory residue limits and safety protocols under SAMR enforcement accelerate domestic manufacturing of probiotic and organic acid alternatives to antibiotic growth promoters.
- India's PLI scheme for animal feed additives:Production-linked incentives reduce capital barriers for domestic fermentation capacity, expanding local supply of enzyme and probiotic formulations for poultry integrators.
- Integrated poultry operations in Shandong and Guangdong provinces:Bulk procurement contracts from vertically coordinated farms concentrate demand for standardized eubiotic blends, generating economies of scale for qualified suppliers.
Market Restraints
- Prebiotic substrate cost volatility:Inulin and fructooligosaccharide prices fluctuate with chicory root harvests in Europe and cassava processing yields in Southeast Asia, compressing margin predictability for blenders.
- Strain banking concentration:Probiotic manufacturing depends on microbial libraries concentrated among European and North American culture collection institutions, creating licensing bottlenecks for Asian formulators.
- Thermostability limitations in pelleting:Spore-forming probiotic strains tolerate feed extrusion temperatures poorly, restricting application in high-heat processed aquaculture feeds prevalent across Vietnam and Indonesia.
Strategic Opportunities
- Underpenetrated ruminant applications in Australia and New Zealand:Methane-reducing probiotic formulations for dairy and beef cattle remain nascent, offering first-mover positioning as environmental scrutiny intensifies.
- EU Green Deal extraterritorial due diligence:Deforestation-free certification requirements for prebiotic substrates create premium tier differentiation for suppliers with traceable inulin supply chains from non-palm sources.
- Direct-to-farm digital distribution platforms:E-commerce procurement channels bypass traditional feed mill intermediaries, enabling smaller swine operations in Vietnam and Thailand to access customized acidification protocols.
Industry Challenges
- Multi-jurisdictional dossier compilation:Divergent registration pathways between China's SAMR, India's FSSAI-BIS joint oversight, and Australia's TGA-APVMA coordination demand specialized regulatory affairs capacity that strains mid-tier manufacturers.
- Enzyme-customization capex requirements:Phytase and xylanase variants tailored to regional grain compositions require dedicated fermentation trains, raising facility investment thresholds for serving corn-soy versus wheat-based diet markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Eubiotics Market |
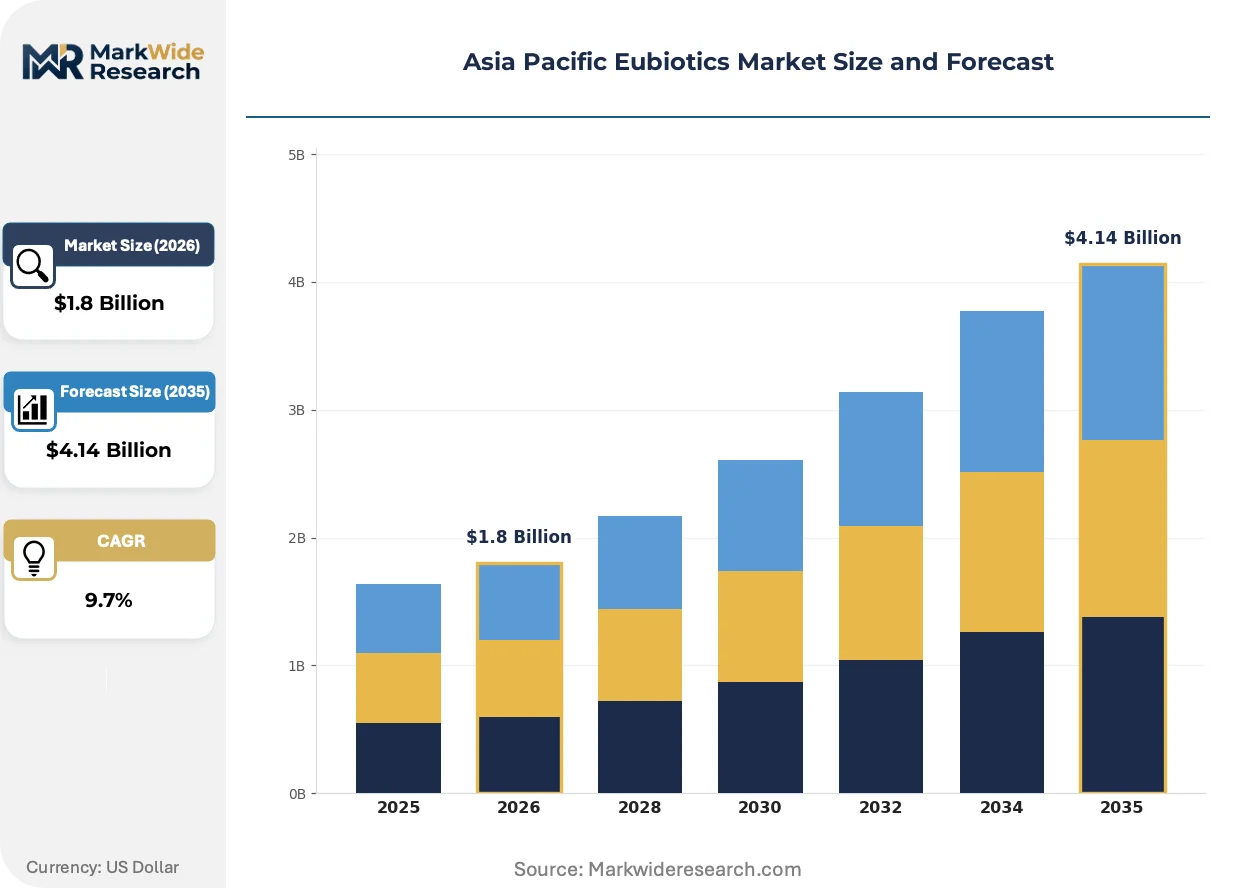
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prebiotics, Probiotics, Organic Acids, Enzymes Application: Animal Feed, Dietary Supplements, Functional Foods, Pharmaceuticals End User: Poultry, Swine, Ruminants, Aquaculture Distribution Channel: Online Retail, Offline Retail, Direct Sales, Distributors |
| Companies Covered | Chr. Hansen A/S, DSM Nutritional Products Inc, Biomin Holding GmbH, Bluestar Adisseo Company, Novonesis Group, IFF (Danisco Animal Nutrition & Health), dsm-firmenich, Lallemand Inc, Kemin Industries Inc, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Eubiotics Market Strategic Shifts
Microbial fermentation advances and precision nutrition platforms are compressing development cycles for next-generation eubiotic formulations, while regulatory harmonization pressures force alignment between national standards and Codex Alimentarius guidelines.
Encapsulation technology for organic acid and probiotic co-delivery is electrifying formulation stability in high-moisture feed environments. Australian and New Zealand ruminant feed mills adopt lipid-matrix coating systems at accelerating rates to protect viable cell counts through pelleting and storage. This convergence is compressing the performance gap between direct-fed microbials and antibiotic growth promoters in intensive grazing systems.
China's SAMR enforcement of GB standards for feed additive safety and residue limits tightens import scrutiny on non-domestic probiotic strains. Industrial consequence manifests in accelerated local strain isolation programs and joint venture fermentation partnerships between multinational suppliers and Chinese biotechnology platforms. Swine operations in Sichuan and Henan provinces face the steepest compliance recalibration as they transition from legacy acidifier blends to documented microbiome-modulating formulations.
Integrated poultry and swine operations consolidate procurement authority through captive feed manufacturing subsidiaries, disintermediating independent distributors. Large-scale producers in India's Maharashtra and Telangana states now specify colony-forming unit guarantees and acid purity certificates directly, bypassing regional compound feed intermediaries. This concentration is most visible in contract farming arrangements where integrators mandate standardized eubiotic protocols across their entire supplier base.
Asia Pacific Eubiotics Market Segmentation
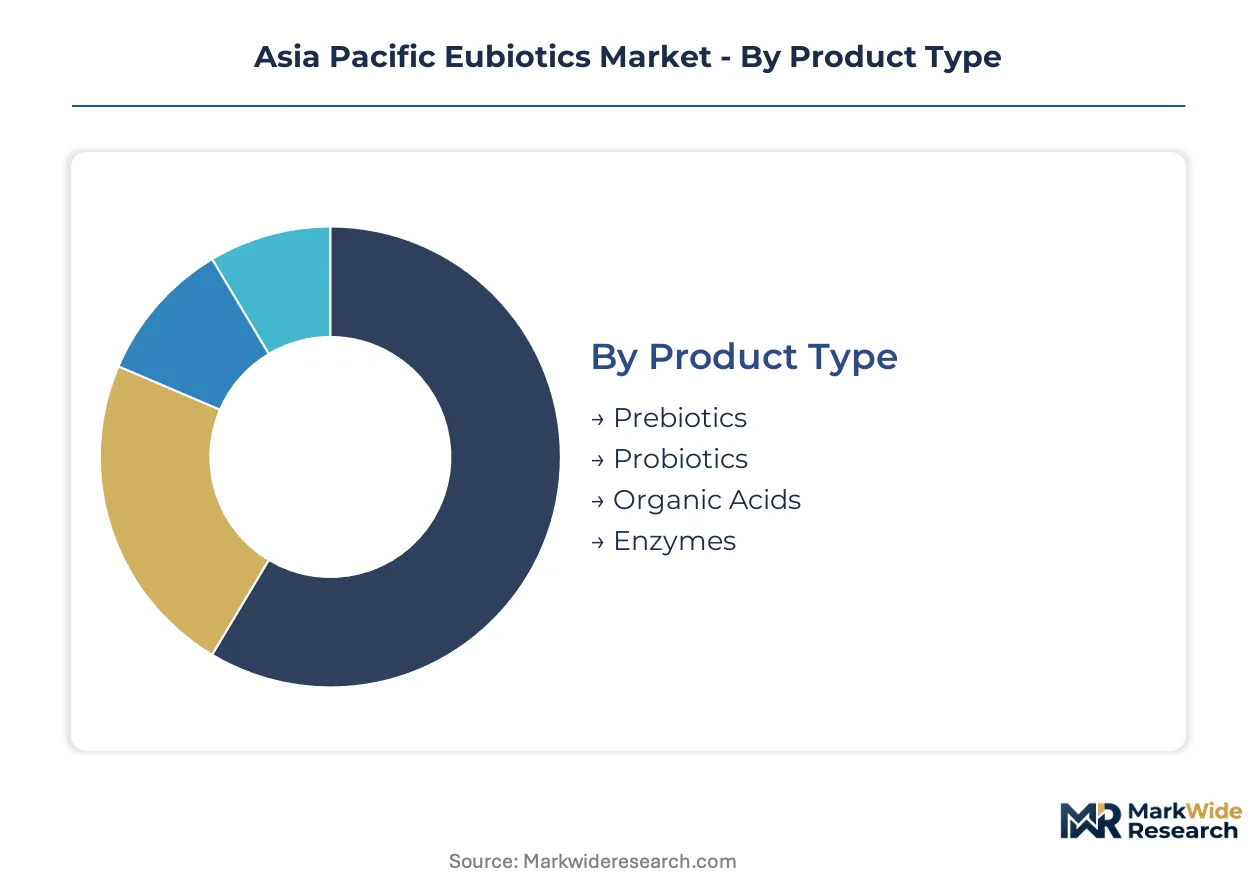
Eubiotics manufacturers in Asia Pacific configure product portfolios around species-specific gut health requirements and feed processing constraints. Segmentation discipline separates volume-driven commodity formulations from premium microbiome-modulating solutions.
Product Type:
Buyers prioritize thermostability and documented colony-forming unit retention through pelleting cycles.
- Probiotics:Live microbial cultures—primarily Bacillus subtilis, Lactobacillus, and Saccharomyces cerevisiae—delivered at specified CFU/g concentrations. Demand concentrates in China's Shandong province integrated poultry operations where integrators mandate standardized gut health protocols across entire supplier bases.
- Organic Acids:Short-chain fatty acid salts including formic, propionic, and butyric acid derivatives, often blended for pH modulation and pathogen suppression. Swine operations in Vietnam and Thailand adopt acidification protocols fastest to control post-weaning diarrhea amid antibiotic withdrawal mandates.
- Prebiotics:Fermentable oligosaccharides and inulin-based substrates that selectively nourish beneficial gut microbiota.
- Enzymes:Exogenous phytase, xylanase, and protease formulations tailored to regional grain compositions.
Probiotics leads on scale; organic acids leads on momentum.
Application:
Formulation complexity escalates with regulatory scrutiny and performance documentation requirements.
- Animal Feed:The dominant commercial channel, encompassing compound feed incorporation, premix blending, and direct-fed microbials. China's SAMR-enforced GB standards for residue limits and safety documentation accelerate reformulation toward documented microbiome-modulating alternatives in Sichuan and Henan swine operations.
- Dietary Supplements:Human-grade probiotic and prebiotic formulations targeting digestive wellness applications.
- Functional Foods:Fermented dairy, beverages, and fortified products with added microbial or fiber components.
- Pharmaceuticals:Clinical-grade preparations for therapeutic microbiome interventions.
Animal feed dominates absolute volume; dietary supplements shows steepest expansion trajectory.
End User:
Species physiology and production intensity dictate formulation specifications and delivery mechanisms.
- Poultry:Broiler and layer operations drive bulk demand for heat-stable probiotic strains and acidifier blends. India's Maharashtra and Telangana contract farming arrangements specify CFU guarantees and acid purity certificates directly, bypassing regional compound feed intermediaries.
- Swine:Post-weaning diarrhea control requirements prioritize organic acid complexes and targeted probiotic strains.
- Ruminants:Dairy and beef cattle applications emphasize methane-reducing microbial formulations.
- Aquaculture:Shrimp and finfish operations in Vietnam and Indonesia face thermostability constraints in high-heat extruded feeds.
Poultry leads on procurement concentration; swine leads on reformulation urgency.
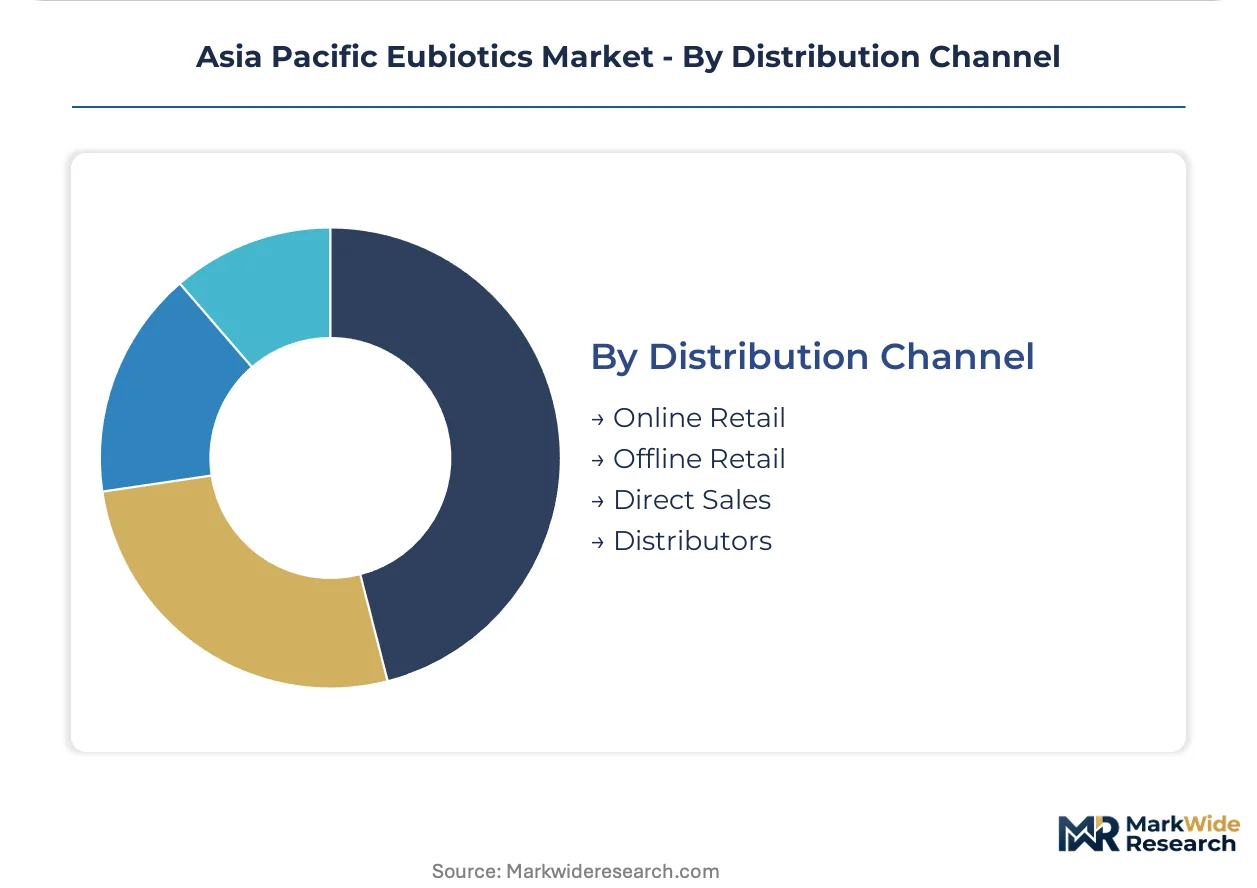
Distribution Channel:
Channel selection reflects operation scale, technical support needs, and regulatory compliance complexity.
- Direct Sales:Large integrators and captive feed manufacturers negotiate bulk contracts with technical service attachments. Vertically coordinated producers in Guangdong province consolidate procurement through subsidiary feed mills, disintermediating independent distributors entirely.
- Distributors:Regional compound feed blenders and smaller livestock operations rely on intermediary inventory and formulation support.
- Online Retail:E-commerce platforms enable smaller Vietnamese and Thai swine operations to access customized acidification protocols.
- Offline Retail:Traditional agricultural supply stores serving fragmented smallholder segments.
Direct sales commands margin pools; online retail gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong province anchors Asia Pacific eubiotics procurement through vertically integrated poultry operations that mandate standardized gut health protocols across entire supplier bases.
China
Integrated swine and poultry operations in Sichuan and Henan provinces drive bulk demand for documented microbiome-modulating formulations. SAMR enforcement of GB standards for feed additive safety and residue limits accelerates domestic strain isolation programs and joint venture fermentation partnerships. Guangdong province concentrates captive feed manufacturing subsidiaries that disintermediate independent distributors entirely.
India
Contract farming arrangements in Maharashtra and Telangana specify colony-forming unit guarantees and acid purity certificates directly from manufacturers. The PLI scheme for animal feed additives reduces capital barriers for domestic fermentation capacity expansion. Poultry integrators in these states now bypass regional compound feed intermediaries through direct procurement mandates.
Vietnam
Expanding swine operations adopt acidification protocols fastest to control post-weaning diarrhea amid antibiotic withdrawal pressures. Mycotoxin-binding organic acid complexes occupy defensible positioning as feed safety scrutiny intensifies. Aquaculture feed mills in the Mekong Delta region confront thermostability constraints in high-heat extruded shrimp and finfish feeds.
Australia
Dairy and beef cattle applications emphasize methane-reducing microbial formulations as environmental scrutiny intensifies across ruminant sectors. TGA and APVMA coordination on veterinary probiotic registration pathways creates compliance complexity that favors manufacturers with multi-jurisdictional dossier expertise. Feed mills adopt lipid-matrix coating systems to protect viable cell counts through pelleting and storage cycles.
Thailand
Smaller swine operations access customized acidification protocols through e-commerce procurement channels that bypass traditional feed mill intermediaries. Post-weaning diarrhea control requirements prioritize organic acid complexes and targeted probiotic strains. Bangkok-based distributors face margin compression as direct-to-farm digital platforms capture growing share of additive transactions.
Asia Pacific Eubiotics Market Competitive Environment
Global majors compete with regional champions across microbial strain access and fermentation capacity deployment. Market structure tilts toward consolidation at the probiotic supply tier while organic acid blending retains fragmentation. Three archetypes dominate: European culture collection licensors, Asian fermentation joint venture partners, and specialty acid complex formulators. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure thermostable strain access and regional manufacturing presence.
Within the culture collection licensing tier, Chr. Hansen A/S and DSM Nutritional Products Inc exemplify European-based players leveraging microbial libraries to anchor supply relationships across ruminant and aquaculture applications. Biomin Holding GmbH occupies a specialist position in mycotoxin-binding organic acid complexes. Among Asia-headquartered competitors, Bluestar Adisseo Company and Novonesis Group represent regional fermentation scale players. Lallemand Inc and Kemin Industries Inc sit within the North American-origin tier pursuing Asia Pacific expansion through technical service attachments.
| Leading Market Players |
|---|
| Chr. Hansen A/S |
| DSM Nutritional Products Inc |
| Biomin Holding GmbH |
| Bluestar Adisseo Company |
| Novonesis Group |
| IFF (Danisco Animal Nutrition & Health) |
| dsm-firmenich |
| Lallemand Inc |
| Kemin Industries Inc |
| Others |
Value Chain & Pricing Dynamics
Joint-venture fermentation partnerships between multinational suppliers and Chinese biotechnology platforms concentrate ownership of probiotic manufacturing capacity, tightening pricing discipline as domestic strain isolation programs reduce import dependency and compress margin pools for non-localized suppliers.
Pricing Analysis
Input-cost pass-through from chicory root harvest volatility and cassava processing yields in Southeast Asia intensifies margin compression for prebiotic blenders, while spore-forming strain thermostability premiums sustain price differentiation between standard acidifier formulations and lipid-matrix coated probiotic variants. Three-tier pricing structure across premium, standard, and economy levels separates CFU-guaranteed direct-fed microbials from commodity acid salts, with integrated poultry operations in Shandong province commanding volume discounts that independent Vietnamese swine farms cannot access. Pricing pressure stems from SAMR enforcement of GB documentation requirements, which raises compliance costs for imported strains. Smallholder aquaculture feed mills in Indonesia exhibit highest price sensitivity due to thermostability failure rates in high-heat extrusion.
Supply Chain Analysis
Local-content rules under India's PLI scheme for animal feed additives and China's GB standards for feed safety are reshaping sourcing patterns toward domestic fermentation capacity, reducing reliance on European culture collection licensing. Microbial strain libraries concentrate in Denmark and the Netherlands, while organic acid precursor chemicals feed from Chinese petrochemical complexes and Thai oleochemical processors. Single-source vulnerability in Bacillus subtilis strain access creates supply chain risk for Asian formulators lacking proprietary culture collections. Distribution runs through captive feed manufacturing subsidiaries of large integrators in Guangdong and Maharashtra, disintermediating regional compound feed distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia Pacific eubiotics market reads as a late-cycle quality story, with procurement concentration in integrated poultry operations forcing specification upgrades toward documented CFU retention and acid purity certification.
For Market Incumbents: Deepen backward integration into proprietary strain banking to escape European culture collection licensing bottlenecks, while expanding captive fermentation capacity in Shandong and Guangdong provinces to defend margin pools against domestic Chinese competitors. SAMR documentation requirements for GB standards compliance represent the critical regulatory threat demanding multi-jurisdictional dossier expertise as a defensive moat. For New Entrants and Emerging Players: Launch via direct-to-farm digital distribution platforms targeting smaller Vietnamese and Thai swine operations bypassed by captive feed mill subsidiaries of large integrators. Underpenetrated methane-reducing probiotic formulations for Australian and New Zealand ruminant applications offer the most penetrable white-space target, with environmental scrutiny intensifying demand for documented microbiome-modulating alternatives. For Investors and Strategic Acquirers: Animal health conglomerates seeking microbiome platform expansion are the most active acquirer in this space, with fermentation-scale specialists possessing thermostable strain libraries commanding premium positioning. Five-to-ten year viability hinges on deforestation-free certification capabilities for prebiotic substrates under EU Green Deal extraterritorial reach. Monitor divergence between China's SAMR enforcement trajectory and Codex Alimentarius harmonization progress as the critical inflection signal for reformulation cost exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Joint Venture Fermentation Partnership | Localizes probiotic manufacturing under China's SAMR GB standards compliance requirements. |
| Strain Library Acquisition | Secures thermostable Bacillus subtilis access for high-heat aquaculture feed applications. |
| Direct-to-Farm Digital Platform Launch | Bypasses captive feed mill intermediaries serving Vietnamese and Thai smallholder swine operations. |
| Deforestation-Free Certification Program | Qualifies prebiotic substrate suppliers for EU Green Deal supply chain due diligence compliance. |
| Lipid-Matrix Coating Capacity Expansion | Protects viable cell counts through Australian and New Zealand ruminant feed pelleting cycles. |
Study Parameters
Multiple input streams — regulatory filing analysis, customs trade data, and fermentation capacity databases — were reconciled against primary interviews with probiotic strain development directors, feed mill procurement managers, and veterinary regulatory affairs specialists across China, India, Vietnam, and Australia. Secondary validation drew from SAMR GB standard documentation, FSSAI-BIS joint oversight circulars, TGA-APVMA coordination protocols, and APVMA registration pathway records. Bottom-up volume modeling across species-specific application tiers triangulated with top-down value estimates derived from PLI scheme disbursement tracking and integrated poultry operation procurement disclosures.
Data-stream reconciliation anchored projections across the analysis window to segmentation dimensions spanning product type, species application, and distribution channel intensity. CAGRs were derived from elasticity modeling of antibiotic withdrawal mandate compliance timelines against feed conversion efficiency improvement curves. Industry-specific forecast inputs incorporated thermostability failure rates in Vietnamese aquaculture extrusion and methane-reducing formulation adoption curves in New Zealand dairy systems.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory divergence between China's SAMR national standards and Codex Alimentarius harmonization progress, plus prebiotic substrate cost volatility from European chicory root harvest disruption. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Biotechnology
Red Seaweed Extract Market
Food Biotechnology
Bangladesh Starch and Starch Derivative Market
Food Biotechnology
Trypsin Market
Food Biotechnology
Perilla Protein Market
Food Biotechnology
Glucose Oxidase Market
Food Biotechnology
Phycocyanin Market
Food Biotechnology
Casein Peptone Market
Food Biotechnology
Hemoglobin Feed Market
Food Biotechnology
Papain Market
Food Biotechnology
Carbohydrate Enzyme Preparation Market
Food Biotechnology
Salmon Polynucleotide (PN) Market
Food Biotechnology
Colostrum Market
Food Biotechnology
Brown Algae Protein Market
Food Biotechnology
Lupin Protein Market
Food Biotechnology
Global Feed Enzymes Market
Food Biotechnology
Global Genetically Modified (GMO) Food Market