
 Apigenin Market | 2026-2036
Apigenin Market Size, Share, and Industry Trends Forecast 2026-2036
Apigenin Market Analysis
ISO 22000 food safety management certification is redrawing competitive boundaries for apigenin suppliers seeking entry into regulated pharmaceutical and nutraceutical channels. Sigma-Aldrich (Merck KGaA) leverages its analytical standards portfolio to anchor premium positioning in research-grade apigenin. Shaanxi QingLan Bio-Technology Co., Ltd. dominates bulk botanical extraction through backward integration into chamomile and parsley feedstock cultivation in northwest China. Extrasynthese specializes in rare flavonoid reference materials, differentiating its catalog from commodity-grade competitors.
Apigenin is a naturally occurring flavone, specifically 4',5,7-trihydroxyflavone, extracted primarily from chamomile (Matricaria recutita), parsley, and celery sources through solvent extraction or supercritical CO2 methods, valued for its anti-inflammatory, anxiolytic, and potential chemopreventive properties in therapeutic and wellness applications. The powder segment leads volume due to its flexibility in bulk pharmaceutical and supplement manufacturing, though capsule formulations command superior unit economics through finished-dose branding. Dietary supplements represent the most mature application channel, while pharmaceutical development of apigenin for targeted oncology support programs shows the fastest trajectory for high-purity extract demand. Synthetic formulation types occupy the price-sensitive mass market, but organic-certified natural apigenin extracts capture concentrated margin pools from clean-label brands in European and North American nutraceutical markets.
The U.S. FDA oversees apigenin as a dietary ingredient under DSHEA, while the European Food Safety Authority evaluates novel food and health claim submissions for flavonoid-based products, with both frameworks elevating analytical documentation burdens for market access. China's National Medical Products Administration and its GB standards for botanical extracts impose additional testing protocols on exported apigenin, particularly for pesticide residue and heavy metal thresholds. Stakeholders must monitor evolving pharmacokinetic study requirements from EMA and FDA that could reclassify high-dose apigenin from supplement to drug jurisdiction, fundamentally altering commercialization pathways and investment timelines.
Market Dynamics
ISO 22000 certification requirements are compressing supplier margins while erecting entry barriers for unqualified botanical extractors, forcing a bifurcation between pharmaceutical-grade and commodity-grade apigenin supply tiers.
Growth Catalysts
- Oncology adjuvant protocols:German and US pharmaceutical formulators are embedding apigenin into supportive care regimens, creating pull-through demand for high-purity extracts.
- EFSA novel food assessments:Tightening purity thresholds for flavonoid extracts are advantaging certified suppliers with established analytical documentation.
- Shaanxi extraction clusters:Concentrated botanical processing infrastructure in northwest China is achieving economies of scale that lower unit costs for global nutraceutical contract manufacturers.
Market Restraints
- Chamomile feedstock volatility:Weather-dependent cultivation cycles in primary growing regions create input cost instability for natural extractors.
- Single-province supply concentration:China's Shaanxi province dominates bulk extraction, exposing buyers to localized disruption risks from environmental enforcement actions.
- Synthetic substitution pressure:Laboratory-synthesized apigenin occupies price-sensitive mass-market channels, compressing margins for organic-certified natural producers.
Strategic Opportunities
- Pharmaceutical reclassification pathways:EMA and FDA pharmacokinetic study requirements could elevate high-dose apigenin to drug jurisdiction, opening prescription-channel revenue streams.
- Clean-label premium positioning:European and North American nutraceutical brands are capturing concentrated margin pools through organic-certified natural extract positioning.
- Supercritical CO2 technology convergence:Advanced extraction methods combined with in-line chromatographic purification are enabling solvent-free pharmaceutical-grade output.
Industry Challenges
- Analytical chemist scarcity:Qualified personnel for flavonoid quantification and impurity profiling command premium compensation, constraining quality control scaling.
- Multi-jurisdiction compliance timelines:Simultaneous navigation of US FDA DSHEA documentation, EFSA novel food dossiers, and China NMPA GB standards extends product launch cycles.
- Legacy equipment retrofit costs:Transitioning solvent-based extraction facilities to supercritical CO2 systems demands substantial capital redeployment with extended payback periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Apigenin Market |
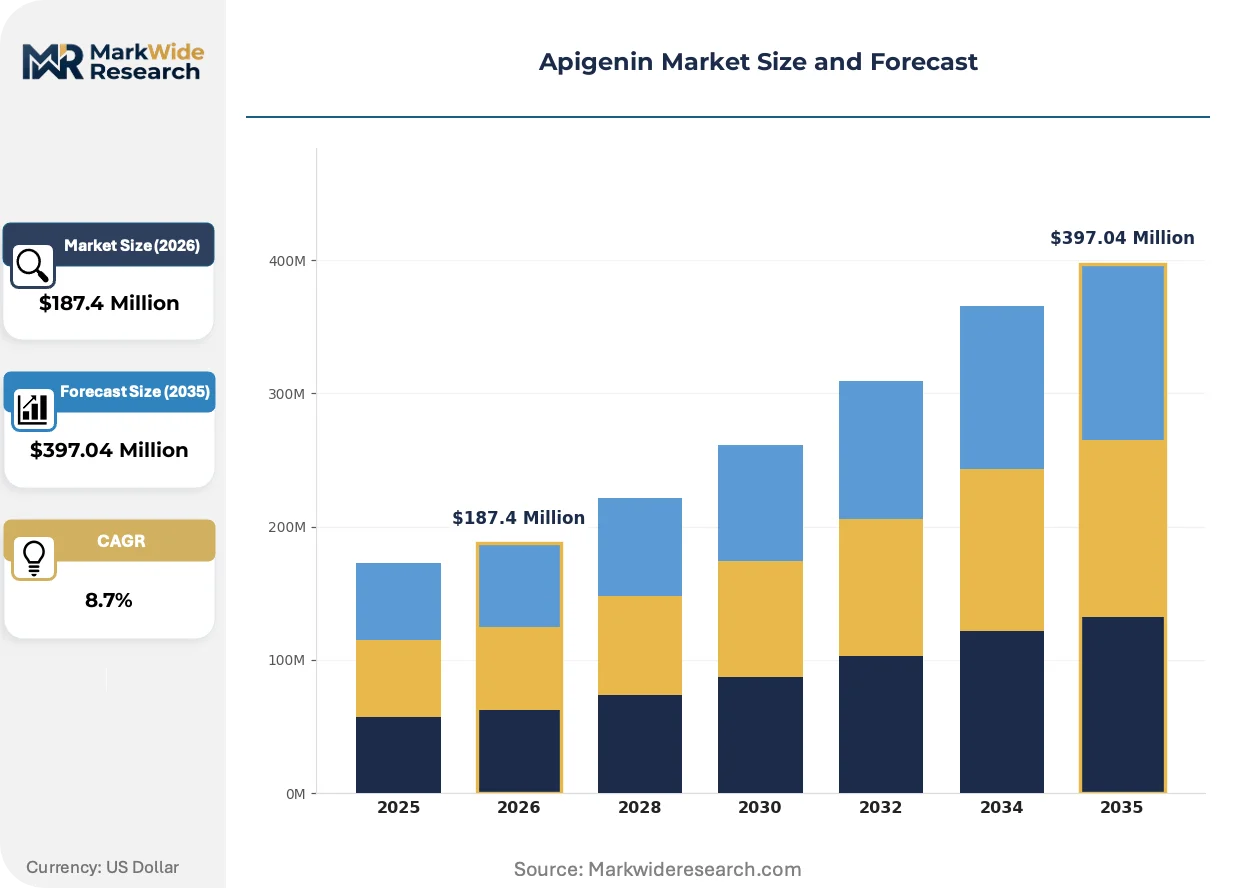
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Extract, Liquid, Capsule Application: Dietary Supplements, Pharmaceuticals, Cosmetics, Food & Beverages End User: Healthcare, Nutraceuticals, Cosmeceuticals, Food Industry Formulation Type: Natural, Synthetic, Organic, Conventional |
| Companies Covered | Sigma-Aldrich (Merck KGaA), Indofine Chemical Company Inc., Cayman Chemical Company, TCI Chemicals, Monteloeder S.L., Extrasynthese, Shaanxi QingLan Bio-Technology Co., Ltd., Xi'an Lyphar Biotech Co., Ltd., Abcam plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Apigenin Market Emerging Trajectories
Extraction technology maturation and regulatory documentation burdens are simultaneously elevating quality thresholds and consolidating supplier tiers across the apigenin value chain.
Supercritical CO2 extraction is supplanting conventional solvent-based methods in pharmaceutical-grade production. European and North American nutraceutical contract manufacturers are accelerating adoption to meet residue-free specifications. This transition is compressing the viable supplier base to capitalized operators with integrated purification capabilities.
EFSA's tightening novel food ingredient assessments are forcing comprehensive toxicological dossiers for flavonoid health claims. Suppliers must now submit batch-specific chromatographic fingerprints and stability data. Organic-certified natural extractors in Germany and France are responding by vertically integrating into controlled cultivation to secure audit trails.
Buyer consolidation among multinational nutraceutical brands is displacing fragmented spot-market purchasing with multi-year supply agreements. Large contract manufacturers in the United States are mandating ISO 22000 certification and dedicated production lines. This pattern is most visible in the oncology adjuvant segment, where pharmaceutical formulators require supply security for clinical trial continuity.
Apigenin Market Segmentation
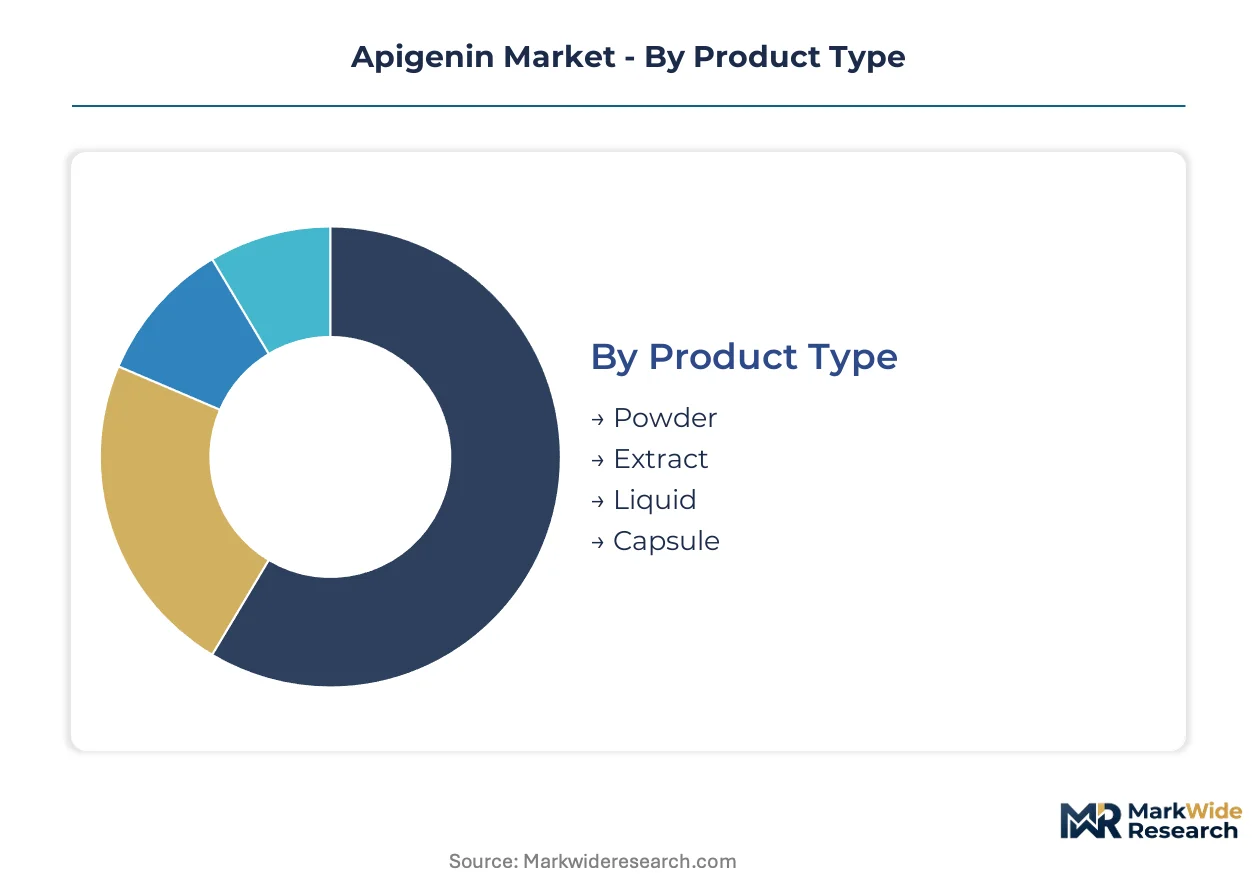
Apigenin's commercial structure fragments across four distinct categorization schemes, each mapping to divergent margin architectures and regulatory compliance burdens. Pharmaceutical-grade powder commands premium multiples against commodity liquid extracts, while application-level segmentation reveals oncology adjuvant protocols as the highest-value demand pocket.
Product Type:
Premium extraction yields concentrate in powder and capsule formats, where pharmaceutical and branded nutraceutical channels absorb price premiums for stability and dose precision.
- Powder:Crystalline or micronized apigenin with standardized flavone content serves bulk pharmaceutical manufacturing and supplement formulation. German oncology formulators and U.S. contract manufacturers in New Jersey and California drive specification-grade demand for clinical trial continuity and adjuvant protocol integration.
- Capsule:Finished-dose gelatin or vegetable cellulose shells containing measured apigenin doses capture superior unit economics through direct-to-consumer branding. North American and European clean-label wellness brands extract concentrated margin pools by combining organic certification with finished-product positioning.
- Extract:Semi-purified botanical concentrates from chamomile or parsley feedstock supply intermediate processing tiers.
- Liquid:Solubilized formulations for beverage fortification and topical applications occupy price-sensitive mass-market channels.
The dominant share belongs to Powder, while Capsule is closing the gap fastest.
Application:
End-use concentration tracks regulatory pathway complexity, with pharmaceutical development timelines extending value capture horizons against commoditized food additive deployment.
- Dietary Supplements:Mature application channel encompassing capsules, tablets, and bulk powder for wellness positioning. U.S. FDA DSHEA oversight and EFSA novel food assessments impose documentation burdens that advantage certified suppliers with established analytical protocols.
- Pharmaceuticals:Targeted oncology support programs and anxiolytic development pipelines demand high-purity extracts with batch-specific chromatographic validation. EMA and FDA pharmacokinetic study requirements are elevating quality thresholds and consolidating supplier tiers to ISO 22000-certified operators.
- Cosmetics:Topical anti-inflammatory and antioxidant applications in premium skincare formulations.
- Food & Beverages:Functional beverage fortification and novel food ingredient deployment facing EFSA purity threshold tightening.
Dietary Supplements holds volume leadership, though Pharmaceuticals is expanding most quickly through adjuvant protocol adoption.
End User:
Customer-type segmentation aligns procurement sophistication with specification stringency, from hospital pharmacy formularies to mass-market retail placement.
- Healthcare:Hospital systems, oncology clinics, and integrative medicine practices prescribing apigenin for supportive care regimens. German university medical centers and U.S. National Cancer Institute-affiliated institutions are embedding flavonoid protocols into standardized adjuvant care pathways.
- Nutraceuticals:Contract manufacturers and branded supplement houses serving wellness and preventive health positioning. China's Shaanxi province extraction clusters supply global nutraceutical contract manufacturers achieving economies of scale through concentrated botanical processing infrastructure.
- Cosmeceuticals:Premium skincare brands leveraging apigenin's anti-inflammatory properties for topical delivery systems.
- Food Industry:Functional food developers navigating novel food ingredient regulatory pathways across multiple jurisdictions.
Nutraceuticals commands the broadest supplier base, while Healthcare is gaining share fastest through clinical protocol codification.
Formulation Type:
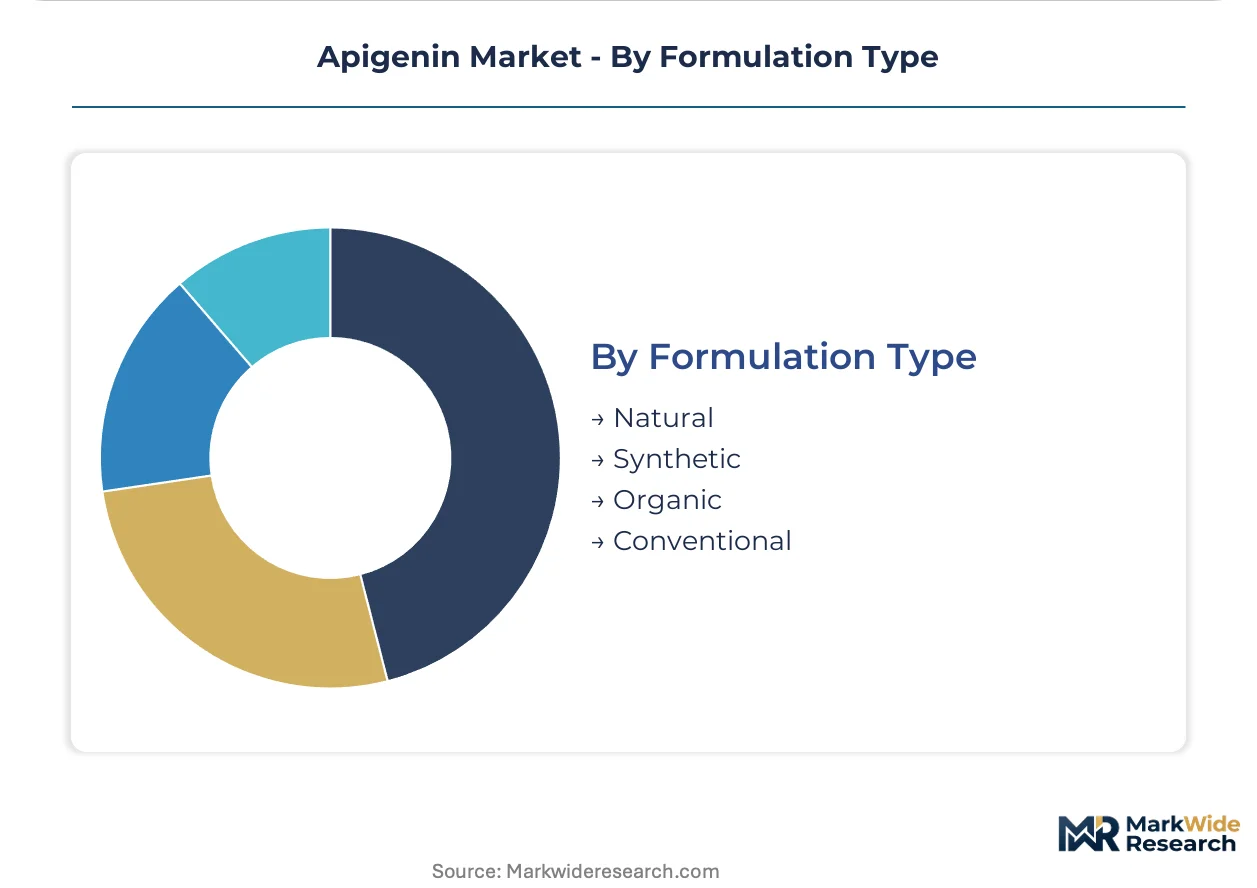
Certification tier stratification creates parallel margin architectures, with organic-natural positioning capturing concentrated premium pools against synthetic commoditization.
- Natural:Botanically derived apigenin from chamomile, parsley, or celery sources through solvent extraction or supercritical CO2 methods. European and North American clean-label brands extract concentrated margin pools through supply chain transparency and organic certification alignment.
- Organic:Certified organic cultivation and extraction meeting USDA NOP or EU Organic standards. French and German extractors are vertically integrating into controlled cultivation to secure audit trails for EFSA novel food dossier requirements.
- Synthetic:Laboratory-synthesized apigenin occupying price-sensitive mass-market channels through cost-optimized production.
- Conventional:Non-certified natural extraction serving intermediate price-performance positioning.
Natural formulation leads volume, while Organic is climbing the fastest through premium channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical handling infrastructure underwrites northwest Europe's role in flavonoid distribution, while China's Xi'an-Xianyang logistics corridor anchors Asia-Pacific supply consolidation.
United States
Oncology adjuvant protocols at NCI-affiliated medical centers in Houston and Boston drive specification-grade apigenin procurement. FDA DSHEA documentation requirements for dietary ingredients advantage certified suppliers with established analytical protocols. New Jersey contract manufacturers cluster near pharmaceutical R&D corridors to secure clinical trial supply continuity.
Germany
University medical centers in Heidelberg and Munich embed flavonoid protocols into standardized supportive care regimens. EMA pharmacokinetic study guidelines elevate quality thresholds for high-dose apigenin candidates. Bavarian extraction specialists pursue vertical integration into controlled chamomile cultivation to satisfy EFSA novel food dossier demands.
China
Shaanxi province's concentrated botanical processing infrastructure supplies global nutraceutical contract manufacturers through economies of scale. NMPA GB standards impose pesticide residue and heavy metal testing protocols on exported apigenin. Xi'an extraction clusters achieve solvent-free pharmaceutical-grade output through supercritical CO2 technology convergence.
France
Clean-label wellness brands in Paris and Lyon extract concentrated margin pools through organic-certified natural extract positioning. EFSA's tightening novel food ingredient assessments force comprehensive toxicological dossiers for flavonoid health claims. Provence-based extractors secure audit trails through controlled parsley and celery feedstock cultivation.
Japan
PMDA oversight of functional food ingredients creates documentation burdens that advantage established analytical suppliers. METI's promotion of preventive health applications drives demand for standardized flavonoid extracts. Osaka-Kobe pharmaceutical manufacturing corridors source high-purity apigenin for anxiolytic development pipelines.
Apigenin Market Vendor Landscape
Listed leaders compete with private specialists across certification tiers, creating a bifurcated structure where pharmaceutical-grade suppliers command premium positioning against commodity extractors. The vendor base stratifies into three archetypes: diversified chemical conglomerates with analytical standards portfolios, regional botanical extraction specialists with backward integration into feedstock cultivation, and rare flavonoid reference material catalog houses. Competitive moves concentrate on ISO 22000 certification acquisition and supercritical CO2 capacity expansion.
Within the diversified chemical tier, Sigma-Aldrich (Merck KGaA) exemplifies premium positioning through research-grade analytical standards. Among China-based extraction specialists, Shaanxi QingLan Bio-Technology Co., Ltd. and Xi'an Lyphar Biotech Co., Ltd. occupy positions anchored in northwest China's botanical processing infrastructure. Extrasynthese represents the rare flavonoid reference material archetype, differentiating through specialized catalog depth rather than commodity volume.
| Leading Market Players |
|---|
| Sigma-Aldrich (Merck KGaA) |
| Indofine Chemical Company Inc. |
| Cayman Chemical Company |
| TCI Chemicals |
| Monteloeder S.L. |
| Extrasynthese |
| Shaanxi QingLan Bio-Technology Co., Ltd. |
| Xi'an Lyphar Biotech Co., Ltd. |
| Abcam plc |
| Others |
Supply Flow & Price Mechanics
Supercritical CO2 extraction scale economies in Shaanxi province compress unit costs for pharmaceutical-grade apigenin while establishing price floors that commodity solvent-based extractors cannot match. ISO 22000 certification requirements add fixed compliance costs that widen spreads between certified and uncertified supply tiers.
Pricing Analysis
Volume-discount tiering structures separate pharmaceutical-grade powder contracts from spot-market liquid extract purchases. Three-tier pricing stratifies across premium organic-certified natural extracts, standard pharmaceutical-grade powders, and economy synthetic formulations. Cost compression in the synthetic tier intensifies as Chinese laboratory producers expand capacity. Nutraceutical contract manufacturers exhibit highest price sensitivity, while oncology formulators absorb premiums for batch-validated supply security.
Supply Chain Analysis
China dominates bulk botanical extraction, with Shaanxi province housing concentrated supercritical CO2 processing infrastructure for global nutraceutical supply. German and French extractors draw from controlled chamomile and parsley cultivation for EFSA-compliant audit trails. Feedstock volatility from weather-dependent cultivation cycles in primary growing regions creates input cost instability. Distribution runs through Rotterdam's chemical handling infrastructure for European pharmaceutical channels and New Jersey contract manufacturing clusters for U.S. oncology protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Apigenin sits in early-cycle expansion, with oncology adjuvant protocol adoption at NCI-affiliated centers creating foundational demand before broader pharmaceutical penetration.
For Market Incumbents: Consolidate supplier tiers through ISO 22000 certification acquisition and dedicated production line investments in Shaanxi or Bavaria. Synthetic substitution pressure from Chinese laboratory producers threatens natural extract margins, making backward integration into controlled cultivation a defensive necessity for premium positioning. For New Entrants and Emerging Players: Lead with supercritical CO2 capacity targeting the pharmaceutical-grade powder segment, where analytical chemist scarcity constrains incumbent scaling. White-space exists in European organic-certified extraction for EFSA novel food dossier compliance, with French and German brands paying concentrated premiums for supply chain transparency. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors extraction specialists with integrated purification capabilities over commodity botanical processors. Long-term viability hinges on pharmacokinetic study progression that could elevate high-dose apigenin to prescription-channel jurisdiction. Watch EMA and FDA study requirements as the inflection signal for drug-classification revenue expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Capacity Expansion | Enables solvent-free pharmaceutical-grade output meeting EFSA residue specifications. |
| ISO 22000 Certification Acquisition | Unlocks multi-year supply agreements with U.S. and German oncology formulators. |
| Backward Integration into Cultivation | Secures audit trails for EFSA novel food dossiers and organic certification alignment. |
| Pharmacokinetic Study Investment | Positions high-dose apigenin for potential EMA and FDA drug jurisdiction reclassification. |
| Long-term Supply Agreement | Guarantees clinical trial continuity for pharmaceutical formulators in Houston and Boston. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with extraction facility managers, pharmaceutical formulators, regulatory affairs specialists, and nutraceutical procurement directors; and secondary validation through FDA DSHEA filings, EFSA novel food dossiers, NMPA GB standards, customs trade data, and SEC disclosures from listed chemical suppliers. Bottom-up volume modeling triangulated against top-down market sizing from production capacity assessments.
Across the projection horizon, the analytical framework modeled segmentation dimensions including product grade tier, end-use application channel, formulation certification type, and regional regulatory cluster. CAGRs derived from production capacity expansion timelines, adoption curve assumptions for oncology adjuvant protocols, and pricing trajectory analysis across certified and uncertified supply tiers. Forecast inputs incorporated EMA pharmacokinetic study progression scenarios and EFSA purity threshold tightening schedules.
The analysis sits within stated boundaries; outcomes outside continued regulatory support for flavonoid health claims or sustained pharmaceutical interest in adjuvant applications would require recalibration. Forecasts reflect assumptions about Shaanxi supply concentration stability and supercritical CO2 technology diffusion rates. Recalibration cycles align with material shifts in EMA and FDA study requirements or EFSA novel food assessment precedents.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Biotechnology
Zein Protein Market
Food Biotechnology
Global Food Biotechnology Market
Food Biotechnology
Chlorella Market
Food Biotechnology
Biopreservation Market
Food Biotechnology
Flaxseed Gum Market
Food Biotechnology
Beta-Propeller Phytases Market
Food Biotechnology
Papain Market
Food Biotechnology
Europe Eubiotics Market
Food Biotechnology
Asia Pacific Eubiotics Market
Food Biotechnology
Phycocyanin Market
Food Biotechnology
Hemoglobin Feed Market
Food Biotechnology
Bovine Colostrum Market
Food Biotechnology
Microalgae Market
Food Biotechnology
Genistein Market
Food Biotechnology
South America Feed Prebiotics Market
Food Biotechnology
Perilla Protein Market