
 Global Feed Enzymes Market | 2026-2036
Global Feed Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Feed Enzymes Market Analysis
Consolidation among poultry integrators is expanding the addressable market for high-volume enzyme contracts. Novozymes A/S leverages its fermentation technology leadership to sustain premium positioning in phytase supply chains. BASF SE anchors European distribution through backward integration into specialty enzyme manufacturing. DuPont de Nemours, Inc. competes on thermostability performance, differentiating its protease portfolio for pelleted feed applications.
Feed enzymes are protein-based biocatalysts, typically produced via submerged fermentation of fungal or bacterial strains, that hydrolyze anti-nutritional factors in animal feed to improve nutrient bioavailability. Phytases dominate value generation by liberating bound phosphorus from plant-based raw materials, reducing inorganic phosphate supplementation costs. Proteases are gaining structural momentum in aquaculture formulations, where high-protein diets for salmon and shrimp create margin pools for specialized alkaline protease variants. Powder formulations retain volume leadership across ruminant applications, though liquid enzymes are displacing legacy formats in automated broiler feeding systems.
The EU Green Deal and REACH frameworks constrain chemical additive use, while FDA guidelines in the United States push for veterinary feed directive compliance, collectively elevating enzyme demand as a compliant performance alternative. China's SAMR enforces GB standards on feed additive safety, shaping market access requirements for imported enzyme concentrates. Stakeholders must monitor regulatory divergence between jurisdictions to align product registration strategies with shifting compliance thresholds.
Market Dynamics
Poultry integrators in Brazil and Thailand are consolidating procurement around multi-year enzyme supply agreements, compressing vendor selection cycles and elevating contract volume thresholds for market access. This buyer-side concentration is restructuring competitive dynamics across phytase and protease supply chains.
Growth Catalysts
- EU Green Deal Farm to Fork Strategy:Binding antibiotic-reduction targets are elevating enzyme substitution demand across European livestock operations, with phytases capturing the largest compliance-driven volume uplift.
- Southeast Asian Aquaculture Expansion:Shrimp and tilapia producers in Vietnam and Indonesia are scaling alkaline protease programs to optimize protein digestibility in high-performance marine feeds.
- Automated Broiler Feeding Systems:Liquid enzyme formats are displacing powder formulations in Thailand and Brazil as integrators retrofit houses for precision dosing and reduced labor handling.
Market Restraints
- Fermentation Input Cost Volatility:Corn steep liquor and soy-based nitrogen sources for submerged fungal cultivation face agricultural commodity price swings that compress enzyme producer margins.
- Chinese Import Registration Bottlenecks:SAMR's GB standard enforcement creates 18-24 month approval timelines for foreign enzyme concentrates, delaying market entry for non-domestic suppliers.
- Inorganic Phosphate Price Collapses:Periodic dips in dicalcium phosphate spot markets temporarily erode the cost advantage of phytase phosphorus liberation, slowing substitution momentum.
Strategic Opportunities
- Indian Poultry Integration Wave:Nascent contract farming expansion in Telangana and Karnataka creates first-mover potential for phytase-protease bundled programs in layer and broiler operations.
- Precision Fermentation Convergence:Cell-free biocatalysis platforms are opening recombinant enzyme production pathways that bypass traditional strain cultivation capital intensity.
- EU REACH Chemical Additive Restrictions:Accelerating bans on synthetic growth promoters are widening the approved feed additive window for carbohydrase and lipase variants in swine diets.
Industry Challenges
- Enzymologist Talent Scarcity:Industrial microbiology and protein engineering expertise concentrates in Danish and Dutch research clusters, constraining R&D scale-up in emerging production geographies.
- Thermostability Certification Delays:Pellet mill temperature validation protocols for novel protease variants extend field trial timelines by 8-14 months before commercial registration.
- Legacy Powder-to-Liquid System Retrofits:Automated dosing infrastructure requirements force Brazilian integrators to sequence barn upgrades across multi-year capital cycles, fragmenting adoption timing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Feed Enzymes Market |
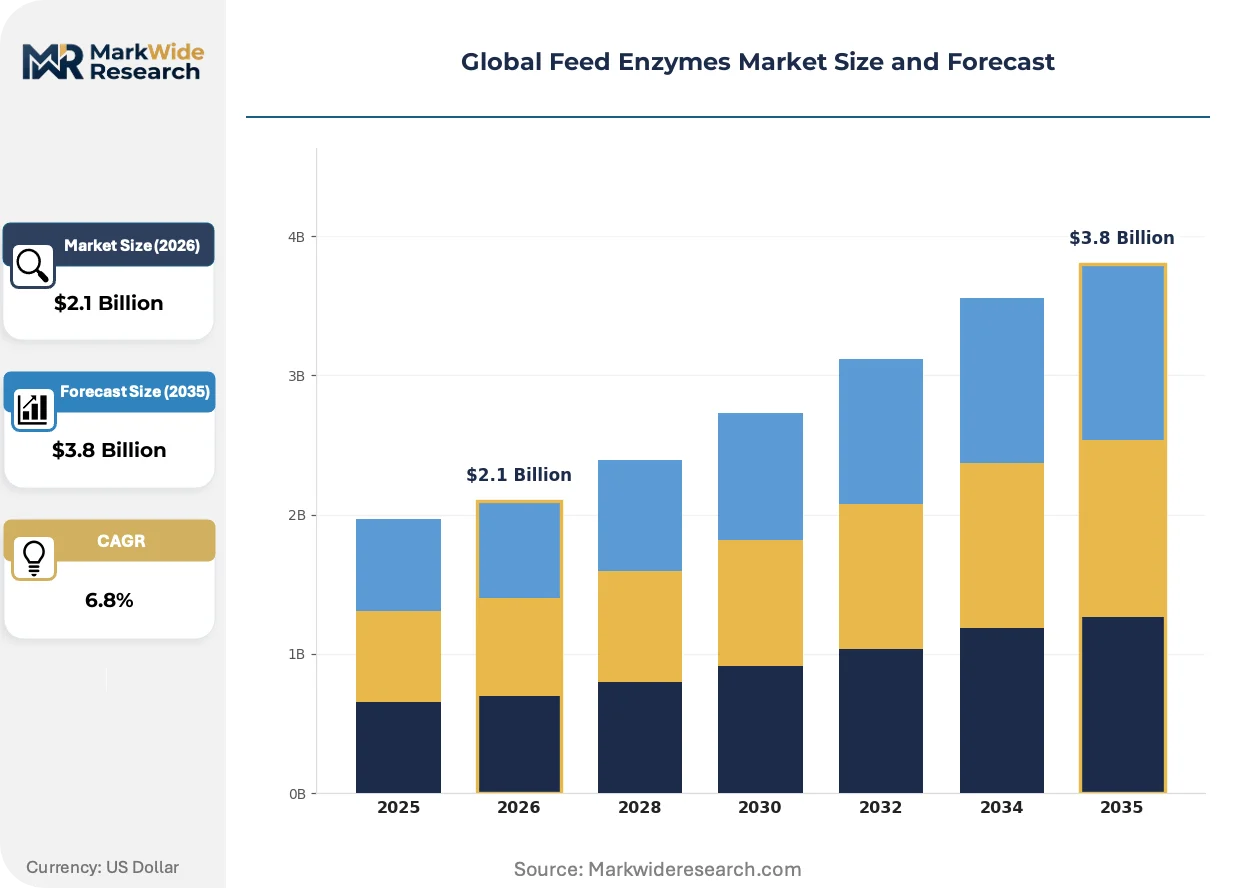
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
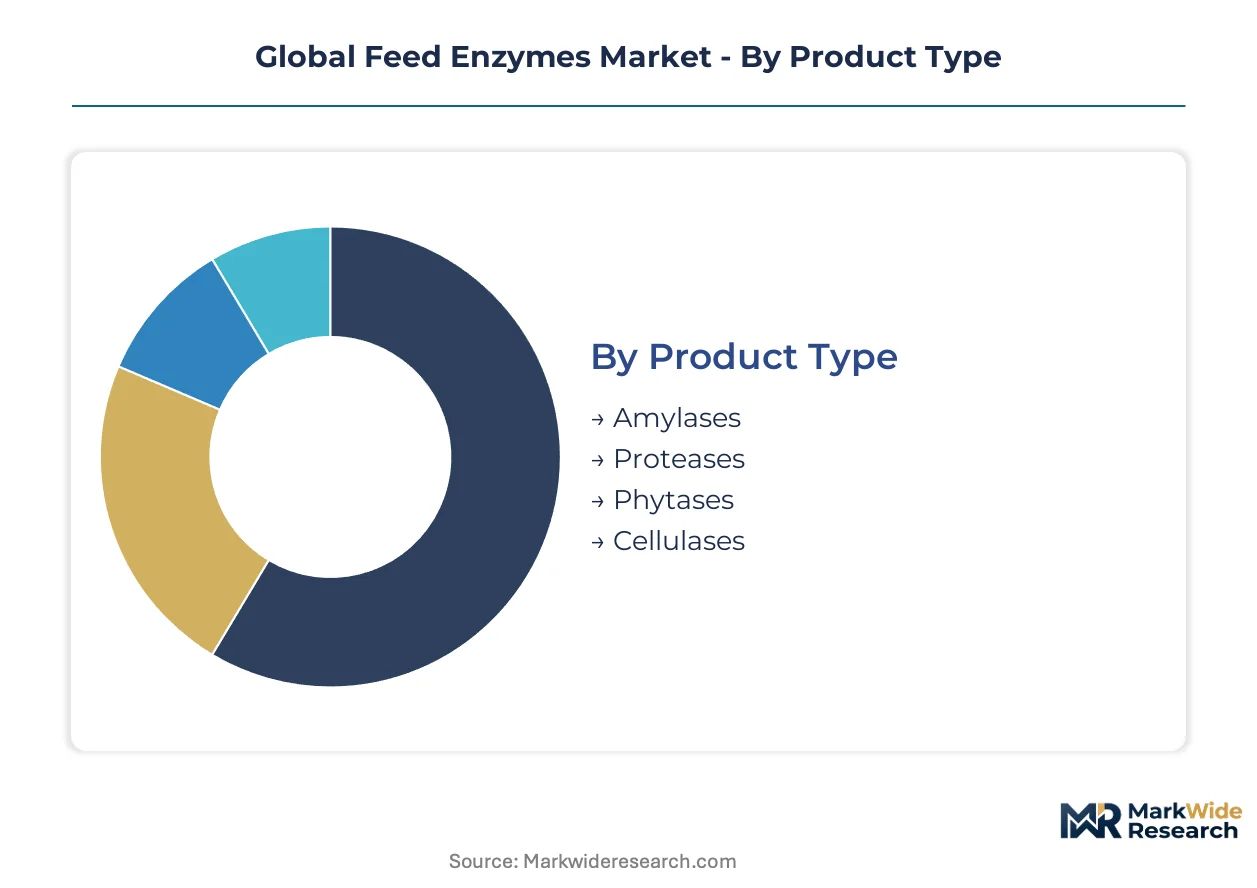
| Segmentation | Product Type: Amylases, Proteases, Phytases, Cellulases Application: Poultry, Swine, Ruminants, Aquaculture Form: Powder, Liquid, Granules, Pellets End User: Feed Manufacturers, Livestock Farmers, Aquaculture Producers, Pet Food Companies |
| Companies Covered | BASF SE, Novozymes A/S, DuPont de Nemours, Inc., Associated British Foods plc, Koninklijke DSM N.V., Adisseo France S.A.S., Chr. Hansen Holding A/S, AB Vista, Alltech, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Feed Enzymes Market Emerging Trajectories
Enzyme engineering platforms and regulatory chemistry restrictions are converging to reshape product development priorities. Suppliers are racing to deliver heat-stable, multi-enzyme cocktails that satisfy both performance metrics and compliance frameworks.
Granulated thermostable phytase variants are consolidating supplier relationships among Southeast Asian aquafeed mills. These engineered formulations withstand pelleting temperatures above 85°C without activity loss. Vietnamese shrimp feed producers are adopting them at accelerated rates to maintain phosphorus release efficiency through high-shear processing. The technology is consolidating procurement decisions around fewer vendors capable of delivering validated heat stability certificates.
REACH framework amendments are tightening residual chemical limits in feed additives, directly elevating enzyme demand as compliant performance alternatives. ECHA's revised authorization requirements are disqualifying several synthetic growth promoters from swine and poultry rations. European compound feed manufacturers are responding by expanding carbohydrase and protease inclusion rates to recover digestibility gains lost to withdrawn chemistry.
Direct procurement contracts between enzyme producers and large poultry integrators are displacing traditional distributor intermediaries in Brazil and Thailand. These bilateral arrangements lock in volume commitments and technical service support, compressing margin pools for regional feed additive traders. The pattern is most visible in São Paulo state and Thailand's Eastern Economic Corridor, where integrators with 50+ million bird annual placements command supply chain restructuring.
Global Feed Enzymes Market Segmentation
Enzyme procurement patterns diverge sharply across livestock species and production systems. Buyers prioritize thermostability thresholds, dosing automation compatibility, and regulatory compliance bundles when selecting formulations.
Product Type:
Cost tier separates commodity phytase buyers from premium protease purchasers seeking alkaline variants for marine diets.
- Phytases:These enzymes hydrolyze phytic acid to liberate bound phosphorus from plant meals, eliminating inorganic phosphate supplementation costs. Poultry integrators in Brazil and Thailand anchor procurement volumes as they retrofit operations for antibiotic-free production under EU Green Deal-aligned export protocols.
- Proteases:Alkaline and neutral protease variants break down complex proteins into absorbable peptides, improving amino acid utilization in high-performance feeds. Southeast Asian shrimp producers in Vietnam and Indonesia drive structural momentum as they optimize protein digestibility in marine diets facing raw material cost pressure.
- Amylases:Starch-hydrolyzing enzymes improve energy extraction from cereal grains in swine and poultry rations.
- Cellulases:Fiber-degrading enzymes unlock nutritional value from plant cell walls in ruminant forage supplements.
Volume sits with phytases; growth tilts toward proteases.
Application:
Species-specific digestive physiology dictates enzyme selection, with monogastric operations requiring distinct biocatalyst portfolios from ruminant systems.
- Poultry:Broiler and layer operations deploy phytase-protease cocktails to maximize feed conversion ratios in intensive housing systems. Brazilian integrators in São Paulo state command multi-year supply contracts as they scale automated feeding infrastructure.
- Aquaculture:Marine and freshwater species demand specialized alkaline protease formulations capable of functioning in varying pH environments. Vietnamese shrimp feed mills lead adoption of granulated thermostable variants that withstand pelleting temperatures above 85°C.
- Swine:Post-weaning diets incorporate carbohydrase blends to reduce digestive disorders and improve nutrient absorption in young pigs.
- Ruminants:Dairy and beef operations utilize fibrolytic enzymes to enhance forage digestibility and volatile fatty acid production in the rumen.
Poultry commands installed base; aquaculture posts the steepest expansion trajectory.
Form:
Customer infrastructure maturity separates powder-format legacy users from liquid-format adopters pursuing precision dosing.
- Powder:Dry enzyme concentrates remain standard across ruminant applications and smaller poultry operations lacking automated handling systems. Livestock farmers in India's Telangana and Karnataka states rely on powder formats as contract farming expands without capital for barn retrofitting.
- Liquid:Pumpable enzyme solutions enable metered injection into automated broiler feeding lines, reducing labor handling and dosing variability. Thai integrators in the Eastern Economic Corridor accelerate displacement of legacy formats as they modernize houses for precision nutrition.
- Granules:Coated particulate formulations protect enzyme activity through high-shear pelleting processes in aquafeed manufacturing.
- Pellets:Pre-formed enzyme matrices simplify handling for smaller feed mills with limited liquid storage infrastructure.
Powder retains volume leadership; liquid gains share fastest in automated systems.
End User:
Scale and technical capability separate integrated livestock operators from merchant feed compounders.
- Feed Manufacturers:Commercial compounders formulate enzyme-premix combinations for diverse customer portfolios, requiring multi-species biocatalyst flexibility. European manufacturers respond to ECHA REACH restrictions by expanding carbohydrase inclusion rates to replace disqualified synthetic growth promoters.
- Aquaculture Producers:Vertically integrated shrimp and tilapia operations source direct from enzyme producers, bypassing distributor intermediaries to lock in volume commitments and technical service support. Indonesian producers scale alkaline protease programs as they optimize protein digestibility in high-performance marine feeds.
- Livestock Farmers:Independent poultry and swine operators purchase enzyme-supplemented feeds from regional compounders without direct procurement involvement.
- Pet Food Companies:Specialty manufacturers utilize limited protease inclusions for premium companion animal formulations targeting digestibility claims.
Feed manufacturers anchor volume; aquaculture producers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corn and soybean cultivation belts in the United States and Brazil anchor raw material supply chains for fermentation-derived enzyme production. These agricultural localities concentrate phytase manufacturing infrastructure near feed grain terminals.
United States
Poultry integrators in the Southeast and Midwest deploy phytase-protease cocktails to meet FDA veterinary feed directive compliance for antibiotic-free operations. The FDA's VFD enforcement tightens prescription requirements for medically important antimicrobials, elevating enzyme substitution. Iowa and North Carolina house the densest concentrations of contract broiler operations retrofitting automated feeding systems.
Brazil
São Paulo state integrators command multi-year enzyme supply agreements as they scale antibiotic-free production for EU export markets. ANVISA's feed additive registration protocols align with European import standards, streamlining compliance pathways. The São Paulo-Paraná corridor concentrates the nation's largest poultry placement densities and liquid enzyme dosing infrastructure.
China
Domestic enzyme producers expand capacity to serve aquaculture operations in Guangdong and Fujian provinces facing SAMR GB standard enforcement on imported concentrates. SAMR's 18-24 month foreign registration timelines delay market entry for non-domestic suppliers. The Yangtze River Delta clusters shrimp feed mills adopting granulated thermostable protease variants.
Germany
Compound feed manufacturers respond to ECHA REACH restrictions on synthetic growth promoters by expanding carbohydrase inclusion rates in swine diets. The EU Green Deal Farm to Fork strategy binds member states to antibiotic-reduction targets, directly elevating enzyme demand. Lower Saxony and North Rhine-Westphalia concentrate the nation's feed milling capacity and enzyme formulation R&D.
Vietnam
Shrimp producers in the Mekong Delta scale alkaline protease programs to optimize protein digestibility in high-performance marine feeds. The country's fisheries regulator enforces residue limits that disqualify several synthetic growth promoters from aquafeed rations. Cần Thơ and An Giang provinces anchor the densest concentrations of vertically integrated shrimp operations sourcing direct from enzyme producers.
Global Feed Enzymes Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue precision fermentation platforms and cell-free biocatalysis pathways. The market structures around three tiers: multinational fermentation specialists with backward integration into strain development, regional formulators serving single-species feed markets, and technology licensors commercializing novel thermostable variants. Strategic moves concentrate on capacity expansion in Southeast Asian aquaculture corridors and portfolio diversification into multi-enzyme cocktails.
Within the multinational tier, Novozymes A/S and BASF SE occupy positions defined by fermentation technology leadership and European distribution anchoring respectively. DuPont de Nemours, Inc. exemplifies thermostability-focused product differentiation. These entities represent archetypes of premium positioning through technical performance validation, supply chain integration, and regulatory compliance bundling rather than commodity volume competition.
| Leading Market Players |
|---|
| BASF SE |
| Novozymes A/S |
| DuPont de Nemours, Inc. |
| Associated British Foods plc |
| Koninklijke DSM N.V. |
| Adisseo France S.A.S. |
| Chr. Hansen Holding A/S |
| AB Vista |
| Alltech, Inc. |
| Others |
Supply Flow & Price Mechanics
Corn steep liquor price indices cascade through submerged fermentation supply chains, compressing margin pools for phytase producers while elevating premium tiers for thermostable protease variants validated above 85°C. Brazilian integrators in São Paulo state leverage multi-year volume commitments to extract service-bundled pricing from fermentation specialists, fragmenting spot-market liquidity for uncontracted buyers.
Pricing Analysis
Technical service bundling separates premium phytase supply agreements from unbundled commodity transactions lacking pellet mill validation support. Three-tier pricing structure across premium, standard, and economy levels reflects thermostability certification grade, volume scale, and geographic delivery cost from Danish and Dutch production clusters. Pricing pressure stems from inorganic phosphate spot market volatility that periodically erodes phytase substitution economics. Merchant feed compounders in Southeast Asia exhibit highest price sensitivity; vertically integrated poultry operations in Thailand's Eastern Economic Corridor accept premium tiers for locked-in technical support.
Supply Chain Analysis
Refrigerated freight costs from fermentation facilities in Denmark and the Netherlands to Southeast Asian aquafeed mills constrain liquid enzyme format penetration against powder alternatives. Supply concentration rests on submerged cultivation infrastructure in China, Brazil, and the United States, drawing from corn steep liquor, soy-based nitrogen sources, and molasses feedstocks. Single-source vulnerability concentrates in strain development intellectual property held by Danish and Dutch research clusters. Distribution runs through direct procurement contracts displacing regional feed additive traders in São Paulo state and Vietnam's Mekong Delta.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation capacity scarcity in thermostable protease production props pricing power for validated suppliers, constraining new entrant scale-up timelines and sustaining incumbent margins across the analysis window.
For Market Incumbents: Anchor multi-enzyme cocktail portfolios in Southeast Asian aquaculture corridors to defend against precision fermentation entrants commercializing cell-free biocatalysis platforms. Expand backward integration into specialty strain development to capture R&D scale-up bottlenecks constraining competitor thermostability certification timelines. Lock in Brazilian poultry integrators through automated dosing infrastructure partnerships that fragment rival access to São Paulo-Paraná corridor placement volumes. For New Entrants and Emerging Players: Begin with alkaline protease formulations targeting Vietnamese shrimp feed mills seeking granulated thermostable alternatives to disqualified synthetic growth promoters under fisheries residue limits. Penetrate India's Telangana and Karnataka contract farming expansion before capital-intensive barn retrofitting accelerates liquid format displacement. Pursue white-label supply agreements with European compound feed manufacturers responding to ECHA REACH restrictions on carbohydrate inclusion rate expansion. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision fermentation platforms with cell-free biocatalysis pathways in Southeast Asian production geographies facing enzymologist talent scarcity. Long-term viability hinges on recombinant enzyme production economics bypassing traditional strain cultivation capital intensity. Watch SAMR GB standard enforcement timelines as inflection indicator for foreign concentrate market access windows in China's Yangtze River Delta shrimp feed cluster.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | New fermentation lines in Vietnam's Mekong Delta reduce logistics costs for shrimp feed mills. |
| Backward Integration | In-house strain development captures thermostability IP concentrated in Danish research clusters. |
| Long-term Supply Agreement | Multi-year contracts with São Paulo integrators lock out competitor access to Brazil's largest placement volumes. |
| Joint Venture | Local partnerships with Indonesian aquaculture producers bypass SAMR registration bottlenecks for foreign concentrates. |
| Technology Licensing | Precision fermentation platforms open recombinant production pathways without traditional cultivation capital. |
Methodological Framework
Multi-period observation of phytase-protease procurement contract volumes and pellet mill validation timelines anchored the trend analysis, supplemented by interviews with fermentation plant managers, poultry integrator procurement leads, aquafeed mill technical directors, and regulatory affairs specialists at enzyme formulators. Secondary validation drew from customs/trade data, SEC 10-K filings, SAMR GB standard enforcement notices, and ECHA REACH restriction amendments. Bottom-up segmentation modeling triangulated against top-down industry association capacity estimates.
Input-output matrices mapped enzyme activity yields to fermentation input costs across product type, application species, formulation format, and end-user scale dimensions over the projection horizon. CAGRs derived from segment-level volume trajectories weighted by thermostability certification penetration and automated dosing infrastructure retrofit rates. Forecast inputs incorporated corn steep liquor price volatility and inorganic phosphate substitution elasticity.
Underlying measurement precision varies by segment; aquaculture protease adoption carries tighter precision than ruminant cellulase penetration given direct procurement contract visibility. Forecasts reflect documented assumptions on regulatory enforcement timelines and commodity price correlation structures. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Biotechnology
Trypsin Market
Food Biotechnology
Brown Algae Protein Market
Food Biotechnology
Beta-Propeller Phytases Market
Food Biotechnology
Beta Lactoglobulin Protein Market
Food Biotechnology
Europe Eubiotics Market
Food Biotechnology
North America Eubiotics Market
Food Biotechnology
Global Food Biotechnology Market
Food Biotechnology
Casein Peptone Market
Food Biotechnology
Lupin Protein Market
Food Biotechnology
Hemoglobin Feed Market
Food Biotechnology
Bovine Colostrum Market
Food Biotechnology
Zein Protein Market
Food Biotechnology
Apigenin Market
Food Biotechnology
Salmon Polynucleotide (PN) Market
Food Biotechnology
Trans-Galactooligosaccharides Market
Food Biotechnology
Colostrum Market