
 Global Recombinant Cell Culture Supplements Market | 2026-2036
Global Recombinant Cell Culture Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Global Recombinant Cell Culture Supplements Market Intelligence
Single-use bioreactor integration with recombinant protein expression workflows is reconfiguring upstream manufacturing economics across the biopharmaceutical sector. Thermo Fisher Scientific leverages its dual position in cell culture media and analytical instrumentation to capture full workflow value. Merck KGaA anchors European supply through its recombinant insulin-like growth factor portfolio for serum-free applications. Lonza Group AG specializes in custom recombinant supplement manufacturing for contract development clients.
Recombinant cell culture supplements comprise proteins, growth factors, cytokines, and chemically defined additives produced through engineered host cell lines to support in vitro cell propagation without animal-derived components. These supplements typically achieve purity thresholds exceeding 95% through chromatographic purification and are formulated to deliver consistent lot-to-lot performance in biopharmaceutical manufacturing. Growth factors dominate product type revenue due to their essential role in maintaining cell viability during extended culture passages. Chemically defined media deployment is expanding fastest as regulators restrict undefined animal-derived inputs in commercial therapeutics. Monoclonal antibody production applications concentrate margin pools given their scale requirements and regulatory scrutiny.
The FDA enforces serum-free documentation for investigational new drug submissions, while EMA's MDR framework extends traceability requirements to cell culture inputs across European manufacturing sites. China's NMPA has aligned biologics manufacturing guidelines with chemically defined media standards, reshaping procurement patterns for multinational sponsors operating in Asia. Stakeholders must monitor evolving pharmacopeial monographs for recombinant albumin and transferrin as these specifications determine market access for substitute formulations.
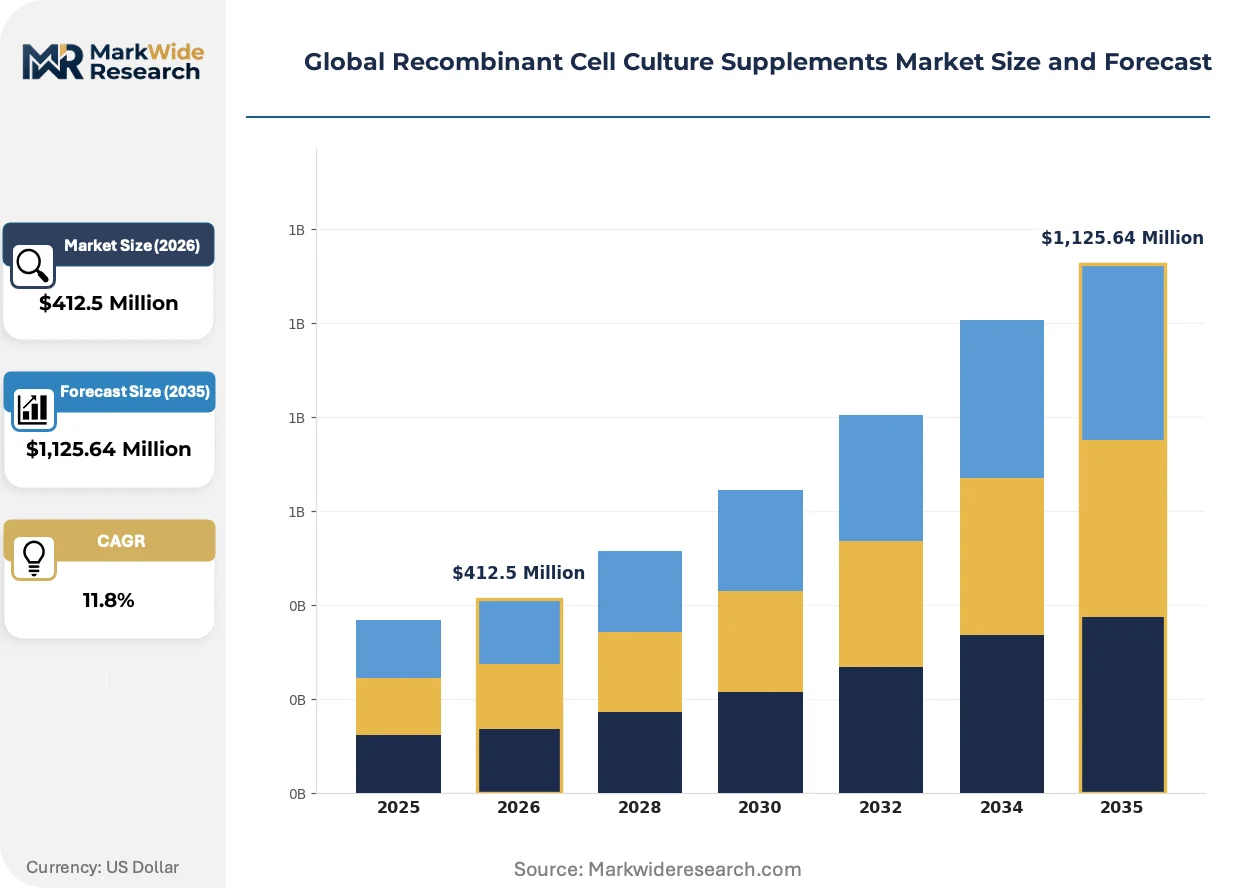
Market Dynamics
FDA and EMA serum-free documentation mandates are compressing adoption timelines for chemically defined formulations, forcing biopharmaceutical manufacturers to requalify upstream workflows around recombinant inputs.
Growth Catalysts
- EMA MDR Traceability Requirements:European manufacturing sites must document cell culture input provenance, accelerating demand for recombinant albumin and transferrin with certified supply chains.
- Monoclonal Antibody Manufacturing Scale-Up:Commercial biologics facilities require consistent lot-to-lot performance that only engineered growth factors deliver, expanding procurement volumes for recombinant insulin-like growth factors.
- China NMPA Alignment:China's biologics guidelines now mirror chemically defined media standards, compelling multinational sponsors to source recombinant supplements for Asian manufacturing footprints.
Market Restraints
- Chromatographic Purification Cost Structure:Recombinant supplement production requires multi-step protein purification that consumes significant resin and buffer inputs, compressing margin pools below animal-derived alternatives.
- Host Cell Line Supply Concentration:Engineered CHO and HEK293 expression systems concentrate among a limited supplier base, creating vulnerability for manufacturers dependent on consistent recombinant protein yields.
- Pharmacopeial Monograph Lag:USP and EP standards for recombinant transferrin remain under development, delaying market access for substitute formulations against established bovine-derived specifications.
Strategic Opportunities
- India Biologics Manufacturing Expansion:CDSCO's streamlined biologics approval pathways attract contract manufacturing investment, creating demand for serum-free media components in emerging production clusters.
- Cell Therapy Media Formulation:CAR-T and iPSC-derived therapeutic manufacturing requires specialized cytokine cocktails, opening premium positioning for custom recombinant supplement portfolios.
- Continuous Bioprocessing Convergence:Integration of perfusion bioreactor technology with real-time analytics enables just-in-time recombinant supplement dosing, reducing inventory carrying costs for multi-product facilities.
Industry Challenges
- Cell Line Development Specialist Scarcity:Engineered host cell optimization for recombinant protein expression requires rare molecular biology expertise, constraining capacity expansion at CDMO facilities.
- Multi-Site Qualification Complexity:Global biopharmaceutical sponsors must harmonize recombinant supplement specifications across FDA, EMA, and NMPA jurisdictions, extending validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Recombinant Cell Culture Supplements Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $1,125.64 Million |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Growth Factors, Cytokines, Enzymes, Hormones, Lipids, Trace Elements Application: Monoclonal Antibody Production, Vaccine Development, Gene Therapy, Cell Line Development, Protein Expression End User: Biopharmaceutical Companies, Contract Research Organizations, Academic Institutes, Biotechnology Startups Deployment: Serum-Free Media, Chemically Defined Media, Animal-Derived Media, Synthetic Media |
| Companies Covered | Thermo Fisher Scientific Inc., Merck KGaA, Lonza Group AG, Sartorius AG, STEMCELL Technologies Inc., InVitria, Bio-Techne Corporation, Sino Biological Inc., FUJIFILM Irvine Scientific Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Recombinant Cell Culture Supplements Market Strategic Shifts & Innovations
Single-use technologies and continuous processing architectures are compressing the economic boundaries between upstream and downstream operations, reshaping how recombinant supplements integrate into biomanufacturing workflows.
Automated perfusion control systems are collapsing the distinction between batch-fed and continuous culture economics. Biopharmaceutical manufacturers operating multi-product facilities are adopting these platforms to reduce media changeover downtime. The technology is collapsing capital allocation toward centralized media preparation suites rather than distributed batch formulation.
REACH authorization requirements for residual animal-derived components in imported biologics are tightening documentation burdens on European manufacturers. EMA's extended traceability framework now covers tier-two suppliers of cell culture inputs. Contract development organizations with EU manufacturing exposure are qualifying recombinant alternatives ahead of 2026 authorization deadlines.
Consolidated procurement through preferred supplier agreements is displacing spot-market purchasing for high-volume recombinant growth factors. Large-scale monoclonal antibody manufacturers are negotiating multi-year supply contracts with volume commitments. This concentration is most visible in Germany and Switzerland, where clustered biologics production sites aggregate demand for insulin-like growth factor-1 formulations.
Global Recombinant Cell Culture Supplements Market Segmentation
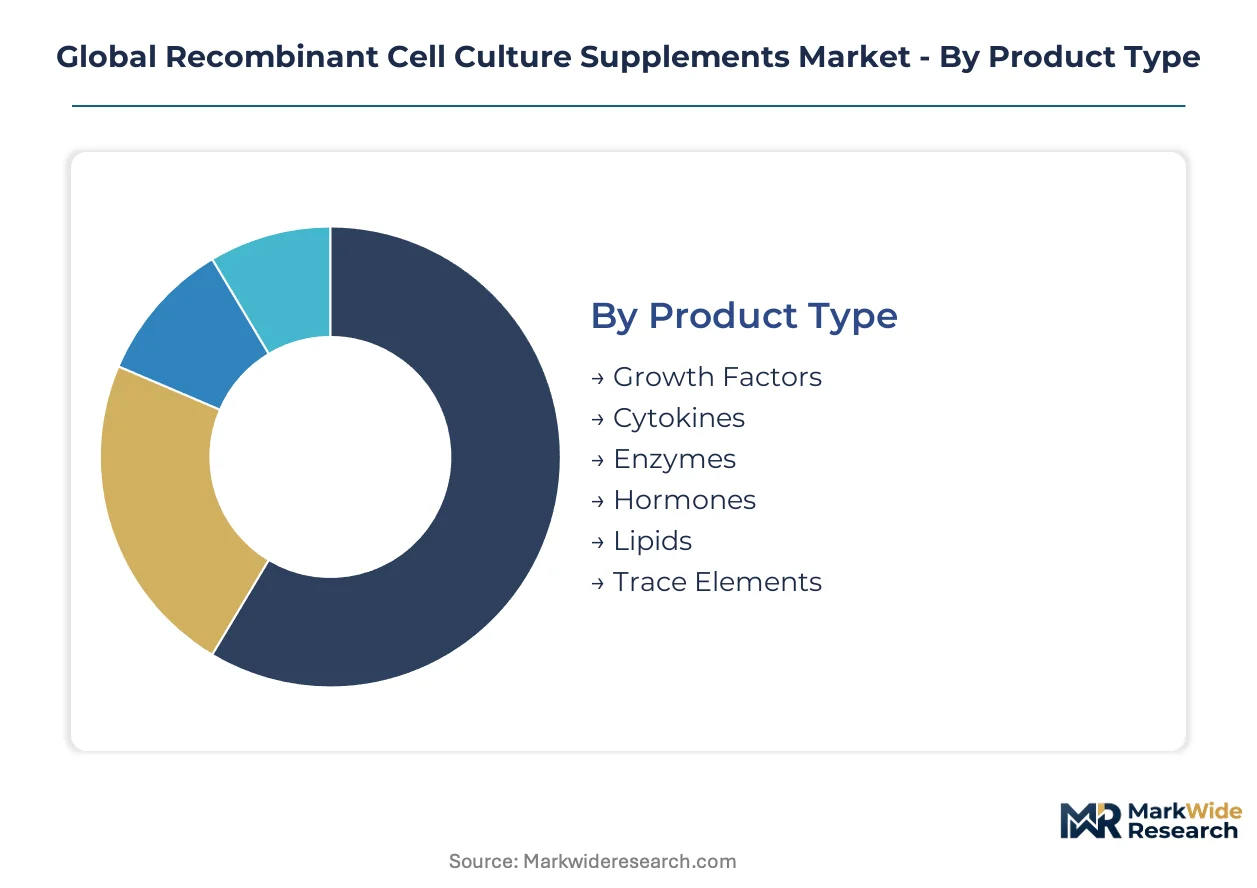
Recombinant cell culture supplements segment along technical specifications that determine manufacturing compatibility, regulatory qualification burden, and pricing tier. Understanding these divisions reveals where procurement budgets concentrate and which formulations command premium positioning.
Product Type:
Growth factors turn inventory fastest due to their consumption rate in extended culture passages, while trace elements and lipids sit longer in storage given their lower dosing requirements.
- Growth Factors:Engineered proteins such as insulin-like growth factor-1 and fibroblast growth factors maintain cell viability across multiple passages. Demand concentrates in monoclonal antibody facilities in Germany and Switzerland, driven by EMA traceability mandates that disqualify animal-derived alternatives.
- Cytokines:Signaling proteins including interleukins and interferons regulate cell differentiation and proliferation. Procurement is accelerating in CAR-T manufacturing sites across the US, where FDA serum-free documentation requirements for investigational new drug submissions force rapid qualification of recombinant sources.
- Enzymes:Recombinant proteases and nucleases facilitate cell dissociation and DNA processing.
- Hormones:Engineered insulin and hydrocortisone analogs support metabolic regulation in serum-free formulations.
- Lipids:Chemically defined fatty acid and cholesterol supplements replace undefined lipid mixtures.
- Trace Elements:Purified selenium, copper, and zinc formulations at microgram-scale dosing.
Growth factors anchor the volume base while cytokines gain share at the steepest rate.
Application:
Cost tier stratification separates high-volume commodity applications from specialized premium segments requiring custom formulation development.
- Monoclonal Antibody Production:Large-scale CHO cell cultures consume recombinant supplements in multi-kilogram quantities per campaign. Manufacturing sites in China cluster procurement for insulin-like growth factors as NMPA guidelines align with chemically defined standards.
- Gene Therapy:AAV and lentiviral vector production demands specialized cytokine cocktails with stringent purity thresholds. US-based contract development organizations command premium pricing for qualified recombinant inputs supporting FDA-submitted gene therapy programs.
- Vaccine Development:Viral seed stock amplification in mammalian or insect cell lines.
- Cell Line Development:Early-stage host cell optimization and clone selection workflows.
- Protein Expression:Recombinant therapeutic protein production in microbial or mammalian systems.
Monoclonal antibody production captures the largest procurement budgets while gene therapy applications expand most quickly.
End User:
Customer type determines contract structure, with large biopharmaceuticals negotiating multi-year supply agreements while smaller entities rely on spot purchasing.
- Biopharmaceutical Companies:Integrated manufacturers operating commercial-scale facilities drive consolidated procurement through preferred supplier agreements. German and Swiss production clusters aggregate demand for insulin-like growth factor-1 formulations with certified supply chains.
- Contract Research Organizations:CDMOs serving multiple sponsors require flexible inventory management and rapid lot qualification. European CROs with REACH authorization deadlines are pre-qualifying recombinant alternatives ahead of residual animal-component restrictions.
- Academic Institutes:Research-scale purchasing with limited volume commitments.
- Biotechnology Startups:Early-stage companies prioritizing cost efficiency over supply chain redundancy.
Biopharmaceutical companies anchor the volume base while contract research organizations gain share at the steepest rate.
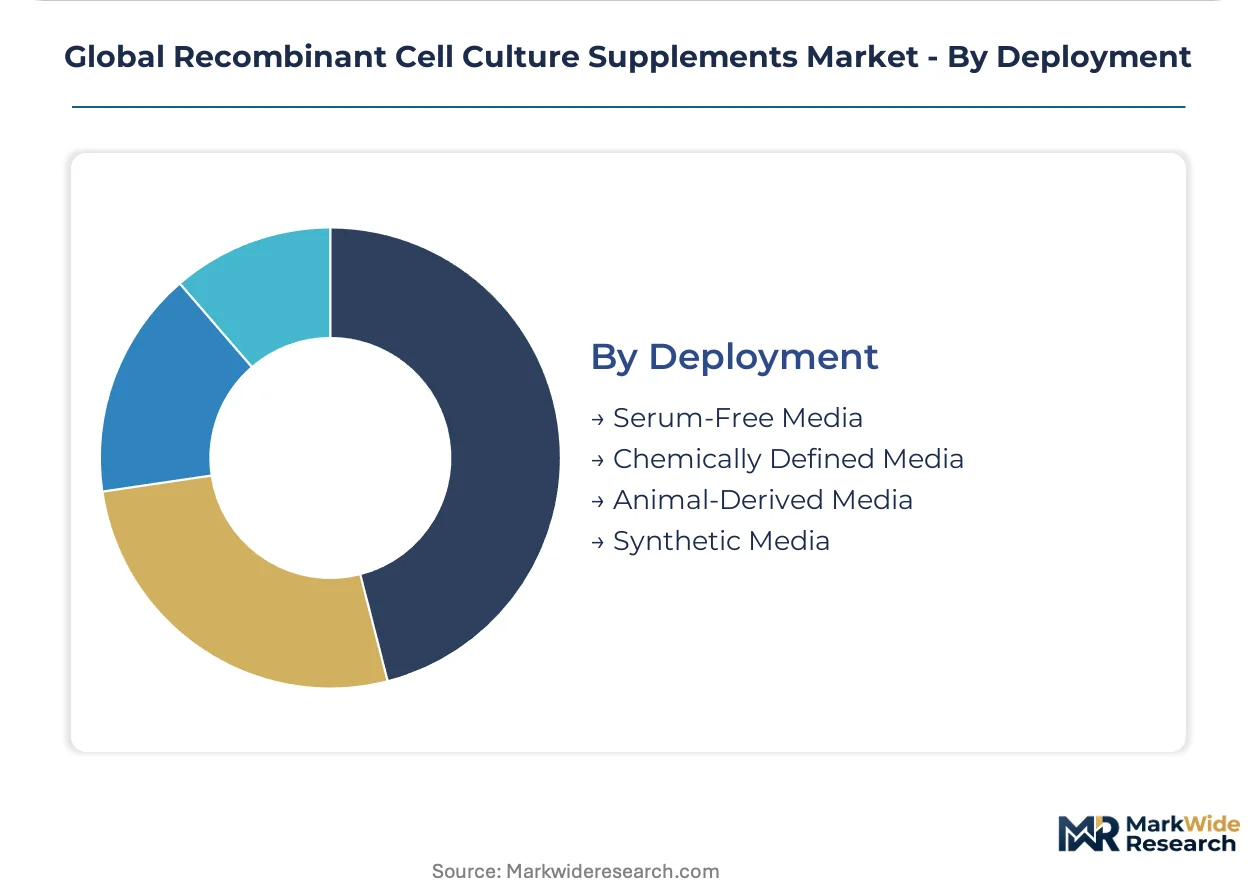
Deployment:
Supply concentration favors chemically defined media as regulatory pressure compresses adoption timelines for serum-free formulations.
- Chemically Defined Media:Every component specified by molecular structure and concentration, eliminating lot-to-lot variability. EMA MDR traceability requirements and FDA serum-free mandates are accelerating deployment across European and US manufacturing sites.
- Serum-Free Media:Eliminates fetal bovine serum while permitting undefined plant hydrolysates. China NMPA alignment with chemically defined standards is displacing serum-free formulations in multinational Asian manufacturing footprints.
- Animal-Derived Media:Traditional formulations with bovine serum albumin and transferrin.
- Synthetic Media:Fully artificial formulations with no biological origin components.
Serum-free media anchors the installed base while chemically defined media gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biopharmaceutical manufacturers in the United States, Germany, China, Switzerland, and India concentrate procurement for recombinant cell culture supplements, driven by regulatory mandates and clustered production infrastructure.
United States
FDA serum-free documentation requirements for investigational new drug submissions force rapid qualification of recombinant alternatives. CAR-T manufacturing sites across Greater Boston and the San Francisco Bay Area accelerate cytokine procurement. Boston's contract development organizations command premium pricing for qualified inputs supporting gene therapy programs.
Germany
EMA MDR traceability requirements disqualify animal-derived supplements in commercial biologics manufacturing. REACH authorization deadlines for residual animal components compress adoption timelines for recombinant formulations. The Rhine-Main region aggregates demand for insulin-like growth factor-1 through clustered monoclonal antibody production facilities.
China
NMPA alignment with chemically defined media standards compels multinational sponsors to source recombinant supplements for Asian manufacturing footprints. Shanghai and Suzhou biologics parks concentrate cell line development capacity. CDMOs in the Yangtze River Delta negotiate multi-year supply contracts for engineered growth factors.
Switzerland
Swissmedic enforces documentation standards mirroring EMA chemically defined media guidelines. Basel's integrated biopharmaceutical manufacturers drive consolidated procurement through preferred supplier agreements. The country's production clusters anchor European demand for certified recombinant albumin and transferrin supply chains.
India
CDSCO streamlined biologics approval pathways attract contract manufacturing investment from multinational sponsors. Hyderabad and Bengaluru emerging as serum-free media formulation hubs for export-oriented production. Domestic CDMOs pre-qualify recombinant alternatives to meet sponsor qualification requirements for FDA and EMA submissions.
Global Recombinant Cell Culture Supplements Market Key Industry Players
Channel-controlling players compete with product-specialist players across a moderately consolidated structure. Integrated life science conglomerates leverage dual positions in media and instrumentation to capture workflow value. Custom manufacturing specialists and regional biochemical suppliers occupy distinct strategic tiers. Dominant competitive moves include capacity expansion in high-growth Asian markets and strategic partnerships for cell line development services.
Among diversified life science conglomerates, Thermo Fisher Scientific Inc. and Merck KGaA exemplify channel-controlling archetypes through integrated media and analytical portfolios. Lonza Group AG occupies a specialist position in custom recombinant supplement manufacturing for contract development clients. These three entities anchor competitive positioning across the premium and mid-market tiers.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Merck KGaA |
| Lonza Group AG |
| Sartorius AG |
| STEMCELL Technologies Inc. |
| InVitria |
| Bio-Techne Corporation |
| Sino Biological Inc. |
| FUJIFILM Irvine Scientific Inc. |
| Others |
Cost & Logistics Intelligence
Undercapacity in European chromatographic resin production is compressing supplier margins while concentrating pricing power among integrated media conglomerates. This utilization squeeze forces biopharmaceutical manufacturers to accept longer-term contracts with volume commitments, reshaping procurement economics across recombinant supplement tiers.
Pricing Analysis
Cost-plus contracts indexed to raw fermentation feedstock costs dominate long-term supply agreements for recombinant growth factors. Three-tier pricing structure across GMP-certified premium, research-grade standard, and bulk economy levels separates qualified inputs for commercial biologics from exploratory applications. Pricing pressure stems from multi-step protein purification resin costs that consume disproportionate margin pools. Contract research organizations exhibit highest price sensitivity due to sponsor pass-through constraints, while integrated biopharmaceuticals prioritize lot-to-lot consistency over unit economics.
Supply Chain Analysis
Tariff exposure between United States and China dominates supply chain risk planning for recombinant supplement procurement. Manufacturing concentrates in Germany, Switzerland, and China, with engineered CHO cell lines and HEK293 expression systems anchoring upstream capacity. The supply chain draws from specialized fermentation media, chromatographic resins, and sterile filtration assemblies as critical inputs. Single-source vulnerability concentrates around host cell line suppliers, creating qualification bottlenecks for manufacturers scaling recombinant protein output. Distribution runs through direct manufacturer relationships with large biopharmaceuticals and distributor networks serving fragmented research accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face a substitution defense against plant-derived hydrolysate formulations that exploit regulatory lag in chemically defined standards. Animal-component-free alternatives threaten to displace engineered recombinant proteins in cost-sensitive research applications.
For Market Incumbents: Insulate qualified supply relationships through backward integration into host cell line development capabilities. Secure multi-year volume commitments from German and Swiss monoclonal antibody manufacturers before REACH authorization deadlines compress adoption timelines. Prioritize certification investment in USP and EP monograph alignment for recombinant transferrin to preempt bovine-derived substitute qualification.
For New Entrants and Emerging Players: Pursue custom cytokine formulation contracts with CAR-T manufacturing sites in Greater Boston and San Francisco Bay Area. Target gene therapy CDMOs as the most penetrable segment, where FDA serum-free documentation requirements force rapid supplier qualification. Position through rapid lot-release capabilities and dedicated technical support teams that incumbent conglomerates cannot replicate at scale.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across continuous bioprocessing-integrated supplement portfolios. Five-to-ten year viability favors specialists with captive cell line development expertise and established pharmacopeial dossiers. Monitor EMA MDR traceability enforcement as the signal indicating pricing power shift toward certified supply chain operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Cell Line Development Acquisition | Captive CHO and HEK293 expression systems reduce single-source vulnerability for recombinant protein yields. |
| Pharmacopeial Monograph Investment | USP and EP standard alignment accelerates market access against bovine-derived transferrin specifications. |
| Continuous Bioprocessing Partnership | Perfusion bioreactor integration enables just-in-time supplement dosing for multi-product facilities. |
| Asian Manufacturing Footprint Expansion | Shanghai and Suzhou biologics parks concentrate NMPA-aligned demand for chemically defined formulations. |
| CDMO Preferred Supplier Agreement | Multi-year contracts with European contract research organizations lock in volume ahead of REACH deadlines. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with biopharmaceutical manufacturing executives, regulatory affairs leads, CDMO procurement managers, and cell line development specialists; and secondary validation against FDA investigational new drug filings, EMA marketing authorization submissions, NMPA biologics guidelines, and pharmacopeial monograph drafts. Bottom-up segmentation modeling triangulated against top-down industry revenue estimates across product type, application, and deployment dimensions.
Forecast inputs incorporated regulatory mandate adoption curves, capacity expansion announcements, and substitution elasticity between recombinant and animal-derived supplements. Segmentation dimensions spanned growth factor versus cytokine product categories, monoclonal antibody versus gene therapy applications, and chemically defined versus serum-free deployment modes. CAGRs derived from fitted adoption curves reflecting EMA MDR, FDA serum-free, and NMPA alignment enforcement patterns across the projection horizon.
Sensitivities concentrate around pharmacopeial monograph publication timing, host cell line supply disruptions, and tariff regime changes affecting US-China biologics trade. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and manufacturing capacity commissioning schedules. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Micro-Bioreactors Market
Biotechnology Equipment
Biologic Imaging Reagents Market
Biotechnology Equipment
Global Single-Use Bioreactor Market
Biotechnology Equipment
US Cell Culture Media Market
Biotechnology Equipment
Global Competent Cells Market
Biotechnology Equipment
Balanced Salt Solution for Cell Culture Market
Biotechnology Equipment
Fluorescence Immunoassay Analyzers Market
Biotechnology Equipment
Cartridges for RT-PCR Automatic Systems Market
Biotechnology Equipment
Cellbag Bioreactor Chambers Market
Biotechnology Equipment
Airlift Bioreactors Market
Biotechnology Equipment
Single-Use Bioprocess Sensor Calibration and Validation Test Systems Market
Biotechnology Equipment
In-Vitro Fertilization (IVF) Microscopes Market
Biotechnology Equipment
Lab Scale Bioreactors Market
Biotechnology Equipment
Biochemistry Analyzers Market
Biotechnology Equipment
Automated Cell Culture Systems Market
Biotechnology Equipment
North America Life Science Tools Market