
 Biotech Flavors Market | 2026-2036
Biotech Flavors Market Size, Share, and Industry Trends Forecast 2026-2036
Biotech Flavors Market Analysis
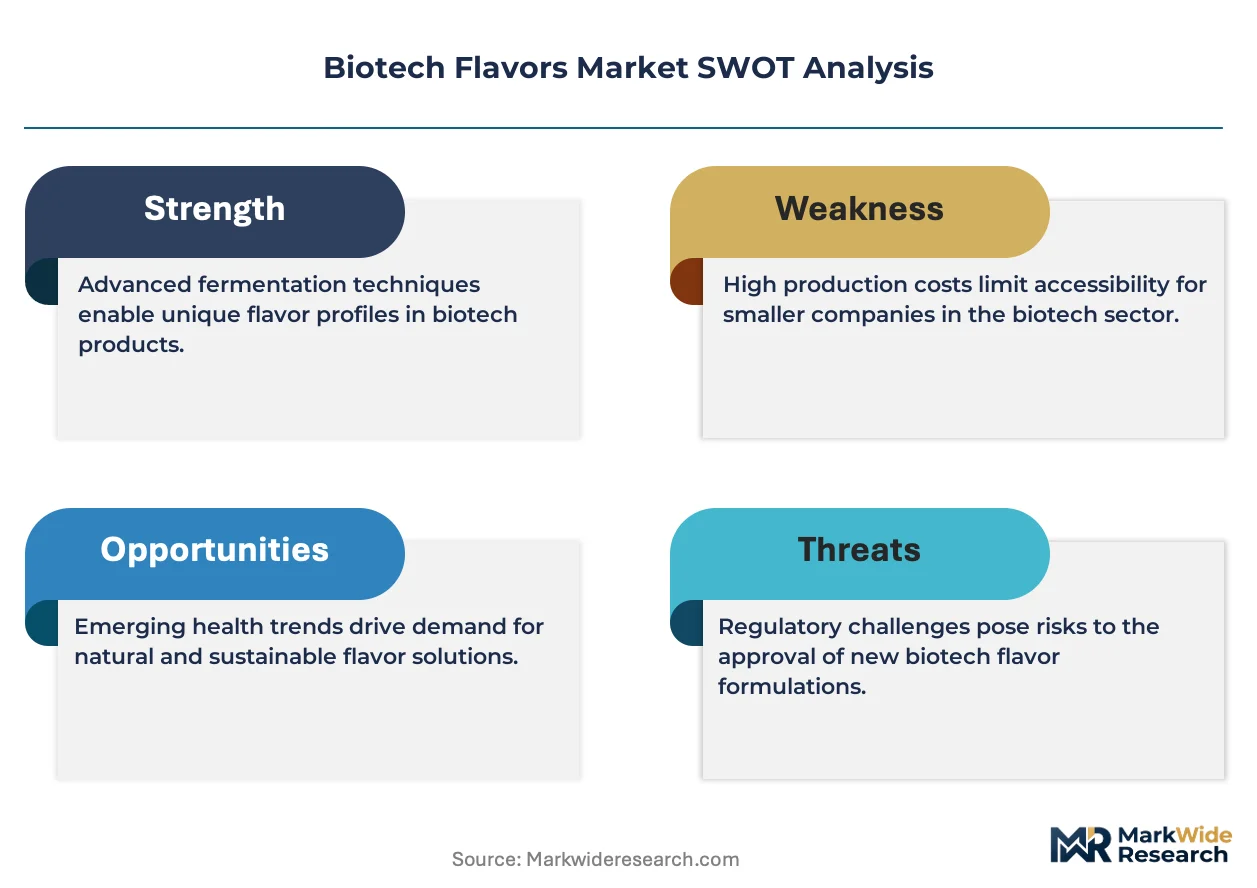
ISO 22000 certification is unwinding competitive access for smaller biotech flavor suppliers that lack validated food safety management systems. Givaudan SA leverages captive biotechnology platforms across Switzerland and Singapore to sustain leadership in precision fermentation for natural vanillin. Firmenich SA anchors its position through deep R&D partnerships with academic microbiology labs in France and Denmark. Symrise AG competes by controlling specialty enzyme supply chains that convert plant sugars into targeted aromatic molecules.
Biotech flavors comprise volatile and non-volatile compounds produced through microbial fermentation, enzymatic conversion, or cell-culture systems operating at pH 4.5–7.0 and temperatures between 25°C and 37°C, serving primarily to replicate or enhance sensory profiles in formulated consumer goods. Natural flavors lead absolute revenue contribution due to clean-label positioning across European and North American retail channels, while flavor enhancers represent the fastest-expanding category as sodium-reduction mandates intensify reformulation activity in processed foods. Liquid form dominates manufacturing throughput for beverage applications, though powder form commands margin premiums in dry-mix nutraceuticals where shelf stability and dosing precision matter.
FDA GRAS self-affirmation and EFSA novel food assessments govern market entry timelines for new microbial strains, with REACH registration in Europe adding toxicological documentation burdens that favor established players with dedicated regulatory affairs teams. The USDA National Organic Program and JAS organic standards in Japan further segment addressable demand by certifying fermentation substrates and carrier materials. Stakeholders must monitor evolving definitions of "natural" across jurisdictions, as regulatory divergence between FDA enforcement discretion and EU enzymatic process disclosures threatens to fragment formulation strategies.
Market Dynamics
Fermentation-derived flavor compounds are restructuring procurement patterns as beverage manufacturers bypass traditional botanical extraction in favor of microbial cell factories that deliver batch-to-batch consistency.
Growth Catalysts
- EU Green Deal carbon-neutrality targets:Food manufacturers across Germany and France face Scope 3 emission reduction mandates that favor biotech processes over solvent-intensive extraction.
- Sodium-reduction reformulation:Processed food producers in the United States are expanding purchases of umami-enhancing yeast extracts to maintain palatability without salt.
- Precision fermentation scale-up:Singapore's biomanufacturing hubs now host commercial vanillin production facilities serving Asia-Pacific flavor houses.
Market Restraints
- Feedstock price volatility:Corn sugar and molasses costs fluctuate with agricultural commodity cycles, compressing margins for enzyme-dependent conversion processes.
- Strain development timelines:EFSA novel food assessments and FDA GRAS self-affirmation procedures extend commercialization cycles for new microbial production platforms.
- Petrochemical-derived aroma substitution:Synthetic vanillin and ethyl esters retain cost advantages in mass-market confectionery applications.
Strategic Opportunities
- India FSSAI clean-label enforcement:Domestic food brands face tightening additive disclosure rules that create openings for fermentation-derived natural flavor positioning.
- Cell-culture hybrid systems:Convergence of plant cell suspension with microbial co-culture enables production of complex terpene profiles impossible through single-organism fermentation.
- Dry-mix nutraceutical channels:Powder-format biotech flavors address shelf-stability requirements in functional beverage premixes targeting direct-to-consumer subscription models.
Industry Challenges
- ISO 22000 certification gaps:Smaller fermentation startups lack validated food safety management systems required by multinational food manufacturers.
- Downstream processing bottlenecks:Chromatographic purification and spray-drying infrastructure demands capital commitments that strain mid-scale biotech operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biotech Flavors Market |
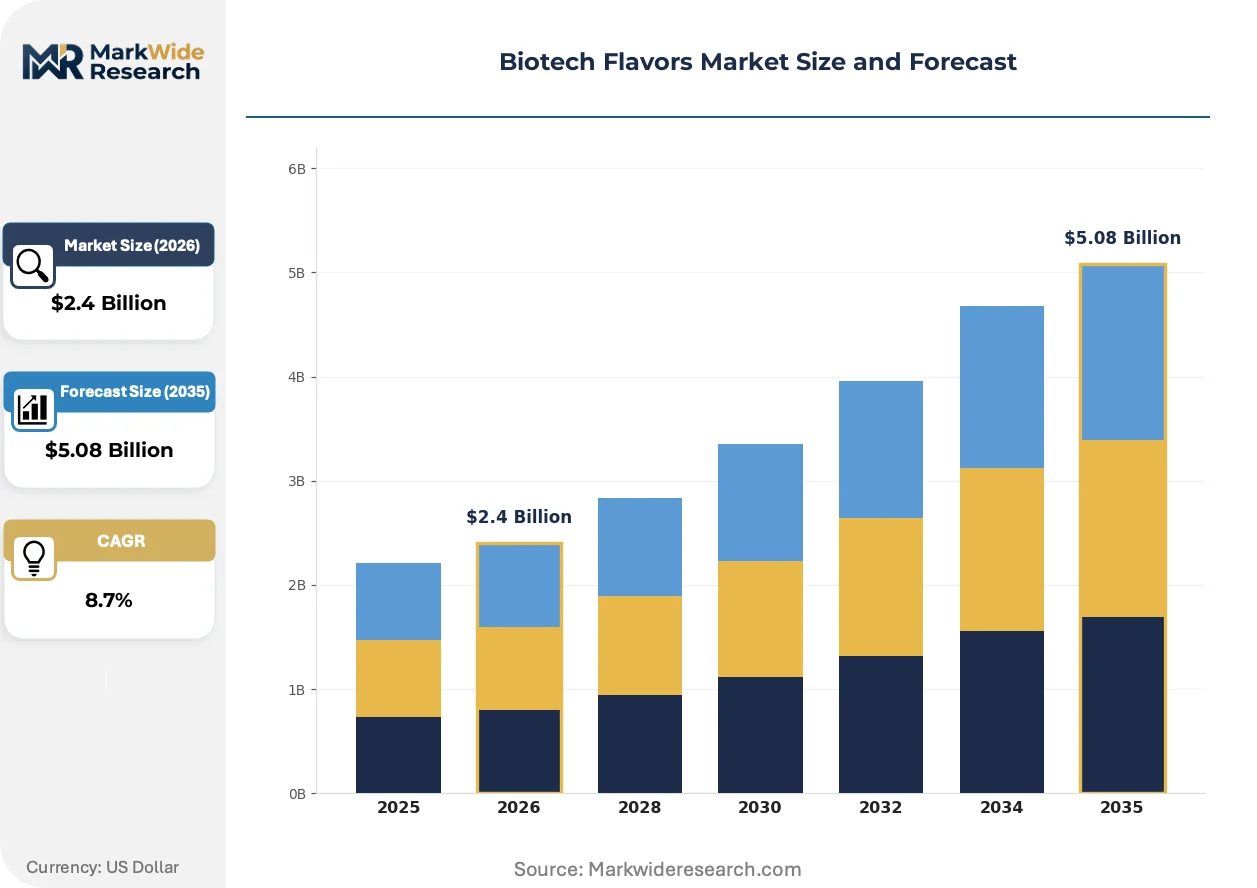
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Flavors, Synthetic Flavors, Essential Oils, Flavor Enhancers Application: Food & Beverages, Pharmaceuticals, Cosmetics, Nutraceuticals Form: Liquid, Powder, Granular, Paste Customer Type: Food Manufacturers, Beverage Companies, Personal Care Industries, Research Institutions |
| Companies Covered | Givaudan SA, Firmenich SA, International Flavors & Fragrances Inc., Symrise AG, Takasago International Corporation, Sensient Technologies Corporation, Kerry Group, BASF SE, Bell Flavors & Fragrances Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biotech Flavors Market Emerging Trajectories
Continuous bioprocessing configurations are replacing batch fermentation as the dominant manufacturing paradigm, compressing capital intensity and enabling real-time quality monitoring.
Precision fermentation using engineered yeast and filamentous fungi is supplanting vanilla orchid cultivation and chemical synthesis for natural vanillin supply. Major beverage conglomerates in Switzerland and the Netherlands have converted procurement specifications to accept only fermentation-derived vanillin for premium product lines. This shift is collapsing the historical price premium between natural and synthetic vanillin while concentrating supply among biotechnology-integrated flavor houses.
REACH registration requirements under ECHA oversight now mandate full toxicological dossiers for enzymatic process intermediates entering European food contact applications. Flavor compound suppliers must document substance identity down to 0.1% impurity thresholds. German and Danish flavor houses have responded by internalizing analytical chemistry capabilities previously outsourced to contract research organizations.
Direct-strain sourcing contracts now link food manufacturers to specific microbial production facilities rather than trading through distributor intermediaries. Nestlé and Unilever procurement teams negotiate fermentation capacity reservations with named biotechnology partners. This disintermediation is most pronounced in Germany, where R&D co-location agreements between flavor houses and academic microbiology labs enable rapid strain customization for client-specific aromatic profiles.
Biotech Flavors Market Segmentation
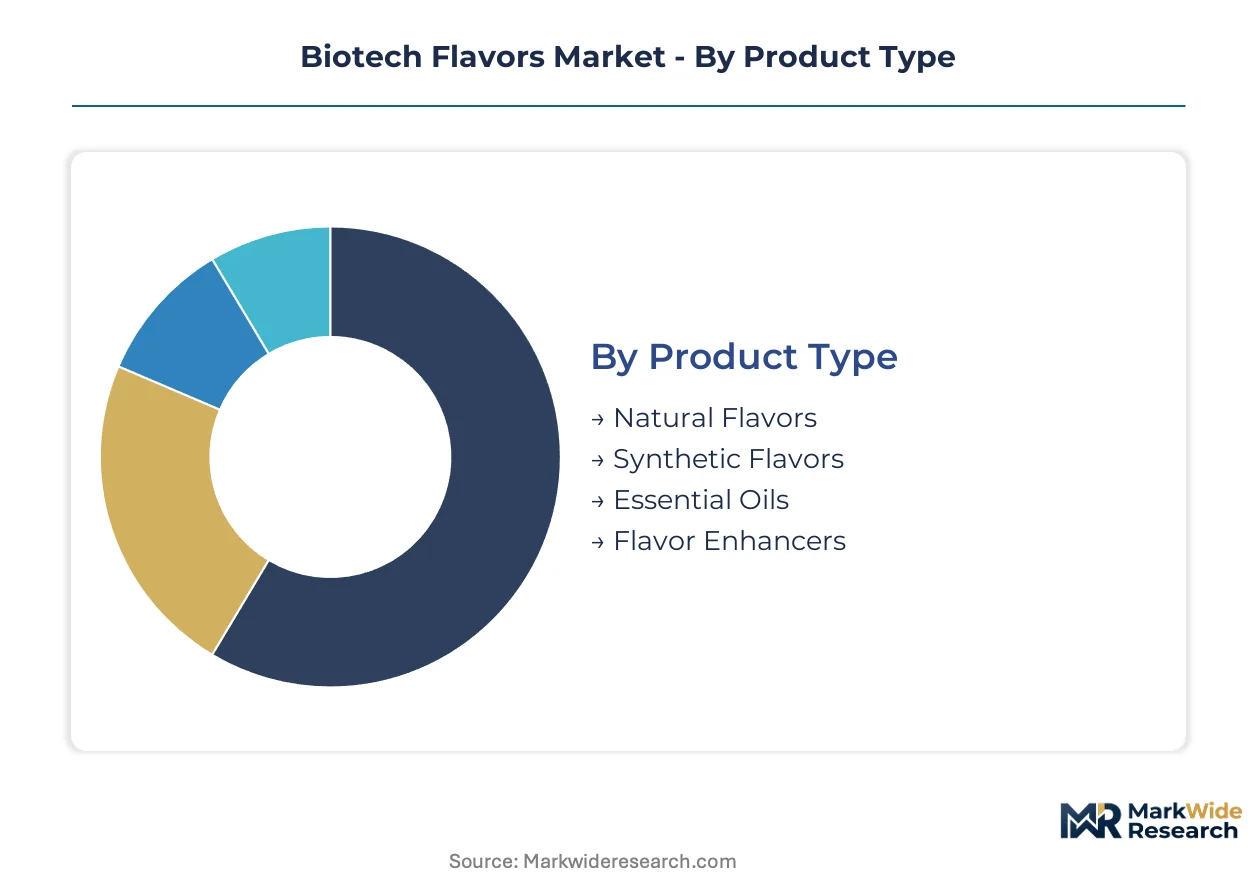
Segmentation in biotech flavors reveals where substitution pressure from petrochemical synthetics and botanical extracts concentrates most intensely. Procurement teams map these divisions to align fermentation capacity with end-use purity requirements and regulatory exposure.
Product Type:
Natural flavors face the stiffest substitution threat from synthetic alternatives in cost-sensitive confectionery, while flavor enhancers confront sodium-reduction mandates that could accelerate or displace demand depending on reformulation success.
- Natural Flavors:Volatile and non-volatile compounds derived from microbial fermentation or enzymatic conversion, replicating sensory profiles of botanical sources without agricultural land use. Beverage manufacturers in Germany and Switzerland have converted premium procurement specifications to fermentation-derived vanillin exclusively, collapsing the historical price premium against synthetic alternatives. Demand concentrates where clean-label positioning commands retail shelf access.
- Flavor Enhancers:Yeast extracts and nucleotide compounds intensifying umami perception to enable sodium reduction in processed foods. Processed food producers across the United States are expanding purchases to maintain palatability under tightening FDA sodium guidance. This segment gains share fastest as reformulation mandates intensify.
- Synthetic Flavors:Petrochemical-derived aroma molecules including ethyl vanillin and ester compounds.
- Essential Oils:Terpene-rich extracts from microbial co-culture systems replicating citrus and herbal profiles.
Natural flavors retain volume leadership; flavor enhancers hold the steepest expansion curve.
Application:
Cost tier stratification separates commodity food applications from premium pharmaceutical and nutraceutical channels where purity premiums justify biotech production complexity.
- Food & Beverages:Largest addressable volume spanning carbonated drinks, dairy alternatives, and savory applications. Beverage companies bypass traditional botanical extraction in favor of microbial cell factories delivering batch-to-batch consistency. Procurement concentrates in Germany where flavor houses cluster around Frankfurt and Hamburg.
- Pharmaceuticals:Masking agents for pediatric and geriatric drug formulations requiring precise dosing and impurity documentation. EMA and FDA validation requirements favor suppliers with dedicated regulatory affairs teams and ISO 22000 certification.
- Nutraceuticals:Functional beverage premixes and dietary supplements.
- Cosmetics:Fragrance and flavor cross-over compounds for lip care and oral hygiene products.
Food and beverages dominates absolute volume; nutraceuticals climbs fastest on direct-to-consumer subscription model growth.
Form:
Manufacturing throughput and margin capture diverge sharply between liquid formats optimized for beverage integration and powder formats commanding premiums in dry-mix applications.
- Liquid:Dominates manufacturing throughput for beverage applications with seamless integration into continuous processing lines. Singapore's biomanufacturing hubs now host commercial production facilities serving Asia-Pacific flavor houses with liquid vanillin output.
- Powder:Commands margin premiums in dry-mix nutraceuticals where shelf stability and dosing precision matter for functional beverage premixes. Spray-drying infrastructure demands capital commitments that strain mid-scale biotech operations.
- Granular:Intermediate format for industrial-scale seasoning and savory applications.
- Paste:High-viscosity format for bakery and confectionery compound integration.
Liquid retains volume leadership; powder holds the steepest expansion curve.
Customer Type:
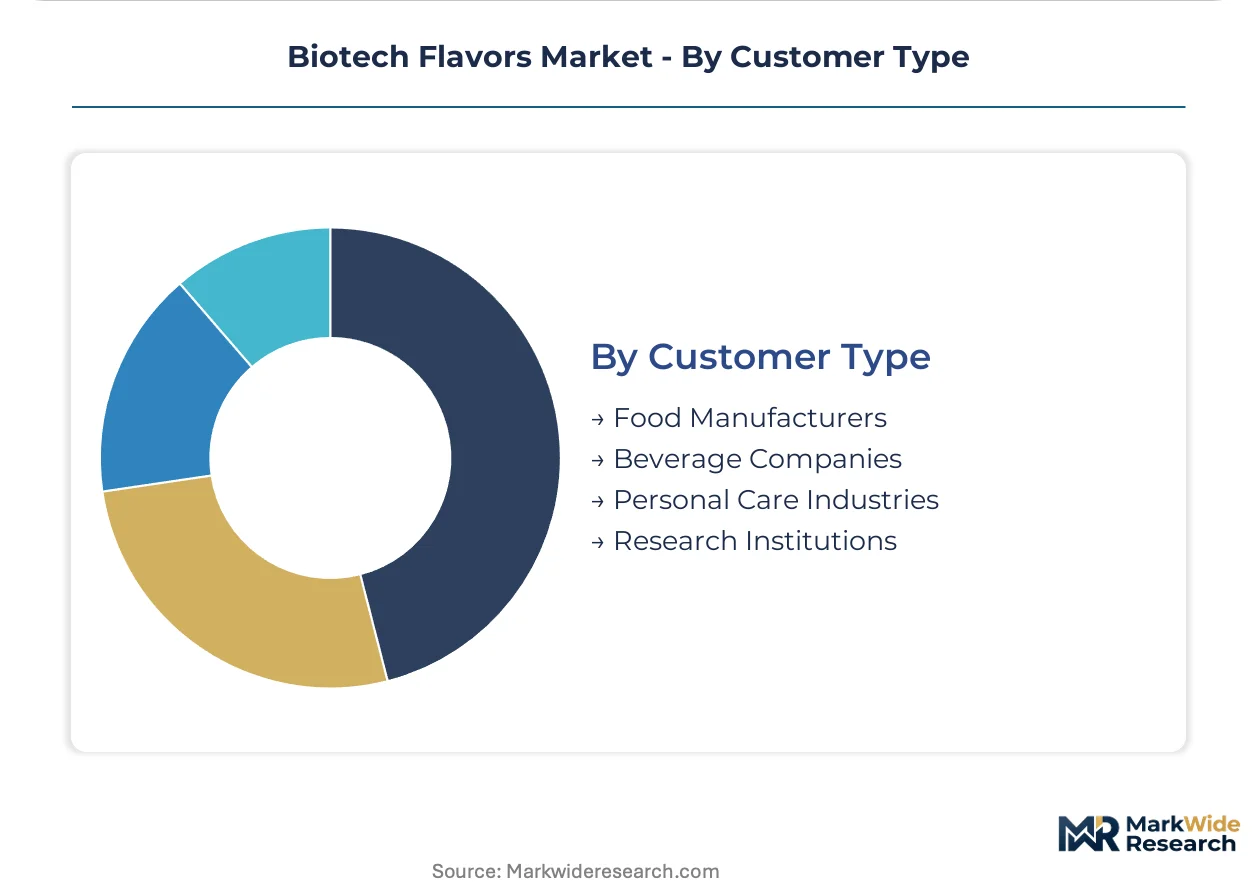
Supply concentration among multinational food manufacturers creates tiered access barriers that favor established biotechnology-integrated flavor houses over smaller fermentation startups.
- Food Manufacturers:Multinational processed food producers with direct-strain sourcing contracts linking to named microbial production facilities. Nestlé and Unilever procurement teams negotiate fermentation capacity reservations with specific biotechnology partners, disintermediating traditional distributors.
- Beverage Companies:Carbonated and non-carbonated drink producers driving precision fermentation scale-up for natural vanillin and citrus terpenes. Major conglomerates in the Netherlands have converted procurement specifications to fermentation-derived inputs exclusively.
- Personal Care Industries:Cosmetics and oral hygiene product manufacturers.
- Research Institutions:Academic microbiology labs in France and Denmark partnering with flavor houses on strain customization for client-specific aromatic profiles.
Food manufacturers retain volume leadership; beverage companies hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal carbon-neutrality targets are redirecting procurement budgets toward fermentation-derived alternatives across major food manufacturing hubs. National regulators are tightening purity documentation requirements, reshaping where biotech flavor capacity concentrates.
Germany
Scope 3 emission reduction mandates for processed food producers are accelerating adoption of microbial cell factories over solvent-intensive extraction. REACH registration under ECHA oversight requires full toxicological dossiers for enzymatic process intermediates. Flavor houses cluster around Frankfurt and Hamburg, with R&D co-location agreements between commercial suppliers and academic microbiology labs enabling rapid strain customization.
United States
Processed food producers are expanding purchases of umami-enhancing yeast extracts to maintain palatability under tightening FDA sodium guidance. FDA GRAS self-affirmation procedures govern market entry timelines for new microbial strains. Direct-strain sourcing contracts link Nestlé and Unilever procurement teams to named biotechnology partners, disintermediating traditional distributors.
Switzerland
Precision fermentation scale-up for natural vanillin is attracting premium beverage procurement specifications. Swissmedic oversight applies to flavor compounds entering pharmaceutical masking applications. Givaudan SA leverages captive biotechnology platforms across Swiss facilities to sustain leadership in precision fermentation.
Singapore
Biomanufacturing hubs now host commercial vanillin production facilities serving Asia-Pacific flavor houses. The country's national food safety regulator enforces alignment with ISO 22000 certification requirements for imported fermentation-derived ingredients. Liquid-format production capacity serves regional beverage manufacturers converting procurement specifications to fermentation-derived inputs.
India
Domestic food brands face tightening FSSAI clean-label enforcement that creates openings for fermentation-derived natural flavor positioning. BIS standards for food additives are converging with international purity benchmarks. Maharashtra and Gujarat host emerging fermentation startups targeting contract manufacturing relationships with multinational food manufacturers.
Biotech Flavors Market Vendor Landscape
Player mix skews toward biotechnology-integrated flavor houses with captive fermentation capacity. Three tiers structure competitive access: multinational integrated houses with dedicated regulatory affairs teams, mid-scale specialists controlling specialty enzyme supply chains, and emerging fermentation startups lacking validated food safety management systems. Dominant competitive moves include direct-strain sourcing contracts that disintermediate traditional distributors, and internalization of analytical chemistry capabilities to meet REACH documentation burdens.
Within the integrated multinational tier, Givaudan SA, Firmenich SA, and Symrise AG exemplify archetypes defined by their relationship to biotechnology infrastructure. Givaudan SA occupies a position anchored in captive precision fermentation platforms. Firmenich SA represents the R&D partnership model with academic microbiology labs. Symrise AG sits within the supply chain control archetype through specialty enzyme sourcing. These three Swiss and German entities collectively illustrate how regulatory compliance scale and biotechnology integration determine competitive access in procurement negotiations with multinational food manufacturers.
| Leading Market Players |
|---|
| Givaudan SA |
| Firmenich SA |
| International Flavors & Fragrances Inc. |
| Symrise AG |
| Takasago International Corporation |
| Sensient Technologies Corporation |
| Kerry Group |
| BASF SE |
| Bell Flavors & Fragrances Inc. |
| Others |
Supply Flow & Price Mechanics
Commercial-scale fermentation capacity utilization above eighty percent in Singapore and Germany establishes price floors that smaller biotech flavor suppliers cannot match without ISO 22000 certification investments. This scale concentration compresses margins for mid-tier enzyme-dependent converters while amplifying procurement leverage for multinational food manufacturers negotiating direct-strain sourcing contracts.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with ISO 22000-validated suppliers commanding fifteen to twenty percent premiums over uncertified competitors in European procurement specifications. Three-tier pricing structure separates REACH-registered precision fermentation vanillin from GRAS-self-affirmed natural flavors and synthetic petrochemical alternatives. Cost compression in standard-tier natural flavors intensifies as corn sugar and molasses feedstock volatility feeds through enzyme conversion economics. Beverage conglomerates exhibit lowest price sensitivity, prioritizing batch-to-batch consistency and regulatory documentation over unit cost in premium product lines.
Supply Chain Analysis
Just-in-time inventory strategies dominate liquid-format beverage applications, while powder-format nutraceutical customers maintain strategic stockpiles against spray-drying capacity constraints. Supply concentrates in Germany, Switzerland, and Singapore, with Frankfurt and Hamburg hosting flavor house clusters that internalize analytical chemistry for REACH compliance. Raw material dependencies center on agricultural sugar feedstocks, specialty enzyme supply chains, and chromatographic purification resins. Single-source vulnerability runs through engineered yeast strain repositories controlled by integrated multinational houses. Distribution runs through direct-strain sourcing contracts that disintermediate traditional chemical distributors, linking Nestlé and Unilever procurement teams to named biotechnology partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation scale-up constitutes a high-growth disruption as EU Green Deal carbon-neutrality targets restructure procurement budgets toward microbial cell factories over solvent-intensive extraction. This regulatory inflection compresses commercialization timelines for biotechnology-integrated flavor houses while erecting certification barriers for emerging competitors.
For Market Incumbents: Secure captive fermentation capacity reservations through R&D co-location agreements with academic microbiology labs in France and Denmark, insulating against strain development timeline extensions from EFSA novel food assessments. Internalize analytical chemistry capabilities to absorb REACH documentation burdens without contract research organization dependency. Defend margin position by controlling specialty enzyme supply chains that convert plant sugars into targeted aromatic molecules, blocking mid-scale competitors from cost parity. For New Entrants and Emerging Players: Differentiate on FSSAI clean-label enforcement openings in India, where domestic food brands face tightening additive disclosure rules without established fermentation-derived supply relationships. Target dry-mix nutraceutical channels for functional beverage premixes, where powder-format shelf stability requirements and dosing precision command margin premiums that liquid-format competitors cannot easily replicate. Pursue contract manufacturing relationships with multinational food manufacturers seeking geographic diversification beyond German and Swiss supply clusters. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among biotechnology-integrated flavor houses with direct-strain sourcing contracts linking to named microbial production facilities, as these agreements embed multi-year capacity reservations with penalty structures. Long-term viability over the next decade rests on regulatory compliance scale rather than unit cost optimization, favoring acquisition targets with dedicated EFSA and FDA affairs teams. Monitor EFSA novel food assessment queue lengths as the critical inflection signal, as approval acceleration would unlock stranded strain development investments across the competitive landscape.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Commercial vanillin production in Singapore biomanufacturing hubs serves Asia-Pacific flavor houses with batch-to-batch consistency. |
| REACH Registration Internalization | German and Danish flavor houses absorb ECHA toxicological documentation burdens without contract research organization dependency. |
| Direct-Strain Sourcing Contracts | Nestlé and Unilever procurement teams negotiate fermentation capacity reservations that disintermediate traditional distributor intermediaries. |
| ISO 22000 Certification Investment | Validated food safety management systems unlock multinational food manufacturer procurement specifications for emerging fermentation startups. |
| Cell-Culture Hybrid System Development | Convergence of plant cell suspension with microbial co-culture enables complex terpene profiles impossible through single-organism fermentation. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interviews with flavor house R&D directors, regulatory affairs leads at biotechnology-integrated multinationals, procurement managers at beverage conglomerates, and academic microbiology lab principal investigators in France and Denmark. Secondary validation drew from EFSA novel food assessment databases, REACH registration filings under ECHA oversight, FDA GRAS notification inventories, and customs trade data tracking fermentation-derived ingredient flows. Bottom-up strain development pipeline analysis triangulated against top-down procurement budget allocations at major food manufacturers.
Across the analysis window, the forecasting framework modeled volume and value outputs through segmentation across natural flavors, flavor enhancers, synthetic alternatives, and essential oils by product type; food and beverages, pharmaceuticals, nutraceuticals, and cosmetics by application; liquid, powder, granular, and paste by form; and food manufacturers, beverage companies, personal care industries, and research institutions by customer type. CAGRs were derived from elasticity-adjusted adoption curves incorporating EU Green Deal compliance deadlines, FDA sodium reduction guidance timelines, and FSSAI clean-label enforcement phase-ins. Industry-specific inputs included precision fermentation yield improvement trajectories and chromatographic purification cost curves.
The analysis sits within stated boundaries; outcomes outside sustained EU carbon-neutrality policy commitment and stable agricultural feedstock pricing would require recalibration. Forecasts reflect assumptions regarding EFSA assessment throughput, REACH documentation burden stability, and continued beverage manufacturer preference for fermentation-derived vanillin. Practitioners should keep alternative scenarios live as regulatory divergence between FDA enforcement discretion and EU enzymatic process disclosure requirements evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Biotechnology
Europe Eubiotics Market
Food Biotechnology
Glucose Oxidase Market
Food Biotechnology
Global GMO Testing Market
Food Biotechnology
Africa Eubiotics Market
Food Biotechnology
Casein Peptone Market
Food Biotechnology
Biopreservation Market
Food Biotechnology
Bovine Colostrum Market
Food Biotechnology
Bangladesh Starch and Starch Derivative Market
Food Biotechnology
Flaxseed Gum Market
Food Biotechnology
Chlorella Market
Food Biotechnology
Red Seaweed Extract Market
Food Biotechnology
Phycocyanin Market
Food Biotechnology
Perilla Protein Market
Food Biotechnology
Lupin Protein Market
Food Biotechnology
Beta-Propeller Phytases Market
Food Biotechnology
Global Genetically Modified (GMO) Food Market