
 Genistein Market | 2026-2036
Genistein Market Size, Share, and Industry Trends Forecast 2026-2036
Genistein Market Analysis
Multi-source botanical extraction is pivoting toward vertically integrated supply chains as genistein suppliers seek raw material security. Merck KGaA leverages its pharmaceutical-grade purification infrastructure to serve high-specification research markets. DSM Nutritional Products anchors its position through captive soybean processing and fermentation-derived isoflavone platforms. Cayman Chemical differentiates via analytical standard production for clinical and preclinical research channels.
Genistein is an isoflavone phytoestrogen found predominantly in soybeans, structurally characterized by a 4H-1-benzopyran-4-one core with hydroxyl substitutions at the 5, 7, and 4' positions, extracted via solvent-based or fermentation-assisted methods for use in hormone-modulating and antioxidant applications. The powder segment dominates current volume as bulk ingredient procurement serves nutraceutical and pharmaceutical formulators. Functional foods represent the fastest-growing application as manufacturers fortify beverages and dairy alternatives with standardized isoflavone content. Online retail channels capture expanding margin pools by reducing intermediary costs and enabling direct-to-consumer positioning for premium genistein supplements.
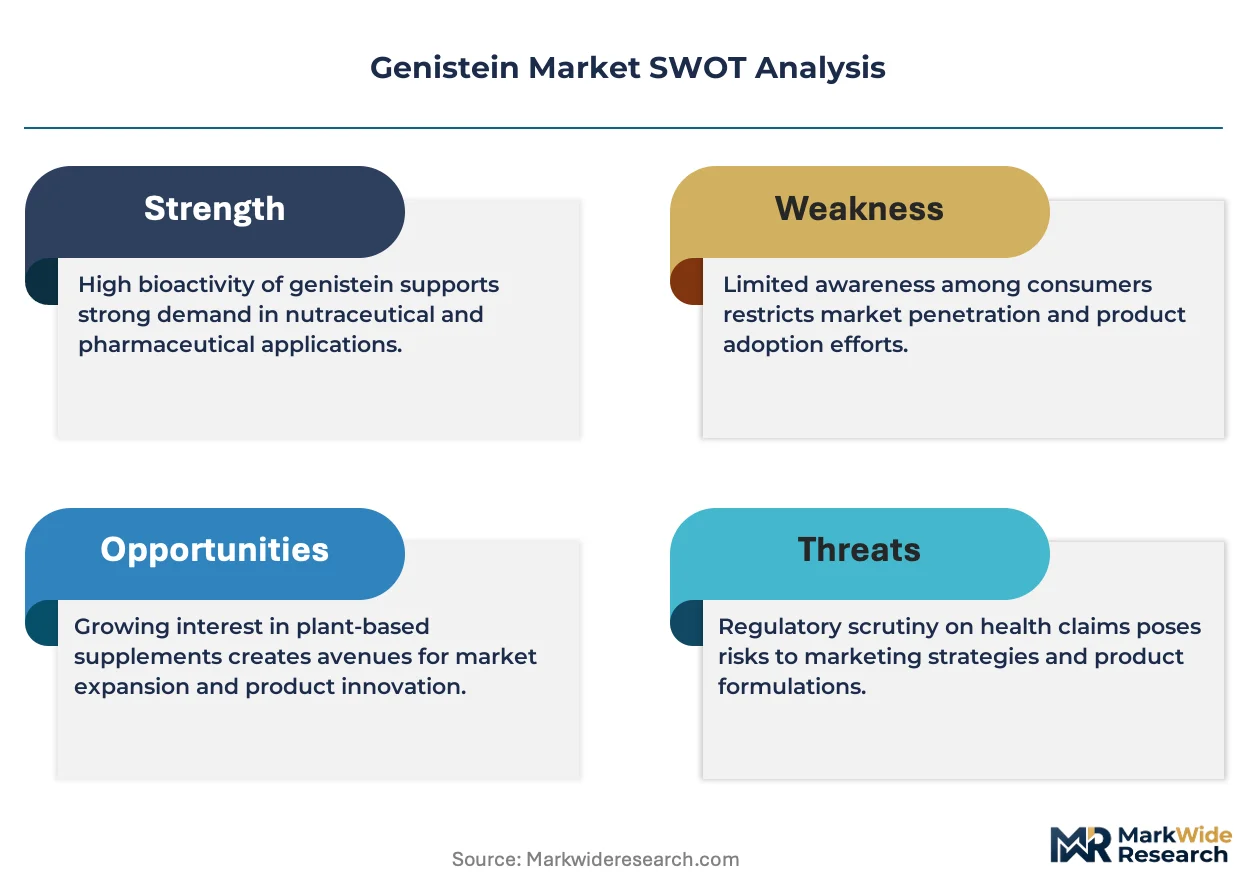
FDA dietary supplement Current Good Manufacturing Practice regulations enforce identity testing and contaminant controls for genistein products sold in the United States. EFSA novel food assessments govern market entry for non-traditional soy-derived extracts within European Union member states. ISO 17025 accreditation requirements shape laboratory-quality standards for analytical verification of isoflavone potency. Stakeholders must monitor evolving pharmacovigilance frameworks as regulators scrutinize phytoestrogen safety profiles across pediatric and hormone-sensitive populations.
Market Dynamics
Genistein supply chains are consolidating around fermentation-derived production platforms as manufacturers seek to bypass agricultural commodity volatility and secure pharmaceutical-grade purity standards.
Growth Catalysts
- EFSA Novel Food Pathways:Streamlined safety assessments for non-traditional soy extracts accelerate European market entry for fermented genistein isolates.
- Functional Beverage Formulation:Dairy alternative manufacturers in the United States incorporate standardized isoflavone content to support hormone-health positioning claims.
- Microbial Cell Factory Engineering:CRISPR-optimized yeast strains achieve gram-per-liter genistein titers, collapsing extraction costs versus solvent-based soybean processing.
Market Restraints
- Input Cost Volatility:Non-GMO soybean premiums fluctuate with Brazilian harvest cycles, compressing margins for botanical extractors dependent on raw material spot markets.
- Regulatory Friction:FDA identity testing requirements under 21 CFR Part 111 impose analytical validation burdens that disproportionately constrain small-batch supplement manufacturers.
- Phytoestrogen Substitution:Resveratrol and lignan formulations compete for shelf space in menopause-support categories, fragmenting isoflavone demand concentration.
Strategic Opportunities
- Indian Nutraceutical Expansion:FSSAI functional food regulations create compliance pathways for fermented genistein ingredients targeting urban preventive health segments.
- Clinical Research Contracting:Oncology and metabolic syndrome trials require analytical-grade reference materials, opening premium pricing tiers beyond commodity nutraceutical supply.
- Direct-to-Consumer Subscription Models:Online wellness platforms bypass wholesale distribution markups, capturing margin pools previously allocated to retail intermediaries.
Industry Challenges
- ISO 17025 Talent Scarcity:Accredited isoflavone quantification requires mass spectrometry specialists, creating recruitment bottlenecks for quality control expansion.
- Pharmacovigilance Integration:Post-market surveillance systems must capture adverse event data across hormone-sensitive populations, complicating multi-jurisdiction product stewardship.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Genistein Market |
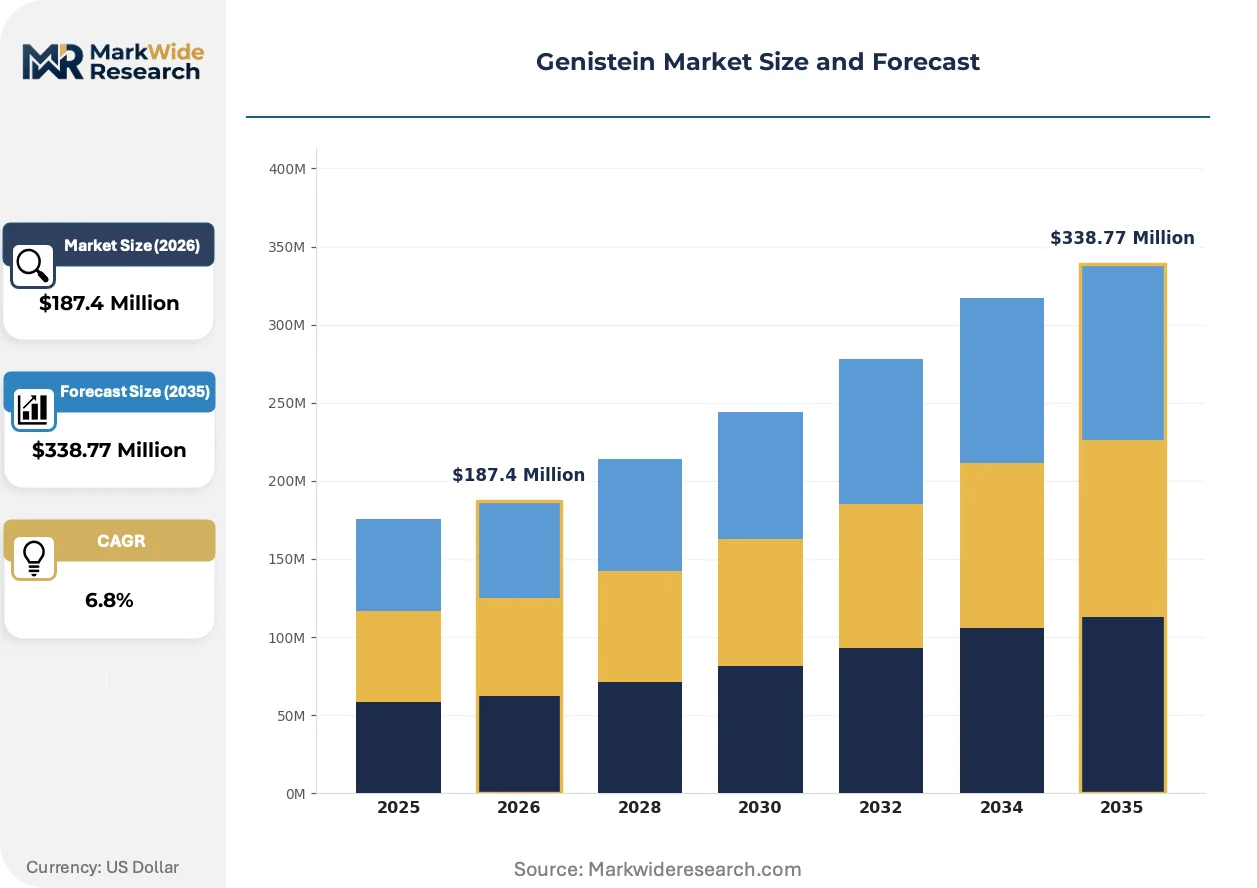
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Capsule, Liquid, Tablet Application: Nutraceuticals, Pharmaceuticals, Cosmetics, Functional Foods End User: Healthcare Professionals, Retail Consumers, Food Industry, Cosmetic Manufacturers Distribution Channel: Online Retail, Specialty Stores, Pharmacies, Supermarkets |
| Companies Covered | Merck KGaA, Tocris Bioscience, Cayman Chemical, PhytogenX, Inc., MedChemexpress LLC, HBCChem, Inc., Tokyo Chemical Industry, Toronto Research Chemicals, DSM Nutritional Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Genistein Market Emerging Trajectories
Fermentation infrastructure and precision extraction technologies are compressing production timelines while regulatory harmonization efforts reshape cross-border ingredient qualification protocols.
Continuous chromatography systems paired with simulated moving bed technology is automating genistein purification from complex fermentation broths. Pharmaceutical contract manufacturers in Germany and Switzerland deploy these platforms to achieve 99.5% purity specifications for research chemical supply. The capital intensity of this equipment is consolidating toll processing capacity among specialized fermentation houses.
EFSA's 2023 guidance on novel food equivalence assessments creates accelerated pathways for fermentation-derived isoflavones previously categorized as non-traditional. European ingredient suppliers leverage these protocols to position microbial genistein as chemically identical to botanical extracts. Supplement formulators in France and the Netherlands now specify fermentation origin to bypass soybean allergen labeling requirements.
Ingredient buyers are consolidating supplier relationships around vertically integrated producers offering certificate-of-analysis transparency. Nutraceutical brands in the United States now require batch-level HPLC potency verification and contaminant screening documentation. This qualification burden favors larger fermentation operators with captive analytical laboratories over commodity traders.
Genistein Market Segmentation
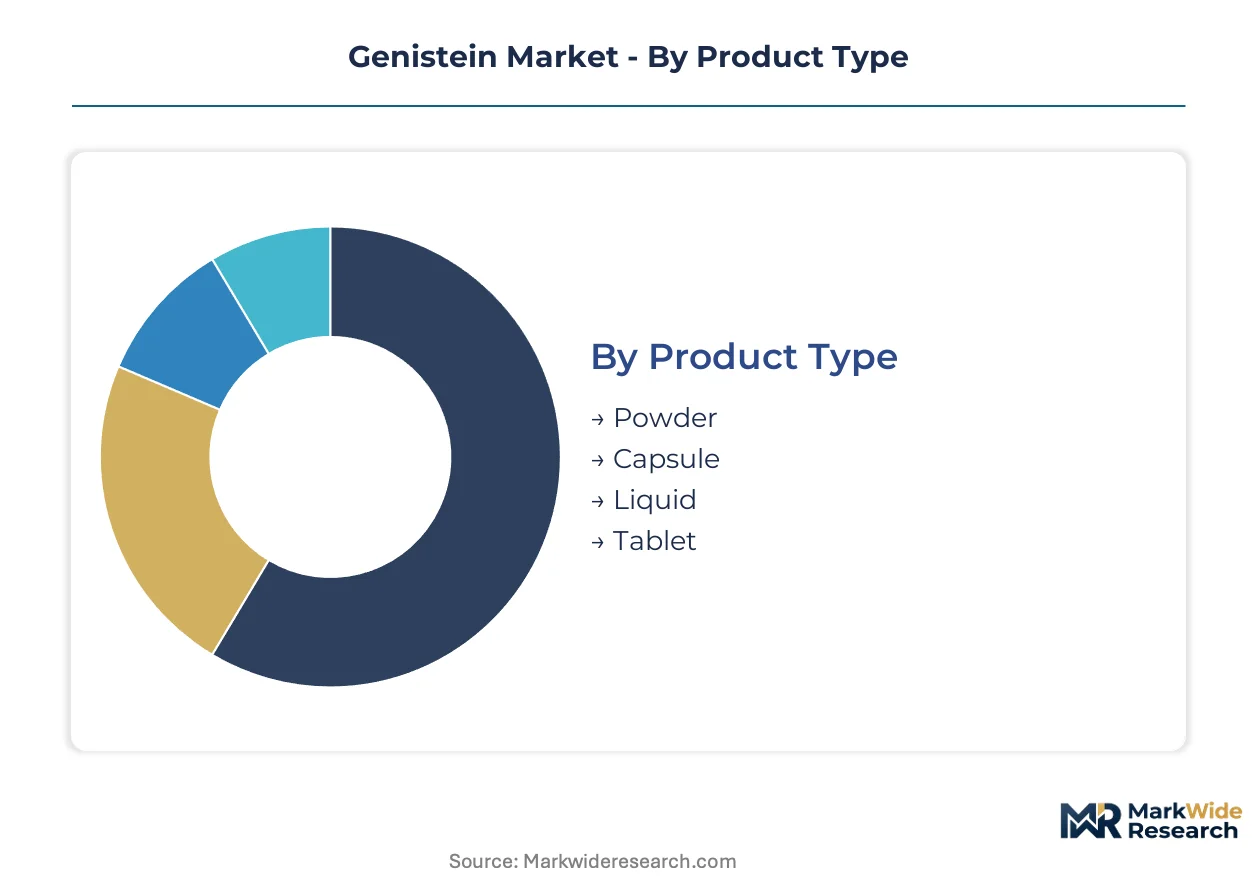
Genistein formulations span standalone bulk ingredients and embedded finished goods, with each configuration demanding distinct purity specifications, regulatory pathways, and customer procurement behaviors. Understanding where segments sit on this integration spectrum clarifies margin structures and competitive dynamics across the value chain.
Product Type:
Powder and liquid formats serve bulk procurement channels for downstream formulators, while capsules and tablets target direct consumption with embedded dosing precision and stability engineering.
- Powder:Unformulated crystalline or spray-dried material standardized to isoflavone content percentages serves nutraceutical compounders and pharmaceutical excipient blenders. Demand concentrates in United States contract manufacturing organizations seeking pharmaceutical-grade material for menopause-support supplement lines, though FDA identity testing requirements under 21 CFR Part 111 elevate analytical qualification costs for smaller procurement batches.
- Liquid:Ethanol or propylene glycol solutions enable beverage fortification and tincture manufacturing with simplified homogenization. Functional food manufacturers in France and the Netherlands specify fermentation-derived liquid genistein to bypass soybean allergen labeling under EFSA novel food guidance while achieving rapid dispersion in dairy alternative matrices.
- Capsule:Hard-shell gelatin or HPMC encapsulation delivers pre-measured dosing for direct-to-consumer wellness positioning. Retail supplement brands favor two-piece capsules for formulation flexibility with co-ingredients like vitamin D or black cohosh.
- Tablet:Compressed formulations with binders and disintegrants target pharmacy shelf presence and prescription-adjacent positioning. German and Swiss pharmaceutical contract manufacturers specify tablet formats for clinical trial supply and research chemical distribution.
Powder leads volumes today; liquid is gaining share fastest.
Application:
Cost tier stratification separates commodity nutraceutical supply from premium pharmaceutical and functional food segments, with regulatory burden and purity specification driving margin differentiation.
- Nutraceuticals:Dietary supplement formulations targeting hormone health, bone density, and cardiovascular support constitute the foundational demand base. United States supplement brands procure standardized isoflavone extracts for menopause-support SKUs, with online retail channels capturing margin pools through direct-to-consumer subscription models.
- Functional Foods:Beverage and dairy alternative fortification with standardized isoflavone content supports hormone-health positioning claims. Manufacturers face EFSA novel food assessment requirements for non-traditional soy-derived extracts, though fermentation-derived genistein achieves accelerated equivalence pathways.
- Pharmaceuticals:Analytical-grade reference materials and investigational drug substances serve oncology and metabolic syndrome clinical trials. Cayman Chemical and Merck KGaA anchor this tier through mass spectrometry-verified potency certificates and ISO 17025-accredited quality systems.
- Cosmetics:Topical antioxidant and phytoestrogen applications in anti-aging formulations command premium pricing through derma-cosmetic positioning. Korean and Japanese beauty brands drive demand for micronized powder with enhanced epidermal penetration specifications.
Nutraceuticals anchor current revenue; functional foods are climbing the fastest.
End User:
Customer type determines procurement sophistication, with healthcare professionals and food manufacturers demanding certificate-of-analysis transparency while retail consumers prioritize brand trust and convenience.
- Healthcare Professionals:Integrative medicine practitioners and clinical nutritionists specify genistein for hormone-modulating protocols, requiring third-party tested material with heavy metal and pesticide residue documentation. United States naturopathic practices drive demand for fermented-origin isolates with reduced endocrine-disrupting contaminant risk.
- Food Industry:Dairy alternative and functional beverage manufacturers procure bulk isoflavones for standardized fortification. Indian urban preventive health segments create expansion opportunities as FSSAI functional food regulations establish compliance pathways for fermented genistein ingredients.
- Retail Consumers:Direct purchasers through online wellness platforms and specialty supplement retailers prioritize subscription convenience and clean-label positioning. E-commerce margin capture enables premium pricing for organic-certified and non-GMO verified products.
- Cosmetic Manufacturers:Derma-cosmetic formulators seek micronized genistein with enhanced stability in emulsion systems. Korean beauty conglomerates specify fermentation-derived material for reduced color and odor versus botanical extracts.
Healthcare professionals dominate premium tier procurement; food industry volume is expanding most quickly.
Distribution Channel:
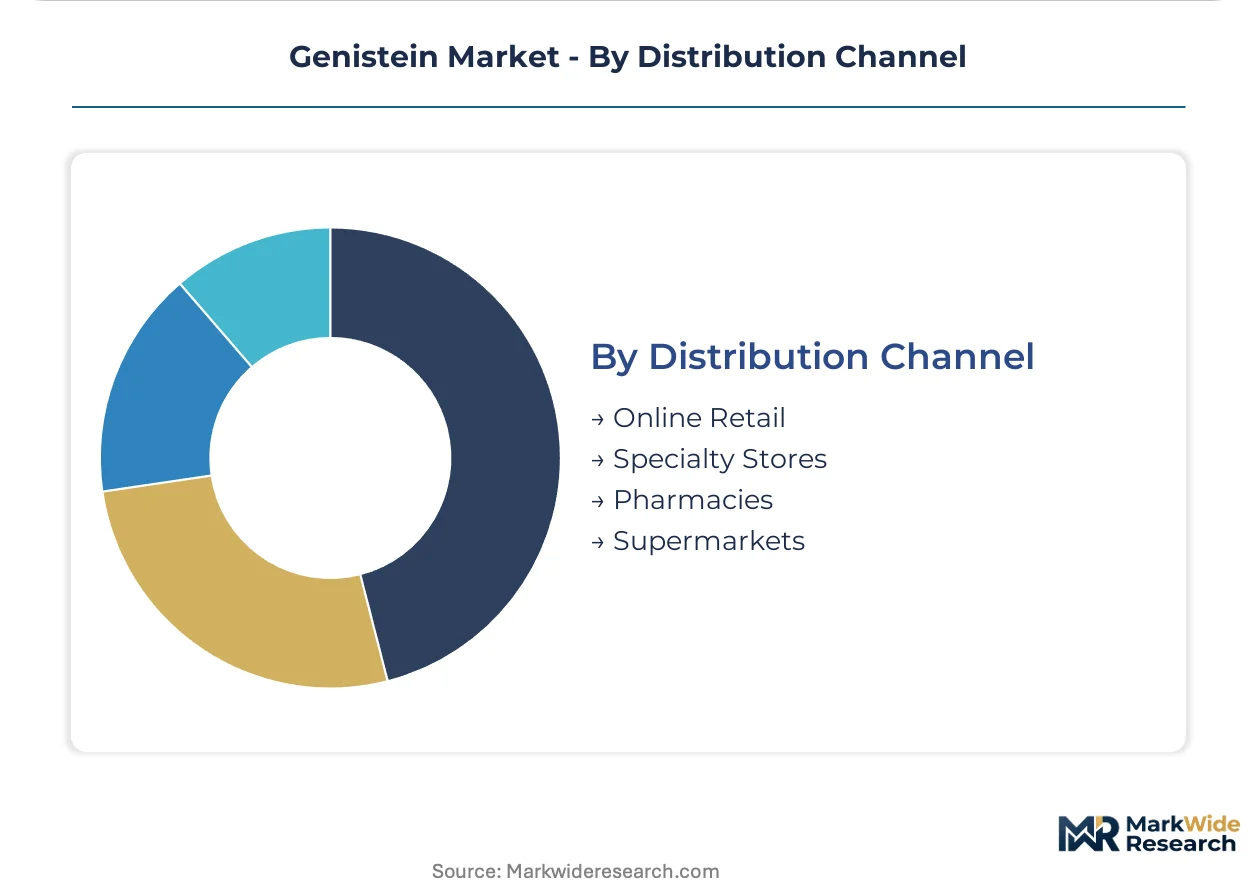
Geography of demand concentration shapes channel strategy, with United States online retail capturing direct-to-consumer growth while European pharmacy and specialty store networks maintain regulatory credibility.
- Online Retail:Direct-to-consumer wellness platforms and marketplace sellers bypass wholesale distribution markups, capturing margin pools previously allocated to retail intermediaries. Subscription models lock in recurring revenue for United States genistein supplement brands with hormone-health positioning.
- Pharmacies:Brick-and-mortar and digital pharmacy networks provide regulatory credibility and pharmacist consultation for menopause-support categories. German and Swiss pharmacy chains maintain strict supplier qualification requiring ISO 17025-accredited analytical documentation.
- Specialty Stores:Health food retailers and natural product co-ops serve clean-label seeking consumers with organic and non-GMO verification requirements. United States regional chains differentiate through third-party certification transparency.
- Supermarkets:Mass-market grocery channels expand functional food and beverage availability, though shelf space competition with resveratrol and lignan formulations fragments isoflavone visibility.
Pharmacies maintain the highest trust premium; online retail shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
DSM Nutritional Products anchors European fermentation capacity for isoflavone production, while United States functional food manufacturers drive bulk procurement volumes. Chinese fermentation houses expand microbial genistein output for export markets. Indian nutraceutical formulators leverage FSSAI functional food regulations to access urban preventive health segments.
United States
Functional beverage manufacturers in California and the Pacific Northwest fortify dairy alternatives with standardized isoflavone content for hormone-health positioning. FDA dietary supplement Current Good Manufacturing Practice regulations under 21 CFR Part 111 enforce identity testing and contaminant controls for botanical extracts. Greater Boston hosts analytical-grade reference material suppliers serving oncology clinical trials requiring mass spectrometry-verified potency certificates.
Germany
Pharmaceutical contract manufacturers in Bavaria and North Rhine-Westphalia deploy continuous chromatography systems for 99.5% purity genistein purification. EFSA novel food equivalence assessments enable accelerated market entry for fermentation-derived isoflavones previously categorized as non-traditional. Frankfurt-Rhine-Main clusters integrate toll processing capacity with ISO 17025-accredited quality systems for research chemical distribution.
China
Fermentation houses in Jiangsu and Shandong provinces engineer CRISPR-optimized yeast strains achieving gram-per-liter genistein titers. The country's national food safety regulator evaluates novel food applications for microbial-derived phytoestrogens under evolving biotech ingredient frameworks. Yangtze River Delta biotech parks consolidate upstream strain development with downstream purification infrastructure for export-grade output.
India
FSSAI functional food regulations establish compliance pathways for fermented genistein ingredients targeting Mumbai and Delhi-NCR urban preventive health segments. Maharashtra-based nutraceutical formulators integrate isoflavones into menopause-support supplement lines distributed through pharmacy networks. Karnataka's biotechnology corridor attracts contract fermentation capacity for export-oriented isoflavone production.
Japan
Cosmetic manufacturers in Osaka and Tokyo prefectures procure micronized genistein for derma-cosmetic anti-aging formulations with enhanced epidermal penetration specifications. PMDA oversight of quasi-drug ingredients shapes stability testing requirements for topical phytoestrogen applications. Kanto region beauty conglomerates specify fermentation-derived material for reduced color and odor profiles versus botanical extracts.
Genistein Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue microbial fermentation platforms and direct-to-consumer subscription models. Market structure consolidates around vertically integrated fermentation operators with captive analytical laboratories and certificate-of-analysis transparency. Three archetypes dominate: pharmaceutical-grade reference material suppliers, nutraceutical bulk compounders, and cosmetic-grade micronization specialists. Competitive moves center on backward integration into strain engineering capabilities and geographic expansion through EFSA novel food equivalence certifications.
Within the pharmaceutical-grade tier, Merck KGaA and Cayman Chemical exemplify analytical-standard production for clinical and preclinical research channels. DSM Nutritional Products anchors the nutraceutical bulk segment through fermentation-derived isoflavone platforms. These three entities represent distinct capability concentrations: Merck KGaA leverages pharmaceutical-grade purification infrastructure, Cayman Chemical differentiates via mass spectrometry-verified potency certificates, and DSM Nutritional Products integrates captive soybean processing with microbial cell factory engineering.
| Leading Market Players |
|---|
| Merck KGaA |
| Tocris Bioscience |
| Cayman Chemical |
| PhytogenX, Inc. |
| MedChemexpress LLC |
| HBCChem, Inc. |
| Tokyo Chemical Industry |
| Toronto Research Chemicals |
| DSM Nutritional Products |
| Others |
Supply Flow & Price Mechanics
EU Green Deal sustainability mandates gate qualified supply and premium-tier pricing access for genistein producers, as fermentation-derived platforms with verified carbon footprints command price premiums while conventional solvent-extracted material faces margin compression from compliance costs.
Pricing Analysis
Input-cost pass-through from Brazilian non-GMO soybean premiums and CRISPR-optimized yeast strain licensing fees shapes tiered pricing across botanical and fermentation-derived genistein. Pharmaceutical-grade material with ISO 17025-accredited potency certificates commands the highest tier, while commodity powder for nutraceutical compounding faces acute price sensitivity from United States contract manufacturing organizations. Cost compression in standard-grade supply is intensifying as Chinese fermentation houses expand gram-per-liter titer yields, eroding extraction cost advantages.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Singapore anchor hub-and-spoke patterns for fermentation-derived genistein, with cold-chain warehousing for liquid formats and ambient storage for crystalline powder. Supply concentrates in China, Germany, and India, with Jiangsu Province fermentation houses feeding European toll processors and Maharashtra-based formulators serving domestic pharmacy networks. Raw material flows draw from Brazilian non-GMO soybean estates, engineered yeast master cell banks, and chromatography resin suppliers. Single-source vulnerability in CRISPR strain IP creates supply chain risk. Distribution runs through pharmaceutical-grade reference material distributors for research channels and direct-to-consumer platforms for supplement brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Genistein market margins expand through fermentation cost-down curves displacing botanical extraction, while premium-tier pricing concentrates in analytical-grade reference materials for oncology clinical trials.
For Market Incumbents: Cement backward integration into engineered yeast strain development to lock in titer yield advantages against emerging microbial cell factory specialists. Expand captive analytical laboratory capacity for ISO 17025-accredited batch certification, defending position against commodity traders lacking certificate-of-analysis transparency. Prioritize EFSA novel food equivalence dossiers for fermentation-derived material to accelerate European market access. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the lowest customer acquisition friction for hormone-health positioning in the United States wellness segment. Target FSSAI-compliant fermented genistein supply to Indian urban preventive health markets, where pharmacy network penetration remains underdeveloped. Pursue white-label manufacturing partnerships with dairy alternative brands seeking standardized isoflavone fortification. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap fermentation operators with captive strain engineering capabilities because supply chain consolidation favors vertically integrated producers with analytical transparency. Fermentation houses achieving gram-per-liter titers represent acquisition targets with defendable cost structures. Watch CRISPR regulatory guidance from China's national food safety regulator as inflection indicator for microbial-derived phytoestrogen market access.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Strain Engineering | Captive CRISPR-optimized yeast platforms collapse extraction costs versus soybean-dependent competitors. |
| EFSA Novel Food Dossier Submission | Fermentation-derived equivalence certifications unlock European functional food and beverage fortification channels. |
| ISO 17025 Laboratory Accreditation | Third-party potency verification commands premium pricing from German and Swiss pharmaceutical contract manufacturers. |
| Direct-to-Consumer Subscription Launch | Online wellness platforms bypass wholesale markups and capture recurring revenue in United States menopause-support categories. |
| FSSAI Functional Food Compliance Investment | Regulatory pathway establishment enables access to Mumbai and Delhi-NCR urban preventive health segments. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fermentation plant managers, nutraceutical procurement leads at United States contract manufacturing organizations, regulatory affairs specialists navigating EFSA novel food pathways, and pharmacy category buyers in German and Swiss distribution networks. Secondary validation drew from FDA 21 CFR Part 111 guidance documents, EFSA novel food assessment registers, FSSAI functional food notifications, and customs trade data for isoflavone extract flows. Bottom-up segment sizing and top-down market triangulation cross-checked volume estimates across the analysis window.
Segment-weighting approaches modeled genistein demand across product type dimensions including powder, liquid, capsule, and tablet formats; application tiers spanning nutraceuticals, functional foods, pharmaceuticals, and cosmetics; and distribution channels from online retail through pharmacy networks. CAGRs were derived from growth rate convergence modeling across these dimensions, incorporating fermentation titer yield improvement curves and regulatory approval timeline assumptions for novel food equivalence pathways.
The model assumes a particular technology adoption path; alternative pathways for microbial cell factory engineering would alter the outlook if regulatory frameworks shift toward stricter GMO labeling or if botanical extraction achieves cost parity through solvent recovery innovations. Forecasts reflect documented assumptions regarding EFSA assessment velocity and FSSAI implementation timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Biotechnology
Pullulanase Market
Food Biotechnology
Flaxseed Gum Market
Food Biotechnology
Trans-Galactooligosaccharides Market
Food Biotechnology
Trypsin Market
Food Biotechnology
Phycocyanin Market
Food Biotechnology
Europe Eubiotics Market
Food Biotechnology
Direct-Fed Microbial Products Market
Food Biotechnology
Brown Algae Protein Market
Food Biotechnology
Prebiotics Market
Food Biotechnology
Red Seaweed Extract Market
Food Biotechnology
Global Food Biotechnology Market
Food Biotechnology
Biotech Flavors Market
Food Biotechnology
Zein Protein Market
Food Biotechnology
Bangladesh Starch and Starch Derivative Market
Food Biotechnology
Chlorella Market
Food Biotechnology
Asia Pacific Eubiotics Market