
 Direct-Fed Microbial Products Market | 2026-2036
Direct-Fed Microbial Products Market Size, Share, and Industry Trends Forecast 2026-2036
Direct-Fed Microbial Products Market Outlook
Project finance and contract-manufacturing arrangements is fragmenting capital requirements across the Direct-Fed Microbial Products competitive landscape. Chr. Hansen Holding A/S leverages its strain-banking capabilities to dominate high-value probiotic formulations for ruminant nutrition. Kemin Industries anchors its position through backward integration into fermentation capacity, while Lallemand specializes in yeast-based direct-fed microbials for monogastric species.
Direct-fed microbial products comprise live or viable cultures of bacteria, yeast, or fungi administered to animals through feed or drinking water, typically delivered at concentrations ranging from 10^6 to 10^9 colony-forming units per gram depending on target species and intended physiological effect. These formulations function primarily to stabilize gastrointestinal microbiota, enhance nutrient digestibility, and support immune competence in production animals. Multi-strain combinations currently command premium positioning due to synergistic colonization effects, while powder formulations retain volume leadership across livestock farms because of blending compatibility with existing feed-milling infrastructure. The aquaculture end-user segment exhibits the fastest structural expansion as shrimp and salmon producers confront intensifying pathogen pressure in high-density systems.
The FDA's Veterinary Feed Directive and the EU's feed additive authorization process under EFSA jointly elevate barriers to novel microbial strain commercialization, compelling developers to invest in multi-year safety and efficacy dossiers. China's NMPA and Ministry of Agriculture equivalent standards for feed-grade microorganisms add further complexity for suppliers targeting integrated pork and poultry operations. Stakeholders must monitor evolving residue-testing protocols and strain-specific registration requirements as regulatory divergence between major jurisdictions intensifies compliance costs.
Market Dynamics
Regulatory pressure on sub-therapeutic antibiotics in livestock production is compressing adoption timelines for microbial alternatives, while strain-banking capabilities and fermentation capacity constraints concentrate competitive advantage among integrated suppliers.
Growth Catalysts
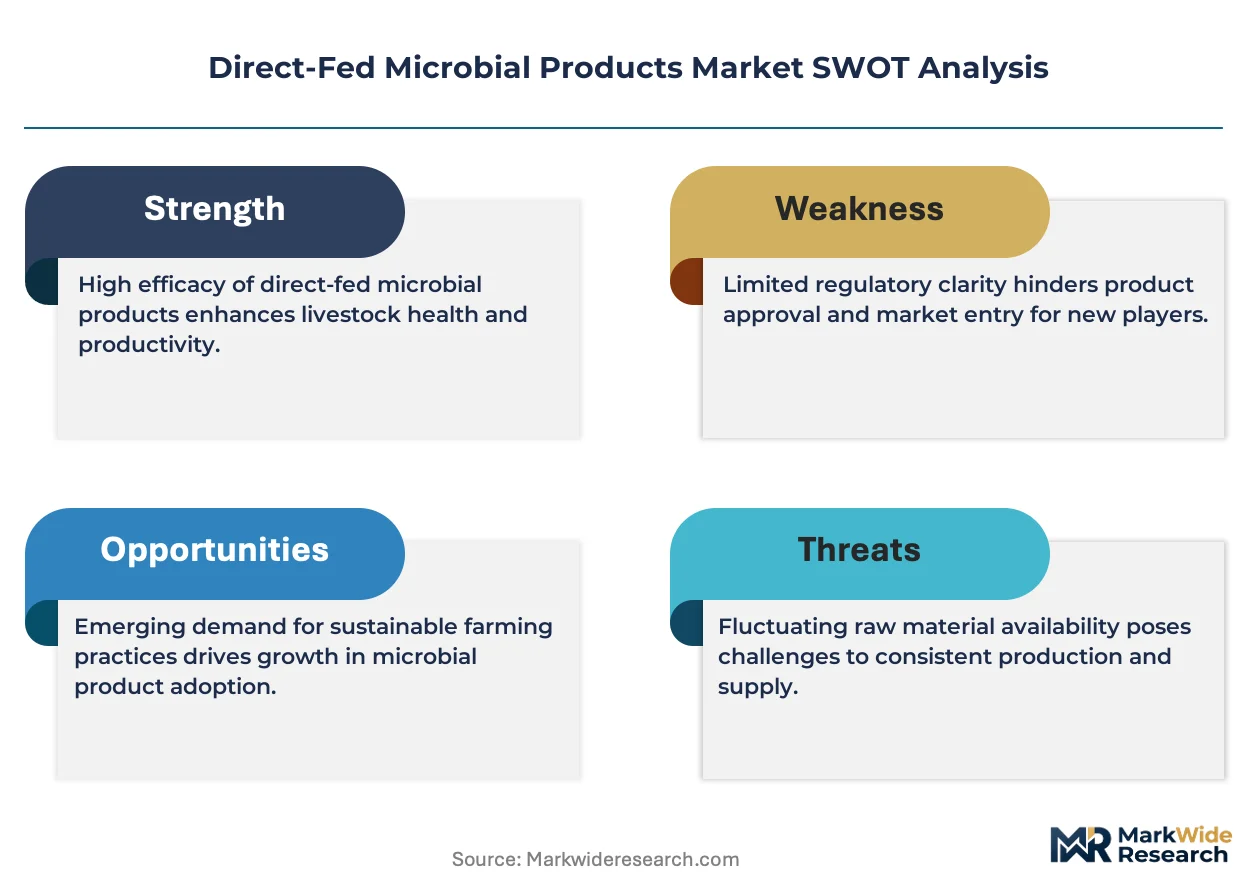
- Antibiotic withdrawal mandates:The FDA's Veterinary Feed Directive and EFSA's feed additive authorization framework compel livestock producers toward microbial growth promoters across North American and European dairy operations.
- Aquaculture intensification:Shrimp and salmon producers in high-density systems deploy direct-fed microbials to manage pathogen pressure without chemical residues.
- Multi-strain synergies:Formulations combining bacterial and yeast cultures demonstrate superior colonization persistence, justifying premium positioning in ruminant nutrition programs.
Market Restraints
- Strain registration costs:EFSA's multi-year safety and efficacy dossier requirements elevate capital barriers for novel microbial commercialization.
- Live culture stability:Viability loss during pelleting and storage limits formulation options for feed-mill integration.
- Regulatory divergence:China's NMPA standards for feed-grade microorganisms impose parallel compliance burdens distinct from Western frameworks.
Strategic Opportunities
- Underpenetrated monogastric segments:Swine operations in Southeast Asia present expansion targets as antibiotic restrictions propagate through supply chains.
- Water-delivery systems:Drinking water administration formats bypass feed-mill infrastructure constraints in backyard poultry operations.
- Carbon accounting integration:EU Green Deal methane reduction incentives position rumen-modifying microbials as qualifying interventions for dairy carbon credits.
Industry Challenges
- Strain characterization expertise:Genomic identification and stability testing capabilities remain concentrated among specialized contract research organizations.
- Cross-border documentation:Harmonizing CFU enumeration methods between ISO and national veterinary pharmacopeia standards delays multi-territory launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Direct-Fed Microbial Products Market |
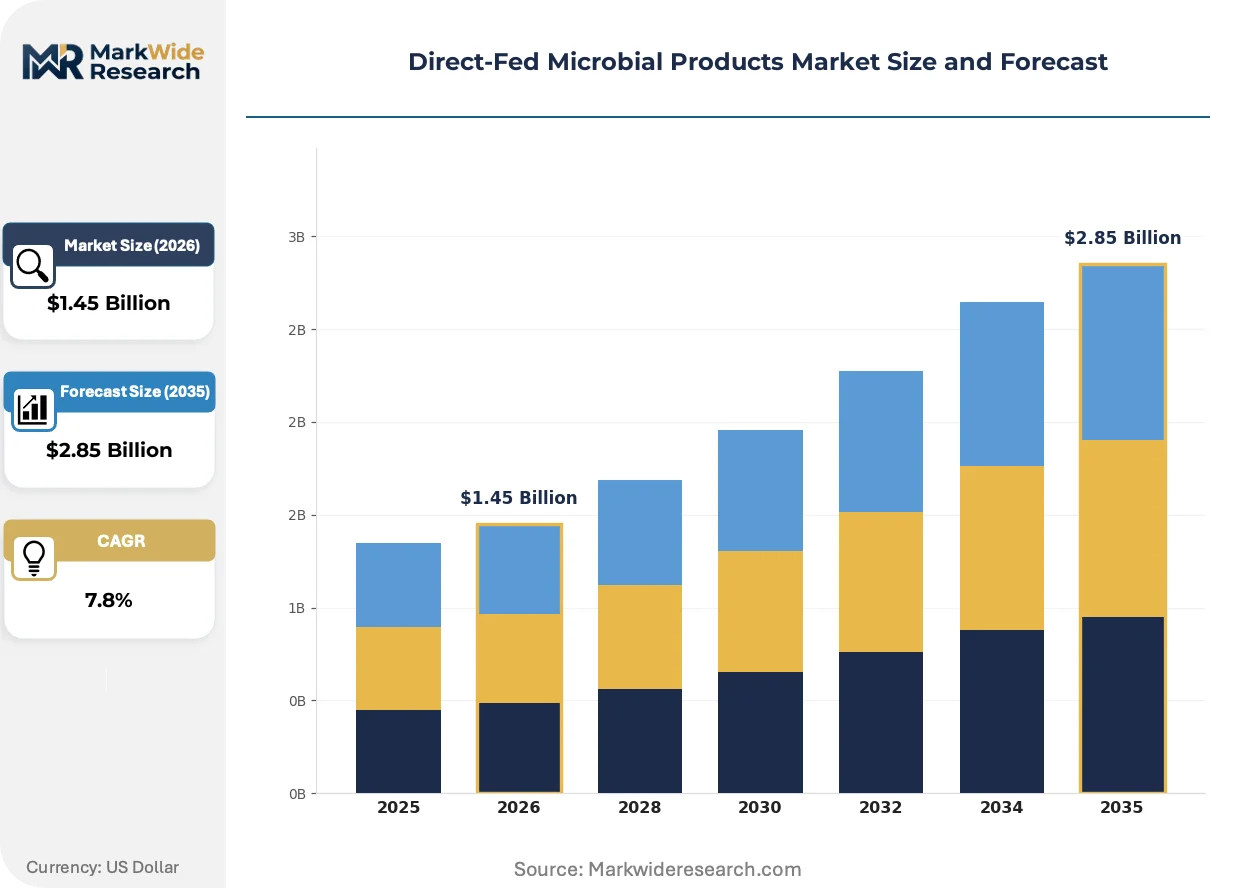
| Market Size in 2026 | $1.45 Billion |
| Market Size in 2035 | $2.85 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Strain, Multi-Strain, Probiotics, Prebiotics End User: Livestock Farms, Aquaculture, Pet Feed, Nutritional Supplements Distribution Channel: Online Retail, Direct Sales, Distributors, wholesalers Formulation Type: Powder, Liquid, Granular, Pelleted |
| Companies Covered | Archer Daniels Midland Company, Kemin Industries, Chr. Hansen Holding A/S, Koninklijke DSM, Novus International, Bio-Vet, Lallemand, Biomin Holding GmbH, Alltech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Direct-Fed Microbial Products Market Strategic Shifts
Formulation science and delivery mechanisms are converging to extend microbial viability through feed processing while regulatory frameworks harden around residue testing and strain traceability.
Encapsulation technologies are hybridizing live cultures with lipid and polysaccharide matrices to protect viability through steam pelleting temperatures. Poultry integrators in the southeastern United States are piloting these thermotolerant formulations to eliminate post-pelleting liquid application steps. The technology is hybridizing powder and liquid delivery categories, compressing equipment capital requirements for mid-scale feed mills.
EFSA's evolving criteria for qualified presumption of safety status now require whole-genome sequencing data for novel bacterial strains. This industrial consequence elevates dossier preparation costs and extends development timelines for academic spinouts. European ruminant feed compounders are responding by consolidating procurement around established strain libraries with existing regulatory clearances.
Integrated livestock operations are unbundling microbial procurement from compound feed contracts to negotiate direct supply relationships with strain developers. This channel disintermediation bypasses traditional feed additive distributors in large North American dairy cooperatives. The shift is most visible in California's Central Valley, where processor-backed sustainability mandates require documented microbial intervention in milk supply bases.
Direct-Fed Microbial Products Market Segmentation
Direct-fed microbial products exhibit distinct performance profiles across formulation and delivery categories. Strain stability requirements and feed-mill integration constraints create divergent commercial trajectories for each segment.
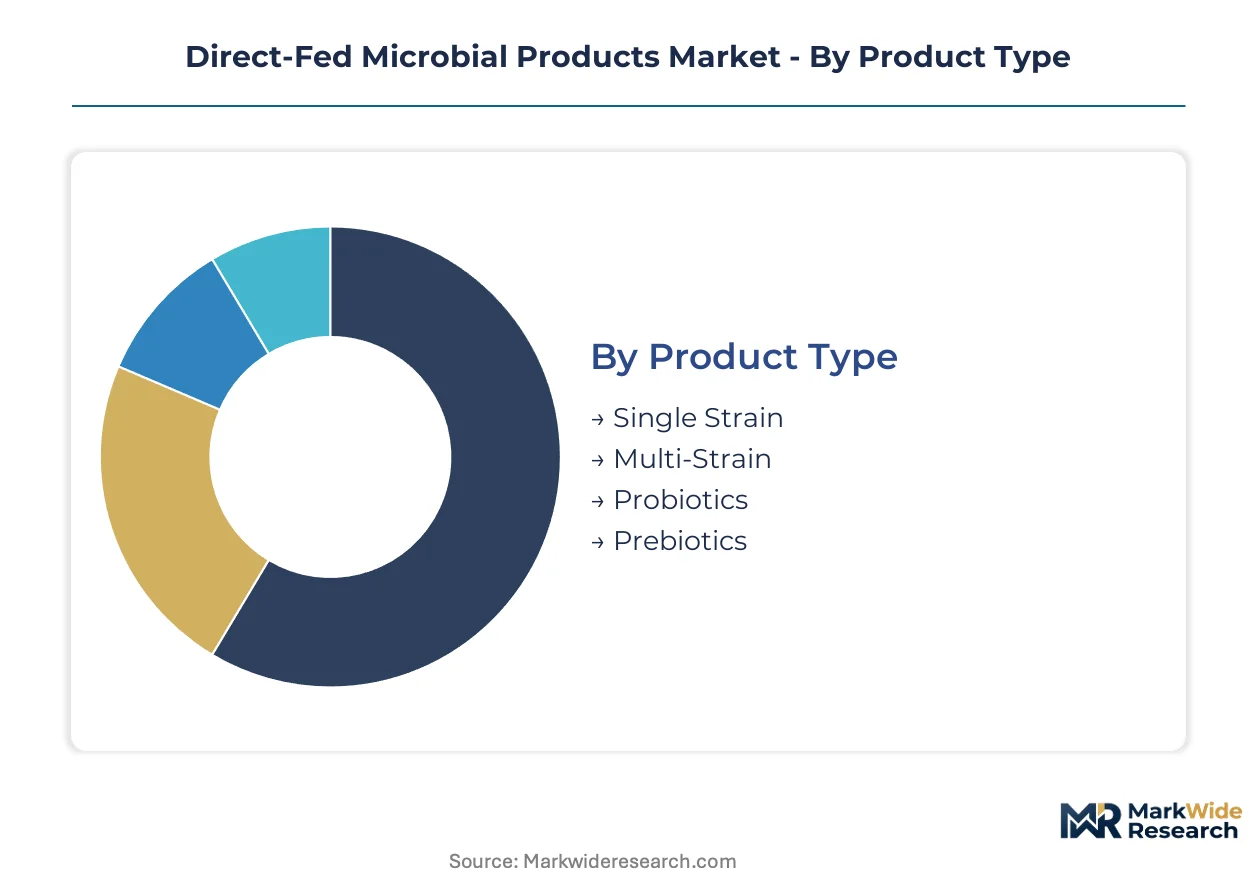
Product Type:
After-sales technical support intensity varies sharply across product categories, with multi-strain formulations demanding sustained field advisory while single-strain products require minimal post-sale intervention.
- Multi-Strain:Combinations of bacterial and yeast cultures engineered for synergistic colonization persistence in ruminant gastrointestinal tracts. Demand concentrates in North American dairy cooperatives where processor-backed sustainability mandates require documented microbiome intervention. EFSA's whole-genome sequencing requirements for novel strain combinations elevate dossier costs and extend commercialization timelines.
- Single Strain:Isolated bacterial or fungal cultures standardized to specific CFU concentrations for targeted physiological effects. Poultry integrators in the southeastern United States favor these formulations for their predictable stability profiles and simpler regulatory documentation.
- Probiotics:Live beneficial microorganisms administered to establish or maintain gut microbiota balance in production animals.
- Prebiotics:Non-digestible substrates that selectively stimulate growth or activity of beneficial gut microbiota.
Multi-Strain holds the largest share; momentum sits with Probiotics as genomic characterization capabilities expand.
End User:
Cost tier stratification separates capital-intensive livestock operations from price-sensitive backyard producers.
- Livestock Farms:Industrial-scale cattle, swine, and poultry operations deploying microbials for growth promotion and feed conversion efficiency. North American dairy operations drive volume as FDA Veterinary Feed Directive restrictions on sub-therapeutic antibiotics intensify adoption. California's Central Valley processor-backed sustainability programs mandate documented microbial intervention across milk supply bases.
- Aquaculture:Shrimp and salmon producers in high-density systems utilizing direct-fed microbials for pathogen management without chemical residue risks. Southeast Asian shrimp farms exhibit steepest expansion trajectory as intensification pressures mount.
- Pet Feed:Companion animal nutrition applications targeting digestive health and immune support in premium pet food formulations.
- Nutritional Supplements:Specialized formulations for therapeutic or performance-enhancing applications beyond standard feed integration.
Livestock Farms command dominant volume; Aquaculture climbs the fastest as pathogen pressure intensifies in high-density production systems.
Distribution Channel:
Customer type fragmentation separates integrated operations negotiating direct supply relationships from fragmented backyard producers dependent on intermediaries.
- Direct Sales:Strain developers supplying large livestock cooperatives through unbundled procurement arrangements bypassing traditional feed additive distributors. Large North American dairy operations leverage this channel to secure documented sustainability credentials for processor contracts.
- Distributors:Specialized feed additive distributors maintaining regional inventories and technical field support for mid-scale compounders. European ruminant feed compounders consolidate procurement through these channels around established strain libraries with existing EFSA clearances.
- Online Retail:E-commerce platforms serving small-scale livestock operations and companion animal owners with standardized formulations.
- Wholesalers:Bulk volume intermediaries aggregating demand from fragmented regional feed mills.
Distributors retain volume leadership; Direct Sales gains share fastest as integrated operations disintermediate traditional channels.
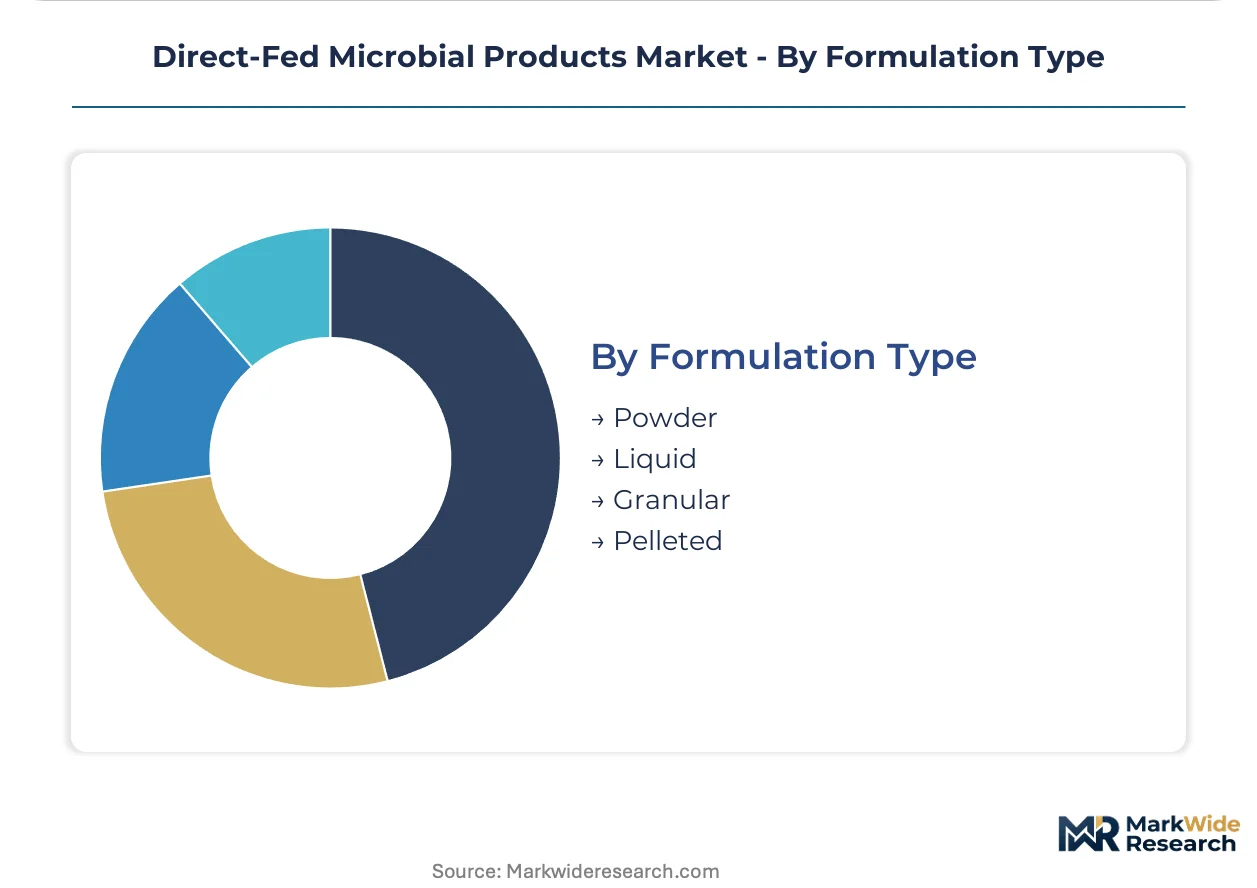
Formulation Type:
Supply concentration in thermotolerant encapsulation capabilities is reshaping competitive positioning across delivery formats.
- Powder:Dry formulations blending compatibly with existing feed-milling infrastructure across livestock farms. Volume leadership persists due to low equipment capital requirements and established handling protocols.
- Liquid:Aqueous suspensions for drinking water administration bypassing feed-mill constraints in backyard poultry operations. Post-pelleting application steps create operational complexity for mid-scale mills.
- Granular:Intermediate particle size formulations balancing flowability with protection during mechanical handling.
- Pelleted:Compressed formulations requiring thermotolerant encapsulation to protect viability through steam pelleting temperatures.
Powder holds the largest share; Pelleted gains momentum as encapsulation technologies hybridize delivery categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory pressure on sub-therapeutic antibiotics is compressing adoption timelines for microbial alternatives across major livestock-producing economies. National feed additive frameworks and processor-backed sustainability mandates are reshaping procurement patterns in concentrated dairy and poultry regions.
United States
California's Central Valley dairy cooperatives drive volume as processor sustainability programs mandate documented microbial intervention in milk supply bases. The FDA's Veterinary Feed Directive restricts antibiotic growth promoters, compelling adoption in southeastern poultry integrators. Thermotolerant encapsulation pilots in Georgia and Alabama eliminate post-pelleting liquid application steps.
Germany
EFSA's whole-genome sequencing requirements for novel bacterial strains elevate dossier costs and extend commercialization timelines for academic spinouts. Ruminant feed compounders consolidate procurement around established strain libraries with existing regulatory clearances. Bavaria's dairy processing clusters anchor demand for documented microbiome interventions in supply chain contracts.
China
NMPA standards for feed-grade microorganisms impose parallel compliance burdens distinct from Western frameworks for integrated pork and poultry operations. Yangtze River Delta producers confront intensifying pathogen pressure in high-density systems. The Ministry of Agriculture equivalent standards shape product development pathways for domestic compounders.
Brazil
Swine operations in southern states present expansion targets as antibiotic restrictions propagate through export-oriented supply chains. ANVISA's evolving residue-testing protocols align with EU import requirements for microbial intervention documentation. São Paulo's integrated poultry processors pilot direct supply relationships with strain developers.
Netherlands
EU Green Deal methane reduction incentives position rumen-modifying microbials as qualifying interventions for dairy carbon credits in Randstad processing clusters. EFSA's feed additive authorization framework compels livestock producers toward microbial growth promoters. Wageningen University's research corridors anchor strain characterization expertise for European compounders.
Direct-Fed Microbial Products Market Competitive Environment
On the supply side, the industry is consolidating around integrated suppliers with captive fermentation capacity and established strain libraries. Tiered competitive dynamics separate global strain developers from regional compounders and specialized yeast cultivators. Three archetypes dominate: integrated biotechnology platforms, fermentation-focused ingredient suppliers, and yeast-specialist cultivators. Capacity expansion and backward integration into fermentation infrastructure represent the dominant competitive moves.
Among biotechnology-anchored platforms, Chr. Hansen Holding A/S and Koninklijke DSM occupy positions exemplifying strain-banking capabilities and multi-territory regulatory clearances. Kemin Industries represents the fermentation-integrated archetype with captive upstream production capacity. Lallemand sits within the yeast-specialist tier, anchoring positioning in monogastric applications. These three entities collectively illustrate the capability concentration shaping procurement consolidation among large livestock cooperatives.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Kemin Industries |
| Chr. Hansen Holding A/S |
| Koninklijke DSM |
| Novus International |
| Bio-Vet |
| Lallemand |
| Biomin Holding GmbH |
| Alltech |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on thermotolerant encapsulation specialists compresses pricing spreads between powder and pelleted formulations while forcing feed mills into captive supply arrangements with strain developers. EFSA's whole-genome sequencing mandates and China's NMPA parallel compliance burdens determine both certification-grade premiums and geographic sourcing decisions across integrated livestock operations.
Pricing Analysis
Certification level creates the primary spread, with EFSA-cleared multi-strain formulations commanding substantial premiums over single-strain alternatives lacking dossier documentation. Three-tier pricing structure across premium, standard, and economy levels reflects after-sales technical support intensity, with multi-strain products bundling sustained field advisory. Cost compression in standard-tier powder formulations is intensifying because feed mills internalize blending capabilities. Backyard poultry operators exhibit highest price sensitivity, while California dairy cooperatives prioritize documented sustainability credentials over unit economics.
Supply Chain Analysis
Upstream fermentation feedstock sourcing draws from Denmark, the Netherlands, and the United States where Chr. Hansen, DSM, and Kemin Industries anchor captive production capacity. Critical inputs include specialized growth media, cryoprotectant formulations for culture banking, and lipid-polysaccharide matrices for thermotolerant encapsulation. Single-source vulnerability concentrates in thermotolerant encapsulation capabilities, with European and North American mills dependent on a limited supplier base. Distribution runs through specialized feed additive distributors maintaining regional inventories, though direct sales channels gain share as integrated operations disintermediate traditional intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The direct-fed microbial products market is recovering from a cyclical trough as antibiotic withdrawal mandates across major livestock-producing regions reset procurement baselines. Regulatory pressure on sub-therapeutic growth promoters creates durable replacement demand for microbial alternatives.
For Market Incumbents: Pre-empt channel disintermediation by consolidating direct supply relationships with California dairy cooperatives and Southeast Asian shrimp integrators before competitors capture processor-backed sustainability mandates. Anchor defensive positioning through backward integration into thermotolerant encapsulation capacity, neutralizing the single-source vulnerability threatening margin stability. Elevation of EFSA dossier costs presents a consolidation lever against academic spinouts lacking multi-year safety documentation resources.
For New Entrants and Emerging Players: Establish a beachhead in water-delivery system formats for backyard poultry operations, bypassing feed-mill infrastructure constraints that exclude powder-centric incumbents. Southeast Asian swine operations present the most penetrable geography as antibiotic restrictions propagate through export-oriented supply chains. A go-to-market angle anchored in drinking water administration compatibility eliminates capital barriers for mid-scale producers while sidestepping established distributor relationships.
For Investors and Strategic Acquirers: EFSA's evolving qualified presumption of safety criteria reshapes the acquisition landscape toward strain libraries with existing regulatory clearances rather than novel discovery platforms. Long-term viability over the coming decade rests on fermentation capacity scale and multi-territory dossier coverage rather than single-market penetration. Acquisition target archetypes include specialized yeast cultivators with monogastric positioning and contract research organizations with genomic characterization capabilities. The signal to watch is consolidation momentum among European ruminant feed compounders consolidating procurement around established strain libraries.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Kemin Industries demonstrates how captive upstream production insulates margin pressure from contract-manufacturing queues. |
| Multi-Territory Regulatory Dossier Investment | Chr. Hansen's strain-banking capabilities leverage EFSA clearances to compress commercialization timelines in China's NMPA framework. |
| Thermotolerant Encapsulation Technology Licensing | Poultry integrators in Georgia and Alabama pilot lipid-matrix formulations to eliminate post-pelleting liquid application steps. |
| Direct Supply Relationship Unbundling | Large North American dairy cooperatives bypass traditional feed additive distributors to secure documented sustainability credentials. |
| Carbon Credit Qualification Pathway | EU Green Deal methane reduction incentives position rumen-modifying microbials for dairy processor-backed intervention mandates. |
Study Parameters
Two parallel data streams informed the analysis: primary field engagement with industry stakeholders and secondary validation across regulatory and trade databases. Interview participants included strain development executives at biotechnology platforms, regulatory affairs leads navigating EFSA and NMPA frameworks, procurement directors at integrated livestock cooperatives, technical field advisors supporting multi-strain formulation deployment, and fermentation operations managers. Secondary sources encompassed FDA Veterinary Feed Directive implementation records, EFSA feed additive authorization dossiers, customs data tracking fermentation equipment imports, and SEC filings from publicly traded ingredient suppliers. Bottom-up volume estimates from end-user segments were cross-referenced against top-down capacity assessments from major fermentation facilities.
Forecast inputs considered strain registration timelines, antibiotic restriction propagation patterns, and encapsulation technology adoption curves across the projection horizon. Segmentation dimensions modeled include product type, end-user species, formulation format, and distribution channel, with additional granularity on regulatory clearance status. CAGRs were derived from slope analysis of historical adoption curves adjusted for policy inflection points. Industry-specific forecast inputs incorporated EFSA whole-genome sequencing cost trajectories and EU Green Deal methane credit eligibility thresholds for rumen-modifying interventions.
Sensitivities concentrate around regulatory divergence between Western and Chinese frameworks, thermotolerant encapsulation supplier consolidation, and feed mill internalization of blending capabilities. Forecasts reflect assumptions about sustained antibiotic withdrawal momentum and processor sustainability mandate expansion. Cross-checking against EFSA authorization pipeline data and NMPA feed-grade microorganism registration disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Biotechnology
Bangladesh Starch and Starch Derivative Market
Food Biotechnology
Carbohydrate Enzyme Preparation Market
Food Biotechnology
Chlorella Market
Food Biotechnology
Salmon Polynucleotide (PN) Market
Food Biotechnology
Biotech Flavors Market
Food Biotechnology
Biopreservation Market
Food Biotechnology
Colostrum Market
Food Biotechnology
Lupin Protein Market
Food Biotechnology
Trypsin Market
Food Biotechnology
Zein Protein Market
Food Biotechnology
Glucose Oxidase Market
Food Biotechnology
Perilla Protein Market
Food Biotechnology
Casein Peptone Market
Food Biotechnology
Trans-Galactooligosaccharides Market
Food Biotechnology
Microalgae Market
Food Biotechnology
Pullulanase Market