
 North America Eubiotics Market | 2026-2036
North America Eubiotics Market Size, Share, and Industry Trends Forecast 2026-2036
North America Eubiotics Market Analytics
Organic acid formulations is hardening as the default replacement for zinc oxide and antibiotic growth promoters in swine and poultry rations. Cargill Incorporated leverages its integrated grain-to-feed infrastructure to control input costs across the value chain. BASF SE anchors its position through specialized propionic and formic acid blends engineered for North American feed mill specifications. Royal DSM competes on microbial strain intellectual property, sustaining R&D intensity in lactic acid bacteria development.
Eubiotics comprise live microorganisms, fermentable fibers, short-chain fatty acids, and enzymatic catalysts that modulate gastrointestinal microbiota to enhance nutrient absorption, pathogen exclusion, and immune competence in animals and humans. Probiotics and organic acids command the largest share of product value, with enzymes representing the fastest-expanding margin pool as precision-formulation capabilities advance. The animal feed application dominates volume consumption, while human nutraceuticals and functional foods concentrate premium pricing power in the United States and Canada.
The FDA Veterinary Feed Directive and EPA biopesticide registration pathways govern product approval, label claims, and manufacturing facility compliance across the United States. Health Canada and the PMRA administer parallel oversight for Canadian entrants, with CFIA feed regulations adding inspection-layer requirements for cross-border suppliers. Stakeholders must monitor evolving state-level antibiotic restriction bills and emerging carbon-accounting rules for livestock supply chains to anticipate product specification shifts and certification demands.
Market Dynamics
The FDA Veterinary Feed Directive continues to compress antibiotic growth promoter use across US livestock operations, redirecting capital toward microbiome-modulating feed additives and accelerating eubiotic formulation R&D cycles.
Growth Catalysts
- Antibiotic restriction mandates:The FDA Veterinary Feed Directive eliminates over-the-counter antibiotic access for growth promotion, forcing swine and poultry integrators toward organic acid and probiotic alternatives.
- Midwest feedlot corridor concentration:Iowa-to-Texas cattle finishing operations generate concentrated demand for rumen-modulating eubiotics that improve feed conversion efficiency.
- Precision fermentation advances:Novel production methods slash lactic acid bacteria cultivation costs, expanding margin pools for mid-tier feed compounders.
Market Restraints
- Propionic acid price volatility:Feed-grade organic acid input costs fluctuate with petrochemical and agricultural feedstock markets, compressing blender margins.
- Canadian cross-border compliance friction:Health Canada and CFIA inspection-layer requirements add timeline risk for US suppliers serving Ontario and Quebec poultry integrators.
- Live probiotic stability limitations:Spore-forming strain shelf life constraints restrict distribution radius and cold-chain feasibility for certain formulations.
Strategic Opportunities
- Layer hen cage-free transition:California and Massachusetts state mandates for enriched housing systems elevate stress-related gut health challenges, opening premium eubiotic positioning.
- Carbon accounting integration:Emerging livestock supply chain emissions tracking creates certification demand for microbiome solutions that reduce enteric methane.
- Direct-to-contract grower channels:Bypassing traditional distributor networks lets specialty eubiotic firms capture margin from independent poultry operators in Georgia and Arkansas.
Industry Challenges
- Microbial strain IP complexity:Patent thickets around proprietary lactic acid bacteria isolates force licensing negotiations that delay product launch timelines.
- Feed mill integration friction:Legacy batching systems require retrofitting for heat-sensitive live probiotic inclusion, raising capex barriers for smaller regional mills.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Eubiotics Market |
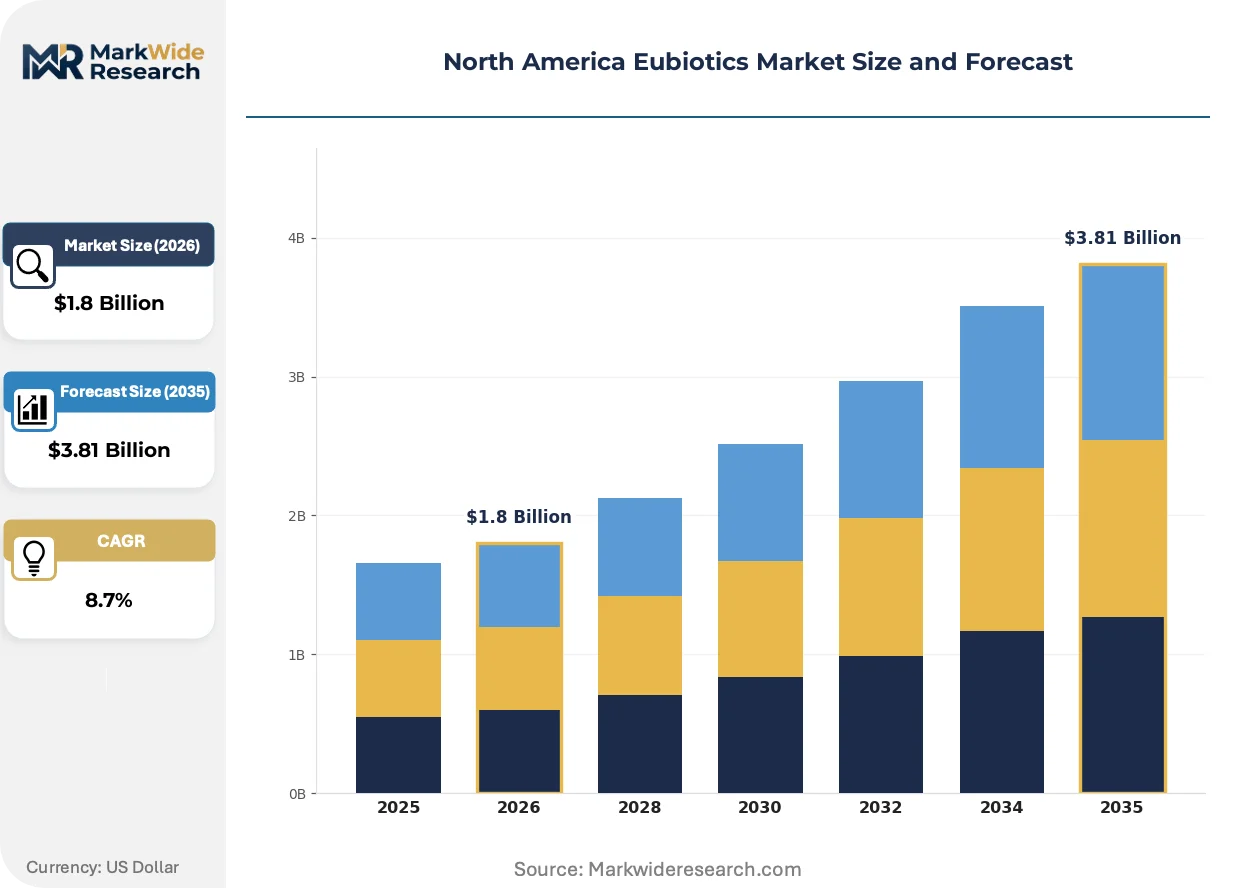
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Probiotics, Prebiotics, Organic Acids, Enzymes Application: Animal Feed, Human Nutraceuticals, Dietary Supplements, Functional Foods Form: Powder, Liquid, Granules, Tablets End User: Agriculture, Food Industry, Healthcare, Pharmaceuticals |
| Companies Covered | Novus International Inc., Royal DSM, BASF SE, Behn Meyer Group, Addcon, Cargill Incorporated, Chr. Hansen A/S, E. I. Du Pont De Nemours and Company, Kemin Industries Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Eubiotics Market Evolving Landscape
Multi-strain synbiotic formulations are displacing single-ingredient additives as US integrators demand measurable return on microbiome investment. Formulation science, regulatory data requirements, and procurement sophistication are converging to reshape competitive positioning.
Postbiotic metabolite concentrates—cell-free supernatants containing short-chain fatty acids and bioactive peptides—are consolidating technical validation efforts among swine nutritionists seeking alternatives to live culture handling complexity. Large integrators in North Carolina and Iowa are piloting these shelf-stable formats for nursery pig diets. The technology is consolidating R&D spending away from traditional freeze-dried probiotic powders toward metabolite characterization and standardization.
The EPA biopesticide registration pathway now governs an expanding subset of eubiotic claims involving pathogen inhibition, adding data generation burdens for entrants seeking dual-function labels. Registration timelines stretch 18-24 months for novel microbial strains not previously cleared for feed use. Poultry-focused suppliers with existing EPA dossiers gain first-mover advantage in the layer segment where Salmonella reduction claims carry premium pricing power.
Outcome-based feed additive contracts are displacing traditional tonnage-based purchasing across major US protein packer supply chains. Tyson Foods and Pilgrim's Pride integrators now tie eubiotic supplier payments to measurable feed conversion or mortality reduction metrics. This shift concentrates procurement authority with nutritionist teams and compresses supplier margins for products lacking robust trial data.
North America Eubiotics Market Segmentation
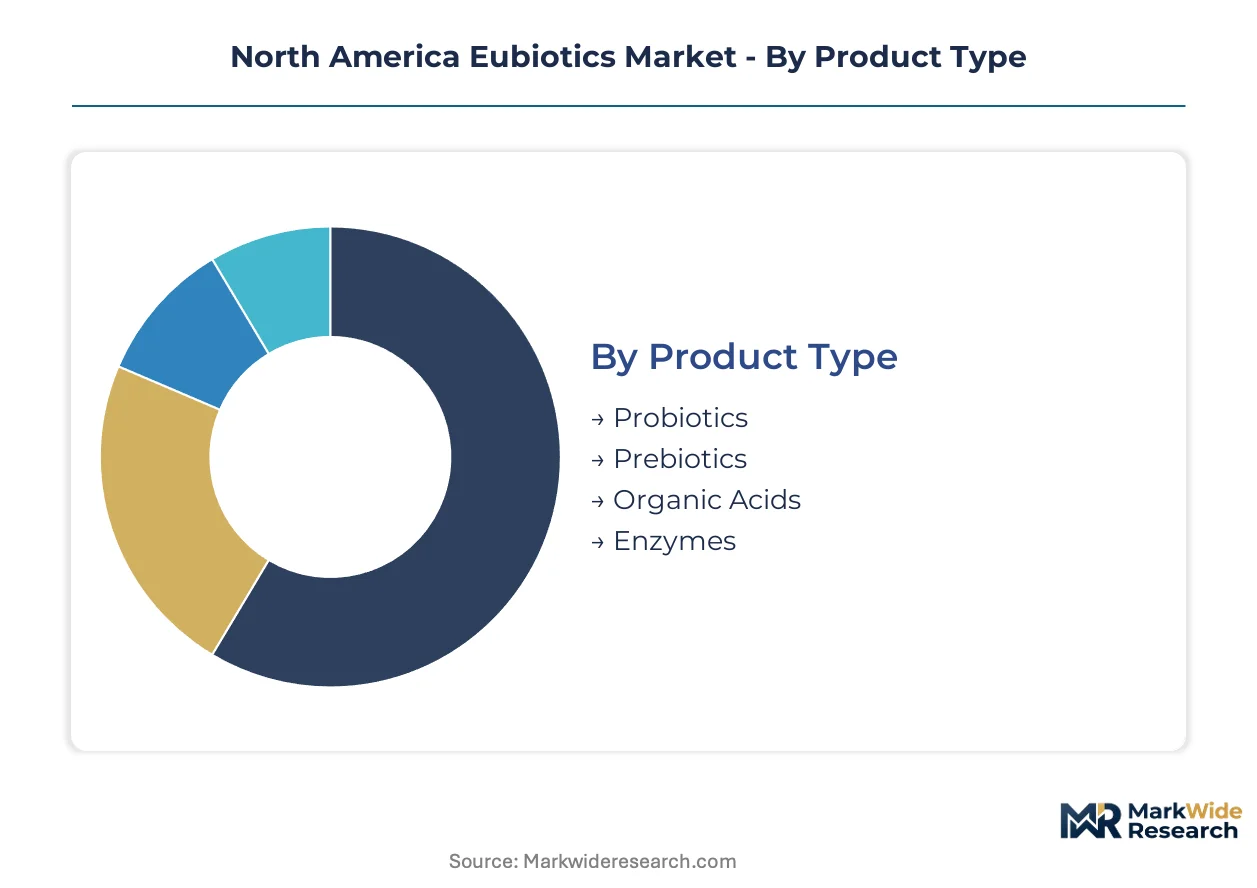
Eubiotic procurement in North America stratifies sharply across species-specific feed formulations and human wellness positioning, with regulatory pathways and shelf-stability requirements fragmenting supplier economics. Buyers weight microbiome efficacy validation against handling complexity and EPA registration status when selecting across product categories.
Product Type:
Feed formulators prioritize documented pathogen inhibition and heat stability when allocating budget across microbiome-modulating inputs.
- Probiotics:Live microbial cultures—primarily lactic acid bacteria and Bacillus spores—deliver direct colonization benefits in poultry and swine gut environments. Demand clusters with Iowa-to-Georgia integrators seeking Salmonella reduction claims for layer operations under FDA Veterinary Feed Directive compliance pressure.
- Organic Acids:Propionic, formic, and butyric acid formulations acidify gut pH to suppress gram-negative pathogens while improving mineral absorption. Midwest feedlot corridors from Texas to Nebraska drive volume for rumen-modulating blends that replace antibiotic growth promoters in cattle finishing rations.
- Prebiotics:Fermentable oligosaccharides and resistant starches selectively nourish beneficial microbiota without live culture handling constraints.
- Enzymes:Exogenous carbohydrases and proteases unlock nutrient bioavailability from plant-based feedstuffs, with phytase dominating phosphorus release applications.
Organic acids lead on scale; enzymes lead on momentum.
Application:
End-use economics diverge between commodity feed tonnage and premium-priced human wellness channels.
- Animal Feed:Poultry, swine, and cattle rations absorb the majority of eubiotic volume, with post-weaning pig diets and broiler starter feeds commanding the highest inclusion rates per ton. Tyson Foods and Pilgrim's Pride supply chains now tie supplier payments to feed conversion ratio improvements.
- Functional Foods:Fermented dairy and beverage applications carry premium positioning in California and Massachusetts retail corridors, though regulatory substantiation burdens constrain claim breadth.
- Human Nutraceuticals:Capsule and powder formats target digestive wellness and immune modulation in direct-to-consumer channels.
- Dietary Supplements:Standalone probiotic SKUs compete on CFU count transparency and strain-specific clinical backing.
Animal feed dominates absolute volume; functional foods capture the steepest margin expansion.
Form:
Handling infrastructure and climate exposure dictate format selection across the value chain.
- Powder:Spray-dried and freeze-dried concentrates serve feed mill batching systems and supplement manufacturing, with moisture sensitivity limiting distribution radius in humid southeastern states.
- Liquid:Acid and enzyme solutions integrate via spray application at feed mills, offering precise dosing control for large-volume operations.
- Granules:Coated particulates protect heat-sensitive probiotics during pelleting processes, expanding formulation options for high-temperature feed processing.
- Tablets:Compressed formats serve human supplement and veterinary prescription channels requiring dose standardization.
Powder leads on scale; granules lead on momentum.
End User:
Procurement sophistication and regulatory scrutiny intensity vary dramatically across buyer categories.
- Agriculture:Integrated poultry and swine operations concentrate demand through nutritionist-directed specifications, with independent contract growers in Arkansas and Georgia emerging as a direct-sales target for specialty suppliers.
- Food Industry:Fermented product manufacturers and clean-label formulators seek eubiotic inputs for shelf-life extension and sensory profile modulation.
- Healthcare:Clinical nutrition and hospital formulary procurement demands strain-level documentation and lot traceability exceeding feed-grade requirements.
- Pharmaceuticals:Live biotherapeutic product developers navigate FDA IND pathways for microbiome-based drug candidates, with manufacturing standards diverging sharply from feed additive norms.
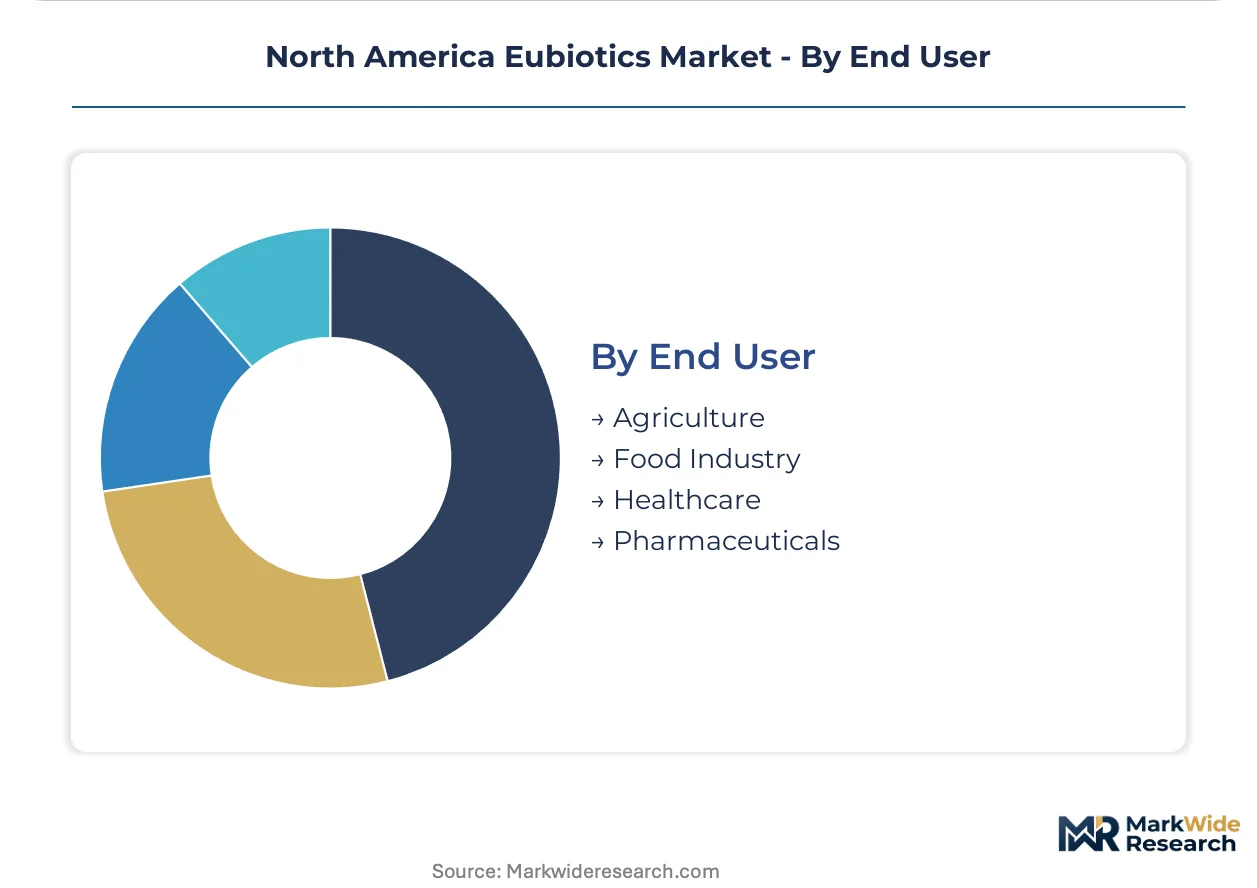
Agriculture leads on scale; pharmaceuticals lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Iowa-to-Georgia poultry and feedlot corridor anchors North American eubiotic demand, with state-level antibiotic restrictions and integrated processor procurement reshaping supplier geography across the continent.
United States
Midwestern feedlot operations from Nebraska to Texas and Southeastern broiler integrators in Georgia and Arkansas concentrate procurement volume. The FDA Veterinary Feed Directive eliminates over-the-counter antibiotic access for growth promotion, redirecting formulation budgets toward organic acid and probiotic alternatives. California and Massachusetts cage-free mandates for layer hens elevate stress-related gut health challenges, opening premium eubiotic positioning in those state markets.
Canada
Ontario and Quebec poultry integrators drive cross-border demand for EPA-registered microbial strains with Salmonella reduction claims. Health Canada and the PMRA administer parallel oversight for feed additive approval, with CFIA inspection-layer requirements adding timeline risk for US suppliers serving Canadian operations. Prairie cattle finishing operations in Alberta generate concentrated demand for rumen-modulating organic acid blends.
Mexico
Jalisco and Guanajuato poultry production clusters expand eubiotic adoption as processors align with US export standards for antibiotic-free certification. The country's national agricultural regulator enforces feed additive safety protocols that increasingly mirror FDA guidance documents. Querétaro and Aguascalientes feed mill corridors attract investment from multinational suppliers seeking geographic diversification.
North America Eubiotics Market Competitive Landscape
Portfolio diversification dominates the current landscape as incumbent chemical and nutrition companies expand microbial offerings through acquisition and internal R&D acceleration. The vendor base stratifies across three tiers: integrated agribusiness conglomerates with captive distribution, specialized fermentation technology firms with strain IP libraries, and regional feed additive blenders serving independent livestock operations. Market structure rewards backward integration into fermentation capacity and forward integration into nutritionist-directed technical service teams.
Among diversified chemical conglomerates, BASF SE exemplifies the integrated archetype through its specialized organic acid production infrastructure. Royal DSM occupies a position within the microbial technology tier, anchored by intellectual property concentration in lactic acid bacteria development. Cargill Incorporated represents the agribusiness-integrated model, leveraging grain origination and feed manufacturing assets to control input costs across the value chain.
| Leading Market Players |
|---|
| Novus International Inc. |
| Royal DSM |
| BASF SE |
| Behn Meyer Group |
| Addcon |
| Cargill Incorporated |
| Chr. Hansen A/S |
| E. I. Du Pont De Nemours and Company |
| Kemin Industries Inc. |
| Others |
Value Network & Pricing Analysis
Integrated poultry processors from Iowa to Georgia concentrate procurement authority through nutritionist-directed specifications, anchoring contract-based long-term offtake as the dominant pricing model across the North America eubiotics market. This buyer concentration feeds back into supplier consolidation pressures, with formulation houses competing on trial data depth rather than spot-price undercutting.
Pricing Analysis
Input-cost pass-through from propionic acid and agricultural feedstock volatility shapes blender margin structures across organic acid formulations. Three-tier pricing structure across premium, standard, and economy levels separates EPA-registered microbial strains with Salmonella reduction claims from generic organic acid blends and commodity probiotic powders. Cost compression in standard-tier organic acids is intensifying because petrochemical derivative pricing tracks energy market swings. Independent contract growers in Arkansas and Georgia exhibit highest price sensitivity, while layer operations under California cage-free mandates show lowest sensitivity due to stress-related gut health premiums.
Supply Chain Analysis
Workforce availability in fermentation-specialized manufacturing geographies constrains capacity expansion for lactic acid bacteria cultivation, with technical talent pools concentrating in the Netherlands, Denmark, and select US Midwest research corridors. Raw material dependencies center on corn-derived dextrose for fermentation media, petrochemical feedstocks for organic acid synthesis, and specialized cryoprotectants for freeze-dried probiotic stabilization. Single-source vulnerability runs through proprietary microbial strain libraries held by incumbent fermentation technology firms. Distribution runs through integrated feed mill networks and direct-to-contract grower channels bypassing traditional agricultural distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
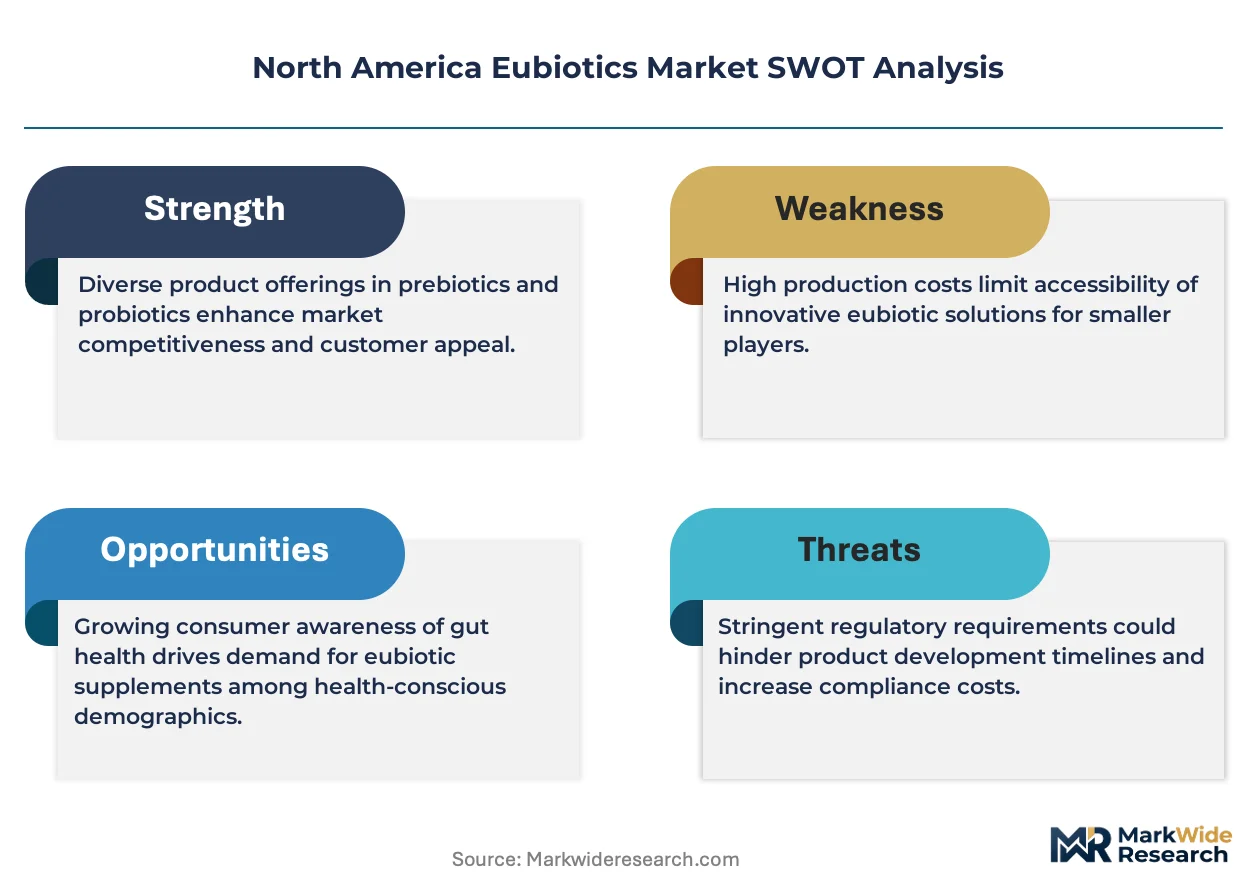
The North America eubiotics market reads as a late-cycle quality story, with FDA Veterinary Feed Directive compliance pressure redirecting formulation budgets toward microbiome solutions with documented pathogen inhibition data.
For Market Incumbents: Hedge against propionic acid price volatility through backward integration into fermentation capacity or captive supply agreements with agricultural feedstock processors. BASF SE and Royal DSM demonstrate the defensive value of specialized organic acid infrastructure and microbial strain IP libraries respectively. Certification investment in EPA biopesticide registration pathways protects pricing power as dual-function claims consolidate procurement authority with nutritionist teams. For New Entrants and Emerging Players: The FDA Veterinary Feed Directive in the United States opens a window for postbiotic metabolite concentrates targeting swine nursery diets, where shelf-stable formats bypass live culture handling complexity. White-space targets include direct-to-contract grower channels in Georgia and Arkansas, and carbon-accounting certification for enteric methane reduction in Midwest feedlot corridors. A technical service team go-to-market angle bypasses distributor margin capture. For Investors and Strategic Acquirers: Specialized fermentation technology firms with strain IP libraries are the most active acquirer in this space, with diversified nutrition and chemical conglomerates seeking microbial capability additions. Long-term viability hinges on precision fermentation cost curves and regulatory data requirements for novel strain approval. Watch EPA registration timeline compression as the inflection signal indicating competitive moat widening for dossier-heavy entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Cargill Incorporated controls input costs through captive corn origination and feed manufacturing assets. |
| EPA Biopesticide Registration Pathway | Poultry-focused suppliers with existing dossiers gain first-mover advantage in Salmonella reduction claims. |
| Direct-to-Contract Grower Channel Development | Specialty eubiotic firms capture margin from independent poultry operators in Georgia and Arkansas. |
| Postbiotic Metabolite Concentrate Launch | Large integrators in North Carolina and Iowa pilot shelf-stable formats for nursery pig diets. |
| Carbon Accounting Certification Program | Microbiome solutions reducing enteric methane attract livestock supply chain emissions tracking demand. |
Research Methodology
Bottom-up animal feed modeling reconciled against top-down fermentation capacity tracking forms the analytical core of this study. Primary interviews with nutrition directors at integrated poultry operations, procurement leads at feed compounders, regulatory affairs specialists at microbial technology firms, and technical service veterinarians supply demand-side validation. Secondary sources include FDA Veterinary Feed Directive guidance documents, EPA biopesticide registration databases, CFIA feed regulations, and SEC filings from diversified nutrition conglomerates. Cross-referencing bottom-up species-specific inclusion rate assumptions against top-down organic acid and probiotic production capacity estimates ensures dimensional consistency.
Historical trendline analysis across organic acid price indices, fermentation yield improvements, and regulatory approval timelines informs projection mechanics. Segmentation dimensions modeled include product type, application, form, and end user, with species-specific feed conversion ratio sensitivity as an industry-specific overlay. CAGRs derive from curve-fitting approaches applied to documented adoption rates and capacity expansion announcements. Forecast inputs incorporate precision fermentation cost trajectories and state-level antibiotic restriction bill progression.
Revisions become necessary when EPA registration timelines extend beyond baseline assumptions, propionic acid feedstock markets experience sustained volatility, or carbon-accounting rules for livestock supply chains mandate new certification standards. Material deviation in these triggers warrants pause and re-evaluation of volume and value assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Biotechnology
Direct-Fed Microbial Products Market
Food Biotechnology
Research-Grade Proteins Market
Food Biotechnology
Zein Protein Market
Food Biotechnology
Global Food Biotechnology Market
Food Biotechnology
Pullulanase Market
Food Biotechnology
Colostrum Market
Food Biotechnology
Glucose Oxidase Market
Food Biotechnology
Brown Algae Protein Market
Food Biotechnology
Chlorella Market
Food Biotechnology
Non-Animal Alternative Testing Market
Food Biotechnology
Africa Eubiotics Market
Food Biotechnology
Beta-Propeller Phytases Market
Food Biotechnology
Red Seaweed Extract Market
Food Biotechnology
Global GMO Testing Market
Food Biotechnology
Bangladesh Starch and Starch Derivative Market
Food Biotechnology
Lupin Protein Market