
 Global Food Biotechnology Market | 2026-2036
Global Food Biotechnology Market Size, Share, and Industry Trends Forecast 2026-2036
Global Food Biotechnology Market Analysis
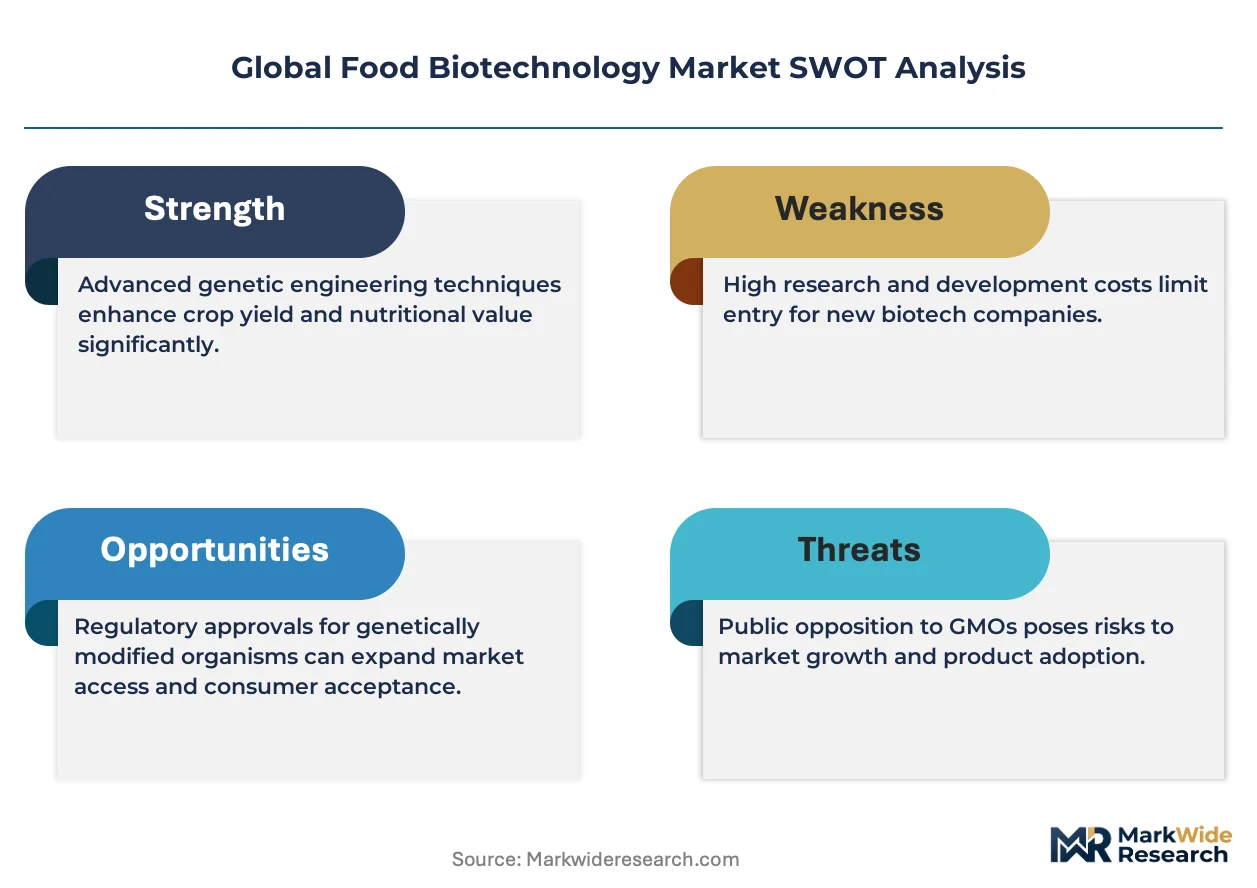
Premium-grade enzyme formulations is rotating toward wider commercial deployment as food processors seek cleaner-label solutions. BASF SE leverages its fermentation expertise to supply high-purity enzymes for bakery and dairy applications. Bayer CropScience AG anchors its position through integrated seed-and-trait platforms that reduce agricultural input intensity. Syngenta AG competes via advanced biopesticide pipelines targeting resistance management in row crops.
Food biotechnology encompasses the application of molecular biology, genetic engineering, and cell culture techniques to modify organisms, develop novel ingredients, or enhance processing efficiency, typically operating at pilot scales of 10,000–100,000 liters for industrial enzyme production. Its primary purpose centers on improving yield, nutritional profiles, shelf stability, or functional properties across the food supply chain. Genetically Modified Organisms occupy the largest value share as staple crop traits dominate planted hectares, while Enzymes capture accelerating growth from precision fermentation scale-up in alternative protein and clean-label sectors. CRISPR-Cas9 commands outsized R&D investment despite regulatory heterogeneity, whereas Recombinant DNA retains mature commercial traction in oilseed and grain modification.
The FDA governs food additive and GRAS determinations for biotech-derived ingredients in the United States, while the EMA and EFSA jointly assess novel food and feed risks under EU regulatory frameworks, and China's NMPA and SAMR administer safety reviews for genetically modified organisms and novel food materials. These agencies shape market access timelines, labeling obligations, and cross-border trade flows for biotech food products. Stakeholders must monitor evolving gene-editing classifications across jurisdictions to anticipate compliance costs and commercialization pathways.
Market Dynamics
Precision fermentation scale-up is compressing production timelines for alternative proteins and functional enzymes, forcing incumbent suppliers to reconfigure bioreactor networks or surrender margin to agile contract manufacturers.
Growth Catalysts
- CRISPR-Cas9 regulatory clarity:The FDA's streamlined gene-edited food review pathway accelerates product development cycles for trait-enhanced crops in the United States.
- Clean-label enzyme demand:Bakery and dairy processors replace chemical additives with fermentation-derived enzymes to meet retailer certification requirements.
- Brazil's biotech crop expansion:Soybean and corn hectares under genetically modified cultivation drive sustained demand for stacked-trait seeds and companion agbiotech inputs.
Market Restraints
- Input cost volatility:Sugar feedstock prices for precision fermentation fluctuate with Brazilian ethanol policy shifts, squeezing contract manufacturer margins.
- Supply concentration risk:Industrial enzyme production clusters in Denmark and the Netherlands create geographic vulnerability to energy price shocks.
- Regulatory friction:EFSA's novel food classification delays for gene-edited ingredients block European market entry for CRISPR-derived products.
Strategic Opportunities
- Underpenetrated geography:India's FSSAI novel food framework revision opens pathways for fermented alternative proteins in urban consumer markets.
- Technology convergence:AI-driven strain optimization combined with automated bioreactor control slashes development cycles for specialty enzymes.
- Regulatory tailwind:China's dual carbon goals incentivize precision fermentation as a lower-emission protein production pathway versus conventional agriculture.
Industry Challenges
- Bioprocess engineering talent scarcity:Fermentation scale-up expertise concentrates in legacy pharma hubs, forcing food biotech firms to poach or train.
- Capex intensity:Commercial-grade bioreactor installations demand 50,000+ liter stainless-steel infrastructure with multi-year depreciation horizons.
- IP licensing complexity:CRISPR patent thickets involving Broad Institute and Corteva Agriscience complicate freedom-to-operate for gene-edited food traits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Food Biotechnology Market |
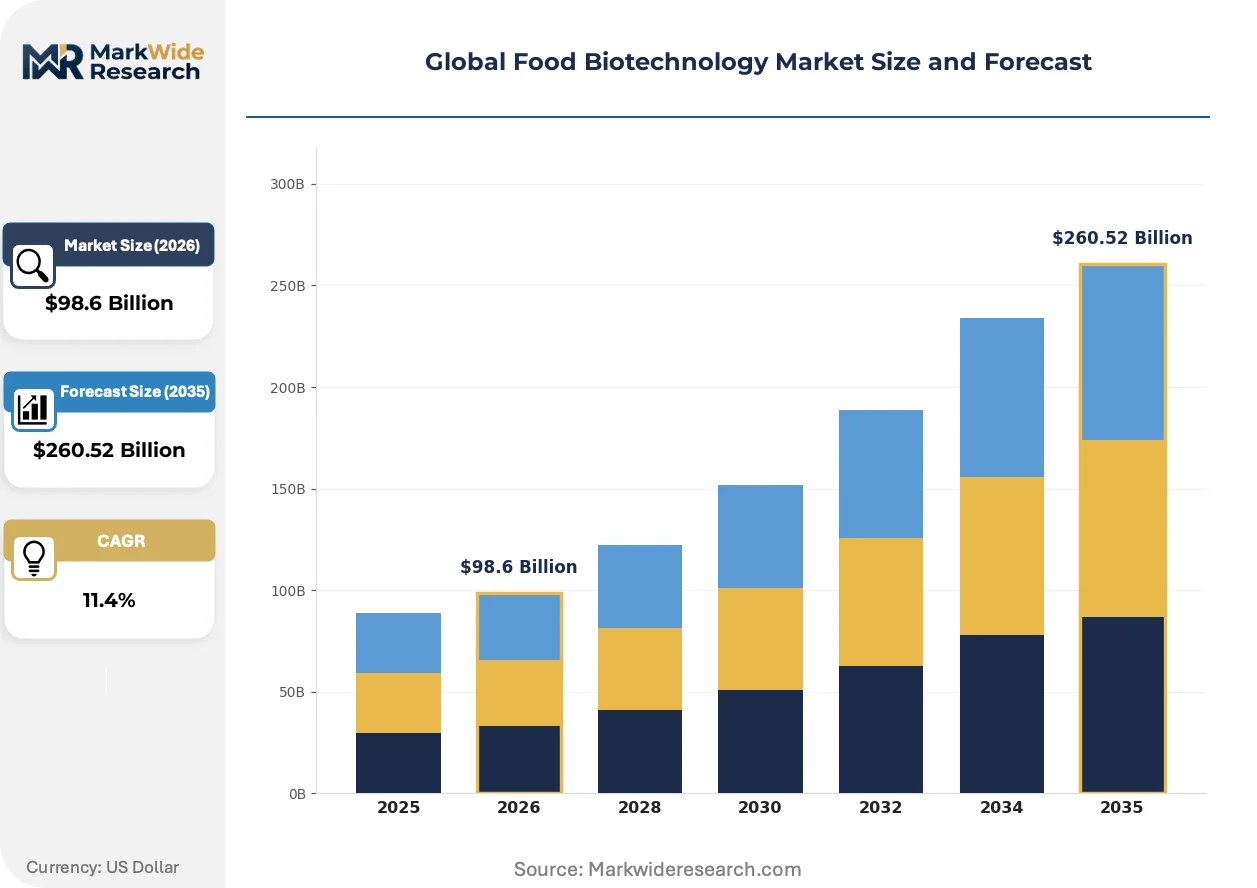
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $260.52 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Genetically Modified Organisms, Enzymes, Biopesticides, Biofertilizers Application: Crop Improvement, Food Processing, Animal Feed, Waste Management End User: Agriculture, Food Industry, Research Institutions, Biotechnology Firms Technology: Crispr-Cas9, Recombinant DNA, Fermentation, Tissue Culture |
| Companies Covered | BASF SE, Bayer CropScience AG, Syngenta AG, Corteva Agriscience, Dow AgroSciences LLC, AquaBounty Technologies, ABS Global, Arcadia Biosciences, Camson Bio Technologies Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Food Biotechnology Market Emerging Trajectories
Biomanufacturing hardware and computational biology are converging to compress R&D-to-commercial timelines, while regulatory heterogeneity forces parallel compliance strategies across major markets.
Single-use bioreactor systems for precision fermentation are miniaturizing downstream processing footprints. Alternative protein startups deploy 2,000-liter disposable vessels for pilot-scale validation before committing to stainless-steel infrastructure. This modular approach is miniaturizing capital barriers for new market entrants, fragmenting production geography away from legacy fermentation clusters.
REACH chemical registration requirements for novel enzyme formulations tighten purity documentation obligations for European suppliers. Industrial biotech firms must submit extended toxicity dossiers for fermentation byproducts previously exempt under grandfathered approvals. Bakery enzyme suppliers face reformulation pressure to eliminate residual host-cell proteins triggering new EFSA scrutiny.
Direct-to-manufacturer ingredient sourcing is displacing traditional distributor networks for high-value enzymes. Large food processors negotiate multi-year offtake agreements with fermentation specialists, bypassing regional chemical distributors. This channel compression is most visible in North American dairy and beverage sectors where CPG giants consolidate supplier panels to secure volume commitments.
Global Food Biotechnology Market Segmentation
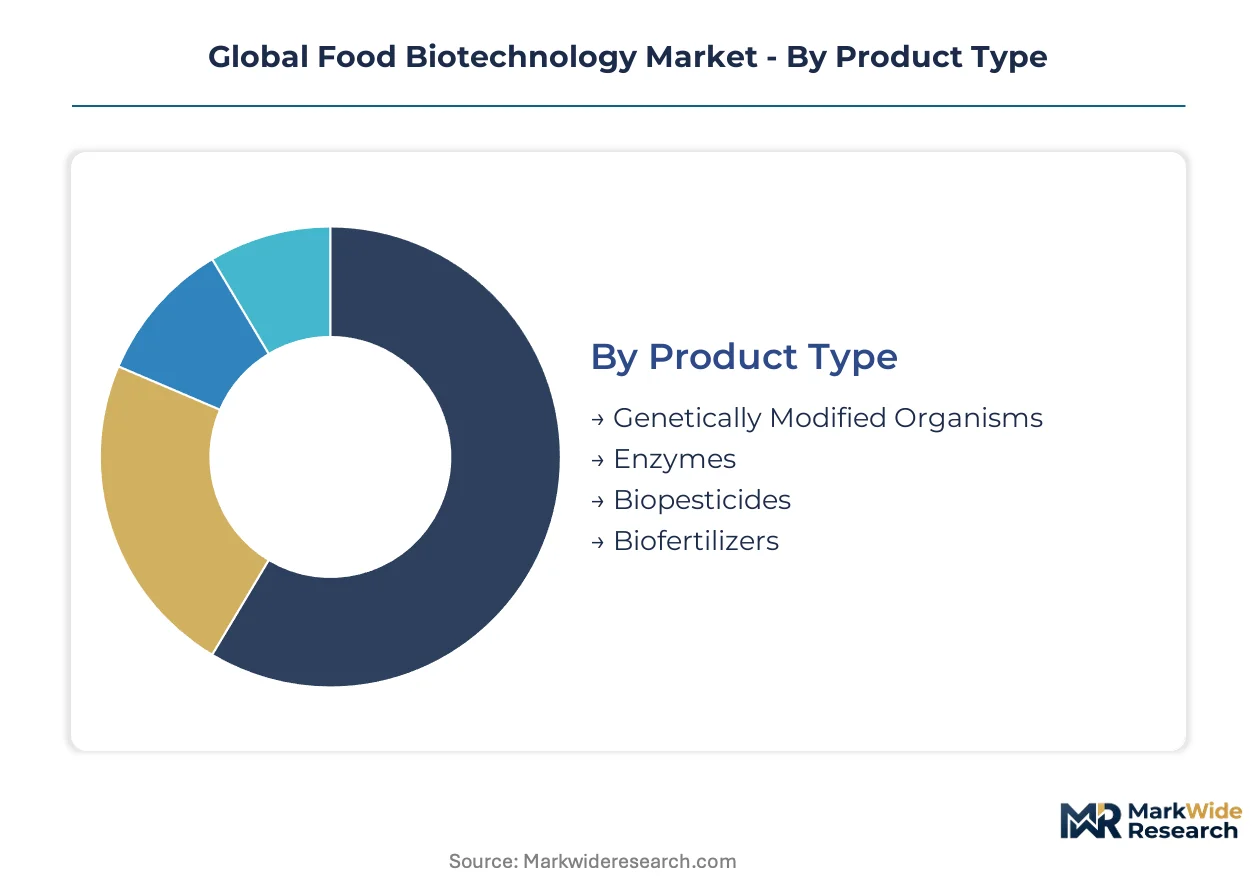
Segmentation in food biotechnology reveals distinct margin architectures across product types, applications, and enabling technologies. Each dimension carries unique regulatory exposure, capital intensity, and customer concentration patterns that reshape competitive strategy.
Product Type:
Premium margins concentrate in high-purity enzyme formulations where fermentation scale-up expertise creates defensible moats, while commodity-trait GMOs compete on volume and regulatory approval speed.
- Genetically Modified Organisms:Stacked-trait seeds for soy, corn, and cotton dominate planted hectares across Brazil, the United States, and Argentina. Bayer CropScience and Corteva Agriscience capture recurring revenue through trait licensing fees tied to seed sales, though EFSA's novel food classification delays erode European margin potential.
- Enzymes:Precision fermentation yields high-specificity proteases, lipases, and carbohydrases for clean-label bakery and dairy processing. Novozymes and DSM-Firmenich supply multi-ton quantities to CPG giants seeking GRAS-certified alternatives to chemical additives, with capacity clustering in Denmark and the Netherlands creating supply vulnerability.
- Biopesticides:Microbial and biochemical crop protection products target resistance management in integrated pest management programs.
- Biofertilizers:Nitrogen-fixing and phosphate-solubilizing microbial inoculants reduce synthetic fertilizer dependence in sustainable agriculture protocols.
The dominant share belongs to Genetically Modified Organisms, while Enzymes is closing the gap fastest as precision fermentation capacity expands.
Application:
Volume gravitates toward crop improvement where trait deployment scales across millions of hectares, yet food processing commands superior pricing power through direct manufacturer relationships.
- Crop Improvement:CRISPR-edited and transgenic traits enhance yield, drought tolerance, and pest resistance in row crops. Brazil's stacked-trait soybean expansion and China's biotech corn commercialization drive hectare growth, with seed companies monetizing through technology fees per bag.
- Food Processing:Enzymatic solutions replace chemical additives in starch modification, juice clarification, and dairy texture optimization. North American and European bakery processors negotiate multi-year offtake agreements with fermentation specialists, bypassing traditional distributor networks to secure volume commitments.
- Animal Feed:Phytase enzymes and amino acid-producing microbes improve feed conversion ratios in poultry and swine operations.
- Waste Management:Cellulolytic and ligninolytic enzyme systems convert agricultural residues to fermentable sugars for circular bioeconomy applications.
Crop Improvement holds the volume advantage, though Food Processing exhibits the steepest expansion trajectory as clean-label mandates proliferate.
End User:
Procurement sophistication varies sharply: agriculture buyers prioritize trait performance and regulatory approval breadth, while biotechnology firms value IP freedom-to-operate and strain optimization speed.
- Agriculture:Commercial farms and cooperatives adopt stacked-trait seeds and companion agbiotech inputs based on field efficacy and local regulatory acceptance. Brazilian and Argentine soybean producers represent concentrated demand for glyphosate-tolerant and insect-resistant traits.
- Food Industry:Multinational CPG manufacturers and regional processors source enzymes and fermented ingredients through consolidated supplier panels. Direct-to-manufacturer contracting displaces distributor intermediaries for high-value bakery and dairy applications.
- Research Institutions:Universities and government laboratories license CRISPR tools and germplasm for trait discovery and regulatory science.
- Biotechnology Firms:Precision fermentation startups and gene-editing companies develop proprietary strains and seek regulatory approvals for novel food ingredients.
Agriculture commands the largest procurement volume, with Food Industry gaining share fastest as ingredient sourcing consolidates.
Technology:
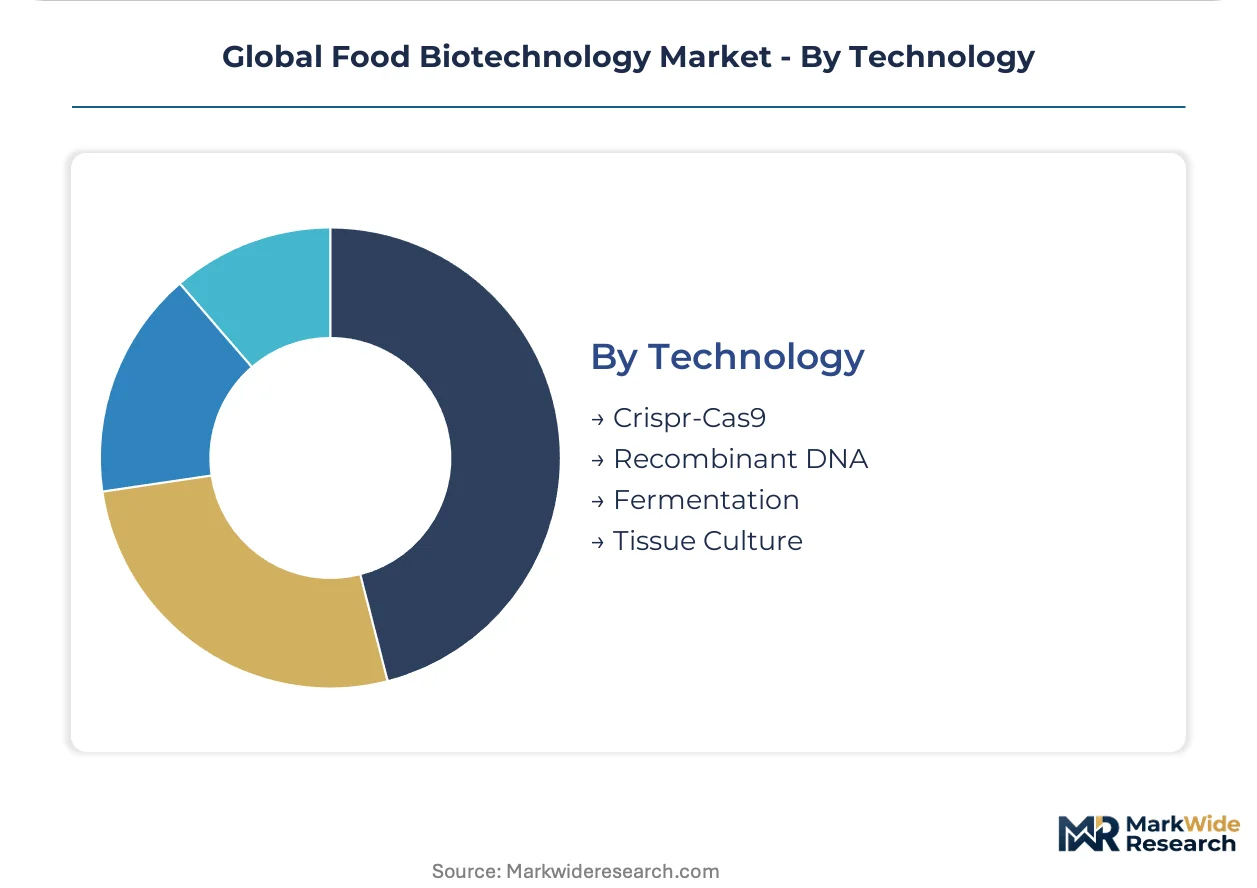
R&D investment intensity peaks in gene-editing platforms where patent thickets and regulatory heterogeneity create competitive barriers, while mature recombinant DNA technologies offer predictable approval pathways.
- CRISPR-Cas9:Site-directed nuclease systems enable precise trait editing without transgene insertion, triggering divergent regulatory treatment across jurisdictions. The FDA's streamlined review pathway accelerates U.S. commercialization, while EFSA's novel food classification blocks European market entry for gene-edited products.
- Recombinant DNA:Plasmid-based gene transfer underpins commercialized GMO traits in oilseeds, grains, and specialty crops. Decades of regulatory precedent in the United States, Brazil, and Canada provide approval predictability, though consumer resistance persists in certain European and Asian markets.
- Fermentation:Microbial cell factories produce enzymes, alternative proteins, and functional ingredients at pilot through commercial scale.
- Tissue Culture:Micropropagation and somatic embryogenesis accelerate breeding cycles for vegetatively propagated crops.
Recombinant DNA retains commercial dominance, yet CRISPR-Cas9 is climbing fastest as regulatory clarity emerges in major cultivation markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in food biotechnology ingredients concentrate in jurisdictions with divergent regulatory postures toward gene-edited crops and precision fermentation outputs. Nations with streamlined approval pathways attract biomanufacturing investment, while restrictive markets depend on cross-border enzyme and trait shipments.
United States
Stacked-trait corn and soybean cultivation drives sustained demand for agbiotech inputs across the Corn Belt and Delta regions. FDA's streamlined gene-edited food review pathway accelerates commercialization timelines for CRISPR-derived products. Greater Boston and Research Triangle Park host precision fermentation startups scaling alternative protein production.
Brazil
Expanding genetically modified soybean and corn hectares underpin global seed-and-trait demand, with farmers adopting glyphosate-tolerant and insect-resistant varieties. ANVISA coordinates with MAPA on novel food safety assessments for biotech-derived ingredients. São Paulo state's Ribeirão Preto cluster anchors industrial enzyme manufacturing for Latin American food processors.
China
Biotech corn commercialization and precision fermentation scale-up align with national food security and dual carbon policy objectives. NMPA and SAMR administer safety reviews for genetically modified organisms and novel food materials. Yangtze River Delta biomanufacturing hubs expand stainless-steel bioreactor capacity for alternative protein production.
Germany
Clean-label enzyme demand from bakery and dairy processors sustains fermentation-derived ingredient imports despite domestic regulatory constraints. EFSA's novel food classification delays constrain CRISPR-derived product development, pushing R&D investment toward recombinant DNA platforms. North Rhine-Westphalia's industrial biotech corridor maintains enzyme purification and formulation expertise.
India
FSSAI novel food framework revision opens pathways for fermented alternative proteins targeting urban consumer markets. Phytase enzyme adoption in poultry feed improves conversion ratios across Andhra Pradesh and Telangana operations. Karnataka's Bengaluru biotech cluster attracts contract fermentation capacity for export-oriented ingredient manufacturing.
Global Food Biotechnology Market Vendor Landscape
Listed leaders compete with private specialists across trait licensing and enzyme supply dimensions. Consolidation around integrated seed-and-trait platforms coexists with fragmentation in precision fermentation services. Three archetypes dominate: diversified chemical conglomerates with fermentation expertise, crop science majors with stacked-trait portfolios, and agile biomanufacturing specialists. Competitive moves center on capacity expansion in alternative protein fermentation and strategic partnerships for gene-editing IP access.
Within the diversified conglomerate tier, BASF SE and Bayer CropScience AG exemplify scale-driven positions spanning industrial enzymes through agricultural biotechnology. Syngenta AG occupies a specialist position in crop protection and seed platforms. These entities anchor competitive dynamics through integrated supply chains and recurring technology fee structures rather than transactional ingredient sales.
| Leading Market Players |
|---|
| BASF SE |
| Bayer CropScience AG |
| Syngenta AG |
| Corteva Agriscience |
| Dow AgroSciences LLC |
| AquaBounty Technologies |
| ABS Global |
| Arcadia Biosciences |
| Camson Bio Technologies Ltd |
| Others |
Supply Flow & Price Mechanics
Precision fermentation scale-up is displacing chemical synthesis routes for high-purity enzymes, simultaneously pulling production geography toward Denmark and the Netherlands while compressing margins for legacy suppliers unable to retrofit stainless-steel infrastructure.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake agreements for fermentation-derived enzymes, with pricing stratifies across premium GRAS-certified, standard food-grade, and economy technical-grade tiers. Price differentiation hinges on certification level — FDA GRAS versus EFSA novel food approval — and volume scale commitments above 100-ton annual volumes. Pricing pressure stems from Brazilian sugar feedstock volatility linked to ethanol policy shifts, squeezing contract manufacturer margins. Multinational CPG manufacturers exhibit lowest price sensitivity due to clean-label mandates, while regional bakery processors face acute cost compression.
Supply Chain Analysis
Strategic stockpile preferences dominate enzyme procurement as food processors buffer against Danish and Dutch supply concentration risks. Geographic supply centers on Denmark, the Netherlands, and China's Yangtze River Delta biomanufacturing hubs. Raw material dependencies include glucose syrup, yeast extract, and specialty nitrogen sources for fermentation media. Single-source vulnerability concentrates in industrial enzyme purification capacity clustered around Copenhagen and Delft. Distribution runs through direct-to-manufacturer channels displacing traditional chemical distributors for high-value bakery and dairy applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as multinational CPG manufacturers consolidate supplier panels and negotiate multi-year offtake agreements, fragmenting pricing leverage among smaller regional processors.
For Market Incumbents: Compound fermentation capacity advantages by securing captive glucose supply contracts with Brazilian ethanol producers and accelerating GRAS self-determination filings for novel enzyme formulations. Defensive positioning requires backward integration into feedstock sourcing to buffer sugar price volatility threatening contract manufacturer margins. For New Entrants and Emerging Players: Contract fermentation services for precision protein production represent the most penetrable white-space as legacy pharma CDMOs under-serve food-grade requirements. Target India's FSSAI novel food pathway revision for fermented alternative protein commercialization. Go-to-market execution should emphasize modular single-use bioreactor deployments minimizing capital barriers. For Investors and Strategic Acquirers: Capital is best deployed toward precision fermentation specialists with demonstrated strain optimization platforms and regulatory submission track records across FDA and EFSA jurisdictions. Long-term viability favors entities with freedom-to-operate clearance in CRISPR patent thickets. Monitor EFSA gene-edited food classification decisions as inflection signal for European market access timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Alternative protein production in Yangtze River Delta hubs aligns with China's dual carbon policy objectives. |
| GRAS Self-Determination Filing | FDA pathway acceleration reduces commercialization timelines for novel enzyme formulations in bakery applications. |
| Backward Integration into Feedstock | Captive glucose supply from Brazilian ethanol producers buffers sugar price volatility squeezing margins. |
| Single-Use Bioreactor Deployment | Modular 2,000-liter vessels fragment production geography away from legacy Danish fermentation clusters. |
| EFSA Novel Food Submission | European regulatory approval unlocks enzyme sales to clean-label dairy processors facing REACH compliance pressure. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with fermentation process engineers, regulatory affairs directors at enzyme suppliers, procurement leads at multinational CPG manufacturers, and contract manufacturing officers; alongside secondary validation through FDA GRAS notifications, EFSA novel food opinions, Brazilian ANVISA safety assessments, Chinese SAMR GMO approvals, and customs trade data on enzyme imports. Bottom-up capacity modeling triangulated against top-down expenditure estimates from disclosed bioreactor installation projects.
Across the projection horizon, the analytical framework modeled volume and value trajectories by product type — genetically modified organisms, enzymes, biopesticides, biofertilizers — application segment, end-user procurement sophistication tier, and enabling technology platform. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Industry-specific forecast inputs included precision fermentation capacity buildout timelines and CRISPR regulatory classification shifts across FDA, EFSA, and NMPA jurisdictions.
Underlying assumptions cover sustained Brazilian biotech crop expansion, Chinese biotech corn commercialization acceleration, and EFSA gene-edited food pathway clarification, with deviation risk concentrated in sugar feedstock price volatility and European regulatory friction blocking CRISPR-derived product entry. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Biotechnology
Non-Animal Alternative Testing Market
Food Biotechnology
Carbohydrate Enzyme Preparation Market
Food Biotechnology
Cultured Meat Market
Food Biotechnology
Microalgae Market
Food Biotechnology
Biotech Flavors Market
Food Biotechnology
Biopreservation Market
Food Biotechnology
Global Feed Enzymes Market
Food Biotechnology
Bangladesh Starch and Starch Derivative Market
Food Biotechnology
Genistein Market
Food Biotechnology
Prebiotics Market
Food Biotechnology
Research-Grade Proteins Market
Food Biotechnology
Pullulanase Market
Food Biotechnology
Flaxseed Gum Market
Food Biotechnology
Brown Algae Protein Market
Food Biotechnology
Hemoglobin Feed Market
Food Biotechnology
Colostrum Market