
 China VNA and PACS Market | 2026-2036
China VNA and PACS Market Size, Share, and Industry Trends Forecast 2026-2036
China VNA and PACS Market Intelligence
Subscription-based software-defined archiving is pivoting how vendors monetize storage capacity in China's hospital networks. Neusoft Corporation leverages its domestic R&D footprint to anchor cloud-native VNA deployments across provincial health systems. GE Healthcare competes through in-house production of AI-enhanced workflow engines that integrate with existing hospital information systems. Fujifilm differentiates by specializing in hybrid architectures that bridge legacy on-premise PACS with municipal cloud nodes.
Vendor Neutral Archive and Picture Archiving and Communication System denote medical informatics systems that manage DICOM and non-DICOM imaging data across heterogeneous clinical environments, typically supporting storage capacities exceeding petabyte scale with sub-second retrieval latency for diagnostic workstations. Their primary purpose centers on eliminating proprietary data silos while enabling longitudinal patient imaging records across multi-site health networks. Enterprise Imaging Platform solutions currently lead margin pools as hospitals consolidate radiology, cardiology, and pathology workflows onto unified architectures. Cloud-Based deployment represents the fastest-expanding segment, though On-Premise systems still dominate transaction volume among county-level hospitals with constrained IT budgets.
NMPA cybersecurity guidelines for medical device software, MIIT cloud service classification requirements, and GB/T health data interoperability standards collectively shape product certification timelines and procurement eligibility across provincial tenders. SAMR pricing oversight on public hospital capital expenditures further constrains vendor pricing flexibility, particularly for imported systems subject to foreign exchange volatility. Stakeholders must monitor how municipal health commissions weight domestic versus foreign supplier quotas in upcoming integrated platform tenders.
Market Dynamics
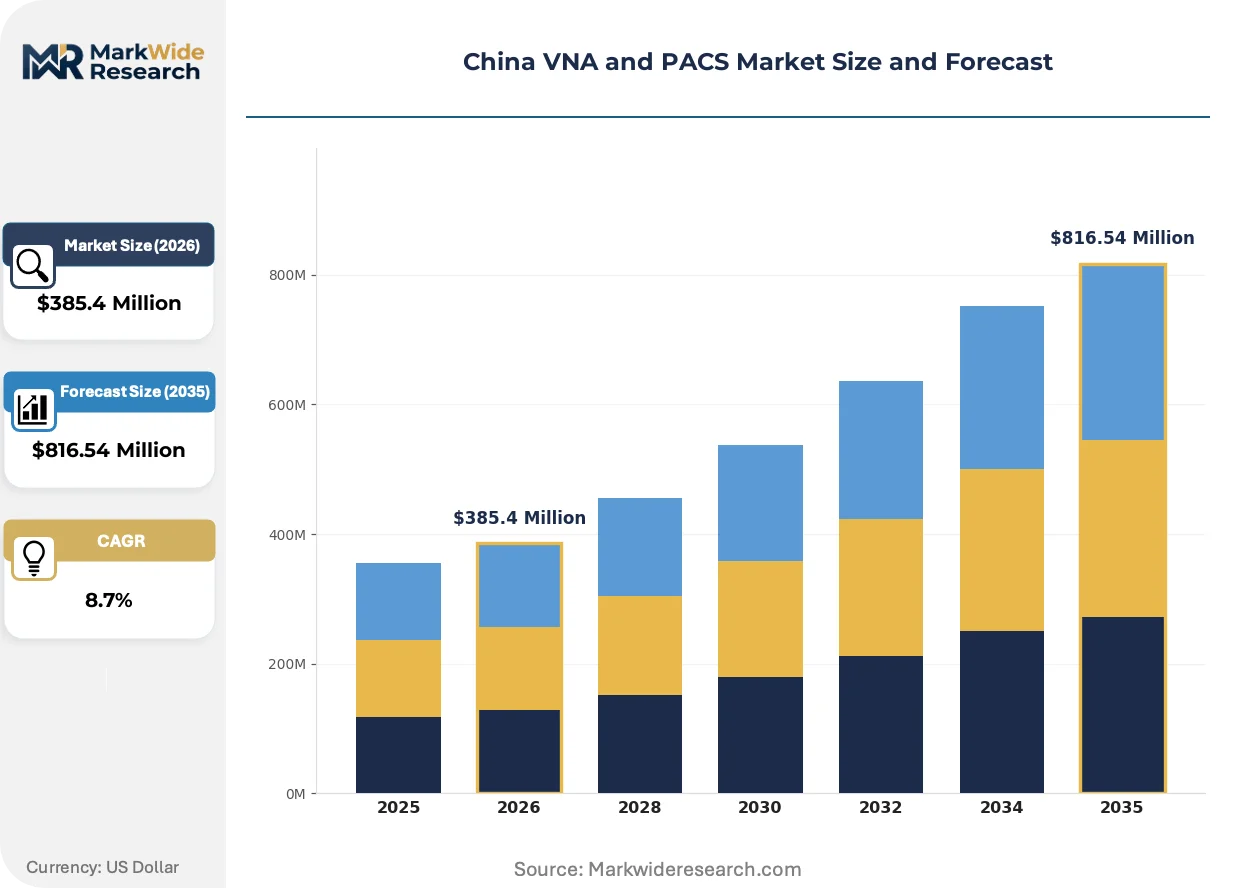
Cloud-native enterprise imaging platforms are compressing procurement cycles across China's provincial health systems as municipal commissions consolidate radiology, cardiology, and pathology workflows onto unified architectures. This infrastructure consolidation is redrawing competitive boundaries between domestic R&D specialists and multinational workflow engine providers.
Growth Catalysts
- NMPA Interoperability Mandates:Tier-three hospitals in Sichuan and Hunan provinces face accelerated compliance deadlines for cross-facility imaging data exchange, forcing wholesale platform upgrades.
- MIIT Cloud Service Classification:Standardized certification pathways for medical data hosting services have reduced vendor qualification timelines from 18 to 9 months in Yangtze River Delta municipalities.
- Enterprise Imaging Consolidation:Hospital groups are unifying departmental silos onto single VNA backbones to eliminate redundant storage infrastructure and enable longitudinal patient records.
Market Restraints
- Imported System Foreign Exchange Exposure:SAMR pricing oversight caps capital expenditure flexibility for hospitals purchasing foreign-denominated imaging platforms, compressing vendor margins on cross-border transactions.
- County-Level IT Budget Constraints:On-premise PACS systems still dominate transaction volume among rural hospitals lacking dedicated cloud infrastructure teams or fiber connectivity.
- Legacy DICOM Format Lock-In:Proprietary compression algorithms from incumbent PACS vendors create data migration friction that delays enterprise archive deployments by 6-14 months.
Strategic Opportunities
- Hybrid Architecture Penetration:Bridge solutions connecting on-premise departmental PACS with municipal cloud nodes address the 40% of tier-two hospitals requiring staged migration paths.
- Pathology Workflow Integration:Whole-slide imaging convergence with radiology archives opens margin pools in oncology centers seeking unified diagnostic workstations.
- GB/T Health Data Standards Alignment:Domestic vendors certifying early against revised interoperability protocols gain preferential scoring in provincial tender evaluations.
Industry Challenges
- DICOM-Non-DICOM Harmonization:Cardiology cine loops, ophthalmology OCT volumes, and dermatology photography lack standardized metadata schemas, forcing custom integration engineering for each deployment.
- Sub-Second Retrieval Engineering:Diagnostic workstation latency requirements below 500 milliseconds demand edge caching architectures that strain hospital network engineering capacity.
- Cross-Province Data Sovereignty:Municipal health commissions impose conflicting data residency rules that fragment cloud archive architectures across provincial borders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China VNA and PACS Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $816.54 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing Solution Offering: Vendor Neutral Archive, Picture Archiving and Communication System, Radiology Information System, Enterprise Imaging Platform End User Type: Hospitals, Diagnostic Centers, Specialty Clinics, Telemedicine Providers, Research Institutions Application Area: Medical Imaging Storage, Workflow Integration, Data Analytics, Remote Collaboration, Clinical Decision Support |
| Companies Covered | Beijing Tianjian Source Technology Co. Ltd., Shenzhen Mindray Bio-Medical Electronics Co. Ltd., Neusoft Corporation, Carestream, Winning Health Technology Group Co., Xi'an Huahai Medical Info-Tech Co. Ltd., GE Healthcare, Fujifilm, EBM Technologies Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China VNA and PACS Market Strategic Shifts & Innovations
Artificial intelligence inference engines are embedding directly into imaging workflow orchestration layers, shifting value capture from storage capacity toward real-time diagnostic assistance. This architectural pivot favors vendors with in-house AI training pipelines over pure infrastructure providers.
AI-enhanced workflow engines are integrating predictive study routing and automated hanging-protocol selection into diagnostic workstations. Tier-three hospitals in Shanghai and Hangzhou are deploying these capabilities at pilot scale, with procurement committees mandating native AI integration in 60% of new enterprise platform tenders. The technology is integrating radiologist efficiency metrics directly into hospital performance dashboards, compressing report turnaround time from hours to minutes for emergency stroke protocols.
NMPA cybersecurity guidelines for medical device software now require penetration testing documentation and source code audit trails for cloud-connected imaging platforms. Manufacturers must submit updated technical files demonstrating encryption-at-rest and role-based access controls, extending product certification timelines by 4-6 months. Imported systems face additional scrutiny under MIIT data localization requirements, prompting some vendors to establish domestic hosting partnerships.
Subscription-based capacity pricing is displacing perpetual license models for archive storage, with municipal health commissions favoring operational expenditure treatment over capital budget allocation. Software-defined storage pools allow hospitals to scale petabyte-class repositories without hardware procurement cycles. County-level facilities in western provinces lag this transition, maintaining capital-intensive on-premise deployments due to constrained IT staffing and unpredictable network reliability.
China VNA and PACS Market Segmentation
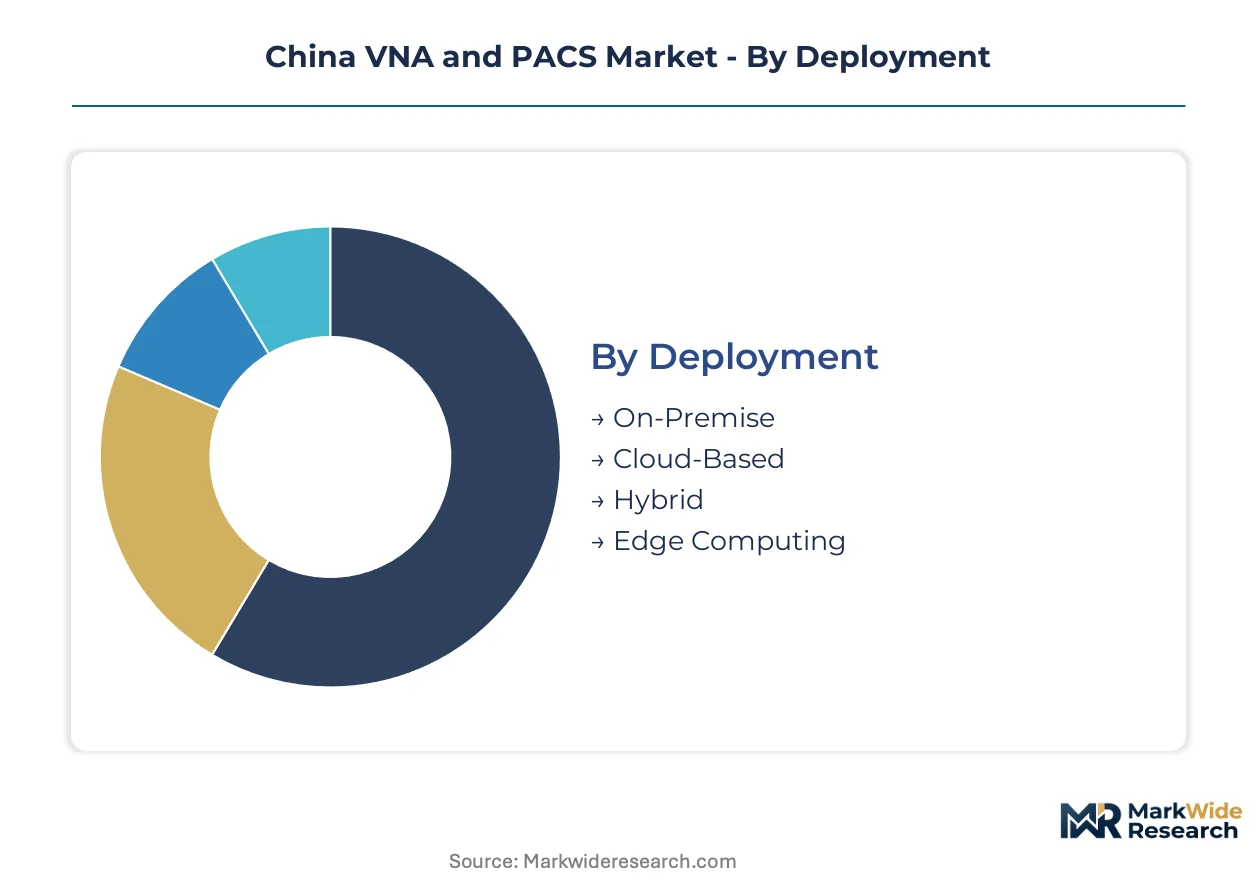
Procurement patterns across China's hospital networks diverge sharply by infrastructure maturity and regulatory compliance timelines. Understanding these segment boundaries clarifies where domestic vendors capture volume versus where multinational workflow specialists defend premium positioning.
Deployment:
Upgrade cycles vary dramatically by facility IT staffing depth and fiber connectivity reliability, creating a four-way split in infrastructure procurement.
- On-Premise:Hardware-anchored installations with dedicated server rooms and local storage arrays dominate county-level hospitals in western provinces lacking reliable broadband. These deployments face compressed margins under SAMR capital expenditure oversight.
- Cloud-Based:Municipal health commissions in Shanghai and Hangzhou prioritize subscription models that shift imaging archives from capital to operational budgets. MIIT cloud service classification requirements have streamlined vendor qualification, accelerating tender participation.
- Hybrid:Bridge architectures connecting departmental PACS with municipal cloud nodes address tier-two hospitals requiring staged migration without workflow disruption.
- Edge Computing:Distributed caching nodes positioned within hospital networks deliver sub-second retrieval latency for diagnostic workstations in stroke centers and emergency departments.
Volume placements concentrate in On-Premise systems; the faster expansion belongs to Cloud-Based deployment.
Solution Offering:
Margin pools align with workflow integration depth, from standalone storage repositories to unified diagnostic platforms spanning multiple specialties.
- Vendor Neutral Archive:Centralized DICOM and non-DICOM repositories eliminating proprietary data silos across multi-site networks. Provincial health systems in Sichuan and Hunan mandate VNA backbones for NMPA interoperability compliance.
- Picture Archiving and Communication System:Departmental imaging workstations with hanging-protocol automation and study routing. Legacy PACS installations create data migration friction that delays enterprise archive replacements.
- Radiology Information System:Order management and report distribution modules integrating with hospital information systems. These solutions face margin pressure from bundled enterprise platform tenders.
- Enterprise Imaging Platform:Unified architectures consolidating radiology, cardiology, and pathology workflows onto single VNA infrastructures. Tier-three hospitals lead procurement as they eliminate redundant storage systems.
Revenue concentration sits with Enterprise Imaging Platform deployments; Vendor Neutral Archive captures the steepest expansion trajectory as provincial mandates force infrastructure consolidation.
End User Type:
Budget authority and procurement complexity fragment demand across five distinct organizational categories with diverging technical requirements.
- Hospitals:Tier-three public facilities drive petabyte-scale archive procurement with sub-second latency requirements for diagnostic workstations. Municipal health commissions in the Yangtze River Delta consolidate purchasing across hospital groups.
- Diagnostic Centers:High-volume imaging facilities prioritize throughput optimization and automated study routing over deep storage capacity.
- Specialty Clinics:Cardiology and ophthalmology practices require specialized handling for cine loops and OCT volumes lacking standardized metadata schemas.
- Telemedicine Providers:Remote consultation platforms demand low-bandwidth image compression and mobile-optimized viewer applications.
- Research Institutions:Academic medical centers prioritize long-term longitudinal datasets and integration with clinical trial management systems.
Transaction value clusters in Hospitals; Specialty Clinics are expanding most quickly as oncology and cardiology centers digitize diagnostic workflows.
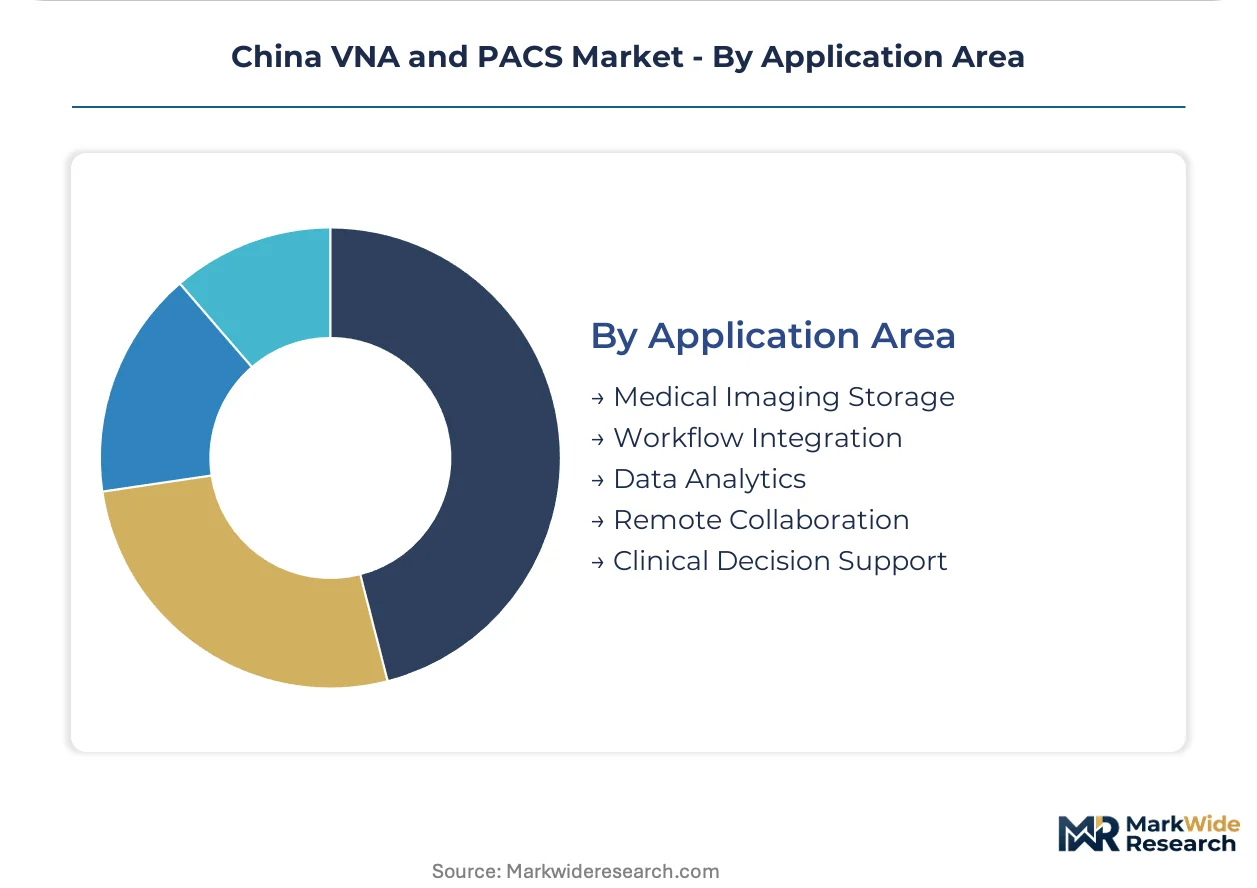
Application Area:
Functional requirements stratify by clinical urgency and data processing sophistication, from passive storage to real-time decision assistance.
- Medical Imaging Storage:Petabyte-class repositories with encryption-at-rest and role-based access controls meeting NMPA cybersecurity guidelines. Certification timelines extend 4-6 months for cloud-connected platforms.
- Workflow Integration:AI-enhanced study routing and automated hanging-protocol selection compress radiologist report turnaround times. Shanghai pilot deployments demonstrate minute-level emergency stroke protocol completion.
- Data Analytics:Population health dashboards and operational efficiency metrics derived from imaging metadata. These capabilities remain underdeveloped outside tier-one municipal networks.
- Remote Collaboration:Multi-site consultation platforms enabling cross-facility diagnostic review. Conflicting provincial data residency rules fragment cloud archive architectures.
- Clinical Decision Support:Embedded AI inference engines providing real-time diagnostic assistance at the point of care. NMPA medical device software regulations require penetration testing documentation and source code audit trails.
Current procurement emphasizes Medical Imaging Storage; Clinical Decision Support is gaining share fastest as AI integration becomes mandatory in enterprise platform tenders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of VNA and PACS infrastructure concentrates in eastern coastal manufacturing zones, while consumption spreads across provincial health systems responding to NMPA interoperability mandates. Domestic R&D centers anchor cloud-native platform development, with deployment demand fragmenting across tiered hospital networks.
Yangtze River Delta
Shanghai and Hangzhou municipal health commissions prioritize cloud-based enterprise imaging consolidation across hospital groups. MIIT cloud service classification requirements have streamlined vendor qualification timelines, accelerating procurement of subscription-archiving platforms. The region hosts the country's densest concentration of tier-three facilities deploying AI-enhanced diagnostic workstations.
Sichuan-Chongqing
Tier-three public hospitals in Sichuan province face compressed compliance deadlines for cross-facility imaging data exchange under NMPA interoperability mandates. Provincial health systems accelerate wholesale platform upgrades to eliminate proprietary data silos. Chengdu anchors western China's largest concentration of enterprise VNA backbone deployments.
Hunan Province
Changsha-based hospital groups consolidate radiology, cardiology, and pathology workflows onto unified architectures to meet accelerated NMPA deadlines. SAMR pricing oversight constrains capital expenditure flexibility for imported systems, favoring domestic vendor participation in provincial tenders. The province leads central China in hybrid architecture adoption bridging on-premise PACS with municipal cloud nodes.
Beijing-Tianjin-Hebei
Research institutions and academic medical centers in Beijing prioritize long-term longitudinal imaging datasets and clinical trial integration capabilities. NMPA cybersecurity guidelines requiring penetration testing documentation extend certification timelines for cloud-connected platforms. The capital region concentrates national regulatory expertise shaping GB/T health data interoperability standards.
Shandong Peninsula
County-level hospitals across Shandong maintain on-premise PACS dominance due to constrained IT staffing and fiber connectivity gaps. SAMR capital expenditure oversight compresses margins for hardware-anchored installations. Jinan and Qingdao municipal networks pilot edge computing nodes delivering sub-second retrieval latency for emergency stroke protocols.
China VNA and PACS Market Key Industry Players
Capital-heavy infrastructure producers compete with asset-light workflow software designers for margin capture in China's hospital procurement. The market structure fragments across multinational medical technology conglomerates, diversified domestic conglomerates, and specialized medical informatics developers. Three strategic archetypes dominate: domestic R&D specialists leveraging local certification advantages, multinational workflow engine providers integrating AI capabilities, and hybrid architecture specialists bridging legacy and cloud deployments. Competitive moves concentrate on strategic partnerships with municipal health commissions and portfolio diversification into pathology workflow integration.
Among domestic R&D specialists, Neusoft Corporation anchors cloud-native VNA deployments across provincial health systems. GE Healthcare exemplifies the multinational workflow engine archetype competing through in-house AI production. Fujifilm occupies a position specializing in hybrid architectures that connect legacy on-premise PACS with municipal cloud nodes.
| Leading Market Players |
|---|
| Beijing Tianjian Source Technology Co. Ltd. |
| Shenzhen Mindray Bio-Medical Electronics Co. Ltd. |
| Neusoft Corporation |
| Carestream |
| Winning Health Technology Group Co. |
| Xi'an Huahai Medical Info-Tech Co. Ltd. |
| GE Healthcare |
| Fujifilm |
| EBM Technologies Inc. |
| Others |
Cost & Logistics Intelligence
NMPA cybersecurity guidelines for medical device software gate qualified supply access and premium-tier pricing eligibility for cloud-connected imaging platforms. SAMR pricing oversight on public hospital capital expenditures compresses vendor margins while MIIT cloud service classification requirements extend certification timelines, reshaping how domestic and foreign suppliers compete in provincial tenders.
Pricing Analysis
Cost compression in county-level facilities accelerates as on-premise PACS deployments face SAMR capital expenditure caps and constrained IT budgets. Subscription-based SaaS-tiered pricing dominates municipal health commissions in Shanghai and Hangzhou, with premium-mid-economy pricing differentiation separating AI-enhanced enterprise platforms from basic archive storage. Price differentiation traces to NMPA certification grade and after-sales service bundling. Pricing pressure intensifies in tier-three hospitals as domestic vendors leverage GB/T standards alignment to undercut imported systems. County-level buyers exhibit highest price sensitivity; tier-three facilities with NMPA compliance deadlines show lowest.
Supply Chain Analysis
Software engineering talent availability in Beijing, Shanghai, and Hangzhou anchors cloud-native platform development for enterprise imaging systems. Hardware component sourcing draws from domestic server manufacturers and Taiwan-based semiconductor suppliers for edge computing nodes. Raw material dependencies include enterprise-grade storage arrays, fiber optic infrastructure, and AI accelerator chips. Supply chain risk centers on single-source vulnerability for specialized DICOM compression algorithms from legacy PACS vendors. Distribution runs through municipal health commission consolidated tenders and provincial hospital group procurement frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's VNA and PACS market functions as a vertical-integration race where control over AI training pipelines and cloud infrastructure determines margin capture. Players are pursuing downstream lever dominance through pathology workflow integration and municipal health commission partnerships.
For Market Incumbents: Deploy hybrid architecture engineering to bridge legacy on-premise PACS with municipal cloud nodes, defending against pure-cloud domestic specialists. Incumbents should deepen backward integration into AI inference engine production to offset margin compression from SAMR pricing oversight. Certification investment in revised GB/T health data interoperability protocols secures preferential tender scoring against emerging entrants lacking regulatory track records. For New Entrants and Emerging Players: The price-point gap between premium AI-enhanced enterprise platforms and economy-tier on-premise archives creates entry space for tier-two hospitals requiring staged migration paths. White-space targets include Sichuan and Hunan provincial health systems facing compressed NMPA compliance deadlines. Pathology workflow integration offers the most penetrable application area as oncology centers digitize diagnostic workflows. A go-to-market angle anchored to MIIT cloud service classification pre-certification accelerates vendor qualification timelines. For Investors and Strategic Acquirers: Provincial tender announcements mandating native AI integration in enterprise platform specifications are the leading indicator that workflow engine capabilities are consolidating market power. Long-term viability across the projection horizon favors vendors with captive cloud infrastructure and in-house AI production rather than pure storage providers. Acquisition target archetypes include hybrid architecture specialists with proven municipal health commission relationships. The signal to watch is NMPA cybersecurity guideline enforcement intensity affecting imported system market access.| Strategic Initiative | Industry Significance |
|---|---|
| Pathology Workflow Integration | Whole-slide imaging convergence with radiology archives opens margin pools in oncology centers. |
| GB/T Standards Early Certification | Domestic vendors certifying against revised interoperability protocols gain preferential provincial tender scoring. |
| AI Inference Engine Development | In-house AI training pipelines shift value capture from storage capacity toward real-time diagnostic assistance. |
| Municipal Cloud Node Partnership | MIIT cloud service classification requirements streamline vendor qualification in Yangtze River Delta municipalities. |
| Edge Computing Infrastructure Deployment | Sub-second retrieval latency for stroke centers demands distributed caching nodes within hospital networks. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with hospital purchasing committee members, biomedical engineers, municipal health commission IT directors, and GPO contracts managers combined with NMPA device registration databases, MIIT cloud service classification records, and provincial tender announcement archives. Bottom-up facility-level procurement tracking and top-down health system expenditure modeling provided triangulation across data streams.
Data-stream reconciliation across deployment mode, solution offering tier, hospital classification, and application area dimensions shaped the analytical framework. CAGRs were derived from trend extrapolation anchored to documented procurement cycles and regulatory compliance timelines. Forecast inputs included NMPA interoperability mandate enforcement schedules, MIIT cloud certification pipeline velocity, and provincial health system consolidation patterns.
Inputs from NMPA registration databases and municipal tender archives were available through the study window; gaps in county-level hospital IT expenditure reporting introduce uncertainty bands around on-premise PACS volume estimates. Forecasts reflect assumptions regarding SAMR pricing oversight continuity and fiber connectivity expansion in western provinces. Material deviation in NMPA cybersecurity guideline enforcement intensity or MIIT data localization requirement scope warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
China Digital Radiology Market
Medical Imaging
Canada Mammography Market
Medical Imaging
Digital Pathology Scanner Calibration and Image Quality Test Systems Market
Medical Imaging
Digital Telepathology Market
Medical Imaging
Argentina Diagnostic Imaging Equipment Market
Medical Imaging
Global Electroretinography Market
Medical Imaging
Global Nuclear Imaging Equipment Market
Medical Imaging
Asia Pacific Nuclear Imaging Market
Medical Imaging
Global Dental Panoramic Radiography Market
Medical Imaging
X-Ray Flat Panel Detectors Market
Medical Imaging
X-Ray Devices Market
Medical Imaging
Dental Diagnostic Imaging Equipment Market
Medical Imaging
Ga 68 DOTATOC Market
Medical Imaging
Nuclear Magnetic Resonance Spectroscopy Market
Medical Imaging
Global Pediatric Magnetic Resonance Imaging (MRI) Market
Medical Imaging
Medical X-Ray Films Market