
 Digital Pathology Scanner Calibration and Image Quality Test Systems Market | 2026-2036
Digital Pathology Scanner Calibration and Image Quality Test Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Pathology Scanner Calibration and Image Quality Test Systems Market Insights
The EU AI Act and FDA's software-as-medical-device guidance is realigning how scanner manufacturers validate optical performance across deployment sites. Hamamatsu Photonics leverages its photomultiplier heritage to sustain precision in fluorescence calibration modules for high-throughput pathology labs. Leica Biosystems anchors its competitive position through integrated slide scanner and quality assurance bundles that dominate European hospital procurement. Philips competes by extending its enterprise imaging footprint into digital pathology quality workflows across American integrated delivery networks.
Digital Pathology Scanner Calibration and Image Quality Test Systems comprise hardware and software platforms that measure spatial resolution, color fidelity, and focus accuracy against standardized test patterns such as USAF 1951 targets or custom slide phantoms, ensuring whole slide images meet diagnostic confidence thresholds for primary diagnosis. The technology dimension centers on optical calibration and color accuracy testing, where margin pools concentrate because these modules require frequent recertification to maintain compliance with evolving scanner sensitivity specifications. Application demand in medical diagnostics leads absolute volume, while pharmaceutical research represents the fastest-growing segment as drug developers adopt digital pathology endpoints in regulated toxicology studies.
FDA software-as-medical-device oversight, EU MDR Class IIa device classification for scanner software, and CAP laboratory accreditation standards collectively shape product roadmaps by mandating traceable calibration records and inter-laboratory reproducibility documentation. ISO 15189 medical laboratory requirements in Japan and South Korea further compress time-to-compliance for vendors entering Asia-Pacific academic hospital tenders. Stakeholders must monitor how regulatory divergence between FDA predicate-based clearance and EU MDR clinical evidence requirements fragments validation protocol design and service delivery economics.
Market Dynamics
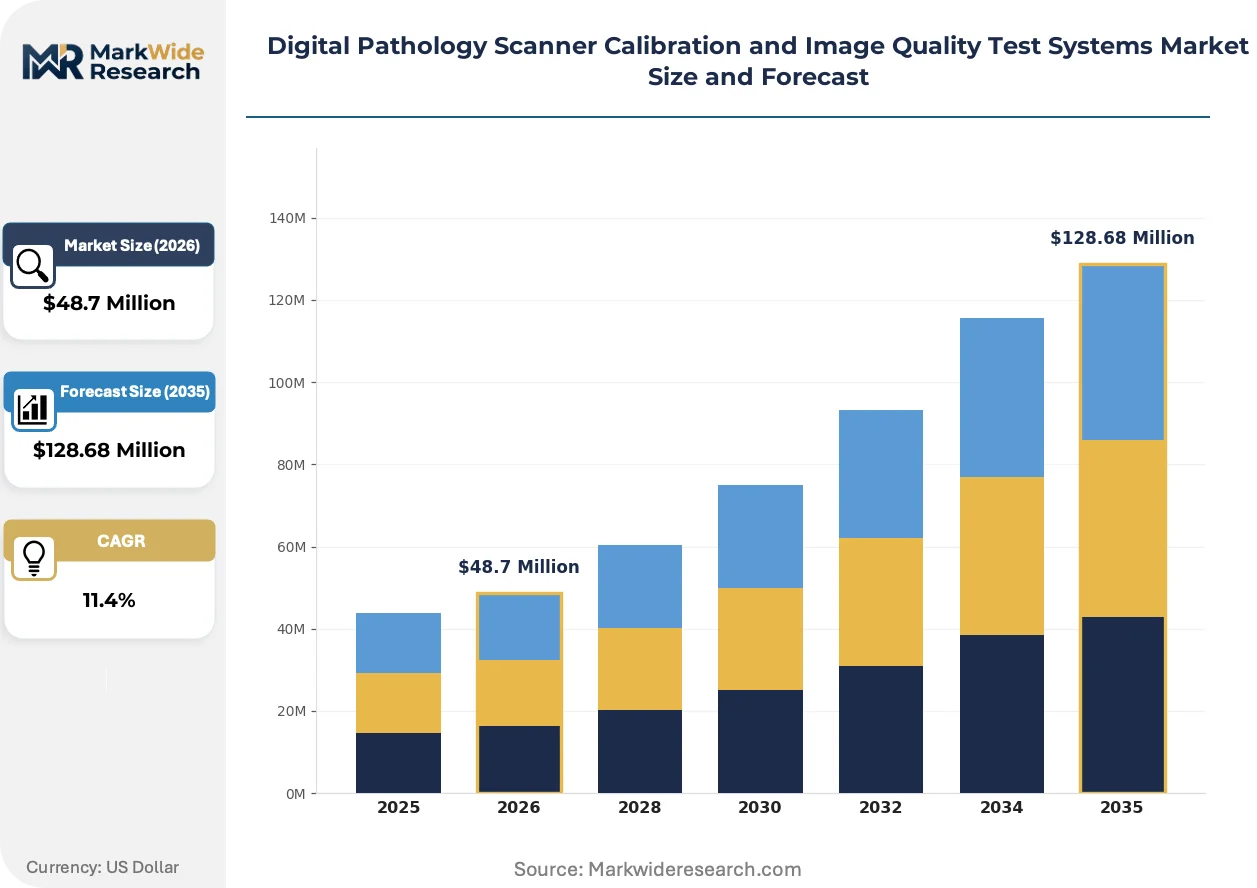
The FDA's software-as-medical-device enforcement and EU MDR Class IIa classification are compressing certification timelines while fragmenting validation protocols across jurisdictions, forcing vendors to maintain parallel compliance architectures.
Growth Catalysts
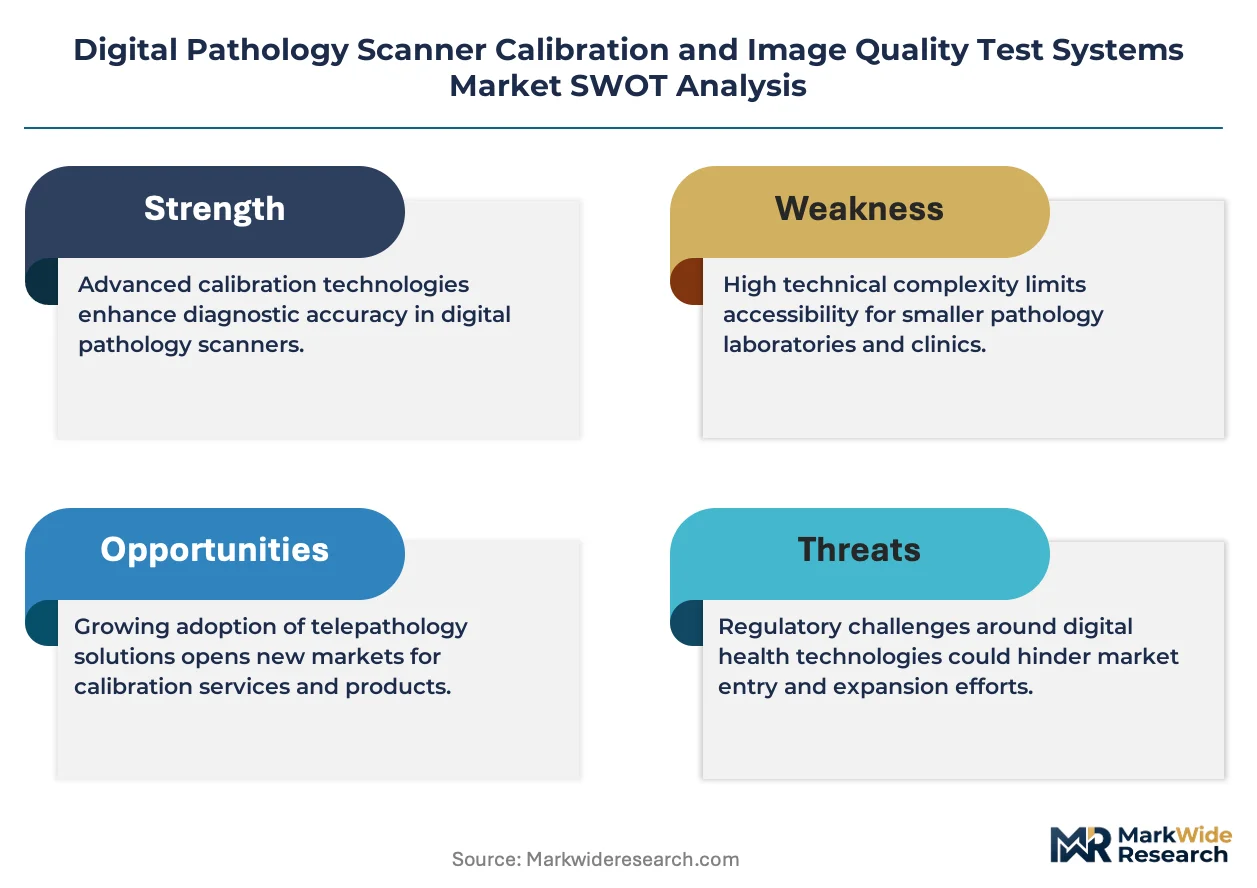
- EU AI Act enforcement:Mandatory algorithmic transparency requirements for diagnostic software are expanding procurement of traceable calibration systems in European reference laboratories.
- Pharmaceutical toxicology digitization:Drug developers adopting digital pathology endpoints in regulated studies are driving validation tool demand for multi-site reproducibility documentation.
- Academic medical center consolidation:University hospital networks in Germany and the United States are centralizing diagnostic platforms and standardizing whole slide imaging validation protocols.
Market Restraints
- Optical component supply concentration:Precision photomultiplier tubes and calibrated reference slides depend on a limited supplier base concentrated in Japan and Germany.
- Regulatory divergence friction:FDA predicate-based clearance pathways conflict with EU MDR clinical evidence requirements, doubling documentation burdens for multi-market vendors.
- Capital intensity barriers:Establishing ISO 17025-accredited calibration laboratories requires substantial fixed investment in climate-controlled facilities and traceable artifact libraries.
Strategic Opportunities
- Asia-Pacific laboratory accreditation expansion:ISO 15189 implementation in Japan and South Korea is opening tender opportunities for vendors with localized service networks.
- Cloud-based calibration-as-a-service:Remote validation platforms are emerging as an alternative to on-premise hardware for mid-tier pathology labs.
- Fluorescence multiplexing convergence:Integration of hyperspectral imaging with traditional brightfield calibration is creating new module categories for advanced research applications.
Industry Challenges
- Metrology expertise scarcity:Cross-disciplinary talent combining optical engineering with clinical laboratory operations remains concentrated in a handful of academic centers.
- Legacy scanner integration complexity:Retrofitting quality assurance protocols onto installed bases of first-generation whole slide imagers demands customized phantom design.
- Inter-laboratory reproducibility documentation:CAP accreditation standards require extensive round-robin testing that strains vendor service capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Pathology Scanner Calibration and Image Quality Test Systems Market |
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $128.68 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flatbed Scanners, Slide Scanners, Whole Slide Imaging Systems, Digital Microscopes, Virtual Slide Scanners Technology: Optical Calibration, Color Accuracy Testing, Resolution Measurement, Contrast Evaluation, Autofocus Verification Application: Medical Diagnostics, Pharmaceutical Research, Academic Studies, Forensic Analysis, Veterinary Pathology End User: Clinical Laboratories, Research Institutes, Contract Research Organizations, Biotech Companies, Diagnostic Centers |
| Companies Covered | Hamamatsu Photonics, F. Hoffmann-La Roche, Philips, Leica Biosystems, Epredia, 3DHISTECH, Proscia, Indica Labs, Visiopharm, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Pathology Scanner Calibration and Image Quality Test Systems Market Trends and Innovations
Artificial intelligence validation protocols and automated phantom analysis are compressing calibration cycles while raising precision thresholds across diagnostic and research applications.
Machine learning-based image quality assessment is automating defect detection in whole slide scans at throughput rates impossible with human visual inspection. High-volume pathology labs in the United States are deploying these systems for real-time focus and color fidelity monitoring. The technology is automating routine calibration checks and redirecting specialist labor toward complex failure mode analysis.
EU MDR clinical evidence requirements are mandating prospective validation studies for scanner software updates, extending certification timelines by twelve to eighteen months. European hospital procurement committees now require documented traceability chains for all calibration artifacts used in diagnostic workflows. Vendors are responding by establishing captive calibration laboratories within the EU to maintain service level agreements.
Integrated delivery networks are consolidating vendor relationships and demanding bundled scanner-plus-validation contracts with unified performance guarantees. American academic medical centers are leading this shift, replacing discrete hardware purchases with multi-year service agreements. The model compresses switching flexibility but reduces internal procurement overhead for specialized optical equipment.
Digital Pathology Scanner Calibration and Image Quality Test Systems Market Segmentation
Calibration system procurement patterns diverge sharply between high-throughput diagnostic networks and specialized research installations. Volume concentration in medical diagnostics compresses unit economics, while pharmaceutical research commands premium pricing for validated reproducibility documentation.
Product Type:
Flatbed scanners anchor volume procurement through lower capital thresholds, while whole slide imaging systems capture premium margins from enterprise diagnostic networks.
- Flatbed Scanners:Entry-level calibration platforms utilizing standardized test charts for basic spatial resolution verification. Demand clusters in small diagnostic centers across India and Southeast Asia where capital constraints dominate procurement decisions.
- Slide Scanners:Automated slide handling systems with integrated USAF 1951 target validation for high-throughput pathology workflows. Academic medical centers in Germany and the United States standardize on these platforms for centralized diagnostic networks.
- Whole Slide Imaging Systems:Enterprise-grade platforms combining brightfield and fluorescence calibration modules with traceable artifact libraries. FDA software-as-medical-device enforcement drives replacement cycles in American integrated delivery networks.
- Digital Microscopes:Hybrid systems merging traditional optical inspection with automated image quality metrics. Research institutes in Japan deploy these for hyperspectral imaging validation.
- Virtual Slide Scanners:Cloud-integrated platforms enabling remote calibration-as-a-service delivery. Contract research organizations adopt these for multi-site toxicology study standardization.
Mature deployment sits with slide scanners. Newer deployment is concentrated in virtual slide scanners.
Technology:
Optical calibration modules generate recurring revenue through mandatory recertification cycles, whereas color accuracy testing faces compressed margins from software-based alternatives.
- Optical Calibration:Hardware-intensive validation of objective lens alignment, stage positioning accuracy, and illumination uniformity using calibrated reticles. European reference laboratories under EU MDR Class IIa requirements sustain replacement demand for these modules.
- Color Accuracy Testing:Spectrophotometric verification of scanner color reproduction against standardized reference slides. CAP laboratory accreditation standards in the United States mandate quarterly testing, creating steady service revenue.
- Resolution Measurement:Automated analysis of modulation transfer function and Nyquist sampling compliance. Pharmaceutical toxicology digitization drives adoption for regulatory submission documentation.
- Contrast Evaluation:Quantitative assessment of dynamic range and signal-to-noise ratios across magnification levels. Academic studies in South Korea leverage these metrics for AI training dataset validation.
- Autofocus Verification:Real-time monitoring of z-stack precision and focus repeatability. High-throughput pathology labs deploy these systems to reduce rescan rates and pathologist review time.
Resolution measurement is gaining share fastest in pharmaceutical applications. Optical calibration retains the largest installed base across clinical laboratories.
Application:
Medical diagnostics commands absolute volume through regulatory-mandated quality assurance, while pharmaceutical research exhibits the steepest expansion trajectory from digital pathology endpoint adoption.
- Medical Diagnostics:Primary diagnosis workflows requiring CAP-accredited calibration protocols and inter-laboratory reproducibility documentation. University hospital networks in the United States and Germany consolidate procurement through multi-year service agreements.
- Pharmaceutical Research:Regulated toxicology studies demanding traceable calibration chains for FDA submission packages. Multi-site reproducibility requirements drive validation tool standardization across global drug development programs.
- Academic Studies:Methodology development and AI algorithm training requiring flexible phantom design. Research institutes in Japan and South Korea expand procurement for hyperspectral imaging research.
- Forensic Analysis:Chain-of-custody documentation for digital evidence admissibility. Specialized calibration protocols address courtroom scrutiny of image authenticity.
- Veterinary Pathology:Companion animal diagnostic networks adopting whole slide imaging for remote specialist consultation. Mid-tier veterinary laboratories represent an emerging customer segment.
Medical diagnostics maintains the deepest installed base. Pharmaceutical research is expanding most quickly.
End User:
Clinical laboratories concentrate demand through bundled scanner-plus-validation contracts, while contract research organizations fragment procurement across specialized service providers.
- Clinical Laboratories:Hospital-based and independent pathology labs requiring ISO 15189-compliant calibration documentation. European reference laboratories under EU AI Act transparency mandates expand traceable system procurement.
- Research Institutes:Academic medical centers and national laboratories developing next-generation imaging protocols. Germany's university hospital networks lead standardization efforts for centralized diagnostic platforms.
- Contract Research Organizations:Multi-site toxicology and clinical trial service providers requiring harmonized validation across distributed scanner fleets. FDA software-as-medical-device oversight extends certification timelines for these customers.
- Biotech Companies:Precision medicine developers integrating digital pathology biomarkers into therapeutic development. Venture-funded startups in the United States prioritize cloud-based calibration-as-a-service to conserve capital.
- Diagnostic Centers:Independent imaging facilities and pathology reference labs serving regional hospital networks. ISO 17025 accreditation requirements in Japan and South Korea compress vendor qualification timelines for these customers.
Clinical laboratories represent the most mature customer relationships. Biotech companies are concentrating newer procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Japan and Germany where precision optical component manufacturing anchors supply chains, while consumption tilts toward the United States and Western European hospital networks driving diagnostic digitization mandates.
United States
FDA software-as-medical-device enforcement and CAP laboratory accreditation standards drive procurement from university hospital networks and integrated delivery networks. Academic medical centers in Boston and the Research Triangle expand centralized diagnostic platforms with bundled validation contracts. The Southeast corridor attracts calibration-as-a-service providers targeting mid-tier pathology labs.
Germany
EU MDR Class IIa device classification and EU AI Act transparency mandates reshape procurement from university hospital networks and reference laboratories. The Baden-Württemberg and Bavaria clusters concentrate scanner manufacturing and captive calibration laboratory establishment. Berlin-Brandenburg hosts metrology expertise development for inter-laboratory reproducibility documentation.
Japan
ISO 15189 medical laboratory requirements and PMDA quality system regulations compress vendor qualification timelines for academic hospital tenders. The Kanto region around Tokyo anchors photomultiplier tube production and precision optical component supply. Osaka-Kansai laboratories pioneer hyperspectral imaging validation protocols for research applications.
South Korea
ISO 15189 implementation and MFDS medical device quality standards open tender opportunities for vendors with localized service networks. The Seoul Capital Area concentrates demand from high-throughput pathology labs adopting AI training dataset validation. Daegu-Gyeongbuk emerges as a hub for contrast evaluation metrics in digital pathology research.
United Kingdom
NHS digital pathology transformation programs and MHRA software guidance drive standardization across regional hospital networks. The London-Southeast corridor leads procurement of whole slide imaging validation tools for cancer diagnostic networks. The Midlands cluster develops forensic analysis calibration protocols for digital evidence admissibility.
Digital Pathology Scanner Calibration and Image Quality Test Systems Market Competitive Landscape
The competitive structure tilts toward integrated diagnostic platform vendors with captive calibration capabilities. Three to five specialist firms control precision optical component supply while ten to fifteen vendors compete downstream in software and service layers. The field separates into optical heritage manufacturers, integrated scanner-software bundlers, and emerging cloud-native calibration platforms. Consolidation pressure manifests through multi-year service agreement mandates and captive laboratory establishment.
Among Japanese precision optical specialists, Hamamatsu Photonics exemplifies the heritage archetype leveraging photomultiplier tube expertise for fluorescence calibration modules. European integrated platform vendors Leica Biosystems and Philips occupy positions bridging scanner hardware with enterprise imaging workflows. These three firms anchor the competitive terrain while smaller specialists cluster in software analytics and phantom design niches.
| Leading Market Players |
|---|
| Hamamatsu Photonics |
| F. Hoffmann-La Roche |
| Philips |
| Leica Biosystems |
| Epredia |
| 3DHISTECH |
| Proscia |
| Indica Labs |
| Visiopharm |
| Others |
Pricing and Supply Chain Analysis
Metrology expertise concentration in Baden-Württemberg and Tokyo-Kanto widens pricing-tier spreads between ISO 17025-accredited calibration laboratories and mid-tier service providers. Labor-cost differentials between these precision-optics clusters and emerging service hubs compress margins on standardized color-accuracy testing while sustaining premiums for fluorescence calibration modules.
Pricing Analysis
Margin tightening in mid-tier calibration services traces to software-based color verification tools displacing hardware-intensive optical modules. Three-tier pricing structure across enterprise-grade whole slide imaging systems, mid-market slide scanners, and entry-level flatbed platforms reflects certification-grade differentiation and after-sales bundling intensity. Cost-down pressure on basic resolution measurement accelerates because pharmaceutical contract research organizations consolidate vendor relationships. Academic medical centers in Germany exhibit lowest price sensitivity due to EU MDR-mandated traceability requirements, while independent diagnostic centers in Southeast Asia face acute capital constraints.
Supply Chain Analysis
Refurbishment flows for photomultiplier tubes and calibrated reference slides concentrate reverse-logistics capacity in Hamamatsu and Munich, extending asset lifecycles for high-value optical components. Precision photomultiplier tube manufacturing draws from Japan and Germany, with calibrated glass substrate supply anchored in Schott AG's Mainz operations and specialized Japanese ceramics producers. Single-source vulnerability in photomultiplier heritage manufacturing exposes downstream scanner vendors to allocation risk during academic procurement surges. Distribution runs through captive calibration laboratories for enterprise accounts and regional distributor networks for mid-tier pathology labs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply scarcity in ISO 17025-accredited metrology talent props pricing power for vendors with captive laboratory infrastructure. Capacity bottlenecks in precision optical component fabrication limit rapid scaling by new entrants.
For Market Incumbents: To counter cloud-native calibration-as-a-service entrants, Hamamatsu Photonics and Leica Biosystems should deepen backward integration into photomultiplier tube refurbishment capacity in Japan and Germany. Captive control over traceable artifact libraries in the EU and United States defends service-level agreements against emerging remote-validation platforms. For New Entrants and Emerging Players: Cloud-based validation platforms offer the most penetrable route for mid-tier pathology labs in the United States Southeast corridor and South Korea's Seoul Capital Area. SaaS-tiered calibration delivery bypasses capital-intensity barriers that protect incumbent hardware bundling. Target biotech companies prioritizing capital conservation over asset ownership through subscription-based fluorescence module access. For Investors and Strategic Acquirers: Re-rating potential sits with specialist phantom-design software firms given FDA software-as-medical-device enforcement extending certification timelines. Long-term viability favors acquisition targets combining AI-based defect detection with established clinical laboratory relationships. Watch for inflection in pharmaceutical toxicology study digitization rates as signal for validation tool demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Calibration Laboratory Establishment | EU MDR Class IIa requirements in Germany mandate localized traceable artifact chains for hospital procurement. |
| Cloud-Based Calibration-as-a-Service Launch | Remote validation platforms bypass ISO 17025 facility investment for mid-tier American pathology networks. |
| AI-Integrated Phantom Analysis Development | Machine learning defect detection automates routine calibration checks in high-throughput CAP-accredited laboratories. |
| Fluorescence Multiplexing Module Expansion | Hyperspectral imaging convergence creates premium module categories for pharmaceutical research applications. |
| Academic Medical Center Partnership Consolidation | Bundled scanner-plus-validation contracts with unified performance guarantees reduce procurement overhead. |
Research Methodology
Multi-period observation of scanner procurement patterns, calibration recertification cycles, and regulatory filing timelines anchored the trend analysis, supplemented by interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and pathology laboratory directors. Primary fieldwork drew from FDA 510(k) clearance databases, EU MDR technical documentation, CAP laboratory accreditation records, and ISO 15189 implementation reports across Japan and South Korea. Bottom-up segmentation modeling triangulated against top-down market sizing from precision optical component trade flows.
Input-output matrices mapped product-type, technology, application, and end-user dimensions across the projection horizon. CAGRs derived from segmented growth-rate blending weighted by procurement volume concentration in medical diagnostics and pharmaceutical research. Forecast inputs incorporated EU AI Act implementation pace, FDA software-as-medical-device enforcement intensity, and academic medical center consolidation rates.
The model holds under sustained regulatory enforcement of traceable calibration documentation; deviation in harmonization between FDA predicate-based clearance and EU MDR clinical evidence requirements would shift vendor compliance cost structures. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Positron Emission Tomography Devices (PET) Market
Medical Imaging
South Korea Mammography Market
Medical Imaging
Quantitative Pathology Imaging Market
Medical Imaging
Australia Digital Radiology Market
Medical Imaging
Intraoperative Imaging Market
Medical Imaging
South Africa Diagnostic Imaging Equipment Market
Medical Imaging
Middle East and Africa Digital X-Ray Devices Market
Medical Imaging
Industrial Computed Radiography Market
Medical Imaging
X-Ray Devices Market
Medical Imaging
Image Guided Radiotherapy Market
Medical Imaging
Teleradiology Market
Medical Imaging
Spain Computed Tomography Market
Medical Imaging
Global Medical Imaging Workstation Market
Medical Imaging
Medical Imaging Software Market
Medical Imaging
Image Guided Therapy Market
Medical Imaging
Handheld Ultrasound Scanners Market