
 Argentina Diagnostic Imaging Equipment Market | 2026-2036
Argentina Diagnostic Imaging Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Argentina Diagnostic Imaging Equipment Market Outlook
ANMAT's updated medical device registration framework is restructuring the cost-of-entry calculus for imported diagnostic imaging systems. GE Healthcare leverages its established service infrastructure to sustain long-term equipment contracts across Argentine public hospitals. Siemens Healthcare anchors its position through localized technical training programs that reduce downtime for MRI and CT installations. Philips Healthcare differentiates by competing on integrated digital workflow platforms that connect radiology departments to hospital information systems.
Argentina diagnostic imaging equipment encompasses ionizing and non-ionizing radiation systems engineered to produce visual representations of internal body structures for clinical diagnosis, with magnetic field strengths in MRI typically ranging from 1.5 to 3.0 Tesla and CT scanners achieving spatial resolution below 0.5 millimeters. X-ray systems occupy the largest installed base due to lower capital requirements and broader point-of-care deployment, while MRI segments command premium pricing driven by specialized neurology and orthopedic applications. Ultrasound technology leads growth trajectories in outpatient clinics where portability and absence of ionizing radiation attract ambulatory investment, and 3D imaging capabilities are displacing conventional reconstruction methods in cardiology departments seeking volumetric functional assessment.
ANMAT enforces Good Manufacturing Practice alignment with MERCOSUR medical device directives, while the Argentine Ministry of Health coordinates federal procurement through the National Program of Medical Technology. These regulatory layers shape demand by mandating local technical support commitments and extended warranty structures that favor established multinational suppliers over new entrants. Stakeholders must monitor pending harmonization between Argentine standards and evolving MERCOSUR technical regulations to anticipate compliance cost shifts.
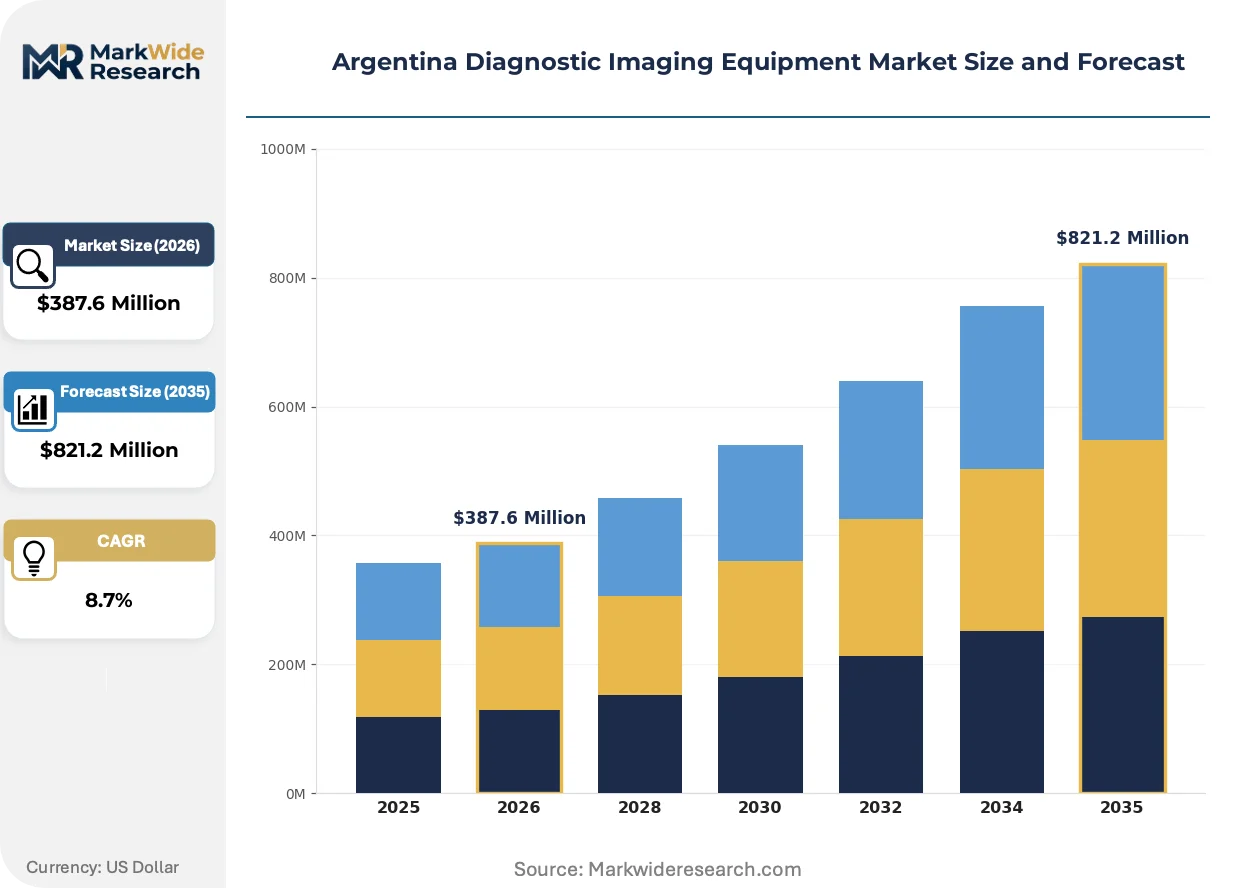
Market Dynamics
ANMAT's accelerated registration timelines for medical devices are compressing vendor qualification cycles while simultaneously elevating technical documentation burdens for imported diagnostic imaging systems entering Argentine public procurement channels.
Growth Catalysts
- Federal Hospital Modernization:Argentina's National Program of Medical Technology is channeling investment toward tertiary care centers in Buenos Aires and Córdoba province, expanding installed capacity for MRI and CT modalities.
- ANMAT Regulatory Alignment:MERCOSUR medical device directive harmonization is streamlining cross-border equipment certification, reducing duplicate compliance costs for suppliers operating across Argentina, Brazil, and Uruguay.
- Point-of-Care Ultrasound:Portable systems without ionizing radiation are penetrating outpatient clinics and emergency departments, displacing conventional radiography in ambulatory diagnostic workflows.
Market Restraints
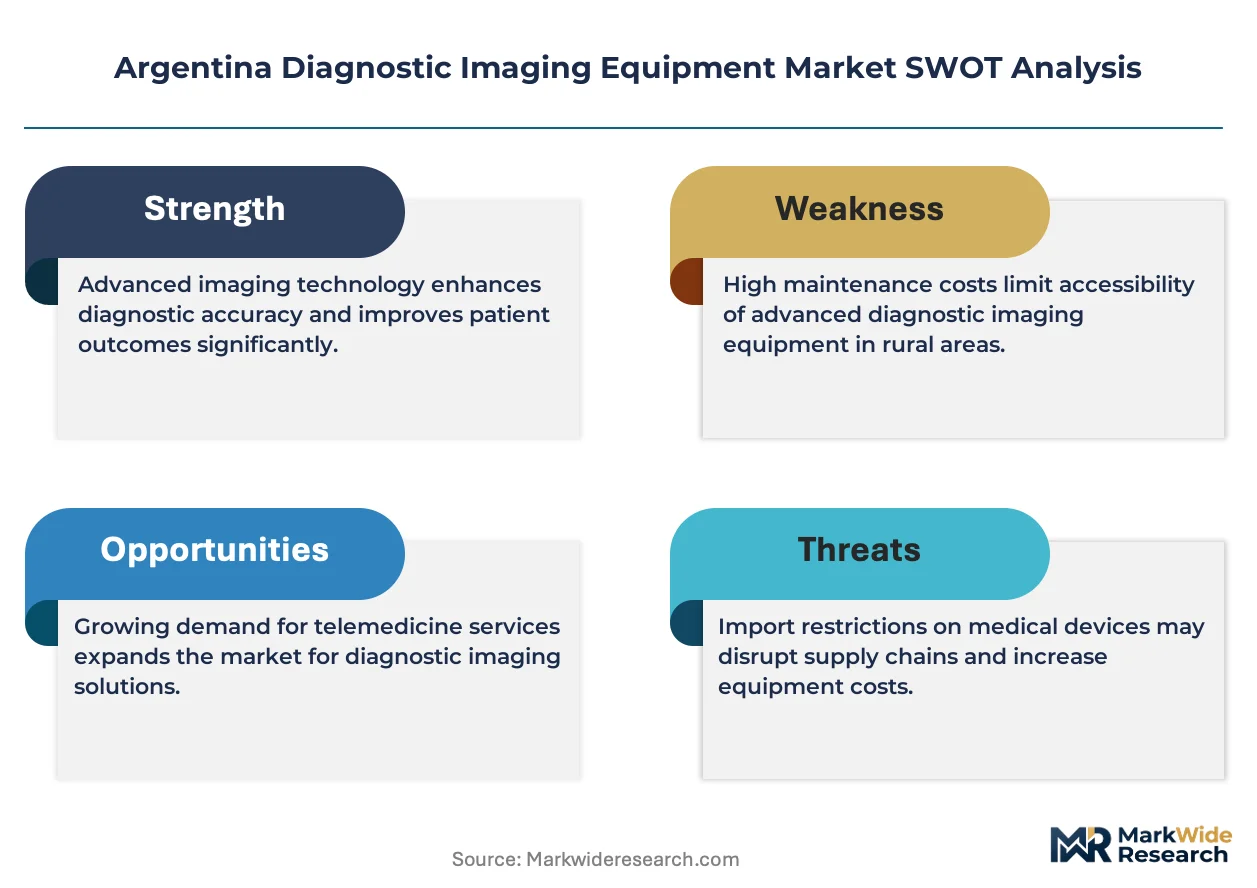
- Import Tariff Structure:Argentina's customs regime imposes significant landed cost premiums on finished imaging systems, compressing margins for distributors serving public hospital segments.
- Foreign Exchange Volatility:Peso-dollar instability disrupts equipment financing arrangements and extended warranty pricing for multinational suppliers.
- Specialized Technical Labor Scarcity:MRI field service engineers and CT calibration specialists concentrate in metropolitan Buenos Aires, leaving provincial installations dependent on remote support protocols.
Strategic Opportunities
- Patagonia Regional Expansion:Underpenetrated provinces in southern Argentina present whitespace for mobile imaging units serving dispersed populations outside major urban corridors.
- AI-Assisted Image Reconstruction:Machine learning algorithms integrated into CT and MRI workstations are reducing scan times and contrast agent requirements, creating differentiation for early adopters.
- Public-Private Partnership Models:Equipment leasing structures with performance-based maintenance clauses are emerging as alternatives to capital purchase in fiscally constrained provinces.
Industry Challenges
- Biomedical Engineering Talent Pipeline:Argentine universities produce insufficient graduates with hybrid competencies in imaging physics and digital system troubleshooting, forcing vendors to internalize training costs.
- Legacy PACS Integration:Hospital information system fragmentation complicates seamless connectivity for new digital workflow platforms, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Argentina Diagnostic Imaging Equipment Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X-Ray, MRI, CT Scanner, Ultrasound End User: Hospitals, Diagnostic Centers, Research Institutes, Outpatient Clinics Technology: 3D Imaging, Computed Radiography, Mobile Imaging, Contrast Imaging Application: Cardiology, Orthopedics, Oncology, Neurology |
| Companies Covered | GE Healthcare, Siemens Healthcare, Philips Healthcare, Canon Medical Systems Corporation, Fujifilm Holdings, Esaote SpA, Carestream Health Inc, Hitachi Medical Corporation, Hologic Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Argentina Diagnostic Imaging Equipment Market Strategic Shifts
Digital convergence between imaging hardware and hospital information infrastructure is redefining competitive positioning, with workflow integration and data interoperability now outweighing raw technical specifications in procurement evaluations.
Artificial intelligence embedded in CT and MRI reconstruction engines is unifying diagnostic speed with dose reduction objectives. Tertiary hospitals in Buenos Aires are deploying these systems to compress patient throughput bottlenecks. The technology is unifying previously separate purchasing decisions for hardware and analytics software into single-vendor contracts.
ANMAT's updated medical device registration framework is tightening Good Manufacturing Practice verification requirements for imported systems. Suppliers must now demonstrate localized technical support capabilities before market authorization. MRI and CT segments face the steepest compliance adjustments as these modalities carry the highest risk classifications under MERCOSUR directives.
Hospital purchasing committees are consolidating vendor relationships around comprehensive service agreements rather than discrete equipment transactions. Public sector buyers in Córdoba province are leading this transition, bundling maintenance, training, and upgrade pathways into multi-year contracts. This behavioral shift favors established suppliers with proven Argentine service infrastructure over new market entrants.
Argentina Diagnostic Imaging Equipment Market Segmentation
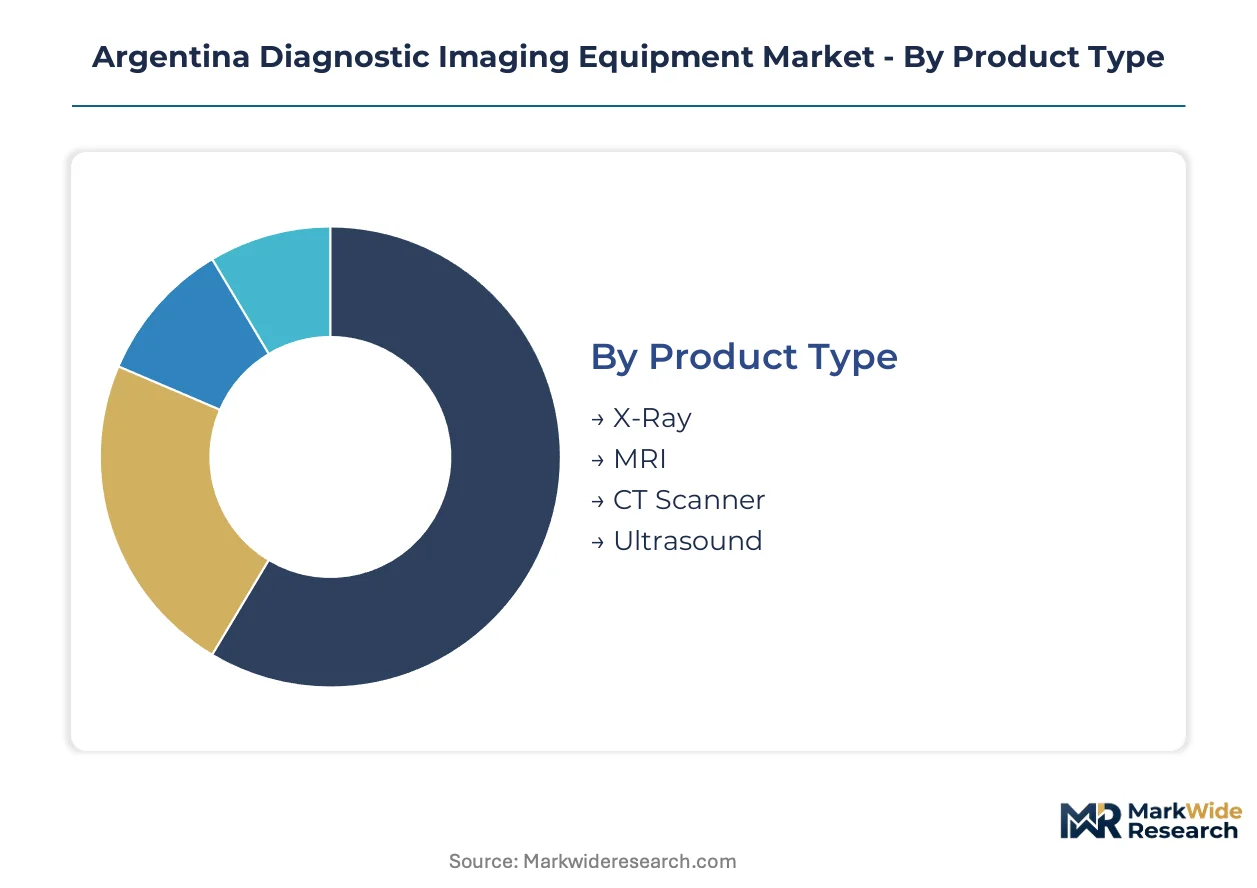
Segmentation reveals how capital deployment and clinical utility diverge across Argentine healthcare infrastructure. Procurement patterns in Buenos Aires tertiary centers differ sharply from provincial outpatient networks, creating distinct competitive arenas for equipment vendors.
Product Type:
Capital intensity varies dramatically across modalities, with MRI and CT systems requiring infrastructure investments that X-ray and ultrasound platforms avoid.
- X-Ray:Fixed and portable systems utilizing ionizing radiation to capture skeletal and thoracic images with minimal site preparation requirements. Demand concentrates in municipal hospitals across Buenos Aires province where federal modernization programs prioritize rapid throughput for trauma and respiratory diagnostics.
- MRI:Superconducting magnet systems generating 1.5 to 3.0 Tesla fields for soft-tissue visualization without ionizing radiation. Córdoba's tertiary referral centers absorb the bulk of new installations, driven by neurology and orthopedic subspecialty expansion requiring high-contrast resolution.
- CT Scanner:Computed tomography platforms achieving sub-millimeter spatial resolution through rotating X-ray arrays and detector banks. ANMAT risk classification elevates compliance costs for these systems.
- Ultrasound:Piezoelectric transducer systems operating across 2-18 MHz frequency ranges for real-time anatomical assessment. Portability attracts ambulatory investment in underpenetrated Patagonia provinces.
X-Ray absorbs the bulk of installed capacity; Ultrasound is expanding most quickly.
End User:
Facility type determines financing mechanisms and service contract structures across Argentine procurement channels.
- Hospitals:Inpatient institutions with 24-hour emergency capacity and surgical suites. Public hospital procurement through the National Program of Medical Technology channels federal investment toward MRI and CT modalities in metropolitan Buenos Aires.
- Diagnostic Centers:Dedicated imaging facilities operating outside hospital campuses with scheduled appointment workflows. Volume-based pricing models dominate these settings.
- Research Institutes:Academic medical centers with dual clinical and investigational mandates. Equipment specifications prioritize research protocol flexibility over throughput metrics.
- Outpatient Clinics:Ambulatory care sites without overnight admission capacity. Point-of-care ultrasound penetration is climbing the fastest in this segment due to lower capital barriers and absence of shielding requirements.
Hospitals command the largest equipment budgets; Outpatient Clinics are gaining share fastest.
Technology:
Digital sophistication tiers separate premium procurement from standard replacement cycles in Argentine radiology departments.
- 3D Imaging:Volumetric reconstruction algorithms generating spatial datasets from multi-planar acquisitions. Cardiology departments in Buenos Aires private hospitals are adopting these platforms for functional assessment.
- Computed Radiography:Phosphor plate systems digitizing conventional X-ray exposures without film processing. Legacy infrastructure in provincial public hospitals sustains demand for this transitional technology.
- Mobile Imaging:Self-contained CT and X-ray units mounted on vehicle platforms for remote deployment. Patagonia regional expansion strategies favor this configuration.
- Contrast Imaging:Protocols utilizing iodinated or gadolinium-based agents to enhance vascular and tissue differentiation. Oncology applications drive adoption in specialized cancer centers.
Computed Radiography dominates current installed base; Mobile Imaging shows steepest expansion trajectory.
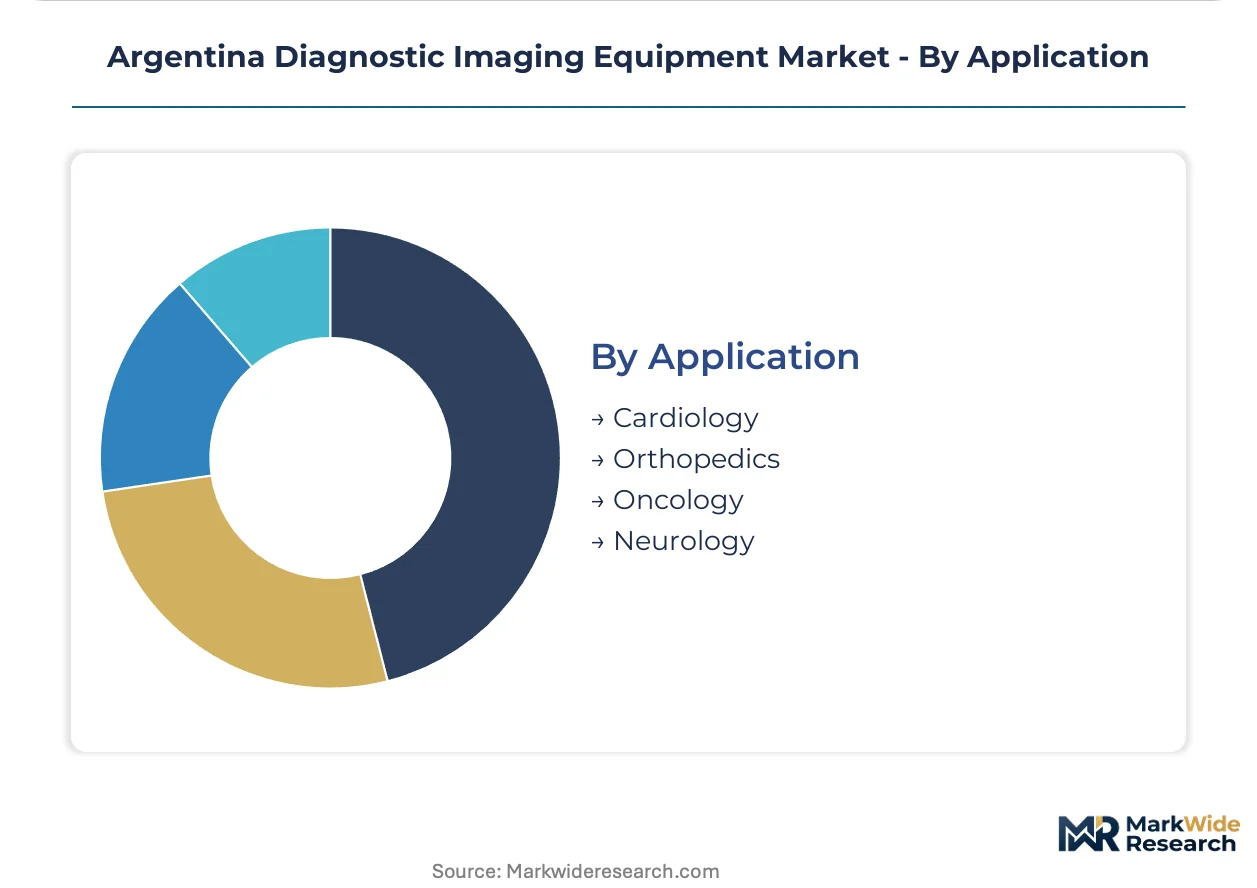
Application:
Clinical specialty requirements dictate technical specifications and reimbursement pathways for equipment acquisition.
- Cardiology:Imaging protocols assessing cardiac structure, function, and perfusion under stress and rest conditions. 3D echocardiography and CT coronary angiography are displacing invasive catheterization in Buenos Aires tertiary centers.
- Orthopedics:Musculoskeletal visualization spanning trauma, degenerative disease, and sports medicine. MRI field strength requirements peak in this application for ligament and cartilage resolution.
- Oncology:Tumor detection, staging, and treatment response monitoring across multimodal platforms. Contrast-enhanced protocols dominate procurement specifications.
- Neurology:Brain and spinal cord assessment for stroke, demyelination, and neurodegenerative conditions. Functional MRI capabilities separate premium from standard system configurations.
Orthopedics accounts for substantial procedure volume; Cardiology is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metropolitan Buenos Aires concentrates diagnostic imaging demand through federal hospital procurement programs, while provincial networks in Córdoba and emerging southern regions fragment equipment deployment across uneven infrastructure tiers.
Buenos Aires Metropolitan Area
Tertiary care centers drive MRI and CT procurement through the National Program of Medical Technology. ANMAT registration requirements mandate localized technical support commitments for all imported systems. Hospital clusters in Palermo and Recoleta districts anchor service infrastructure for multinational suppliers.
Córdoba Province
Neurology and orthopedic subspecialty expansion fuels 1.5 to 3.0 Tesla MRI installations at referral centers. Provincial health authorities coordinate equipment financing through federal-provincial cost-sharing arrangements. The Córdoba capital region absorbs the bulk of high-field magnet deployments outside Buenos Aires.
Santa Fe Province
Rosario's industrial corridor sustains diagnostic center networks serving manufacturing workforce health programs. Municipal hospital budgets prioritize X-ray and ultrasound modalities with lower capital barriers. Private imaging chains concentrate in the Gran Rosario urban agglomeration.
Mendoza Province
Wine industry occupational health programs generate specialized musculoskeletal imaging demand. Provincial public hospitals rely on remote service protocols from Buenos Aires-based field engineers. The Greater Mendoza metro represents the largest Andean foothills equipment market.
Patagonia Region
Dispersed populations in Neuquén, Río Negro, and Chubut provinces create whitespace for mobile CT and X-ray units. Federal infrastructure investment lags behind northern provinces, constraining fixed-site installation economics. Oil and gas sector health services in Comodoro Rivadavia anchor private diagnostic demand.
Argentina Diagnostic Imaging Equipment Market Competitive Environment
North American and European producers anchor the premium equipment tier; Japanese and Italian specialists hold mid-market positions through targeted modality expertise. The vendor structure concentrates around comprehensive service agreements rather than discrete equipment transactions. Three archetypes dominate: full-line multinationals with Argentine service infrastructure, regional European specialists in ultrasound and MRI, and Asian manufacturers competing on capital efficiency. Consolidation pressure and AI-integrated platform differentiation represent the dominant competitive vectors reshaping procurement relationships.
Among the full-line multinational tier, GE Healthcare, Siemens Healthcare, and Philips Healthcare occupy positions defined by service network depth and federal contract tenure. These firms exemplify the integrated hardware-software-service archetype that public hospital procurement committees increasingly favor. Their established technical training programs and extended warranty structures create qualification barriers that newer entrants struggle to surmount under ANMAT's tightened registration timelines.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthcare |
| Philips Healthcare |
| Canon Medical Systems Corporation |
| Fujifilm Holdings |
| Esaote SpA |
| Carestream Health Inc |
| Hitachi Medical Corporation |
| Hologic Inc |
| Others |
Value Chain & Pricing Dynamics
Multinational vendors with established Argentine service infrastructure anchor pricing discipline through bundled long-term contracts that internalize technical training and warranty costs. ANMAT registration requirements elevate compliance expenditures for new entrants, compressing their margin flexibility against incumbents who amortize fixed costs across decade-long federal hospital relationships.
Pricing Analysis
Lead-time premiums for expedited MRI and CT delivery separate standard procurement cycles from emergency replacement scenarios in Argentine public hospitals. Three-tier pricing structure across premium, standard, and economy levels reflects field strength gradients in MRI and detector row counts in CT systems. Cost compression in economy-tier ultrasound runs through volume-scale manufacturing by Asian producers serving outpatient clinic expansion. Public hospital procurement committees demonstrate highest price sensitivity, while private tertiary centers in Buenos Aires absorb premium pricing for integrated digital workflow platforms.
Supply Chain Analysis
Freight costs from Germany, the Netherlands, and Japan constitute substantial landed cost premiums for finished imaging systems entering Argentine ports. Superconducting magnet wire draws from specialized producers in Japan and Germany, while detector arrays source from South Korean and Taiwanese semiconductor fabricators. Single-source vulnerability concentrates in helium cooling systems for MRI superconducting magnets, forcing distributors to maintain strategic buffer inventories. Distribution runs through Buenos Aires-based authorized service depots that pre-position spare parts for ANMAT-mandated local technical support commitments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Argentina's diagnostic imaging market sits in a technology-transition phase where AI-embedded reconstruction engines are displacing conventional hardware-centric procurement criteria. Legacy PACS infrastructure fragmentation creates implementation friction that rewards vendors with integration expertise.
For Market Incumbents: Lock in multi-year service contracts with Patagonia regional hospitals before mobile imaging unit competitors establish field presence. Deepen backward integration into AI software development to differentiate CT and MRI platforms as integrated diagnostic ecosystems rather than discrete hardware sales. ANMAT's accelerated registration timelines threaten to compress vendor qualification cycles for new entrants, but established players can exploit documentation expertise as a defensive moat.
For New Entrants and Emerging Players: Capture whitespace in underpenetrated Patagonia provinces through mobile CT and X-ray units deployed via public-private partnership structures. Point-of-care ultrasound in outpatient clinics represents the most penetrable segment given lower capital barriers and absence of shielding requirements. Partner with provincial health authorities to pilot equipment leasing models with performance-based maintenance clauses that circumvent fiscal constraints blocking capital purchases.
For Investors and Strategic Acquirers: ANMAT's tightened Good Manufacturing Practice verification requirements is the leading indicator that regulatory compliance capabilities will separate viable acquisition targets from stranded assets. Long-term viability over the next decade hinges on software-integrated platform differentiation rather than hardware manufacturing scale. Target regional European ultrasound specialists with established MERCOSUR certification pathways and proven Argentine service networks.
| Strategic Initiative | Industry Significance |
|---|---|
| ANMAT Registration Pre-Positioning | Early documentation investment accelerates market authorization timelines against compressed vendor qualification cycles. |
| AI Software Companion Development | Machine learning reconstruction engines unify hardware and analytics into single-vendor contracts preferred by purchasing committees. |
| Provincial Service Depot Expansion | Localized technical support capabilities satisfy ANMAT mandates while reducing downtime for MRI and CT installations. |
| Mobile Imaging Unit Deployment | Self-contained vehicle platforms access dispersed Patagonia populations outside fixed-site installation economics. |
| Public-Private Partnership Structuring | Performance-based leasing alternatives unlock fiscally constrained provincial markets blocked from capital purchases. |
Study Parameters
ANMAT regulatory filings, MERCOSUR technical directive databases, and Argentine Ministry of Health procurement records formed the secondary backbone for market sizing and compliance timeline analysis. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and field service technicians validated equipment deployment patterns and service infrastructure gaps. Bottom-up installed base enumeration across Buenos Aires, Córdoba, and Patagonia provinces combined with top-down federal budget allocation analysis to triangulate market value estimates.
Historical trendline analysis of public hospital procurement cycles through the National Program of Medical Technology established baseline growth trajectories across the projection horizon. Segmentation modeling incorporated product type, end-user facility tier, technology sophistication level, and clinical application intensity. CAGRs derived from equipment replacement cycle analysis, subspecialty expansion rates in neurology and orthopedics, and ambulatory clinic penetration patterns for point-of-care ultrasound.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to peso-dollar exchange volatility and pending MERCOSUR harmonization shifts. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Ultrasound Market
Medical Imaging
Global Electroretinography Market
Medical Imaging
Intraoperative Imaging Market
Medical Imaging
Global Veterinary Radiography System Market
Medical Imaging
Mobile Computed Tomography Scanners Market
Medical Imaging
US Gadolinium-Based Contrast Media Market
Medical Imaging
Global Medical Imaging Workstation Market
Medical Imaging
PACS and RIS Market
Medical Imaging
Magnetic Resonance Imaging (MRI) Equipment Market
Medical Imaging
Medical Image Analysis Software Market
Medical Imaging
India Digital Radiology Market
Medical Imaging
X-Ray Devices Market
Medical Imaging
Germany Digital Pathology Market
Medical Imaging
AI-Based Medical Imaging Algorithm Validation Test Platforms Market
Medical Imaging
Open Magnetic Resonance Imaging System Market
Medical Imaging
Latin America Medical Imaging Software Market