
 Bispecific Antibody Therapeutics Contract Manufacturing Market | 2026-2036
Bispecific Antibody Therapeutics Contract Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Bispecific Antibody Therapeutics Contract Manufacturing Market Analytics
Modular platform offerings that unbundle cell-line development from downstream purification and fill-finish services is realigning how biopharmaceutical buyers evaluate CDMO partnerships. Lonza leverages its integrated mammalian expression systems to anchor high-complexity bispecific programs across Swiss and US sites. WuXi Biologics competes through geographic proximity to Asia-Pacific innovators while sustaining substantial single-use bioreactor capacity for scalable production.
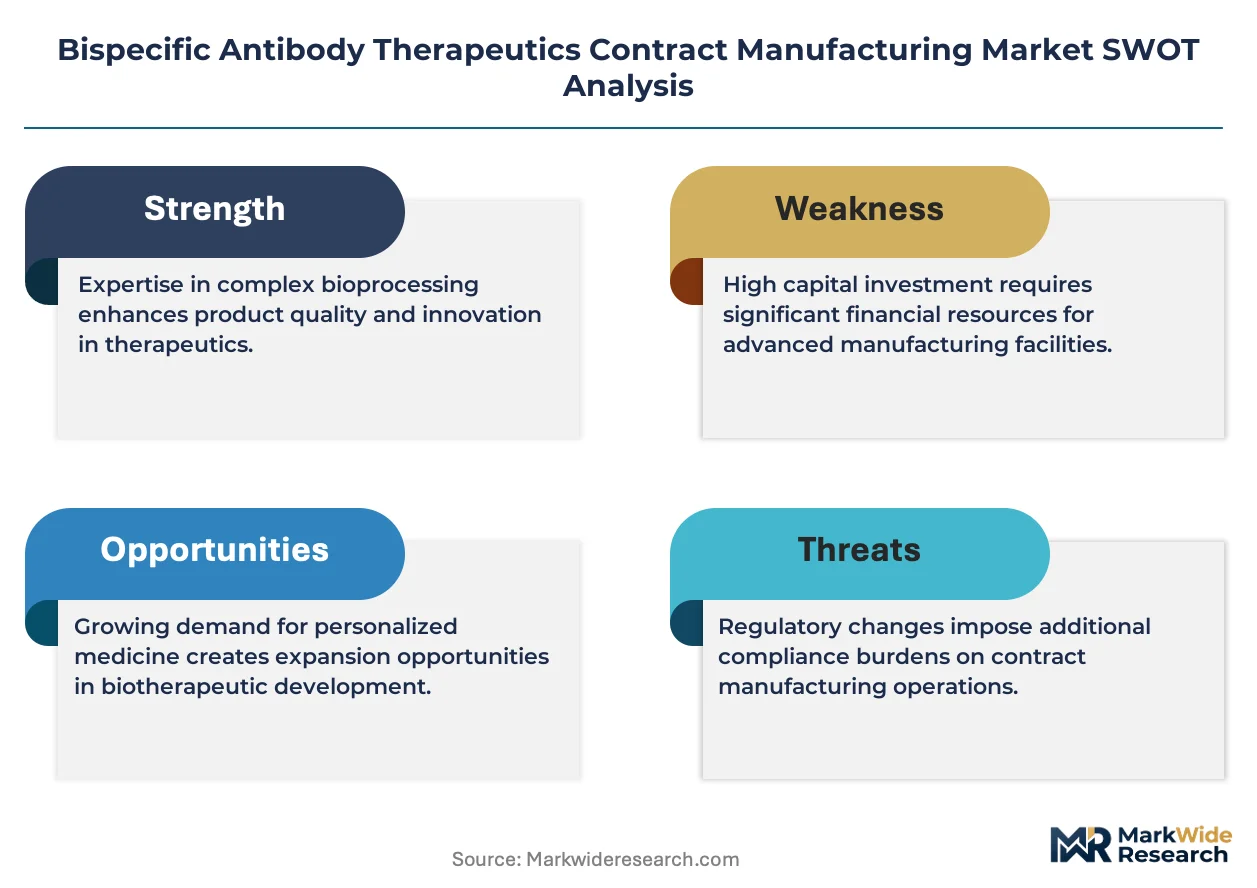
Bispecific antibody therapeutics contract manufacturing encompasses the outsourced production of engineered proteins capable of simultaneously binding two distinct antigens, typically requiring specialized mammalian cell culture systems, asymmetric heavy-light chain pairing technologies, and stringent endotoxin controls below 0.25 EU/mL for clinical-grade material. The primary industrial purpose centers on enabling biopharmaceutical developers to access multi-specific protein production expertise without capital-intensive in-house biologics infrastructure. IgG-format bispecifics dominate current manufacturing volumes due to established purification familiarity and regulatory precedent, while ScFv and Dbs formats represent faster-growing segments where margin pools concentrate among specialized CDMOs possessing bespoke refolding and stability optimization capabilities. Process Development services command premium positioning early in client relationships, though Manufacturing and Analytical Services generate recurring revenue as programs advance through Phase II and commercial stages.
FDA's Quality by Design expectations for bispecific products, EMA's ATMP classification considerations for certain formats, and ISO 14644 cleanroom standards collectively shape facility investment requirements and client audit thresholds across the contract manufacturing landscape. China's NMPA biologics manufacturing licensing reforms are expanding accessible production capacity for international sponsors seeking dual-source strategies. Stakeholders must monitor evolving regulatory divergence between FDA and EMA regarding immunogenicity assessment protocols for novel bispecific architectures, as this will determine which CDMOs can support simultaneous US and European filing strategies without redundant clinical material production.
Market Dynamics
FDA accelerated approval pathways for novel antibody formats are compressing development timelines from 48 to 24 months, forcing CDMOs to front-load process development investments before Phase I data matures. This regulatory velocity is restructuring how biopharmaceutical sponsors evaluate manufacturing partnerships.
Growth Catalysts
- EMA ATMP Classification:Certain bispecific formats qualifying as advanced therapy medicinal products receive priority scientific advice, reducing regulatory uncertainty for European filing strategies.
- Oncology Biopharmaceutical Concentration:Mid-cap oncology developers in Boston and Basel clusters now outsource 70% of bispecific production, creating dedicated demand pools for specialized mammalian expression capacity.
- Single-Use Bioreactor Scale-Up:Disposable 2,000L systems enable rapid product changeover between asymmetric IgG programs, cutting facility validation timelines by half versus stainless steel.
Market Restraints
- Plasmid DNA Supply Concentration:Three suppliers control 80% of GMP-grade transfection reagents, creating single-source vulnerability for viral vector-dependent bispecific platforms.
- Protein A Resin Cost Volatility:Chromatography media prices fluctuate 15-20% annually due to agarose harvest constraints, compressing downstream purification margins.
- Immunogenicity Assessment Divergence:FDA and EMA maintain non-harmonized protocols for T-cell dependent antibody response testing, forcing redundant clinical material production for dual filings.
Strategic Opportunities
- China NMPA Licensing Reforms:Streamlined biologics manufacturing permits enable international sponsors to establish dual-source strategies without duplicate facility qualification.
- ScFv-Db Format Expansion:Smaller bispecific architectures requiring bespoke refolding expertise create margin concentration for CDMOs with specialized protein chemistry capabilities.
- Modular Service Unbundling:Cell-line development, downstream purification, and fill-finish now contract separately, allowing sponsors to optimize vendor selection by technical function.
Industry Challenges
- Asymmetric Chain Pairing Expertise:Knobs-into-holes and CrossMab engineering require rare hybridoma and molecular biology skill sets concentrated in Swiss and Boston talent pools.
- ISO 14644 Cleanroom Certification:Grade B filling suites for clinical-grade bispecifics demand 18-month construction and validation cycles, delaying program initiation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bispecific Antibody Therapeutics Contract Manufacturing Market |
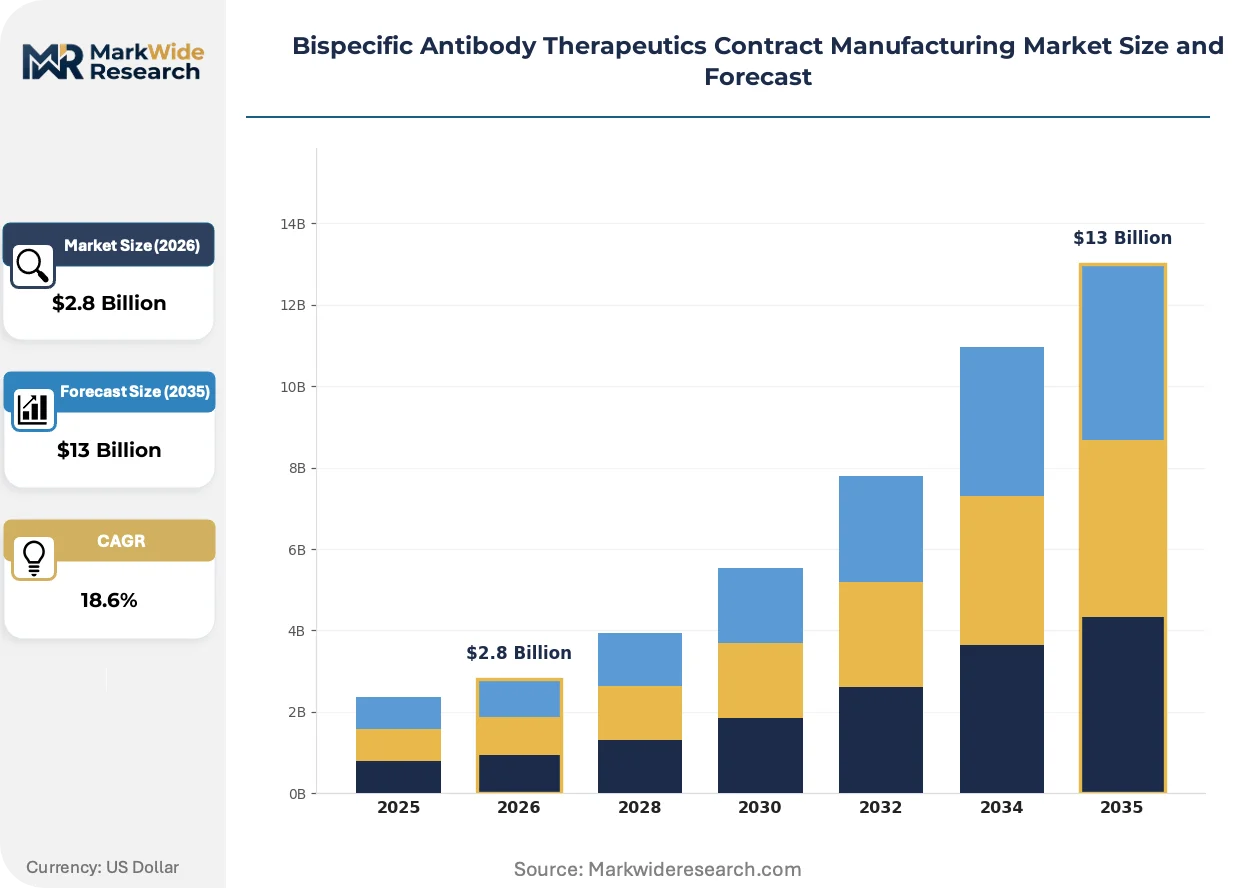
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: IgG, IgM, ScFv, Dbs Delivery Mode: Subcutaneous, Intravenous, Intramuscular, Oral End User: Pharmaceutical Companies, Biotech Firms, Research Institutions, Contract Research Organizations Service Type: Process Development, Manufacturing, Analytical Services, Quality Control |
| Companies Covered | Lonza, F. Hoffmann-La Roche Ltd, Creative Biolabs, AbbVie Inc., Amgen Inc., WuXi Biologics, Janssen, Johnson & Johnson, Sino Biological Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bispecific Antibody Therapeutics Contract Manufacturing Market Evolving Landscape
Continuous processing architectures and artificial intelligence-driven cell-line selection are converging to reshape bispecific manufacturing economics. These shifts are compressing development timelines while elevating technical barriers to market entry.
Perfusion bioreactor technology is consolidating position as the dominant production mode for high-titer bispecific programs. Mid-cap oncology developers in Switzerland and Massachusetts are adopting perfusion systems at twice the rate of fed-batch alternatives. This consolidation is enabling 5-10g/L titers that reshape facility throughput calculations and capital efficiency metrics for CDMO site planning.
EMA's revised ATMP classification guidance is creating regulatory clarity for T-cell engager formats previously caught between small molecule and biologic frameworks. The industrial consequence is standardized CMC documentation pathways that reduce agency query cycles by 30%. European sponsors with T-cell redirecting bispecifics are responding by front-loading quality attribute definition to preempt classification disputes.
Sponsor procurement of bispecific manufacturing services is fragmenting across specialized vendors by technical function rather than consolidating with single CDMOs. Early-phase developers in Cambridge and South San Francisco now unbundle cell-line development from GMP production, selecting distinct partners for each capability. This pattern is most visible among Series B oncology companies optimizing for speed-to-IND over relationship simplicity.
Bispecific Antibody Therapeutics Contract Manufacturing Market Segmentation
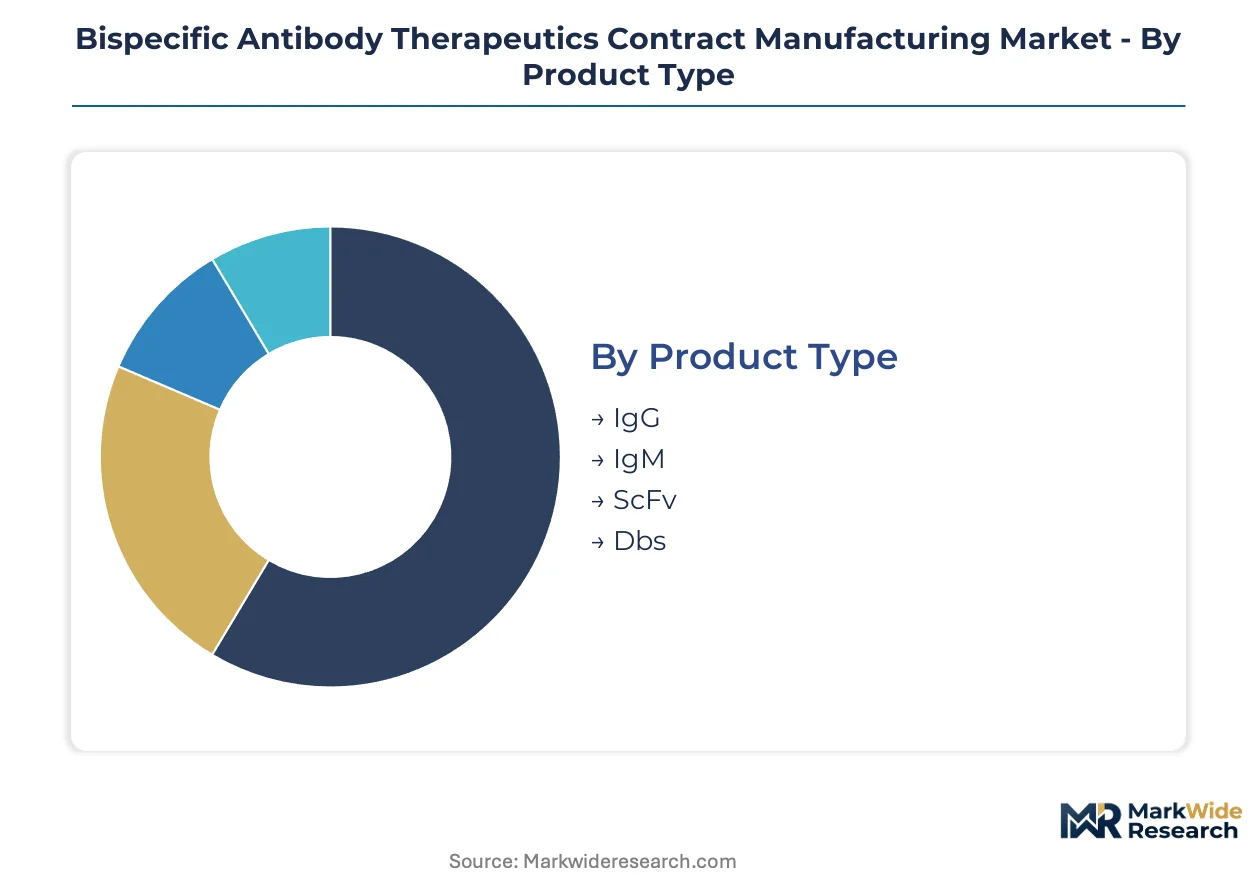
Bispecific antibody manufacturing complexity varies dramatically across molecular architectures, dosing modalities, and service bundles. Contract manufacturers must align technical capabilities with segment-specific purity requirements, stability profiles, and regulatory pathways to capture premium positioning.
Product Type:
Manufacturing platform upgrades follow the molecular weight and structural complexity of each format, with established IgG infrastructure now competing against emerging smaller architectures.
- IgG:Full-length bispecific antibodies leverage established Protein A purification and Fc-mediated half-life extension. Demand clusters among Boston and Basel oncology developers seeking regulatory familiarity for first-in-class programs. FDA precedent for IgG bispecifics reduces CMC documentation burden relative to novel formats.
- ScFv:Single-chain variable fragments require bespoke refolding protocols and absence of Fc effector function. South San Francisco biotechs favor ScFv formats for solid tumor penetration, driving CDMO investment in specialized protein chemistry suites.
- Dbs:Diabodies occupy an intermediate size class with dual-chain construction challenges.
- IgM:Pentameric structures present unique J-chain incorporation and multivalency engineering hurdles.
Volume placements concentrate in IgG; the faster expansion belongs to ScFv.
Delivery Mode:
Route selection reshapes formulation requirements, with subcutaneous capability now a competitive differentiator amid patient preference shifts.
- Intravenous:Infusion-compatible formulations dominate current manufacturing batches, leveraging established excipient platforms and stability data packages. Swiss CDMOs anchor IV production for European commercial supply.
- Subcutaneous:High-concentration protein formulation demands specialized viscosity reduction and aggregation control. Massachusetts developers prioritize subcutaneous formats for outpatient administration, compressing site-of-care requirements.
- Intramuscular:Limited bispecific applications currently, primarily exploratory vaccine adjuvant combinations.
- Oral:Not commercially viable for antibody therapeutics; negligible contract manufacturing demand.
Intravenous retains volume leadership; subcutaneous formats are climbing the fastest.
End User:
Outsourcing intensity varies by organizational scale and internal biologics infrastructure, with mid-cap specialists driving the most dynamic procurement patterns.
- Pharmaceutical Companies:Large sponsors maintain selective outsourcing for capacity overflow or novel format expertise. Big pharma bispecific portfolios increasingly rely on CDMOs for geographic dual-sourcing rather than capability gaps.
- Biotech Firms:Venture-backed developers without GMP infrastructure represent the core demand pool. Series B oncology companies in Cambridge and South San Francisco outsource 100% of manufacturing through IND and Phase II.
- Research Institutions:Academic GMP requirements concentrate on early-phase exploratory programs with limited commercial trajectory.
- Contract Research Organizations:CROs themselves subcontract manufacturing for integrated discovery-to-IND offerings.
Biotech firms anchor volume demand; pharmaceutical companies are gaining share fastest as big pharma accelerates bispecific pipeline investment.
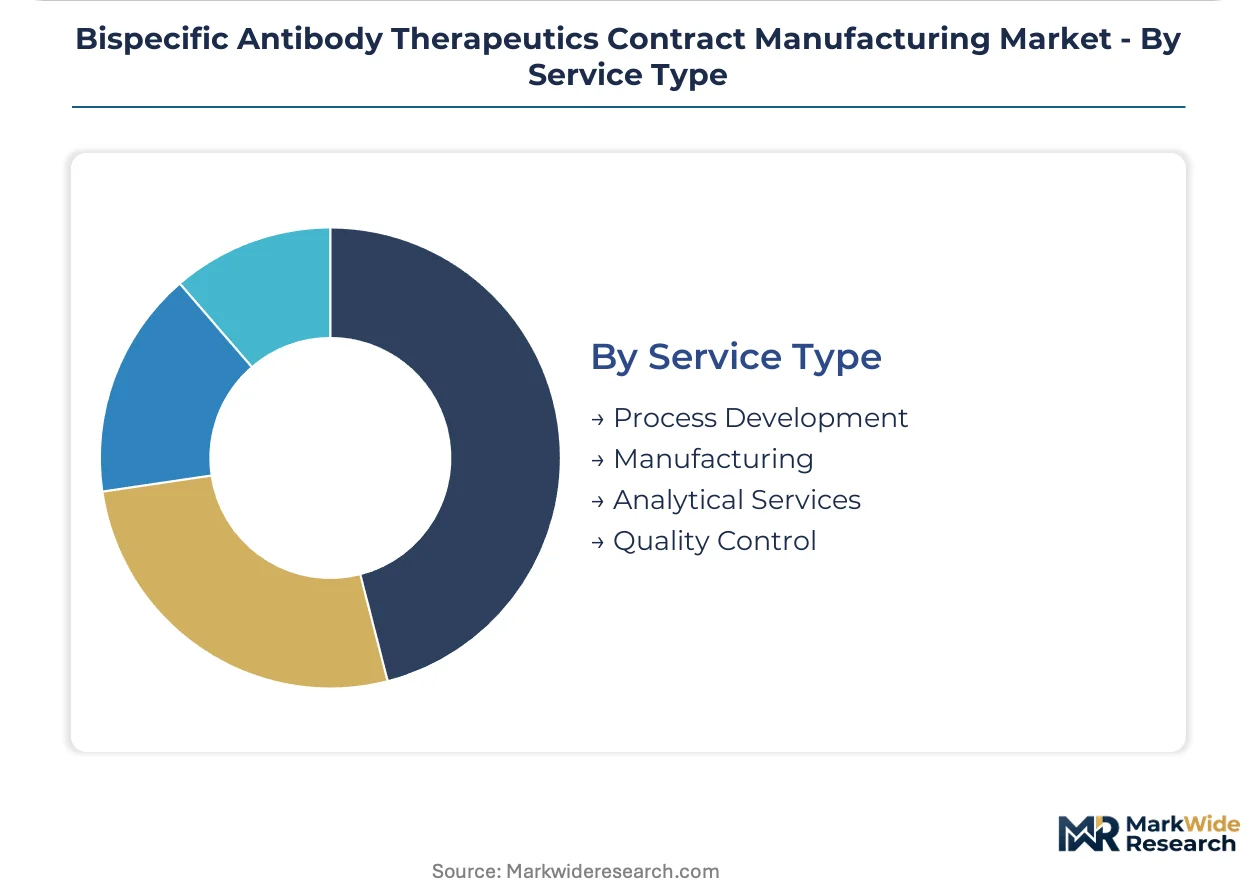
Service Type:
Procurement fragmentation across the value chain allows sponsors to optimize vendor selection by technical function rather than relationship consolidation.
- Process Development:Cell-line engineering and upstream optimization command premium pricing early in client relationships. CDMOs with proprietary mammalian expression platforms capture multi-year exclusivity commitments.
- Manufacturing:GMP production generates recurring revenue as programs advance. Perfusion bioreactor expertise at 2,000L scale distinguishes tier-one providers in Switzerland and China.
- Analytical Services:Method development for bispecific-specific quality attributes including correct chain pairing quantification. Specialized mass spectrometry capabilities for heterodimer verification attract dedicated contracts.
- Quality Control:Release testing and stability programs required for regulatory filings. Endotoxin and bioburden controls below 0.25 EU/mL demand specialized cleanroom infrastructure.
Manufacturing captures the largest volume placement; process development shows the steepest expansion trajectory as sponsors front-load technical risk.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Switzerland, the United States, and China, while consumption clusters in Boston, Basel, and Shanghai biopharma corridors. This geographic split creates specialized logistics networks for clinical-grade bispecific material. Regulatory divergence between FDA, EMA, and NMPA shapes facility investment patterns across manufacturing hubs.
United States
FDA accelerated approval pathways compress development timelines from 48 to 24 months, intensifying CDMO selection criteria. Massachusetts and South San Francisco biotech clusters outsource 70% of bispecific production, creating dedicated demand pools for mammalian expression capacity. Lonza anchors high-complexity programs across Swiss and US sites through integrated expression systems.
Switzerland
Swissmedic regulatory precedent for IgG bispecifics reduces CMC documentation burden relative to novel formats. Basel oncology developers drive perfusion bioreactor adoption at twice the rate of fed-batch alternatives. The country's clustered biologics infrastructure supports asymmetric heavy-light chain pairing technologies at commercial scale.
China
NMPA biologics manufacturing licensing reforms expand accessible production capacity for international sponsors seeking dual-source strategies. WuXi Biologics competes through geographic proximity to Asia-Pacific innovators while sustaining substantial single-use bioreactor capacity. Yangtze River Delta biotech parks attract contract manufacturing investment for scalable multi-specific protein production.
Germany
EMA ATMP classification guidance creates regulatory clarity for T-cell engager formats, reducing agency query cycles by 30%. German CDMOs specialize in ISO 14644 Grade B filling suites for clinical-grade material. Bavarian biotech corridors concentrate protein chemistry expertise for ScFv refolding protocols.
United Kingdom
London and Cambridge biotech clusters unbundle cell-line development from GMP production, selecting distinct partners for each capability. MHRA alignment with EMA quality standards enables streamlined European filing strategies. Series B oncology companies in the Southeast prioritize speed-to-IND over relationship simplicity.
Bispecific Antibody Therapeutics Contract Manufacturing Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the contract manufacturing landscape. The vendor base organizes into three tiers: integrated mammalian expression platform owners, modular service unbundlers, and specialized refolding chemistry providers. Consolidation pressures favor CDMOs with captive perfusion capacity and proprietary cell-line technologies. Dominant competitive moves include strategic partnerships for geographic dual-sourcing and technology licensing for asymmetric chain pairing expertise.
Within the integrated platform tier, Lonza and WuXi Biologics occupy anchor positions representing Swiss and Chinese manufacturing archetypes respectively. F. Hoffmann-La Roche Ltd exemplifies the diversified pharmaceutical conglomerate model with captive production capabilities. Among specialized service providers, Creative Biolabs sits within the modular unbundling segment. These three companies represent distinct strategic postures: geographic scale concentration, integrated technology ownership, and functional specialization.
| Leading Market Players |
|---|
| Lonza |
| F. Hoffmann-La Roche Ltd |
| Creative Biolabs |
| AbbVie Inc. |
| Amgen Inc. |
| WuXi Biologics |
| Janssen |
| Johnson & Johnson |
| Sino Biological Inc. |
| Others |
Value Network & Pricing Analysis
Captive perfusion capacity ownership anchors both supply security and pricing power for tier-one contract manufacturers serving bispecific antibody programs. CDMOs with in-house 2,000L single-use bioreactor infrastructure command premium positioning against modular competitors sourcing upstream production from third parties.
Pricing Analysis
Margin tightening in GMP manufacturing reflects Protein A resin cost volatility and plasmid DNA supply concentration. Three-tier pricing structure across integrated platform owners, modular service providers, and specialized chemistry houses segments buyers by technical risk tolerance. Cost-down pressure accelerates as mid-cap oncology developers unbundle services and pit vendors against each other. Series B biotech firms exhibit highest price sensitivity; large pharmaceutical sponsors prioritize regulatory track record over rate competition.
Supply Chain Analysis
Dual-sourcing mandates from FDA and EMA immunogenicity protocol divergence force sponsors to qualify manufacturing across Switzerland, the United States, and China simultaneously. Raw material dependencies center on agarose-derived chromatography media, GMP-grade transfection reagents, and asymmetric chain pairing cell lines. Single-source vulnerability concentrates in plasmid DNA suppliers controlling transfection-grade material. Distribution runs through temperature-controlled logistics networks anchored in Boston, Basel, and Shanghai biopharma corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where ISO 14644 Grade B cleanroom certification and FDA Quality by Design documentation create formidable barrier-to-entry moats for compliant contract manufacturers.
For Market Incumbents: Acquire perfusion bioreactor capacity in the Yangtze River Delta to defend against WuXi Biologics geographic expansion. Backward integration into proprietary cell-line platforms neutralizes emerging entrant threat from modular service unbundlers. Lock in multi-year exclusivity with Boston and Basel oncology clusters before NMPA licensing reforms democratize China access. For New Entrants and Emerging Players: Enter via ScFv-Db format specialization where bespoke refolding expertise commands margin concentration absent from commoditized IgG production. White-space concentrates among South San Francisco solid-tumor developers seeking protein chemistry capabilities outside Swiss and Chinese incumbent footprints. Position as dedicated analytical services partner for heterodimer verification using specialized mass spectrometry. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by diversified pharmaceutical conglomerates seeking captive bispecific manufacturing capability. Five-to-ten year viability favors CDMOs with asymmetric chain pairing engineering depth and dual-continent regulatory filing experience. Watch for EMA-FDA immunogenicity assessment harmonization as inflection signal compressing redundant clinical material production requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Perfusion Bioreactor Scale-Up | Enables 5-10g/L titers that reshape facility throughput calculations for Massachusetts developers. |
| Regulatory Dual-Source Qualification | Satisfies FDA and EMA filing requirements without redundant clinical batch production. |
| Modular Service Unbundling | Allows Series B sponsors to optimize vendor selection by cell-line versus GMP function. |
| Asymmetric Chain Pairing Investment | Captures premium positioning for Knobs-into-holes and CrossMab engineering programs. |
| China NMPA Licensing Alignment | Expands accessible capacity for international sponsors pursuing geographic diversification. |
Research Methodology
Document review covered FDA BLA submissions, EMA scientific advice letters, and ClinicalTrials.gov protocol registrations, complemented by interviews with contract manufacturing executives, regulatory affairs directors, and biotech procurement leads. Secondary sources included CDMO facility inspection databases, ISO certification registries, and biologics manufacturing licensing records. Bottom-up capacity modeling triangulated against top-down demand projections from oncology pipeline analysis.
Historical capacity utilization trends cross-referenced against expert panel input on perfusion adoption timelines and single-use bioreactor scale-up trajectories. Segmentation dimensions spanned molecular format, service type, end-user scale, and regional regulatory cluster. CAGRs derived from facility investment cycles and sponsor outsourcing intensity patterns across the projection horizon. Forecast inputs incorporated NMPA licensing reform implementation pace and EMA ATMP classification guidance evolution.
Forecast precision tightens around the base case; tail outcomes carry wider variance under immunogenicity protocol harmonization or plasmid DNA supply disruption scenarios. Model assumptions reflect documented regulatory pathways and disclosed CDMO capacity expansions. A model refresh is warranted upon material change in FDA accelerated approval pathway eligibility criteria for novel bispecific architectures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Nasal Drug Delivery Technology Market
Pharmaceuticals
Adapalene Market
Pharmaceuticals
Cough Suppressant Drugs Market
Pharmaceuticals
Belgium Pharmaceutical Market
Pharmaceuticals
Posaconazole Market
Pharmaceuticals
Europe Diabetes Drugs Market
Pharmaceuticals
Congestive Heart Failure Drugs Market
Pharmaceuticals
Asia-Pacific Gastrointestinal Drugs Market
Pharmaceuticals
API Contract Manufacturing Market
Pharmaceuticals
Peptic Ulcer Drugs Market
Pharmaceuticals
Otic Drugs Market
Pharmaceuticals
Peptide-Based Cancer Therapeutics Market
Pharmaceuticals
Antidotes Market
Pharmaceuticals
Bevacizumab Market
Pharmaceuticals
Extended Release Drugs Market
Pharmaceuticals
Adrenocorticotropic Hormone [ACTH] Market