
 Global Vendor-Neutral Archive (VNA) and PACS Market | 2026-2036
Global Vendor-Neutral Archive (VNA) and PACS Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vendor-Neutral Archive (VNA) and PACS Market Foresight
Enterprise imaging procurement is tilting toward subscription and managed-service models as health systems seek predictable IT expenditures. GE Healthcare leverages its installed base of diagnostic equipment to anchor hybrid deployment conversations with integrated hardware-software bundles. Siemens Healthineers differentiates through AI-native workflow layers embedded within its imaging informatics stack. FUJIFILM Holdings Corporation extends its position from film and chemistry origins into cloud-native VNA infrastructure for mid-size hospital networks.
Vendor-Neutral Archive and PACS denotes medical imaging informatics systems that ingest, store, and distribute DICOM and non-DICOM clinical imaging data across departmental boundaries using standardized communication protocols. These systems functionally replace siloed departmental archives with centralized repositories that enable longitudinal patient imaging records, advanced visualization, and interoperability with electronic health records. Cloud-based deployment represents the fastest-expanding configuration as healthcare IT departments prioritize capital efficiency and remote accessibility, while on-premise installations retain dominance in markets with stringent data residency requirements. Integrated PACS solutions command concentrated margin pools where vendors bundle advanced visualization and analytics modules, whereas standalone VNA offerings compete on interoperability breadth and vendor-agnostic positioning.
FDA 21 CFR Part 820 quality system regulations govern software-as-medical-device classifications for diagnostic imaging platforms in the United States, while the EU Medical Device Regulation (MDR) and GDPR impose conformity and data governance obligations on European deployments. Japan's PMDA and METI coordinate digital health standards that influence imaging informatics procurement specifications for university hospitals. Stakeholders must monitor evolving interoperability mandates from national regulators and cloud security frameworks to align product roadmaps with compliance-driven purchasing cycles.
Market Dynamics
Cloud-native architectures are compressing replacement cycles for legacy on-premise PACS installations as hospital CIOs prioritize operational expenditure models over capital-intensive infrastructure commitments.
Growth Catalysts
- DICOMweb and FHIR interoperability mandates:Health systems in the United States face CMS-promulgated data-sharing requirements that accelerate decommissioning of proprietary departmental archives.
- Enterprise imaging consolidation:Multi-site hospital networks in Germany deploy centralized VNA infrastructure to unify radiology, cardiology, and pathology imaging workflows under single governance frameworks.
- AI-augmented diagnostic workflows:Machine learning inference pipelines require standardized image repositories that legacy siloed PACS cannot support, pulling replacement demand forward.
Market Restraints
- Data residency compliance costs:Japan's METI guidelines and Germany's BSI cloud security standards impose localization requirements that inflate total cost of ownership for cross-border deployments.
- Specialized DICOM migration expertise scarcity:Health IT labor markets in secondary cities lack sufficient trained personnel to execute large-scale archive transitions without vendor dependency.
- Hybrid deployment complexity:Organizations maintaining edge imaging nodes for latency-sensitive modalities face integration overhead that extends project timelines beyond initial forecasts.
Strategic Opportunities
- Mid-size network penetration in Japan:Prefectural hospital consortia outside Tokyo and Osaka remain underpenetrated by enterprise VNA vendors focused on university medical centers.
- Longitudinal imaging record monetization:Payer organizations in the United States seek population health analytics derived from multi-year DICOM repositories, creating new revenue streams beyond software licensing.
- Edge-to-cloud orchestration platforms:Convergence of containerized workloads and software-defined storage enables vendors to offer tiered latency guarantees for different clinical modalities.
Industry Challenges
- Legacy PACS data normalization:Decades of non-standard DICOM private tags and proprietary compression schemes require manual mapping exercises that consume implementation resources.
- Cross-functional governance alignment:Radiology, cardiology, and pathology departments maintain independent budget authority, complicating enterprise-wide procurement decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vendor-Neutral Archive (VNA) and PACS Market |
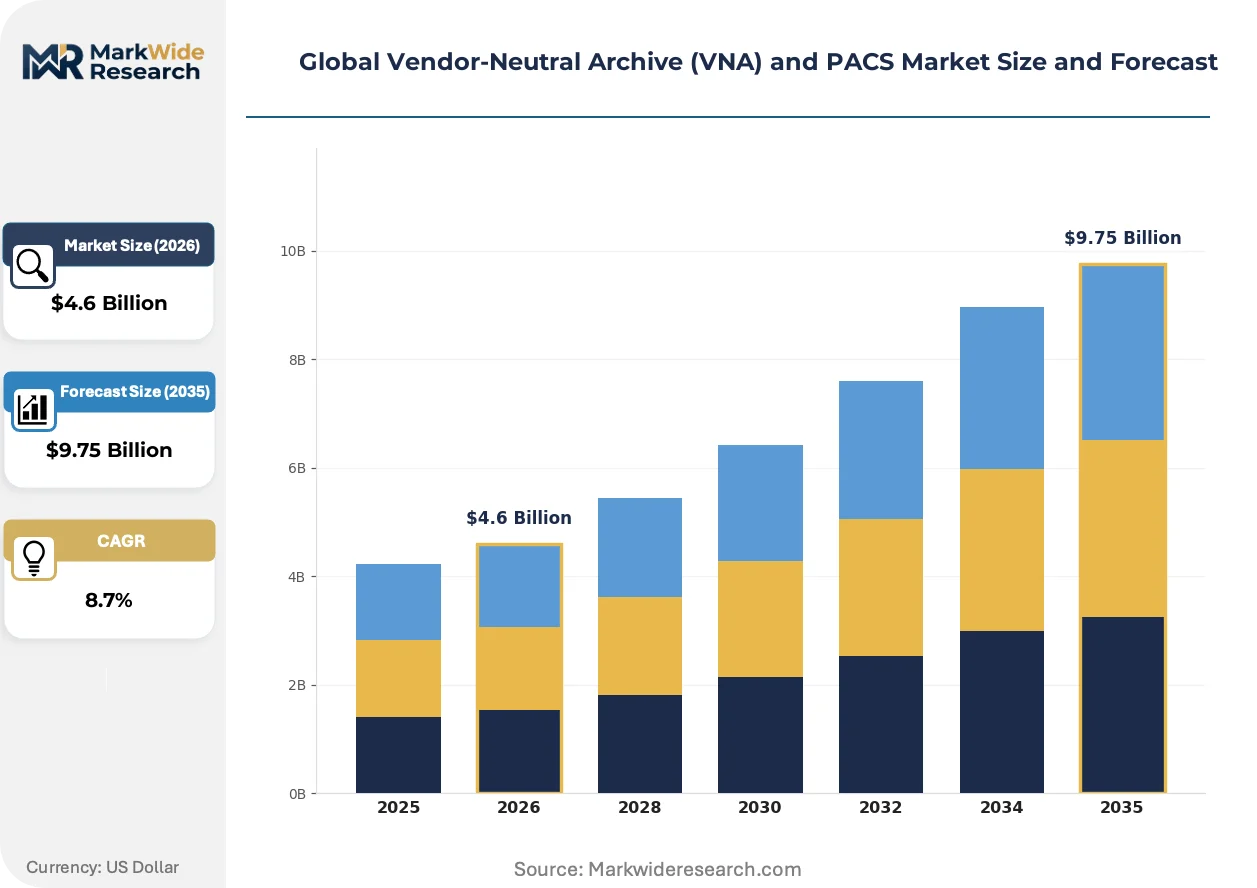
| Market Size in 2026 | $4.6 Billion |
| Market Size in 2035 | $9.75 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Edge Solution Type: Vendor-Neutral Archive, Picture Archiving and Communication System, Integrated PACS, Advanced Visualization Application: Radiology, Cardiology, Orthopedics, Oncology, Neurology End User: Hospitals, Diagnostic Centers, Specialty Clinics, Research Institutions |
| Companies Covered | Agfa-Gevaert Group, GE Healthcare, FUJIFILM Holdings Corporation, Sectra AB, Koninklijke Philips N.V., Siemens Healthineers AG, Hyland Software, Inc., Canon Medical Systems Corporation, Intelerad Medical Systems Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vendor-Neutral Archive (VNA) and PACS Market Shifts & Advancements
Artificial intelligence integration and subscription commercial models are restructuring how imaging informatics capabilities are delivered and consumed across health system tiers.
DICOMweb-based image exchange protocols are migrating from experimental implementations to production-grade deployments. Regional health information exchanges in the United States and Nordic hospital networks adopt these RESTful interfaces to replace legacy VPN-dependent transfer mechanisms. This migration from proprietary network architectures is compressing the addressable market for traditional PACS broker middleware vendors.
The EU Medical Device Regulation's software-as-medical-device classification requirements impose conformity assessment obligations on diagnostic visualization modules embedded within VNA platforms. European notified bodies have extended review timelines for AI-augmented workflow tools, delaying product launches by six to eighteen months. German and French hospital procurement committees now require MDR certification documentation as mandatory evaluation criteria, filtering vendor pools.
Hospital capital committees now favor operational expenditure models that transfer infrastructure lifecycle risk to vendors. Subscription contracts with guaranteed uptime service-level agreements displace perpetual license purchases with separate maintenance agreements in United States integrated delivery networks. This preference shift is most visible in California and Texas health systems where private equity-backed consolidation has centralized IT governance functions.
Global Vendor-Neutral Archive (VNA) and PACS Market Segmentation
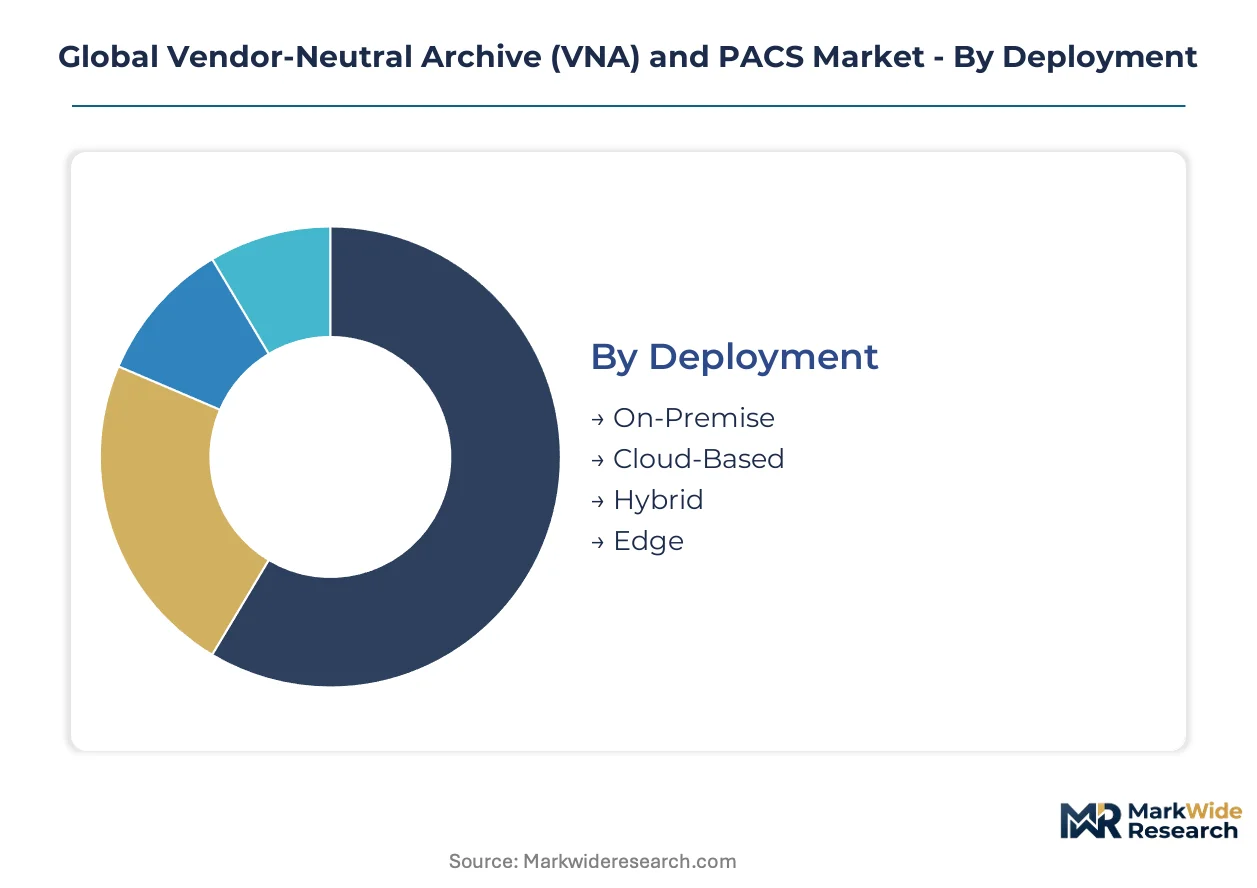
Segmentation of the Global Vendor-Neutral Archive (VNA) and PACS Market reveals distinct procurement patterns across infrastructure configurations, clinical domains, and institutional tiers. Each dimension carries specific interoperability requirements and compliance obligations that reshape vendor competitive positioning.
Deployment:
Cost tier differentiation separates capital-intensive perpetual ownership from operational expenditure models that transfer infrastructure risk to vendors.
- On-Premise:Hardware-resident installations within hospital data centers deliver maximum data sovereignty control. German university hospitals and Japanese national medical centers specify on-premise configurations to satisfy BSI cloud security standards and METI data localization guidelines.
- Cloud-Based:Multi-tenant SaaS architectures eliminate capital expenditure cycles and enable elastic storage scaling. United States integrated delivery networks in California and Texas are rotating procurement toward subscription contracts with guaranteed uptime SLAs.
- Hybrid:Split architectures maintain latency-sensitive modalities at edge nodes while archiving historical studies to centralized cloud repositories.
- Edge:Containerized deployments co-located with imaging equipment address real-time diagnostic workflow requirements.
On-Premise holds installed capacity. Cloud-Based is rotating up the share rankings.
Solution Type:
Application maturity varies sharply between established departmental systems and emerging enterprise consolidation platforms.
- Vendor-Neutral Archive:Centralized DICOM repositories decouple storage from acquisition modalities to enable longitudinal patient imaging records. Multi-site hospital networks in Germany deploy VNA infrastructure to unify radiology, cardiology, and pathology workflows under single governance.
- Picture Archiving and Communication System:Traditional departmental archives remain entrenched in mid-size United States hospitals where migration complexity stalls replacement timelines.
- Integrated PACS:Bundled hardware-software configurations anchor vendor relationships through diagnostic equipment tie-ins.
- Advanced Visualization:AI-augmented diagnostic layers require standardized image repositories that legacy siloed systems cannot support.
Picture Archiving and Communication System retains legacy dominance. Vendor-Neutral Archive is climbing the fastest as enterprise imaging consolidation accelerates.
Application:
Clinical volume concentration determines storage throughput requirements and visualization sophistication levels.
- Radiology:CT and MRI modalities generate the highest DICOM study volumes with established workflow integration. United States health systems face CMS-promulgated data-sharing requirements that accelerate decommissioning of proprietary radiology archives.
- Cardiology:CATH lab and echocardiography workflows demand specialized hanging protocols and measurement tools. German cardiology departments maintain independent budget authority, complicating enterprise-wide procurement decisions.
- Orthopedics:3D reconstruction and surgical planning applications drive advanced visualization module attachment.
- Oncology:Longitudinal imaging comparison across treatment cycles requires robust prior study retrieval capabilities.
- Neurology:Functional MRI and PET neuroimaging impose specialized processing pipeline requirements.
Radiology holds installed capacity. Cardiology is rotating up the share rankings.
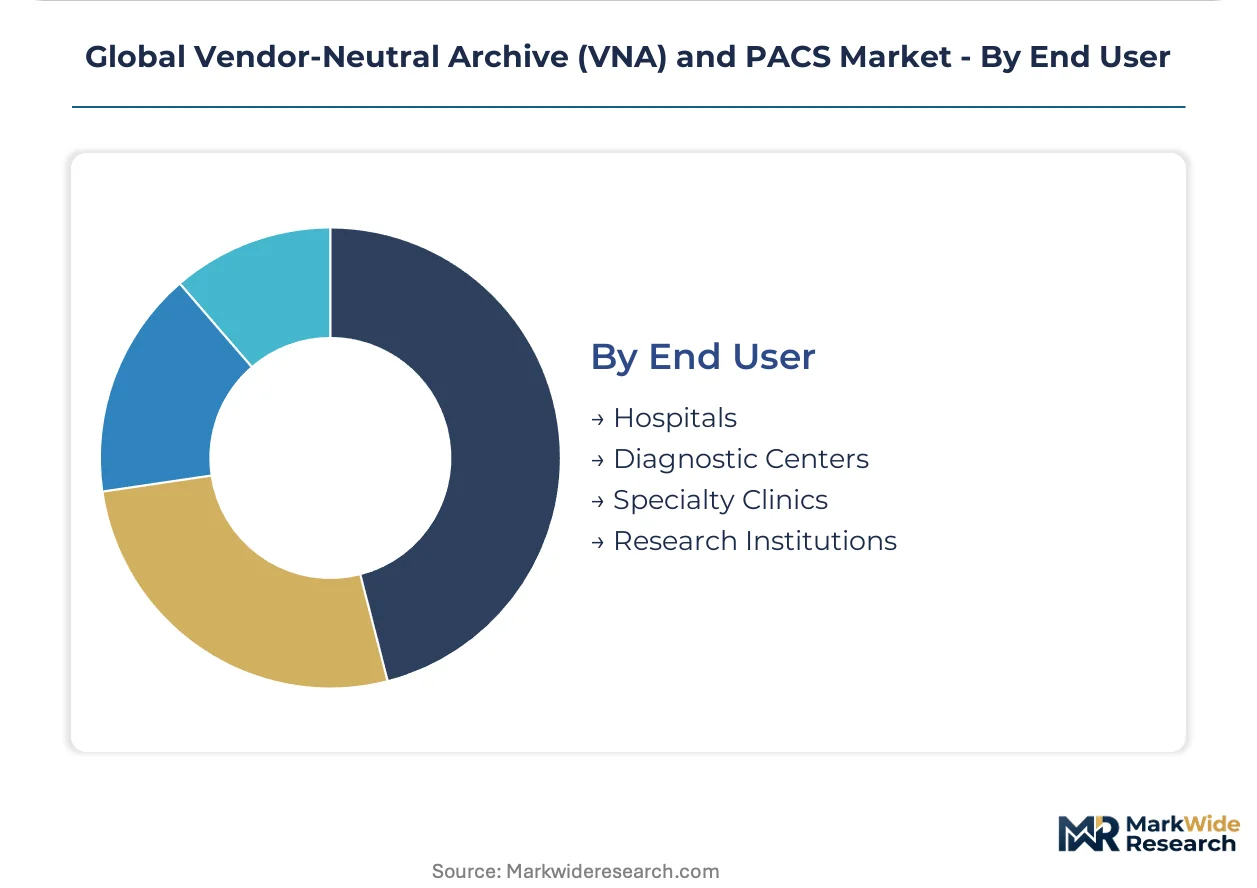
End User:
Customer type shapes contract scale, integration complexity, and regulatory scrutiny intensity.
- Hospitals:Enterprise-scale deployments across radiology, cardiology, and pathology departments command the largest contract values. Prefectural hospital consortia in Japan outside Tokyo and Osaka remain underpenetrated by enterprise VNA vendors.
- Diagnostic Centers:High-throughput outpatient imaging facilities prioritize rapid study distribution and teleradiology connectivity.
- Specialty Clinics:Focused orthopedics and cardiology practices seek modular solutions with minimal IT infrastructure overhead.
- Research Institutions:University medical centers require de-identification pipelines and multi-site collaboration tools for clinical trial imaging.
Hospitals hold installed capacity. Diagnostic Centers is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
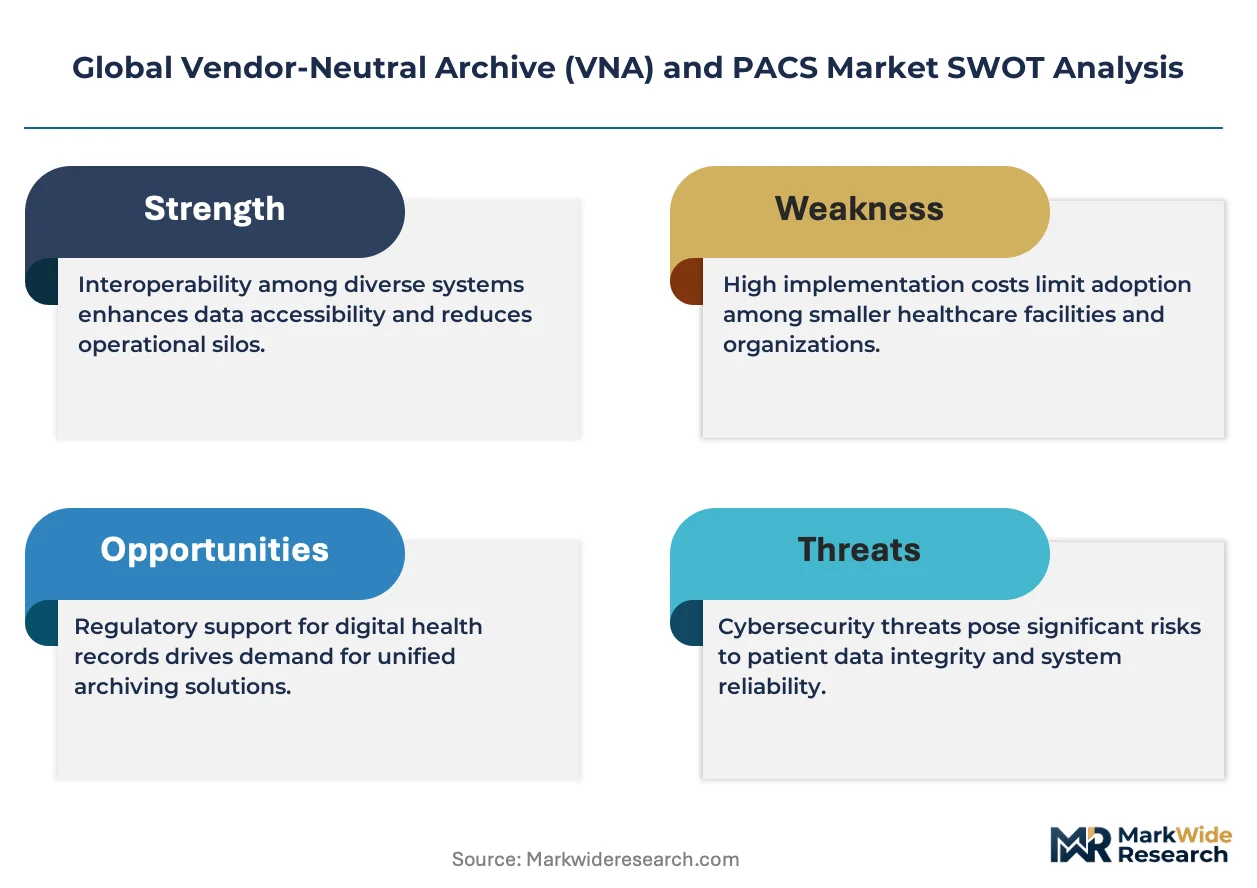
Pricing power concentrates in German university hospital networks, while United States integrated delivery networks extract volume discounts through centralized procurement consortia.
United States
CMS interoperability mandates and private equity-backed health system consolidation drive enterprise VNA procurement. FDA 21 CFR Part 820 quality system regulations govern software-as-medical-device classifications for diagnostic imaging platforms. California and Texas IDNs rotate procurement toward subscription contracts with guaranteed uptime SLAs.
Germany
Multi-site hospital networks deploy centralized VNA infrastructure to unify radiology, cardiology, and pathology workflows. BSI cloud security standards impose localization requirements that inflate total cost of ownership for cross-border deployments. Bavarian university hospitals specify on-premise configurations to satisfy stringent data sovereignty controls.
Japan
Prefectural hospital consortia outside Tokyo and Osaka remain underpenetrated by enterprise VNA vendors. PMDA and METI coordinate digital health standards that influence imaging informatics procurement specifications for university hospitals. Kansai region medical centers advance enterprise imaging consolidation strategies with hybrid deployment architectures.
United Kingdom
NHS long-term plan commitments accelerate decommissioning of proprietary departmental archives in favor of vendor-neutral repositories. GDPR and EU MDR impose conformity and data governance obligations on European deployments. London and Southeast England health systems prioritize cloud-native architectures with elastic storage scaling.
France
Regional health information exchanges adopt DICOMweb-based image exchange protocols to replace legacy VPN-dependent transfer mechanisms. ANSM and CNIL coordinate medical device and data protection oversight for imaging informatics deployments. Paris and Île-de-France university hospitals require MDR certification documentation as mandatory evaluation criteria.
Global Vendor-Neutral Archive (VNA) and PACS Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying interoperability modules and visualization engines. Market structure consolidates around diagnostic equipment manufacturers with captive software portfolios and independent software vendors with vendor-agnostic positioning. Three archetypes dominate: imaging modality OEMs with bundled offerings, pure-play VNA specialists with interoperability breadth, and IT infrastructure vendors with cloud-native architectures. Competitive moves concentrate on strategic partnerships for AI-augmented workflow layers and geographic expansion through regional system integrators.
Within the integrated systems tier, GE Healthcare leverages its installed base of diagnostic equipment to anchor hybrid deployment conversations. Siemens Healthineers AG differentiates through AI-native workflow layers embedded within its imaging informatics stack. FUJIFILM Holdings Corporation extends its position from film and chemistry origins into cloud-native VNA infrastructure for mid-size hospital networks.
| Leading Market Players |
|---|
| Agfa-Gevaert Group |
| GE Healthcare |
| FUJIFILM Holdings Corporation |
| Sectra AB |
| Koninklijke Philips N.V. |
| Siemens Healthineers AG |
| Hyland Software, Inc. |
| Canon Medical Systems Corporation |
| Intelerad Medical Systems Inc. |
| Others |
Supply & Pricing Matrix
Cloud infrastructure concentration among United States hyperscalers anchors margin distribution downstream toward software vendors with native SaaS architectures rather than hardware-dependent integrators. This upstream compute-storage concentration compresses differentiation for on-premise system bundlers while elevating pricing power for vendors controlling AI-augmented workflow layers.
Pricing Analysis
Configured-to-order enterprise deployments command premiums exceeding standard SaaS tiers by embedding hybrid edge nodes and custom DICOM migration services. Subscription contracts with guaranteed uptime SLAs now dominate United States integrated delivery network procurement, though German university hospitals resist this shift due to BSI cloud security compliance costs. Price differentiation hinges on FDA 510(k) certification tier for diagnostic visualization modules and volume scale across multi-site deployments. Pricing pressure stems from cloud-native entrants undercutting perpetual license maintenance rates, squeezing legacy PACS vendors most acutely in mid-size hospital segments where capital committees prioritize operational expenditure predictability.
Supply Chain Analysis
Taiwanese server OEMs and United States hyperscale data center operators hold concentrated manufacturing capacity for imaging informatics infrastructure. Hardware components draw from South Korean memory suppliers and Chinese optical storage manufacturers, while software development rests on Indian engineering services clusters. Single-source vulnerability runs through specialized DICOM parsing libraries controlled by a narrow vendor set. Distribution runs through regional system integrators in Germany and Japan who localize deployment and compliance documentation for hospital procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise imaging consolidation represents early-cycle expansion as multi-site hospital networks accelerate decommissioning of departmental silos. CMS interoperability mandates and EU MDR software-as-medical-device classifications pull replacement demand forward across United States and European health systems.
For Market Incumbents: Insulate installed base relationships through backward integration into edge computing hardware and captive AI training data pipelines. GE Healthcare and Siemens Healthineers should deepen diagnostic equipment-software bundling to lock out pure-play VNA specialists. Cloud-native entrants threaten margin pools in mid-size United States hospitals where subscription pricing resets customer lifetime value calculations. For New Entrants and Emerging Players: Pursue prefectural hospital consortia in Japan outside Tokyo and Osaka, where enterprise VNA penetration remains underdeveloped relative to university medical centers. Cardiology workflow unification offers the most penetrable application segment given persistent departmental budget autonomy that stalls radiology-centric vendors. A teleradiology connectivity-first go-to-market angle bypasses entrenched PACS replacement complexity. For Investors and Strategic Acquirers: Capital is best deployed toward pure-play VNA specialists with proven DICOMweb interoperability stacks and established hospital system partnerships in Germany or the United States. Long-term viability across the analysis window favors vendors controlling both cloud-native architectures and regulatory certification pathways for AI-augmented diagnostic modules. The signal to watch is FDA breakthrough device designation velocity for imaging informatics platforms, indicating which vendors can compress MDR review timelines in Europe.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | GE Healthcare leverages diagnostic equipment installed base to anchor hybrid deployment conversations with unified hardware-software bundles. |
| Strategic Partnership | Siemens Healthineers embeds AI-native workflow layers through collaborations with radiology AI developers requiring standardized image repositories. |
| Geographic Expansion | FUJIFILM Holdings Corporation extends film and chemistry origins into cloud-native VNA infrastructure for underpenetrated Japanese prefectural networks. |
| Acquisition of Specialist Firm | Consolidation targets DICOMweb middleware vendors as RESTful protocols displace legacy VPN-dependent transfer mechanisms in Nordic exchanges. |
| Product Launch | Containerized edge-to-cloud orchestration platforms enable tiered latency guarantees for latency-sensitive CATH lab and surgical planning modalities. |
Research Methodology
Operator-level perspectives from hospital CIOs, radiology department heads, GPO contracts managers, and biomedical engineers anchored the qualitative base for this analysis. Primary interviews combined with secondary validation across FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EU MDR notified body documentation. Bottom-up deployment modeling across on-premise, cloud-based, hybrid, and edge configurations triangulated against top-down health system IT expenditure tracking.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation dimensions spanning deployment architecture, solution type, clinical application, and institutional tier. CAGRs derived from elasticity-adjusted replacement cycle compression and enterprise imaging consolidation penetration curves. Forecast inputs incorporated DICOMweb protocol adoption velocity and AI-augmented workflow module attachment rates.
The forecast holds incumbent behavior within observed patterns; aggressive cloud-native pricing moves by hyperscaler-backed entrants or accelerated FDA software-as-medical-device reclassifications would shift outcomes. Quarterly review of hospital capital committee procurement minutes and notified body MDR review timeline disclosures is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Digital Breast Tomosynthesis (DBT) Equipment Market
Medical Imaging
Global CT Scanners Market
Medical Imaging
Magnetic Resonance Imaging (MRI) Contrast Agents Market
Medical Imaging
MR-Linac and Image-Guided Radiotherapy QA Measurement Systems Market
Medical Imaging
Global Positron Emission Tomography [PET] Scanners Market
Medical Imaging
Interventional X - Ray Systems Market
Medical Imaging
Cone Beam CT Scanner Market
Medical Imaging
Global 3D Ultrasound Market
Medical Imaging
Italy Digital X-Ray Market
Medical Imaging
Global Medical Imaging Workstation Market
Medical Imaging
Global Image-Guided Radiation Therapy (IGRT) Market
Medical Imaging
Breast Imaging Market
Medical Imaging
Europe Nuclear Medicine Market
Medical Imaging
Brazil Nuclear Imaging Market
Medical Imaging
C-Arms Market
Medical Imaging
Nuclear Magnetic Resonance Spectroscopy Market