
 Ga 68 DOTATOC Market | 2026-2036
Ga 68 DOTATOC Market Size, Share, and Industry Trends Forecast 2026-2036
Ga 68 DOTATOC Market Foresight
Buyer concentration among nuclear medicine departments is shifting from fragmented hospital networks toward centralized academic medical centers with cyclotron capabilities. Siemens Healthineers AG leverages its integrated PET-CT platform footprint to control distribution channels across major European markets. ITM Isotopen Technologien München AG anchors its position through captive isotope production, while Telix Pharmaceuticals competes via specialized radiopharmaceutical pipelines targeting somatostatin receptor imaging.
Ga 68 DOTATOC is a gallium-68 labeled somatostatin analog radiotracer synthesized through chelator-mediated radiolabeling of DOTA-Tyr3-octreotide, designed for positron emission tomography imaging of somatostatin receptor-positive neuroendocrine tumors. Its primary commercial purpose centers on superior diagnostic accuracy compared to conventional imaging modalities, enabling precise tumor localization and staging. Radiopharmaceuticals command the dominant product category due to stringent manufacturing requirements and limited producer authorization, while neuroendocrine tumor imaging anchors application demand with pancreatic tumor detection representing the fastest-expanding clinical segment. Deployment through hospital-based settings captures the majority of procedure volume, though mobile imaging units are gaining traction for rural access expansion.
FDA oversight of positron emission tomography agents under current good manufacturing practice standards shapes production facility investments and quality control protocols, while EMA's radiopharmaceutical guidelines under the EU Clinical Trials Regulation govern market access across European member states. Germany's national pharmaceutical regulator enforces additional batch-release requirements that filter smaller competitors from supply chains. Stakeholders must monitor evolving reimbursement decisions for theranostic pairing with lutetium-based therapies, as this linkage will determine future volume commitments from oncology clinics and research institutes.
Market Dynamics
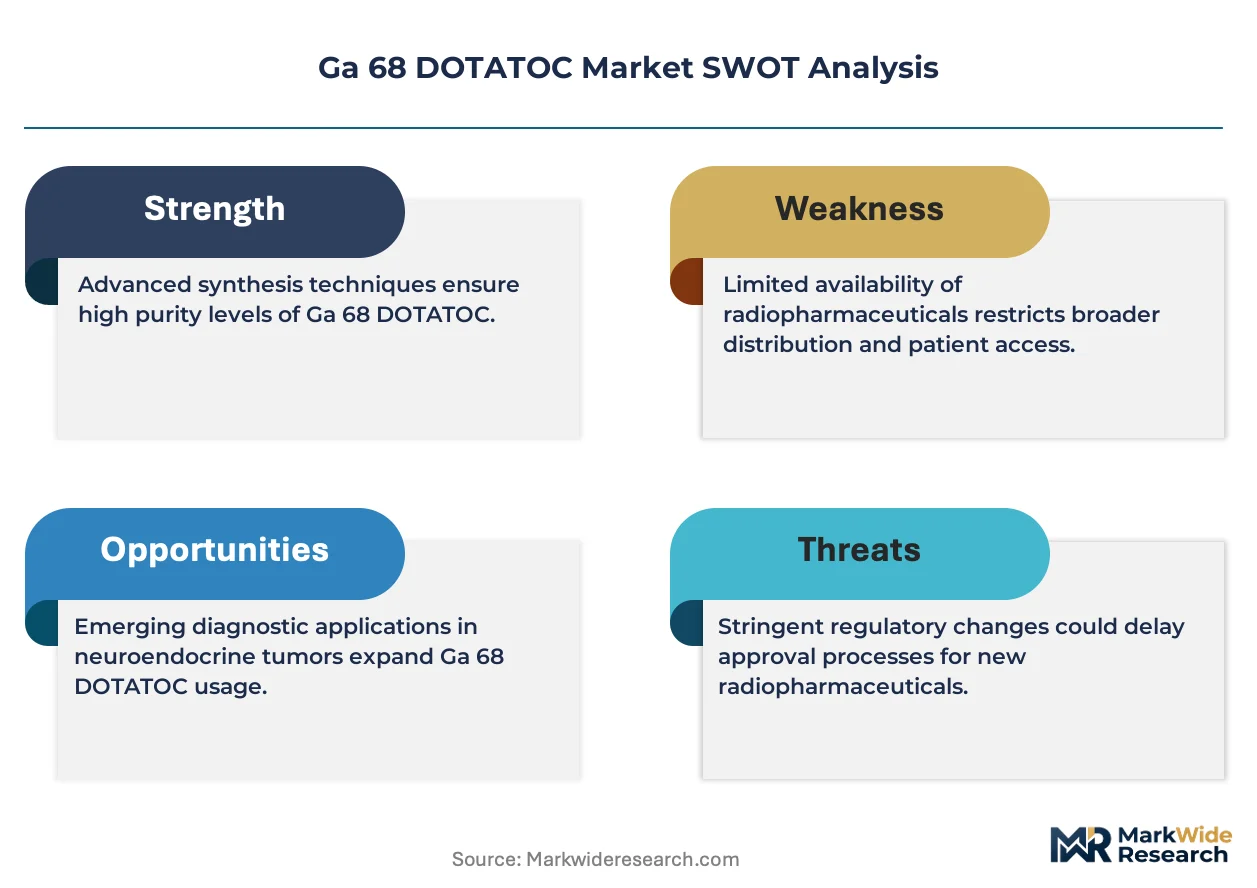
Regulatory convergence around theranostic pairing is compressing the competitive window for standalone diagnostic providers, forcing capital deployment into lutetium-177 production capabilities before reimbursement pathways fully mature.
Growth Catalysts
- FDA cGMP harmonization:Unified manufacturing standards for positron emission tomography agents are reducing facility duplication costs and accelerating multi-site licensing for radiopharmaceutical networks.
- Somatostatin receptor theranostics:Clinical validation of gallium-68 imaging as a predictive biomarker for lutetium-based therapy response is creating procedure bundling incentives across oncology departments.
- German cyclotron infrastructure:Dense regional coverage of isotope production facilities is enabling same-day radiotracer delivery to satellite diagnostic centers without on-site synthesis capability.
Market Restraints
- German BfArM batch-release requirements:Extended quality verification timelines for imported gallium-68 kits are limiting supply flexibility and favoring domestic producers with established regulatory relationships.
- Generator dependence:Concentrated germanium-68/gallium-68 generator manufacturing in Belgium and the Netherlands creates single-source vulnerability for European supply chains.
- Short half-life logistics:The 68-minute radioactive decay window of gallium-68 enforces rigid cold-chain distribution radii that exclude rural markets without mobile PET-CT deployment.
Strategic Opportunities
- Mobile imaging units:Truck-mounted PET-CT systems with onboard radiopharmaceutical preparation are extending neuroendocrine tumor detection into underserved regions of Spain and Italy.
- EMA centralized marketing authorization:Mutual recognition procedures for radiopharmaceuticals are streamlining cross-border commercialization and reducing national regulatory fragmentation.
- Artificial intelligence quantification:Machine learning-based standardized uptake value analysis is reducing inter-reader variability and enabling remote diagnostic interpretation.
Industry Challenges
- Radiochemist workforce scarcity:Specialized training programs for gallium-68 labeling and quality control are failing to match cyclotron facility expansion timelines.
- Reimbursement code alignment:Disconnected procedural coding for diagnostic imaging versus subsequent therapeutic dosing is fragmenting revenue capture across hospital departments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ga 68 DOTATOC Market |
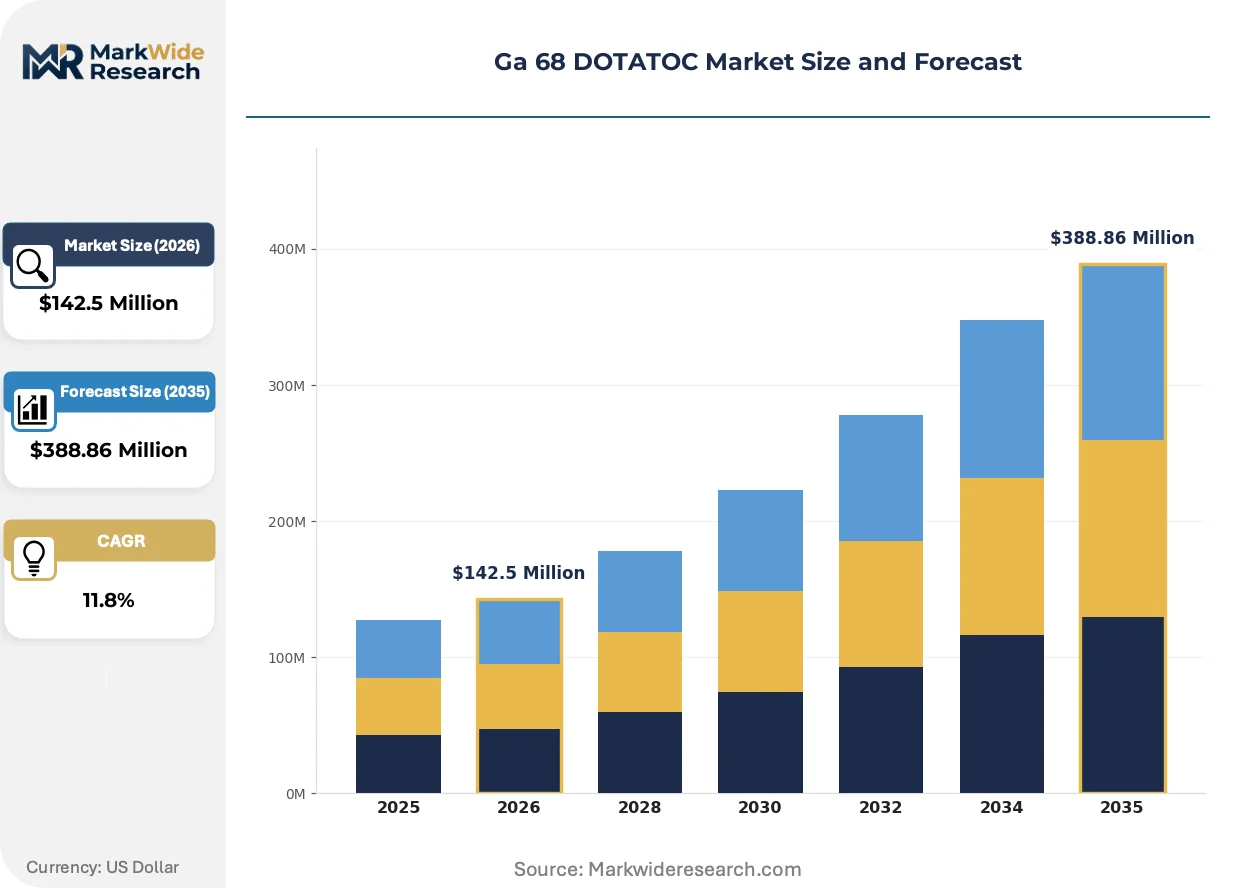
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $388.86 Million |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radiopharmaceuticals, Positron Emission Tomography Agents, Diagnostic Radiotracers, Somatostatin Analogs Application: Neuroendocrine Tumor Imaging, Pancreatic Tumor Detection, Prostate Cancer Diagnosis, Brain Tumor Visualization End User: Diagnostic Centers, Nuclear Medicine Departments, Oncology Clinics, Research Institutes Deployment: Hospital-Based, Standalone Clinics, Mobile Imaging Units, Academic Medical Centers |
| Companies Covered | Siemens Healthineers AG, ITM Isotopen Technologien München AG, Advanced Accelerator Applications, Telix Pharmaceuticals, IASON GmbH, HTA Co., Ltd., Peking Union Medical College Hospital, Radiomedix, RayzeBio, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ga 68 DOTATOC Market Shifts & Advancements
Automation in radiopharmaceutical synthesis is compressing production batch times while artificial intelligence applications are reshaping image interpretation workflows across nuclear medicine departments.
Cold-kit gallium-68 radiopharmaceutical formulations are consolidating manufacturing economics for hospital radiopharmacies. These lyophilized precursor vials enable on-site radiolabeling without dedicated cyclotron infrastructure. Community hospitals and smaller diagnostic centers are adopting this format to participate in neuroendocrine tumor imaging programs previously restricted to academic medical centers.
EMA's updated radiopharmaceutical guidelines under the EU Clinical Trials Regulation are standardizing investigational new drug requirements across member states. This framework reduces redundant national submissions for multi-center trials. Sponsors are restructuring clinical development programs to prioritize centralized regulatory pathways over fragmented national approvals.
Hospital procurement committees are consolidating vendor relationships for theranostic isotope pairs. Buyers are negotiating multi-year supply agreements that bundle gallium-68 diagnostic doses with lutetium-177 therapeutic allocations. This bundling pattern is most pronounced in German and French university hospital networks where integrated nuclear medicine and oncology departments control purchasing decisions.
Ga 68 DOTATOC Market Segmentation
Segmentation in the Ga 68 DOTATOC market reveals how regulatory complexity, clinical workflow integration, and infrastructure requirements fragment commercial opportunities across distinct buyer profiles and use cases. Understanding these divisions enables targeted positioning for manufacturers navigating heterogeneous nuclear medicine ecosystems.
Product Type:
FDA cGMP standards and EMA radiopharmaceutical guidelines impose tiered certification burdens that concentrate production authorization among segments with captive isotope supply or cold-kit manufacturing capabilities.
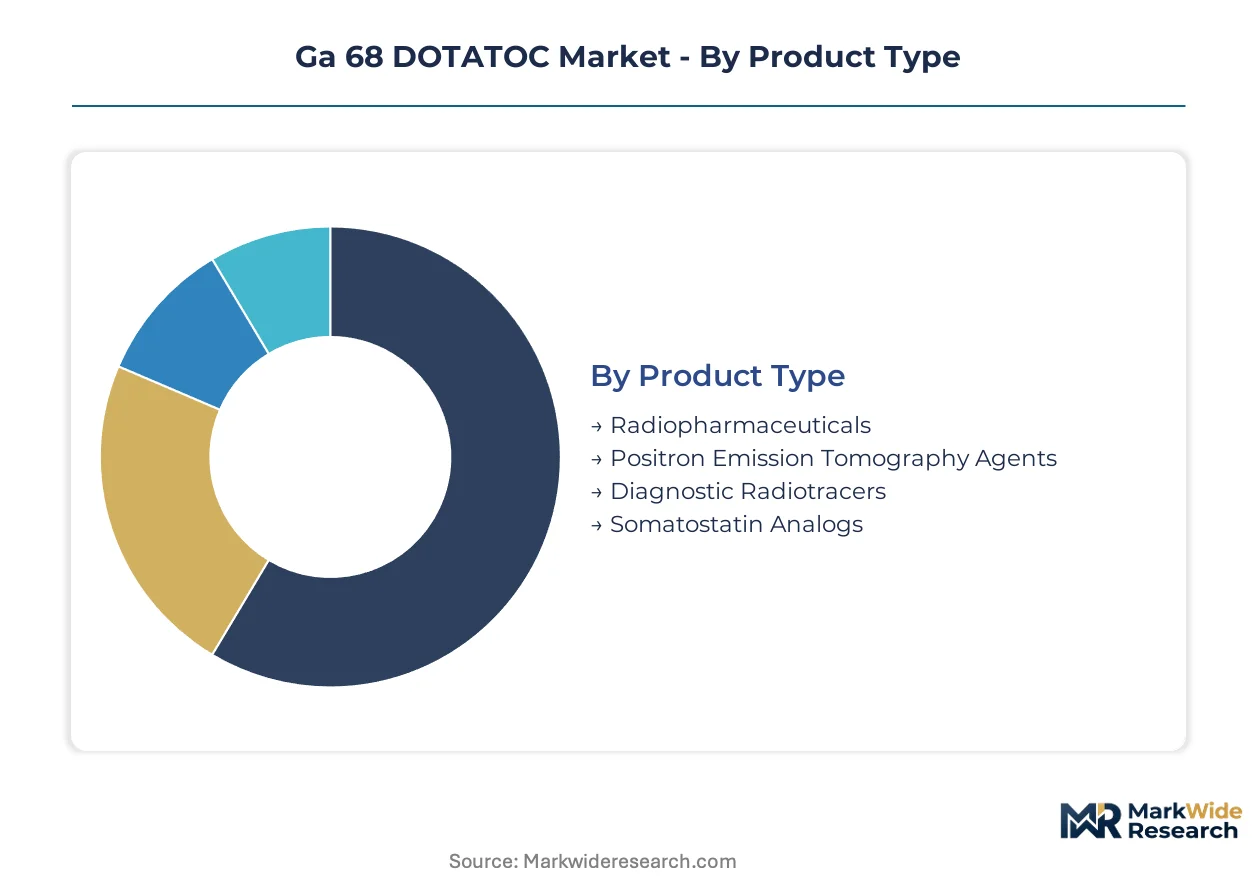
- Radiopharmaceuticals:Gallium-68 labeled compounds synthesized under sterile conditions with real-time quality release testing. Demand clusters in German university hospitals with integrated cyclotron infrastructure and established BfArM relationships. German BfArM batch-release timelines favor domestic producers with regulatory track records.
- Positron Emission Tomography Agents:Compounds optimized for PET-CT acquisition protocols with standardized uptake value quantification. Concentrated demand in US academic medical centers where FDA cGMP compliance costs filter smaller competitors. Reimbursement bundling with lutetium-177 therapies is reshaping procurement criteria.
- Diagnostic Radiotracers:Broad category encompassing tumor-targeting agents with chelator-mediated radiolabeling.
- Somatostatin Analogs:Peptide-based compounds binding somatostatin receptor subtypes 2 and 5 with high affinity.
Radiopharmaceuticals sits at the top of the volume ranking, with Positron Emission Tomography Agents climbing the fastest.
Application:
Clinical validation intensity and payer coverage thresholds create divergent margin profiles across oncology subspecialties, with pancreatic and neuroendocrine applications commanding premium positioning due to superior diagnostic accuracy claims.
- Neuroendocrine Tumor Imaging:Established indication with robust somatostatin receptor expression profiling. Demand concentrates in US and German tertiary referral centers where theranostic pairing with lutetium-177 Lu 177 DOTATATE is standardizing care pathways. FDA recognition of gallium-68 DOTATOC as a predictive biomarker is accelerating procedure volume.
- Pancreatic Tumor Detection:Fastest-expanding segment driven by superior sensitivity for small pancreatic neuroendocrine tumors versus conventional CT and MRI. German oncology networks are prioritizing this application for early-stage intervention decisions. EMA guidelines on radiopharmaceutical investigational use are streamlining multi-center trial access.
- Prostate Cancer Diagnosis:Emerging application competing with PSMA-targeted agents for receptor-positive phenotypes.
- Brain Tumor Visualization:Niche use case for meningioma characterization based on somatostatin receptor density.
Neuroendocrine Tumor Imaging commands the largest procedure base, with Pancreatic Tumor Detection expanding most quickly.
End User:
Procurement authority and capital deployment capacity separate institutional buyers, with integrated nuclear medicine departments capturing volume through theranostic bundling while standalone diagnostic centers rely on cold-kit formulations.
- Diagnostic Centers:Outpatient facilities with PET-CT capability but limited on-site radiochemistry. German satellite centers leverage regional cyclotron networks for same-day gallium-68 delivery without BfArM import delays.
- Nuclear Medicine Departments:Hospital-based units with radiopharmacy infrastructure and trained radiochemist staff. US academic centers dominate due to FDA cGMP facility investments and research protocol integration.
- Oncology Clinics:Community-based practices referring patients to imaging partners or deploying mobile PET-CT units.
- Research Institutes:Investigational use sites driving clinical validation for novel indications and theranostic combinations.
Nuclear Medicine Departments anchor revenue concentration, with Diagnostic Centers gaining share fastest through cold-kit adoption.
Deployment:
Fixed infrastructure versus mobile capability determines addressable market radius, with hospital-based settings capturing complex cases while mobile units extend reach to underserved geographies facing radiochemist scarcity.
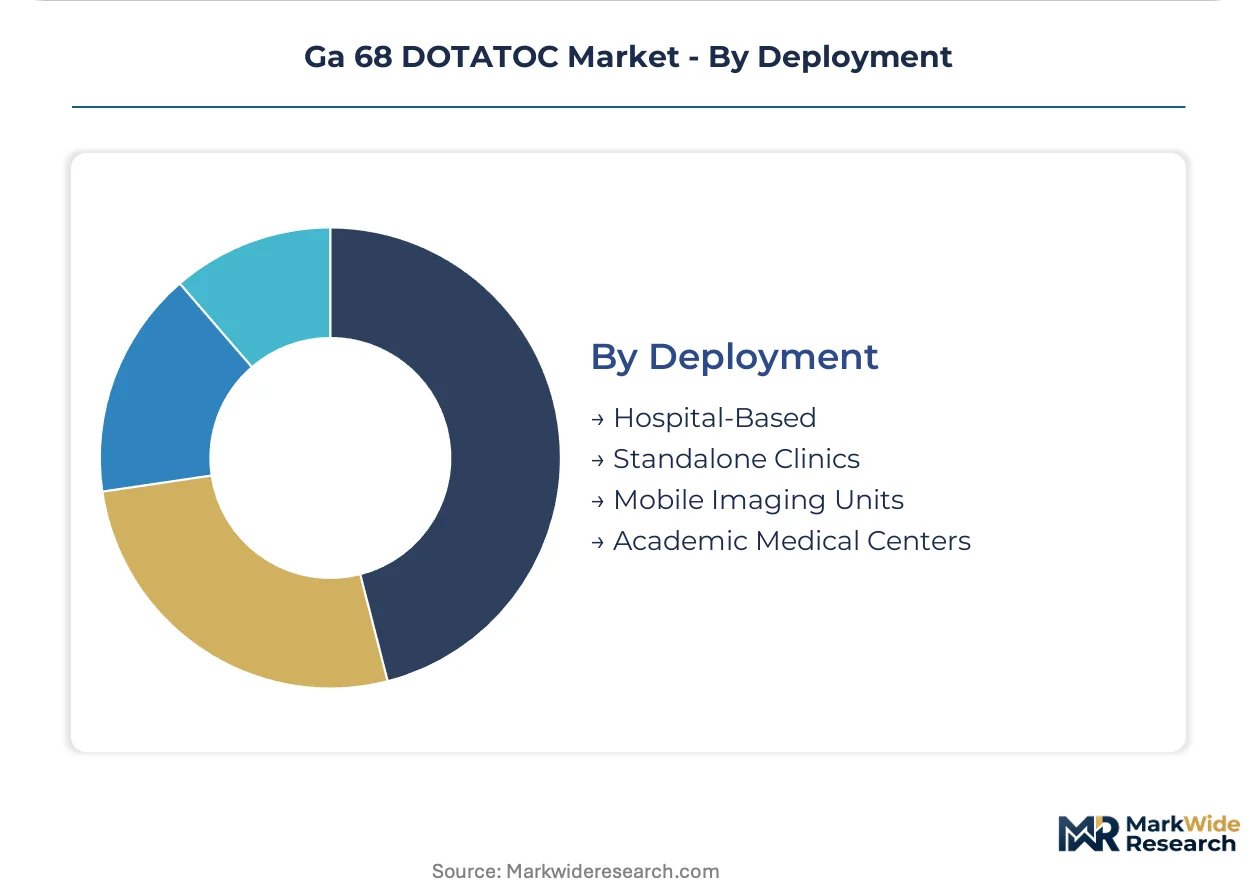
- Hospital-Based:Integrated delivery within tertiary care facilities with on-site cyclotron or generator infrastructure. German university hospitals command this segment through captive isotope production and BfArM regulatory efficiency.
- Standalone Clinics:Independent diagnostic facilities dependent on external radiopharmaceutical supply chains.
- Mobile Imaging Units:Truck-mounted PET-CT systems with onboard radiopharmacy preparation. Spain and Italy are deploying these units for rural neuroendocrine tumor detection where fixed infrastructure is uneconomical. The 68-minute gallium-68 half-life enforces strict geographic radius constraints.
- Academic Medical Centers:Research-intensive institutions with dual diagnostic and therapeutic isotope capabilities.
Hospital-Based deployment retains volume leadership, with Mobile Imaging Units showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's cyclotron density enables same-day gallium-68 delivery networks that the United States has yet to replicate at equivalent geographic coverage, while both markets diverge sharply from emerging economies lacking PET-CT infrastructure depth.
United States
Academic medical centers in Boston, Houston, and Los Angeles drive procedure volume through integrated theranostic programs pairing gallium-68 imaging with lutetium-177 therapy. FDA cGMP compliance costs for positron emission tomography agents filter smaller competitors from multi-site licensing. The Mayo Clinic Rochester campus anchors a regional hub-and-spoke model extending cold-kit radiopharmaceutical access to satellite diagnostic centers across the Upper Midwest.
Germany
University hospital networks in Munich, Heidelberg, and Essen command neuroendocrine tumor imaging volume through captive isotope production and established BfArM regulatory relationships. The national pharmaceutical regulator enforces batch-release requirements that favor domestic producers with quality verification track records. Baden-Württemberg's dense cyclotron infrastructure enables just-in-time radiotracer delivery to outpatient diagnostic centers lacking on-site synthesis capability.
France
Parisian teaching hospitals and Lyon-based nuclear medicine departments are consolidating vendor relationships for theranostic isotope pair bundling. ANSM oversight of radiopharmaceutical manufacturing shapes facility investment decisions across the Île-de-France region. The Gustave Roussy Institute in Villejuif anchors clinical validation networks for somatostatin receptor imaging protocols extending into community oncology practices.
Italy
Mobile imaging units are penetrating rural neuroendocrine tumor detection gaps in Sicily, Calabria, and the Apennine spine where fixed PET-CT infrastructure remains uneconomical. EMA centralized marketing authorization procedures under the EU Clinical Trials Regulation are streamlining cross-border supply chain integration for radiopharmaceutical networks. Milan's Policlinico di Milano serves as a northern hub coordinating cold-kit distribution to satellite centers in Lombardy and Veneto.
Spain
Barcelona and Madrid academic centers are deploying truck-mounted PET-CT systems with onboard radiopharmacy preparation to extend somatostatin receptor imaging into underserved autonomous communities. The country's national pharmaceutical regulator enforces quality standards aligned with EMA guidelines that govern multi-center trial access for novel radiotracer indications. Hospital Clínic de Barcelona anchors a regional network coordinating generator supply logistics for gallium-68 production across Catalonia.
Ga 68 DOTATOC Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across a market structure consolidating around integrated PET-CT platform control and captive isotope production capabilities. Siemens Healthineers AG leverages its imaging hardware footprint to shape distribution channel access, while ITM Isotopen Technologien München AG anchors supply security through backward integration into generator manufacturing. Three archetypes dominate: diversified medical technology conglomerates with integrated diagnostics portfolios, specialized radiopharmaceutical producers with cyclotron infrastructure, and emerging biotechnology firms with theranostic pipeline assets. Competitive moves center on multi-year supply agreement bundling of diagnostic and therapeutic isotopes, plus strategic partnerships securing germanium-68 generator supply commitments.
Among Germany-based radiopharmaceutical specialists, ITM Isotopen Technologien München AG and IASON GmbH occupy positions defined by regulatory track records with BfArM and EMA frameworks. Telix Pharmaceuticals represents the theranostic-focused archetype, with pipeline concentration on somatostatin receptor imaging and lutetium-based therapy pairing. Siemens Healthineers AG exemplifies the diversified conglomerate model, leveraging PET-CT installed base density to influence procurement criteria across hospital networks. These three entities collectively illustrate how competitive positioning stratifies across infrastructure control, regulatory relationships, and therapeutic pipeline depth.
| Leading Market Players |
|---|
| Siemens Healthineers AG |
| ITM Isotopen Technologien München AG |
| Advanced Accelerator Applications |
| Telix Pharmaceuticals |
| IASON GmbH |
| HTA Co., Ltd. |
| Peking Union Medical College Hospital |
| Radiomedix |
| RayzeBio |
| Others |
Supply & Pricing Matrix
Theranostic bundling negotiations by German and French university hospital networks are compressing standalone diagnostic margins and forcing suppliers to restructure cost bases around multi-year isotope pair commitments.
Pricing Analysis
Capacity additions in Germany are reshaping price floors for gallium-68 DOTATOC as domestic cyclotron networks reduce import dependency and BfArM batch-release premiums. Contract-based long-term offtake agreements dominate, with price differentiation resting on FDA cGMP certification tier and captive generator supply security. Pricing pressure stems from cold-kit formulations enabling smaller diagnostic centers to bypass traditional radiopharmacy infrastructure. Community hospitals exhibit highest price sensitivity; academic medical centers with integrated theranostic programs demonstrate lowest sensitivity due to bundled revenue capture.
Supply Chain Analysis
Radiochemist workforce scarcity across Belgium and the Netherlands is constraining generator manufacturing expansion and tightening gallium-68 precursor availability. Supply concentrates in Germany, Belgium, and the United States, with raw material dependencies on germanium-68/gallium-68 generators, DOTA-chelator peptides, and pharmaceutical-grade sterile water. Single-source vulnerability in concentrated generator manufacturing creates structural risk. Distribution runs through regional cyclotron hub-and-spoke networks with same-day cold-chain delivery to satellite diagnostic centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market hinges on automation-driven production cost compression and premium-tier positioning through theranostic pairing validation.
For Market Incumbents: Acquire specialized radiochemistry workforce pipelines and captive generator manufacturing assets to defend against cold-kit disintermediation. Siemens Healthineers AG and ITM Isotopen Technologien München AG should deepen cyclotron infrastructure control in Baden-Württemberg and Bavaria to maintain BfArM regulatory efficiency advantages. Investment in lutetium-177 production capabilities secures bundling leverage before reimbursement pathways fully mature. For New Entrants and Emerging Players: EMA centralized marketing authorization under the EU Clinical Trials Regulation opens a window for streamlined multi-country entry without redundant national submissions. Target mobile imaging unit deployment in rural Spain and Italy where fixed PET-CT infrastructure remains uneconomical and radiochemist scarcity excludes incumbent competition. Partner with established generator suppliers to secure precursor access without vertical infrastructure investment. For Investors and Strategic Acquirers: Asymmetric upside sits with theranostic-focused biotechnology firms with pipeline concentration on somatostatin receptor imaging and lutetium-based therapy pairing. Long-term viability over the next decade depends on regulatory validation of gallium-68 as a predictive biomarker for therapy response. Watch for reimbursement code alignment between diagnostic imaging and therapeutic dosing as the critical inflection signal for volume commitment sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA cGMP harmonization accelerates multi-site licensing for radiopharmaceutical networks. |
| Manufacturing Scale-Up | Automation in radiopharmaceutical synthesis compresses batch times and reduces radiochemist dependency. |
| Long-term Supply Agreement | Multi-year isotope pair bundling secures volume commitments from oncology departments. |
| Pipeline Diversification | Theranostic pairing with lutetium-177 therapies expands addressable market beyond standalone diagnostics. |
| Geographic Expansion | Mobile imaging units extend neuroendocrine tumor detection into underserved rural regions. |
Research Methodology
Bottom-up nuclear medicine department modeling reconciled against top-down radiopharmaceutical production tracking forms the analytical core of this study. Primary interviews with cyclotron facility managers, radiochemists, hospital procurement committees, and nuclear medicine department heads combined with secondary validation from FDA filings, EMA submission databases, BfArM batch-release records, and hospital procurement databases. Triangulation between demand-side procedure volume estimates and supply-side isotope production capacity ensures cross-verified outputs.
Input-output matrices segment volume and value projections across product type, application, end user, and deployment mode dimensions throughout the forecast period. CAGRs derive from procedure volume trajectories, reimbursement pathway maturation timelines, and cyclotron facility expansion schedules. Forecast inputs incorporate theranostic pairing adoption rates, cold-kit formulation penetration, and mobile imaging unit deployment curves.
Revisions become necessary when reimbursement decisions for theranostic pairing diverge from modeled assumptions or when generator supply disruptions alter radiotracer availability. Material deviation in FDA or EMA regulatory timelines, BfArM batch-release requirement changes, or radiochemist workforce expansion shortfalls warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Fluoroscopy C-Arms Market
Medical Imaging
Pre-Clinical Imaging System Market
Medical Imaging
3D Medical and Surgical Imaging Platform Market
Medical Imaging
Japan Diagnostic Imaging Market
Medical Imaging
Cranial Doppler Market
Medical Imaging
Germany Digital Pathology Market
Medical Imaging
Global Contrast-Enhanced Ultrasound Market
Medical Imaging
Positron Emission Tomography Devices (PET) Market
Medical Imaging
United States Computed Tomography Market
Medical Imaging
Global Computer Vision in Healthcare Market
Medical Imaging
South America Mammography Market
Medical Imaging
Medical Image Analysis Software Market
Medical Imaging
Global Cardiac Imaging Software Market
Medical Imaging
China VNA and PACS Market
Medical Imaging
Vendor Neutral Archive Market
Medical Imaging
US Contrast Media Market