
 Dental Diagnostic Imaging Equipment Market | 2026-2036
Dental Diagnostic Imaging Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Diagnostic Imaging Equipment Market Insights
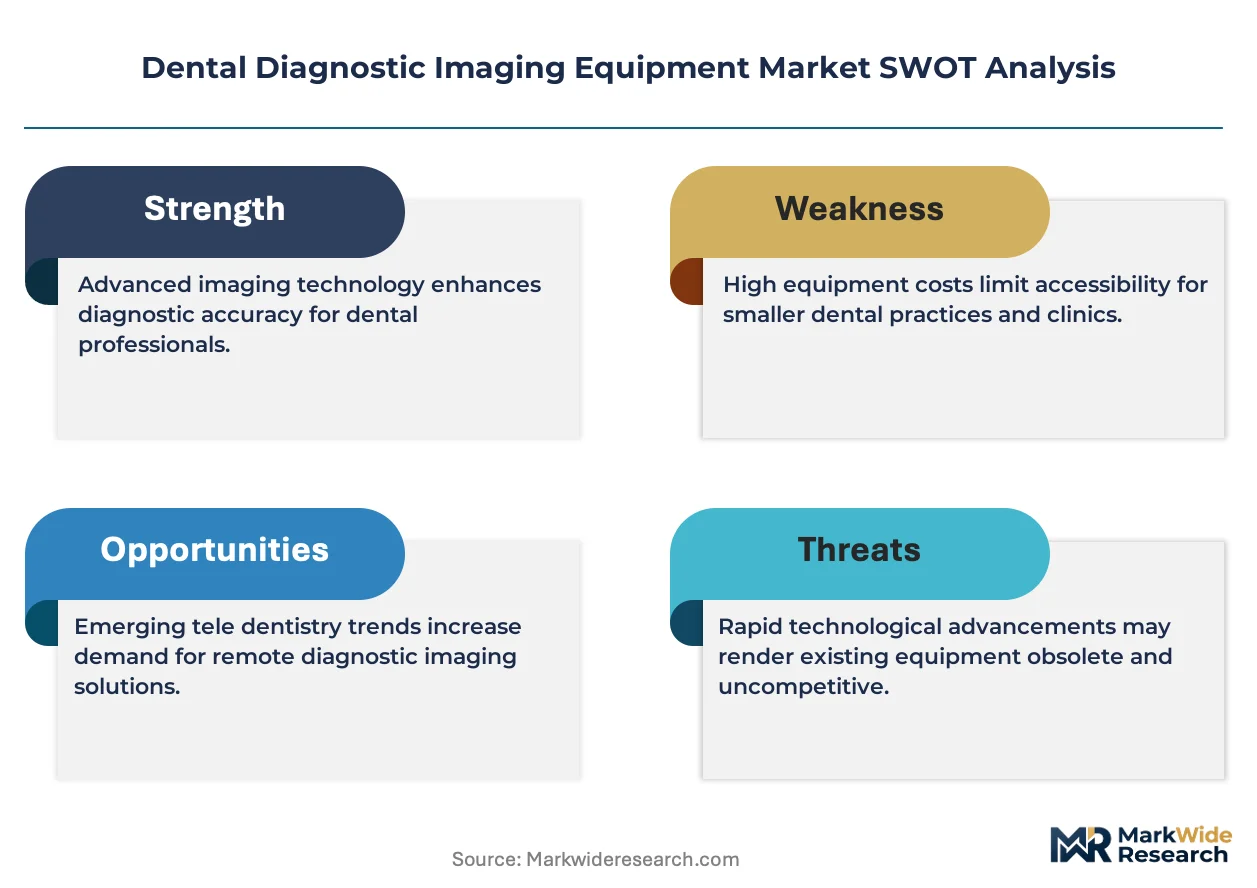
Radiologic technologist shortages across developed markets is bifurcating the competitive landscape between automated digital workflows and labor-intensive film-based alternatives. Dentsply Sirona leverages its integrated CAD/CAM and imaging ecosystem to capture recurring software revenue from dental offices. Planmeca Oy anchors its position through Finnish-designed open-architecture software that interoperates with third-party practice management systems. Vatech Co., Ltd. specializes in compact cone beam CT units engineered for space-constrained Asian clinics.
Dental diagnostic imaging equipment encompasses intraoral and extraoral systems that capture anatomical structures using ionizing radiation, digital sensors, or optical scanning at resolutions spanning microns to millimeters, primarily enabling clinicians to detect caries, plan implant placement, and assess periodontal bone loss. Cone beam CT and 3D X-ray systems command premium positioning due to their indispensable role in oral surgery and orthodontic treatment planning where volumetric accuracy determines clinical outcomes. Digital imaging technology dominates replacement demand as film-based modalities retreat to cost-sensitive rural clinics and legacy installations where capital constraints delay modernization.
FDA 510(k) clearances govern new device entry in the United States while the EU MDR imposes stricter clinical evidence requirements on CBCT manufacturers seeking CE marking for European distribution. The EPA administers radiation safety standards for X-ray emitting equipment, and state dental boards enforce operator certification that shapes training and service attach rates. Stakeholders must weigh regulatory compliance costs against the margin expansion available from AI-integrated imaging platforms that reduce interpretation time and liability exposure.
Market Dynamics
AI-assisted radiology platforms are compressing interpretation cycles and forcing equipment manufacturers to bundle software subscriptions with hardware sales, restructuring recurring revenue models across dental practices.
Growth Catalysts
- EU MDR pathway acceleration:Stricter clinical evidence requirements for CE marking on cone beam CT systems are filtering out marginal competitors and consolidating demand around validated manufacturers in European dental markets.
- Practice consolidation in Germany:Reimbursement incentives favor capital-intensive imaging upgrades as larger dental groups replace fragmented solo practices, concentrating equipment procurement volumes.
- Digital sensor technology:Solid-state intraoral sensors are eliminating film processing infrastructure and darkroom space requirements, enabling clinic footprint reduction and workflow automation.
Market Restraints
- Supply concentration in rare earth phosphors:Digital sensor manufacturing depends on terbium and europium-doped compounds sourced through concentrated Asian refining channels, exposing production schedules to geopolitical friction.
- Ionizing radiation liability:ALARA (As Low As Reasonably Achievable) exposure protocols enforced by the EPA and state dental boards constrain imaging frequency and create malpractice exposure for overutilization.
- Optical intraoral scanners:Non-radiographic alternatives for restorative dentistry are capturing indications previously requiring bitewing radiographs, compressing addressable volume for traditional X-ray equipment.
Strategic Opportunities
- India's PLI scheme for medical devices:Production-linked incentives for domestic manufacturing of diagnostic equipment are attracting CBCT assembly investments to serve price-sensitive South Asian clinics.
- Tele-dentistry integration:Cloud-based image sharing between general dentists and specialists is creating demand for DICOM-compatible systems with embedded encryption and remote consultation workflows.
- AI Act compliance premium:European dental practices are prioritizing imaging platforms with pre-certified algorithmic diagnostic aids to preempt liability exposure under the EU AI Act's high-risk system classifications.
Industry Challenges
- Radiologic technologist certification gaps:State dental boards enforce operator training requirements that outpace educational program throughput, creating bottlenecks for equipment deployment and service attach rates.
- Legacy PACS integration:Older practice management systems lack API architectures for seamless image import, forcing expensive middleware development or complete software stack replacement.
- CE marking timeline compression:EU MDR's expanded clinical evidence requirements are extending certification cycles from 12 to 24 months, freezing product launch schedules and R&D amortization periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Diagnostic Imaging Equipment Market |
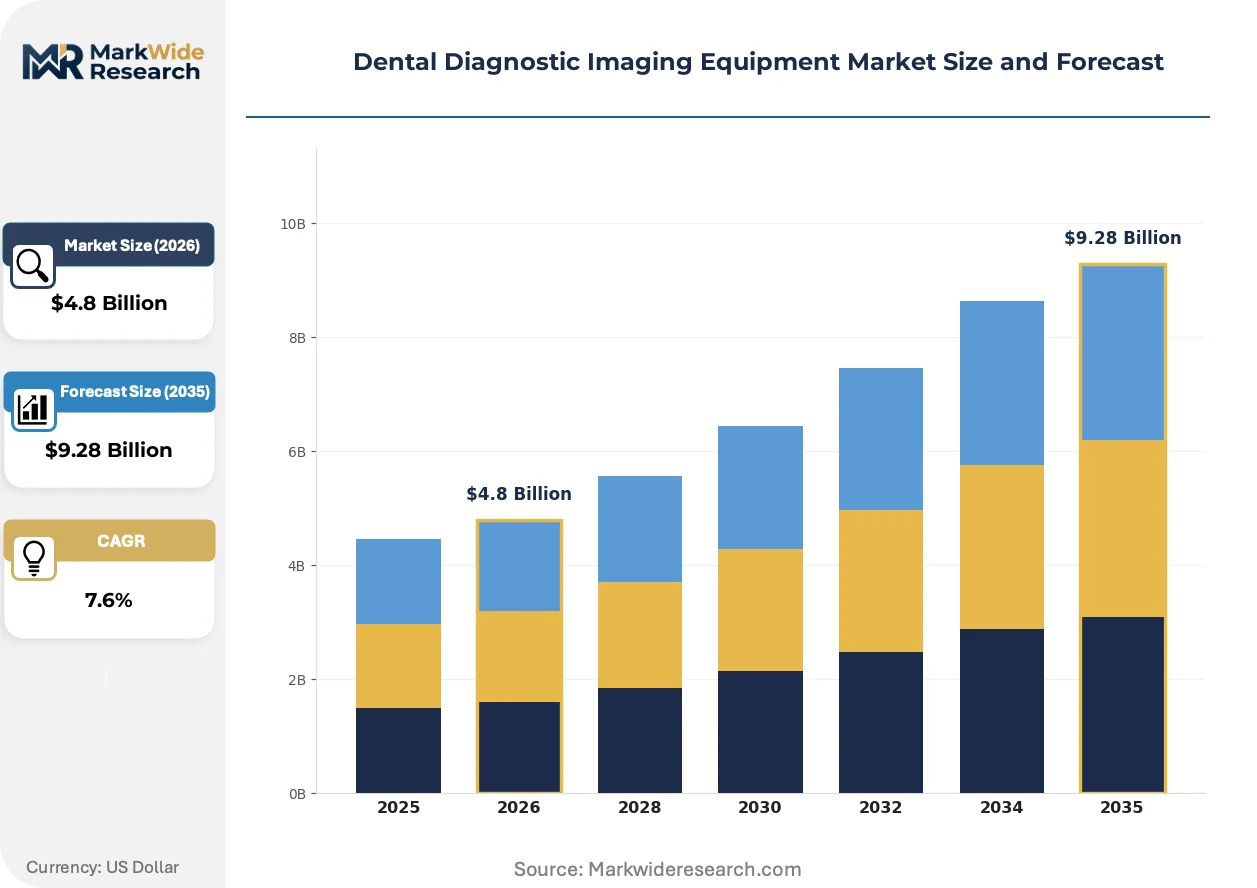
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intraoral Cameras, Cone Beam CT, 2D X-Ray, 3D X-Ray Technology: Digital Imaging, Film-based Imaging, Laser Imaging, Ultrasonic Imaging End User: Dental Offices, Hospitals, Clinics, Research Institutions Application: Teeth Diagnosis, Periodontal Assessment, Oral Surgery, Orthodontics |
| Companies Covered | Envista Holdings Corporation, Dentsply Sirona, Planmeca Oy, Carestream Health, Acteon Group, Dürr Dental SE, Vatech Co., Ltd., Align Technology, Inc., 3Shape A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Diagnostic Imaging Equipment Market Trends and Innovations
Workflow automation and algorithmic interpretation are restructuring how dental practices capture, process, and monetize diagnostic data, shifting competitive advantage from hardware specifications to software-enabled clinical decision support.
Photostimulable phosphor plates are decomposing the residual film-based intraoral imaging market by offering digital compatibility without sensor tethering constraints. Solo practitioners in rural United States markets are adopting plate systems to defer capital outlays for wired sensors while achieving diagnostic workflow integration. This hybrid approach is compressing the addressable market for conventional film and chemistry suppliers.
FDA 510(k) clearance pathways for AI-assisted radiology are formalizing algorithmic performance benchmarks that manufacturers must document through clinical validation studies. The industrial consequence is a bifurcation between venture-backed imaging AI developers with regulatory affairs capacity and hardware incumbents acquiring algorithmic capabilities through partnership. CBCT manufacturers seeking premium positioning are most affected, bundling lesion detection software to justify unit price premiums.
Group dental practices are consolidating procurement authority into centralized supply chain functions that negotiate enterprise imaging contracts across multi-location networks. Independent dental supply distributors are losing share to manufacturer-direct sales teams and group purchasing organizations that aggregate volume for pricing leverage. This concentration is most visible in the United States where dental service organizations now control equipment specification for thousands of affiliated practices.
Dental Diagnostic Imaging Equipment Market Segmentation
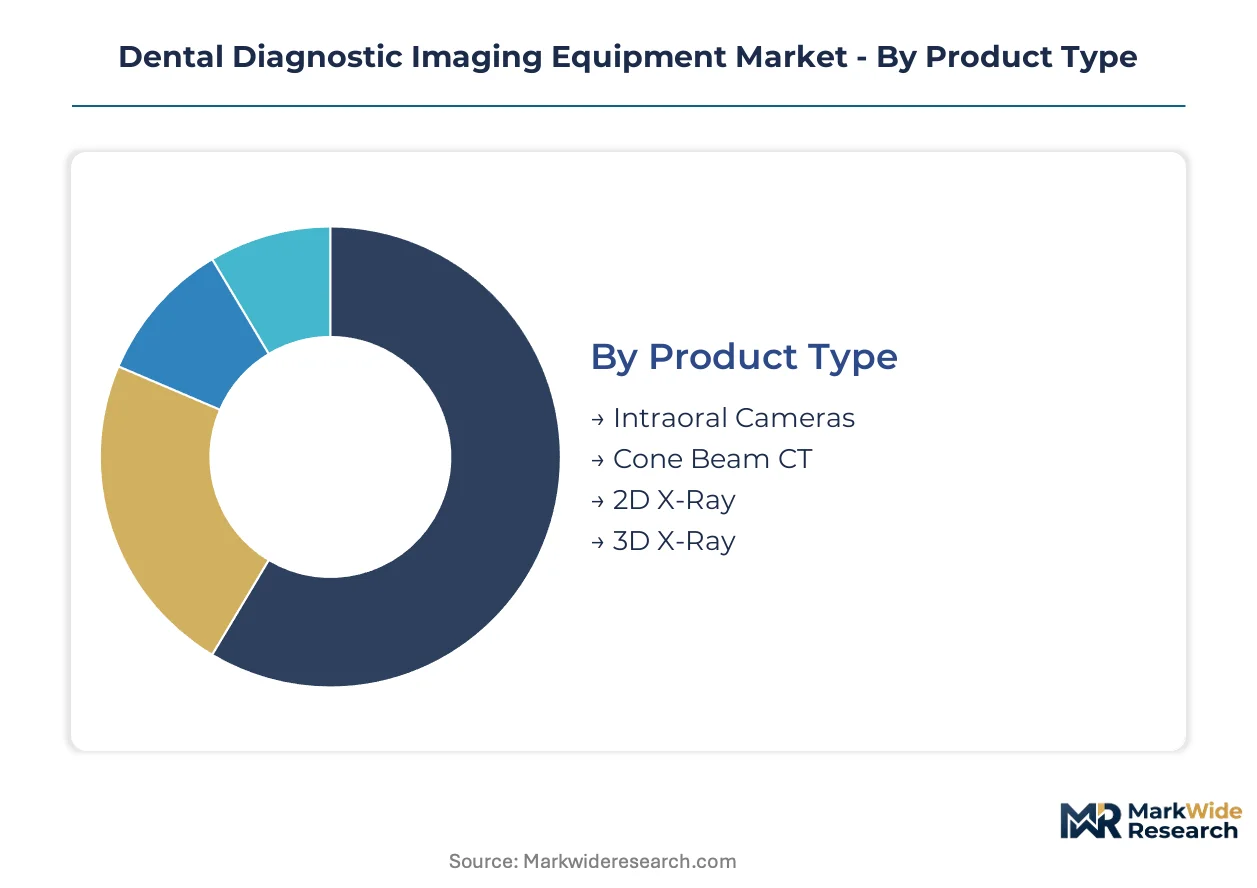
Dental diagnostic imaging equipment segments diverge sharply by capital intensity and regulatory pathway, with premium 3D systems concentrating in consolidated US and German group practices while compact 2D units penetrate price-sensitive solo clinics across India and Southeast Asia.
Product Type:
Domestic demand in Germany and the United States concentrates on high-margin volumetric systems, while export-led growth flows toward compact Asian markets prioritizing footprint efficiency.
- Cone Beam CT:Volumetric acquisition systems generate sub-millimeter isotropic resolution across 15-20 cm fields of view. Demand clusters in German dental service organizations and US oral surgery centers where implant planning volume justifies capital outlay. FDA 510(k) clearance timelines and EU MDR clinical evidence requirements filter marginal competitors.
- 3D X-Ray:Digital tomographic reconstruction enables orthodontic treatment planning and complex endodontic assessment. Japanese and South Korean orthodontic chains drive replacement cycles, displacing legacy panoramic systems through superior diagnostic yield per exposure.
- Intraoral Cameras:Optical capture devices for surface documentation and patient communication.
- 2D X-Ray:Conventional radiographic systems for routine caries detection and bitewing series.
Cone Beam CT holds the largest share; momentum sits with 3D X-Ray as orthodontic chains consolidate procurement authority.
Technology:
Cost tier stratification separates premium digital workflows from economy film alternatives, with laser and ultrasonic modalities occupying narrow specialty niches.
- Digital Imaging:Solid-state sensors and photostimulable phosphor plates eliminate chemical processing infrastructure. German and US practices achieve workflow automation and darkroom space reclamation, while Indian clinics under the PLI scheme adopt digital for export competitiveness.
- Film-based Imaging:Silver halide emulsion systems persist in rural United States solo practices and legacy installations where capital constraints delay modernization. Supply concentration in rare earth phosphors for digital alternatives accelerates film's terminal decline.
- Laser Imaging:Optical coherence tomography for soft tissue assessment and caries detection without ionizing radiation.
- Ultrasonic Imaging:Acoustic mapping for periodontal pocket depth measurement and calculus localization.
Digital Imaging dominates volume; Film-based Imaging retains residual utility only where regulatory enforcement lags.
End User:
Customer type determines service attach rates and software subscription penetration, with institutional buyers extracting pricing leverage unavailable to fragmented solo operators.
- Dental Offices:General practice and specialty clinics constitute the primary procurement channel. US dental service organizations and German group practices centralize imaging specification across multi-location networks, forcing manufacturer-direct sales engagement and enterprise contract structures.
- Hospitals:Academic medical centers and integrated delivery networks prioritize DICOM interoperability and PACS integration. India's hospital chains under Ayushman Bharat expansion drive CBCT installations for oral-maxillofacial surgery departments.
- Clinics:Ambulatory surgical centers and community health facilities with constrained capital budgets.
- Research Institutions:University dental schools and imaging validation laboratories for algorithmic training datasets.
Dental Offices command the largest installed base; Hospitals are expanding most quickly as oral surgery consolidates into institutional settings.
Application:
Application maturity varies by diagnostic standard-of-care evolution, with implant planning and orthodontic assessment now requiring volumetric data while caries detection tolerates lower-resolution alternatives.
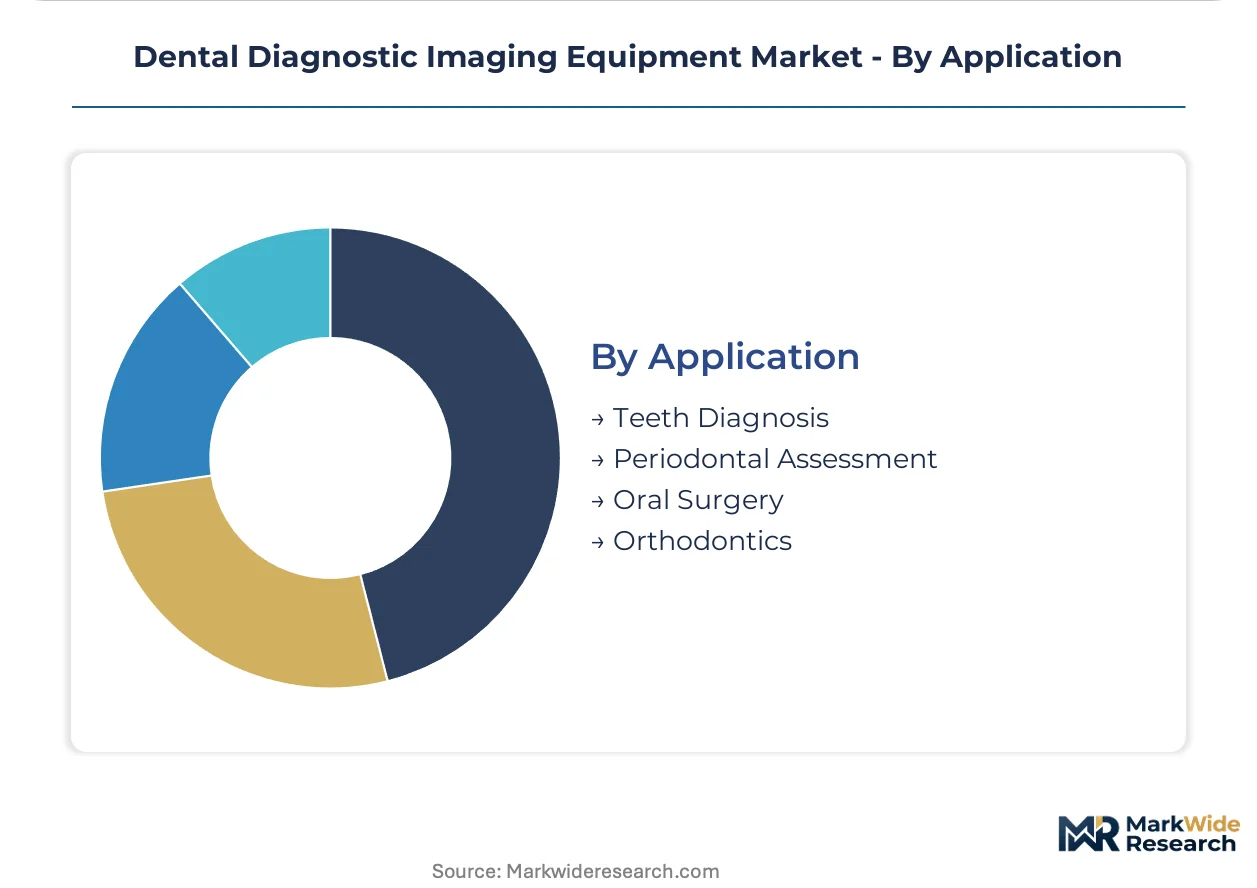
- Oral Surgery:Implant placement, third molar extraction, and pathology assessment demand sub-millimeter spatial accuracy. German and US oral surgeons specify CBCT as standard of care, with malpractice exposure driving adoption for complex cases.
- Orthodontics:Treatment planning for skeletal discrepancy and airway assessment requires full-arch volumetric capture. Clear aligner therapy growth in South Korea and Japan propels 3D imaging replacement of panoramic systems.
- Teeth Diagnosis:Caries detection and restorative treatment planning through intraoral and bitewing radiography.
- Periodontal Assessment:Bone level measurement and furcation involvement evaluation for disease staging.
Oral Surgery holds the largest share; Orthodontics is gaining share fastest through aligner therapy volume expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by dental practice structure. German group practices deploy premium volumetric systems at scale, while Indian solo operators prioritize compact footprint units under production-linked incentive schemes.
United States
FDA 510(k) clearance pathways for AI-assisted radiology accelerate equipment replacement cycles in dental service organizations. The EPA administers radiation safety standards that constrain imaging frequency and shape operator certification requirements. California and Texas dental groups concentrate procurement authority through centralized supply chain functions serving multi-location networks.
Germany
Practice consolidation and reimbursement incentives favor capital-intensive imaging upgrades across larger dental groups replacing fragmented solo practices. The EU MDR imposes stricter clinical evidence requirements on CBCT manufacturers seeking CE marking for European distribution. Bavaria and North Rhine-Westphalia host dense clusters of group practices driving concentrated equipment procurement volumes.
India
The PLI scheme for medical devices attracts CBCT assembly investments to serve price-sensitive South Asian clinics. The Central Drugs Standard Control Organization governs import licensing and quality standards for diagnostic equipment. Maharashtra and Karnataka dental chains under Ayushman Bharat expansion drive installations for oral-maxillofacial surgery departments.
Japan
Orthodontic chains consolidate procurement authority and displace legacy panoramic systems through 3D imaging replacement cycles. The Pharmaceuticals and Medical Devices Agency oversees pre-market approval for advanced radiological equipment. Tokyo and Osaka metropolitan areas concentrate clear aligner therapy volume propelling volumetric system demand.
South Korea
Export-oriented manufacturers supply compact cone beam CT units engineered for space-constrained Asian clinics. The Ministry of Food and Drug Safety regulates radiation-emitting medical devices through licensing and post-market surveillance. Seoul Capital Area orthodontic networks drive replacement demand for digital tomographic reconstruction systems.
Dental Diagnostic Imaging Equipment Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the former capturing recurring software revenue through bundled hardware-software ecosystems and the latter competing on footprint efficiency and open-architecture interoperability. The market structure reflects bifurcation between automated digital workflows and legacy film-based alternatives. Three archetypes dominate: integrated platform vendors, compact equipment specialists, and open-software architects. Competitive moves concentrate on strategic partnerships for AI algorithm integration and geographic expansion through distributor-to-direct sales transitions.
Within the integrated platform tier, Dentsply Sirona and Envista Holdings Corporation exemplify vendors capturing recurring revenue through software subscriptions bundled with hardware sales. Planmeca Oy anchors the open-architecture segment through Finnish-designed software interoperability. Vatech Co., Ltd. occupies a position among compact equipment specialists serving space-constrained clinic environments.
| Leading Market Players |
|---|
| Envista Holdings Corporation |
| Dentsply Sirona |
| Planmeca Oy |
| Carestream Health |
| Acteon Group |
| Dürr Dental SE |
| Vatech Co., Ltd. |
| Align Technology, Inc. |
| 3Shape A/S |
| Others |
Pricing and Supply Chain Analysis
Photostimulable phosphor plate adoption replacing wired intraoral sensors in rural United States solo practices simultaneously shifts component sourcing toward Asian rare earth refiners and compresses pricing power for premium digital sensor manufacturers serving consolidated group practices.
Pricing Analysis
Long-term enterprise contracts dominate procurement between dental service organizations and integrated platform vendors, with subscription-bundled hardware-software ecosystems commanding premium positioning over transactional per-unit sales. Price differentiation separates FDA-cleared AI-assisted radiology tiers from basic digital capture systems, with certification level and after-sales service attach rates driving margin expansion. Cost compression in the compact 2D segment intensifies as India's PLI scheme attracts domestic assembly investments. Solo practitioners in rural markets exhibit highest price sensitivity, while German group practices prioritize diagnostic yield over acquisition cost.
Supply Chain Analysis
Strategic stockpiling of terbium and europium-doped phosphor compounds buffers CBCT manufacturers against rare earth supply volatility, contrasting with just-in-time sensor assembly for standard digital radiography units. Manufacturing concentration in China, South Korea, and Finland shapes component availability for volumetric systems and open-architecture software platforms. Digital sensor production draws from concentrated Asian refining channels for rare earth phosphors, creating single-source vulnerability for premium imaging manufacturers. Distribution runs through manufacturer-direct sales teams serving consolidated dental groups and independent distributors targeting fragmented solo practices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Optical intraoral scanner penetration threatens traditional bitewing radiograph volumes, forcing incumbents to defend substitution-driven compression in restorative dentistry indications.
For Market Incumbents: Shield software subscription revenue by embedding AI-assisted radiology platforms into hardware sales before optical scanning captures additional indications. Acquire algorithmic capabilities through partnership rather than organic development to compress FDA 510(k) clearance timelines. Prioritize backward integration into rare earth phosphor supply channels to offset Asian refining concentration risks.
For New Entrants and Emerging Players: FDA 510(k) fast-track pathways for AI-assisted lesion detection algorithms offer regulatory entry points for venture-backed developers lacking legacy hardware installed bases. Target India's price-sensitive South Asian clinics with compact CBCT units engineered for space-constrained environments under PLI scheme incentives. Pursue open-architecture software interoperability as the primary go-to-market angle against integrated platform bundling.
For Investors and Strategic Acquirers: EU MDR clinical evidence requirements reshaping CE marking timelines filter marginal competitors and consolidate demand around validated manufacturers with regulatory affairs capacity. Acquisition targets with pre-certified algorithmic diagnostic aids command premium positioning under the EU AI Act's high-risk system classifications. Watch radiologic technologist certification throughput as the inflection signal for equipment deployment bottlenecks and service attach rate compression.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Algorithm Integration Partnership | FDA 510(k) clearance bundling accelerates hardware-software ecosystem lock-in for dental service organizations. |
| CE Marking Pathway Investment | EU MDR clinical evidence requirements filter marginal competitors and consolidate European demand around validated manufacturers. |
| Hospital System Partnership | Ayushman Bharat expansion in Maharashtra and Karnataka drives CBCT installations for oral-maxillofacial surgery departments. |
| Software Companion Development | DICOM-compatible platforms with embedded encryption enable cloud-based tele-dentistry workflows between generalists and specialists. |
| Reimbursement Strategy Alignment | German group practice consolidation leverages reimbursement incentives for capital-intensive imaging upgrade procurement. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with dental equipment procurement managers, biomedical engineers at hospital systems, GPO contracts administrators, and regulatory affairs specialists at CBCT manufacturers; and secondary validation through FDA 510(k) clearance databases, EU MDR CE marking registries, hospital procurement contract disclosures, and dental practice consolidation filings. Bottom-up equipment shipment modeling triangulated against top-down dental service organization capital expenditure surveys anchored volume estimates across the analysis window.
Across the projection horizon, the analytical framework segmented by product type, technology tier, end-user category, and application area to isolate growth vectors. CAGRs derived from replacement cycle analysis of film-to-digital transitions and orthodontic chain consolidation patterns. Forecast inputs incorporated AI-assisted radiology adoption curves and EU MDR certification timeline compression effects on competitive dynamics.
Decision-makers should treat outputs as directional under assumptions of continued dental service organization consolidation and stable rare earth phosphor supply channels; material deviation would warrant model refresh. Revision becomes warranted when optical intraoral scanner technical specifications cross thresholds enabling caries detection parity with bitewing radiography.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Brazil Nuclear Imaging Market
Medical Imaging
3D Imaging Surgical Solution Market
Medical Imaging
Industrial Computed Radiography Market
Medical Imaging
Canada Nuclear Imaging Market
Medical Imaging
Orthopedic Radiology Equipment Market
Medical Imaging
South America Digital X-Ray Devices Market
Medical Imaging
Angiography Imaging Systems Market
Medical Imaging
Interventional Radiology Market
Medical Imaging
Global Medical Imaging Phantoms Market
Medical Imaging
India Magnetic Resonance Imaging Market
Medical Imaging
Digital X Ray Market
Medical Imaging
Argentina Mammography Market
Medical Imaging
Wireless Intraoral Camera Market
Medical Imaging
South America Fluoroscopy Market
Medical Imaging
Refurbished Medical Imaging Devices Market
Medical Imaging
Weightbearing Low Dose (CT) Systems Market