
 Digital Telepathology Market | 2026-2036
Digital Telepathology Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Telepathology Market Outlook
Cloud-native whole-slide imaging architecture is fragmenting the legacy on-premises vendor landscape. Philips Healthcare leverages its enterprise imaging footprint to anchor multi-site hospital deployments across Europe. Hamamatsu Photonics K.K. sustains leadership in high-resolution scanner hardware through in-house sensor fabrication. 3DHISTECH specializes in brightfield and fluorescence scanning systems that dominate academic research workflows in Central Europe.
Digital telepathology encompasses the acquisition, management, and interpretation of pathology specimens through digitized whole-slide images at resolutions typically exceeding 20x optical magnification, enabling remote diagnosis and collaborative consultation. The technology serves primary industrial purposes in reducing diagnostic turnaround times and expanding specialist access to underserved regions. Whole Slide Imaging systems command the largest installed base but face margin compression as scanner hardware commoditizes. AI-Enhanced Diagnosis represents the fastest-expanding segment, with algorithm developers capturing value through recurring software licenses rather than capital equipment sales. Cloud-Based Solutions are displacing on-premises infrastructure among mid-sized diagnostic centers seeking operational flexibility without IT overhead.
FDA regulates whole-slide imaging devices as Class II medical instruments under 21 CFR 864, requiring premarket notification for clinical diagnostic use. The European Medical Device Regulation imposes stricter clinical evidence requirements for AI-embedded diagnostic software, extending approval timelines for algorithm developers. ISO 15189 accreditation standards for medical laboratories increasingly mandate digital workflow validation, shaping procurement criteria across hospital systems. Stakeholders must weigh regulatory compliance investments against the acceleration of decentralized pathology service models.
Market Dynamics
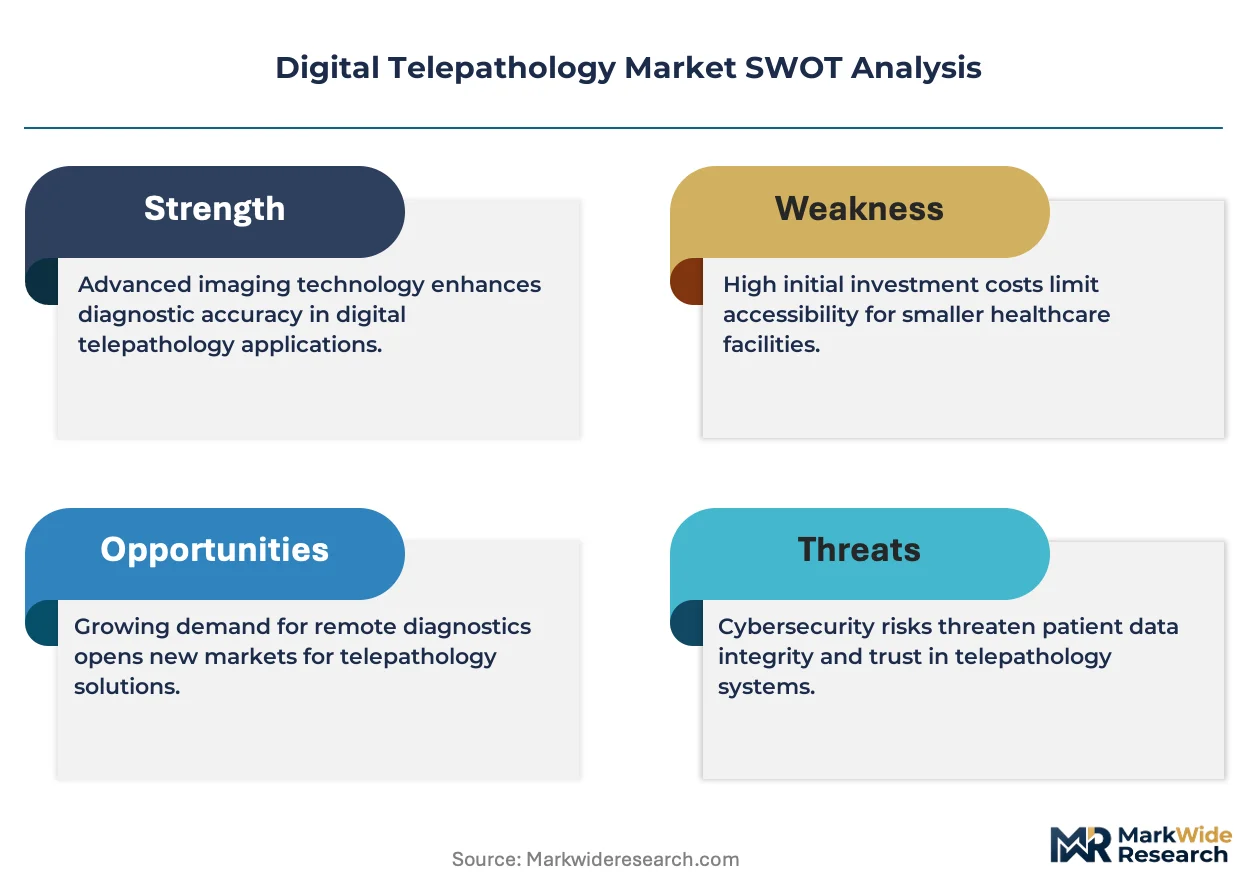
Cloud-native whole-slide imaging is virtualizing pathology infrastructure, collapsing the traditional distinction between diagnostic production and consumption while forcing incumbents to abandon perpetual-license business models.
Growth Catalysts
- FDA 21 CFR 864 clearance streamlining:The FDA's refined premarket notification pathway for Class II whole-slide imaging devices accelerates commercial entry for scanner manufacturers targeting clinical diagnostic use in the United States.
- University medical center network consolidation:German university hospitals are building interoperable national telepathology networks that aggregate specialist capacity across previously fragmented regional pathology departments.
- AI-embedded diagnostic software licensing:Algorithm developers capture recurring revenue through subscription-based deployment models that bypass capital-intensive hardware sales cycles.
Market Restraints
- European MDR clinical evidence requirements:The Medical Device Regulation imposes extended approval timelines for AI-embedded diagnostic software, compressing margin timelines for algorithm developers seeking CE marking.
- High-resolution sensor supply concentration:In-house CMOS sensor fabrication capabilities concentrate among Japanese optical component specialists, creating supply bottleneck risks for scanner OEMs without captive sensor production.
- On-premises infrastructure depreciation cycles:Hospital pathology departments face stranded asset risk from multi-year amortization schedules that conflict with cloud migration timelines.
Strategic Opportunities
- Mid-sized diagnostic center cloud migration:European mid-tier pathology centers seek operational flexibility without IT overhead, creating white space for cloud-native platform vendors.
- ISO 15189 digital workflow mandates:Accreditation standards increasingly require digital validation, reshaping procurement criteria across hospital laboratory networks.
- Fluorescence-brightfield hybrid scanning convergence:Academic research workflows in Central Europe drive demand for multi-modal systems that consolidate previously separate instrument categories.
Industry Challenges
- Pathologist digital literacy gaps:Diagnostic workforce training programs lag scanner deployment schedules, creating utilization bottlenecks in newly digitized departments.
- Legacy LIS-PACS integration complexity:Hospital information system interoperability requirements extend implementation timelines and inflate professional services costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Telepathology Market |
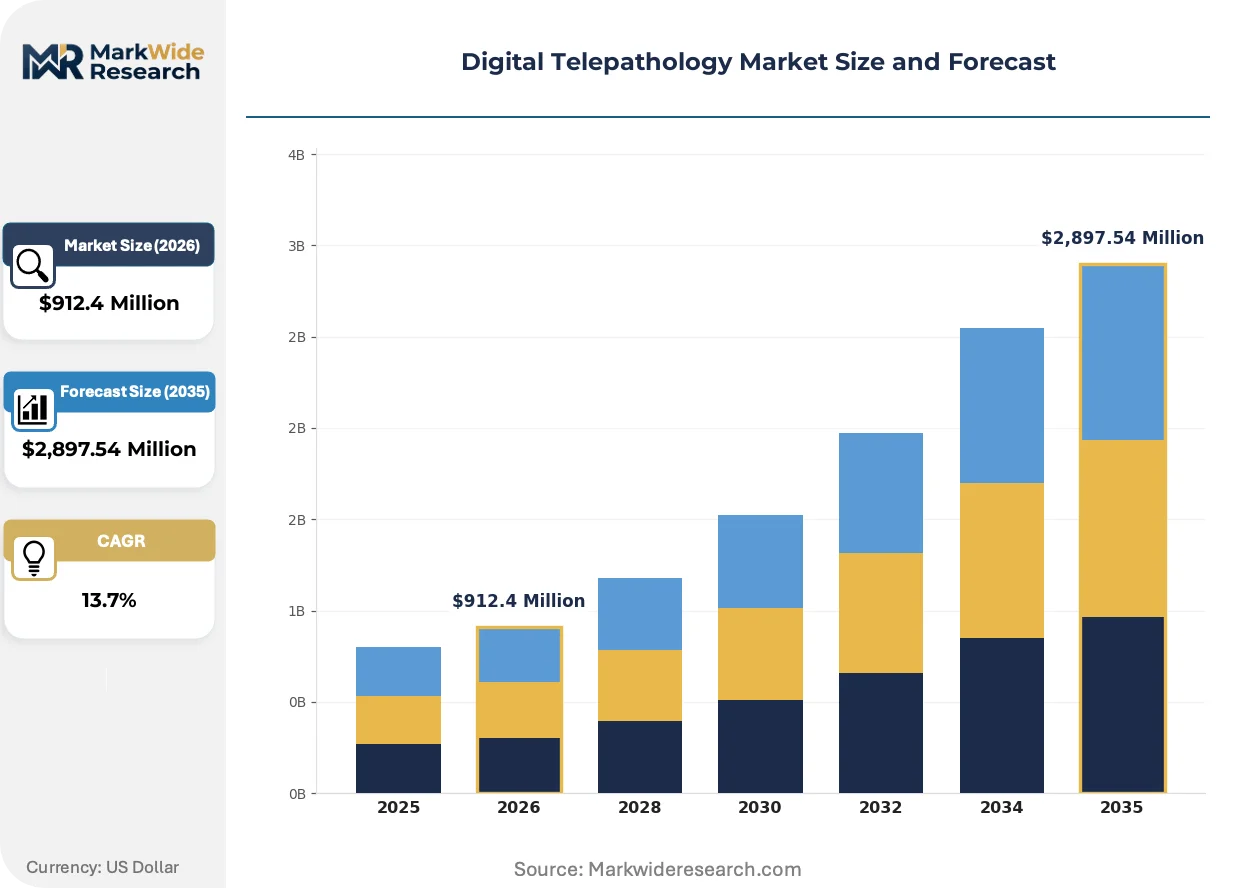
| Market Size in 2026 | $912.4 Million |
| Market Size in 2035 | $2,897.54 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Whole Slide Imaging, Digital Scanning, Image Analysis Software, AI-Enhanced Diagnosis End User: Hospitals, Research Laboratories, Diagnostic Centers, Academic Institutions Application: Remote Diagnosis, Education, Quality Control, Research Solution: Cloud-Based Solutions, On-Premises Solutions, Mobile-Based Solutions, Hybrid Solutions |
| Companies Covered | Philips Healthcare, Leica Biosystems, Roche Diagnostics, 3DHISTECH, Olympus Corporation, Visiopharm, Hamamatsu Photonics K.K., OptraSCAN, Sectra AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Telepathology Market Strategic Shifts
Computational pathology is converging with enterprise imaging architectures, redefining how diagnostic value flows through healthcare delivery networks and where margin capture concentrates.
Whole-slide imaging is virtualizing specimen review workflows, replacing physical slide courier networks with real-time remote consultation capabilities. Community hospital pathology departments are adopting cloud-hosted platforms within 12-18 month procurement cycles. This virtualization is compressing geographic barriers to specialist access while fragmenting the legacy on-premises vendor landscape.
The EU AI Act's risk classification framework for medical device software is reshaping algorithm development roadmaps, forcing developers to front-load clinical validation investments. High-risk AI diagnostic tools face conformity assessment requirements that extend time-to-market by 18-24 months. German notified bodies are experiencing capacity constraints that delay CE marking for fluorescence-based AI applications.
Subscription-based software licensing is displacing perpetual scanner-and-software bundles as the dominant commercial structure. Mid-sized European diagnostic centers are unbundling hardware procurement from algorithm access, favoring vendors with modular pricing. This shift concentrates most visibly in the Netherlands and Belgium, where regional pathology cooperatives aggregate purchasing across multiple hospital sites.
Digital Telepathology Market Segmentation
Technology architecture and deployment models determine margin capture in digital telepathology. End-user procurement patterns fragment across capital-intensive hospital systems and lean diagnostic cooperatives.
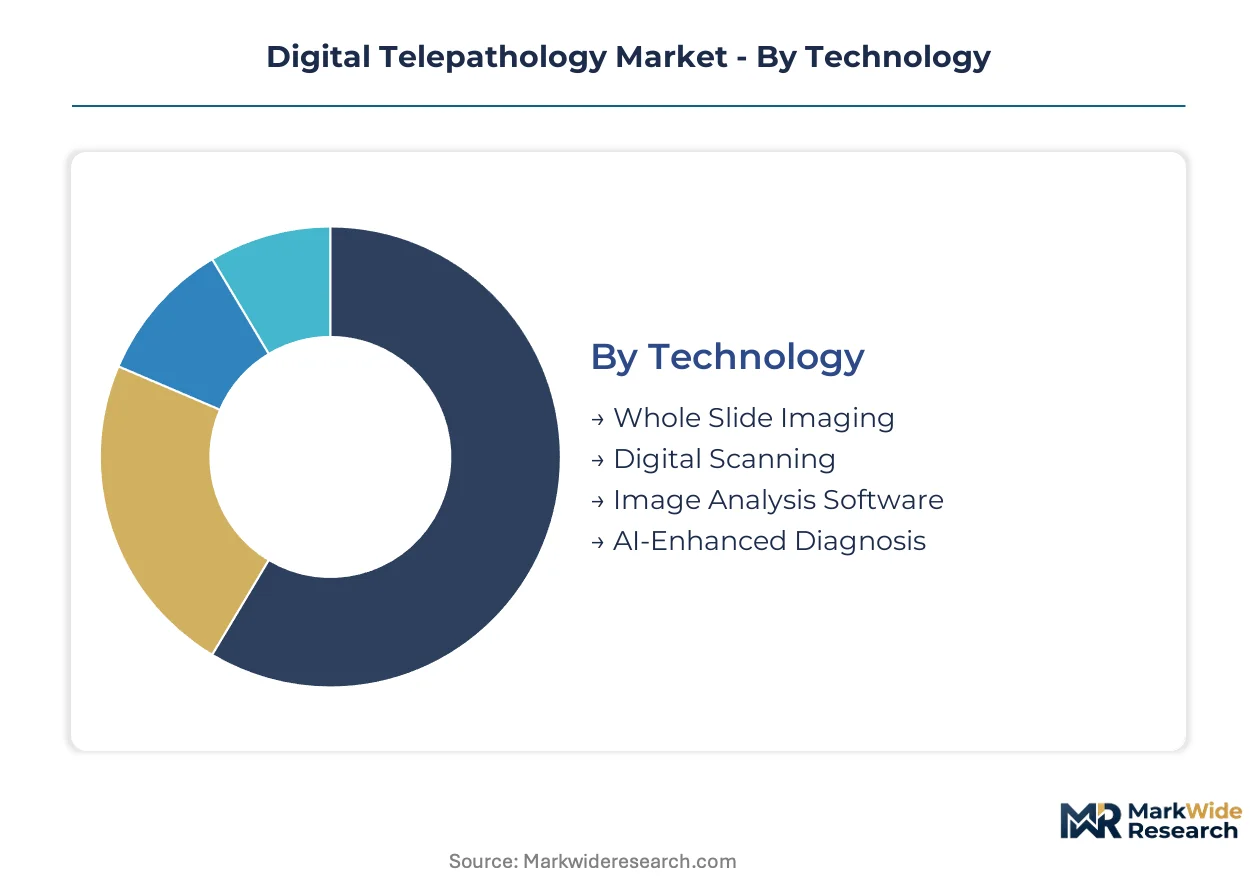
Technology:
Technical sophistication tiers separate hardware-intensive platforms from algorithm-driven software layers.
- Whole Slide Imaging:High-resolution scanner hardware digitizes glass slides at 20x-40x optical magnification with automated focus stacking. Hospital pathology departments in Germany and the United States concentrate procurement for multi-site diagnostic networks.
- AI-Enhanced Diagnosis:Machine learning algorithms classify tissue patterns, grade tumors, and flag regions of interest for pathologist review. Research laboratories in the Netherlands and Belgium drive subscription licensing demand for computational pathology tools.
- Digital Scanning:Brightfield and fluorescence capture systems convert physical specimens into standardized digital formats.
- Image Analysis Software:Quantitative morphometry tools measure cellular features and biomarker expression patterns.
Whole Slide Imaging commands the established base. The steepest expansion runs through AI-Enhanced Diagnosis.
End User:
Customer scale and capital availability shape procurement velocity across institutional categories.
- Hospitals:Integrated health systems deploy enterprise-wide telepathology platforms linking central laboratories with satellite facilities. University medical centers in Germany aggregate regional pathology capacity through national network architectures.
- Diagnostic Centers:Mid-sized independent laboratories seek cloud-native solutions minimizing IT infrastructure investment. European cooperatives in the Netherlands consolidate purchasing across multiple sites.
- Research Laboratories:Academic and commercial R&D facilities prioritize multi-modal imaging for translational studies.
- Academic Institutions:Medical schools and teaching hospitals integrate telepathology into resident training curricula.
Hospitals anchor installed capacity. Diagnostic centers are gaining share fastest through cloud migration.
Application:
Functional use cases span clinical revenue generation to non-revenue educational workflows.
- Remote Diagnosis:Real-time specialist consultation replaces physical slide courier networks, collapsing geographic barriers to subspecialist access. Community hospitals in underserved United States regions concentrate adoption for frozen section support.
- Education:Digital slide repositories enable asynchronous case review and standardized competency assessment. Medical schools across Central Europe deploy platforms for remote histopathology instruction.
- Quality Control:Automated image analysis validates diagnostic consistency across distributed pathologist networks.
- Research:Large-scale tissue biobanks leverage digitization for retrospective biomarker studies.
Remote Diagnosis generates primary revenue. Education shows the steepest volume climb as training programs digitize.
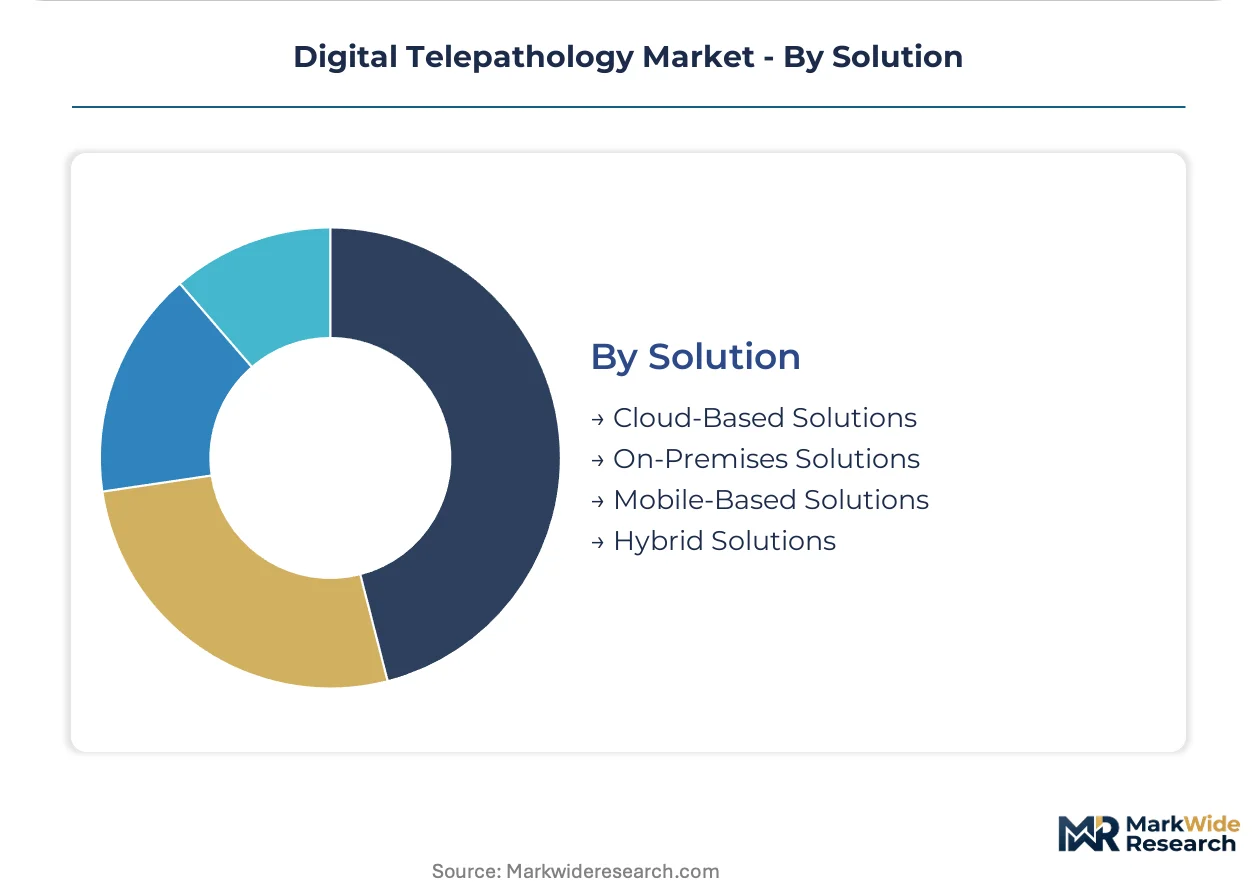
Solution:
Deployment architecture determines operational flexibility versus data sovereignty tradeoffs.
- Cloud-Based Solutions:Vendor-hosted platforms eliminate server maintenance and enable elastic compute scaling for AI workloads. Mid-sized European diagnostic centers prioritize operational flexibility without dedicated IT staffing.
- On-Premises Solutions:Local infrastructure maintains direct control over patient data and network latency. German university hospitals favor this model for integration with existing enterprise imaging archives.
- Hybrid Solutions:Mixed architectures retain sensitive primary diagnosis on-site while leveraging cloud for archival and AI processing.
- Mobile-Based Solutions:Tablet-optimized viewers enable point-of-care consultation and field pathology support.
On-Premises Solutions hold legacy commitments. Cloud-Based Solutions capture the steepest adoption trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement departments and university medical centers constitute the primary buyer archetypes, with purchasing authority concentrating in integrated health systems across North America and Western Europe. Regional deployment patterns diverge sharply between enterprise-scale hospital networks and mid-sized diagnostic cooperatives seeking cloud-native alternatives.
United States
FDA 21 CFR 864 clearance pathways accelerate scanner commercialization for clinical diagnostic use. Community hospital systems in the Southeast and Midwest deploy remote consultation platforms to access subspecialist pathologists. The Mayo Clinic and Cleveland Clinic anchor multi-site telepathology networks spanning dozens of affiliated hospitals.
Germany
University medical centers in Berlin, Munich, and Heidelberg consolidate regional pathology capacity through interoperable national networks. The EU Medical Device Regulation imposes extended clinical evidence requirements for AI-embedded diagnostic software. The Rhine-Ruhr metropolitan corridor hosts dense clusters of diagnostic laboratories migrating to cloud-hosted platforms.
Netherlands
Regional pathology cooperatives aggregate purchasing across multiple hospital sites, favoring modular subscription pricing over capital-intensive hardware bundles. The Dutch national healthcare IT infrastructure supports standardized digital pathology data exchange. Academic medical centers in Utrecht and Rotterdam drive demand for fluorescence-brightfield hybrid scanning systems.
Japan
Hamamatsu Photonics K.K. and other domestic optical component specialists maintain captive CMOS sensor fabrication capabilities. The Pharmaceuticals and Medical Devices Agency (PMDA) regulates whole-slide imaging devices under risk-based classification frameworks. Tokyo and Osaka metropolitan areas concentrate hospital pathology department digitization initiatives.
United Kingdom
NHS England's pathology network consolidation program mandates digital workflow adoption across regional laboratory hubs. The Medicines and Healthcare products Regulatory Agency (MHRA) enforces post-Brexit alignment with EU MDR clinical evidence standards. London teaching hospitals and Manchester pathology networks lead procurement of AI-enhanced diagnostic platforms.
Digital Telepathology Market Competitive Environment
Channel-controlling players compete with product-specialist players across three distinct tiers. Enterprise imaging vendors leverage installed base relationships to anchor multi-site hospital deployments. Scanner hardware specialists defend margin through proprietary sensor fabrication and optical engineering. Algorithm developers capture recurring revenue through subscription licensing models that bypass capital equipment cycles. Dominant competitive moves include strategic partnerships between hardware OEMs and AI software vendors, plus geographic expansion through distributor networks in underserved European markets.
Within the enterprise imaging tier, Philips Healthcare and Sectra AB exemplify channel-controlling archetypes that integrate telepathology modules into broader diagnostic imaging portfolios. Among hardware-specialist players, Hamamatsu Photonics K.K. occupies a position defined by in-house sensor production capabilities, while 3DHISTECH represents the academic-research-focused archetype dominating Central European brightfield and fluorescence workflows. Roche Diagnostics and Leica Biosystems sit within the life sciences conglomerate tier, leveraging reagent and consumable pull-through to anchor scanner placements.
| Leading Market Players |
|---|
| Philips Healthcare |
| Leica Biosystems |
| Roche Diagnostics |
| 3DHISTECH |
| Olympus Corporation |
| Visiopharm |
| Hamamatsu Photonics K.K. |
| OptraSCAN |
| Sectra AB |
| Others |
Value Chain & Pricing Dynamics
Single-source CMOS sensor dependency in Japanese optical component manufacturing determines both scanner pricing tier spreads and supply chain configuration across digital telepathology hardware. FDA 21 CFR 864 clearance bottlenecks amplify pricing power for cleared-device vendors while compressing margins for algorithm developers facing EU MDR clinical evidence requirements.
Pricing Analysis
Cost-plus contracts with semiconductor raw material indexation dominate scanner hardware procurement between Japanese sensor fabricators and whole-slide imaging OEMs. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared clinical systems from research-grade instruments and refurbished legacy platforms. Pricing pressure stems from cloud-native software vendors unbundling algorithm access from capital equipment sales. Mid-sized European diagnostic centers exhibit highest price sensitivity through cooperative purchasing aggregation, while German university medical centers prioritize integration capability over unit cost.
Supply Chain Analysis
High-resolution CMOS sensor fabrication draws from captive production lines in Japan, with secondary optical component sourcing in Germany and the United States. Specialized glass optics, precision motion control systems, and medical-grade image processing chipsets constitute critical input dependencies. Single-source vulnerability concentrates in Hamamatsu Photonics K.K.'s sensor production facilities. Distribution runs through direct enterprise sales for hospital systems and regional distributor networks for mid-sized diagnostic laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. FDA 510(k) clearance pathways and EU MDR conformity assessment requirements create multi-year barriers that protect installed-base vendors from algorithm-only entrants.
For Market Incumbents: Build switching-cost moats through deep integration with hospital laboratory information systems and enterprise imaging archives. Philips Healthcare and Sectra AB should anchor multi-site deployments through PACS interoperability investments that extend implementation timelines for competitive displacement. Hamamatsu Photonics K.K. must defend sensor fabrication advantage against Korean and Chinese optical component specialists developing alternative supply sources.
For New Entrants and Emerging Players: Cloud infrastructure underpenetration in Southern and Eastern European diagnostic cooperatives offers white-space expansion without direct confrontation with entrenched German university networks. Target mid-sized pathology centers in Spain, Italy, and Poland with modular subscription pricing that unbundles AI algorithm access from scanner hardware procurement. Pursue ISO 15189 accreditation partnerships as a go-to-market angle that accelerates procurement committee approval.
For Investors and Strategic Acquirers: EU AI Act risk classification implementation reshapes the acquisition landscape by extending time-to-market for high-risk diagnostic algorithms and concentrating value in notified-body relationships. Position holdings for a 5-10 year window where regulatory capacity constraints create acquisition premiums for developers with existing CE marking. Target algorithm developers with validated clinical evidence packages and established German notified-body relationships. Monitor notified-body capacity expansion announcements as the primary inflection signal for valuation compression.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | EU MDR clinical evidence requirements compress margin timelines for algorithm developers seeking European market access. |
| Hospital System Partnership | Mayo Clinic and Cleveland Clinic multi-site networks demonstrate anchor-tenant value for platform standardization. |
| Software Companion Development | AI-embedded diagnostic tools capture recurring revenue through subscription licensing that bypasses capital equipment cycles. |
| Backward Integration into Sensor Fabrication | Captive CMOS production insulates Hamamatsu Photonics K.K. from supply bottleneck risks facing scanner OEMs. |
| Reimbursement Strategy | NHS England pathology network consolidation mandates digital workflow adoption across regional laboratory hubs. |
Study Parameters
Two parallel data streams informed the analysis: primary field engagement with industry stakeholders and secondary validation through regulatory filings and procurement databases. Interview program encompassed hospital pathology department directors, biomedical engineers, GPO contracts managers, laboratory information system integrators, and regulatory affairs specialists at scanner manufacturers. Secondary sources included FDA 510(k) premarket notification databases, EUDAMED CE marking records, hospital procurement contract disclosures, and ISO 15189 accreditation registries. Bottom-up scanner shipment estimates triangulated against top-down healthcare IT spending allocations.
Forecast inputs incorporated technology adoption curves across hospital and diagnostic center segments, regulatory approval timeline distributions, and cloud infrastructure penetration rates. Modeled dimensions spanned deployment architecture, end-user scale tier, application type, and regional regulatory cluster. CAGRs derived from logistic diffusion modeling of digitization maturity with scanner replacement cycle assumptions. AI algorithm licensing growth rates incorporated clinical validation cost trajectories and notified-body capacity constraints.
Practitioners should monitor FDA guidance document revisions, EU MDR implementing act updates, and notified-body designation expansions for early signals of forecast variance. Cross-checking against CMS Medicare telehealth reimbursement policy changes and NHS England digital pathology procurement timelines is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Global Medical Cameras Market
Medical Imaging
Enterprise Medical Image Viewers Market
Medical Imaging
Small Animal Imaging (in-Vivo) Market
Medical Imaging
China Computed Tomography Market
Medical Imaging
Ga 68 DOTATOC Market
Medical Imaging
Fluorescein Angiography Market
Medical Imaging
India Mammography Market
Medical Imaging
Industrial X-Ray Machine Market
Medical Imaging
Nuclear Magnetic Resonance Spectroscopy Market
Medical Imaging
Quantitative Pathology Imaging Market
Medical Imaging
North America Digital X-Ray Market
Medical Imaging
Medical Imaging Market
Medical Imaging
Brazil Mammography Market
Medical Imaging
Africa Nuclear Imaging Market
Medical Imaging
Global Medical Imaging Reagents Market
Medical Imaging
Cryo-Electron Microscopy Market