
 Global Healthcare Informatics Market | 2026-2036
Global Healthcare Informatics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Healthcare Informatics Market Foresight
Academic medical centers is reorganizing procurement priorities around AI-enabled diagnostic workflows, displacing traditional community hospital buying patterns. GE HealthCare leverages its imaging informatics portfolio to anchor enterprise contracts across integrated delivery networks. Siemens Healthineers sustains R&D intensity in digital twin applications for precision therapy planning. Epic Systems dominates the EHR layer that feeds downstream analytics and decision-support modules.
Healthcare informatics encompasses the architecture, software, and protocols that capture, store, exchange, and analyze clinical and operational data across care settings, typically operating through HL7 FHIR interoperability standards and cloud-native microservices to enable real-time decision support. Its primary commercial purpose is to reduce clinical variance, accelerate diagnostic throughput, and optimize resource allocation across multi-site health systems. Electronic health records occupy the largest installed base but face margin compression as buyers demand open APIs and modular substitution. Healthcare analytics platforms represent the fastest-expanding margin pool, particularly where vendors bundle predictive models with subscription pricing. Cloud-based deployment is displacing on-premises infrastructure among mid-tier hospitals seeking to defer capital expenditure.
FDA software-as-medical-device guidelines, EU MDR cybersecurity annexes, and HIPAA interoperability mandates collectively elevate compliance costs while creating barriers for uncertified entrants. EMA's expanded scrutiny of clinical algorithm validation is reshaping how European vendors design training data governance. Stakeholders must monitor whether emerging AI liability frameworks in the United States and European Union shift risk allocation toward health systems and away from software vendors.
Market Dynamics
Hospital digitization mandates are compressing procurement cycles while forcing legacy infrastructure replacements, creating a bifurcation between systems capable of real-time interoperability and those facing technical obsolescence.
Growth Catalysts
- FDA software-as-medical-device framework:The United States regulator's classification pathway accelerates vendor certification timelines, expanding the addressable market for algorithmic diagnostic tools.
- Germany Hospital Future Act incentives:Federal procurement budgets now prioritize integrated clinical decision support systems, redirecting capital toward analytics platforms.
- HL7 FHIR interoperability standards:Universal data exchange protocols reduce integration friction between electronic health records and third-party analytics modules.
Market Restraints
- EMA clinical algorithm validation requirements:Expanded scrutiny of training data governance extends product development timelines for European market entry.
- Cloud infrastructure concentration:Mid-tier hospitals face vendor lock-in risks as hyperscale providers dominate secure health data hosting.
- Legacy system technical debt:Proprietary on-premises architectures resist modular substitution, constraining API-driven analytics deployment.
Strategic Opportunities
- India tertiary hospital digitization:CDSCO regulatory alignment with international standards creates entry pathways for certified clinical decision support vendors.
- Digital twin convergence with imaging informatics:Precision therapy planning applications merge simulation capabilities with radiological workflow integration.
- Subscription pricing for predictive analytics:Recurring revenue models displace perpetual licensing in integrated delivery network procurement.
Industry Challenges
- Interoperability engineer scarcity:Health systems compete for specialists capable of mapping HL7 FHIR implementations across heterogeneous electronic health record environments.
- Multi-jurisdiction compliance synchronization:Vendors must reconcile HIPAA interoperability mandates with EU MDR cybersecurity annexes and FDA algorithmic transparency requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Healthcare Informatics Market |
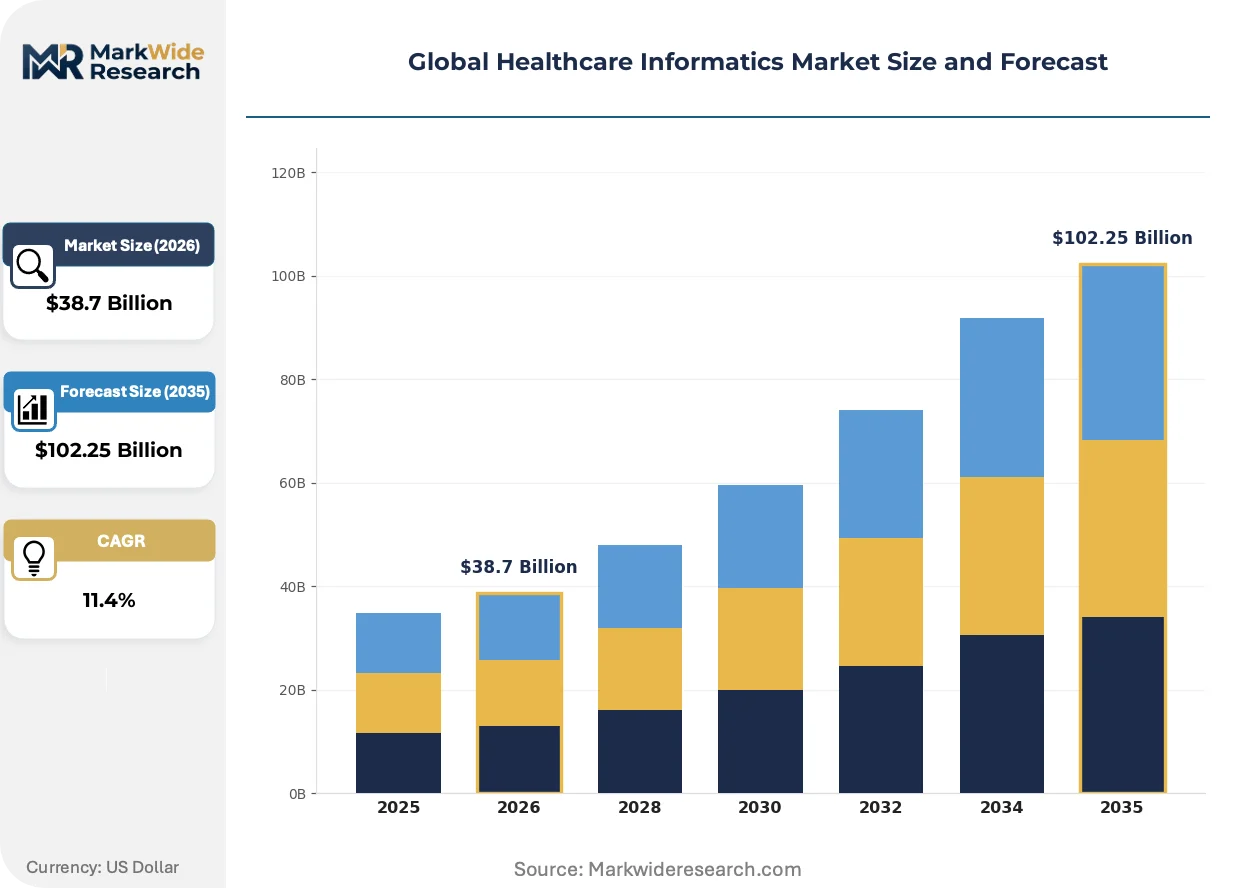
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronic Health Records, Clinical Decision Support Systems, Telemedicine Solutions, Healthcare Analytics Platforms, Patient Management Software Application: Population Health Management, Remote Patient Monitoring, Medical Imaging Analysis, Workflow Automation, Data Integration End User: Hospitals, Diagnostic Laboratories, Research Institutes, Ambulatory Care Centers, Nursing Homes Deployment: Cloud-Based, On-Premises, Hybrid, Web-Based, Mobile Platforms |
| Companies Covered | GE HealthCare, Philips Healthcare, McKesson Corporation, Cognizant, Accenture, Epic Systems, Siemens Healthineers, Allscripts Healthcare Solutions, Oracle Cerner, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Healthcare Informatics Market Shifts & Advancements
Edge computing architectures and federated learning protocols are redistributing computational loads across distributed clinical environments, reducing latency for time-sensitive diagnostic applications.
Point-of-care analytics hardware is miniaturizing diagnostic-grade processing into portable form factors. Rural health clinics and ambulatory surgical centers now deploy tablet-integrated decision support without dedicated server infrastructure. This compression is miniaturizing the traditional capital expenditure barrier that previously confined advanced analytics to academic medical centers.
EU AI Act risk classification tiers impose conformity assessment obligations on clinical algorithm vendors deploying within European Union member states. High-risk diagnostic applications face mandatory post-market monitoring and bias auditing requirements. German hospital procurement committees now prioritize vendors with established EU notified body relationships.
Integrated delivery networks are consolidating vendor relationships around enterprise-scale platform contracts that bundle electronic health records, imaging informatics, and predictive analytics under unified service agreements. Traditional best-of-breed procurement is yielding to single-source accountability models. This concentration is most visible in United States multi-hospital systems seeking operational standardization across state lines.
Global Healthcare Informatics Market Segmentation
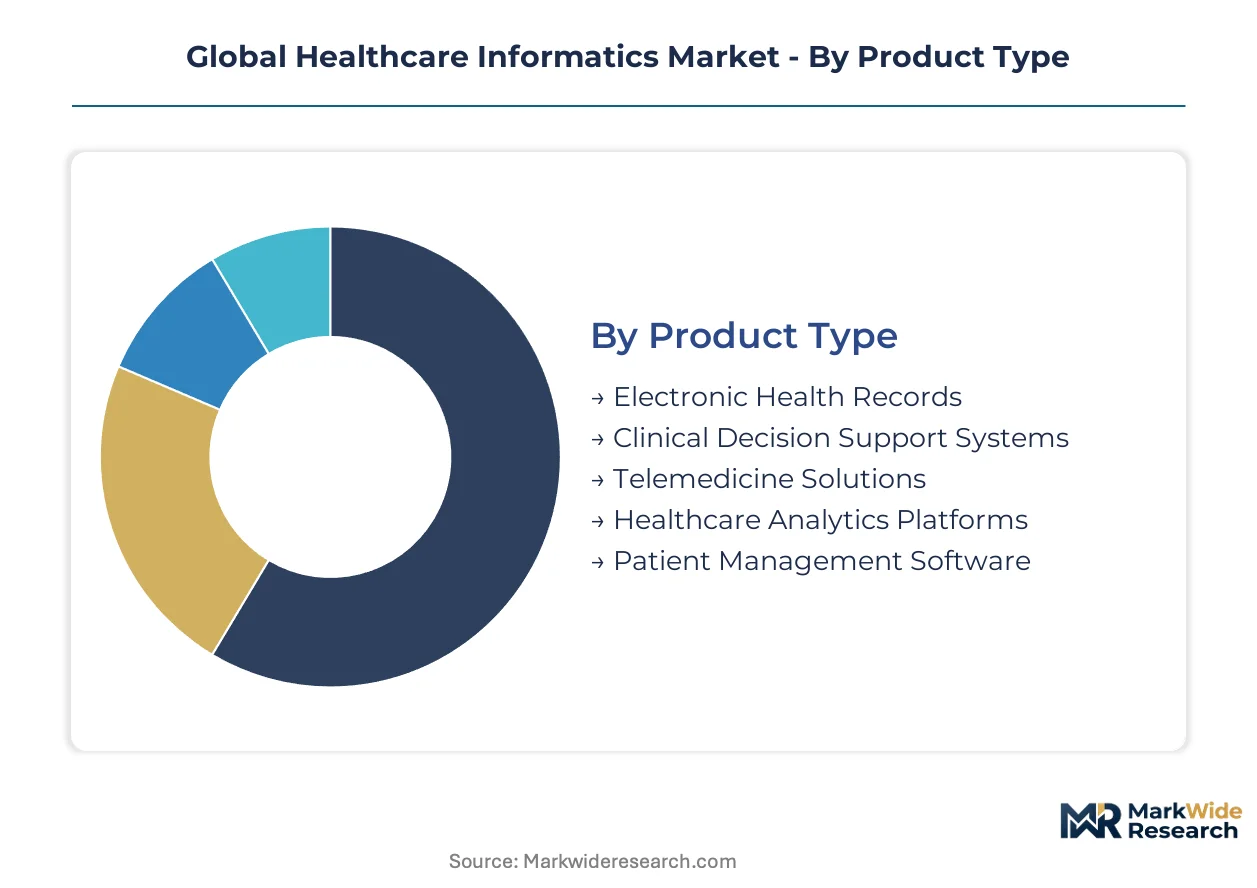
Healthcare informatics segmentation reveals distinct procurement patterns across product architectures, clinical applications, and infrastructure models. Vendor strategies diverge sharply between enterprise hospital systems and distributed ambulatory networks.
Product Type:
Electronic Health Records and Clinical Decision Support Systems anchor procurement in Germany and the United States, while Telemedicine Solutions and Healthcare Analytics Platforms drive export-led growth into India and Brazil.
- Electronic Health Records:Core patient data repositories built on HL7 FHIR interoperability protocols. United States hospital systems under HIPAA mandates prioritize modular EHR architectures that permit API-driven substitution of analytics layers.
- Clinical Decision Support Systems:Algorithmic diagnostic assistants requiring FDA software-as-medical-device certification. German procurement committees under the Hospital Future Act favor integrated CDSS bundles over standalone deployments.
- Telemedicine Solutions:Real-time clinical consultation platforms with embedded video diagnostics and prescription workflows.
- Healthcare Analytics Platforms:Predictive modeling engines processing population-level datasets for resource optimization.
- Patient Management Software:Scheduling, billing, and registration systems bridging front-desk operations with clinical workflows.
Electronic Health Records holds the largest share; momentum sits with Healthcare Analytics Platforms.
Application:
Population Health Management and Remote Patient Monitoring concentrate in value-based care contracts, while Medical Imaging Analysis and Workflow Automation spread across fee-for-service and capitated reimbursement models.
- Population Health Management:Aggregate risk stratification tools identifying high-utilization cohorts for intervention. United States integrated delivery networks bundle PHM analytics with Medicare Advantage contracts to capture shared savings.
- Remote Patient Monitoring:Continuous physiological data capture from wearable and implantable sensors. German hospital systems deploy RPM infrastructure to reduce readmission penalties under federal quality metrics.
- Medical Imaging Analysis:AI-augmented radiological interpretation for lesion detection and quantification.
- Workflow Automation:Robotic process automation eliminating administrative bottlenecks in prior authorization and coding.
- Data Integration:Master data management harmonizing patient identifiers across merged hospital systems.
Population Health Management commands the dominant installed base; Remote Patient Monitoring is climbing the fastest.
End User:
Hospitals and Diagnostic Laboratories absorb premium-priced enterprise licenses, while Ambulatory Care Centers and Nursing Homes gravitate toward subscription-tier deployments with deferred capital requirements.
- Hospitals:Multi-site health systems requiring enterprise-scale interoperability across emergency, inpatient, and surgical departments. Academic medical centers in the United States reorganize procurement around AI-enabled diagnostic workflows.
- Diagnostic Laboratories:High-throughput pathology and genomics facilities integrating LIS with EHR order-entry systems. Indian tertiary hospitals under CDSCO-aligned regulations create entry pathways for certified clinical decision support vendors.
- Research Institutes:Clinical trial data management and real-world evidence generation platforms.
- Ambulatory Care Centers:Federated clinic networks requiring lightweight cloud-native architectures.
- Nursing Homes:Long-term care facilities prioritizing medication management and fall-risk monitoring.
Hospitals dominate absolute spending; Ambulatory Care Centers are gaining share fastest.
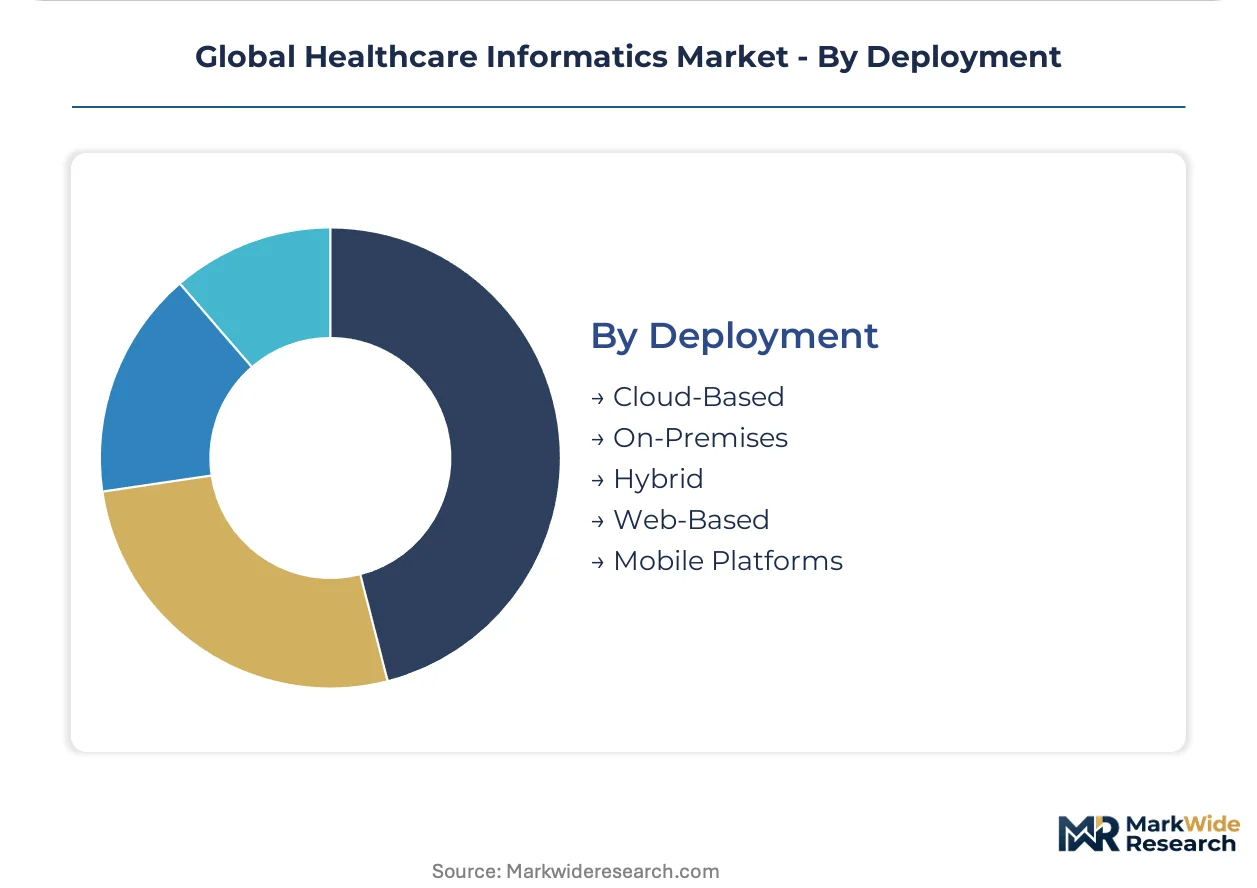
Deployment:
Cloud-Based and Hybrid architectures displace On-Premises infrastructure among mid-tier hospitals seeking operational expenditure models, while Web-Based and Mobile Platforms penetrate rural and point-of-care environments.
- Cloud-Based:Hyperscale-hosted environments with elastic compute for machine learning inference. Mid-tier United States hospitals defer capital expenditure through subscription pricing, though vendor lock-in risks concentrate around AWS, Azure, and Google Cloud.
- Hybrid:Sensitive data retained on-premises with burst compute dispatched to cloud infrastructure. German hospital digitization incentives under the Hospital Future Act reshape procurement budgets toward hybrid architectures satisfying EU MDR cybersecurity annexes.
- On-Premises:Legacy proprietary servers resisting modular substitution due to technical debt.
- Web-Based:Browser-accessible applications eliminating client-side installation requirements.
- Mobile Platforms:Tablet and smartphone-integrated decision support for bedside and home care.
On-Premises retains the largest legacy footprint; Cloud-Based shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German healthcare informatics vendors export clinical decision support systems to United States academic medical centers under FDA software-as-medical-device certification pathways. This transatlantic trade corridor channels European algorithmic innovation into American hospital procurement cycles.
United States
Academic medical centers in Boston and Stanford reorganize procurement around AI-enabled diagnostic workflows. FDA software-as-medical-device guidelines compress vendor certification timelines while elevating compliance barriers. Epic Systems anchors enterprise contracts across integrated delivery networks from its Wisconsin headquarters.
Germany
Federal hospital digitization incentives under the Hospital Future Act redirect capital toward integrated clinical decision support systems. EU MDR cybersecurity annexes reshape procurement specifications for cloud-hosted patient data. Siemens Healthineers sustains R&D intensity in digital twin applications from its Erlangen operations.
India
Tertiary hospital digitization in Maharashtra and Karnataka creates entry pathways for certified clinical decision support vendors. CDSCO regulatory alignment with international standards accelerates import clearance for algorithmic diagnostic tools. Hyderabad's health technology cluster attracts hyperscale cloud infrastructure investments.
United Kingdom
NHS integrated care systems consolidate vendor relationships around enterprise-scale platform contracts. GDPR interoperability mandates intersect with post-Brexit regulatory divergence from EU MDR frameworks. London's digital health corridor concentrates health analytics startups seeking NHS procurement pathways.
Japan
PMDA software-as-medical-device classifications accelerate market entry for algorithmic diagnostic tools from overseas vendors. METI hospital digitization subsidies support cloud migration among mid-tier regional medical centers. Tokyo-Osaka health technology corridor hosts domestic imaging informatics specialists.
Global Healthcare Informatics Market Competitive Landscape
Listed leaders compete with private specialists across certification depth and enterprise contract scale. The vendor base stratifies between imaging hardware incumbents expanding into software layers and pure-play analytics platforms seeking hospital system anchor clients. Three archetypes dominate: integrated imaging-to-informatics conglomerates, electronic health record platform owners, and cloud-native algorithmic specialists. Consolidation concentrates around enterprise-scale bundles while modular substitution threats pressure perpetual license margins.
Within the integrated hardware-software tier, GE HealthCare and Siemens Healthineers represent imaging informatics incumbents leveraging installed radiological equipment bases. Epic Systems occupies a distinct position as electronic health record platform owner feeding downstream analytics modules. Among IT services specialists, Cognizant and Accenture exemplify system integrators bridging legacy infrastructure with cloud-native deployments.
| Leading Market Players |
|---|
| GE HealthCare |
| Philips Healthcare |
| McKesson Corporation |
| Cognizant |
| Accenture |
| Epic Systems |
| Siemens Healthineers |
| Allscripts Healthcare Solutions |
| Oracle Cerner |
| Others |
Supply & Pricing Matrix
Hyperscale cloud infrastructure concentration in the United States and Germany creates procurement leverage that compresses margins for mid-tier hospital systems while elevating price floors for enterprise-grade clinical decision support systems with FDA software-as-medical-device certification.
Pricing Analysis
Current-generation cloud-native analytics platforms command subscription premiums against prior-generation on-premises licensing and next-generation edge-computing deployments. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA certification tier and HL7 FHIR interoperability depth. Pricing pressure stems from mid-tier hospital budget constraints under deferred capital expenditure models. Ambulatory care centers exhibit highest price sensitivity; academic medical centers demonstrate lowest sensitivity due to bundled enterprise contracting.
Supply Chain Analysis
The United States anchors hyperscale cloud hosting infrastructure for clinical data, Germany concentrates digital twin simulation hardware production, and India assembles point-of-care tablet-integrated diagnostic devices. Component dependencies include GPU accelerators for machine learning inference, specialized medical-grade displays, and encrypted storage arrays. Single-source vulnerability concentrates around AWS, Azure, and Google Cloud for health data hosting. Distribution runs through group purchasing organizations and integrated delivery network procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital digitization mandates are driving a cyclical recovery as federal procurement budgets redirect capital toward analytics platforms and AI-enabled diagnostic workflows.
For Market Incumbents: Consolidate enterprise-scale platform contracts across imaging informatics, electronic health records, and predictive analytics layers to defend against modular substitution threats. Deepen FDA software-as-medical-device certification portfolios to maintain pricing power against cloud-native algorithmic specialists. Prioritize HL7 FHIR interoperability engineering capacity to capture German Hospital Future Act incentive flows. For New Entrants and Emerging Players: Lead with point-of-care analytics hardware miniaturization targeting rural health clinics and ambulatory surgical centers in India and Brazil. Exploit CDSCO regulatory alignment pathways for certified clinical decision support systems. Deploy tablet-integrated subscription pricing to bypass traditional capital expenditure barriers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors cloud-native algorithmic specialists with established EU notified body relationships and federated learning protocol capabilities. Long-term viability over the next decade hinges on post-market monitoring infrastructure for EU AI Act compliance. Watch FDA liability framework shifts as the inflection indicator for risk allocation between vendors and health systems.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software-as-Medical-Device Submission | Accelerates market entry for algorithmic diagnostic tools under compressed certification timelines. |
| Hospital System Partnership | Secures anchor clients for enterprise-scale platform bundles across integrated delivery networks. |
| CE Marking Pathway | Unlocks German procurement committees prioritizing EU notified body relationships under MDR annexes. |
| Software Companion Development | Extends imaging hardware incumbents into high-margin analytics subscription revenue pools. |
| Reimbursement Strategy | Captures shared savings in United States Medicare Advantage population health management contracts. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with hospital procurement committee members, biomedical engineers, GPO contracts managers, and clinical informatics officers; and secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement registries, and EU MDR notified body certification records. Bottom-up and top-down triangulation cross-validated vendor revenue estimates against federal digitization budget disclosures.
Across the projection horizon, the analytical framework modeled segmentation across deployment architecture, end-user scale tier, clinical application type, and regional regulatory cluster. CAGRs derived from elasticity-adjusted adoption curves incorporating hospital capital expenditure cycles and cloud infrastructure penetration rates. Forecast inputs included HL7 FHIR interoperability implementation timelines and EU AI Act risk classification rollout patterns.
The analysis sits within stated boundaries; outcomes outside sustained federal digitization incentives or accelerated FDA certification pathways would require recalibration. Forecasts reflect documented assumptions regarding cloud infrastructure concentration and multi-jurisdiction compliance synchronization feasibility. Recalibration cycles align with material shifts in FDA software-as-medical-device guidance and EU MDR cybersecurity enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Informatics
Global Laboratory Information System Market
Health Informatics
IHE XDS.B Market
Health Informatics
Global Healthcare Business Intelligence (BI) Market
Health Informatics
Healthcare Prescriptive Analytics Market
Health Informatics
Global Cardiology Information System Market
Health Informatics
Healthcare Cybersecurity Market
Health Informatics
Laboratory Informatics Market
Health Informatics
US Laboratory Informatics Market
Health Informatics
Cat Allergy in Humans Market
Health Informatics
Healthcare Laboratory Informatics Market
Health Informatics
Healthcare Clinical Analytics Market
Health Informatics
Healthcare Natural Language Processing Market
Health Informatics
AI in Healthcare Market
Health Informatics
Global Natural Language Processing (NLP) in Healthcare and Life Sciences Market
Health Informatics
Health Information Exchange (HIE) Market
Health Informatics
Global Non Clinical Information System Market