
 Global Pediatric Magnetic Resonance Imaging (MRI) Market | 2026-2036
Global Pediatric Magnetic Resonance Imaging (MRI) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pediatric Magnetic Resonance Imaging (MRI) Market Foresight
Aftermarket service revenue is fragmenting as OEMs and third-party providers compete for multi-vendor maintenance contracts across installed pediatric MRI bases. Siemens Healthineers leverages its remote diagnostic platforms to sustain long-term service agreements in European children's hospitals. GE HealthCare anchors its position through proprietary helium conservation technologies that reduce operating costs for high-field systems. Koninklijke Philips NV differentiates via adaptive scanning protocols that minimize sedation requirements in neonatal populations.
Pediatric magnetic resonance imaging employs magnetic fields and radio waves to generate detailed anatomical images without ionizing radiation, typically operating at field strengths from 0.5 Tesla to 3.0 Tesla with specialized surface coils sized for neonatal through adolescent body dimensions. Closed MRI systems dominate current installed bases due to superior signal-to-noise ratios for neurological and oncological diagnostics, while open MRI configurations address claustrophobia and patient positioning challenges in orthopedic and cardiac applications. Functional MRI represents the fastest-growing technology segment as research institutions and pediatric hospitals integrate real-time brain activity mapping into pre-surgical planning for epilepsy and tumor resections.
The FDA enforces stringent premarket review for pediatric-specific MRI coils and contrast agents under its pediatric device consortia framework, while the EU Medical Device Regulation mandates clinical evidence for child-applicable indications beyond adult-equivalent clearances. Japan's PMDA requires localized pediatric safety data for high-field systems, creating divergent approval pathways that shape manufacturer regional launch sequencing. Stakeholders must monitor evolving helium supply constraints and cryogen-free magnet alternatives that could reshape total cost of ownership calculations for pediatric imaging programs.
Market Dynamics
Helium supply constraints are forcing pediatric MRI programs to reassess total cost of ownership, accelerating adoption of cryogen-free magnet architectures and remote service models that reduce dependency on scarce cryogenic resources.
Growth Catalysts
- FDA Pediatric Device Consortia:Streamlined premarket pathways for child-optimized coils reduce regulatory friction and accelerate time-to-market for specialized neonatal imaging hardware.
- Sedation-free protocols:Adaptive scanning algorithms minimize anesthesia requirements in university children's hospitals, expanding eligible patient populations and throughput capacity.
- German referral networks:University children's hospitals in Heidelberg, Munich, and Berlin anchor centralized neuroimaging hubs that concentrate complex case volumes and justify dedicated high-field installations.
Market Restraints
- Helium price volatility:Global helium supply concentration in Qatar and the United States creates input cost uncertainty for conventional superconducting magnet operations.
- PMDA pediatric data requirements:Japan's regulator mandates localized safety trials for high-field systems, extending approval timelines and delaying regional product launches.
- CT substitution in trauma:Emergency departments default to computed tomography for acute pediatric cases due to MRI's scan duration and motion sensitivity limitations.
Strategic Opportunities
- India pediatric imaging gap:Underpenetrated tertiary care infrastructure in Maharashtra and Karnataka creates whitespace for mid-field systems with simplified siting requirements.
- AI-assisted reconstruction:Deep learning algorithms converging with accelerated acquisition protocols enable diagnostic-quality imaging at reduced field strengths.
- EU MDR Article 61:Clinical evidence requirements for pediatric-specific indications create first-mover advantages for manufacturers with established child safety databases.
Industry Challenges
- Pediatric radiologist scarcity:Fellowship-trained specialists capable of interpreting neonatal neuroimaging remain concentrated in academic medical centers, limiting community hospital service expansion.
- Legacy system integration:PACS interoperability with proprietary vendor formats complicates multi-site image sharing across regional children's hospital networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pediatric Magnetic Resonance Imaging (MRI) Market |
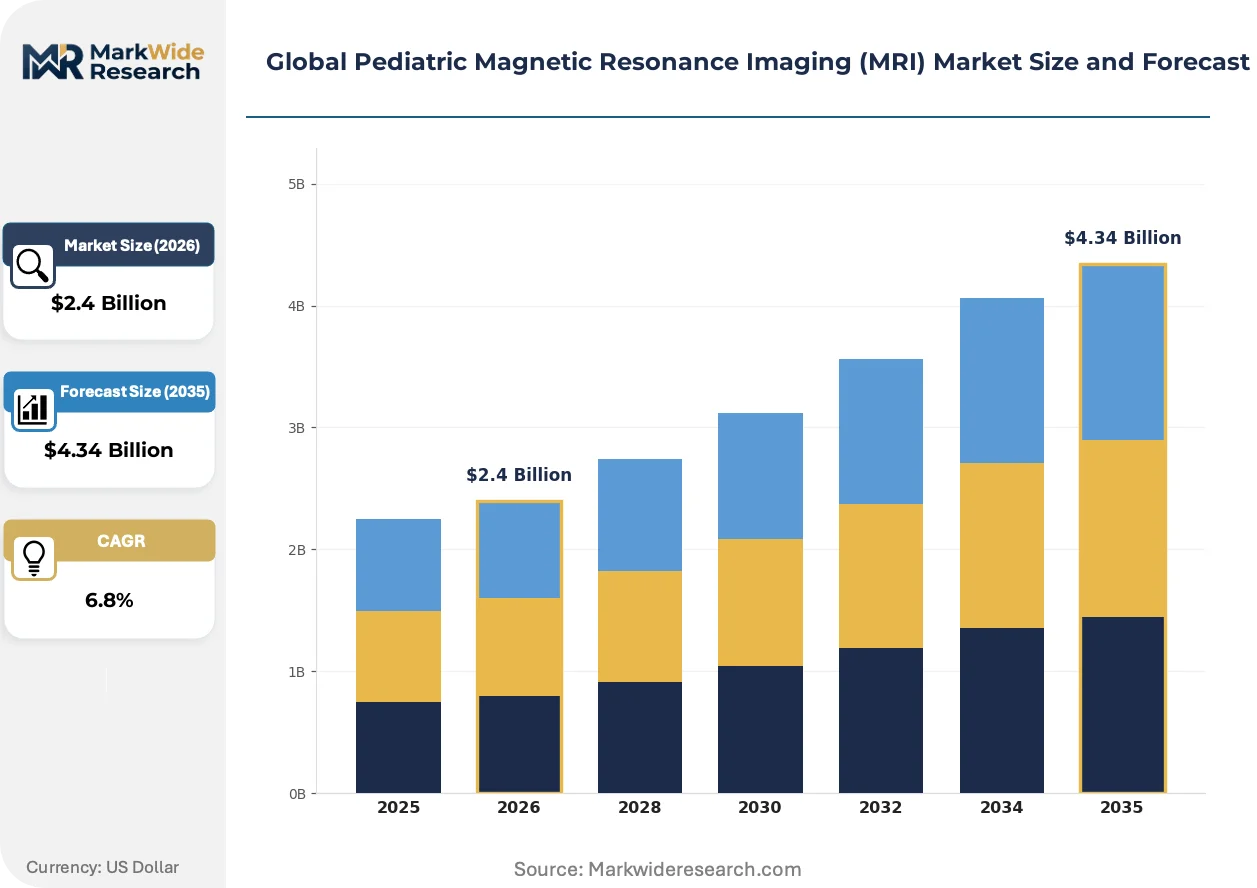
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open MRI, Closed MRI, Extremity MRI, Functional MRI Technology: Proton MRI, High-Field MRI, Ultra-High-Field MRI, Dynamic MRI Application: Neurology, Oncology, Orthopedics, Cardiology End User: Pediatric Hospitals, Imaging Centers, Research Institutions, Private Clinics |
| Companies Covered | Siemens Healthineers AG, GE HealthCare, Koninklijke Philips NV, Neoscan Solutions GmbH, Fujifilm Holdings Corporation, Aspect Imaging Ltd, Hyperfine Inc, LMT Medical Systems GmbH, NORAS MRI products GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pediatric Magnetic Resonance Imaging (MRI) Market Shifts & Advancements
Artificial intelligence is compressing scan times while preserving diagnostic fidelity, fundamentally altering the economics of pediatric MRI service lines and enabling same-day discharge protocols previously requiring overnight observation.
Compressed sensing reconstruction is collapsing the trade-off between image resolution and acquisition speed in functional neuroimaging. Research institutions at Boston Children's Hospital and Great Ormond Street Hospital are deploying these algorithms for pre-surgical epilepsy mapping, reducing scan durations from forty-five minutes to under fifteen minutes. This compression is collapsing the staffing cost structure of pediatric MRI suites and expanding eligible patient age ranges downward into unsedated infant populations.
The EU Medical Device Regulation's pediatric evidence requirements are reshaping manufacturer clinical trial investments. MDR Article 61 mandates child-specific safety and performance data beyond adult-equivalent clearances, forcing sponsors to maintain parallel pediatric cohorts. High-field cardiac applications face the steepest compliance burden, with notified bodies in Germany and the Netherlands demanding extended follow-up periods for hemodynamically unstable neonates.
After-sales service unbundling is fragmenting long-term vendor relationships in European children's hospitals. Procurement departments in France and the United Kingdom are separating hardware maintenance from software upgrade contracts, awarding multi-vendor service agreements to independent technical service organizations. This disintermediation is most advanced in the Benelux region, where hospital consortia leverage collective bargaining power to standardize service level agreements across heterogeneous installed bases.
Global Pediatric Magnetic Resonance Imaging (MRI) Market Segmentation
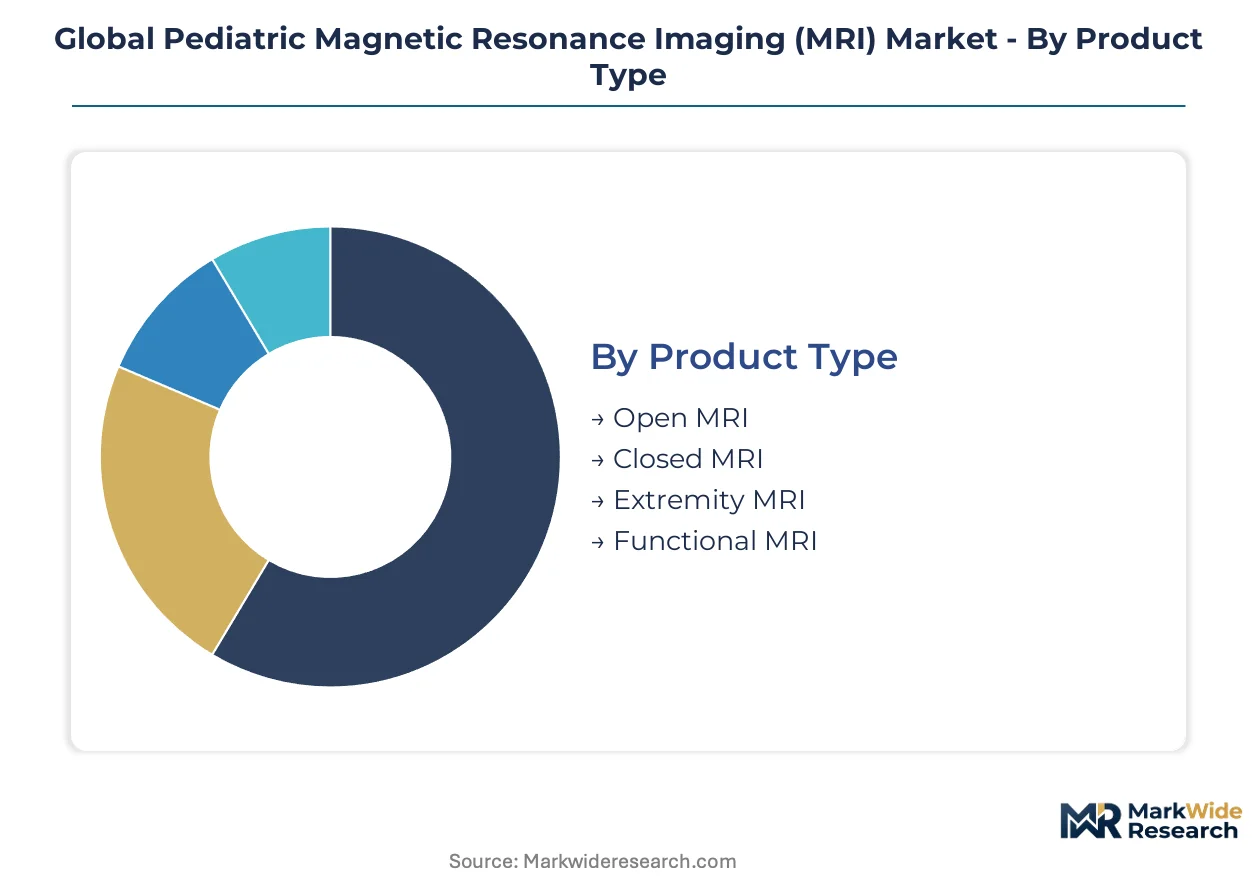
Pediatric MRI segmentation reflects divergent clinical workflows across diagnostic specialties and facility capabilities. Product architecture, field strength configurations, and end-user infrastructure requirements create distinct commercial compartments with non-overlapping procurement criteria.
Product Type:
Mature closed-bore systems anchor installed bases while emerging configurations address unmet positioning and accessibility needs.
- Closed MRI:Superconducting cylindrical bore designs deliver superior signal-to-noise ratios for neurological and oncological diagnostics. German university children's hospitals in Heidelberg and Munich concentrate procurement of 3.0 Tesla closed systems for complex neuroimaging referrals.
- Functional MRI:Real-time blood-oxygen-level-dependent imaging enables pre-surgical brain mapping for epilepsy and tumor resections. Boston Children's Hospital and Great Ormond Street Hospital deploy these systems for intraoperative navigation protocols.
- Open MRI:Vertical or horizontal gap architectures accommodate claustrophobic patients and enable intraoperative access. Pediatric orthopedic applications in Japan drive adoption where positioning flexibility outweighs field strength limitations.
- Extremity MRI:Dedicated limb scanners with reduced siting requirements target sports medicine and rheumatology workflows. Lower capital costs attract private clinic segments in India and Southeast Asia.
Closed MRI retains volume leadership; Functional MRI holds the steepest expansion curve.
Technology:
Cost tier stratification separates premium ultra-high-field research systems from standardized clinical workhorses.
- High-Field MRI:1.5 Tesla to 3.0 Tesla systems constitute the clinical standard for diagnostic accuracy. European children's hospitals under EU MDR Article 61 concentrate procurement here due to established pediatric safety databases.
- Ultra-High-Field MRI:7.0 Tesla and above systems enable sub-millimeter resolution for research applications. Research institutions in the United States and Germany justify capital intensity through grant-funded neurodevelopmental studies.
- Proton MRI:Hydrogen nucleus imaging remains the foundational modality across all field strengths. Widespread technical familiarity sustains its dominance in community hospital settings.
- Dynamic MRI:Real-time cardiac and respiratory-gated acquisition protocols capture moving anatomy. Cardiology applications in pediatric hospitals face steep regulatory validation requirements under PMDA and FDA pediatric device pathways.
High-Field MRI dominates procurement volumes; Ultra-High-Field MRI commands the premium tier expansion.
Application:
Volume concentration in neurology contrasts with emerging utilization patterns in cardiac and musculoskeletal domains.
- Neurology:Brain and spine imaging constitutes the primary volume driver across all pediatric age groups. German referral networks anchor complex case concentration for epilepsy, malformations, and neurooncology.
- Oncology:Staging and treatment response monitoring for pediatric cancers demands high-resolution soft tissue contrast. St. Jude Children's Research Hospital and similar institutions drive protocol standardization.
- Orthopedics:Sports injuries and congenital musculoskeletal anomalies utilize extremity-optimized coils. Sedation-free protocols expand eligible patient populations in community settings.
- Cardiology:Congenital heart defect assessment requires specialized gating and high temporal resolution. Limited pediatric radiologist expertise constrains service line expansion outside academic centers.
Neurology captures the largest procedure volume; Cardiology presents the most constrained but highest-value growth pathway.
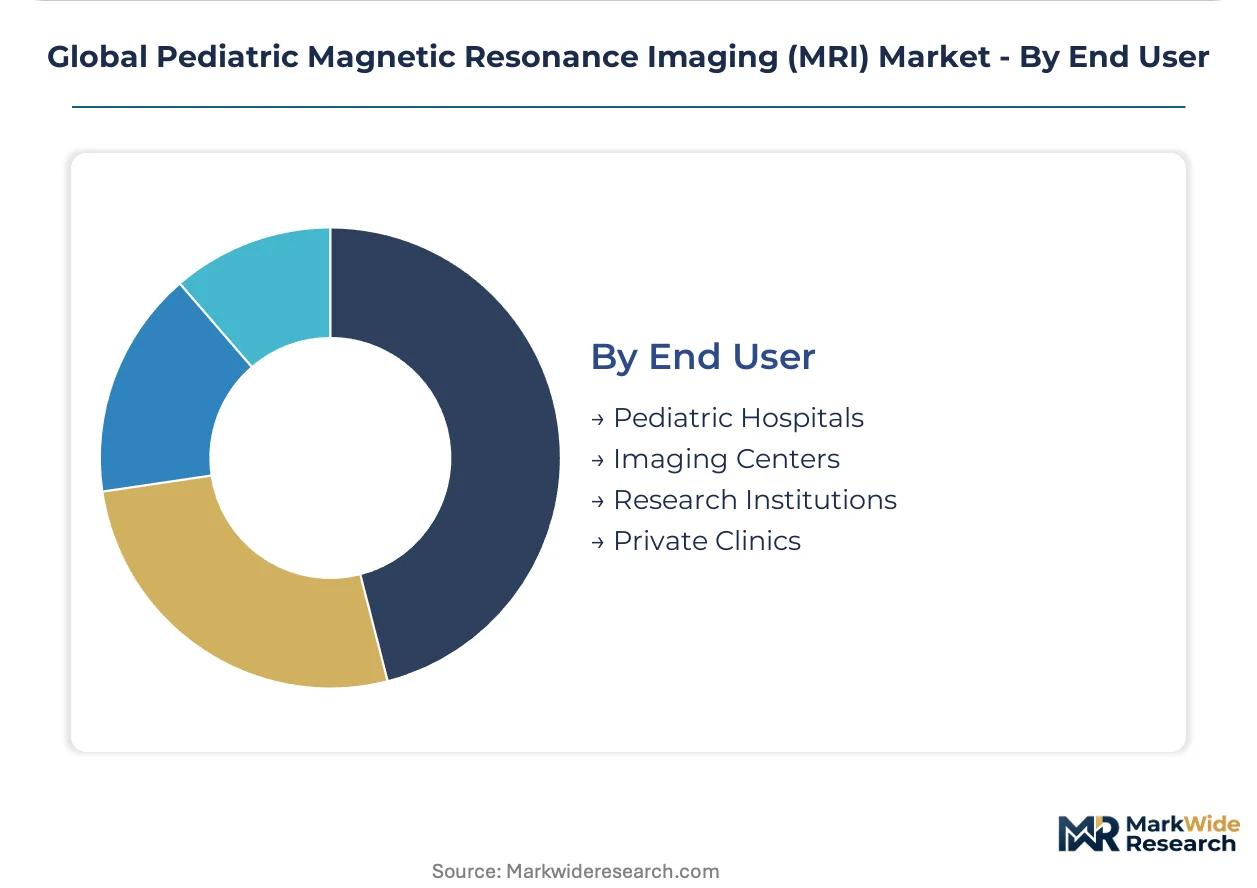
End User:
Customer type determines capital intensity, service contract structure, and regulatory compliance burden.
- Pediatric Hospitals:Dedicated children's hospitals maintain highest scan volumes and most complex case mix. University-affiliated centers in Germany, the United States, and Japan anchor regional referral networks.
- Research Institutions:Academic medical centers prioritize ultra-high-field systems and functional imaging capabilities. Grant funding cycles create lumpy procurement patterns distinct from clinical replacement demand.
- Imaging Centers:Independent diagnostic facilities focus on throughput optimization and standardized protocols. Multi-vendor service agreements fragment traditional OEM relationships.
- Private Clinics:Smaller capital bases favor extremity systems and open configurations with reduced siting costs. India's Maharashtra and Karnataka states show emerging demand concentration.
Pediatric Hospitals sustain installed base dominance; Research Institutions generate the highest per-unit technology premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across pediatric MRI markets. German university hospitals absorb premium pricing for 3.0 Tesla systems, while Indian private clinics prioritize mid-field configurations with minimal siting costs. This divergence shapes manufacturer regional launch sequencing and service model design.
Germany
Heidelberg and Munich anchor Europe's densest concentration of pediatric neuroimaging referrals. The EU MDR Article 61 framework mandates child-specific clinical evidence beyond adult clearances, extending validation timelines for high-field cardiac applications. Siemens Healthineers maintains remote diagnostic platforms across university children's hospital networks in Baden-Württemberg and Bavaria.
United States
Boston Children's Hospital and St. Jude Children's Research Hospital drive functional MRI adoption for pre-surgical epilepsy mapping. FDA pediatric device consortia streamline premarket pathways for specialized neonatal coils, reducing regulatory friction versus EU counterparts. Grant-funded research institutions in Massachusetts and Tennessee justify ultra-high-field 7.0 Tesla installations.
Japan
PMDA mandates localized pediatric safety trials for high-field systems, delaying product launches versus Western markets. Tokyo and Osaka academic medical centers concentrate demand for cardiac-gated dynamic MRI in congenital heart defect assessment. Open MRI configurations gain traction in orthopedic applications where positioning flexibility outweighs field strength trade-offs.
India
Maharashtra and Karnataka present underpenetrated whitespace for mid-field systems with simplified infrastructure requirements. CDSCO regulatory pathways for imported medical devices create clearance bottlenecks for premium-tier manufacturers. Private imaging centers in Mumbai and Bangalore prioritize extremity MRI for sports medicine workflows at lower capital thresholds.
United Kingdom
Great Ormond Street Hospital deploys compressed sensing algorithms that collapse scan durations for unsedated infant populations. NHS procurement consortia unbundle hardware maintenance from software upgrade contracts, fragmenting traditional OEM service relationships. London anchors national referral networks for complex oncological staging in pediatric populations.
Global Pediatric Magnetic Resonance Imaging (MRI) Market Competitive Landscape
Capability concentration sits with diversified imaging conglomerates; scale advantage sits with regional specialists in neonatal coil design. The vendor base stratifies across three tiers: full-platform manufacturers with remote service infrastructure, mid-field specialists addressing claustrophobia and positioning constraints, and extremity-focused players targeting private clinic price sensitivity. Dominant competitive moves include helium conservation technology licensing and adaptive scanning protocol partnerships with university research hospitals.
Among diversified health technology conglomerates, Siemens Healthineers AG and GE HealthCare exemplify full-platform archetypes with established pediatric safety databases and cryogen-free magnet development pipelines. Koninklijke Philips NV occupies a position within the adaptive protocol tier, with specialized positioning in sedation-minimization technologies for neonatal populations. Neoscan Solutions GmbH represents the mid-field specialist archetype, targeting European children's hospitals with compact system architectures that reduce siting complexity.
| Leading Market Players |
|---|
| Siemens Healthineers AG |
| GE HealthCare |
| Koninklijke Philips NV |
| Neoscan Solutions GmbH |
| Fujifilm Holdings Corporation |
| Aspect Imaging Ltd |
| Hyperfine Inc |
| LMT Medical Systems GmbH |
| NORAS MRI products GmbH |
| Others |
Supply & Pricing Matrix
Qatar's Ras Laffan helium production complex anchors global cryogen supply for superconducting magnet operations, with its capacity constraints translating directly into input cost volatility for pediatric MRI programs dependent on conventional high-field systems. German university children's hospitals absorb premium pricing for 3.0 Tesla installations, while Indian private clinics in Maharashtra face capital thresholds that compress procurement toward mid-field configurations with minimal siting infrastructure.
Pricing Analysis
After-sales service contracts generate lifetime value exceeding hardware margins, with multi-vendor maintenance agreements fragmenting traditional OEM pricing power across European hospital consortia. Three-tier pricing structure across premium, standard, and economy levels separates research-grade ultra-high-field systems from clinical workhorses and compact extremity configurations. Cost compression in helium-dependent superconducting tiers is intensifying because cryogen price volatility feeds directly into operating expenditure calculations. Private imaging centers in India and Southeast Asia exhibit highest price sensitivity, while German academic medical centers demonstrate lowest elasticity due to grant-funded procurement and complex case concentration.
Supply Chain Analysis
Helium supply concentration between Qatar and the United States dominates upstream risk profiles for conventional magnet architectures, forcing accelerated development of cryogen-free alternatives. Superconducting wire production draws from Japan and Germany, with niobium-titanium alloy supply resting on mining operations in Brazil and Canada. Single-source vulnerability in specialized pediatric coil manufacturing concentrates with German and Japanese component suppliers. Distribution runs through regional equipment distributors serving hospital procurement committees, with direct OEM relationships persisting only for research institution sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pediatric MRI markets operate as a defensive-moat story where regulatory entrenchment through FDA pediatric device consortia and EU MDR Article 61 creates structural barriers to rapid competitive displacement. Switching costs between proprietary coil formats and PACS interoperability standards further cement incumbent positions.
For Market Incumbents: Pre-empt cryogen-free magnet adoption curves by licensing helium conservation technologies to installed base customers before third-party retrofit providers capture service revenue. Vertical integration into neonatal coil manufacturing secures supply continuity against single-source component risks from German and Japanese specialists. Capacity addition in cryogen-free architectures for European university children's hospitals addresses the steepest regulatory compliance burden under EU MDR pediatric evidence requirements.
For New Entrants and Emerging Players: Pursue mid-field system whitespace in Maharashtra and Karnataka where underpenetrated tertiary infrastructure meets price-sensitive private clinic demand. Compact extremity configurations with simplified siting requirements represent the most penetrable product tier against entrenched full-platform manufacturers. Hospital system partnership models with state-level procurement consortia in India bypass direct competition with Siemens Healthineers and GE HealthCare service infrastructures.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among service-integrated OEMs with remote diagnostic platforms and long-term maintenance agreements across heterogeneous installed bases. Long-term viability over a five-to-ten year window favors manufacturers with established pediatric safety databases under FDA and EU MDR frameworks. Acquisition target archetype: mid-field specialists with cryogen-free magnet architectures and compact system designs. The signal to watch is helium price volatility acceleration driving substitution demand toward cryogen-free alternatives.
| Strategic Initiative | Industry Significance |
|---|---|
| Cryogen-Free Magnet Development | Helium supply constraints at Qatar's Ras Laffan complex accelerate manufacturer R&D prioritization of superconducting alternatives. |
| FDA Pediatric Device Consortia Engagement | Streamlined premarket pathways for neonatal coils reduce regulatory friction versus EU MDR Article 61 compliance timelines. |
| Multi-Vendor Service Agreement Expansion | Independent technical service organizations capture procurement unbundling trends in NHS and Benelux hospital consortia. |
| AI-Assisted Reconstruction Partnership | Compressed sensing algorithms at Boston Children's Hospital and Great Ormond Street Hospital collapse scan duration economics. |
| India Distribution Channel Establishment | CDSCO regulatory navigation and state-level procurement relationships unlock Maharashtra and Karnataka whitespace demand. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with pediatric radiologists, hospital biomedical engineers, GPO contracts managers, and MRI service technicians. Secondary validation drew from FDA 510(k) filings, EU MDR notified body documentation, CMS Medicare reimbursement databases, and hospital procurement records. Bottom-up installation base modeling triangulated against top-down market sizing across product architecture, field strength tier, and end-user facility type.
Calibration against historical replacement cycles and grant-funded research procurement patterns anchored volume projections across the modeling period. Segmentation dimensions included product configuration, technology tier, clinical application specialty, and customer facility type. CAGRs were derived from elasticity-adjusted demand curves incorporating helium price scenario analysis and regulatory approval timeline differentials by geography. Forecast inputs weighted PMDA pediatric data requirements for Japan against FDA streamlined pathways for neonatal coil clearances.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cryogen-free magnet specialists or AI reconstruction platform entrants would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Fluoroscopy and Mobile C-Arms Market
Medical Imaging
C-Arms Market
Medical Imaging
North America Nuclear Medicine Market
Medical Imaging
AI Fetal Ultrasound View Detection Software Market
Medical Imaging
Global Contrast-Enhanced Ultrasound Market
Medical Imaging
Mexico Diagnostic Imaging Equipment Market
Medical Imaging
Italy Digital Radiology Market
Medical Imaging
Vendor Neutral Archive Market
Medical Imaging
Ultrasound Image Processing Software Market
Medical Imaging
Australia Mammography Market
Medical Imaging
Argentina Diagnostic Imaging Equipment Market
Medical Imaging
Ultrasound Systems Market
Medical Imaging
Canada Computed Tomography Market
Medical Imaging
Italy Diagnostic Imaging Equipment Market
Medical Imaging
US Digital Radiology Market
Medical Imaging
Cone Beam CT Scanner Market