
 Canada Mammography Market | 2026-2036
Canada Mammography Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Mammography Market Outlook
Software-defined image reconstruction and AI-assisted diagnostic overlays are recalibrating how mammography systems generate recurring revenue beyond hardware placement. Hologic Inc. leverages its integrated assay-to-imaging workflow to anchor high-margin service contracts across Canadian hospital networks. Siemens Healthineers sustains R&D intensity in photon-counting detector technology, while GE Healthcare Technologies Inc. competes through its established distribution footprint in provincial screening tenders.
Mammography encompasses X-ray-based breast imaging systems designed to detect microcalcifications and soft-tissue masses at spatial resolutions below 100 micrometers, with modern digital detectors replacing phosphor-based film cassettes to enable computer-aided detection and tomographic reconstruction. Its primary purpose is population-scale early-stage breast cancer screening and diagnostic workup. Digital mammography occupies the mature installed base where replacement cycles now dominate new-site expansion, while 3D mammography represents the fastest-growing product category as provincial programs fund tomosynthesis upgrades. Screening services capture the largest volume share among service types, though diagnostic services command premium reimbursement rates due to their complex interpretation requirements.
Health Canada's Medical Devices Directorate enforces pre-market licensing and post-market surveillance under the Medical Devices Regulations, shaping product entry timelines and clinical evidence requirements for new mammography technologies. The Canadian Association of Radiologists publishes quality standards and accreditation criteria that directly influence hospital procurement specifications and provincial tender scoring. Provincial health authorities in Ontario, British Columbia, and Alberta operate centralized capital equipment budgets that determine regional deployment velocity. Stakeholders must monitor how provincial screening program expansions and AI reimbursement policy developments interact to reshape capital allocation priorities across the forecast horizon.
Market Dynamics
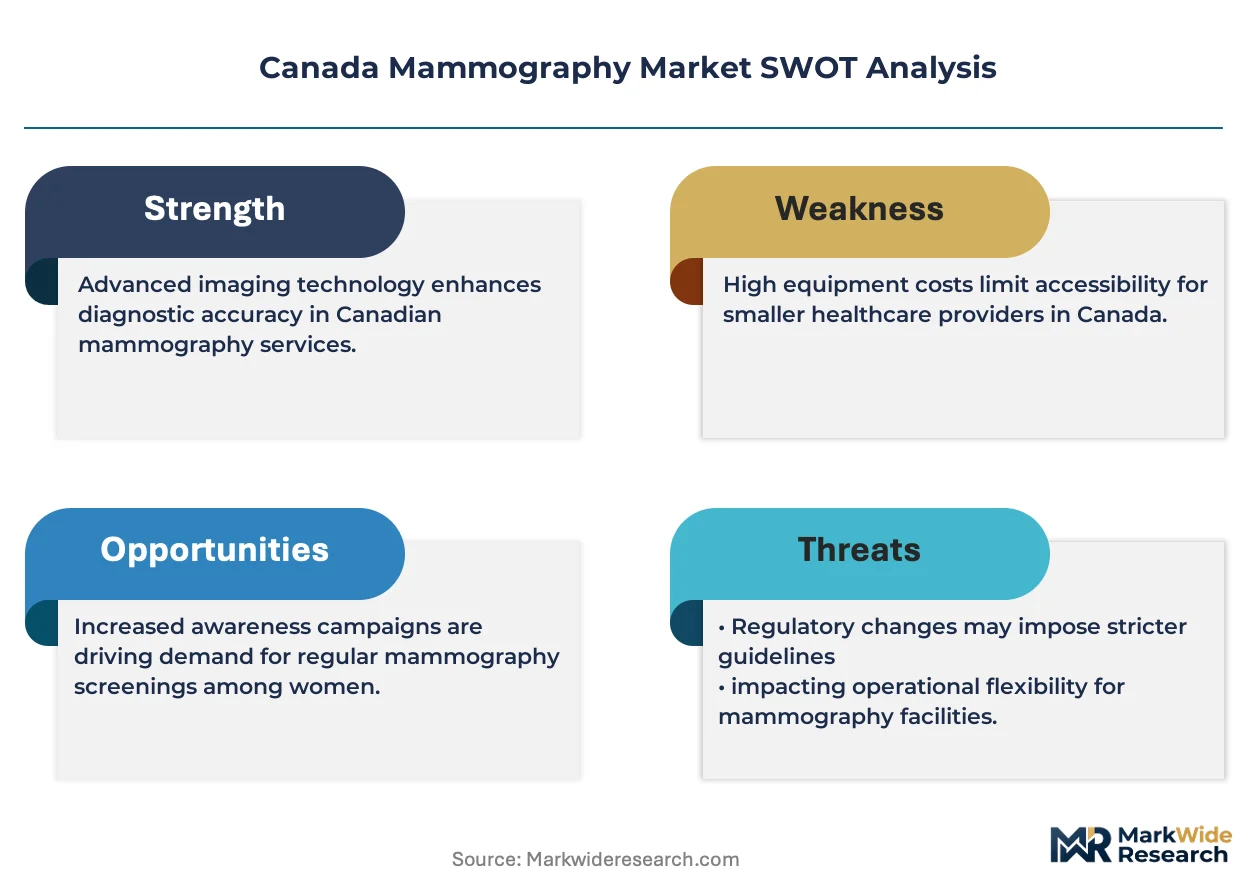
Provincial breast cancer screening programs are accelerating replacement of analog film-based mammography units with 3D tomosynthesis systems, compressing capital equipment cycles and recalibrating service contract economics across Ontario's hospital networks.
Growth Catalysts
- Ontario's centralized screening expansion:The province's breast cancer screening program is widening 3D mammography access through dedicated capital equipment budgets, pulling replacement demand forward in hospital networks.
- Health Canada's Medical Devices Regulations:Pre-market licensing requirements for digital breast tomosynthesis are elevating clinical evidence standards, filtering lower-capability vendors from provincial tenders.
- Photon-counting detector advancement:Next-generation direct-conversion sensors are improving dose efficiency and spatial resolution, creating upgrade pull among diagnostic clinic chains seeking differentiation.
Market Restraints
- Capital intensity of detector replacement:Flat-panel detector modules represent 35-45% of system cost, constraining upgrade frequency in budget-constrained community health centers.
- Quebec's fragmented procurement:Decentralized purchasing across independent diagnostic clinic chains limits volume aggregation and extends sales cycles compared to Ontario's centralized model.
- Radiologist workforce density:Interpretation bottlenecks in rural British Columbia and Atlantic provinces restrict throughput expansion even where equipment is deployed.
Strategic Opportunities
- AI-assisted diagnostic overlays:Machine learning algorithms for microcalcification detection are creating new software revenue streams beyond hardware placement in screening programs.
- Alberta's mobile screening fleet:The province's rural outreach initiatives present untapped demand for transportable 3D mammography systems with teleradiology integration.
- Canadian Association of Radiologists quality mandates:Accreditation criteria updates are forcing analog system obsolescence, generating replacement pull in lagging jurisdictions.
Industry Challenges
- Interoperability with PACS infrastructure:Tomosynthesis datasets strain legacy picture archiving systems, requiring costly middleware upgrades that delay deployment timelines.
- Specialized service technician scarcity:Photon-counting detector calibration and iterative reconstruction algorithm maintenance demand training pipelines that outpace current workforce supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Mammography Market |
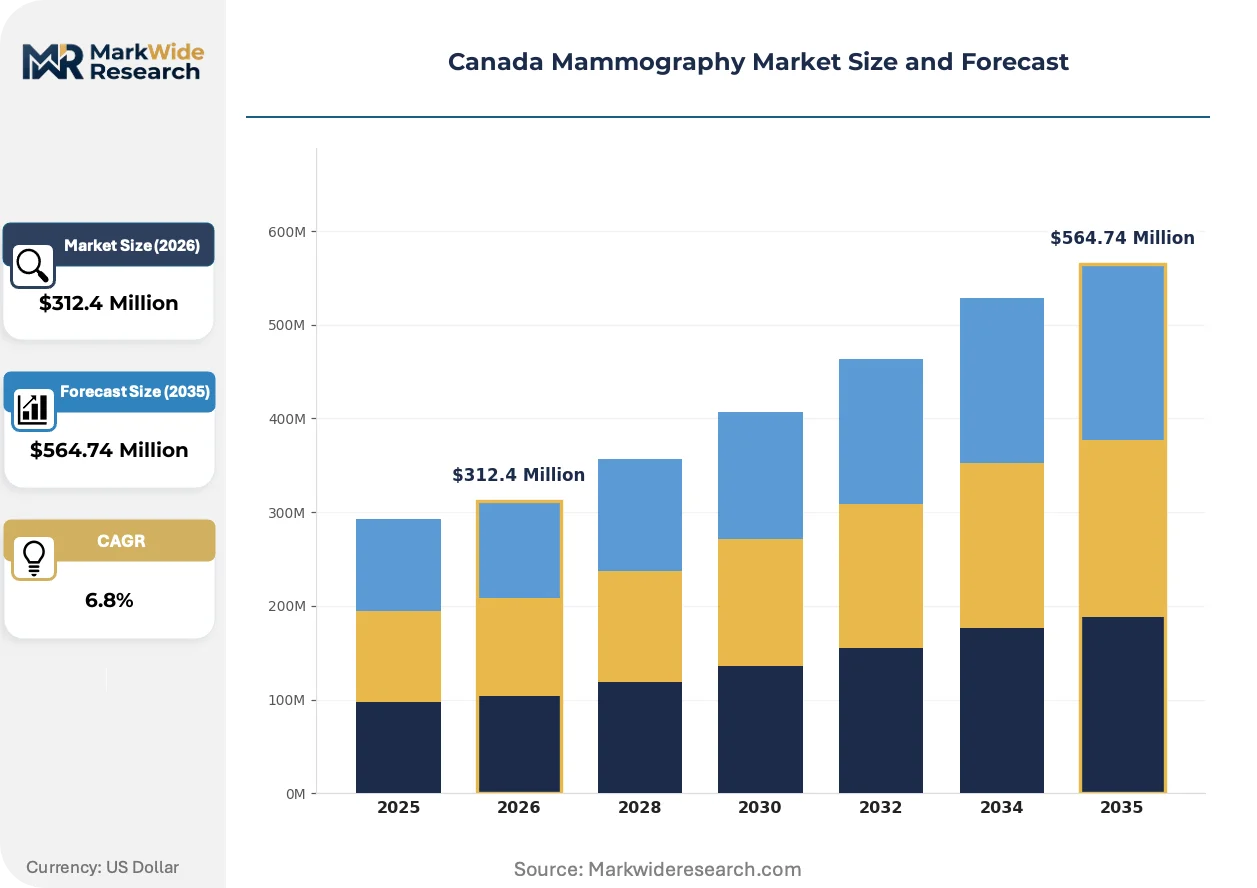
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Mammography, 3D Mammography, Film Screening, Portable Mammography End User: Hospitals, Diagnostic Clinics, Research Laboratories, Outpatient Centers Technology: X-ray Imaging, MRI, Ultrasound, Laser Imaging Service Type: Screening Services, Diagnostic Services, Follow-up Services, Consultation Services |
| Companies Covered | Hologic Inc., GE Healthcare Technologies Inc., Siemens Healthineers, Fujifilm Holdings Corporation, Planmed Oy, Canon Medical Systems Corporation, Koninklijke Philips NV, Carestream Health Inc., Analogic Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Mammography Market Strategic Shifts
Software-defined imaging workflows are displacing hardware-centric value capture, while AI integration and provincial procurement centralization are restructuring how mammography capabilities reach end-users across Canadian healthcare networks.
Photon-counting detector technology is converging with iterative reconstruction algorithms to enable sub-100-micrometer spatial resolution at reduced radiation dose. Ontario's hospital networks are piloting these systems in high-volume screening sites. The convergence is compressing the performance gap between premium diagnostic systems and standard screening configurations, forcing vendors to differentiate through workflow integration rather than raw imaging specifications.
Health Canada's Medical Devices Directorate is tightening post-market surveillance requirements for AI-enabled mammography software under evolving Medical Devices Regulations guidance. Manufacturers must now submit real-world performance data for algorithm updates, extending regulatory timelines. Screening programs in British Columbia and Alberta are prioritizing vendors with established quality management systems to preempt compliance risk.
After-sales service unbundling is fragmenting traditional equipment procurement in Quebec's diagnostic clinic chains. Buyers are separating hardware acquisition from maintenance contracts and software subscriptions, pressuring vendor margins. This pattern is most visible in Montreal's independent imaging centers, where third-party service providers are capturing detector calibration and tube replacement work previously captive to original equipment manufacturers.
Canada Mammography Market Segmentation
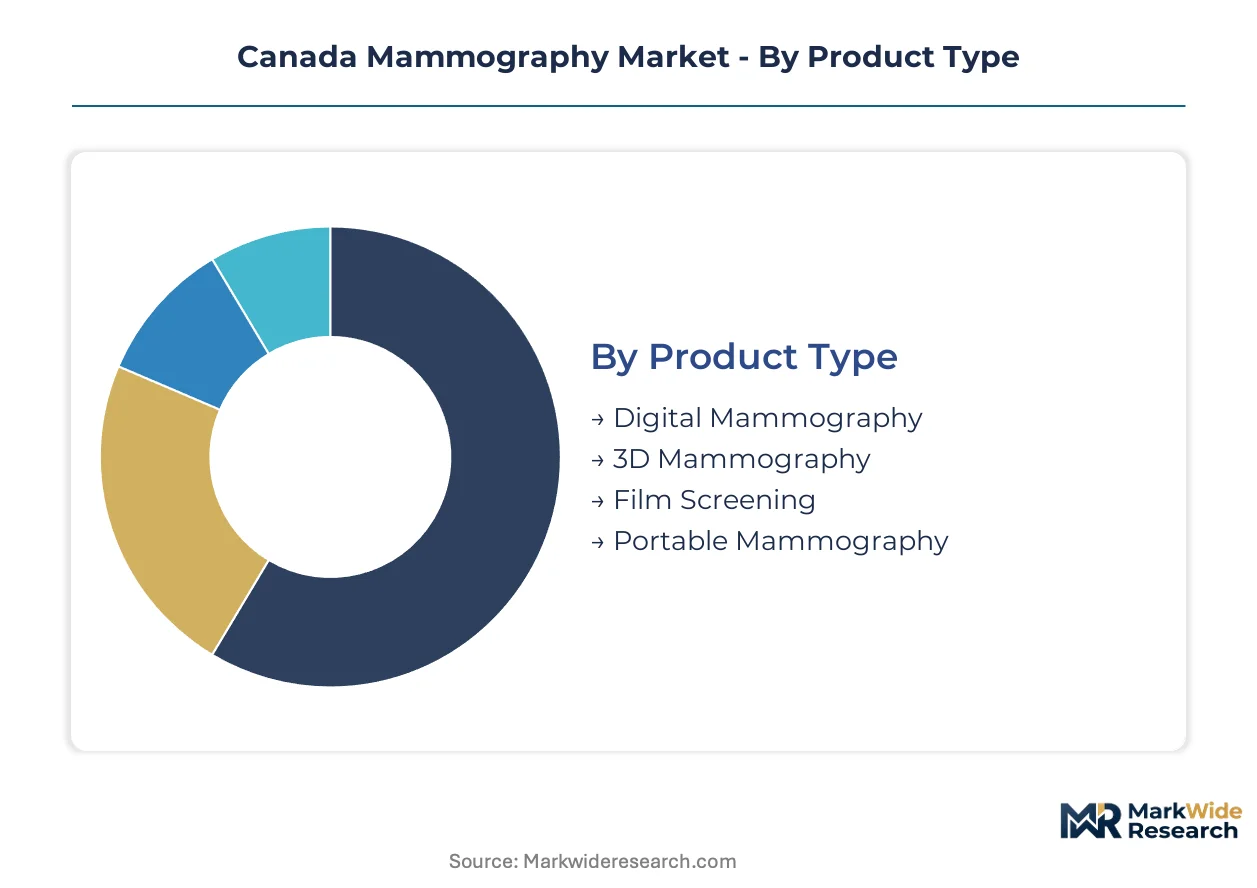
Equipment replacement cycles and provincial procurement centralization are fragmenting demand across distinct product tiers and service models. Understanding where capital concentrates versus where volume expands reveals which segments command premium positioning.
Product Type:
Detector technology upgrades are compressing replacement timelines, with provincial screening programs funding specific architectural transitions.
- Digital Mammography:Flat-panel detector systems with phosphor-based or direct-conversion sensors capture the mature installed base across Ontario's hospital networks. Health Canada's Medical Devices Directorate licensing requirements filter vendor participation in provincial tenders.
- 3D Mammography:Tomosynthesis systems with iterative reconstruction algorithms enable sub-100-micrometer resolution at reduced dose. British Columbia and Alberta screening programs are accelerating deployment in high-volume sites.
- Film Screening:Analog phosphor-cassette systems persist in rural Atlantic provinces and budget-constrained community health centers awaiting capital refresh cycles.
- Portable Mammography:Transportable systems with teleradiology integration serve Alberta's mobile screening fleet and remote British Columbia outreach initiatives.
Digital Mammography sits at the top of the volume ranking, with 3D Mammography climbing the fastest.
End User:
Procurement centralization varies sharply by customer type, reshaping how vendors structure sales cycles and service contracts.
- Hospitals:Ontario's centralized capital equipment budgets aggregate demand across hospital networks, enabling volume pricing and bundled service agreements. These institutions command the highest throughput per system.
- Diagnostic Clinics:Quebec's fragmented independent chains unbundle hardware from maintenance contracts, creating entry points for third-party service providers. Montreal imaging centers exemplify this pattern.
- Research Laboratories:Academic medical centers in Toronto and Vancouver pilot photon-counting detector systems for clinical validation studies.
- Outpatient Centers:Community-based facilities in suburban Alberta and British Columbia handle overflow from hospital screening backlogs.
Hospitals dominate capital deployment, while Diagnostic Clinics are expanding most quickly through acquisition and greenfield development.
Technology:
Imaging modality selection tracks application requirements, with X-ray maintaining primacy for population screening while alternatives capture diagnostic workup.
- X-ray Imaging:Digital breast tomosynthesis and conventional mammography systems generate over 90% of screening volume. Health Canada's pre-market licensing shapes product entry timelines.
- MRI:Magnetic resonance imaging serves high-risk patient surveillance and dense breast tissue evaluation in tertiary referral centers.
- Ultrasound:Handheld and cart-based systems provide adjunctive characterization of palpable masses and guidance for interventional procedures.
- Laser Imaging:Optical coherence tomography and related techniques remain investigational, with limited deployment in research settings.
X-ray Imaging anchors the installed base, with Ultrasound gaining share fastest as a complement to primary screening.
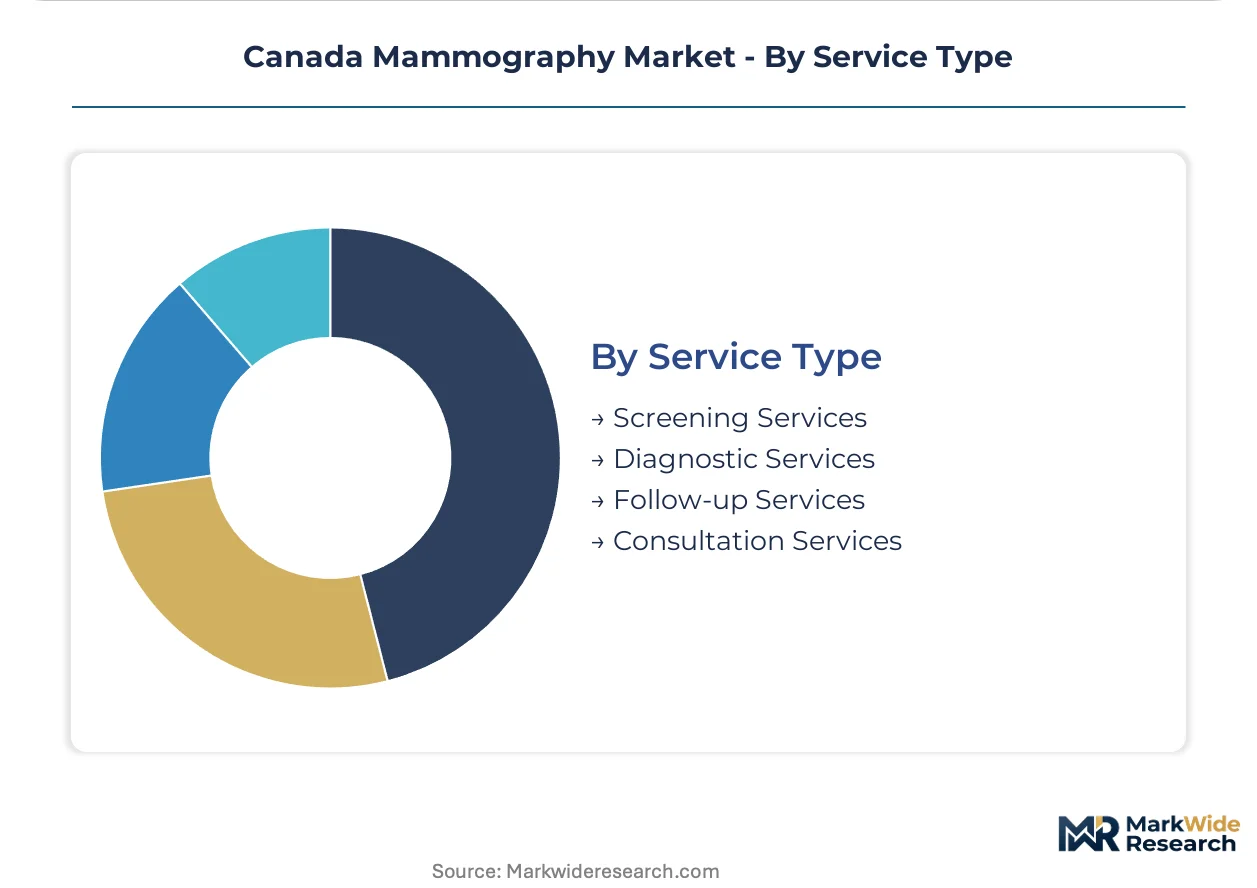
Service Type:
Reimbursement rate differentials and interpretation complexity stratify service economics across the care continuum.
- Screening Services:Asymptomatic population screening programs in Ontario, British Columbia, and Alberta generate the highest exam volumes. Provincial centralized budgets determine regional deployment velocity.
- Diagnostic Services:Symptomatic workup and callback evaluation command premium rates due to specialized interpretation requirements and extended exam protocols.
- Follow-up Services:Surveillance imaging for prior findings and high-risk monitoring creates recurring revenue streams in hospital-based breast centers.
- Consultation Services:Second opinion interpretation and multidisciplinary tumor board participation concentrate in academic medical centers.
Screening Services capture the highest volume ranking, with Diagnostic Services showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ontario's centralized procurement model generates faster equipment refresh cycles than Quebec's fragmented clinic chains, while British Columbia and Alberta prioritize rural access through mobile screening fleets.
Ontario
The province's breast cancer screening program drives concentrated demand through hospital network capital budgets. Health Canada's Medical Devices Directorate licensing requirements filter vendor participation in provincial tenders. Toronto's academic medical centers pilot photon-counting detector systems for clinical validation studies.
Quebec
Independent diagnostic clinic chains unbundle hardware acquisition from service contracts, extending sales cycles. The Canadian Association of Radiologists' quality standards influence procurement specifications in Montreal imaging centers. Third-party service providers capture detector calibration work previously captive to original equipment manufacturers.
British Columbia
Provincial health authorities operate centralized equipment budgets determining regional deployment velocity. Health Canada's post-market surveillance requirements shape product entry timelines for AI-enabled software. Vancouver's tertiary referral centers concentrate MRI capacity for high-risk patient surveillance.
Alberta
Mobile screening fleet expansion creates demand for transportable 3D mammography systems with teleradiology integration. Provincial outreach initiatives target rural communities with limited radiologist workforce density. Calgary's hospital networks anchor high-volume screening throughput in the Prairie region.
Atlantic Canada
Budget-constrained community health centers await capital refresh cycles for analog system replacement. Radiologist interpretation bottlenecks restrict throughput expansion even where equipment deploys. Halifax's regional hospitals serve as referral hubs for New Brunswick and Prince Edward Island screening backlogs.
Canada Mammography Market Competitive Environment
Top-tier vendors anchor provincial screening tenders through integrated workflow offerings, while mid-tier specialists compete on price in Quebec's fragmented diagnostic clinic segment. The vendor base stratifies across three archetypes: multinational imaging conglomerates with assay-to-imaging integration, regional equipment distributors with service contract capabilities, and niche photon-counting detector developers. Dominant competitive moves include strategic partnerships for AI software integration and backward integration into detector manufacturing to control supply chains.
Among North American imaging conglomerates, Hologic Inc. and GE Healthcare Technologies Inc. exemplify the integrated workflow archetype, while Siemens Healthineers anchors the European multinational position in photon-counting detector advancement. These three occupy distinct competitive vectors based on geographic origin and historical installed base relationships.
| Leading Market Players |
|---|
| Hologic Inc. |
| GE Healthcare Technologies Inc. |
| Siemens Healthineers |
| Fujifilm Holdings Corporation |
| Planmed Oy |
| Canon Medical Systems Corporation |
| Koninklijke Philips NV |
| Carestream Health Inc. |
| Analogic Corporation |
| Others |
Value Chain & Pricing Dynamics
Detector-grade bifurcation between photon-counting direct-conversion arrays and legacy phosphor-based flat panels manifests in parallel pricing and sourcing architectures across Canadian procurement channels. Health Canada's Medical Devices Directorate licensing tiers amplify this divergence, as premium systems command bundled service contracts while commodity configurations face unbundled third-party maintenance.
Pricing Analysis
Capacity additions in semiconductor fabrication for direct-conversion sensors are reshaping price floors for premium detector modules, compressing margins on high-end configurations. Three-tier pricing structure across premium, standard, and economy levels separates photon-counting systems with iterative reconstruction from conventional digital units and aging film-based alternatives. Pricing pressure stems from Quebec's diagnostic clinic chains unbundling hardware acquisition from maintenance contracts. Community health centers exhibit highest price sensitivity due to capital equipment budget constraints, while Ontario's hospital networks prioritize throughput optimization over unit cost.
Supply Chain Analysis
Freight costs for precision detector modules from Germany, Japan, and the United States elevate landed costs for Canadian buyers relative to domestic service integration. X-ray tube assemblies, amorphous selenium deposition substrates, and iterative reconstruction software licenses constitute critical input dependencies. Single-source vulnerability concentrates in photon-counting detector crystal growth capabilities. Distribution runs through original equipment manufacturer direct sales for hospital networks and regional equipment distributors serving Quebec's independent diagnostic chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Health Canada's evolving Medical Devices Regulations for AI-enabled mammography software function as a regulatory compounder, accelerating replacement cycles as provincial screening programs preempt compliance risk through quality management system mandates.
For Market Incumbents: Extend service contract penetration in Ontario's hospital networks before third-party providers capture detector calibration workflows. Deepen backward integration into photon-counting crystal manufacturing to secure supply continuity against German and Japanese source concentration. Counter Quebec's unbundling trend through software-defined imaging workflow lock-in that elevates switching costs.
For New Entrants and Emerging Players: Enter via Alberta's mobile screening fleet expansion, where transportable 3D mammography with teleradiology integration faces limited incumbent saturation. Target Atlantic Canada's budget-constrained community health centers with refurbished digital systems and third-party maintenance offerings. Pursue GPO contracts with provincial health authorities as the primary go-to-market channel.
For Investors and Strategic Acquirers: Consolidation pressure builds where photon-counting detector development costs outpace independent R&D funding capacity. Five-to-ten-year viability favors vendors with integrated assay-to-imaging workflows and established Health Canada quality management system certifications. Acquisition target archetype: niche photon-counting detector developers with clinical validation partnerships. Monitor AI reimbursement policy developments as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Health Canada Quality Management System Certification | Preempts regulatory exclusion from provincial screening tenders under evolving Medical Devices Regulations guidance. |
| Photon-Counting Detector Backward Integration | Secures captive supply of direct-conversion sensors against German and Japanese manufacturing concentration. |
| AI-Assisted Diagnostic Software Development | Creates recurring SaaS revenue streams beyond hardware placement in Ontario's centralized screening programs. |
| Mobile Screening Fleet Partnership | Captures Alberta's rural outreach demand for transportable 3D mammography with teleradiology integration. |
| Third-Party Service Provider Acquisition | Defends maintenance contract capture in Quebec's unbundled diagnostic clinic procurement environment. |
Study Parameters
Direct dialogue with hospital purchasing committee members, biomedical engineers at Ontario's academic medical centers, GPO contracts managers, and provincial health authority capital equipment planners grounded qualitative assessment. Secondary validation drew from Health Canada Medical Devices Directorate licensing databases, Canadian Association of Radiologists accreditation records, hospital procurement tender documents, and provincial breast cancer screening program annual reports. Bottom-up equipment installation tracking and top-down provincial budget allocation analysis were triangulated against vendor service contract disclosures.
Bottom-up modeling aggregated system-level deployment data across detector technology tiers, end-user procurement channels, and provincial regulatory clusters. Segmentation dimensions included product architecture, customer concentration, and service unbundling patterns. CAGRs were derived from replacement cycle compression rates and provincial funding trajectory assumptions. Forecast inputs incorporated Health Canada regulatory timeline projections and radiologist workforce density constraints in rural jurisdictions.
Inputs from provincial tender databases and vendor service contract registries were available through the study window; gaps in real-time AI software performance surveillance data introduce uncertainty bands around adoption curve assumptions. Forecasts reflect modeling assumptions regarding regulatory enforcement intensity and provincial budget continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Radiology Services Market
Medical Imaging
Global Dental Radiology and Dental Imaging Devices Market
Medical Imaging
Digital Pathology Market
Medical Imaging
India Ultrasound Devices Market
Medical Imaging
Wireless Intraoral Camera Market
Medical Imaging
Brazil Computed Tomography Market
Medical Imaging
France Computed Tomography Market
Medical Imaging
United Kingdom Mammography Market
Medical Imaging
Global CT Scanners Market
Medical Imaging
Breast Imaging Technologies Market
Medical Imaging
Preclinical Brain Imaging Market
Medical Imaging
Panoramic and Cephalometric Radiography Systems Market
Medical Imaging
Image Guided Therapy Market
Medical Imaging
Latin America Medical Imaging Software Market
Medical Imaging
Molecular Imaging Market
Medical Imaging
North America Computed Tomography (CT) Market