
 Global Nuclear Imaging Equipment Market | 2026-2036
Global Nuclear Imaging Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Nuclear Imaging Equipment Market Outlook
CE marking under the EU Medical Device Regulation is reorganizing competitive access across European territories. Siemens Healthineers AG leverages integrated PET-MR platforms to dominate premium hospital installations. GE Healthcare sustains broad geographic coverage through its hybrid imaging portfolio. Koninklijke Philips N.V. competes on digital detector efficiency and workflow software integration.
Nuclear imaging equipment encompasses systems that detect gamma ray emissions from radiopharmaceuticals administered to patients, utilizing scintillation crystals with spatial resolution thresholds below 5 mm for precise anatomical localization. These devices enable functional metabolic assessment alongside structural imaging, primarily serving cancer staging, myocardial perfusion evaluation, and neurological disorder diagnosis. Positron Emission Tomography systems command the largest installed base among product categories, though Hybrid Imaging Systems capture expanding margin pools through combined modality reimbursement advantages. Digital Detectors are displacing Analog Detectors across technology segments due to superior energy resolution and faster acquisition times. Oncology applications outpace Cardiology in growth velocity as FDG-PET protocols multiply across solid tumor guidelines.
The FDA enforces 21 CFR Part 1020 performance standards for radiation-emitting diagnostic devices, while the EMA coordinates radiopharmaceutical quality benchmarks through centralized marketing authorization pathways. Japan's PMDA maintains distinct submission requirements for nuclear medicine devices that extend approval timelines relative to conventional imaging equipment. Stakeholders must monitor evolving reimbursement codes for theranostic procedures and radiopharmaceutical supply chain security as isotope production capacity constrains system utilization rates.
Market Dynamics
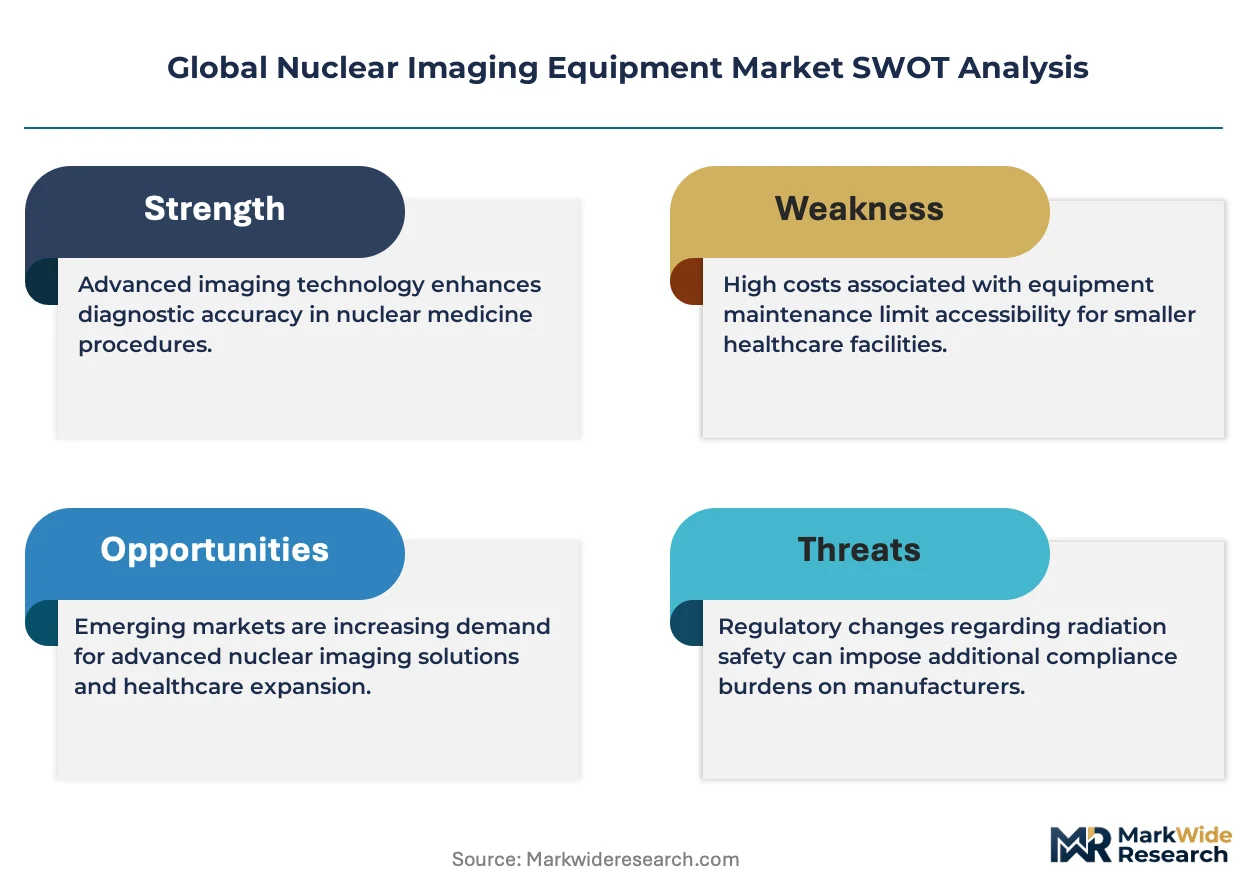
Hybrid imaging modalities are compressing standalone system demand as hospital procurement committees prioritize reimbursement-optimized PET-CT and PET-MR configurations over single-modality investments.
Growth Catalysts
- FDG-PET protocol expansion:National cancer guidelines across Germany, Japan, and the United States now mandate metabolic staging for solid tumors, forcing oncology departments to expand scanner capacity.
- 21 CFR Part 1020:The FDA's tightened performance benchmarks for diagnostic x-ray systems are accelerating replacement cycles for aging gamma camera fleets in US hospital networks.
- Theranostic convergence:Lutetium-177 and actinium-225 radioligand therapies require companion diagnostic imaging, binding nuclear medicine departments to expanded PET procurement budgets.
Market Restraints
- Molybdenum-99 supply concentration:Over eighty percent of global technetium-99m precursor production concentrates in aging research reactors in the Netherlands, Canada, and South Africa, creating isotope shortage vulnerability.
- CE marking friction:The EU Medical Device Regulation's reclassification of hybrid imaging systems as Class III devices extends technical documentation timelines and notified body queue congestion.
- Cyclotron capital intensity:On-site fluorine-18 production requires USD 3-5 million facility investments plus specialized radiochemistry staffing, constraining PET adoption outside major metropolitan hospital clusters.
Strategic Opportunities
- India diagnostic infrastructure:The country's PLI scheme for medical devices and expanding CDSCO fast-track pathways for nuclear medicine equipment create first-mover positioning for hybrid imaging vendors.
- Cardiac amyloidosis imaging:PYP-scintigraphy protocols for transthyretin amyloidosis are multiplying across cardiology guidelines, opening dedicated SPECT application expansion.
- Digital detector convergence:Solid-state cadmium-zinc-telluride sensors combined with AI-based reconstruction algorithms enable portable gamma camera form factors for point-of-care deployment.
Industry Challenges
- Radiopharmaceutical supply chain reconfiguration:Hospital nuclear medicine departments must rebuild logistics networks around reduced Mo-99 reactor output and emerging non-uranium fission production methods.
- Cross-modality workflow integration:PET-CT and PET-MR systems require DICOM-RT and HL7-FHIR interoperability with radiation oncology planning systems, stretching hospital IT integration timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Nuclear Imaging Equipment Market |
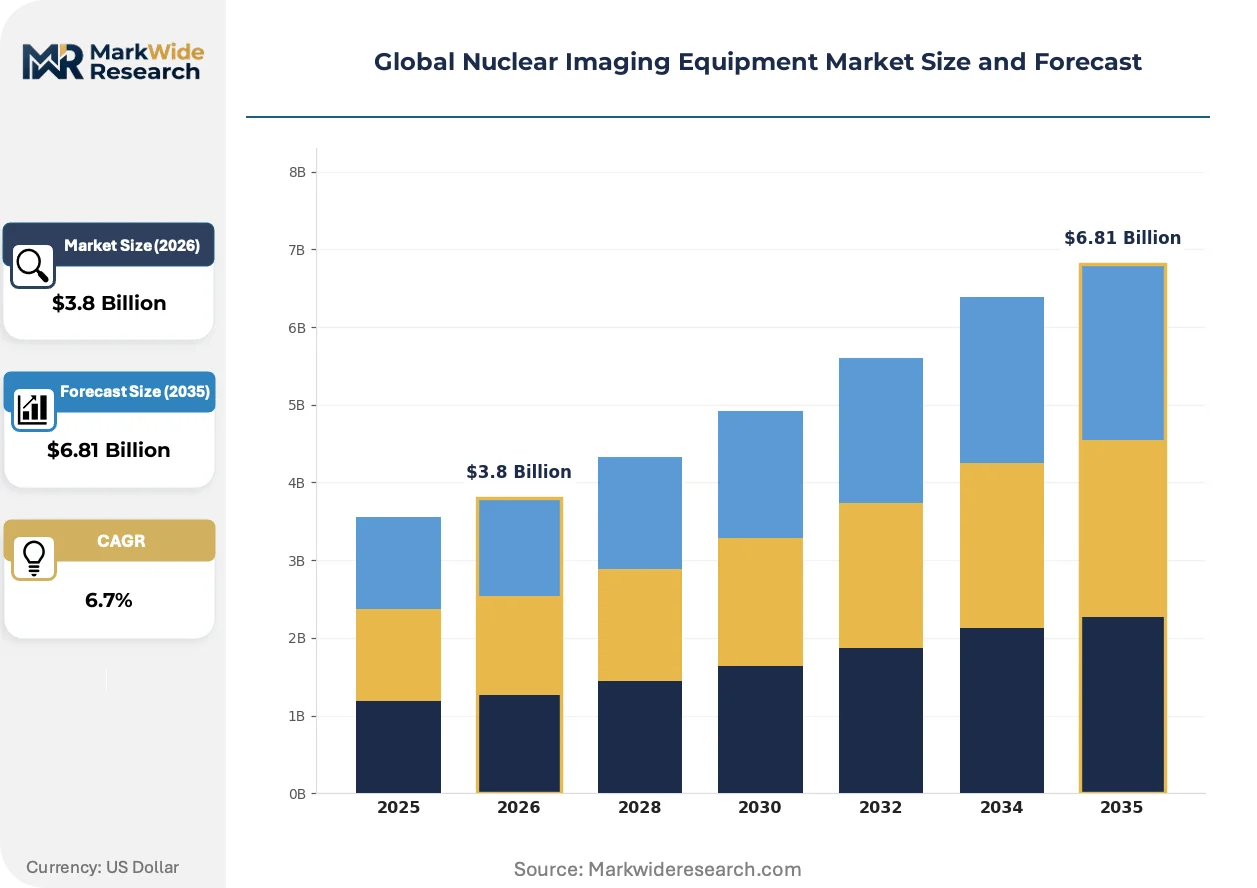
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Positron Emission Tomography, Single Photon Emission Computed Tomography, Hybrid Imaging Systems, Nuclear Medicine Cameras Technology: Digital Detectors, Analog Detectors, Radioactive Isotopes, Imaging Software Application: Cardiology, Oncology, Neurology, Thyroid Disorders End User: Hospitals, Diagnostic Centers, Research Institutes, Outpatient Clinics |
| Companies Covered | Siemens Healthineers AG, GE Healthcare, Koninklijke Philips N.V., Canon Medical Systems Corporation, Neusoft Medical Systems Co Ltd, Mediso Medical Imaging Systems Ltd, Shimadzu Corporation, Digirad Corporation, United Imaging Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Nuclear Imaging Equipment Market Strategic Shifts
Artificial intelligence reconstruction algorithms and solid-state detector materials are compressing acquisition times while expanding diagnostic throughput capacity across installed base expansion and replacement decisions.
Digital PET detector technology is miniaturizing scintillation crystal arrays through silicon photomultiplier substitution for conventional photomultiplier tubes. Academic medical centers in the United States and university hospitals in Germany are adopting these platforms for sub-five-minute whole-body acquisitions. The technology is miniaturizing system footprints sufficiently for outpatient imaging center deployment outside traditional hospital radiology departments.
The EU Medical Device Regulation's Class III reclassification of hybrid imaging systems imposes clinical evidence requirements that extend CE marking timelines by twelve to eighteen months. European notified bodies are prioritizing technical documentation reviews for PET-MR platforms over standalone SPECT systems. German and French hospital procurement committees are delaying tender releases until MDR transition deadlines clarify competitive field stability.
Service unbundling is fragmenting traditional full-service contracts into discrete preventive maintenance, software subscription, and isotope logistics components. Outpatient imaging chains in the United States and Japan are negotiating à la carte service tiers to match utilization volatility. This restructuring concentrates vendor margin pressure in low-utilization rural installations while preserving premium pricing for high-throughput metropolitan sites.
Global Nuclear Imaging Equipment Market Segmentation
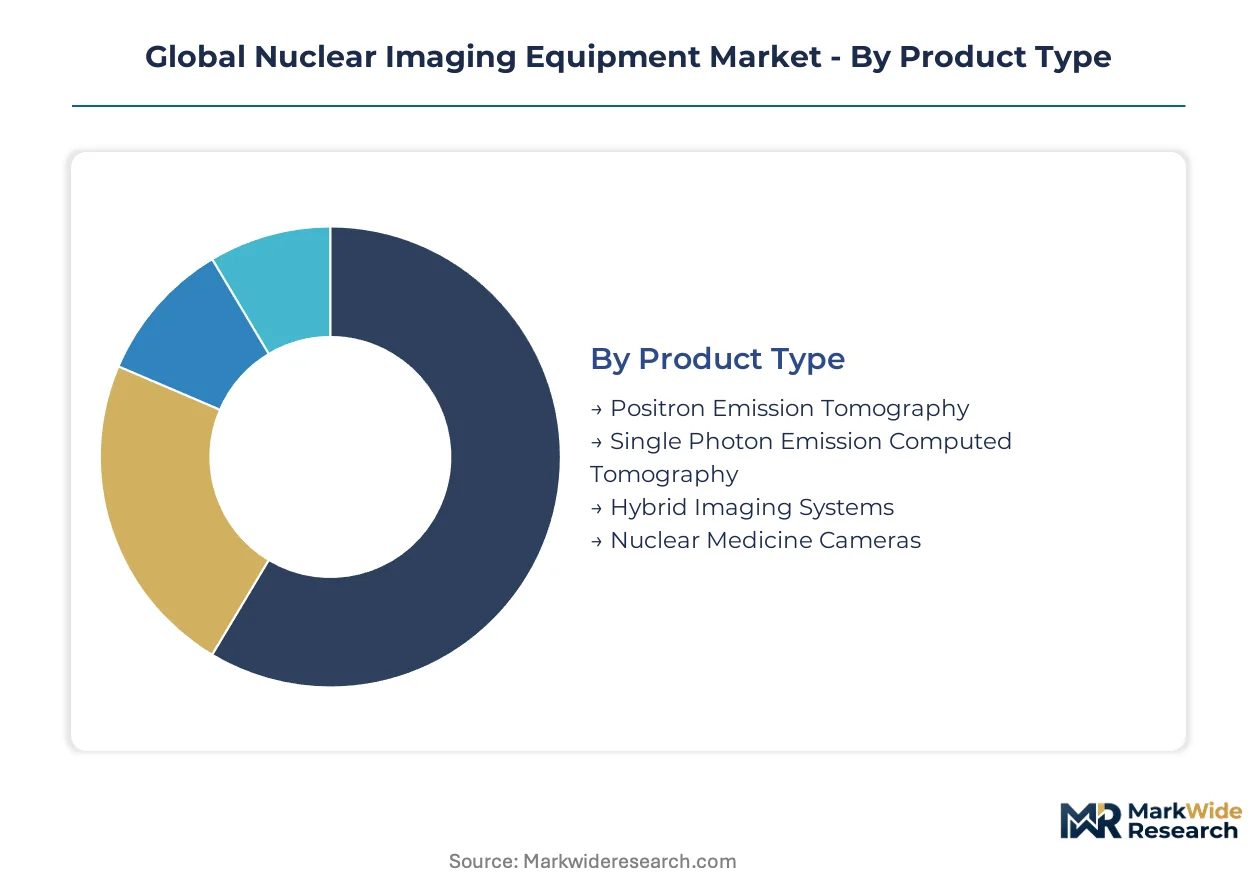
Nuclear imaging equipment segmentation reveals how technology substitution and reimbursement dynamics redistribute procurement budgets across hospital networks. Equipment buyers prioritize hybrid configurations that maximize procedure throughput while minimizing radiopharmaceutical waste.
Product Type:
Substitution pressure concentrates most intensely on standalone SPECT systems as PET-CT and PET-MR platforms absorb capital allocation.
- Positron Emission Tomography:Detects positron-emitting radiopharmaceuticals through coincidence detection with spatial resolution thresholds below 5 mm. Oncology departments in Germany and Japan are expanding FDG-PET capacity to meet national cancer staging guidelines.
- Hybrid Imaging Systems:Combine PET or SPECT with CT or MRI for fused anatomical-functional datasets. These platforms command premium reimbursement rates in US hospital networks, forcing procurement committees to consolidate standalone system purchases.
- Single Photon Emission Computed Tomography:Utilizes gamma-emitting isotopes for myocardial perfusion and bone scintigraphy. Cardiac amyloidosis protocols are extending installed base utility in US cardiology practices.
- Nuclear Medicine Cameras:Basic gamma camera systems for planar imaging and limited tomography. Rural diagnostic centers in India leverage these for cost-constrained thyroid and bone screening programs.
Hybrid Imaging Systems anchors the volume base while Hybrid Imaging Systems gains share at the steepest rate.
Technology:
Cost tier stratification separates premium digital platforms from legacy analog installations facing accelerated replacement cycles.
- Digital Detectors:Silicon photomultiplier arrays and solid-state cadmium-zinc-telluride sensors replace photomultiplier tubes. Academic medical centers in the United States and university hospitals in Germany are adopting these for sub-five-minute whole-body acquisitions.
- Imaging Software:AI-based reconstruction algorithms compress acquisition times while maintaining diagnostic accuracy. FDA-cleared deep learning applications are expanding across US outpatient imaging chains.
- Analog Detectors:Conventional photomultiplier tube-based scintillation counting. Aging installed bases in South Africa and Eastern European markets face Mo-99 supply vulnerability.
- Radioactive Isotopes:Fluorine-18, technetium-99m, and iodine-131 production and logistics. Cyclotron capital requirements constrain F-18 availability outside major metropolitan clusters.
Digital Detectors anchors the volume base while Imaging Software climbs the fastest as hospitals prioritize workflow efficiency.
Application:
Volume concentration in oncology applications is reshaping equipment specification requirements across manufacturer R&D pipelines.
- Oncology:FDG-PET staging for solid tumors, lymphoma response assessment, and radioligand therapy planning. National guidelines in Germany, Japan, and the United States now mandate metabolic imaging for multiple cancer types.
- Cardiology:Myocardial perfusion imaging, viability assessment, and cardiac amyloidosis detection. PYP-scintigraphy protocols for transthyretin amyloidosis are multiplying across US and Japanese cardiology guidelines.
- Neurology:Amyloid and tau PET for Alzheimer's disease, dopaminergic imaging for Parkinson's disease. Research institutes in the United States and Germany drive beta-amyloid tracer adoption.
- Thyroid Disorders:Iodine-131 uptake and imaging for hyperthyroidism and differentiated thyroid cancer. Diagnostic centers in India and Japan maintain consistent demand for dedicated gamma camera protocols.
Cardiology anchors the volume base while Oncology expands most quickly as cancer screening volumes accelerate.
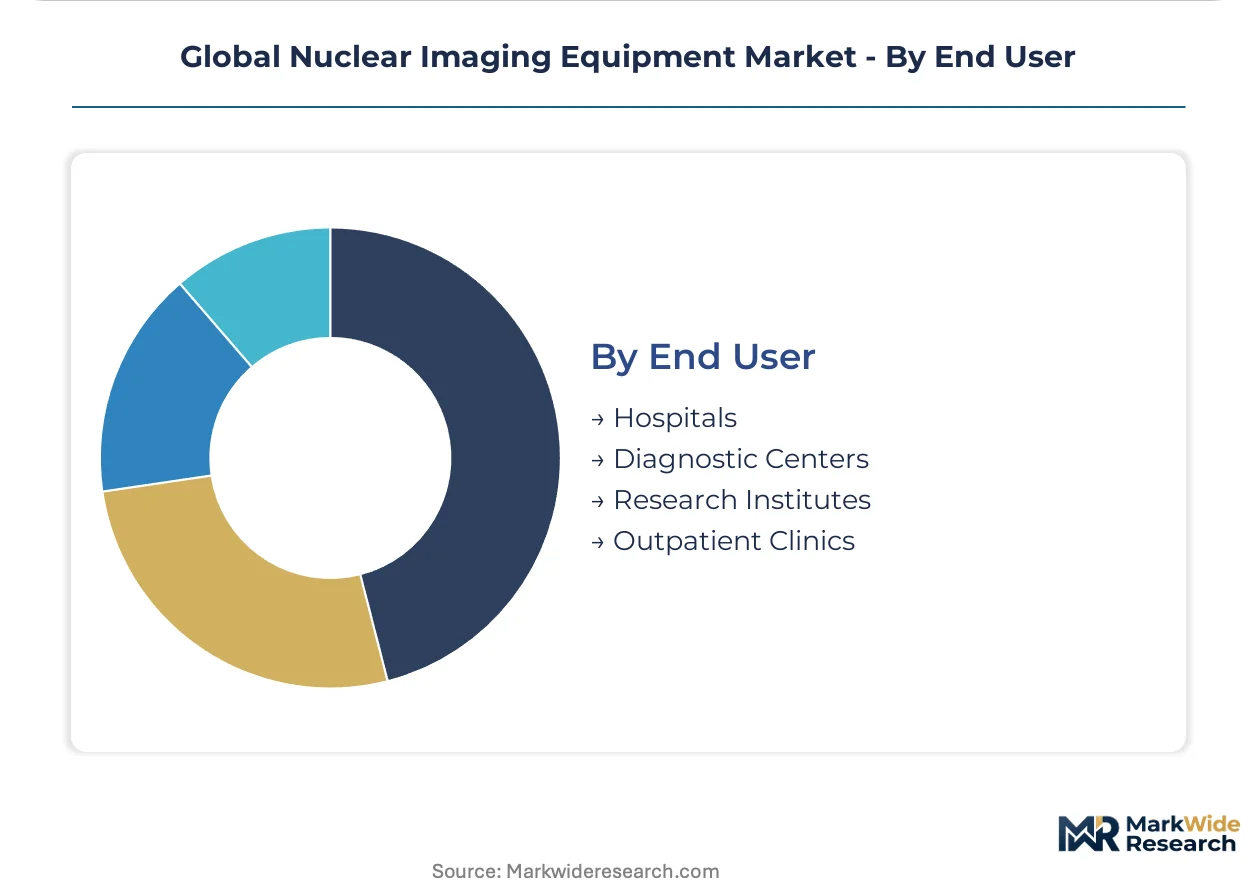
End User:
Customer type differentiation separates high-throughput hospital installations from fragmented outpatient and research demand.
- Hospitals:Integrated health systems with nuclear medicine departments, radiation oncology alignment, and inpatient referral networks. US and German hospital networks are consolidating PET-CT procurement across regional hub-and-spoke models.
- Diagnostic Centers:Independent imaging facilities and outpatient chains negotiating à la carte service contracts. Japanese and US outpatient operators are unbundling preventive maintenance from software subscriptions.
- Research Institutes:Academic medical centers and university hospitals conducting clinical trials and tracer development. German and US institutions lead PET-MR adoption for neuroimaging research.
- Outpatient Clinics:Limited-service facilities for thyroid uptake and basic cardiac stress testing. India's PLI scheme for medical devices is attracting hybrid imaging vendors to establish diagnostic infrastructure.
Hospitals anchors the volume base while Diagnostic Centers gains share fastest as service unbundling concentrates margin pressure on rural installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in the United States, Germany, and Japan command the largest capital allocations for PET-CT and PET-MR platforms. These three markets concentrate aging populations, established reimbursement frameworks, and dense specialist networks that sustain premium equipment demand.
United States
Oncology departments at academic medical centers in Boston and Houston are expanding FDG-PET capacity to meet National Comprehensive Cancer Network staging guidelines. The FDA enforces 21 CFR Part 1020 performance standards that accelerate replacement cycles for aging gamma camera fleets. Outpatient imaging chains in Texas and Florida are unbundling service contracts to match utilization volatility.
Germany
University hospitals in Munich and Heidelberg lead PET-MR adoption for neuroimaging research and radioligand therapy planning. The EU Medical Device Regulation's Class III reclassification of hybrid imaging systems extends CE marking timelines by twelve to eighteen months. Notified bodies in Berlin and Frankfurt prioritize technical documentation reviews for integrated platforms over standalone SPECT systems.
Japan
Cardiology practices in Tokyo and Osaka are deploying PYP-scintigraphy protocols for transthyretin amyloidosis detection. The PMDA maintains distinct submission requirements for nuclear medicine devices that extend approval timelines relative to conventional imaging equipment. Metropolitan hospital networks in Kansai and Kanto regions are consolidating procurement across hub-and-spoke models.
India
Diagnostic infrastructure expansion in Maharashtra and Gujarat is attracting hybrid imaging vendors to establish regional presence. The CDSCO fast-track pathway for nuclear medicine equipment accelerates market entry timelines for qualified manufacturers. The PLI scheme for medical devices subsidizes capital costs for gamma camera installations in tier-two cities.
Netherlands
Radiopharmaceutical production clusters in Petten and Delft concentrate over eighty percent of European technetium-99m precursor supply. Aging research reactors face maintenance cycles that create isotope shortage vulnerability for downstream imaging networks. EMA coordination of centralized marketing authorization pathways shapes quality benchmarks for tracer distribution across member states.
Global Nuclear Imaging Equipment Market Competitive Environment
Player mix skews toward diversified medical technology conglomerates with hybrid imaging portfolios and specialized nuclear medicine vendors with detector technology focus. Siemens Healthineers AG, GE Healthcare, and Koninklijke Philips N.V. command premium hospital installations through integrated platform strategies. Tier-two competitors compete on digital detector efficiency and workflow software integration. Dominant competitive moves include strategic partnerships for radiopharmaceutical supply chain security and technology licensing for solid-state detector miniaturization.
Among diversified imaging conglomerates, Siemens Healthineers AG, GE Healthcare, and Koninklijke Philips N.V. occupy positions that exemplify premium-tier platform integration. These three anchors represent the archetype of broad geographic coverage combined with hybrid modality portfolios. Specialized vendors including Canon Medical Systems Corporation and Shimadzu Corporation sit within focused technology tiers that emphasize detector efficiency and compact system footprints for outpatient deployment.
| Leading Market Players |
|---|
| Siemens Healthineers AG |
| GE Healthcare |
| Koninklijke Philips N.V. |
| Canon Medical Systems Corporation |
| Neusoft Medical Systems Co Ltd |
| Mediso Medical Imaging Systems Ltd |
| Shimadzu Corporation |
| Digirad Corporation |
| United Imaging Healthcare |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between hospital networks and radiopharmaceutical distributors lock in technetium-99m supply access while fixing price visibility against molybdenum-99 reactor output volatility. These contracts tie procurement committees to named isotope suppliers in the Netherlands, Canada, and South Africa, embedding supply risk directly into equipment utilization economics.
Pricing Analysis
Cost-plus contracts with Mo-99 price indexation dominate radiopharmaceutical supply agreements, passing through reactor maintenance cost fluctuations to hospital buyers. Three-tier pricing structure across premium, standard, and economy levels separates PET-MR platforms with silicon photomultiplier arrays from refurbished SPECT gamma cameras and entry-level nuclear medicine cameras. Cost compression in the economy tier is intensifying because India's PLI scheme subsidizes domestic gamma camera assembly, forcing incumbent vendors to unbundle software subscriptions from hardware quotes. Outpatient diagnostic centers in Texas and Florida exhibit highest price sensitivity, while academic medical centers in Boston and Munich prioritize detector resolution specifications over capital expenditure constraints.
Supply Chain Analysis
Petten reactor maintenance cycles in the Netherlands create chokepoint vulnerability for European technetium-99m distribution, with single-source dependency amplifying shortage risk across downstream imaging networks. Molybdenum-99 production concentrates in the Netherlands, Canada, and South Africa, while fluorine-18 cyclotron capacity clusters in the United States, Germany, and Japan. Solid-state cadmium-zinc-telluride sensors, lutetium-based scintillation crystals, and helium-3 neutron detection materials constitute critical component inputs. Tariff exposure on Chinese-sourced rare earth elements for detector manufacturing threatens cost stability. Distribution runs through radiopharmaceutical logistics specialists with cold-chain certification, bypassing conventional medical device distributors for isotope delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflects as DICOM-RT and HL7-FHIR interoperability requirements bind nuclear imaging vendors to radiation oncology planning ecosystems, consolidating procurement decisions around integrated workflow suites rather than standalone hardware specifications.
For Market Incumbents: Compound installed base lock-in by embedding AI reconstruction algorithms into service contract renewals, forcing replacement decisions toward compatible platform upgrades. Acquire cyclotron operators in underserved metropolitan clusters to secure fluorine-18 captive supply against isotope shortage vulnerability. Defend against digital detector miniaturization threats by accelerating silicon photomultiplier R&D partnerships with German university hospitals. For New Entrants and Emerging Players: CDSCO fast-track pathway for nuclear medicine equipment offers regulatory expedited entry into Maharashtra and Gujarat diagnostic infrastructure expansion. Target tier-two Indian cities with portable gamma camera form factors leveraging solid-state detector cost curves. Pursue white-space cardiology amyloidosis protocols in Japanese outpatient clinics where PYP-scintigraphy guidelines multiply faster than incumbent service coverage. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among hybrid imaging vendors with unbundled software subscription tiers, offering visibility through utilization-linked payment structures. Five-to-ten year viability favors platforms with theranostic convergence capabilities binding diagnostic imaging to radioligand therapy planning. Monitor FDA 21 CFR Part 1020 enforcement intensity as signal for replacement cycle acceleration among aging gamma camera fleets.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Class III reclassification extends timelines for PET-MR platforms entering German and French hospital tenders. |
| Hospital System Partnership | Hub-and-spoke procurement consolidation across US integrated delivery networks concentrates volume with single-vendor platforms. |
| Software Companion Development | FDA-cleared AI reconstruction algorithms differentiate digital detector offerings for sub-five-minute acquisition protocols. |
| Reimbursement Strategy | Theranostic procedure code expansion binds PET procurement to Lutetium-177 therapy planning revenue streams. |
| Backward Integration | Cyclotron acquisition in underserved metropolitan clusters secures fluorine-18 supply against Mo-99 shortage vulnerability. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with nuclear medicine department heads, hospital procurement committee chairs, biomedical engineers, GPO contracts managers, and cyclotron facility operators. Secondary validation drew from FDA 510(k) filings, EMA centralized marketing authorization pathways, PMDA submission databases, hospital procurement tender records, and CMS Medicare reimbursement code updates. Bottom-up equipment installation tracking and top-down radiopharmaceutical consumption modeling were triangulated against manufacturer revenue disclosures.
Across the analysis window, forecasts integrate product type substitution dynamics, technology displacement curves, application protocol expansion rates, and end-user consolidation patterns. Segmentation dimensions include hybrid versus standalone modality configuration, digital versus analog detector technology, oncology versus cardiology versus neurology application mix, and hospital versus outpatient versus research institute customer archetype. CAGRs derive from equipment replacement cycle analysis, reimbursement code velocity, and radiopharmaceutical supply constraint modeling.
The analysis sits within stated boundaries; outcomes outside sustained Mo-99 reactor output, stable FDA enforcement posture, and continued theranostic reimbursement expansion would require recalibration. Practitioners should keep alternative scenarios live as EU MDR transition deadlines, isotope production method shifts, and AI reconstruction regulatory pathways evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Global Mini C-Arm Market
Medical Imaging
South America Portable X Ray Devices Market
Medical Imaging
Netherlands Diagnostic Imaging Equipment Market
Medical Imaging
AI-Assisted Digital Radiography Equipment Market
Medical Imaging
AI-Based Medical Imaging Algorithm Validation Test Platforms Market
Medical Imaging
North America Digital Pathology Market
Medical Imaging
Mobile Vascular Imaging Market
Medical Imaging
AI-Enabled Diagnostic Imaging Market
Medical Imaging
Preclinical Brain Imaging Market
Medical Imaging
AI-Assisted Radiology Market
Medical Imaging
Portable MRI Market
Medical Imaging
Global Cone Beam Computed Tomography Market
Medical Imaging
Cone Beam CT Scanner Market
Medical Imaging
Global Artificial Intelligence in Ultrasound Imaging Market
Medical Imaging
United Arab Emirates Diagnostic Imaging Equipment Market
Medical Imaging
Germany Digital X-Ray Market