
 United Kingdom Hospital Supplies Market | 2026-2036
United Kingdom Hospital Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Hospital Supplies Market Analytics
Aftermarket service revenue for capital equipment is reconfiguring margin pools across the United Kingdom hospital supplies sector. B. Braun Melsungen AG leverages its sterilization service infrastructure to capture recurring revenue from NHS trusts. Cardinal Health Inc. anchors its position through direct distribution contracts with acute care networks. Smith & Nephew plc specializes in orthopaedic procedure kits that sustain premium positioning within bundled payment frameworks.
Hospital supplies encompass the instruments, apparatus, consumables, and furnishings required for patient diagnosis, treatment, and surgical intervention within clinical settings, typically manufactured to ISO 13485 quality management standards and sterilized to SAL 10^-6 levels. Their primary purpose is to enable safe, effective, and standardized care delivery across acute and chronic treatment pathways. Disposable supplies command the largest volume share due to single-use mandates in infection control protocols, while diagnostic equipment captures higher per-unit margins driven by imaging and point-of-care testing upgrades. Surgical instruments represent a mature segment where consolidation among sterilization service providers is concentrating aftermarket value capture.
The Medicines and Healthcare products Regulatory Agency (MHRA) enforces UKCA marking requirements for medical devices post-Brexit, compelling manufacturers to establish domestic conformity assessment routes. NHS England's Net Zero Supplier Roadmap mandates carbon footprint disclosure for contracted suppliers, reshaping procurement criteria and supplier qualification processes. Care Quality Commission inspection frameworks tie equipment maintenance records to facility accreditation, elevating the operational priority of supply chain traceability systems. Stakeholders must monitor divergence between retained EU law and emerging UK-specific device regulations to anticipate compliance cost trajectories.
Market Dynamics
NHS England's Net Zero Supplier Roadmap is reconfiguring procurement qualification criteria across the United Kingdom hospital supplies sector. Carbon footprint disclosure mandates are filtering vendor pools and elevating sterilization service providers with established domestic infrastructure.
Growth Catalysts
- Elective surgery backlogs:NHS England's recovery targets for orthopaedic and cardiovascular procedures are expanding demand for procedure-specific kits and single-use surgical consumables across acute trusts.
- MHRA UKCA transition:Post-Brexit conformity assessment requirements are consolidating domestic manufacturing capacity as EU-notified body certificates lose validity for Great Britain placement.
- Private catheterization laboratory expansion:Independent sector treatment centre networks in Greater Manchester and Birmingham are adding interventional cardiology capacity requiring specialized diagnostic and therapeutic supplies.
Market Restraints
- Ethylene oxide sterilization constraints:Environmental permit limitations at UK-based sterilization facilities are creating bottlenecks for polymer-based single-use devices.
- Raw material concentration:Medical-grade polymer supply chains remain concentrated among German and Belgian specialty chemical producers, exposing NHS procurement to continental logistics disruptions.
- MHRA workforce capacity:Conformity assessment body staffing limitations are extending UKCA marking timelines beyond historical CE marking durations.
Strategic Opportunities
- Scotland's remote care infrastructure:NHS Scotland's Highland and Island health boards present underpenetrated demand for point-of-care diagnostic systems reducing patient transport requirements.
- Reusable surgical instrument reprocessing:Carbon accounting frameworks are creating procurement preference for stainless steel instrument sets with validated sterilization cycles over polymer disposables.
- Digital supply chain integration:GS1 UK standards adoption is enabling real-time inventory visibility contracts linking distributor systems directly to hospital enterprise resource planning platforms.
Industry Challenges
- Sterilization validation expertise:NHS trust procurement teams lack technical capacity to evaluate novel low-temperature sterilization technologies against established ethylene oxide and steam protocols.
- Legacy equipment interoperability:Patient monitoring system upgrades in London's hospital networks require middleware solutions bridging proprietary data formats from incumbent capital equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Hospital Supplies Market |
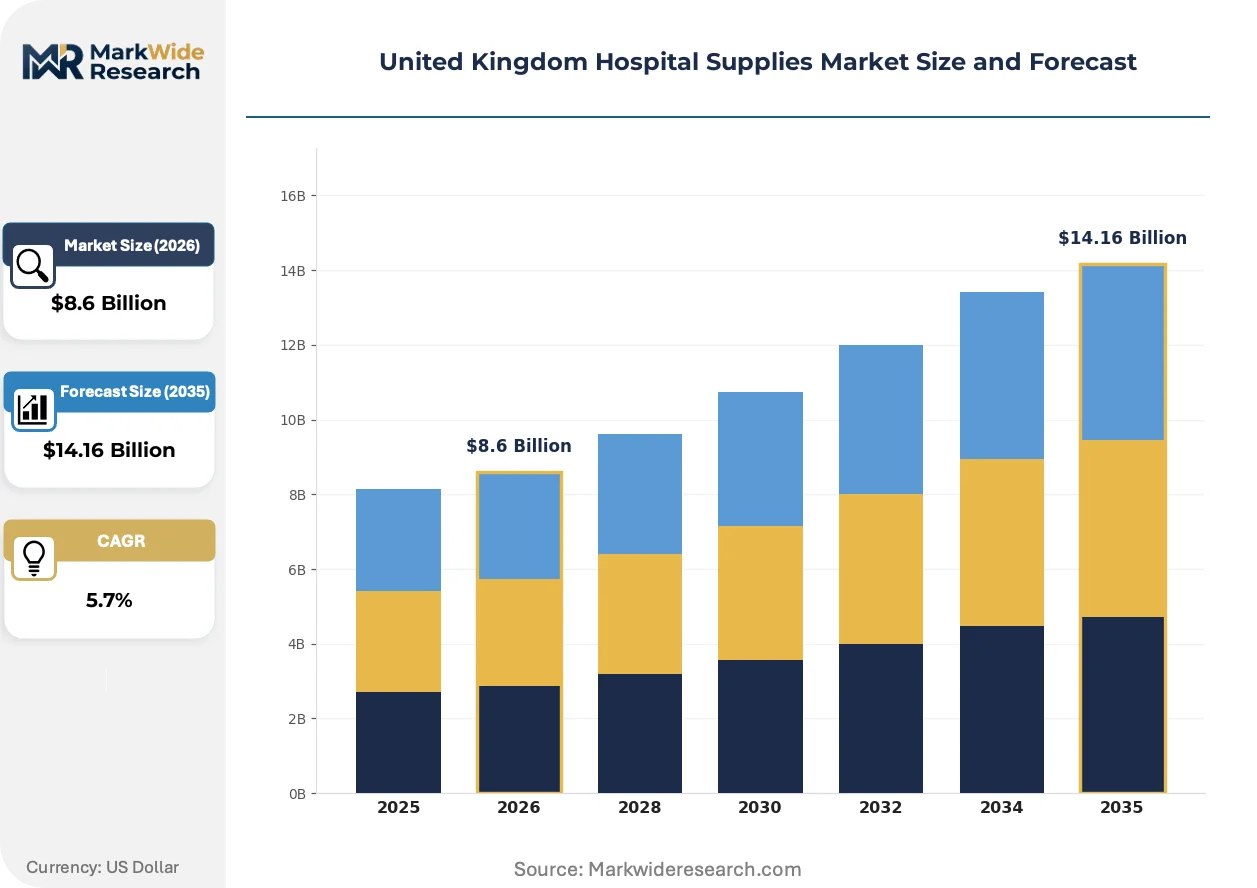
| Market Size in 2026 | $8.6 Billion |
| Market Size in 2035 | $14.16 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Instruments, Diagnostic Equipment, Disposable Supplies, Medical Furniture End User: Public Hospitals, Private Clinics, Research Laboratories, Long-term Care Facilities Delivery Mode: Direct Sales, Online Distribution, Wholesaler, Retail Outlets Application: Emergency Care, Surgical Procedures, Patient Monitoring, Rehabilitation |
| Companies Covered | B. Braun Melsungen AG, 3M, Baxter International Inc., Medtronic, Cardinal Health Inc., Johnson & Johnson, Stryker, Abbott Laboratories, Smith & Nephew plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Hospital Supplies Market Evolving Landscape
Digital traceability infrastructure is displacing paper-based supply chain documentation across NHS procurement frameworks. Real-time location systems and automated inventory management are compressing working capital cycles for acute care networks.
Radio-frequency identification tagging is hybridizing with blockchain-based provenance records for high-value implantable devices. NHS England's specialised commissioning teams are piloting automated recall management systems linking patient electronic health records to lot-level device identifiers. This convergence is compressing liability exposure windows and enabling value-based procurement frameworks for orthopaedic and cardiovascular implants.
Care Quality Commission inspection protocols now mandate demonstrable maintenance records for all patient-facing equipment. Trust accreditation decisions increasingly hinge on supply chain traceability system maturity rather than episodic documentation reviews. Smaller district general hospitals are consolidating procurement compliance functions into shared service centres to meet these elevated documentation standards.
Consolidated procurement through NHS Supply Chain is displacing trust-level tendering for commodity consumables. Acute networks in the West Midlands are adopting framework agreements with embedded carbon accounting requirements, shifting vendor selection criteria beyond unit cost to lifecycle environmental impact. Independent sector providers remain outside this consolidation, maintaining direct purchasing relationships with specialty distributors.
United Kingdom Hospital Supplies Market Segmentation
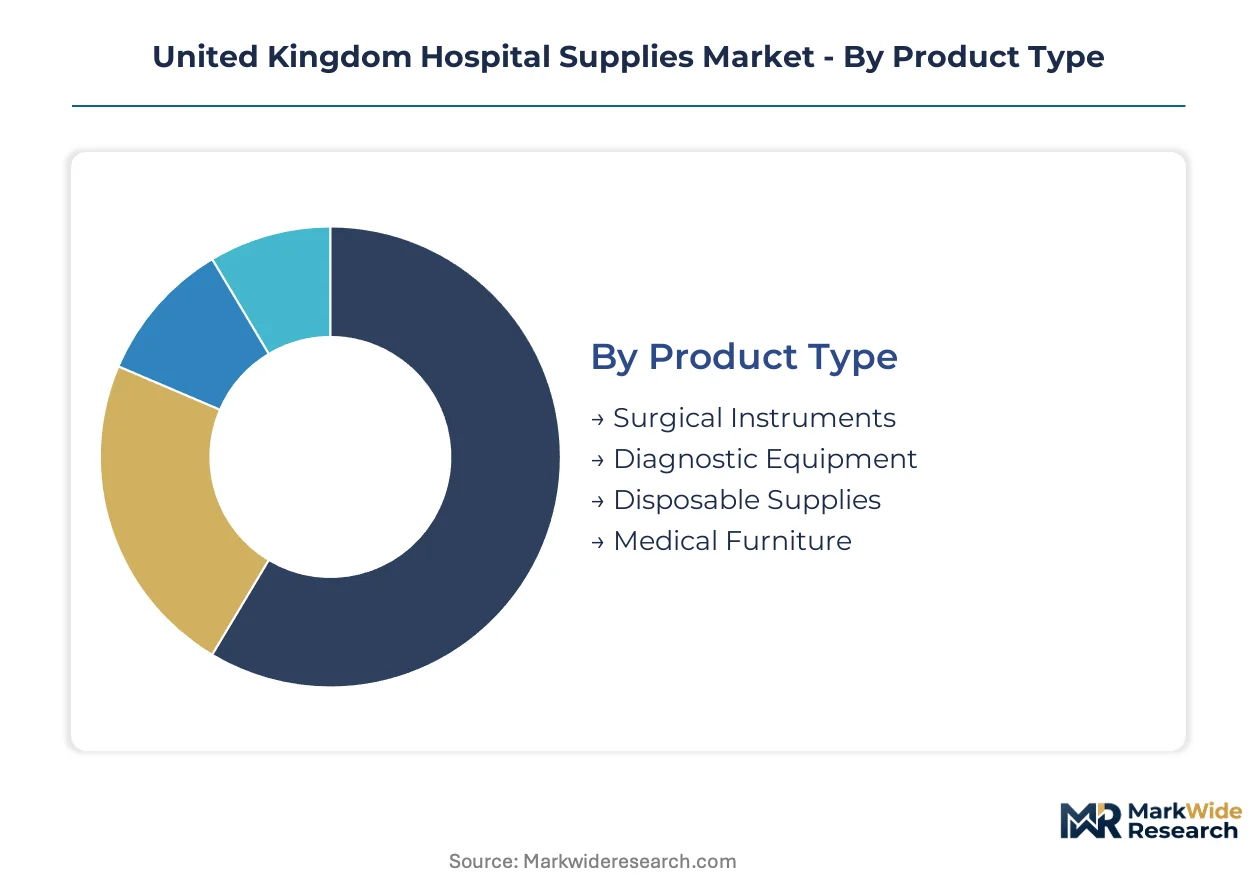
Segmentation in the United Kingdom hospital supplies market reveals how procurement authority, clinical setting, and supply chain configuration reshape competitive access. NHS England's consolidated purchasing power contrasts sharply with independent sector flexibility, creating divergent margin structures across product categories.
Product Type:
Cost tier differentiation separates capital-intensive equipment from high-volume consumables, with sterilization validation requirements further stratifying supplier qualification.
- Surgical Instruments:Stainless steel and polymer-based tools manufactured to ISO 13485 standards, with reusable sets requiring validated sterilization cycles. London's acute trusts concentrate demand for orthopaedic and cardiovascular procedure kits under NHS England's bundled payment frameworks.
- Disposable Supplies:Single-use polymer devices including catheters, drapes, and wound care materials sterilized to SAL 10^-6 levels. Greater Manchester and Birmingham's expanding private catheterization laboratories are driving interventional cardiology consumable procurement.
- Diagnostic Equipment:Imaging systems and point-of-care testing platforms capturing premium margins through technology upgrade cycles.
- Medical Furniture:Patient beds, procedure chairs, and storage systems subject to MHRA UKCA marking and NHS Net Zero carbon disclosure mandates.
Surgical instruments hold installed capacity. Disposable supplies are rotating up the share rankings.
End User:
Customer type determines procurement pathway complexity, with public sector framework compliance contrasting against private sector direct negotiation.
- Public Hospitals:NHS trusts and foundation hospitals operating under NHS Supply Chain consolidated procurement with embedded carbon accounting requirements. Acute networks in the West Midlands are adopting framework agreements linking distributor systems directly to enterprise resource planning platforms.
- Private Clinics:Independent sector treatment centres and specialist chains purchasing outside NHS consolidation. Greater Manchester and Birmingham networks are adding interventional cardiology capacity requiring specialized diagnostic and therapeutic supplies.
- Research Laboratories:Academic medical centres and contract research organizations with distinct procurement protocols for investigational device exemptions.
- Long-term Care Facilities:Nursing homes and rehabilitation centres with lower acuity requirements and reduced sterilization infrastructure investment.
Public hospitals anchor volume concentration. Private clinics are expanding most quickly.
Delivery Mode:
Supply chain configuration separates capital equipment installation from consumable replenishment velocity, with digital integration reshaping inventory management.
- Direct Sales:Manufacturer-to-hospital contracts for capital equipment including patient monitoring systems and imaging platforms. London's hospital network anchors concentrated demand requiring middleware solutions bridging proprietary data formats from incumbent equipment.
- Online Distribution:E-procurement platforms enabling real-time inventory visibility through GS1 UK standards adoption. Smaller district general hospitals are consolidating procurement compliance functions into shared service centres.
- Wholesaler:Regional distributors holding stock for acute trust emergency replenishment.
- Retail Outlets:Limited channel for non-acute consumables and home care products.
Direct sales retains premium equipment control. Online distribution is climbing the fastest.
Application:
Clinical use case determines regulatory scrutiny intensity and reimbursement pathway, with emergency and surgical applications facing highest conformity assessment requirements.
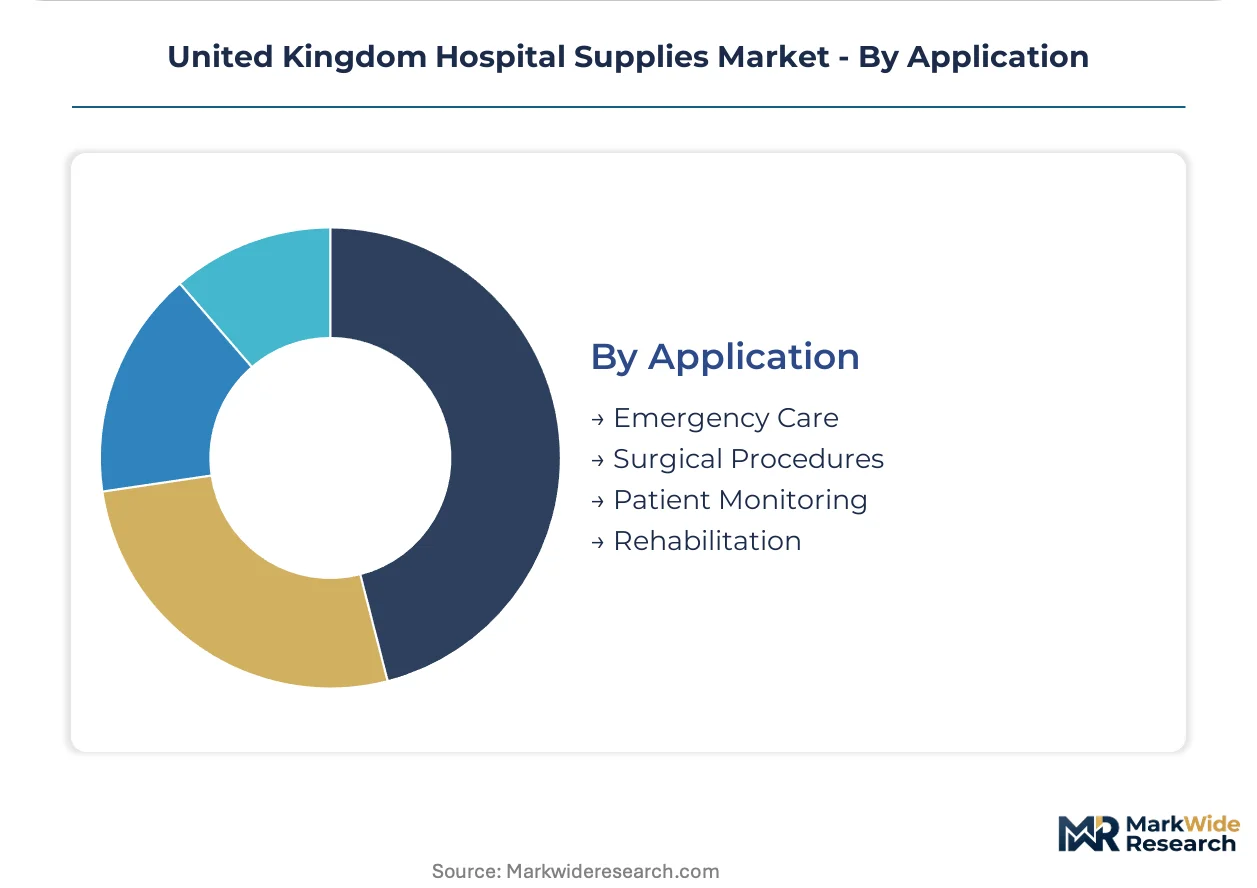
- Surgical Procedures:Orthopaedic, cardiovascular, and general surgery consumables and instruments. NHS England's recovery targets for elective backlogs are expanding demand for procedure-specific kits across acute trusts.
- Patient Monitoring:Continuous vital signs surveillance systems and telemetry infrastructure. London's hospital network concentrates demand for advanced monitoring upgrades.
- Emergency Care:Resuscitation equipment and trauma supplies held in A&E departments.
- Rehabilitation:Physical therapy devices and mobility aids with lower regulatory classification burden.
Surgical procedures command revenue concentration. Patient monitoring is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across the United Kingdom. NHS England's consolidated procurement exerts severe price pressure on commodity consumables, while Scotland's remote care infrastructure commands premium valuations for point-of-care diagnostic systems reducing patient transport burdens.
London and Southeast England
London's hospital network concentrates demand for advanced patient monitoring systems and interventional cardiology suites. NHS England's Net Zero Supplier Roadmap mandates carbon footprint disclosure for all contracted suppliers, reshaping vendor qualification processes. The capital's acute trusts are adopting framework agreements with embedded lifecycle environmental impact criteria, shifting selection beyond unit cost.
Midlands
Greater Manchester and Birmingham anchor expanding private catheterization laboratory capacity requiring specialized diagnostic and therapeutic supplies. Care Quality Commission inspection protocols mandate demonstrable maintenance records for all patient-facing equipment. West Midlands acute networks are consolidating procurement compliance functions into shared service centres to meet elevated documentation standards.
Scotland
NHS Scotland's Highland and Island health boards present underpenetrated demand for point-of-care diagnostic systems. The country's national health service operates distinct procurement protocols from NHS England, creating dual qualification requirements for cross-border suppliers. Remote care infrastructure investments in Aberdeen and Inverness are reducing patient transport requirements through distributed diagnostic capacity.
Wales
Welsh health boards operate under NHS Wales procurement frameworks with tighter capital equipment budgets than English counterparts. The Medicines and Healthcare products Regulatory Agency enforces UKCA marking requirements uniformly across Great Britain, compelling manufacturers to establish domestic conformity assessment routes. Cardiff's university hospital network anchors specialized commissioning for orthopaedic procedure kits.
Northern England
Post-industrial cities including Leeds, Sheffield and Newcastle exhibit elective surgery backlog recovery targets expanding demand for procedure-specific kits. NHS England's specialised commissioning teams are piloting automated recall management systems linking patient electronic health records to lot-level device identifiers. Smaller district general hospitals in Yorkshire are consolidating sterilization validation expertise through regional procurement collaboratives.
United Kingdom Hospital Supplies Market Competitive Landscape
Integrated sterilization service providers and direct-distribution specialists split the market between recurring revenue capture and acute trust procurement efficiency. The vendor base concentrates around three strategic archetypes: sterilization infrastructure operators, orthopaedic procedure kit specialists, and acute network distribution contractors. Consolidation among sterilization service providers is concentrating aftermarket value capture, while framework agreement penetration is displacing trust-level tendering for commodity consumables.
Within the sterilization infrastructure tier, B. Braun Melsungen AG exemplifies the recurring revenue model through service contracts with NHS trusts. Cardinal Health Inc. occupies a position among direct-distribution specialists anchoring acute care network relationships. Smith & Nephew plc represents the orthopaedic procedure kit archetype sustaining premium positioning within bundled payment frameworks. These three players illustrate how divergent strategic postures—sterilization services, distribution scale, and clinical specialization—coexist within a procurement environment tightening traceability and carbon disclosure standards.
| Leading Market Players |
|---|
| B. Braun Melsungen AG |
| 3M |
| Baxter International Inc. |
| Medtronic |
| Cardinal Health Inc. |
| Johnson & Johnson |
| Stryker |
| Abbott Laboratories |
| Smith & Nephew plc |
| Others |
Value Network & Pricing Analysis
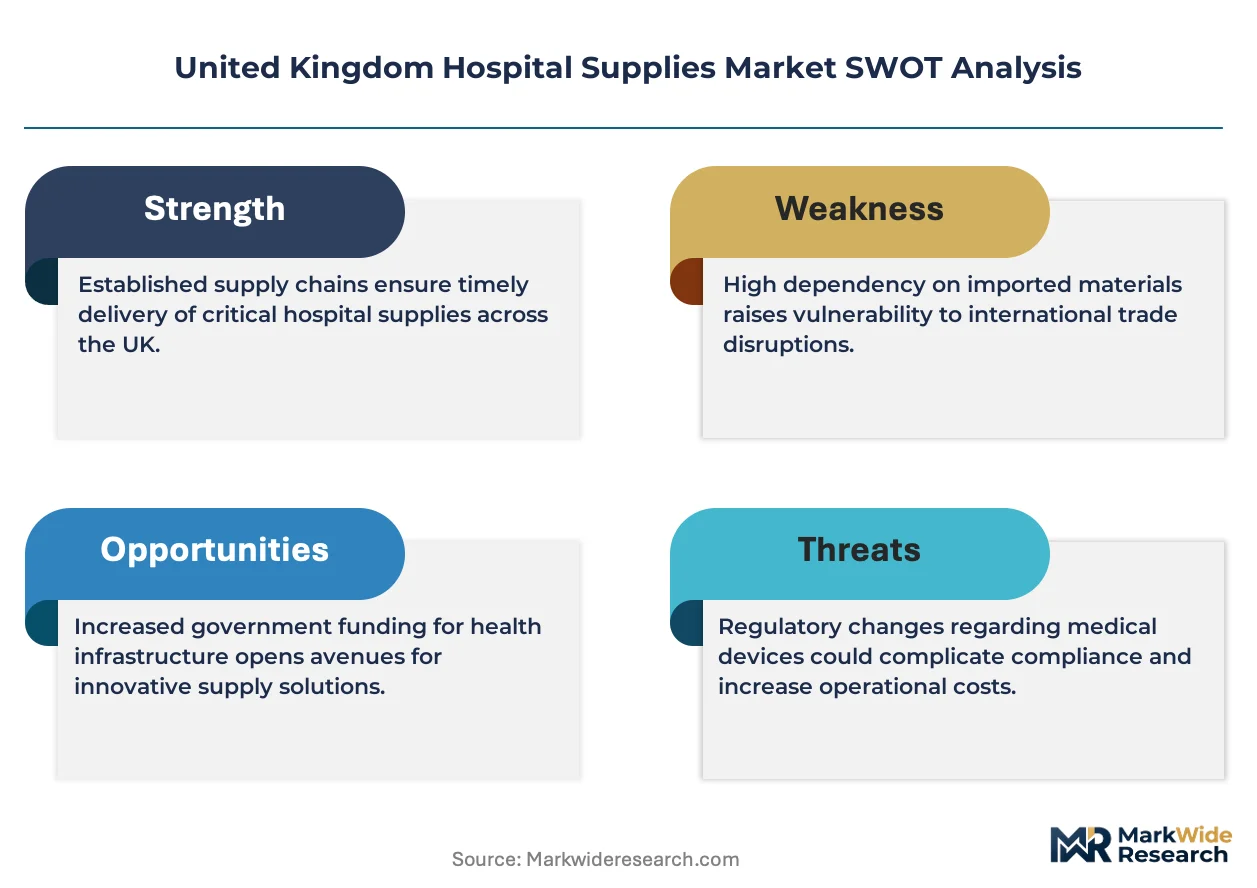
Single-source dependency on German and Belgian medical-grade polymer producers determines both tiered pricing spreads across NHS procurement frameworks and the elongated supply chain configuration tethering UK hospital networks to continental logistics corridors. This concentration amplifies cost volatility transmission while compressing margin buffers for sterilization service providers competing on carbon-disclosure compliance.
Pricing Analysis
Aftermarket sterilization service contracts anchor lifetime value capture for capital equipment vendors serving NHS trusts. Three-tier pricing structure across premium, standard, and economy levels stratifies by UKCA certification tier and bundled maintenance scope. Cost compression in commodity consumables intensifies because NHS Supply Chain consolidation favors framework-compliant vendors with embedded carbon accounting. District general hospitals exhibit highest price sensitivity due to shared service centre procurement pooling, while London acute trusts show lowest sensitivity for patient monitoring upgrades.
Supply Chain Analysis
Medical-grade polymer feedstock draws from German and Belgian specialty chemical producers, with stainless steel surgical instrument blanks sourcing from Italian and Spanish foundries. Raw material dependencies center on ethylene oxide sterilization gases, polymer resins, and precision-machined instrument components. Single-source vulnerability concentrates in ethylene oxide environmental permit holders facing regulatory restriction. Distribution runs through NHS Supply Chain consolidated procurement for consumables, with direct manufacturer contracts governing capital equipment installation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GS1 UK standards adoption and real-time inventory visibility platforms signal a platform-economics inflection where interoperability determines vendor survival. Ecosystem lock-in through ERP-integrated procurement systems is displacing episodic tendering.
For Market Incumbents: Entrench sterilization service infrastructure through multi-year NHS trust contracts embedding carbon footprint validation. Consolidate aftermarket value capture by acquiring regional sterilization validation expertise pools threatened by MHRA workforce capacity constraints. Backward integration into polymer reprocessing technology hedges ethylene oxide permit bottlenecks.
For New Entrants and Emerging Players: Establish a beachhead in Scotland's Highland and Island health boards where point-of-care diagnostic demand outpaces incumbent service coverage. Target private catheterization laboratory networks in Greater Manchester and Birmingham operating outside NHS Supply Chain consolidation. Pursue direct distribution partnerships with independent sector treatment centres bypassing framework compliance overhead.
For Investors and Strategic Acquirers: The market sits at a regulatory-compression phase that favors sterilization infrastructure operators with validated UKCA conformity assessment routes. Long-term viability over the coming decade rests on carbon-accounting procurement preference durability. Monitor MHRA staffing expansion signals as inflection indicator for marking timeline normalization.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Direct ERP integration with NHS trusts secures recurring consumable replenishment contracts. |
| CE Marking Pathway | Dual UKCA-CE certification preserves Great Britain and Northern Ireland market access post-Brexit. |
| Software Companion Development | Middleware solutions bridge proprietary patient monitoring data formats to hospital IT infrastructure. |
| Reimbursement Strategy | Bundled payment framework alignment sustains premium positioning for orthopaedic procedure kits. |
| Backward Integration | In-house polymer reprocessing capacity hedges ethylene oxide sterilization permit constraints. |
Research Methodology
Cross-validation between hospital procurement database analysis and MHRA UKCA registration records anchors the qualitative findings. Primary interviews with NHS trust purchasing committees, biomedical engineering directors, GPO contracts managers, and sterilization service operations heads combined with secondary validation against NHS Supply Chain framework disclosures, Care Quality Commission inspection reports, and GS1 UK standards documentation. Bottom-up demand modeling and top-down procurement spend analysis triangulate market sizing.
Calibration against historical NHS capital equipment replacement cycles and elective surgery backlog recovery trajectories shapes the projection framework. Segmentation dimensions modeled include product type tier, end-user procurement pathway, delivery mode configuration, and clinical application intensity across the analysis window. CAGRs derive from procedure volume elasticity to NHS England recovery targets and technology upgrade cycle compression. Sterilization service contract renewal rates and carbon disclosure compliance thresholds feed industry-specific forecast inputs.
Sensitivities concentrate around MHRA workforce expansion pace, ethylene oxide environmental permit issuance, and NHS Net Zero Supplier Roadmap enforcement intensity. Cross-checking against NHS England annual procurement spend disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Sterile IV Containers Market
Medical Supplies
Surgical Amniotics Market
Medical Supplies
Steam Sterilizer Bag Market
Medical Supplies
Veterinary Syringes Market
Medical Supplies
Sequencing Consumables Market
Medical Supplies
Europe Syringe Market
Medical Supplies
Europe Intravenous Solutions Market
Medical Supplies
Anesthesia Syringes and Needles Market
Medical Supplies
Prepackaged Medical Kits and Trays Market
Medical Supplies
Scintillation Vials Market
Medical Supplies
Global Disposable Blood Bags Market
Medical Supplies
US N95 Mask Market
Medical Supplies
Medical Supply Delivery Service Market
Medical Supplies
Ampoules and Syringes Market
Medical Supplies
Swab Cups Market
Medical Supplies
Nitrile Gloves Market