
 China Smart Power Distribution Systems Market | 2026-2036
China Smart Power Distribution Systems Market Size, Share, and Industry Trends Forecast 2026-2036
China Smart Power Distribution Systems Market Insights
Grid software engineering talent is rotating toward utility-adjacent technology firms, tightening the labor pool for traditional equipment vendors. State Grid Corporation of China leverages its nationwide transmission monopoly to dominate smart meter deployment at scale. Huawei Technologies Co., Ltd. competes through proprietary edge-computing chipsets for distribution automation. NARI Technology Co., Ltd. anchors its position in protective relay systems and SCADA integration.
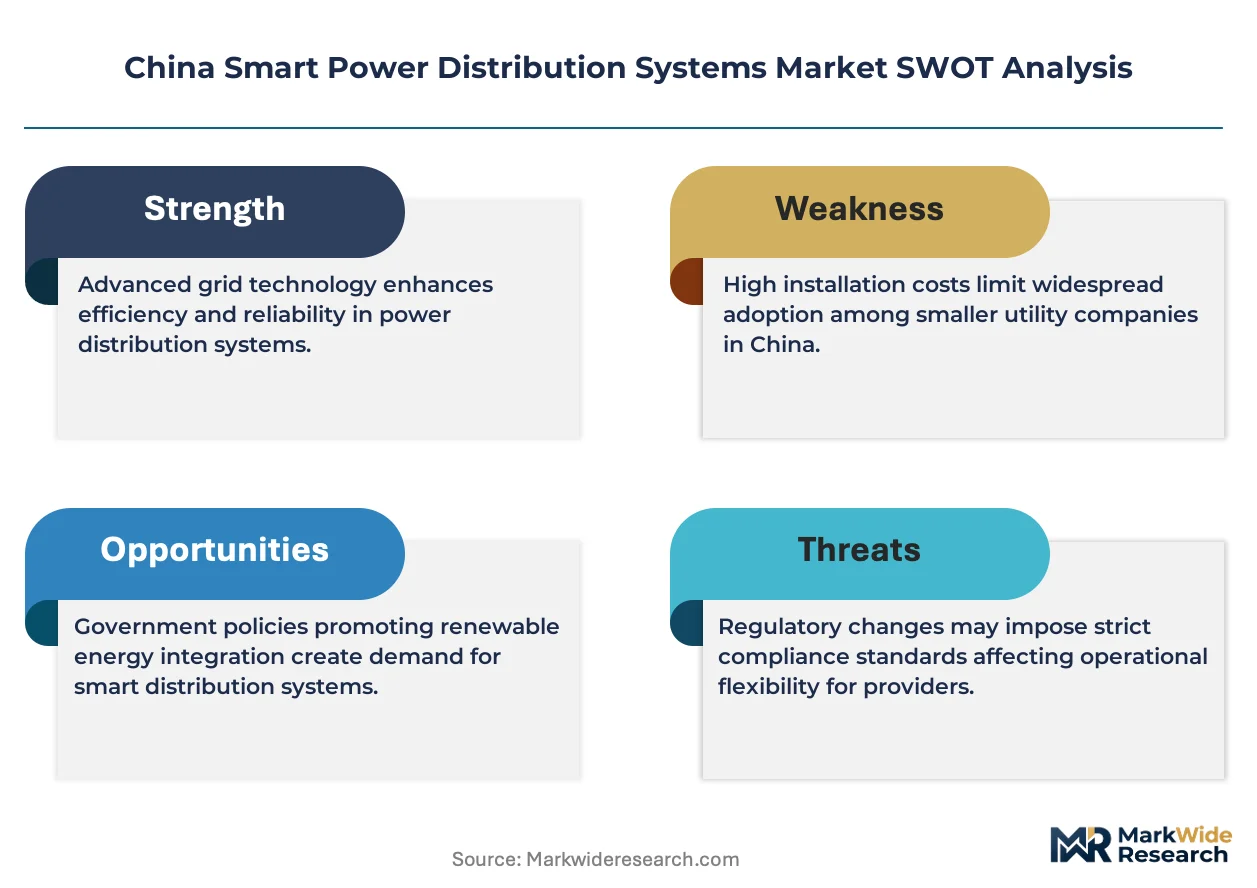
China smart power distribution systems integrate sensing, communication, and control layers to enable real-time fault isolation and load balancing across medium- and low-voltage networks, typically operating at 10 kV to 0.4 kV with latency requirements below 100 milliseconds for protection functions. The primary purpose is to reduce outage duration and accommodate distributed renewable injection from rooftop solar and urban wind installations. Smart meters and distribution automation together capture the dominant share of hardware spending, while AI and big data analytics represent the fastest-expanding technology layer as utilities prioritize predictive maintenance over reactive grid operations. IoT connectivity modules face margin compression from commoditization, though cybersecurity-hardened variants retain pricing power.
MIIT's GB standards for industrial internet security and MEE's emissions-linked grid efficiency mandates are tightening compliance thresholds for foreign and domestic suppliers alike, effectively filtering market access to vendors with certified domestic manufacturing. BIS-equivalent testing protocols for electromagnetic compatibility now extend to software-defined protection relays. Stakeholders must weigh the capital intensity of retrofitting legacy substations against greenfield digital deployments in China's expanding western city clusters.
Market Dynamics
State Grid Corporation of China's monopoly over transmission infrastructure is concentrating procurement power into a single buyer, forcing equipment vendors to restructure pricing and service models around utility-scale deployment timelines rather than commercial flexibility.
Growth Catalysts
- Dual carbon mandates from MEE:Binding emissions intensity targets for provincial grids are accelerating digital substation retrofits in coastal manufacturing zones.
- Distributed solar injection:Rooftop photovoltaic clusters in the Yangtze River Delta require bidirectional power flow management and real-time voltage regulation.
- AI-driven predictive maintenance:Machine learning algorithms trained on SCADA fault histories are reducing outage duration below legacy protection thresholds.
Market Restraints
- Semiconductor supply concentration:Edge-computing chipsets for distribution automation depend on fabrication capacity concentrated in Taiwan and South Korea.
- Legacy asset stranding:Electromechanical relay systems with 30-year depreciation schedules block capital allocation to software-defined protection.
- MIIT cybersecurity certification delays:GB standards for industrial internet security require 18-24 month validation cycles for foreign component suppliers.
Strategic Opportunities
- Western city cluster greenfield deployment:Chengdu-Chongqing and Xi'an urban corridors lack legacy substation infrastructure, enabling native digital architecture.
- 5G-Advanced network slicing:China Mobile and China Telecom are commercializing ultra-reliable low-latency communication for protection-grade grid control.
- Carbon accounting integration:MEE's emissions-linked efficiency mandates create demand for real-time carbon intensity metering at distribution feeders.
Industry Challenges
- Grid software engineering scarcity:Utility-adjacent technology firms are absorbing talent with equity compensation structures unavailable to state-owned equipment vendors.
- Interoperability fragmentation:Proprietary communication protocols from dominant automation suppliers complicate multi-vendor system integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Smart Power Distribution Systems Market |
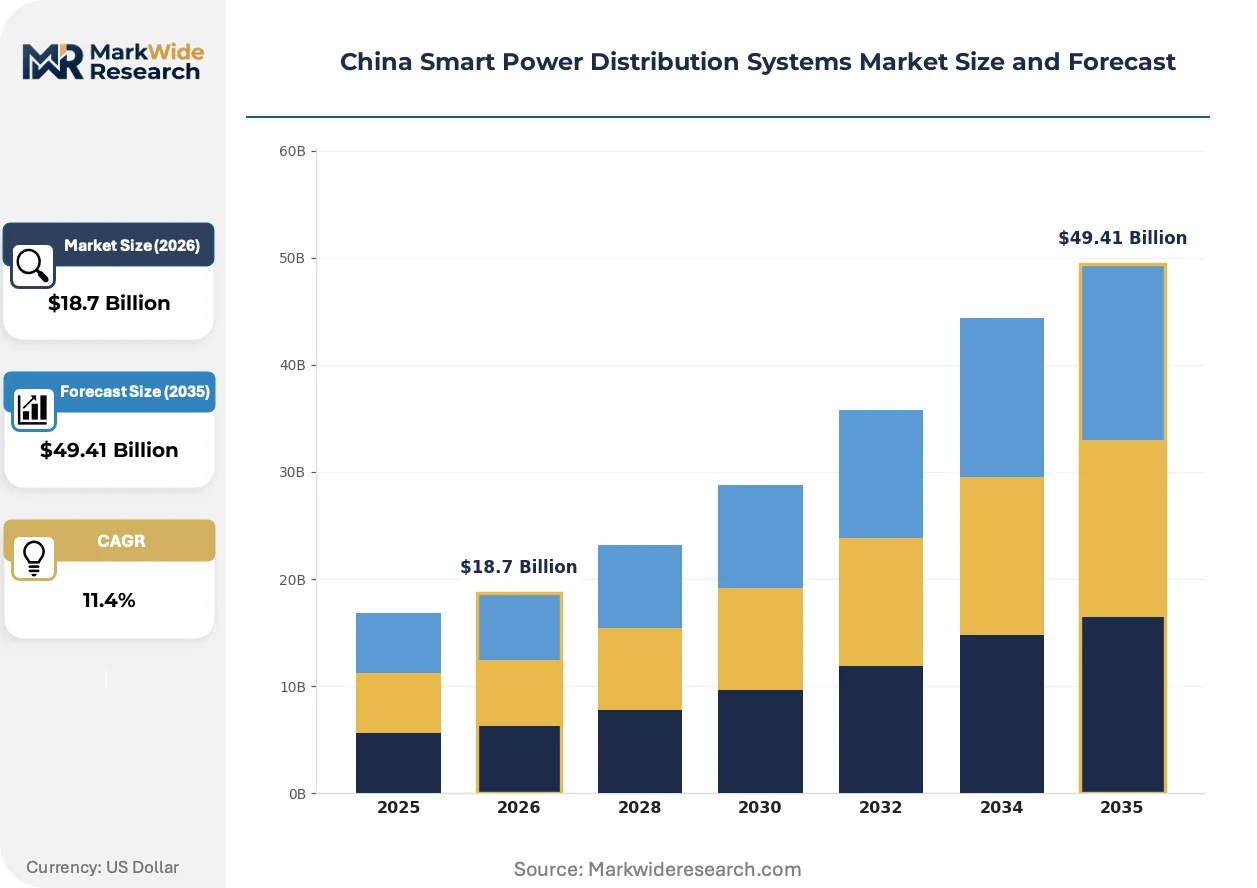
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Meters, Distribution Automation, PLC, Sensors Technology: IoT, Cloud Computing, AI, Big Data End User: Utilities, Residential, Commercial, Industrial Installation: Onshore, Indoor, Outdoor, Retrofit |
| Companies Covered | State Grid Corporation of China (SGCC), China Southern Power Grid (CSG), NARI Technology Co., Ltd., China XD Electric Co., Ltd., Guodian Nanjing Automation Co., Ltd., Huawei Technologies Co., Ltd., Schneider Electric SE, Siemens AG, ABB Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Smart Power Distribution Systems Market Trends and Innovations
Digital twin modeling is compressing commissioning timelines for complex distribution networks while forcing traditional equipment suppliers to develop software competencies or exit medium-voltage automation.
Digital twin platforms for distribution network simulation are supplanting physical commissioning tests for protection relay settings. Provincial grid operators in Jiangsu and Zhejiang are mandating virtual validation before energization. This shift is compressing project delivery schedules while elevating software engineering margins above hardware manufacturing.
MIIT's GB/T 22239-2019 cybersecurity baseline is hardening procurement specifications for all network-connected protection devices. Domestic vendors with certified in-house firmware development are capturing tenders previously open to foreign suppliers. The standard's tiered compliance levels are fragmenting the supplier base into certified integrators and component-only vendors.
State Grid's centralized procurement platform is consolidating annual demand for smart meters and automation terminals into single-tender volumes exceeding provincial utility scale. Equipment vendors are restructuring sales organizations around Beijing headquarters relationships rather than regional branch networks. This concentration is visible in the Yangtze River Delta, where municipal utility procurement autonomy has diminished significantly.
China Smart Power Distribution Systems Market Segmentation
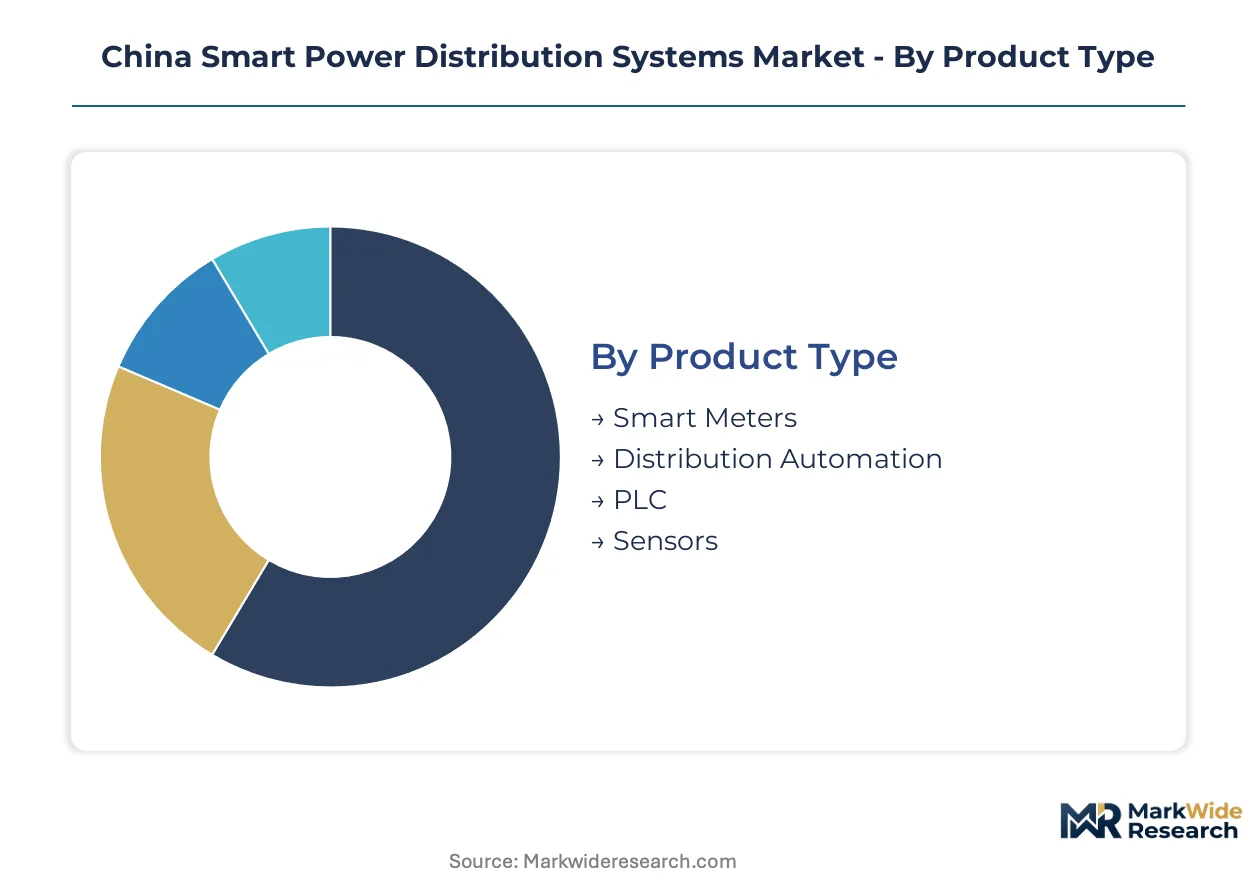
Segmentation in China's smart power distribution systems reveals where procurement power concentrates and which technology layers face displacement risk. State Grid's centralized tendering structure rewards scale in hardware while software competencies determine margin capture.
Product Type:
Smart meters face intensifying substitution pressure from integrated automation terminals that combine metering with edge control, compressing standalone device margins.
- Smart Meters:Bidirectional communication devices with 0.2S accuracy class for revenue-grade measurement. Demand concentrates in Jiangsu and Zhejiang provinces where State Grid executes million-unit tenders annually; AMI integration mandates are phasing out first-generation units.
- Distribution Automation:Fault detection, isolation, and restoration systems operating at 10 kV with sub-100ms response. Chengdu-Chongqing corridor greenfield deployments favor native digital architecture over retrofits.
- PLC:Power line carrier communication modules for last-mile connectivity in dense urban feeders.
- Sensors:Temperature, current, and voltage transducers for real-time thermal monitoring of distribution transformers.
Smart meters anchor the volume base while distribution automation gains share at the steepest rate.
Technology:
Technology cost tiers separate capital-intensive infrastructure layers from rapidly commoditizing connectivity modules.
- IoT:LPWAN and cellular connectivity modules for device telemetry. Margin compression from chipset commoditization is forcing vendors toward cybersecurity-certified variants with MIIT GB/T 22239-2019 compliance.
- Cloud Computing:Provincial grid data centers hosting SCADA historians and analytics workloads. State Grid's internal cloud infrastructure limits third-party provider access in coastal provinces.
- AI:Machine learning models for predictive maintenance trained on fault history databases.
- Big Data:Real-time stream processing for load forecasting and renewable integration.
IoT modules dominate unit shipments while AI expands most quickly as utilities prioritize predictive over reactive operations.
End User:
End user concentration patterns mirror China's ownership structure for grid infrastructure.
- Utilities:State Grid and Southern Power Grid as monopoly transmission and distribution operators. Centralized procurement platforms aggregate annual demand exceeding provincial utility scale; Beijing headquarters relationships determine vendor access.
- Industrial:Steel, chemical, and automotive manufacturing facilities with captive substations requiring power quality management. Yangtze River Delta manufacturing zones drive demand for sag and swell compensation.
- Residential:Apartment complex distribution rooms and rooftop solar aggregation.
- Commercial:Data centers and retail complexes with critical load requirements.
Utilities command procurement volume while industrial microgrids climb the fastest as manufacturers seek resilience against grid instability.
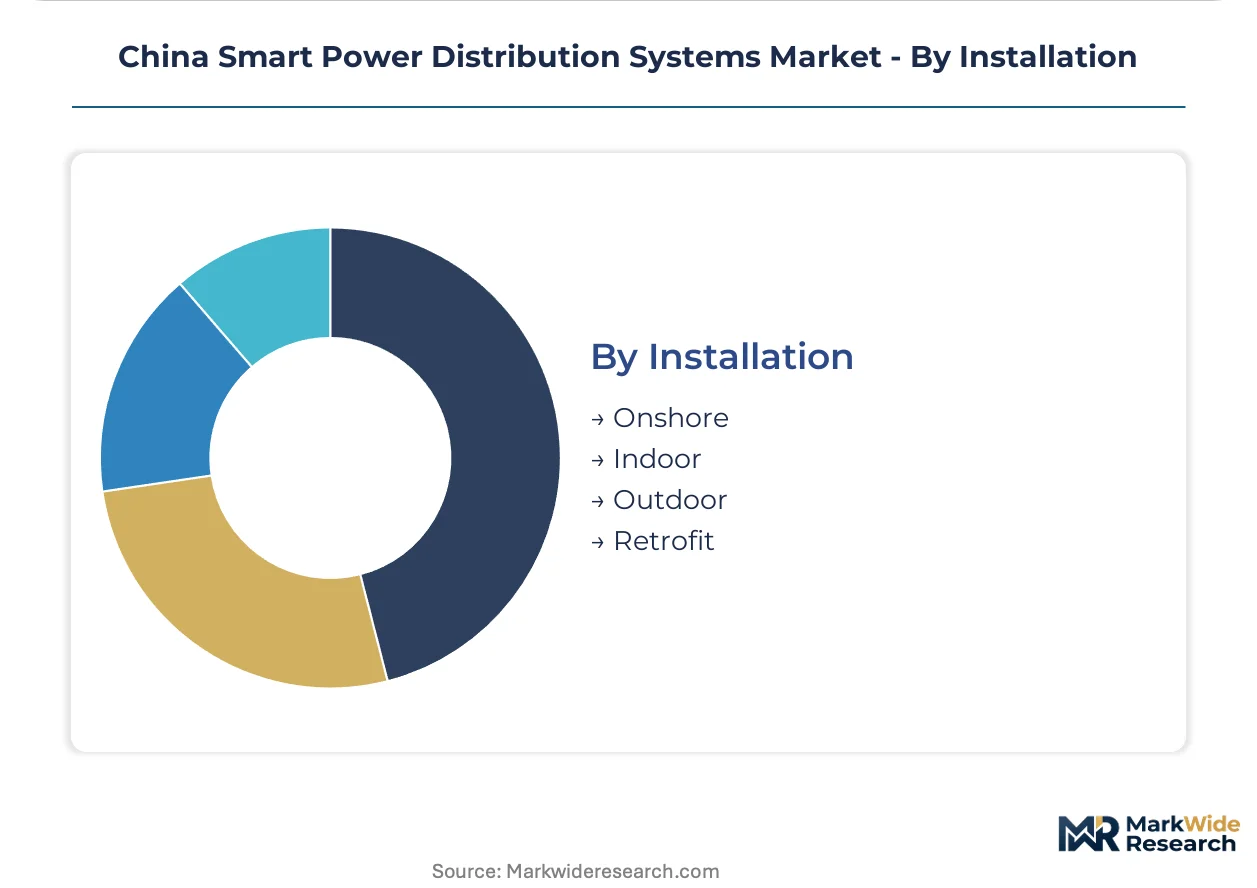
Installation:
Installation modes reflect the geographic split between legacy coastal infrastructure and western greenfield expansion.
- Retrofit:Digital upgrades to electromechanical substations with 30-year depreciation schedules. Legacy asset stranding blocks capital allocation in coastal provinces where equipment remains serviceable.
- Onshore:Underground cable networks in dense urban cores requiring compact switchgear.
- Indoor:Climate-controlled substation buildings for sensitive protection equipment.
- Outdoor:Pole-mounted automation terminals for rural distribution feeders.
Retrofit installations retain the largest installed base while onshore deployment in western city clusters shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT's GB standards and dual carbon mandates under MEE anchor investment flows across China's provincial grids, concentrating procurement in coastal manufacturing belts and western greenfield corridors.
Yangtze River Delta
Jiangsu and Zhejiang provinces drive demand through million-unit smart meter tenders and digital substation retrofits. MEE's emissions intensity targets bind provincial grid operators to efficiency upgrades. Shanghai and Suzhou manufacturing clusters require bidirectional power flow management for rooftop solar aggregation.
Pearl River Delta
Guangdong's industrial load centers generate demand for power quality management and voltage regulation systems. MIIT's industrial internet security standards filter equipment procurement to certified domestic vendors. Shenzhen and Guangzhou data center expansions drive critical load protection requirements.
Beijing-Tianjin-Hebei
Capital region grid modernization prioritizes AI-driven predictive maintenance and SCADA integration. State Grid's centralized procurement platform aggregates annual demand from municipal utilities. Tianjin port electrification and Beijing's urban rail expansion strain distribution capacity.
Sichuan-Chongqing
Western city cluster greenfield deployments favor native digital architecture without legacy electromechanical constraints. MEE's grid efficiency mandates apply binding targets to new provincial grid infrastructure. Chengdu and Chongqing urban corridors lack stranded assets, enabling direct digital substation deployment.
Shandong Peninsula
Coastal manufacturing zones combine heavy industrial load with distributed renewable injection requirements. MIIT cybersecurity certification delays foreign supplier access to protection device tenders. Qingdao and Jinan utility procurement aligns with State Grid's centralized Beijing-directed platforms.
China Smart Power Distribution Systems Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with State Grid's procurement monopoly compressing margins for hardware vendors while elevating software competencies. The market structure concentrates around state-owned transmission operators as sole buyers, forcing equipment restructuring around utility-scale timelines. Two strategic archetypes dominate: vertically integrated domestic champions with certified manufacturing and international automation suppliers navigating compliance delays. Competitive moves center on cybersecurity certification acceleration and digital twin platform development.
Within the state-owned integrated tier, State Grid Corporation of China and China Southern Power Grid occupy positions as monopoly transmission and distribution operators, controlling procurement access. NARI Technology Co., Ltd. exemplifies the domestic specialist archetype with protective relay and SCADA integration positioning. Huawei Technologies Co., Ltd. anchors the technology-adjacent tier through edge-computing capabilities. Schneider Electric SE and Siemens AG represent international suppliers navigating MIIT certification cycles.
| Leading Market Players |
|---|
| State Grid Corporation of China (SGCC) |
| China Southern Power Grid (CSG) |
| NARI Technology Co., Ltd. |
| China XD Electric Co., Ltd. |
| Guodian Nanjing Automation Co., Ltd. |
| Huawei Technologies Co., Ltd. |
| Schneider Electric SE |
| Siemens AG |
| ABB Ltd |
| Others |
Pricing and Supply Chain Analysis
Eighteen-to-twenty-four-month MIIT cybersecurity certification cycles compress inventory turnover for foreign component suppliers while amplifying pricing power for domestic vendors with certified in-house firmware development. State Grid's centralized procurement platform aggregates annual demand into single-tender volumes, forcing equipment vendors to absorb working capital strain in exchange for volume access.
Pricing Analysis
Coastal Jiangsu and Zhejiang provinces command 15-20% premiums over western Sichuan-Chongqing corridors for identical automation hardware due to logistics and certification bundling. Project-based pricing dominates for distribution automation systems, with differentiation driven by MIIT GB/T 22239-2019 certification tier and after-sales service bundling. Cost compression in standalone smart meters is intensifying because integrated automation terminals are displacing standalone devices. Industrial microgrid operators show least price sensitivity due to resilience premiums, while municipal utilities in western corridors remain most price-sensitive.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication for edge-computing chipsets, while China dominates power semiconductor and passive component manufacturing. The supply chain draws from silicon wafers, rare earth magnetic materials, and industrial-grade capacitors. Single-source vulnerability concentrates in advanced node semiconductor fabrication. Distribution runs through State Grid's Beijing-directed centralized tendering platform, with regional branch networks losing procurement autonomy.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as MIIT's tiered cybersecurity compliance fragments the supplier base into certified integrators and component-only vendors, creating niche positioning for specialized firmware developers.
For Market Incumbents: Consolidate through backward integration into certified in-house firmware development to preempt MIIT compliance delays blocking foreign competitors. Acquire software engineering talent pools in Chengdu and Xi'an before utility-adjacent technology firms capture them with equity compensation. State Grid's procurement concentration threatens margin erosion for pure hardware vendors unable to bundle software services. For New Entrants and Emerging Players: Differentiate on cybersecurity certification acceleration services for foreign automation suppliers facing 18-24 month MIIT validation cycles. Target western city cluster greenfield deployments in Sichuan-Chongqing where native digital architecture lacks legacy retrofit constraints. Pursue partnership-based go-to-market with provincial grid operators seeking rapid commissioning through digital twin validation. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because MIIT's GB standards are filtering market access to vendors with certified domestic manufacturing, creating durable moats. Acquisition target archetype: domestic specialists with protective relay expertise and existing MIIT certification. Watch for inflection in provincial grid data center outsourcing decisions as State Grid's internal cloud infrastructure reaches capacity limits.| Strategic Initiative | Industry Significance |
|---|---|
| Cybersecurity Certification Acceleration | MIIT GB/T 22239-2019 compliance unlocks State Grid tender access for foreign suppliers. |
| Digital Twin Platform Development | Jiangsu and Zhejiang provincial mandates for virtual validation before energization compress commissioning timelines. |
| Western Greenfield Deployment Focus | Chengdu-Chongqing corridors lack stranded assets, enabling direct digital substation architecture without retrofit constraints. |
| Edge-Computing Chipset Localization | Domestic fabrication reduces Taiwan and South Korea supply concentration vulnerability for distribution automation. |
| AI-Driven Predictive Maintenance Integration | Machine learning models trained on SCADA fault histories command margin premiums over reactive protection systems. |
Research Methodology
Cross-validation between primary interviews with utility planning officers, grid automation engineers, procurement leads at equipment vendors, and MIIT certification specialists anchors the qualitative findings. Secondary validation draws from State Grid annual procurement disclosures, MIIT GB standards documentation, provincial grid operator tender announcements, and MEE emissions intensity target filings. Bottom-up segment sizing triangulates against top-down macroeconomic drivers across the analysis window.
Sensitivity analysis around semiconductor supply concentration and MIIT certification timeline variability shapes the projection envelope. Segmentation dimensions span product type, technology layer, end-user category, and installation mode. CAGRs derive from installed base growth, replacement cycles for electromechanical relays, and greenfield deployment trajectories in western corridors. Forecast inputs include provincial grid capital expenditure plans and rooftop solar penetration rates in Yangtze River Delta manufacturing zones.
Material uncertainties — semiconductor fabrication capacity allocation, MIIT regulatory enforcement intensity, provincial grid data center outsourcing decisions — sit outside the modeled envelope. Forecasts reflect assumptions about State Grid procurement centralization continuity and dual carbon mandate binding strength. Recalibration cycles align with material shifts in MIIT cybersecurity standard revisions and provincial emissions intensity target updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Grid
AC Grid Connected Microgrid Market
Smart Grid
Europe Smart Grid Security Market
Smart Grid
Smart Grid Home Area Network (HAN) Market
Smart Grid
Saudi Arabia Smart Grid Network Market
Smart Grid
South Korea Smart Grid Network Market
Smart Grid
Microgrid Controller Market
Smart Grid
Global Self-Healing Grid Market
Smart Grid
United States Smart Grid Security Market
Smart Grid
GCC Smart Grid Security Market
Smart Grid
Smart Grid Market
Smart Grid
UK Smart Grid Network Market
Smart Grid
Global Smart Grid Security Market
Smart Grid
North America Microgrid Market
Smart Grid
South and Central America Smart Grid Market
Smart Grid
South Africa Smart Grid Network Market
Smart Grid
Middle-East Smart Grid Network Market