
 Global Self-Healing Grid Market | 2026-2036
Global Self-Healing Grid Market Size, Share, and Industry Trends Forecast 2026-2036
Global Self-Healing Grid Market Foresight
Software-defined grid orchestration is decoupling hardware sales from recurring service revenue across the self-healing grid value chain. Schneider Electric SE leverages its EcoStruxure platform to anchor long-term utility contracts in Europe and North America. ABB sustains technology leadership through its Ability digital portfolio, while Siemens AG dominates integrated substation automation with hardware-software bundles that lock in decade-long maintenance streams.
A self-healing grid autonomously detects, isolates, and restores service after faults through real-time sensor networks, distributed intelligence, and automated switchgear with sub-cycle response thresholds below 100 milliseconds. Its primary purpose is eliminating sustained outages in radial distribution feeders and meshed transmission corridors. Automated Distribution technology leads capital deployment because utilities prioritize sectionalizing and reconfiguration logic over standalone sensing hardware. Communication Networks represent the fastest-growing segment as IEC 61850 and DNP3 protocol adoption forces IP-native backbone upgrades. Grid Automation application revenue pools concentrate where vertically integrated operators bundle control systems with energy storage dispatch.
The US Federal Energy Regulatory Commission Order 2222 and the EU F-Gas Regulation are accelerating interoperability mandates and phasing out sulfur hexafluoride-dependent switchgear, respectively. China's National Energy Administration enforces mandatory fault-location standards that drive smart sensor penetration in state-grid territories. Stakeholders must monitor how cybersecurity certification requirements under IEC 62351 reshape vendor qualification timelines and procurement decision criteria.
Market Dynamics
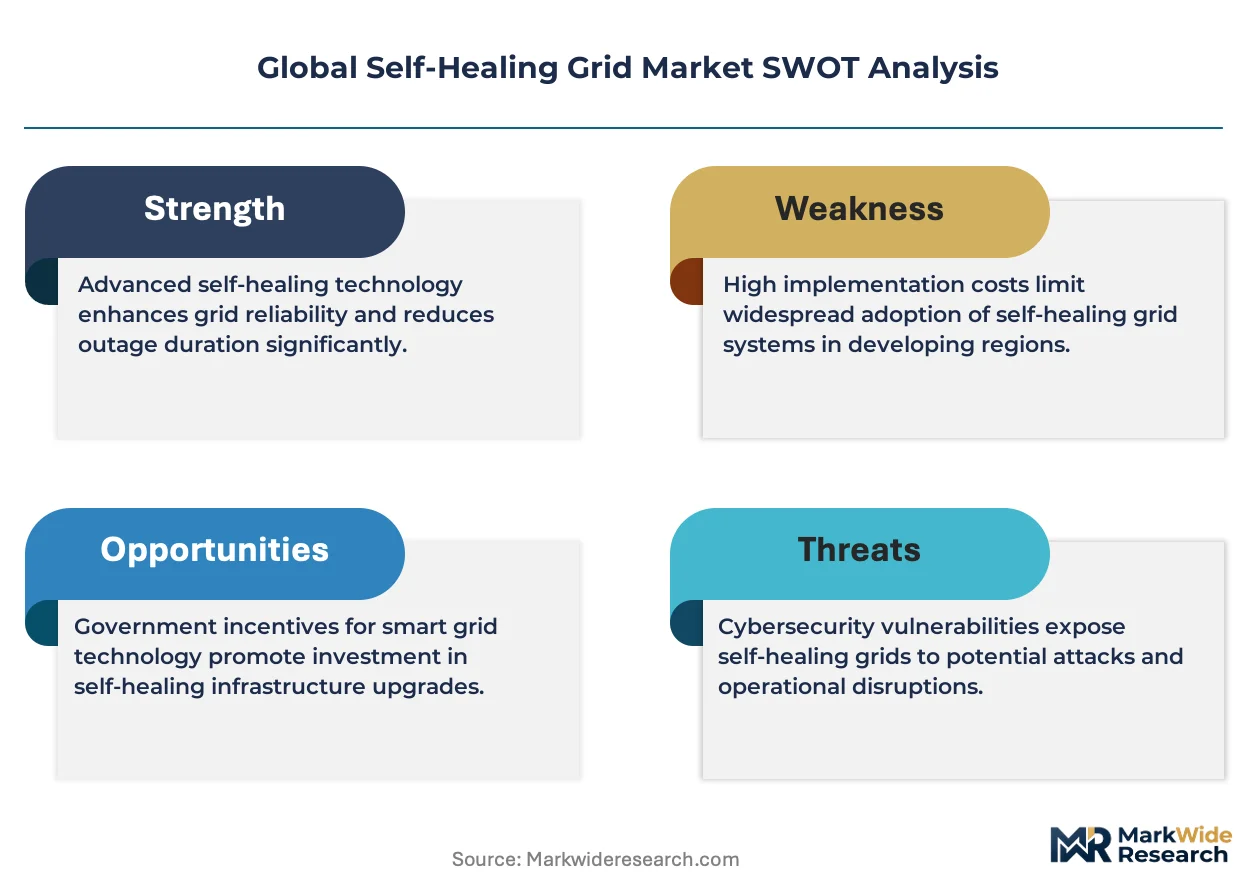
Software-defined orchestration is decoupling hardware from recurring service revenue, forcing vendors to restructure contract economics around multi-year platform subscriptions rather than upfront switchgear sales.
Growth Catalysts
- US Inflation Reduction Act grid modernization mandates:Federal tax credits and direct funding mechanisms accelerate utility procurement of automated restoration systems across distribution networks.
- IEC 61850 protocol standardization:IP-native substation communication architectures enable interoperability between multi-vendor sensor networks and control platforms.
- Islanding-capable microgrid deployment:Critical infrastructure operators in hurricane-prone coastal zones prioritize sectionalizing equipment that maintains service during upstream transmission failures.
Market Restraints
- Copper and rare earth magnet price volatility:Automated switchgear manufacturers face margin compression from concentrated mining supply in the Democratic Republic of Congo and China.
- Sulfur hexafluoride phase-out timelines:EU F-Gas Regulation mandates accelerate replacement cycles for GIS switchgear before alternative insulation technologies reach cost parity.
- Cybersecurity certification bottlenecks:IEC 62351 compliance testing capacity constraints extend vendor qualification timelines by 8-14 months in competitive tenders.
Strategic Opportunities
- India's rural electrification gaps:State distribution companies seek distributed automation solutions for low-density feeders where centralized SCADA deployment remains uneconomical.
- AI-driven predictive maintenance convergence:Machine learning platforms trained on waveform analytics create new revenue streams from failure-mode prediction services.
- Behind-the-meter storage integration:Commercial and industrial microgrid operators bundle battery dispatch with self-healing controls to capture demand charge arbitrage.
Industry Challenges
- Substation automation engineer scarcity:Utilities compete with technology vendors for personnel skilled in IEC 61850 configuration and GOOSE messaging protocol implementation.
- Legacy electromechanical relay interoperability:Brownfield deployments require protocol gateways that introduce latency into sub-100-millisecond protection schemes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Self-Healing Grid Market |
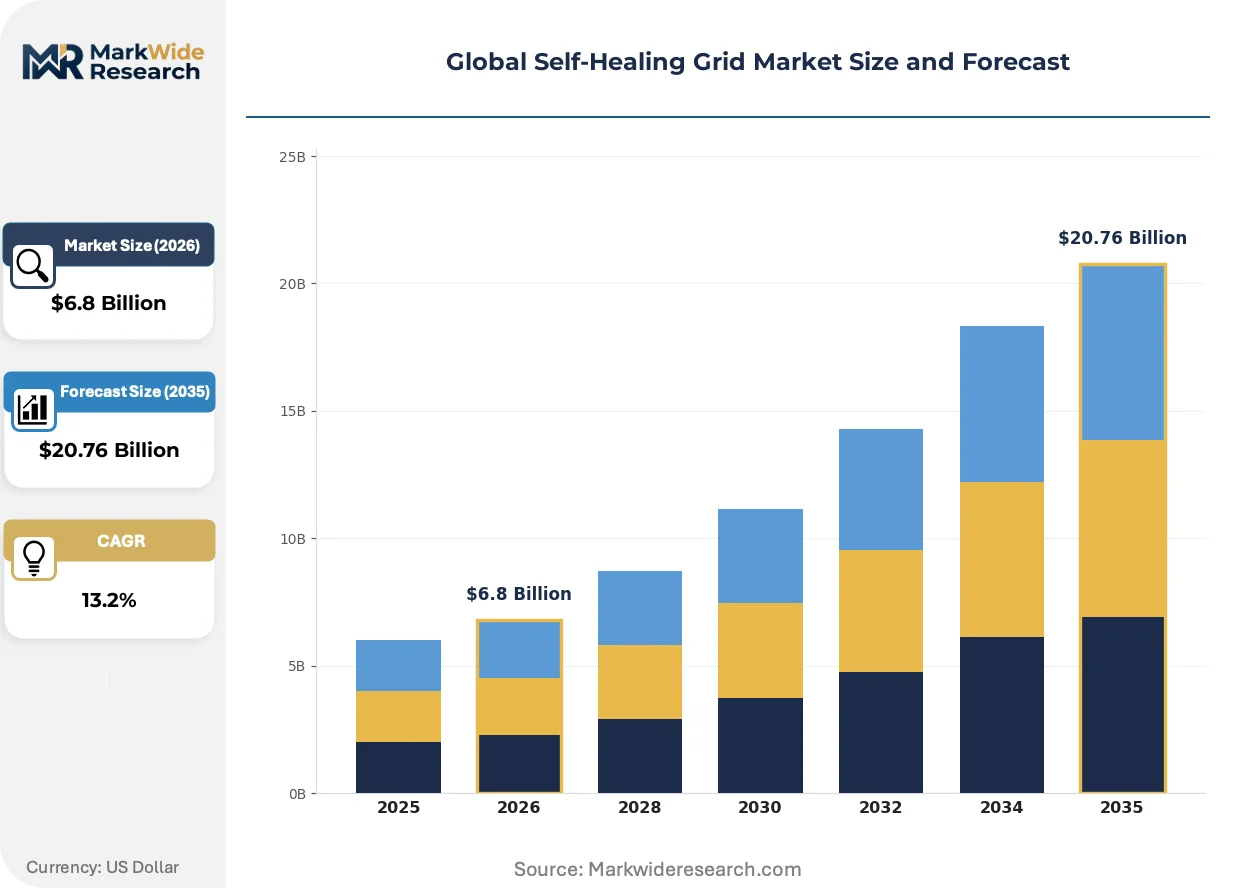
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $20.76 Billion |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Automated Distribution, Fault Detection, Remote Sensing, Smart Sensors, Communication Networks Application: Electric Utilities, Renewable Integration, Microgrid Management, Demand Response, Grid Automation Component: Switchgear, Sensors, Control Systems, Communication Devices, Energy Storage End User: Power Producers, Transmission Operators, Distribution Companies, Grid Operators |
| Companies Covered | S&C Electric Company, Schneider Electric SE, ABB, Landis+Gyr AG, Cisco Systems, Inc., Siemens AG, Eaton Corporation PLC, G&W Electric Company, General Electric Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Self-Healing Grid Market Shifts & Advancements
Real-time digital twins and edge-native control architectures are compressing fault detection-to-restoration intervals from seconds to milliseconds, redefining reliability benchmarks for distribution operators.
Silicon carbide power electronics is electrifying solid-state fault current limiters. These devices replace mechanical reclosers in urban underground networks where arc flash risks constrain conventional switching. European distribution system operators in Germany and the Netherlands lead deployment, attracted by maintenance-free operation cycles exceeding 20 years.
FERC Order 2222 aggregation mandates are reshaping distributed energy resource participation rules. The regulation compels regional transmission organizations to enable behind-the-meter assets in wholesale markets. Grid automation vendors respond with control platforms that coordinate inverter-based resources during fault-induced frequency excursions, with California ISO and NYISO filing compliance tariffs first.
Subscription-based platform licensing is displacing perpetual software sales in utility procurement. European operators particularly favor annual fees covering cyber threat monitoring, algorithm updates, and remote diagnostics. This model concentrates recurring revenue with vendors possessing cloud-native architectures and 24/7 security operations centers.
Global Self-Healing Grid Market Segmentation
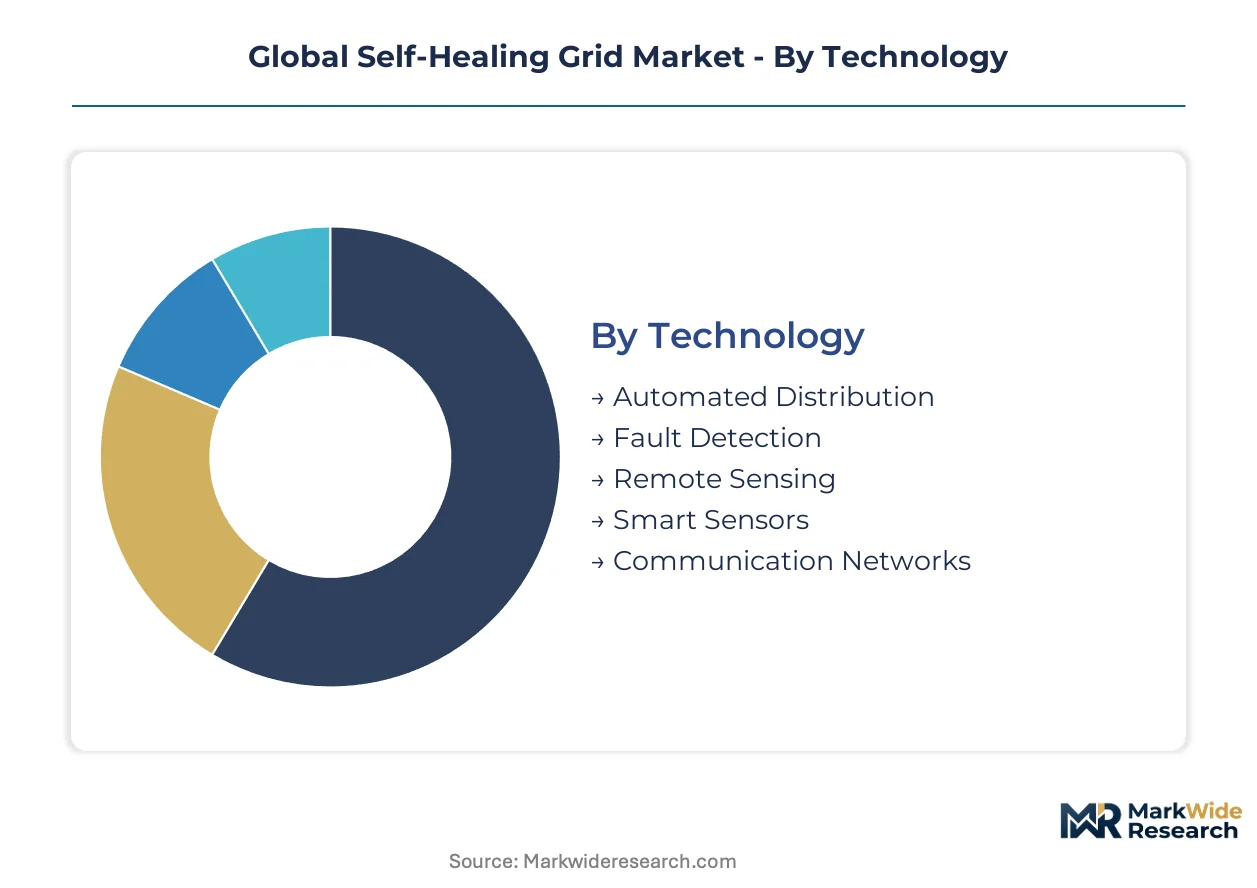
Self-healing grid procurement diverges sharply by capital intensity and operational maturity. Technology selection determines whether utilities pursue hardware-heavy switchgear replacement or software-centric orchestration layers.
Technology:
Capital requirements peak in segments demanding physical infrastructure overhaul versus those enabling software-defined control.
- Automated Distribution:Sectionalizing switchgear and reconfiguration logic form the core of utility capital programs. US distribution operators under IRA funding mandates prioritize this segment for radial feeder hardening.
- Communication Networks:IP-native backbone upgrades for IEC 61850 and DNP3 protocol compliance command substantial infrastructure investment. German and Chinese grid operators drive fastest expansion as interoperability mandates tighten.
- Fault Detection:Real-time waveform analytics platforms identify fault location within milliseconds. China's National Energy Administration enforces mandatory standards here.
- Remote Sensing:Satellite and cellular-connected monitoring devices extend visibility to remote transmission corridors. Deployment concentrates in mountain and coastal zones.
- Smart Sensors:Distributed measurement units with edge processing capability feed data into centralized digital twins. Penetration rises in urban underground networks.
Most installed capacity flows through Automated Distribution. Expansion is steepest in Communication Networks.
Application:
Revenue pools concentrate where control systems bundle with dispatchable assets rather than standalone sensing deployments.
- Grid Automation:Integrated substation control with energy storage dispatch captures the largest revenue share. Vertically integrated European operators favor bundled hardware-software contracts here.
- Microgrid Management:Islanding-capable sectionalizing equipment serves critical infrastructure in hurricane-prone US coastal zones. FERC Order 2222 aggregation rules accelerate procurement.
- Electric Utilities:Traditional distribution operators deploy self-healing logic across radial feeders. IRA tax credits reshape US procurement timelines.
- Renewable Integration:Inverter-based resource coordination during fault-induced frequency excursions. California ISO and NYISO lead compliance filing.
- Demand Response:Behind-the-meter load curtailment synchronized with automated restoration protocols. Commercial and industrial operators capture demand charge arbitrage.
Grid Automation commands the dominant revenue pool. Microgrid Management is gaining share fastest.
Component:
Margin structures vary between electromechanical hardware with decades-long replacement cycles and semiconductor-dependent electronics with faster obsolescence.
- Switchgear:Gas-insulated and solid-state alternatives compete as EU F-Gas Regulation phases out sulfur hexafluoride. Silicon carbide fault current limiters penetrate Dutch and German urban networks.
- Control Systems:Edge-native architectures with sub-100-millisecond response thresholds define competitive positioning. Software-defined orchestration shifts vendor economics toward recurring subscriptions.
- Sensors:Current and voltage measurement devices with IEC 61850-9-2LE sampling compliance. China's state-grid territories enforce mandatory fault-location sensor penetration.
- Communication Devices:Protocol gateways bridging legacy electromechanical relays with IP-native backbones. Brownfield deployments require latency management.
- Energy Storage:Battery dispatch integration with self-healing controls enables behind-the-meter microgrids. Lithium-ion supply concentration in China shapes procurement risk.
Switchgear absorbs the largest capital allocation. Control Systems show the steepest margin expansion.
End User:
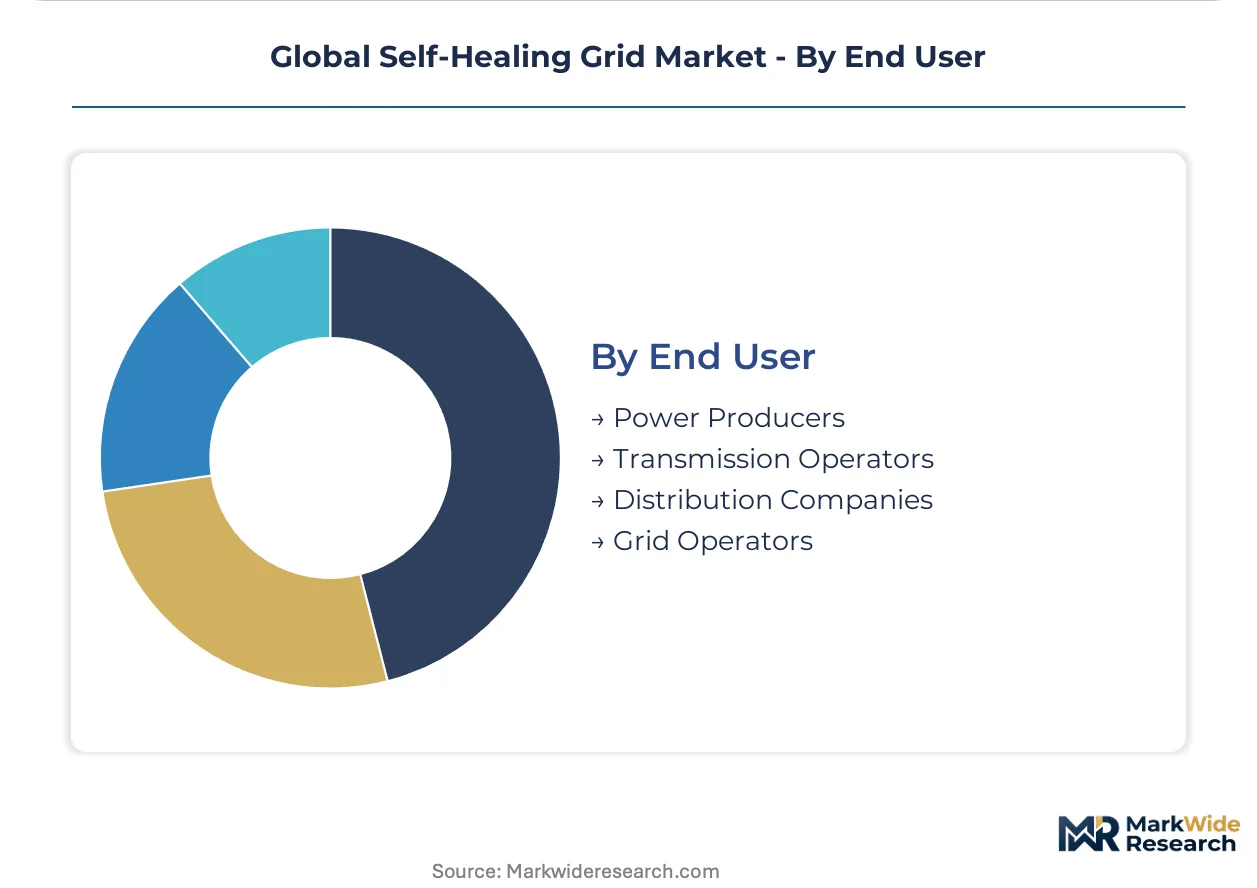
Procurement sophistication diverges between centralized state-grid operators and fragmented municipal distribution companies.
- Distribution Companies:Last-mile operators with direct customer relationships prioritize sectionalizing for outage duration reduction. India's state distribution companies seek distributed automation for low-density rural feeders.
- Grid Operators:Transmission system operators with balancing authority coordinate multi-vendor interoperability. IEC 62351 cybersecurity certification extends their vendor qualification timelines.
- Power Producers:Generator owners integrating self-healing controls with plant protection systems. Combined cycle and renewable assets require distinct fault ride-through logic.
- Transmission Operators:High-voltage corridor managers focus on wide-area situational awareness. Meshed network reconfiguration demands advanced stability analytics.
Distribution Companies represent the deepest installed base. Grid Operators are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's distribution operators deploy solid-state fault current limiters at roughly triple the pace of French utilities, while China's state-grid mandates enforce sensor penetration standards unmatched elsewhere.
United States
Hurricane-hardening investments and FERC Order 2222 aggregation rules drive procurement of islanding-capable sectionalizing equipment. The Inflation Reduction Act channels tax credits toward automated restoration systems across coastal distribution networks. Florida Power & Light and Duke Energy Carolinas lead deployment in storm-prone Southeast corridors.
Germany
Urban underground network operators prioritize maintenance-free silicon carbide switchgear with 20-year replacement cycles. The EU F-Gas Regulation accelerates sulfur hexafluoride phase-out timelines for gas-insulated substations. Distribution system operators in the Ruhr industrial cluster and Dutch border zones pioneer solid-state fault current limiter integration.
China
Mandatory fault-location standards from the National Energy Administration compel smart sensor installation across state-grid territories. Dual carbon goals under the 14th Five-Year Plan subsidize digital substation automation in renewable-rich western provinces. Xinjiang and Inner Mongolia grid operators deploy wide-area monitoring for meshed transmission corridors.
India
State distribution companies seek distributed automation for low-density rural feeders where centralized SCADA remains uneconomical. The Ministry of Power's Smart Grid Mission funds sectionalizing pilots in Maharashtra and Gujarat. Bangalore and Hyderabad technology clusters incubate edge-native control platforms for last-mile operators.
Netherlands
DSOs lead European adoption of silicon carbide fault current limiters in dense urban underground networks. National climate agreements mandate grid resilience upgrades to accommodate offshore wind integration. Rotterdam and Amsterdam metropolitan operators bundle automated reconfiguration with demand response platforms.
Global Self-Healing Grid Market Competitive Landscape
Top-tier vendors anchor integrated hardware-software bundles, while mid-tier specialists compete on protocol-specific configuration services. The vendor base stratifies across three tiers: multinational conglomerates with decade-long maintenance contracts, regional automation houses with IEC 61850 expertise, and emerging platform vendors with cloud-native architectures. Strategic archetypes include subscription-based orchestration providers, solid-state switchgear fabricators, and cybersecurity-certified systems integrators. Competitive moves concentrate on multi-year platform licensing and silicon carbide supply chain partnerships.
Within the integrated systems tier, Schneider Electric SE and Siemens AG exemplify vendors restructuring contract economics around recurring service revenue rather than upfront switchgear sales. ABB occupies a position bridging industrial automation heritage with digital platform migration. These three European-anchored conglomerates represent contrasting approaches to hardware-software decoupling: EcoStruxure-based subscription models, Ability digital portfolios, and integrated substation automation bundles respectively.
| Leading Market Players |
|---|
| S&C Electric Company |
| Schneider Electric SE |
| ABB |
| Landis+Gyr AG |
| Cisco Systems, Inc. |
| Siemens AG |
| Eaton Corporation PLC |
| G&W Electric Company |
| General Electric Company |
| Others |
Supply & Pricing Matrix
Utility procurement teams demanding IEC 61850-compliant interoperability are forcing switchgear vendors to absorb certification and protocol gateway costs, compressing project margins while elevating subscription-based platform economics. This demand-side specification tightening reshapes supplier tiering and concentrates pricing power with vendors possessing cloud-native architectures and 24/7 security operations centers.
Pricing Analysis
Capacity additions in China's silicon carbide substrate fabrication are reshaping price floors for solid-state fault current limiters. The dominant pricing structure stratifies across premium-certified, standard-compliant, and economy-tier equipment levels. Price differentiation hinges on IEC 62351 cybersecurity certification grade and after-sales service bundling. Cost compression in economy-tier switchgear is intensifying because rare earth magnet supply volatility from the Democratic Republic of Congo feeds into permanent magnet actuator costs. Distribution companies in India exhibit the highest price sensitivity due to rural electrification budget constraints, while vertically integrated European grid operators show the least.
Supply Chain Analysis
Freight cost escalation on semiconductor shipments from Taiwan and South Korea is amplifying landed costs for silicon carbide power electronics modules. Manufacturing concentrates in China for lithium-ion battery systems, Germany for precision switchgear assemblies, and the United States for edge-native control platforms. Raw material dependencies center on copper cathodes from Chilean smelters, rare earth concentrates from Chinese separation facilities, and high-purity silicon carbide wafers from Japanese crystal growers. Single-source vulnerability in Chinese lithium-ion cell supply poses structural risk. Distribution runs through authorized systems integrators with IEC 61850 configuration expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FERC Order 2222 aggregation mandates and EU F-Gas Regulation phase-out timelines generate durable procurement tailwinds across multiple geographies.
For Market Incumbents: Cement subscription revenue streams by migrating perpetual software licenses to annual platform fees covering cyber threat monitoring and algorithm updates. Deepen backward integration into silicon carbide supply partnerships to secure fault current limiter cost positions against emerging solid-state specialists. Counter the threat from cloud-native platform entrants by accelerating IEC 62351 certification timelines and embedding 24/7 security operations center capabilities into maintenance contracts. For New Entrants and Emerging Players: Regional automation houses with IEC 61850 configuration expertise represent the most penetrable channel partner type for market access. Target India's state distribution companies seeking distributed automation for low-density rural feeders where centralized SCADA deployment remains uneconomical. Pursue white-space in AI-driven predictive maintenance services trained on waveform analytics, and in behind-the-meter storage integration for commercial microgrid operators. Lead with edge-native control platforms incubated in Bangalore and Hyderabad technology clusters. For Investors and Strategic Acquirers: Asymmetric upside sits with cybersecurity-certified systems integrators possessing IEC 62351 testing capabilities and multi-vendor protocol gateway portfolios. Long-term viability over a multi-year horizon favors vendors with recurring platform revenue exceeding 40 percent of total sales and established utility relationships in hurricane-prone US coastal zones. Monitor FERC Order 2222 compliance tariff filings by California ISO and NYISO as the inflection indicator for distributed energy resource aggregation platform demand.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Supply Partnership | Secures 20-year maintenance-free switchgear cost positions for German and Dutch urban networks. |
| Platform Migration to Subscription Licensing | Locks in decade-long recurring revenue streams with European distribution system operators. |
| IEC 62351 Certification Acceleration | Compresses vendor qualification timelines currently extending 8-14 months in competitive tenders. |
| Edge-Native Control Architecture Development | Enables sub-100-millisecond fault response thresholds for California ISO frequency excursion coordination. |
| Rural Feeder Automation Pilot Expansion | Captures Maharashtra and Gujarat state distribution company procurement under India's Smart Grid Mission. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with utility planning officers, substation automation engineers, EPC contractors, and grid operators with secondary validation against FERC filings, EIA project databases, IEA grid modernization reports, and IEC standards documentation. Bottom-up equipment shipment tracking and top-down utility capital expenditure analysis were triangulated against regional regulatory mandate timelines.
Historical reference periods anchored the forecast window to pre-IRA baseline utility procurement patterns and post-FERC Order 2222 filing acceleration phases. The analytical framework modeled segmentation across technology type, application, component category, and end-user sophistication tier, with regional regulatory framework and grid topology as cross-cutting dimensions. CAGRs were derived from equipment deployment trajectories and service revenue conversion rates. Forecast inputs incorporated silicon carbide power electronics adoption curves and cybersecurity certification bottleneck resolution assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to rare earth supply disruptions, EU F-Gas Regulation enforcement timing, and IEC 62351 testing capacity expansion. Forecasts reflect documented assumptions about utility procurement cycle normalization and interoperability mandate compliance trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Grid
Smart Grid Adoption Market
Smart Grid
Asia-Pacific Smart Grid Network Market
Smart Grid
China Smart Grid Network Market
Smart Grid
AC Grid Connected Microgrid Market
Smart Grid
Global Smart Grid Networking Market
Smart Grid
Europe Microgrid Market
Smart Grid
Global Smart Grid Security Market
Smart Grid
Europe Smart Grid Network Market
Smart Grid
GCC Smart Grid Security Market
Smart Grid
Renewable Energy Integration with Smart Grid Market
Smart Grid
Demand Response Market
Smart Grid
Smart Demand Response Market
Smart Grid
Smart Water Grid Market
Smart Grid
Automated Demand Response Management Systems Market
Smart Grid
South Africa Smart Grid Market
Smart Grid
North America Smart Grid Market